
 Insulated Concrete Form (ICF) Market | 2026-2036
Insulated Concrete Form (ICF) Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Concrete Form (ICF) Market Analysis
Skilled concrete-labor availability is reorganizing how ICF projects scale across North American job sites, with contractors prioritizing systems that reduce pour complexity and crew size. Fox Blocks leverages its vertically integrated foam-concrete supply chain to control material consistency across regional distribution hubs. Amvic Inc. competes through a block-system design that accelerates wall assembly speed for mid-rise commercial frames. BuildBlock Building Systems LLC anchors its position with extensive contractor-training networks that address the same labor bottleneck.
Insulated Concrete Forms are hollow, interlocking modular units—typically molded from expanded polystyrene or polyurethane foam—that receive reinforced concrete pours to create monolithic, thermally resistant wall assemblies with R-values commonly exceeding R-20. The primary industrial purpose centers on delivering structural strength, acoustic dampening, and continuous insulation within a single construction operation. Polystyrene-based ICF products dominate volume shipments due to established supply chains and lower raw-material costs, while polyurethane variants capture margin-rich niches demanding superior thermal performance in passive-house and net-zero builds. Residential construction remains the largest application channel, though institutional structures—schools, hospitals, government facilities—represent the fastest-growing demand pool as public procurement increasingly mandates resilient-design standards.
The US EPA and Department of Energy enforce building-envelope efficiency benchmarks that directly elevate ICF competitiveness against traditional stick-frame and concrete-masonry alternatives. Canada's National Building Code and provincial energy step codes in British Columbia and Ontario similarly tighten thermal-performance requirements that ICF assemblies satisfy natively. Forward-looking stakeholders must monitor how evolving municipal resilience ordinances—particularly seismic and wind-load provisions—will filter allowable wall-system specifications and reshape contractor specification habits.
Market Dynamics
Skilled concrete-labor scarcity is compressing project timelines and forcing contractors toward simplified forming systems that reduce crew size and pour complexity. This structural constraint is reshaping competitive positioning across the ICF supply base.
Growth Catalysts
- US EPA Energy Efficiency Mandates:Building envelope benchmarks are elevating ICF competitiveness against stick-frame alternatives in residential and commercial construction.
- Hurricane-Prone Coastal Zones:Disaster-resilient housing demand in Florida, Texas, and Louisiana is accelerating ICF specification for storm-resistant wall assemblies.
- Passive House Certification:Stringent thermal-performance requirements in net-zero building programs are driving specification of high-R-value ICF systems.
Market Restraints
- Expanded Polystyrene Feedstock Volatility:Petrochemical input cost swings compress margins for foam-form manufacturers during crude price spikes.
- Regional Concrete Supply Concentration:Local ready-mix capacity constraints in remote Sun Belt markets limit ICF project scalability.
- Building Code Fragmentation:Inconsistent municipal adoption of ICF-specific provisions across US jurisdictions creates specification friction.
Strategic Opportunities
- Institutional Construction Vertical:Schools, hospitals, and government facilities represent underpenetrated demand as public procurement mandates resilient-design standards.
- Canada Energy Step Codes:British Columbia and Ontario thermal-performance escalators create regulatory tailwinds for high-performance wall systems.
- Prefabricated Panel Integration:Convergence of ICF with offsite manufacturing is opening modular construction channels for mid-rise commercial frames.
Industry Challenges
- Certified Installer Pipeline:The shortage of trained ICF placement crews extends project timelines and limits contractor capacity expansion.
- Legacy Masonry Specification Habits:Architect and engineer familiarity with concrete masonry unit design creates inertia against ICF system adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Concrete Form (ICF) Market |
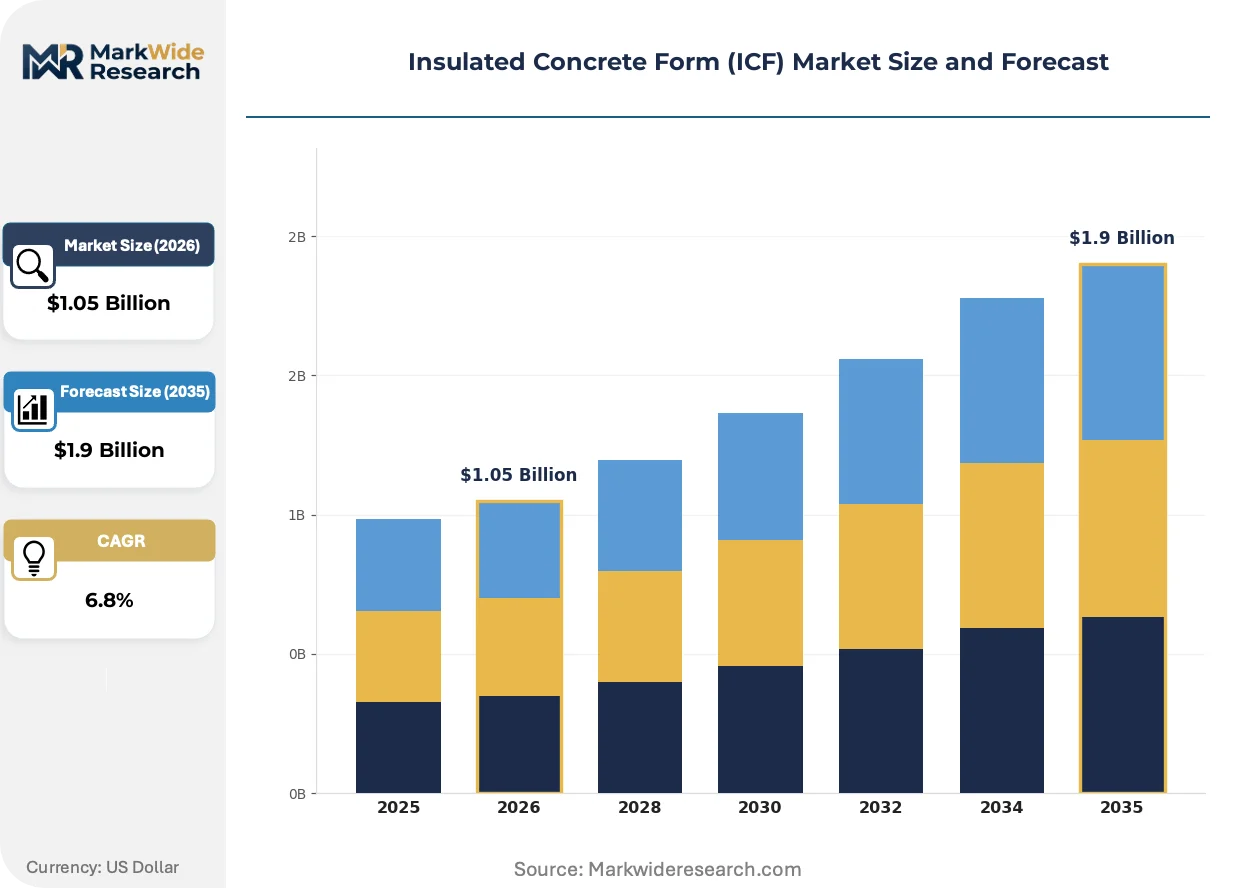
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.9 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Polystyrene, Concrete, Composite Application: Residential Construction, Commercial Buildings, Institutional Structures, Disaster Relief Housing Installation Method: Panelized System, Block System, Traditional Method, Hybrid Approach End User: Contractors, Builders, Architects, DIY Enthusiasts |
| Companies Covered | Fox Blocks, Amvic Inc., BuildBlock Building Systems LLC, Nudura Corporation, Quad-Lock Building Systems Ltd., Logix Brands Ltd., BASF SE, Beco Products Ltd., Superform Products Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Concrete Form (ICF) Market Emerging Trajectories
Material science advances and regulatory ratcheting are compressing traditional construction workflows. Three developments are actively restructuring how thermally efficient wall systems reach job sites.
Polyurethane-core ICF is supplanting expanded polystyrene variants in passive-house and net-zero builds where R-value per inch commands specification priority. High-performance residential developers in the Pacific Northwest and Northeast are specifying these systems at accelerating rates. The shift is compressing market share for conventional polystyrene forms in premium thermal-envelope segments.
Canada's National Building Code and provincial energy step codes in British Columbia and Ontario are tightening thermal-performance baselines that ICF assemblies satisfy without additional insulation layers. The industrial consequence is specification migration away from stick-frame with exterior insulation toward monolithic concrete wall systems. Multi-family residential and mid-rise commercial projects in Vancouver and Toronto are responding fastest to these code escalators.
Buyer specification habits are rotating toward turnkey wall-system providers that bundle engineering, material supply, and crew training. General contractors in the US Sun Belt are consolidating vendor relationships to reduce coordination overhead on complex envelope assemblies. Florida and Texas commercial developers are most visibly shifting procurement toward integrated ICF package contracts that transfer performance risk to single-source suppliers.
Insulated Concrete Form (ICF) Market Segmentation
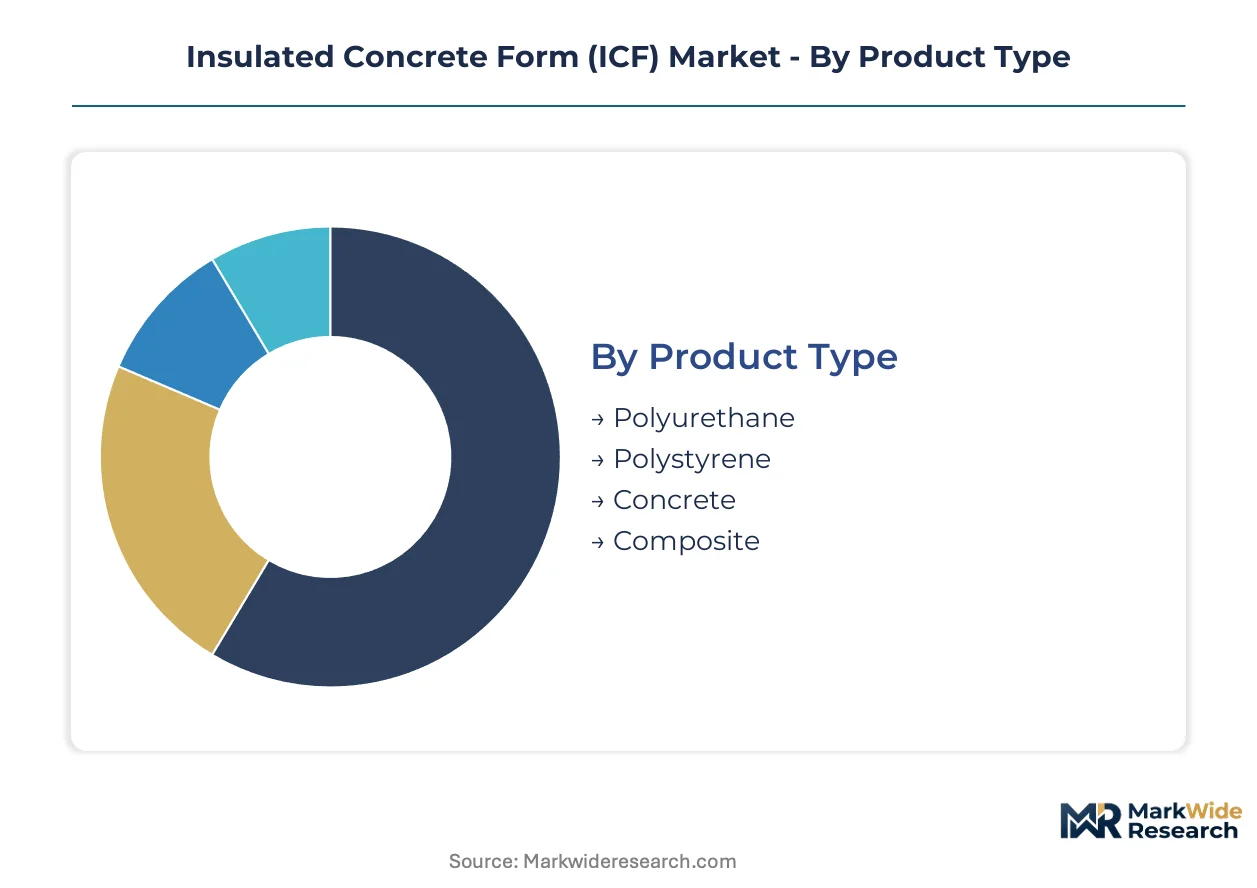
ICF procurement channels fragment sharply across product chemistry and project scale. Specification habits diverge between residential contractors prioritizing cost predictability and institutional buyers demanding certified thermal performance.
Product Type:
Channel mix splits between mass-market distributors moving polystyrene volumes and specialist dealers supplying polyurethane for high-performance envelopes.
- Polystyrene:Expanded polystyrene forms deliver R-values of R-20 to R-25 through established supply chains with lower material costs. Demand concentrates across Sun Belt residential construction where thermal performance must balance against hurricane-resistant structural requirements.
- Polyurethane:Polyurethane-core systems achieve superior R-value per inch, enabling thinner wall assemblies in space-constrained urban infill. Pacific Northwest and Northeast passive-house developers specify these forms at accelerating rates for net-zero certification compliance.
- Concrete:Concrete-integrated ICF variants emphasize structural mass for acoustic dampening in mid-rise commercial frames.
- Composite:Hybrid foam-concrete composites target institutional buyers seeking single-source envelope warranties.
Polystyrene dominates installed base. Polyurethane is where expansion concentrates.
Application:
Cost tier stratification separates premium institutional specifications from economy residential volumes.
- Residential Construction:Single-family and multi-family housing represents the largest volume channel, with coastal Florida and Texas markets driving disaster-resilient specification for wind-load resistance.
- Institutional Structures:Schools, hospitals, and government facilities command premium pricing through resilient-design procurement mandates. British Columbia and Ontario energy step codes accelerate specification for public buildings seeking thermal-performance compliance without additional insulation layers.
- Commercial Buildings:Mid-rise office and retail frames in Vancouver and Toronto respond to code escalators with monolithic wall assemblies.
- Disaster Relief Housing:Rapid-deployment ICF units serve emergency reconstruction in hurricane-recovery zones.
Residential absorbs volume throughput. Institutional commands margin expansion.
Installation Method:
Volume concentration favors systems reducing crew size where concrete-labor scarcity compresses timelines.
- Block System:Interlocking modular units accelerate wall assembly for mid-rise commercial frames, with Amvic Inc. competing through design-optimized configurations.
- Panelized System:Factory-fabricated panels enable offsite manufacturing convergence for mid-rise commercial construction, opening modular channels with reduced job-site labor dependence.
- Traditional Method:Site-assembled forming maintains presence in custom residential where design flexibility outweighs speed.
- Hybrid Approach:Combined panel-block systems target complex envelope geometries in institutional projects.
Block systems anchor residential penetration. Panelized methods are climbing the fastest in commercial specification.
End User:
Customer type determines specification authority and training investment requirements.
- Contractors:General contractors in the US Sun Belt consolidate vendor relationships toward turnkey wall-system providers, transferring performance risk to single-source suppliers through integrated package contracts.
- Builders:Production homebuilders prioritize systems with established crew training networks to address certified installer pipeline constraints.
- Architects:Design professionals specify ICF for thermal-bridge elimination in passive-house certification pathways.
- DIY Enthusiasts:Owner-builders in remote markets drive direct-to-consumer channel development for simplified forming systems.
Contractors control procurement volume. Architects drive specification migration toward high-performance variants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA energy efficiency mandates and hurricane-resistant building codes anchor the United States as the dominant geography, with regulatory tailwinds extending into Canada and selective European markets where thermal-performance standards tighten.
United States
Disaster-resilient housing demand concentrates across Florida, Texas, and Louisiana, where wind-load requirements exceed conventional stick-frame capacity. The EPA's building envelope benchmarks elevate ICF competitiveness against traditional alternatives in residential and commercial construction. Miami-Dade County and Houston metro contractors specify monolithic wall assemblies for mid-rise commercial frames at accelerating rates.
Canada
British Columbia and Ontario energy step codes tighten thermal-performance baselines that ICF assemblies satisfy without supplemental insulation layers. The National Building Code revisions push multi-family residential developers toward high-performance wall systems in Vancouver and Toronto. Calgary institutional builders respond to provincial resilience mandates with certified thermal-envelope specifications.
Germany
Passive House certification pathways drive polyurethane-core ICF specification for net-zero residential developments in Berlin and Munich. The country's national building energy regulations (GEG) compress allowable heating demand thresholds. Bavarian commercial developers integrate monolithic concrete wall systems to meet stringent envelope-performance criteria.
United Kingdom
Building Regulations Part L revisions elevate thermal-efficiency requirements for new residential construction across Greater London and Southeast England. The Future Homes Standard accelerates specification migration toward continuous-insulation wall assemblies. Manchester and Birmingham mid-rise commercial projects adopt ICF frames to satisfy operational-carbon reduction targets.
Australia
Bushfire-resistant construction standards in New South Wales and Victoria expand addressable demand for non-combustible wall systems. The National Construction Code energy-efficiency provisions tighten envelope-performance requirements. Sydney and Melbourne metropolitan developers specify thermally efficient concrete wall assemblies for multi-unit residential frames.
Insulated Concrete Form (ICF) Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with supply-side concentration producing differentiated positioning around material chemistry and installation-system design. The vendor base organizes into three strategic archetypes: vertically integrated foam-concrete producers controlling raw-material consistency, design-optimized block-system specialists accelerating assembly speed, and training-network operators addressing certified installer pipeline constraints. Competitive moves concentrate on backward integration into polystyrene feedstock and geographic expansion through regional distribution hub establishment.
Within the integrated-leader tier, Fox Blocks exemplifies upstream control over foam-concrete supply chains, while Amvic Inc. and BuildBlock Building Systems LLC anchor distinct positioning vectors—Amvic through block-system design optimization and BuildBlock through contractor-training network scale. These three entities occupy positions that reflect the industry's structural response to skilled-labor scarcity and project-timeline compression.
| Leading Market Players |
|---|
| Fox Blocks |
| Amvic Inc. |
| BuildBlock Building Systems LLC |
| Nudura Corporation |
| Quad-Lock Building Systems Ltd. |
| Logix Brands Ltd. |
| BASF SE |
| Beco Products Ltd. |
| Superform Products Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between ICF manufacturers and Sun Belt ready-mix suppliers lock in both concrete access and price visibility for multi-phase residential developments in Florida and Texas. These arrangements insulate project developers from petrochemical feedstock volatility while securing pour capacity during peak construction seasons.
Pricing Analysis
Geographic price spreads between Pacific Northwest polyurethane-core specifications and Sun Belt polystyrene volumes reflect raw-material chemistry and thermal-performance tier differentiation. Project-based contracting dominates, with pricing stratifying across premium passive-house certification, standard residential hurricane-code compliance, and economy multi-family volume tiers. Cost compression in polystyrene forms is intensifying because expanded polystyrene feedstock tracks crude oil indices. Production homebuilders in Texas and Florida exhibit highest price sensitivity, while institutional buyers in British Columbia and Ontario prioritize certified thermal performance over unit cost.
Supply Chain Analysis
The United States and Canada anchor expanded polystyrene bead production for mass-market ICF forms, while Germany and Japan supply polyurethane chemical precursors for high-performance variants. Manufacturing draws from petrochemical feedstocks, concrete admixtures, and steel reinforcement mesh. Single-source vulnerability concentrates in regional ready-mix concrete capacity, where remote Sun Belt markets face pour scheduling constraints. Distribution runs through manufacturer-direct regional hubs serving contractor networks, with specialist dealers handling polyurethane-core specifications for passive-house developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ICF incumbents face sustained substitution pressure from cross-laminated timber and structural insulated panels in mid-rise commercial frames, requiring defensive positioning around code-mandated resilience performance.
For Market Incumbents: Secure backward integration into expanded polystyrene feedstock production to buffer margin compression during crude price spikes. Anchor capacity expansion in Ontario and British Columbia to capture energy step code escalators before structural insulated panels gain specification share in institutional procurement.
For New Entrants and Emerging Players: Lead with panelized ICF systems targeting Vancouver and Toronto mid-rise commercial projects where labor scarcity compresses traditional block assembly timelines. Target institutional construction verticals in Calgary and Edmonton where provincial resilience mandates create specification entry points without entrenched incumbent relationships.
For Investors and Strategic Acquirers: Regional training-network operators with captive installer certification pipelines present acquisition targets given certified crew scarcity constrains industry capacity expansion. Monitor municipal resilience ordinance adoption rates across US Gulf Coast jurisdictions as inflection indicator for disaster-resilient housing specification velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polystyrene Feedstock | Captive bead production insulates Fox Blocks and peers from petrochemical cost volatility. |
| Regional Distribution Hub Establishment | Texas and Florida hubs reduce concrete pour scheduling friction for Sun Belt contractors. |
| Certified Installer Network Expansion | BuildBlock's training scale addresses crew pipeline constraints compressing project timelines. |
| Prefabricated Panel System Development | Amvic's design-optimized configurations accelerate wall assembly for mid-rise commercial frames. |
| Passive-House Certification Pathway Investment | Polyurethane-core specifications capture Pacific Northwest and Northeast net-zero developer demand. |
Methodological Framework
The analysis maps polystyrene-form, polyurethane-core, panelized-system, and block-system segments, each validated through contractor interviews, architect specification reviews, and ready-mix supplier procurement assessments. Primary fieldwork with ICF distributors, commercial general contractors, and municipal building officials combined with secondary validation against EPA building envelope guidance, Canada National Building Code revisions, and provincial energy step code documentation. Bottom-up project pipeline analysis and top-down construction spend allocation triangulate volume estimates.
Consistency checks against external benchmarks validated projections across the analysis window. The modeling framework segments by product chemistry, application vertical, installation method, and end-user procurement authority. CAGRs derive from regression analysis of historical construction permit data and regulatory adoption curves. Forecast inputs include hurricane-resistant building code expansion timelines and Canada energy step code escalation schedules.
The analysis sits within stated boundaries; outcomes outside sustained EPA enforcement of building envelope benchmarks or accelerated Canada step code implementation would require recalibration. Forecasts reflect assumptions regarding skilled concrete-labor availability and petrochemical feedstock stability. Recalibration cycles align with material shifts in municipal resilience ordinance adoption and institutional procurement mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Israel Ceramic Tiles Market
Building & Construction Materials
EPS Sandwich Panels Market
Building & Construction Materials
North America Ceramic Tiles Market
Building & Construction Materials
Europe Construction Repair and Rehabilitation Chemicals Market
Building & Construction Materials
Sound Barriers Market
Building & Construction Materials
Concrete Protective Liners Market
Building & Construction Materials
Brick Market
Building & Construction Materials
Decks Market
Building & Construction Materials
Plastic Formwork Market
Building & Construction Materials
North America Plywood Market
Building & Construction Materials
Global Hydraulic Door Closer Market
Building & Construction Materials
Plastic Fencing Market
Building & Construction Materials
Railing Market
Building & Construction Materials
Europe Geogrids Market
Building & Construction Materials
North America Steel Roofing Market
Building & Construction Materials
Artificial Marble Market