
 Mexican Insulated Panels Market | 2026-2036
Mexican Insulated Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Mexican Insulated Panels Market Insights
Northern Mexico is rewriting the competitive map for insulated panel supply as manufacturing investment flows toward Monterrey and Tijuana. Kingspan Group leverages its international technical standards to anchor premium specification work across industrial cold chain projects. Metl-Span competes aggressively on lead-time reliability for warehouse and distribution center rollouts. Industrias Unypanel SA DE CV dominates domestic retrofit channels through deep regional distributor relationships.
Mexican insulated panels are factory-engineered composite assemblies combining rigid foam insulation cores with metal or structural facings, manufactured via continuous lamination or discontinuous press processes to achieve specified R-values and structural span capabilities. These systems primarily enclose temperature-controlled environments and reduce thermal bridging in commercial envelopes. Foam core panels lead specification volume in cold storage and clean room applications where thermal performance governs operating economics. Structural insulated panels occupy the fastest-growing position in modular building and prefabricated unit construction as developers compress project schedules. Metal faced panels sustain mature margins in commercial roofing retrofits where durability and weathertightness drive replacement cycles.
Mexico's Ministry of Energy (SENER) and the National Housing Commission (CONAVI) enforce thermal efficiency standards that elevate minimum insulation performance in new commercial construction. The Federal Commission for Protection against Sanitary Risks (COFEPRIS) mandates hygienic envelope standards for food processing and pharmaceutical facilities that specify cleanable panel surfaces and joint integrity. Stakeholders must monitor how upcoming building code harmonization with international energy protocols reshapes product certification requirements and local manufacturing investment decisions.
Market Dynamics
Mexico's northern industrial corridor is pulling insulated panel specification toward higher thermal performance grades as cold storage construction accelerates across Baja California, Nuevo León, and Jalisco. SENER's updated energy efficiency codes are compressing payback periods for premium foam core systems in commercial envelopes.
Growth Catalysts
- COFEPRIS hygienic envelope mandates:Food processing and pharmaceutical facilities must deploy cleanable panel surfaces with verified joint integrity, locking in demand for certified metal-faced systems in Monterrey and Tijuana production zones.
- Refrigerated warehouse clustering:Logistics developers along the Baja California corridor are specifying foam core panels for temperature-controlled distribution centers serving cross-border agricultural exports.
- Continuous lamination process improvements:Domestic manufacturers have reduced panel production cycle times, enabling faster fulfillment for modular building projects in Jalisco's expanding industrial parks.
Market Restraints
- Polyol and MDI input volatility:Rigid foam insulation cores depend on petrochemical feedstocks whose price swings compress margin predictability for panel fabricators serving price-sensitive retrofit channels.
- Import dependency for facing substrates:Galvanized steel and aluminum coil supply concentrates in a limited number of international mills, exposing Mexican converters to freight cost surges and currency fluctuation risk.
- Skilled installation labor scarcity:Proper envelope sealing and thermal bridge elimination requires certified erector crews that remain underrepresented in secondary markets outside Mexico City and Monterrey metropolitan areas.
Strategic Opportunities
- Querétaro and Guanajuato industrial expansion:Automotive supplier parks and aerospace clusters in Mexico's central highlands are underpenetrated for clean room panel specification, creating first-mover positioning for technical sales investment.
- Modular housing acceleration:CONAVI's affordable housing programs are piloting structural insulated panels for rapid-assembly social housing, opening volume channels beyond traditional commercial construction.
- Building code harmonization with IECC standards:Anticipated alignment of Mexican thermal performance baselines with international energy protocols would elevate import substitution opportunities for domestic manufacturers holding dual certification.
Industry Challenges
- Certification timeline compression:COFEPRIS and SENER concurrent approval processes for new panel formulations extend product launch cycles, requiring parallel regulatory strategy rather than sequential filing.
- Legacy building stock retrofit complexity:Existing commercial envelopes in Mexico City's dense industrial zones present structural load constraints and dimensional irregularities that complicate panelized overlay installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexican Insulated Panels Market |
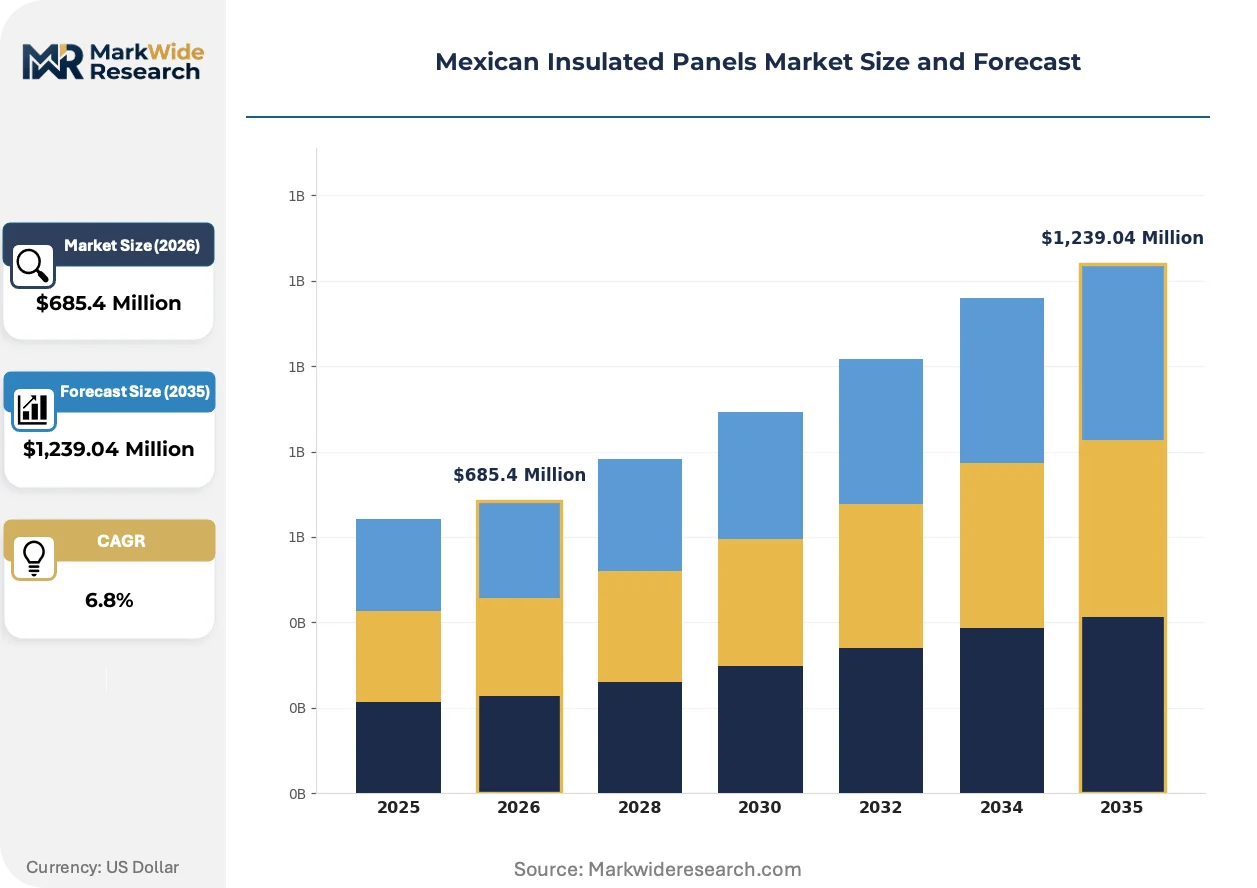
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Core Panels, Metal Faced Panels, Structural Insulated Panels, Sandwich Panels Application: Cold Storage, Clean Rooms, Modular Buildings, Commercial Roofing End User: Food Processing Facilities, Pharmaceutical Plants, Data Centers, Warehouse Facilities Installation Type: New Construction, Retrofit Projects, Prefabricated Units, Mobile Installations |
| Companies Covered | Industrias Unypanel SA DE CV, Kingspan Group, Metl-Span, Centria, All Weather Insulated Panels, Metecno Group, PFB Corporation, Owens Corning, Green Span Profiles, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexican Insulated Panels Market Trends and Innovations
Material science advances and regulatory stringency are converging to redefine competitive advantage in Mexican insulated panel supply. Specification decisions increasingly weight lifecycle thermal performance over first-cost minimization.
Polyisocyanurate foam core technology is hybridizing with vacuum-insulated panel layers to achieve R-values exceeding traditional polyurethane systems by forty percent. Cold storage developers in Baja California are specifying these hybrid assemblies for automated distribution centers where energy density governs operating economics. The convergence is compressing specification windows for conventional EPS-core panels in premium temperature-controlled applications.
SENER's 2024 thermal efficiency code amendments for commercial buildings are mandating continuous insulation strategies that eliminate thermal bridging at structural connections. Industrial envelope designers in Nuevo León are responding by shifting from field-assembled insulation systems toward factory-engineered composite panels with integrated thermal breaks. The regulatory pressure is accelerating certification demand for panel systems tested to ASTM C1363 and ISO 8990 protocols.
Developer procurement patterns are consolidating specification authority toward engineering-procurement-construction firms managing turnkey cold chain projects. Regional distributors serving Jalisco and Tijuana are losing direct contractor relationships as EPCs centralize envelope material selection through national framework agreements. The channel compression is most visible in pharmaceutical logistics construction, where validated envelope performance documentation outweighs local availability in vendor selection criteria.
Mexican Insulated Panels Market Segmentation
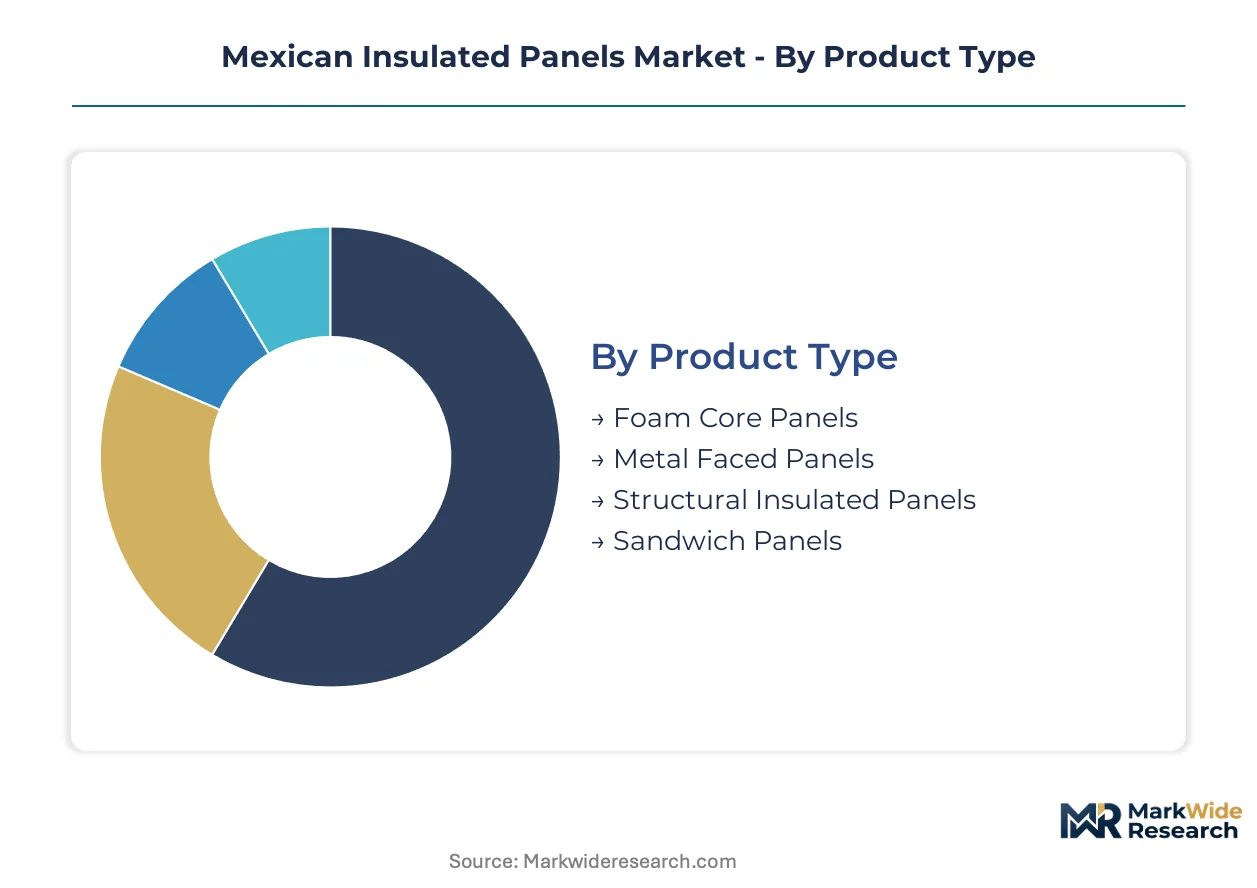
Insulated panel specification in Mexico diverges sharply across thermal performance requirements, structural loading demands, and regulatory compliance thresholds. Understanding these segment boundaries clarifies where manufacturers can defend premium positioning versus where price competition dominates procurement decisions.
Product Type:
Use-case spectrum spans temperature-controlled envelopes requiring maximum thermal resistance through structural assemblies prioritizing speed of erection.
- Foam Core Panels:Rigid polyurethane or polyisocyanurate cores laminated between metal facings deliver specified R-values for cold chain applications. Demand concentrates in Baja California refrigerated warehouses where SENER energy codes compress payback periods for high-performance thermal envelopes. COFEPRIS hygienic mandates lock in metal-faced specifications for food processing zones in Monterrey and Tijuana.
- Structural Insulated Panels:Factory-engineered composite assemblies combining rigid insulation with structural oriented strand board or cementitious facings achieve load-bearing capacity with minimal thermal bridging. Jalisco modular building developers are specifying these systems for accelerated project schedules in Guadalajara industrial parks. CONAVI affordable housing pilots are testing SIP construction for rapid-assembly social housing deployment.
- Metal Faced Panels:Galvanized steel or aluminum skins bonded to insulation cores provide durable weathertight envelopes for commercial roofing retrofits. Nuevo León distribution centers specify these for replacement cycles where durability governs lifecycle economics.
- Sandwich Panels:Multi-layer composite constructions with varied core materials serve general industrial enclosure needs across Mexico's northern manufacturing corridor.
The dominant share belongs to Foam Core Panels, while Structural Insulated Panels is closing the gap fastest.
Application:
Cost tier segmentation separates capital-intensive temperature-controlled infrastructure from maintenance-driven roofing replacement cycles.
- Cold Storage:Automated distribution centers and refrigerated warehouses demand foam core assemblies achieving sub-zero envelope integrity with verified thermal bridge elimination. Baja California agricultural export logistics clusters specify hybrid polyisocyanurate-vacuum panel systems for energy density optimization. SENER code amendments accelerate specification of continuous insulation strategies over field-assembled alternatives.
- Clean Rooms:Pharmaceutical and biotechnology facilities require panel surfaces meeting COFEPRIS hygienic envelope standards with validated joint integrity and cleanability documentation. Monterrey and Tijuana production zones drive specification volume as medical device manufacturing expands.
- Modular Buildings:Prefabricated unit construction compresses project schedules through factory-controlled envelope assembly. Jalisco industrial park developers are shifting procurement toward panelized systems for workforce housing and light manufacturing facilities.
- Commercial Roofing:Retrofit replacement cycles in Mexico City's dense industrial zones favor metal-faced panels where structural load constraints and dimensional irregularities complicate alternative envelope strategies.
Cold Storage commands the largest application share, with Clean Rooms expanding most quickly on pharmaceutical logistics investment.
End User:
Customer type fragmentation reflects divergent compliance burdens across regulated industries versus general logistics operations.
- Food Processing Facilities:COFEPRIS mandates for hygienic envelope standards with cleanable surfaces and verified joint integrity lock in certified metal-faced panel specifications. Monterrey meat processing and dairy operations represent concentrated demand nodes.
- Pharmaceutical Plants:Validated envelope performance documentation requirements outweigh local availability in vendor selection criteria. EPC firms managing turnkey projects centralize specification authority through national framework agreements.
- Data Centers:Thermal management requirements for server infrastructure create demand for high-R-value envelope systems in Querétaro and Guanajuato technology corridors.
- Warehouse Facilities:General logistics and distribution operations across Nuevo León and Jalisco specify standard-performance panels where first-cost minimization dominates procurement.
Food Processing Facilities retain the leading end user position, though Pharmaceutical Plants are gaining share fastest on cross-border medical supply chain investment.
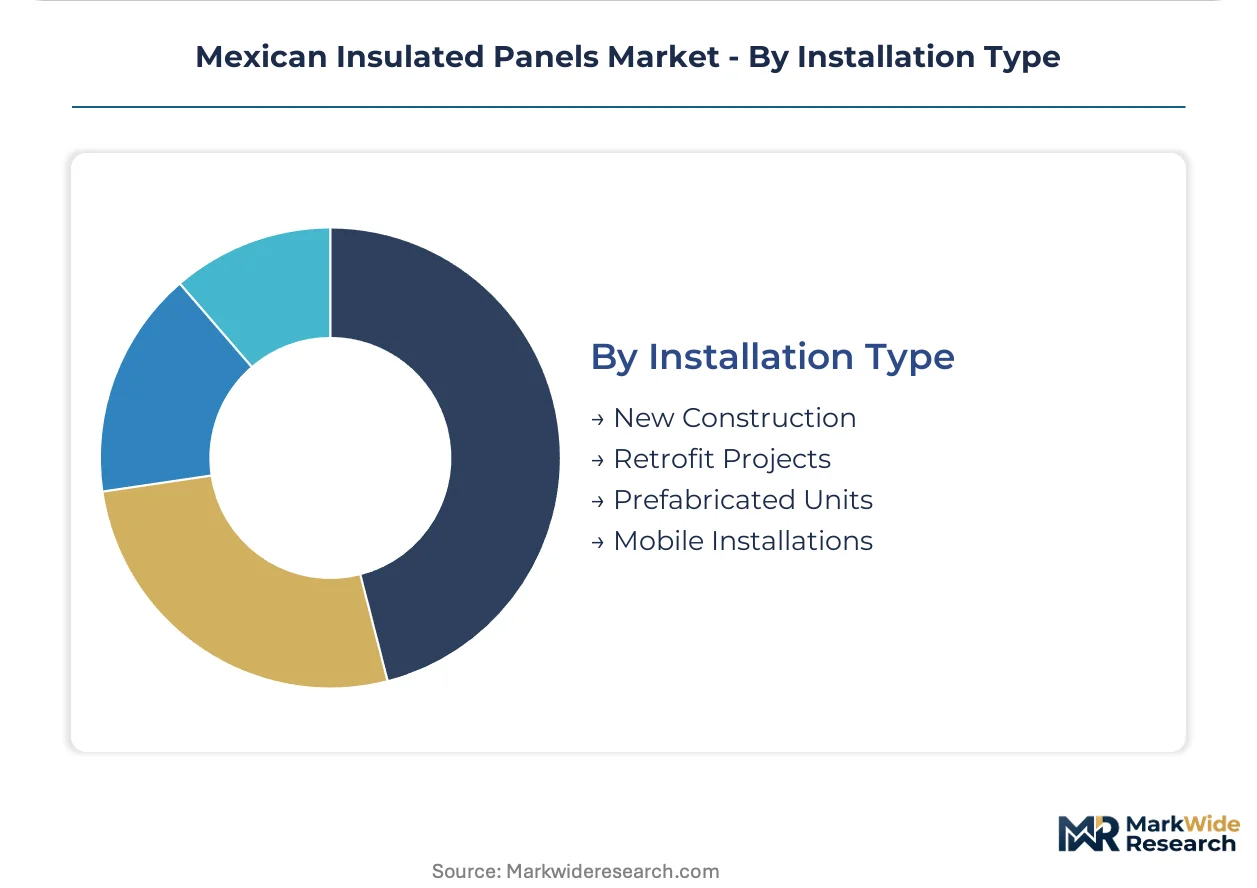
Installation Type:
Volume concentration tracks new industrial construction in northern states against retrofit complexity in Mexico City's legacy building stock.
- New Construction:Greenfield industrial parks in Baja California, Nuevo León, and Jalisco enable optimized panel specification without structural constraints. Continuous lamination process improvements reduce production cycle times for these volume channels.
- Retrofit Projects:Existing commercial envelopes in Mexico City's dense industrial zones present structural load constraints and dimensional irregularities complicating panelized overlay installation. Skilled erector crew scarcity outside metropolitan centers extends project timelines.
- Prefabricated Units:Factory-controlled assembly environments enable precision envelope construction for modular building and clean room applications. CONAVI pilot programs are testing volume deployment for affordable housing.
- Mobile Installations:Temporary and relocatable temperature-controlled structures serve seasonal agricultural processing and emergency pharmaceutical storage needs.
New Construction dominates installation volume, while Prefabricated Units are climbing the fastest on modular building acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Inter-American Highway corridor and Lázaro Cárdenas port complex anchor Mexico's insulated panel distribution network, linking Pacific manufacturing zones to interior industrial markets.
Nuevo León
Automotive supplier parks and aerospace clusters drive clean room panel demand around Monterrey. SENER commercial building codes enforce continuous insulation strategies for new industrial construction. Apodaca and Santa Catarina industrial zones concentrate pharmaceutical logistics facilities requiring COFEPRIS-certified envelope systems.
Baja California
Cross-border agricultural export logistics fuel refrigerated warehouse construction across Tijuana and Mexicali. The state's proximity to California cold chain networks accelerates specification of hybrid polyisocyanurate-vacuum panel systems. Tecate and Ensenada distribution corridors are expanding automated temperature-controlled capacity for produce exports.
Jalisco
Guadalajara's electronics manufacturing base generates demand for clean room and modular building panels. CONAVI affordable housing pilots are testing structural insulated panel construction for rapid-assembly social housing. El Salto and Tlajomulco industrial parks are shifting procurement toward factory-engineered envelope systems.
Bajío Region
Querétaro and Guanajuato automotive corridors remain underpenetrated for technical panel specification relative to northern states. SENER energy efficiency amendments are compressing payback periods for premium thermal envelope investments. Silao and Irapuato supplier parks present first-mover positioning opportunities for certified panel distributors.
Northern Border States
Chihuahua and Coahuila maquiladora operations require temperature-controlled manufacturing environments for medical device and electronics production. COFEPRIS hygienic envelope mandates lock in metal-faced specifications for Ciudad Juárez and Saltillo processing facilities. The region's skilled erector crew scarcity extends project timelines for complex envelope installations.
Mexican Insulated Panels Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on raw material conversion. The Mexican insulated panel market structures around three distinct competitive tiers: international building envelope platforms with multi-country certification authority, regional fabricators optimizing continuous lamination throughput, and domestic distributors anchoring retrofit relationships. Consolidation pressure concentrates among mid-scale operators as EPC procurement centralization favors national framework agreements over regional distributor networks.
Within the international platform tier, Kingspan Group and Metl-Span occupy positions defined by technical specification authority and lead-time reliability. Industrias Unypanel SA DE CV exemplifies the domestic distributor archetype, leveraging regional relationships to anchor retrofit channel penetration. These three entities collectively represent the competitive spectrum spanning premium specification work, warehouse rollout velocity, and localized service density.
| Leading Market Players |
|---|
| Industrias Unypanel SA DE CV |
| Kingspan Group |
| Metl-Span |
| Centria |
| All Weather Insulated Panels |
| Metecno Group |
| PFB Corporation |
| Owens Corning |
| Green Span Profiles |
| Others |
Pricing and Supply Chain Analysis
Galvanized steel and aluminum coil supply concentrates in a limited number of international mills, anchoring margin pools with Mexican converters who face freight cost surges and currency fluctuation risk. This upstream concentration forces domestic panel fabricators to absorb input volatility or pass through costs to price-sensitive retrofit channels.
Pricing Analysis
SENER energy efficiency codes dictate the pricing tier structure across the Mexican insulated panel market. Three-tier pricing structure across premium, standard, and economy levels separates COFEPRIS-certified hygienic envelope systems from commodity warehouse panels. Price differentiation hinges on thermal performance certification and installation service bundling. Cost compression in the economy tier is intensifying because polyol and MDI feedstock volatility squeezes fabricator margins. Warehouse facility developers exhibit highest price sensitivity, while pharmaceutical EPCs prioritize validated performance documentation over unit cost.
Supply Chain Analysis
Extended payment terms from galvanized steel mills in South Korea, China, and the United States strain working capital for Mexican panel converters. Rigid foam insulation cores draw from petrochemical feedstocks anchored in Gulf Coast and Asian refining complexes. Single-source vulnerability for facing substrates exposes fabricators to tariff exposure on aluminum coil imports. Distribution runs through regional distributor networks serving Monterrey and Guadalajara industrial corridors, with EPC framework agreements increasingly bypassing traditional channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent panel manufacturers must defend against substitution from field-assembled insulation systems as SENER codes mandate continuous envelope strategies. The threat of conventional built-up roofing displacing metal-faced retrofits looms where skilled erector crew scarcity extends project timelines.
For Market Incumbents: Entrench specification authority through COFEPRIS certification investment for hygienic envelope systems serving Monterrey pharmaceutical clusters. Backward integration into polyol compounding cushions margin pressure from petrochemical feedstock volatility. Capacity addition in Baja California locks in cross-border agricultural export logistics demand before regional fabricators capture share.
For New Entrants and Emerging Players: Establish a beachhead in Querétaro and Guanajuato automotive supplier parks where clean room panel specification remains underpenetrated relative to northern states. Technical sales investment targeting aerospace cluster procurement committees bypasses entrenched distributor relationships. Modular housing channels through CONAVI pilot programs offer volume scale without competing against Kingspan and Metl-Span in premium cold storage.
For Investors and Strategic Acquirers: Capital is best deployed toward domestic distributors with deep regional erector crew networks and CONAVI program relationships. Long-term viability over the projection horizon rests on positioning for building code harmonization with IECC standards that would elevate dual-certified domestic manufacturers. Watch for SENER amendments accelerating import substitution mandates as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Certification Investment | Locks in pharmaceutical and food processing specification authority in Monterrey production zones. |
| Backward Integration into Polyol Compounding | Cushions margin compression from MDI feedstock volatility in Gulf Coast petrochemical markets. |
| Querétaro Technical Sales Expansion | Captures first-mover positioning in underpenetrated automotive clean room panel specification. |
| CONAVI Modular Housing Partnership | Opens volume channels beyond traditional commercial construction through social housing pilots. |
| EPC Framework Agreement Negotiation | Centralizes envelope material selection authority as national procurement patterns consolidate. |
Research Methodology
Operator-level perspectives from cold storage developers, EPC procurement managers, panel fabricator plant directors, and CONAVI program administrators anchored the qualitative base. Primary interviews combined with secondary validation from SENER regulatory filings, COFEPRIS hygienic envelope standards, customs trade data on steel and aluminum coil imports, and industrial construction permit databases. Bottom-up demand modeling across Baja California, Nuevo León, and Jalisco triangulated against top-down market sizing.
Scenario-bracketing around polyol price volatility bands and SENER code amendment timelines shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, application, end user, and installation type alongside regional regulatory cluster intensity. CAGRs derived from installed base growth rates and replacement cycle analysis incorporated cold storage construction pipeline data and pharmaceutical logistics investment flows.
Stress conditions across MDI feedstock pricing, peso-dollar exchange rate bands, and SENER enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on code harmonization timing and skilled labor availability expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Honeycomb Sandwich Panels Market
Building & Construction Materials
Education Building Design Market
Building & Construction Materials
Magnesium Oxide Boards Market
Building & Construction Materials
Elevated Water Storage Tanks Market
Building & Construction Materials
Building Insulation Materials Market
Building & Construction Materials
Saudi Arabia Tiles Market
Building & Construction Materials
Concrete Cooling Market
Building & Construction Materials
Soil Stabilization Market
Building & Construction Materials
Japan Concrete Conditioner Market
Building & Construction Materials
GRC Conduit Fittings Market
Building & Construction Materials
Europe Construction Repair and Rehabilitation Chemicals Market
Building & Construction Materials
Global Steel Wire Rod Market
Building & Construction Materials
Fiberglass Light Poles Market
Building & Construction Materials
US Steel Rebar Market
Building & Construction Materials
Gypsum and Drywall Market
Building & Construction Materials
Quarry Tiles Market