
 Lightweight Composite External Access Panels and Doors Market | 2026-2036
Lightweight Composite External Access Panels and Doors Market Size, Share, and Industry Trends Forecast 2026-2036
Lightweight Composite External Access Panels and Doors Market Insights
Automated fiber placement and out-of-autoclave curing is narrowing the cost gap between thermoset and thermoplastic composite panels, enabling broader adoption across commercial and defense platforms. GKN Aerospace leverages its proprietary manufacturing processes to sustain leadership in large structural access door assemblies for single-aisle aircraft. Safran anchors its position through integrated design-to-build capabilities that span material qualification and airframe integration. Daher competes by specializing in complex, low-rate production panels for business jet and rotorcraft applications where customization commands premium positioning.
Lightweight composite external access panels and doors are structural closures manufactured from fiber-reinforced polymer matrices, typically carbon fiber or glass fiber prepregs with epoxy or thermoplastic resins, engineered to specific strength-to-weight ratios and fire-smoke-toxicity standards for external mounting on vehicles, vessels, and equipment enclosures. These components serve primarily to protect internal systems while minimizing parasitic weight, with aerospace applications demanding specific impact resistance and pressure cycling performance under FAR 25.571 damage tolerance requirements. Carbon fiber panels dominate aerospace enclosures where specific stiffness requirements justify material costs, while glass fiber solutions occupy marine hatches and telecommunications cabinets where corrosion resistance and electrical insulation take priority over absolute weight savings. Recessed installation types are gaining share in transportation compartments and infrastructure applications where aerodynamic or aesthetic flush surfaces reduce drag and improve sealing performance against environmental ingress.
FAA certification standards under 14 CFR Part 25, EASA CS-25 airworthiness codes, and ISO 2685 fire resistance test protocols collectively dictate material selection, testing regimes, and production qualification pathways for external access panels in commercial aviation. Maritime applications face additional compliance layers from Lloyd's Register and DNV classification society rules for fire integrity and watertight performance in hull and deck-mounted hatches. Stakeholders must monitor evolving EPA and REACH restrictions on resin chemistries and brominated flame retardants, as regulatory shifts in allowable material constituents will force reformulation investments and supplier requalification cycles.
Market Dynamics
Automated fiber placement and out-of-autoclave curing processes are compressing manufacturing cycle times for carbon fiber access panels, altering competitive economics between thermoset and thermoplastic solutions across aerospace procurement programs.
Growth Catalysts
- FAA 14 CFR Part 25 damage tolerance mandates:Airworthiness requirements for impact resistance and fatigue cycling are forcing aluminum replacement with carbon fiber reinforced polymer panels in next-generation narrowbody programs.
- Seattle-Wichita aerospace manufacturing corridor:OEM final assembly concentration around Boeing and Spirit AeroSystems operations is pulling composite panel suppliers into co-location strategies for just-in-time delivery.
- Out-of-autoclave thermoplastic processing:Elimination of autoclave curing cycles reduces energy input and tooling costs, enabling mid-tier suppliers to qualify for commercial aviation contracts previously reserved for vertically integrated manufacturers.
Market Restraints
- Carbon fiber precursor cost volatility:Polyacrylonitrile feedstock prices fluctuate with acrylonitrile monomer supply, compressing margins for panel fabricators locked into fixed-price aerospace contracts.
- Japanese carbon fiber supply concentration:Toray, Teijin, and Mitsubishi Chemical command dominant positions in aerospace-grade precursor and tow production, creating single-source vulnerability for qualified material streams.
- Brominated flame retardant REACH restrictions:ECHA substance evaluation under SVHC protocols is forcing reformulation of epoxy resin systems, triggering 18-24 month requalification cycles with airframe OEMs.
Strategic Opportunities
- Urban air mobility airframe programs:Electric vertical take-off and landing manufacturers require certified lightweight access solutions at production volumes below traditional commercial aviation minimums, opening tier-two supplier participation.
- India PLI scheme for aerospace components:Production-linked incentive structures for defense and civil aviation manufacturing are attracting composite panel investments around Bangalore and Hyderabad industrial corridors.
- Maritime wind turbine service vessel hatches:Offshore wind installation fleets require corrosion-resistant, lightweight deck access solutions where glass fiber composites displace steel at lower certification burden than aviation applications.
Industry Challenges
- Automated fiber placement technician scarcity:Programming and operation of multi-axis AFP systems requires specialized composite manufacturing expertise concentrated among legacy aerospace workforces nearing retirement.
- Damage tolerance certification timeline compression:FAA and EASA are synchronizing fatigue test protocols but diverging on impactor energy levels, forcing dual test matrices for global platform qualification.
- Legacy airframe repair data interoperability:Digital thread requirements for structural health monitoring clash with paper-based maintenance records on in-service fleets, complicating retrofitted panel traceability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lightweight Composite External Access Panels and Doors Market |
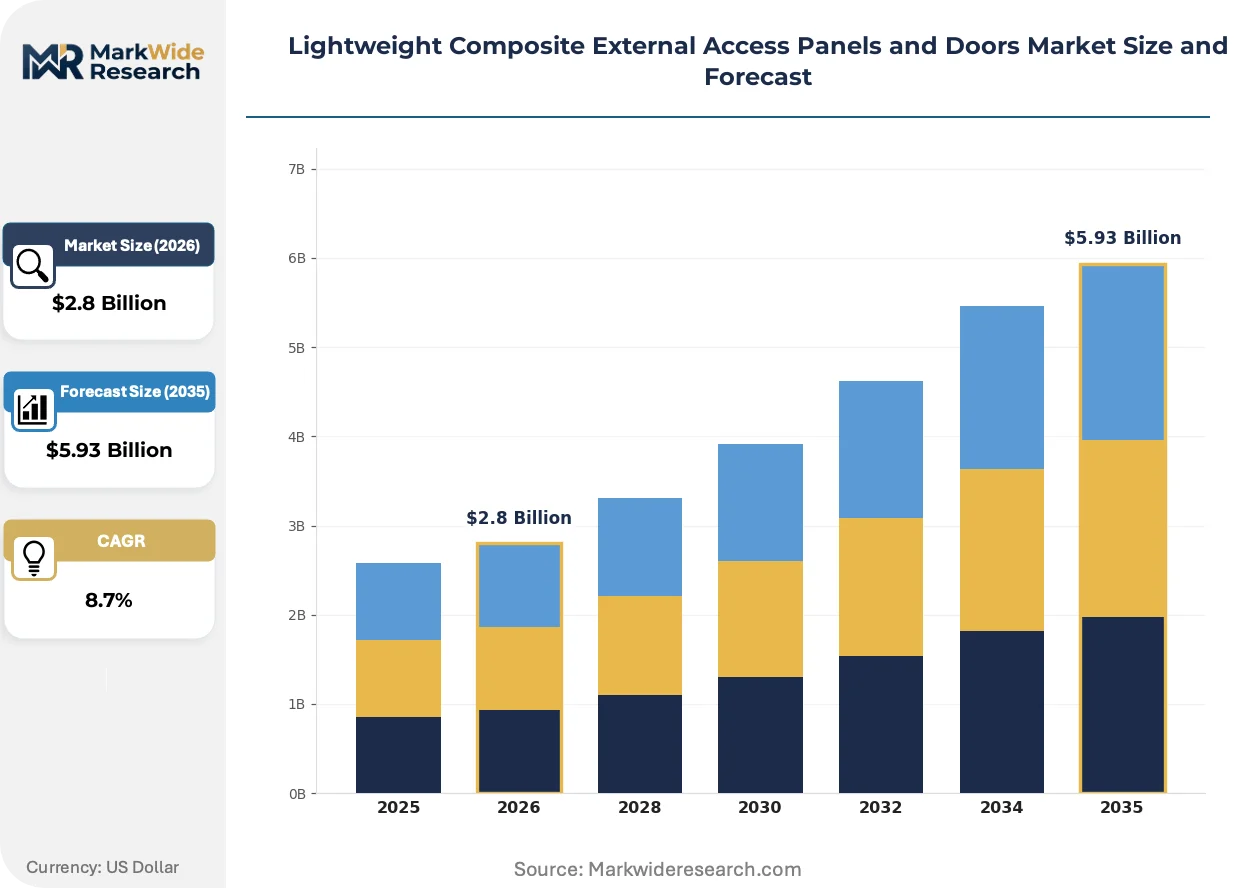
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Carbon Fiber, Glass Fiber, Aramid Fiber, Basalt Fiber, Hybrid Composites Application: Aerospace Enclosures, Marine Hatches, Telecommunications Cabinets, Electrical Enclosures, Transportation Compartments Installation Type: Surface Mounted, Recessed, Hinged, Sliding, Detachable End User Industry: Aerospace, Maritime, Telecommunications, Transportation, Infrastructure |
| Companies Covered | Astronics PECO, Sonaca, Daher, Latécoère, GKN Aerospace, Hutchinson, Triumph Group, Safran, Spirit AeroSystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lightweight Composite External Access Panels and Doors Market Trends and Innovations
Material-process combinations and certification digitization are restructuring how composite access panels move from qualification to serial production, with implications for supplier tier positioning and buyer procurement leverage.
Thermoplastic composite tapes with continuous carbon fiber reinforcement are hybridizing with selective laser melting metallic inserts to create unitized access door assemblies. Regional jet manufacturers in Canada and Brazil are adopting these hybrid structures for emergency exit applications where metallic hinge and latch hardware must integrate seamlessly with composite skins. This convergence is compressing part count and assembly labor content while expanding the addressable market for mid-tier composite specialists previously excluded from primary structure contracts.
EASA CS-25 Amendment 26 introduces explicit requirements for fire resistance testing of access panels in pressurized compartments, extending ISO 2685 flame penetration protocols to previously exempt door categories. European narrowbody retrofit programs must now demonstrate compliance with revised burn-through resistance standards, triggering material substitution away from standard epoxy systems toward phenolic and bismaleimide matrices. Affected operators are consolidating procurement through MRO providers with in-house fire test capabilities rather than分散 qualification across multiple panel suppliers.
Airframe OEMs are consolidating external access panel procurement through designated tier-one aerostructures integrators, compressing direct supplier relationships and shifting commercial terms toward long-term performance agreements. This concentration displaces historical spot-buying patterns for spares and retrofits, favoring suppliers with captive repair station networks and airworthiness release authority. The shift is most visible in United States and France, where Boeing and Airbus have respectively consolidated supply bases around Wichita and Toulouse corridor partners with integrated design-to-build capabilities.
Lightweight Composite External Access Panels and Doors Market Segmentation
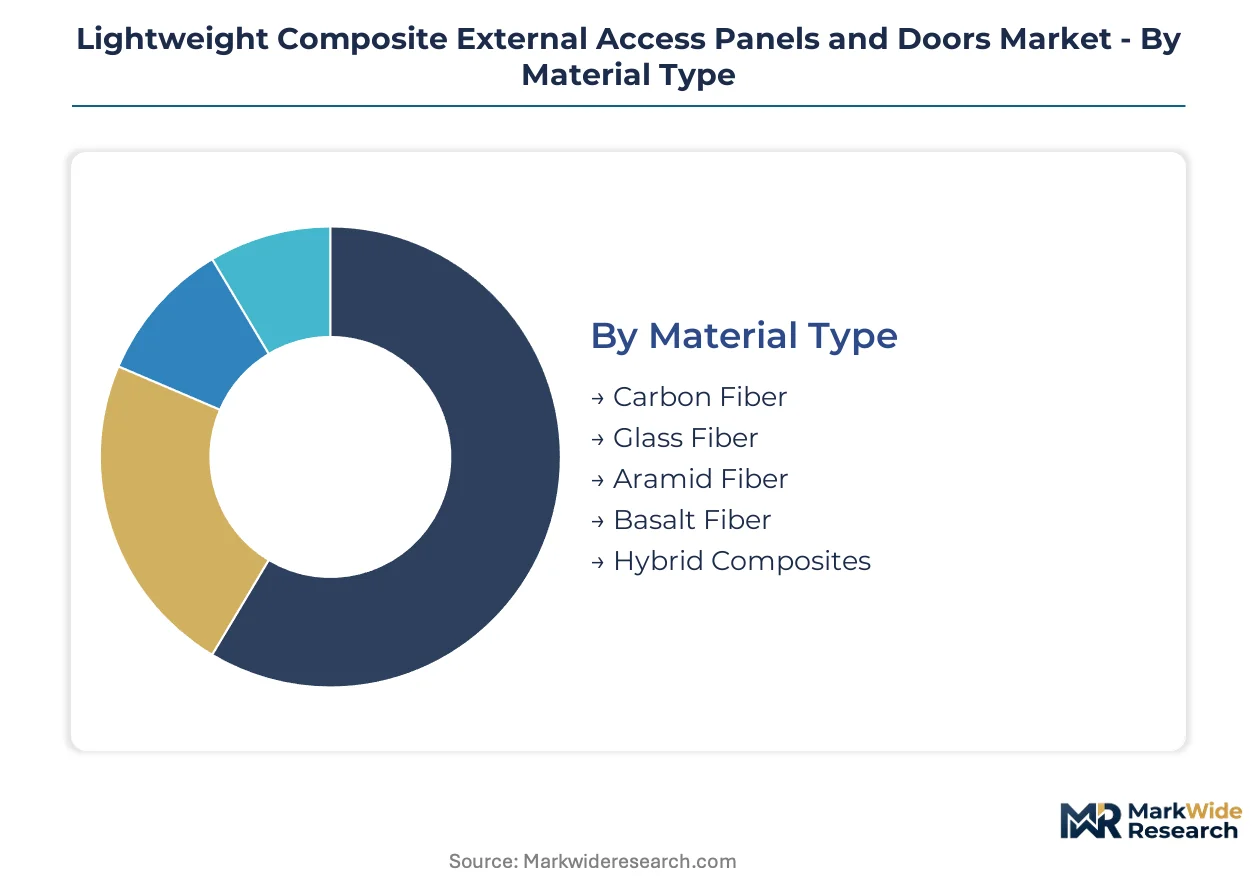
Segmentation in this market tracks material qualification pathways and certification burden across end-use verticals. Procurement specifications diverge sharply between aerospace damage tolerance requirements and maritime corrosion resistance standards, creating distinct supplier positioning strategies.
Material Type:
Mature carbon fiber formulations dominate qualification-heavy applications while emerging alternatives reshape cost-performance tradeoffs in less regulated sectors.
- Carbon Fiber:Aerospace-grade prepregs with epoxy or thermoplastic matrices deliver specific stiffness ratios required for pressurized compartment doors under FAA damage tolerance mandates. Demand concentrates in Seattle and Toulouse manufacturing corridors where Boeing and Airbus narrowbody programs specify Toray T800S and equivalent tow grades.
- Glass Fiber:E-glass and S-glass reinforced polyester or vinyl ester systems occupy marine hatches and telecommunications cabinets where electrical insulation and saltwater corrosion resistance outweigh absolute weight savings. European offshore wind service vessel fleets around Rotterdam and Bremerhaven drive specification of DNV-GL certified glass fiber deck access solutions.
- Aramid Fiber:Kevlar and Twaron reinforcements serve ballistic-rated military vehicle access panels where fragment resistance combines with weight reduction.
- Basalt Fiber:Russian and Ukrainian-sourced basalt roving supplies face disruption, compressing availability for infrastructure applications in Central Asian markets.
- Hybrid Composites:Carbon-glass hybrid laminates balance cost and performance for regional jet programs in Brazil and Canada.
Carbon fiber handles the majority of throughput; basalt fiber is the fastest mover on share.
Application:
Certification intensity varies dramatically across end-use contexts, with aviation applications demanding multi-year qualification cycles that freeze material specifications.
- Aerospace Enclosures:Nacelle access doors, cargo compartment panels, and avionics bay closures must demonstrate fatigue cycling performance under FAR 25.571 and EASA CS-25 Amendment 26 fire resistance protocols. Surface quality and lightning strike conductivity specifications restrict qualified supplier pools.
- Marine Hatches:Glass fiber composite deck and bulkhead access solutions face Lloyd's Register and DNV classification society rules for watertight integrity, with lower testing burden than aviation equivalents enabling faster supplier entry.
- Telecommunications Cabinets:Electrical enclosure panels prioritize electromagnetic interference shielding and UV stability over structural loading, with glass fiber polyester systems standard for 5G infrastructure deployments.
- Electrical Enclosures:Arc flash containment and dielectric strength requirements drive specification of glass fiber and aramid-reinforced systems for utility substation applications.
- Transportation Compartments:Rail and bus external access panels balance impact resistance with aesthetic surface finish, with thermoplastic composites gaining share for interior-exterior integration.
Aerospace enclosures command premium positioning; telecommunications cabinets are expanding most quickly on volume.
Installation Type:
Mechanical integration complexity determines assembly labor content and field service requirements across platform categories.
- Surface Mounted:Flange-fastened panels with exposed gasket seals dominate legacy airframe retrofits and industrial equipment where aerodynamic drag is non-critical.
- Recessed:Flush-mounted solutions with integrated drainage channels are gaining specification in next-generation narrowbody programs and high-speed rail applications where drag reduction and aesthetic continuity drive design.
- Hinged:Integral hinge designs with continuous fiber reinforcement reduce part count in frequently accessed compartments such as avionics bays and engine nacelles.
- Sliding:Track-mounted panels serve space-constrained marine and transportation applications where swing radius is limited.
- Detachable:Quick-release fastening systems support rapid maintenance access in military and emergency vehicle applications.
Surface mounted retains volume leadership; recessed solutions are climbing the fastest on specification share.
End User Industry:
Procurement concentration and qualification timelines create tiered supplier access patterns across vertical demand pools.
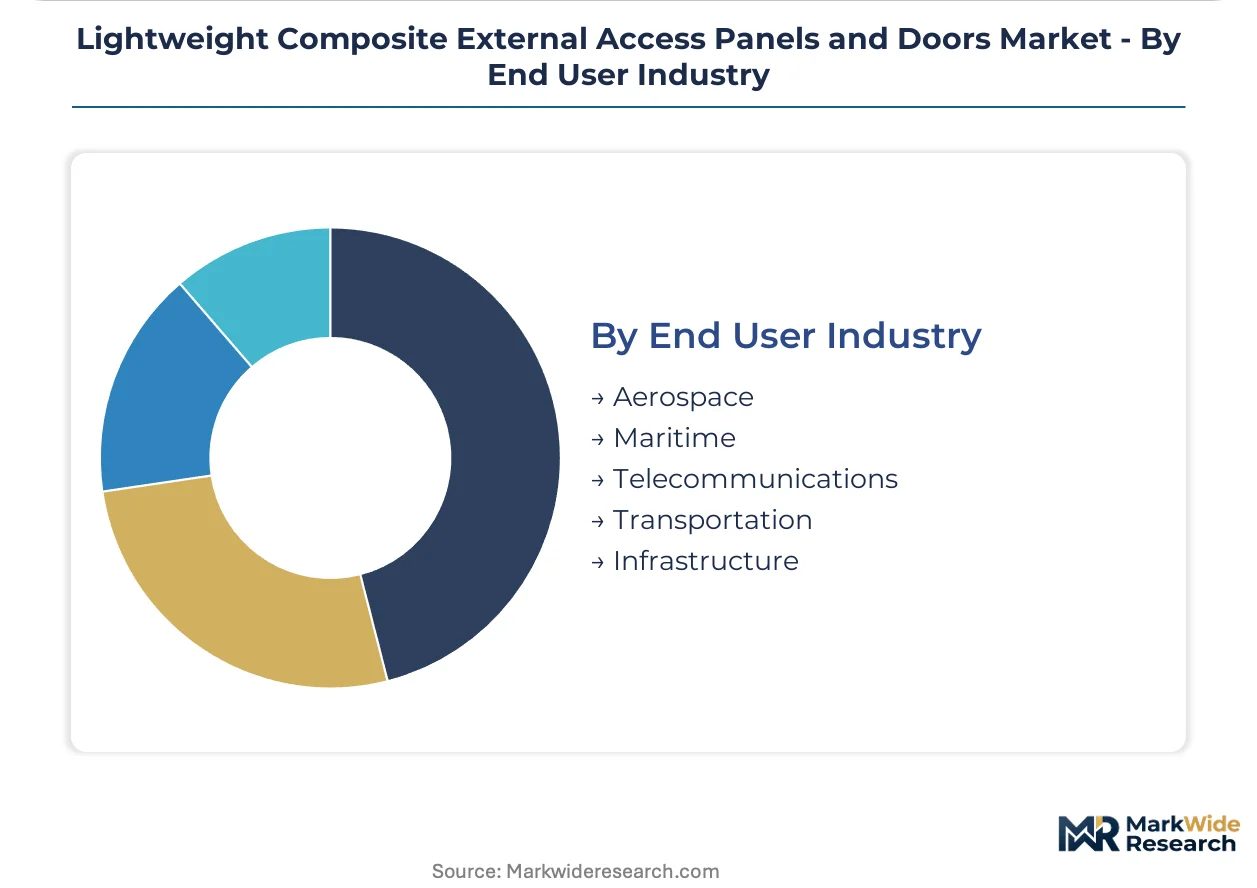
- Aerospace:OEM direct procurement and tier-one aerostructures integrator consolidation around Wichita and Toulouse corridors compress spot-buying opportunities. Long-term performance agreements with Boeing, Airbus, and Bombardier freeze material specifications for program durations.
- Maritime:Shipyard build contracts and fleet operator retrofit programs in Germany, Norway, and South Korea drive demand for corrosion-resistant deck solutions with shorter qualification cycles than aviation.
- Telecommunications:Tower company infrastructure rollouts and data center construction in India and Southeast Asia generate volume demand for standardized enclosure panels with minimal customization.
- Transportation:Rail OEM specifications in France, Germany, and Japan and bus manufacturer requirements in China create fragmented demand with regional certification variations.
- Infrastructure:Bridge inspection hatches, utility vault covers, and building facade access panels face municipal procurement standards with lowest certification burden of all verticals.
Aerospace absorbs the highest value concentration; telecommunications is the steepest expansion trajectory on unit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German composite panel exports flow primarily to Airbus final assembly lines in France and Hamburg, while US suppliers around Seattle and Wichita serve Boeing narrowbody programs with just-in-time logistics.
United States
Seattle and Wichita aerospace manufacturing corridors concentrate demand for carbon fiber access panels on 737 MAX and 777X programs. FAA 14 CFR Part 25 damage tolerance mandates force aluminum replacement in next-generation airframes. Spirit AeroSystems operations in Kansas pull tier-two composite suppliers into co-location strategies for reduced logistics costs.
France
Toulouse anchors European demand through Airbus A320 and A350 final assembly, with Latécoère and Daher maintaining integrated design-to-build capabilities. EASA CS-25 Amendment 26 fire resistance requirements extend ISO 2685 protocols to previously exempt door categories. The Occitanie aerospace cluster around Toulouse-Blagnac drives specification of phenolic matrix systems for burn-through compliance.
Germany
Hamburg Finkenwerder operations specialize in A320 family fuselage sections and cabin outfitting, creating demand for recessed installation panels. REACH SVHC evaluations on brominated flame retardants trigger 18-24 month resin reformulation cycles with airframe OEMs. Premium Aerotec and related suppliers in Bavaria and northern Germany consolidate procurement relationships through long-term performance agreements.
China
COMAC C919 production ramp-up generates qualified supplier opportunities for thermoplastic composite access solutions on indigenous narrowbody platforms. MIIT civil aviation certification requirements align with FAA and EASA standards but impose additional domestic testing protocols. The Shanghai Pudong and Tianjin aerospace industrial zones attract joint ventures from established Western tier-one integrators seeking local content compliance.
India
Bangalore and Hyderabad industrial corridors benefit from PLI scheme incentives for aerospace component manufacturing, including composite panel qualification for defense and civil aviation. DGFT export obligation structures encourage foreign OEMs to establish domestic sourcing for regional jet and helicopter programs. Tata Advanced Systems and related entities build captive composite capabilities to serve Airbus and Boeing offset commitments.
Lightweight Composite External Access Panels and Doors Market Competitive Landscape
On the supply side, the industry is consolidating around tier-one aerostructures integrators with captive airworthiness release authority and repair station networks. Boeing and Airbus procurement concentration in Wichita and Toulouse corridors compresses direct supplier relationships and freezes material specifications for program durations. Two strategic archetypes dominate: vertically integrated aerostructures specialists with full design-to-build capabilities, and focused composite fabricators occupying niche low-rate production segments. Competitive moves center on long-term performance agreements replacing spot-buying patterns, and M&A activity targeting repair station networks for aftermarket capture.
Among established European aerostructures integrators, GKN Aerospace and Safran exemplify the vertically integrated archetype with proprietary manufacturing processes spanning material qualification to airframe integration. Daher occupies a specialized position in complex, low-rate production panels where customization commands premium positioning outside high-volume commercial aviation procurement. These three entities anchor competitive dynamics across the certification-heavy aerospace enclosure segment.
| Leading Market Players |
|---|
| Astronics PECO |
| Sonaca |
| Daher |
| Latécoère |
| GKN Aerospace |
| Hutchinson |
| Triumph Group |
| Safran |
| Spirit AeroSystems |
| Others |
Pricing and Supply Chain Analysis
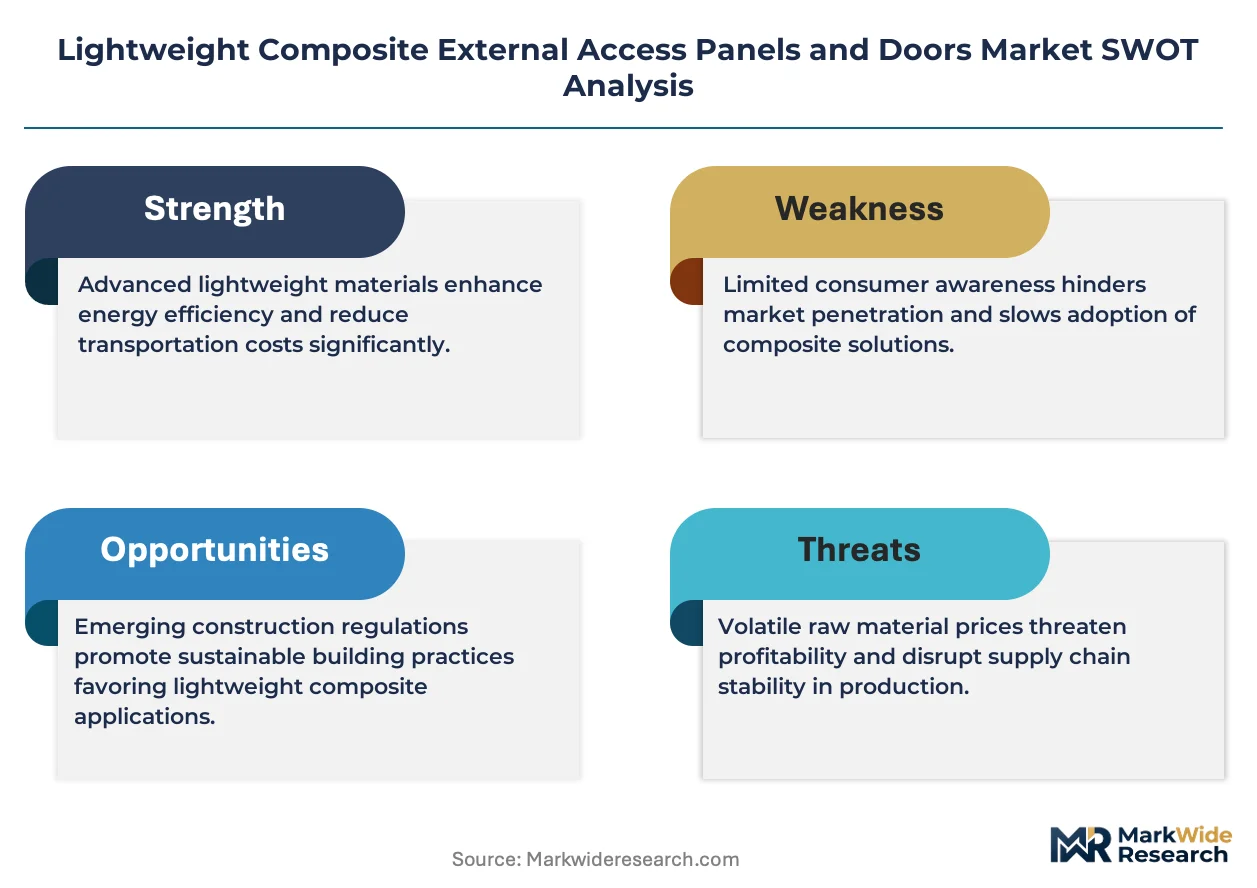
Japanese carbon fiber precursor concentration determines both the spread between aerospace-grade and industrial-grade panel pricing and the geographic shape of qualified supplier networks. Toray, Teijin, and Mitsubishi Chemical's dominance in polyacrylonitrile tow production creates single-source vulnerability that compresses margins for fabricators locked into fixed-price OEM contracts while inflating premiums for dual-qualified material streams.
Pricing Analysis
Current-generation thermoset epoxy panels, prior-generation autoclave-cured assemblies, and next-generation out-of-autoclave thermoplastic solutions occupy distinct pricing tiers separated by certification burden and processing efficiency. Three-tier pricing structure across premium, standard, and economy levels reflects FAA damage tolerance qualification status, with aerospace-grade carbon fiber panels commanding multiples over glass fiber marine equivalents. Cost compression in mid-tier thermoplastic segments is intensifying because automated fiber placement narrows the manufacturing economics gap with legacy thermosets. Defense and business jet operators show lowest price sensitivity due to performance mandates, while telecommunications infrastructure buyers prioritize unit cost over qualification depth.
Supply Chain Analysis
Polyacrylonitrile precursor manufacturing concentrates in Japan, the United States, and Germany, with carbon fiber conversion facilities clustering near aerospace OEM final assembly corridors. Qualified panel fabrication draws from Toray T800S tow, Huntsman epoxy resin systems, and Victrex thermoplastic tapes as primary inputs. Single-source vulnerability in Japanese precursor supply creates structural risk for Boeing and Airbus tier-one suppliers dependent on qualified material streams. Distribution runs through designated aerostructures integrators with captive airworthiness release authority, compressing direct procurement relationships and shifting commercial terms toward long-term performance agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital thread integration across airframe OEMs and MRO providers is creating platform-economics inflection where structural health monitoring interoperability becomes the decisive competitive moat. This shift favors suppliers with embedded software capabilities and repair station network density over pure manufacturing scale.
For Market Incumbents: Harden qualification moats by deepening backward integration into thermoplastic tape production and expanding captive repair station networks in Wichita and Toulouse corridors. Out-of-autoclave process expertise represents the priority defensive lever against mid-tier suppliers achieving FAA certification. Consolidate procurement relationships through long-term performance agreements that freeze material specifications and displace spot-buying patterns for retrofits.
For New Entrants and Emerging Players: Establish a beachhead in urban air mobility access panel segments where production volumes fall below traditional commercial aviation minimums and tier-two qualification pathways remain open. Maritime wind turbine service vessel hatches offer faster entry with DNV certification burden substantially below FAA damage tolerance mandates. Target glass fiber composite solutions for offshore wind fleets around Rotterdam and Bremerhaven where corrosion resistance specifications favor new supplier qualification.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated aerostructures specialists with design-to-build capabilities and airworthiness release authority. Long-term viability over the next decade hinges on capturing aftermarket repair and retrofit revenue streams through embedded structural health monitoring. Watch for EASA-FAA harmonization divergence on impactor energy levels as the signal indicating qualification timeline compression and dual-test matrix cost burdens.
| Strategic Initiative | Industry Significance |
|---|---|
| Out-of-Autoclave Process Qualification | Eliminates energy-intensive curing cycles, enabling mid-tier suppliers to compete for Boeing and Airbus contracts. |
| Thermoplastic Composite Tape Integration | Hybridizes with metallic inserts for unitized door assemblies, compressing part count in regional jet programs. |
| Repair Station Network Expansion | Captures aftermarket retrofit demand as EASA CS-25 Amendment 26 triggers material substitution cycles. |
| Digital Thread Infrastructure | Resolves legacy airframe repair data interoperability gaps for structural health monitoring retrofits. |
| India PLI Scheme Localization | Positions suppliers for COMAC C919 and indigenous narrowbody content requirements around Bangalore. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with composite manufacturing engineers, aerostructures procurement leads at Boeing and Airbus tier-one integrators, FAA designated engineering representatives, and MRO facility managers. Secondary validation drew from FAA 14 CFR Part 25 airworthiness directives, EASA CS-25 amendment documentation, ISO 2685 fire resistance test protocols, and customs trade data for carbon fiber precursor flows. Bottom-up sizing of qualified supplier capacities was triangulated against top-down OEM procurement estimates across the analysis window.
Calibration against historical program delays and certification timeline slippage informed the projection framework. Segmentation modeling tracked material type, application vertical, installation complexity, and end-user industry procurement concentration throughout the forecast period. CAGRs were derived from production ramp schedules for next-generation narrowbody platforms and retrofit cycle timing for fire resistance compliance. Industry-specific inputs included Spirit AeroSystems supplier consolidation patterns and COMAC C919 production qualification milestones.
Macroeconomic conditions sit as an overlay; deviation in aerospace capital expenditure cycles, acrylonitrile monomer pricing, or REACH regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about qualification timeline compression and thermoplastic adoption curves. Material shifts in EASA-FAA harmonization protocols or Japanese precursor supply disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Formwork Market
Building & Construction Materials
Moisture Resistant Plaster Boards Market
Building & Construction Materials
Windows and Doors Market
Building & Construction Materials
US Plywood Market
Building & Construction Materials
Rubber Expansion Joints Market
Building & Construction Materials
United States Gutter Guards Market
Building & Construction Materials
Asphalt Modifiers Market
Building & Construction Materials
Geosynthetics Market
Building & Construction Materials
Asia-Pacific Flanges Market
Building & Construction Materials
Rebars Market
Building & Construction Materials
External Wall Insulation Board Market
Building & Construction Materials
Glue-Laminated Timber Market
Building & Construction Materials
Thinset Mortar Market
Building & Construction Materials
Latex Caulk Market
Building & Construction Materials
India Ready-Mix Concrete Market
Building & Construction Materials
Cement Grinding Aids Market