
 Decorative Tiles Market | 2026-2036
Decorative Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Decorative Tiles Market Intelligence
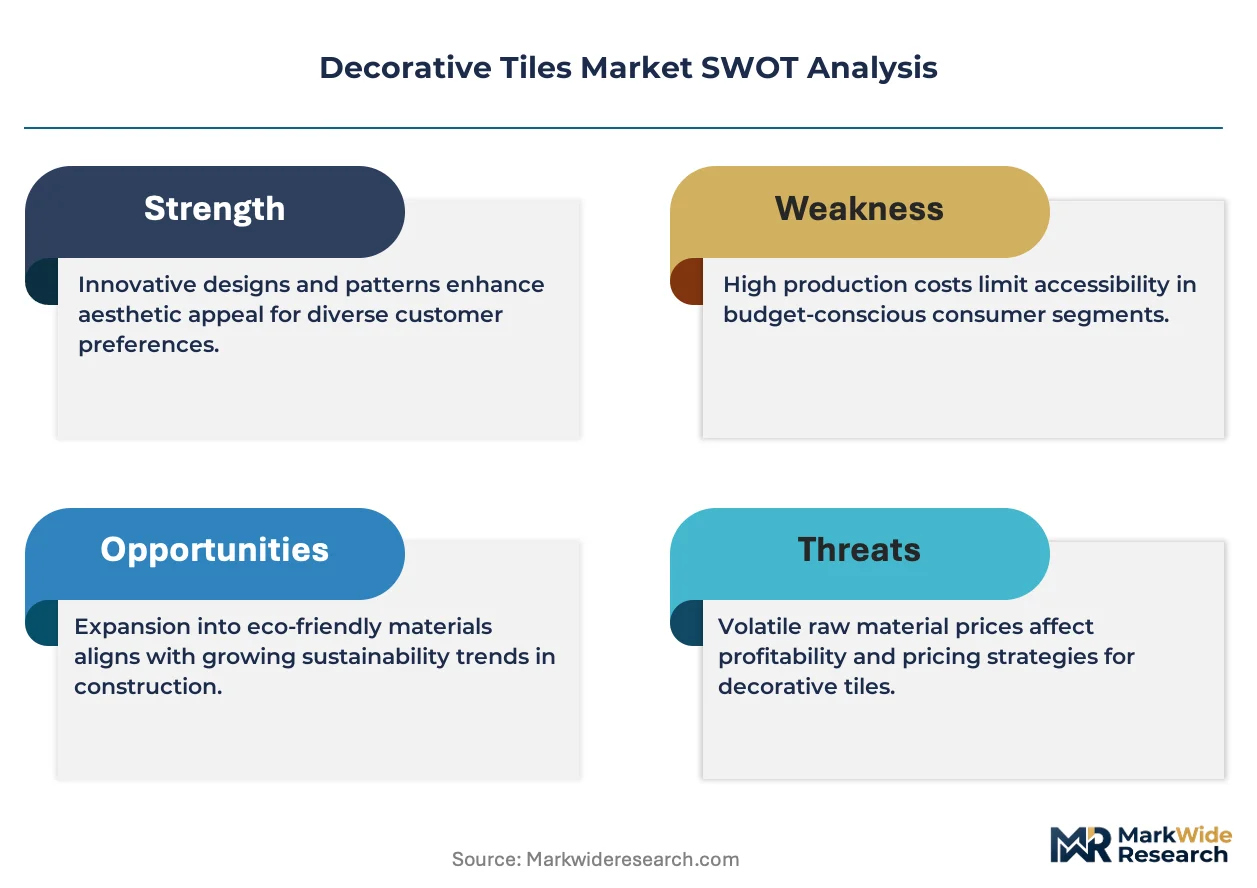
Digital printing technology, allowing for intricate and customized patterns, is fragmenting the traditional mass-produced tile market. Mohawk Industries leverages its extensive distribution network to serve both residential and commercial sectors across North America. Kajaria Ceramics specializes in the Indian domestic market with a focus on porcelain and ceramic varieties. RAK Ceramics competes on a global scale with a broad portfolio that serves diverse architectural needs in Europe and the Middle East.
Decorative tiles are surfacing materials designed primarily for aesthetic appeal in architectural applications. These products are characterized by specific glazes, textures, or printed patterns applied to a ceramic, porcelain, or glass substrate before firing to enhance interior and exterior spaces. Porcelain tiles lead the product segment due to superior durability and water resistance, making them suitable for both flooring and wall coverings. The residential buildings segment remains the largest end user, though demand from commercial complexes is expanding rapidly.
International Organization for Standardization (ISO) 13006 specifies quality and performance criteria for ceramic tiles globally. In Europe, CE marking is mandatory, indicating compliance with health and safety requirements, while in the United States, EPA guidelines on volatile organic compounds influence installation materials. Stakeholder success will be shaped by navigating regional material content regulations and adapting to shifts in consumer preference for sustainable and artisanal designs.
Market Dynamics
The central structural force shaping the decorative tiles market is the widespread adoption of digital printing technology. This innovation is fragmenting the mass-production model by enabling cost-effective, small-batch customization, fundamentally altering competitive dynamics and aesthetic possibilities for designers and end users.
Growth Catalysts
- Urban Construction Projects:Extensive residential and commercial construction, particularly in urban centers across India and other parts of Southeast Asia, is a primary demand driver for all types of decorative tiles.
- Hospitality Sector Renovation:Aesthetic upgrades in hotels, resorts, and restaurants to create unique, brand-aligned environments are spurring demand for customized and high-end decorative tiles, especially those produced with digital printing.
- Sustainability Mandates:The EU's Corporate Sustainability Reporting Directive (CSRD) is increasing demand for tiles with verified recycled content and transparently sourced raw materials, creating a premium for sustainable products.
Market Restraints
- Energy Cost Volatility:The production of ceramic and porcelain tiles is highly energy-intensive, making manufacturers' profit margins vulnerable to fluctuations in the price of natural gas used for firing kilns.
- Substitution from Resilient Flooring:Luxury vinyl tile (LVT) and other resilient flooring products present a significant substitution threat, offering lower installation costs and comparable aesthetics in certain residential and light commercial applications.
- Fragmented Regulatory Compliance:Navigating disparate international standards, such as ISO 13006, European CE marking, and country-specific requirements like BIS in India, increases complexity and cost for global manufacturers.
Strategic Opportunities
- New Product Formats:The development of large-format, thin porcelain slabs opens new applications beyond traditional flooring, including countertops, exterior building facades, and furniture cladding, competing with natural stone and solid surfaces.
- Geographic Expansion:Untapped demand in Latin American markets, including Brazil and Mexico, offers significant growth potential as a rising middle class and expanding tourism sector drive new construction and renovation.
- Channel Disintermediation:Direct-to-consumer (DTC) e-commerce channels provide a route to market for artisanal and specialized tile producers, allowing them to bypass traditional distributors and connect directly with designers and homeowners.
Industry Challenges
- Capital-Intensive Upgrades:Remaining competitive requires continuous and significant capital investment in advanced digital printing equipment, larger-format presses, and energy-efficient kilns, creating high barriers to entry and for smaller players.
- Installation Skill Shortage:A lack of trained installers proficient in handling large-format tiles and executing complex patterns can lead to installation failures, limiting the adoption of higher-value products.
- Certification Lead Times:The lengthy and costly process of obtaining environmental product declarations (EPDs) and other sustainability certifications can delay the market entry of new, innovative green building materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decorative Tiles Market |
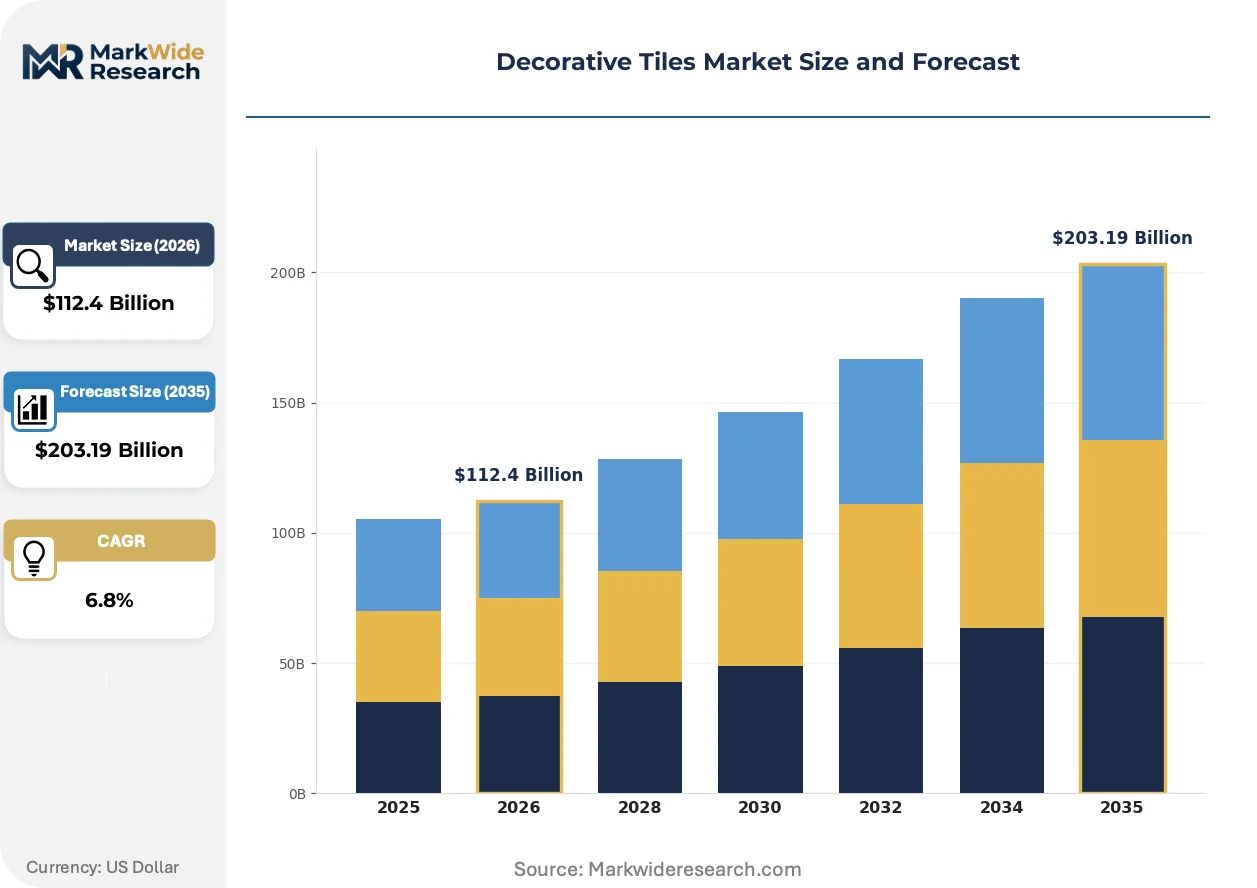
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $203.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic, Porcelain, Glass, Marble, Mosaic, Terracotta Application: Wall Coverings, Flooring, Backsplashes, Outdoor Patios, Accent Walls, Countertops Material: Clay, Natural Stone, Quartz, Crushed Glass, Metal, Composite End User: Residential Buildings, Commercial Complexes, Hospitality Venues, Educational Institutions, Government Facilities, Healthcare Centers |
| Companies Covered | Marazzi, RAK Ceramics, Mohawk Industries, Kajaria Ceramics, Marco Polo, Grupo Lamosa, Daltile, Florim, Porcelanosa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decorative Tiles Market Strategic Shifts & Innovations
Material science and digital workflows are merging, enabling tiles to serve both structural and aesthetic functions. This convergence allows for unprecedented customization while addressing sustainability mandates from regulators and specifiers across the construction industry.
Advanced 3D and digital printing technologies replicate natural materials like marble and wood on porcelain substrates. Commercial end-users in hospitality and retail are rapidly adopting these for consistent quality and lower cost. This technology is virtualizing the supply chain for exotic materials, decoupling high-end aesthetics from the logistical constraints of natural stone.
The European Union's Corporate Sustainability Reporting Directive (CSRD) mandates detailed disclosure on environmental impacts. This compels manufacturers to verify recycled content and production footprints. The porcelain tile segment is most affected, with producers investing in lifecycle assessments to maintain access to the EU market.
A shift in preference towards unique, artisanal designs is challenging mass-produced patterns. This disrupts traditional retail by creating demand for specialized design studios and direct-to-consumer platforms. This trend is most visible in high-end residential projects in North America and Western Europe seeking personalized finishes.
Decorative Tiles Market Segmentation
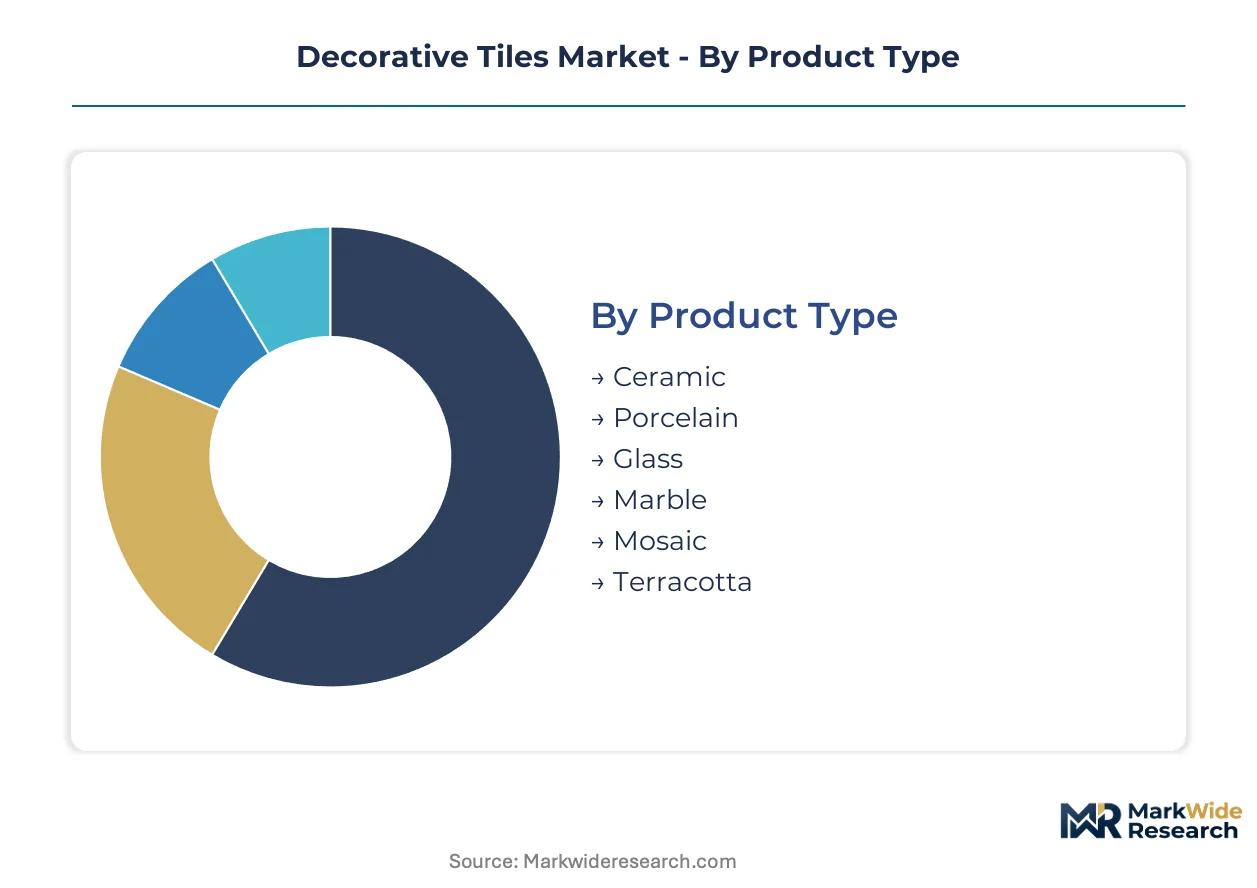
The decorative tiles market is structured by distinct product attributes, application areas, foundational materials, and end-user types. Understanding these segments reveals specific demand patterns and competitive landscapes. Each category reflects varying technical specifications and aesthetic requirements across diverse construction projects.
Product Type:
The product composition dimension captures the fundamental types of decorative tiles available to consumers and specifiers.
- Porcelain:Produced from refined clay fired at extremely high temperatures, porcelain tiles offer exceptional density, water resistance, and durability. Demand concentrates in high-traffic commercial complexes and moisture-prone residential areas due to their performance characteristics.
- Ceramic:Manufactured from a mixture of clay, sand, and other natural materials, ceramic tiles are versatile and cost-effective, typically featuring a glazed surface. Urban construction projects in India drive substantial demand for ceramic varieties, particularly for residential flooring and wall applications.
- Glass:Composed of recycled glass or new glass, these tiles provide a translucent aesthetic and vibrant color options.
- Marble:A natural stone, marble tiles offer a luxurious appearance with unique veining patterns.
- Mosaic:Small, decorative pieces of various materials, mosaic tiles create intricate patterns for artistic installations.
- Terracotta:Unglazed, porous clay tiles, terracotta is favored for its rustic aesthetic in specific architectural styles.
Porcelain holds installed capacity. Glass is rotating up the share rankings.
Application:
The functional utility of decorative tiles drives their adoption across different architectural spaces and design needs.
- Flooring:Decorative tiles used for floor surfaces require high durability, slip resistance, and aesthetic appeal to withstand foot traffic and complement interior design. Residential buildings and commercial complexes represent the largest end-users for floor tile applications.
- Wall Coverings:Applied to vertical surfaces, wall tiles prioritize aesthetic impact, ease of cleaning, and moisture resistance, often featuring intricate patterns or textures. Hospitality venues frequently specify custom wall coverings for unique brand environments.
- Backsplashes:These tiles protect walls from splashes in kitchens and bathrooms, offering a focal point for interior design.
- Outdoor Patios:Designed to withstand weather elements, outdoor patio tiles need frost resistance and high durability.
- Accent Walls:Creating a visual highlight in a room, accent wall tiles often feature bold designs or unique textures.
- Countertops:Large-format porcelain slabs are gaining traction for countertops, offering durability and a seamless aesthetic.
Demand for Flooring applications remains robust. Backsplashes are gaining market traction due to design trends.
Material:
The foundational elements from which decorative tiles are manufactured dictate their performance characteristics and aesthetic versatility.
- Clay:The primary raw material for ceramic and terracotta tiles, clay provides a cost-effective and abundant base for tile production. Extensive residential construction in Southeast Asia fuels the consistent demand for clay-based tile materials.
- Natural Stone:Including marble, granite, and travertine, natural stone offers unique patterns and a premium aesthetic. High-end residential projects in North America often specify natural stone for luxury finishes.
- Quartz:Engineered from natural quartz crystals and resins, quartz provides a durable and non-porous surface.
- Crushed Glass:Utilizing recycled glass, this material contributes to sustainable tile production and offers unique visual effects.
- Metal:Metal tiles, often made from copper, stainless steel, or aluminum, provide a contemporary and industrial aesthetic.
- Composite:Blending various materials, composite tiles offer tailored properties like enhanced flexibility or specific aesthetic blends.
Clay-based materials form the volume backbone. Crushed Glass is seeing increased interest for sustainable designs.
End User:
The ultimate consumer base for decorative tiles varies significantly, influencing product specifications and distribution channels.
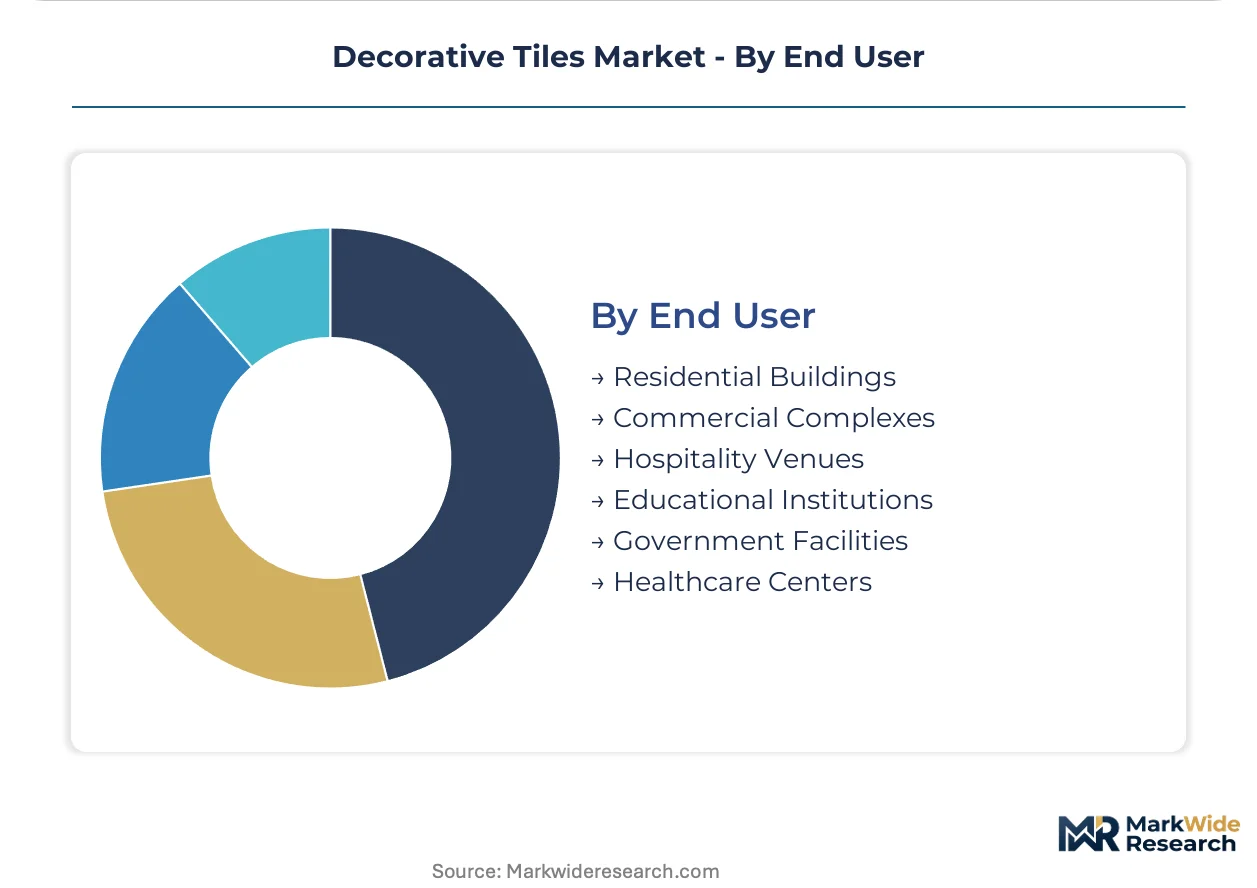
- Residential Buildings:Single-family homes and multi-unit dwellings constitute the largest end-user segment, driven by new construction and renovation cycles. Consumer preference for durable and aesthetically pleasing finishes sustains demand in this sector.
- Commercial Complexes:Office buildings, retail spaces, and public facilities require tiles that combine high durability, ease of maintenance, and specific design aesthetics for brand consistency. Urbanization projects in major cities globally propel demand for commercial tile installations.
- Hospitality Venues:Hotels, resorts, and restaurants invest in decorative tiles for aesthetic upgrades and creating distinctive guest experiences.
- Educational Institutions:Schools and universities use durable and easy-to-clean tiles for high-traffic areas like hallways and cafeterias.
- Government Facilities:Public buildings often specify tiles for longevity and compliance with stringent safety standards.
- Healthcare Centers:Hospitals and clinics require hygienic, non-porous, and easy-to-sanitize tile surfaces.
Residential Buildings represent the largest purchasing segment. Hospitality Venues are expanding most quickly due to renovation cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's robust domestic production of decorative tiles increasingly supplies its own burgeoning construction sector, while also serving demand in neighboring Southeast Asian markets. Diverse regional preferences and stringent regulatory frameworks shape product development and market penetration strategies across key geographies.
India
India's extensive residential and commercial construction projects drive substantial demand for decorative tiles. The Bureau of Indian Standards (BIS) sets quality benchmarks for domestic tile manufacturing. Urban centers like Mumbai experience high demand for ceramic varieties due to rapid urbanization.
United States
United States residential and light commercial construction projects generate consistent demand for decorative tiles. Environmental Protection Agency (EPA) guidelines influence material choices for installation components. The Southeast region's expanding housing market sees a concentration of new tile installations.
Germany
Germany's architectural projects, particularly in commercial and hospitality sectors, require high-quality decorative tiles. CE marking ensures compliance with health and safety standards for products entering the market. Bavaria's sustainable building initiatives foster demand for recycled content tiles.
Brazil
Brazil's rising middle class and expanding tourism sector stimulate new construction and renovation projects. National building codes dictate performance requirements for tile applications in public and private spaces. São Paulo's burgeoning urban developments are a key market for imported and domestic tiles.
United Arab Emirates
United Arab Emirates' ambitious infrastructure and luxury hospitality projects create strong demand for high-end decorative tiles. Local municipality regulations govern the specification and installation of all construction materials. Dubai's luxury hospitality developments extensively utilize customized tile solutions.
Decorative Tiles Market Key Industry Players
Channel-controlling players compete with product-specialist players within the decorative tiles market. This market exhibits a fragmented structure, with numerous participants ranging from large multinational corporations to niche artisanal studios. Strategic archetypes include global manufacturers leveraging extensive distribution networks and regional specialists focusing on specific material types or design aesthetics. Companies primarily engage in geographic expansion and continuous capital investment in advanced digital printing equipment.
At the scale-driven end, Mohawk Industries exemplifies a North American manufacturer leveraging an extensive distribution network to serve both residential and commercial sectors across the continent. Kajaria Ceramics represents a prominent Indian domestic market specialist, concentrating on high-volume porcelain and ceramic varieties for extensive urban construction projects. RAK Ceramics, based in the UAE, anchors a global presence with a broad portfolio serving diverse architectural needs across Europe and the Middle East, adapting effectively to regional aesthetic preferences and regulatory demands.
| Leading Market Players |
|---|
| Marazzi |
| RAK Ceramics |
| Mohawk Industries |
| Kajaria Ceramics |
| Marco Polo |
| Grupo Lamosa |
| Daltile |
| Florim |
| Porcelanosa |
| Others |
Cost & Logistics Intelligence
Energy cost volatility significantly influences decorative tile pricing tiers and the global supply chain configuration. Fluctuations in natural gas prices directly impact manufacturing costs and product availability for key markets.
Pricing Analysis
Digital printing technology creates a pricing gap between customized, high-value tiles and traditional mass-produced varieties. The dominant pricing model is project-based, with differentiation driven by customization level and durability, particularly for porcelain tiles. Pricing softness stems from substitution threats from luxury vinyl tile in residential applications. Hospitality venues exhibit lower price sensitivity for unique, brand-aligned solutions, while residential buyers prioritize cost-effectiveness.
Supply Chain Analysis
Clay, as a primary feedstock for ceramic and porcelain tiles, underpins a supply chain concentrated in India and parts of Southeast Asia. Natural gas dependency for energy-intensive firing processes introduces significant commodity price volatility. Fragmented regulatory compliance across Europe, India, and the US poses a structural risk for global manufacturers. Distribution runs through extensive networks for mass-market products, complemented by direct-to-consumer channels for specialized artisanal designs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The decorative tiles market faces a critical shortage in skilled installation labor, creating a bottleneck for high-value product adoption. This capability gap impacts both project execution and overall market expansion.
For Market Incumbents: Entrench market position by investing significantly in advanced digital printing technology and large-format production. Develop proprietary installation training programs to mitigate skill shortages, a key adoption barrier for high-value products. Leverage extensive distribution networks to counter substitution threats from resilient flooring. Pursue sustainability certifications like EPDs to meet evolving EU CSRD mandates.
For New Entrants and Emerging Players: Establish a beachhead in the direct-to-consumer segment, targeting high-end residential projects seeking artisanal designs. Focus on specialized product formats like thin porcelain slabs for countertop applications, offering an alternative to natural stone. Leverage e-commerce platforms to bypass traditional distribution channels and connect directly with designers. Untapped demand in Latin American markets, like Brazil and Mexico, presents significant growth potential.
For Investors and Strategic Acquirers: The market sits at an innovation-driven consolidation phase that favors technologically advanced manufacturers with strong intellectual property. Long-term viability is underpinned by continuous aesthetic upgrades and sustainability mandates. Target acquisition profiles include digital printing specialists and regional players with established direct-to-consumer channels. Watch for accelerated adoption of large-format porcelain slabs as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Printing Technology Investment | Enables intricate patterns and customization, fragmenting the mass-produced tile market for designers. |
| Vertical Integration into Installation Training | Addresses the skilled installer shortage, facilitating adoption of complex patterns and large-format products. |
| Sustainable Material Certification Program | Meets EU CSRD mandates and growing consumer preference for recycled content and transparent sourcing. |
| Direct-to-Consumer E-commerce Expansion | Bypasses traditional distributors, connecting artisanal producers with discerning homeowners and designers. |
| Large-Format Porcelain Slab Production | Opens new applications like countertops and facades, competing with natural stone and solid surfaces. |
Research Approach
A standing panel of architects, interior designers, tile manufacturers, and distributors provided ongoing calibration for primary data collection. This involved extensive interviews with industry stakeholders, validated against secondary sources including ISO standards, CE marking guidelines, and national building codes. Bottom-up market sizing was triangulated with top-down industry reports, ensuring robust data integrity.
Scenario-bracketing informed the quantitative model, projecting market evolution across the analysis window. Segmentation dimensions included product type, application, end-user, material, and regional regulatory clusters. Compound annual growth rates were derived from historical trends and projected demand drivers like urbanization rates. Hospitality renovation cycles served as a critical industry-specific forecast input.
Macroeconomic conditions sit as an overlay; deviation in energy price fluctuations or construction project delays would shift the trajectory. Forecasts reflect assumptions regarding regulatory stability and material innovation. Cross-checking against external construction spending benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Europe Ready-Mix Concrete Market
Building & Construction Materials
Skirting Board Market
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
Clay Roof Tiles Market
Building & Construction Materials
Saudi Arabia Tiles Market
Building & Construction Materials
Watertight Doors Market
Building & Construction Materials
United Kingdom Timber Cladding Market
Building & Construction Materials
US Plywood Market
Building & Construction Materials
Glass Tiles Market
Building & Construction Materials
Geogrid Market
Building & Construction Materials
Honeycomb Sandwich Panels Market
Building & Construction Materials
Bamboo Engineered Wood Market
Building & Construction Materials
Decorative Concrete Market
Building & Construction Materials
United States Gutter Guards Market
Building & Construction Materials
US Exterior Wall Systems Market
Building & Construction Materials
Poland Cement Market