
 Spray Foam Insulation Market | 2026-2036
Spray Foam Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Spray Foam Insulation Market Outlook
The EPA's Significant New Alternatives Policy is decoupling compliance from legacy formulation economics, forcing reformulation investments that favor well-capitalized producers. BASF SE leverages its integrated polyol supply chain to absorb blowing-agent transition costs without margin erosion. Huntsman International LLC anchors its position through captive MDI production and technical service networks tied to commercial contractors. Dow competes by extending its building science portfolio into whole-wall assemblies that bundle spray foam with air-sealing accessories.
Spray foam insulation comprises polyurethane or polyisocyanurate formulations that expand on application to create monolithic, air-impermeable thermal barriers with R-values ranging from R-3.5 to R-7 per inch depending on cell structure and density. The material's primary purpose is to eliminate convective heat loss while providing vapor control and structural adhesion in building envelopes. Closed cell dominates margin pools in commercial and industrial applications where compressive strength and moisture resistance command specification premiums, while open cell sustains volume leadership in residential new construction where cost-per-R-value governs contractor selection. Hybrid formulations are gaining specification share in agricultural and pre-existing structure retrofits as installers seek to balance performance with material economy.
The EPA's SNAP program, OSHA's isocyanate exposure standards, and the ICC's International Energy Conservation Code collectively shape product chemistry, installer certification requirements, and minimum thermal performance thresholds across the United States. State-level stretch codes in California, New York, and Massachusetts extend these baselines, creating a patchwork compliance environment that favors national distributors with regulatory tracking infrastructure. Stakeholders must monitor blowing-agent GWP trajectories and state adoption timelines for IECC amendments to avoid stranded inventory positions.
Market Dynamics
The EPA's SNAP program is forcing immediate reformulation across the entire polyurethane insulation supply chain, decoupling product economics from legacy hydrofluorocarbon blowing agents and reallocating margin pools toward producers with captive polyol infrastructure.
Growth Catalysts
- Residential Retrofit Demand:Homeowners in the United States are prioritizing envelope upgrades that reduce HVAC load, pulling specification toward high-R-value continuous insulation systems.
- OSHA Isocyanate Standards:Stricter exposure limits are professionalizing the installer base, raising barriers to entry and concentrating volume with certified contractor networks.
- Closed-Cell Compressive Strength:Commercial and industrial specifiers specify the material for structural adhesion in metal building applications where load-bearing meets thermal performance.
Market Restraints
- MDI Supply Concentration:Four producers control North American methylene diphenyl diisocyanate supply, creating input price volatility that compresses formulator margins.
- High-GWP Inventory Stranding:The EPA's phasedown timeline for HFC-245fa and HFC-365mfc leaves distributors exposed to obsolete stock in states adopting 2024 IECC stretch codes.
- Fiberglass and Mineral Wool Substitution:Batt insulation retains cost-per-R leadership in code-minimum residential construction, limiting spray foam to premium segments.
Strategic Opportunities
- Agricultural Building Envelopes:Hybrid open-cell/closed-cell systems are penetrating dairy and poultry facilities where condensation control and thermal stability reduce livestock mortality.
- California Title 24 Compliance:The state's 2022 Energy Code mandates whole-building airtightness testing, creating specification pull for monolithic air barrier systems.
- Pre-Existing Structure Channel:Retrofit-focused distributors are building direct-to-homeowner digital platforms that bypass traditional contractor intermediaries.
Industry Challenges
- Certified Installer Scarcity:The Spray Polyurethane Foam Alliance certification pipeline cannot match demand growth, extending project timelines and limiting geographic expansion.
- Refrigerant Transition Capex:Formulators must invest in low-GWP hydrofluoro-olefin blending equipment and compatibility testing without guaranteed pass-through pricing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spray Foam Insulation Market |
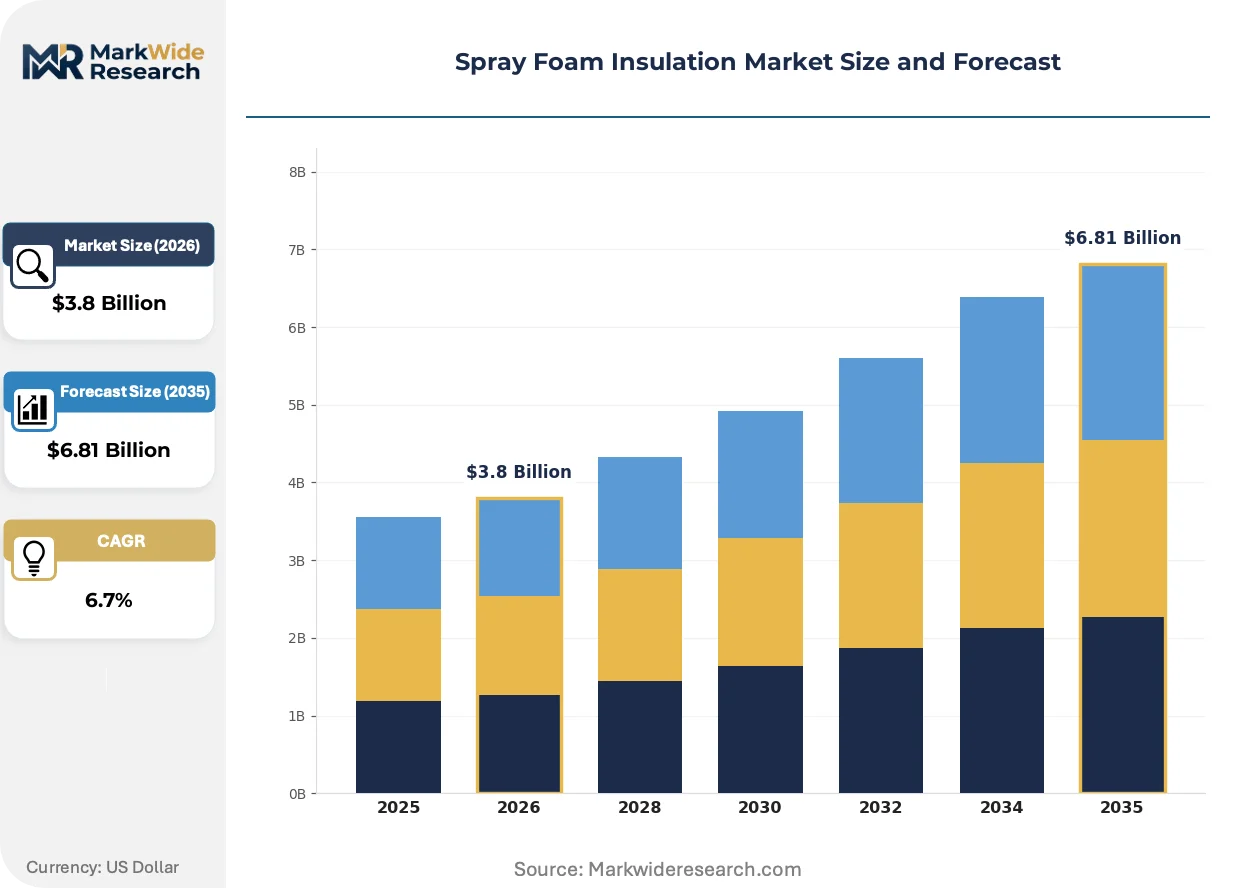
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Cell, Closed Cell, Hybrid, Specialty Foam Application: Residential, Commercial, Industrial, Agricultural Installation Type: Retrofit, New Construction, Pre-existing Structures, DIY End User: Homeowners, Contractors, Builders, Insulation Distributors |
| Companies Covered | BASF SE, Dow, Huntsman International LLC, Johns Manville, CertainTeed, LLC, Covestro AG, Owens Corning, Carlisle Spray Foam Insulation, NCFI Polyurethanes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spray Foam Insulation Market Strategic Shifts
Formulation chemistry, regulatory compliance architecture, and procurement behavior are converging to restructure competitive advantage away from commodity resin access and toward integrated building science capabilities.
Water-blown and hydrofluoro-olefin formulations are absorbing the technical risk of the HFC phaseout by delivering equivalent R-values at marginally higher density. Agricultural and cold-storage contractors are specifying these systems at accelerating rates. The technology is absorbing stranded capital from legacy HFC infrastructure while compressing the competitive set to producers with in-house blowing-agent R&D.
The EPA's Significant New Alternatives Policy is eliminating hydrofluorocarbon options from the acceptable substitutes list on a rolling schedule. Formulators face compressed reformulation windows with each SNAP rule revision. Commercial roofing and industrial cold-chain segments in the United States are responding by locking multi-year supply agreements with producers that have already secured low-GWP listings.
Homebuyers and commercial asset managers are demanding blower-door test documentation as a condition of final payment, shifting contractor selection criteria from cost-per-board-foot to verified air-sealing performance. This behavior is displacing low-bid procurement in the residential retrofit channel. The pattern is most visible in Massachusetts and New York where utility rebate programs require post-installation commissioning.
Spray Foam Insulation Market Segmentation
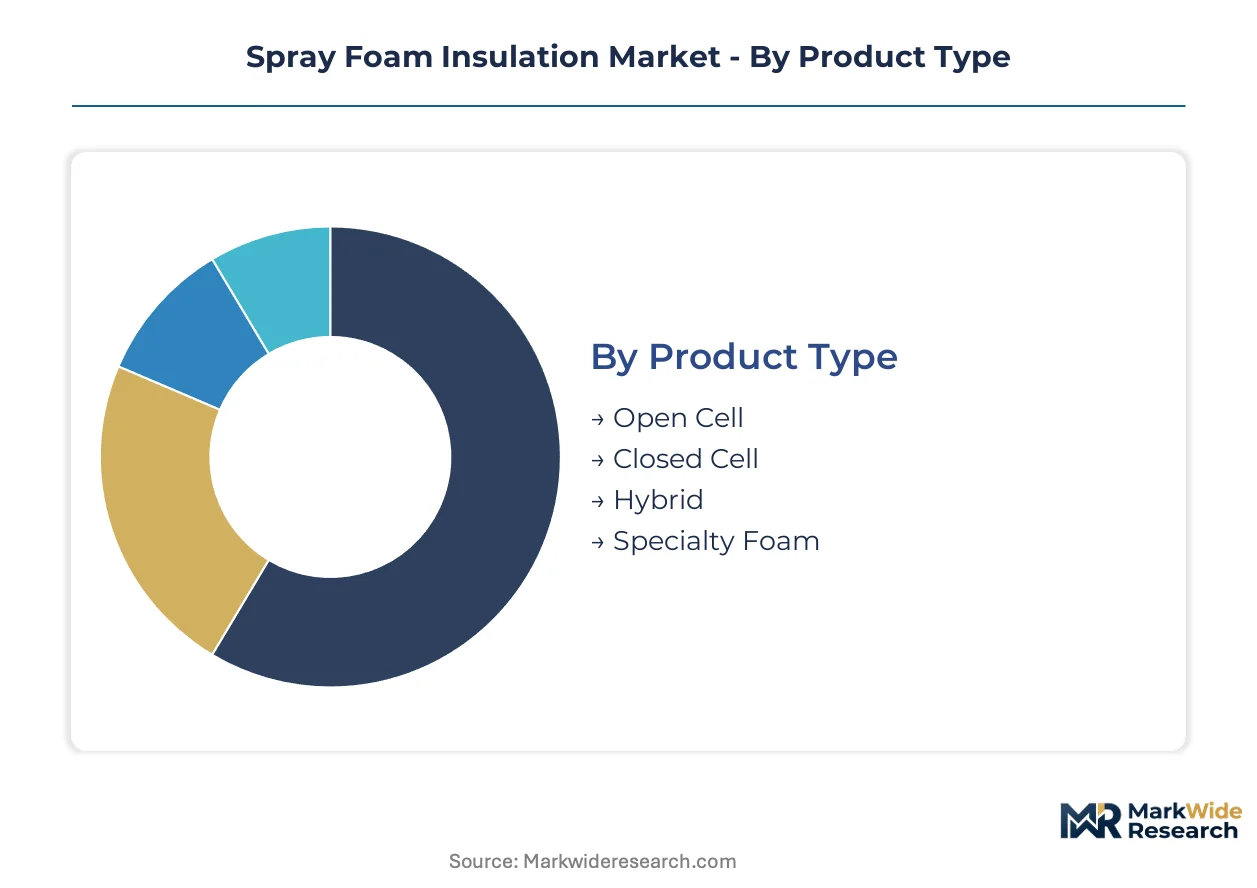
Spray foam insulation segmentation reveals divergent margin economics across cell structures and installation contexts. Volume concentration in residential retrofits contrasts with premium capture in commercial cold-chain applications. Understanding these splits enables targeted capacity allocation and channel investment decisions.
Product Type:
Open cell commands residential volume through lower material cost per R-value, while closed cell extracts premium pricing from commercial specifiers demanding compressive strength and moisture resistance.
- Open Cell:Polyurethane foam with interconnected cellular structure delivering R-3.5 to R-4 per inch. Residential new construction in the southern United States favors this formulation where vapor permeability and acoustic dampening outweigh structural demands. Cost-per-board-foot governs contractor specification in tract housing.
- Closed Cell:Dense monolithic barrier with R-6 to R-7 per inch and 15-25 psi compressive strength. Metal building contractors in Texas and Florida specify this grade for structural adhesion in hurricane-rated envelopes. Moisture impermeability commands specification premiums in below-grade and coastal applications.
- Hybrid:Combined open-cell base layer with closed-cell cap delivers balanced performance at intermediate density. Agricultural building specialists in dairy and poultry facilities specify hybrid systems where condensation control meets budget constraints.
- Specialty Foam:High-density formulations for cold-storage and cryogenic applications. Cold-chain logistics operators in California specify these grades for thermal stability across extreme temperature differentials.
Today's leader: Closed Cell. Tomorrow's challenger: Hybrid.
Application:
Residential channels absorb the majority of material volume, yet commercial and industrial segments concentrate margin pools through performance-based specification and multi-year service contracts.
- Residential:Single-family and multifamily envelope upgrades dominate unit demand. Homeowners in Massachusetts and New York pursue spray foam retrofits where utility rebate programs offset first-cost premiums. Blower-door commissioning requirements tighten contractor selection criteria.
- Commercial:Office, retail, and hospitality envelopes specify high-R continuous insulation. Title 24 compliance in California mandates whole-building airtightness testing, pulling specification toward monolithic spray foam assemblies.
- Industrial:Manufacturing facilities and process plants require thermal stability across operational temperature ranges. Petrochemical processors in Louisiana specify closed-cell systems for pipe insulation and tank farm envelopes.
- Agricultural:Livestock mortality reduction drives dairy and poultry facility upgrades. Thermal stability and condensation control in Wisconsin and Iowa dairy operations reduce veterinary costs and improve milk production metrics.
Residential channels deliver volume scale. Agricultural applications are climbing the fastest as livestock operators quantify thermal performance in mortality reduction.
Installation Type:
Retrofit installations professionalize the contractor base through diagnostic requirements, while new construction channels compete on speed and cost-per-square-foot.
- Retrofit:Existing structure upgrades require blower-door pre-testing and post-installation commissioning. Certified contractors in the Northeast build recurring revenue through utility-sponsored home performance programs.
- New Construction:Production builders specify spray foam for code-minimum compliance in energy-conscious subdivisions. Framing-integrated installation demands coordination with mechanical rough-in schedules.
- Pre-existing Structures:Historic renovation and deep energy retrofits access enclosed cavities through selective demolition. Preservation contractors in Boston and Philadelphia navigate National Park Service guidelines.
- DIY:Two-component disposable kits serve minor repairs and accessory structure applications. Big-box retailers stock limited SKUs for weatherization projects under 200 board feet.
Retrofit channels deepen contractor relationships. DIY kits are gaining share fastest through direct-to-consumer digital platforms.
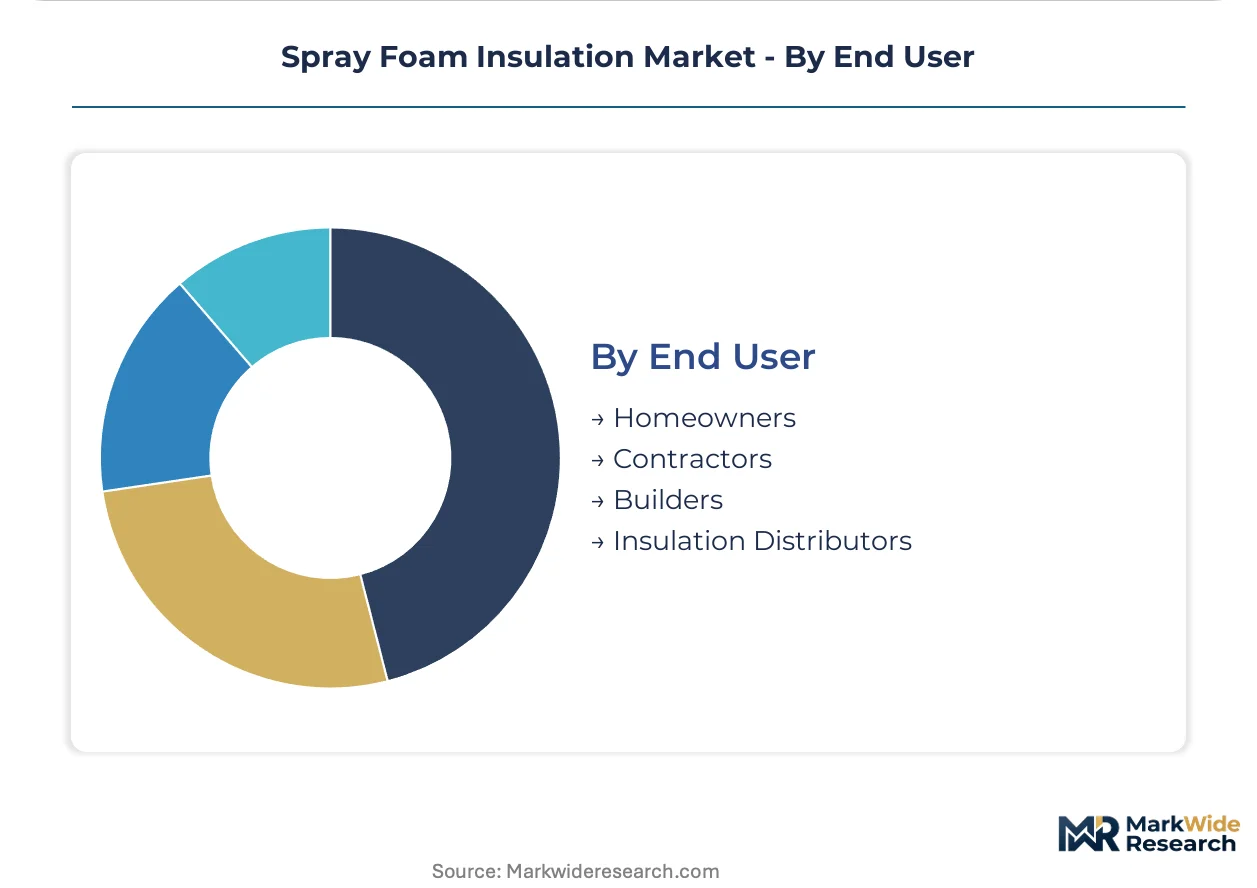
End User:
Contractor networks intermediate the majority of specification decisions, yet distributor consolidation and direct-to-builder programs reshape procurement pathways.
- Homeowners:Final purchasers influence material selection through rebate program eligibility and financing availability. Energy-efficiency-motivated buyers in California and New York research blower-door performance metrics before contractor selection.
- Contractors:Installation specialists control specification through equipment compatibility and crew training investments. SPFA-certified contractors in concentrated metro markets command premium pricing through scarcity positioning.
- Builders:Production and custom home builders negotiate volume pricing through national distribution agreements. Whole-wall assembly procurement bundles spray foam with air-sealing accessories and continuous insulation.
- Insulation Distributors:Regional and national distributors manage inventory exposure across blowing-agent transition timelines. Regulatory tracking infrastructure separates surviving distributors from stranded stock casualties.
Contractors anchor specification control. Builders are expanding most quickly through vertical integration into installation services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified installer networks concentrate in the United States, where utility rebate programs and code stringency create the deepest talent pools. Germany and Japan maintain specialized contractor bases serving industrial cold-chain applications. Emerging demand in Australia and the United Kingdom follows retrofit incentive structures.
United States
Residential retrofits drive volume as homeowners pursue envelope upgrades reducing HVAC load. The EPA's SNAP program accelerates high-GWP blowing agent phaseout, forcing reformulation investments. Massachusetts and New York contractors build recurring revenue through utility-sponsored home performance programs requiring blower-door commissioning.
Germany
Industrial cold-storage and passive house construction sustain premium specification demand. The EU F-Gas Regulation mandates low-GWP blowing agent transitions, compressing reformulation timelines. Bavarian and North Rhine-Westphalian fabricators serve Central European distribution networks with technical-grade formulations.
Japan
Earthquake-resistant building codes and space-constrained urban retrofits pull high-density closed-cell specification. METI energy efficiency standards tighten envelope performance requirements. Osaka and Nagoya industrial corridors host applicator networks serving manufacturing facility upgrades.
Australia
Climate-zone-specific energy codes and bushfire-resistant construction standards reshape product selection. State-level retrofit incentive programs in New South Wales and Victoria accelerate homeowner adoption. Sydney and Melbourne contractors expand into agricultural building envelopes for dairy and poultry thermal stability.
United Kingdom
Historic building preservation and deep energy retrofit programs create cavity-fill demand. PAS 2035 retrofit standards professionalize installer certification requirements. London and Southeast England contractors navigate National Park Service guidelines for pre-existing structure applications.
Spray Foam Insulation Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and distribution infrastructure. The market structure concentrates around integrated chemical producers with captive polyol supply chains and regional formulators with specialized contractor relationships. Three archetypes dominate: multinational resin producers, captive building science platforms, and independent spray foam specialists. Competitive moves center on backward integration into MDI supply and multi-year service contracting with certified installer networks.
Among integrated chemical producers, BASF SE and Dow exemplify archetypes leveraging captive resin infrastructure to absorb blowing-agent transition costs. Huntsman International LLC occupies a position within the MDI-integrated tier, representing producers with technical service networks tied to commercial contractors. These three companies anchor the competitive set through differentiated approaches to formulation economics and channel access.
| Leading Market Players |
|---|
| BASF SE |
| Dow |
| Huntsman International LLC |
| Johns Manville |
| CertainTeed, LLC |
| Covestro AG |
| Owens Corning |
| Carlisle Spray Foam Insulation |
| NCFI Polyurethanes |
| Others |
Value Chain & Pricing Dynamics
MDI feedstock costs cascade through formulation tiers as captive producers in the United States and Germany leverage integrated polyol infrastructure to buffer blowing-agent transition expenses, while independent formulators absorb margin compression or pass through to contractor networks.
Pricing Analysis
Bundled whole-wall assembly pricing dominates commercial specification, separating turnkey air-sealing performance from unbundled material-only procurement in residential retrofits. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade, with SPFA-certified contractors commanding scarcity premiums and DIY kits competing on cost-per-board-foot. Pricing pressure stems from fiberglass substitution in code-minimum construction, compressing open-cell margins. Production builders exhibit highest price sensitivity, while cold-storage operators prioritize thermal performance over first cost.
Supply Chain Analysis
Freight costs from Gulf Coast MDI production centers to Northeast and West Coast application markets amplify regional price dispersion, favoring formulators with distributed blending capacity. Supply concentrates in the United States, Germany, and China, with methylene diphenyl diisocyanate and specialty polyols anchoring upstream dependencies. Single-source vulnerability runs through four North American MDI producers, exposing formulators to input volatility. Distribution runs through national distributors with regulatory tracking infrastructure and direct-to-contractor digital platforms bypassing traditional intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through low-GWP formulation premiums and certified installer scarcity, as the EPA's SNAP program decouples legacy economics from compliance-ready supply chains.
For Market Incumbents: Deepen captive polyol integration to absorb blowing-agent transition costs without pricing erosion. Expand technical service networks tied to commercial roofing and cold-chain contractors. Defend against mineral wool substitution by bundling blower-door commissioning documentation with installation contracts. Prioritize Massachusetts and California utility program eligibility to lock recurring retrofit revenue. For New Entrants and Emerging Players: The gap between premium closed-cell and economy open-cell pricing creates entry space for hybrid formulations in agricultural and pre-existing structure channels. Target dairy and poultry facility retrofits in Wisconsin and Iowa where livestock mortality reduction justifies performance premiums. Penetrate through direct-to-homeowner digital platforms that bypass SPFA-certified contractor intermediaries. Anchor go-to-market around condensation control guarantees backed by veterinary cost reduction metrics. For Investors and Strategic Acquirers: Consolidation pressure builds where distributors face stranded high-GWP inventory exposure and certified installer scarcity extends project timelines. Long-term viability favors producers with in-house low-GWP blowing-agent R&D and captive MDI supply. Acquisition targets include regional formulators with agricultural contractor relationships and distributors with regulatory tracking infrastructure. Watch state adoption timelines for IECC stretch codes as inflection signals for inventory write-down risk and reformulation capex demands.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MDI Supply | Captive feedstock production insulates margin pools from oligopoly pricing volatility. |
| Low-GWP Formulation Certification | EPA SNAP compliance unlocks specification access in California and New York stretch code markets. |
| Certified Installer Network Expansion | SPFA credential scarcity commands project pricing premiums and geographic market control. |
| Agricultural Building Envelope Specialization | Livestock mortality reduction metrics justify hybrid system premiums in dairy and poultry facilities. |
| Direct-to-Consumer Digital Platform | Bypassing contractor intermediaries captures homeowner retrofit demand through utility rebate eligibility tools. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with spray foam formulators, SPFA-certified contractors, national distribution procurement leads, and agricultural facility operators with secondary validation against EPA SNAP rulemakings, ICC IECC amendment databases, state energy office rebate program filings, and customs trade data. Bottom-up volume builds across product types and installation channels triangulated against top-down chemical producer capacity disclosures.
Comparable historical periods anchored growth trajectory assumptions across the projection horizon, with segmentation modeling spanning cell structure density, application context, installation type, and end-user procurement pathway. CAGRs derived from demand elasticity analysis against building code stringency indices and utility incentive program budgets. Industry-specific forecast inputs incorporated MDI supply concentration dynamics and blowing-agent GWP phaseout timelines.
Caveats apply where accelerated IECC adoption or refrigerant transition delays could materially shift the outlook. Forecasts reflect assumptions about certified installer pipeline expansion and low-GWP formulation performance parity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Steep Slope Roofing Materials Market
Building & Construction Materials
South America Industrial Flooring Market
Building & Construction Materials
Mexico Oriented Strand Board Market
Building & Construction Materials
Middle-East and Africa Construction Adhesives Market
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
Indonesia Ready-Mix Concrete Market
Building & Construction Materials
Door Hinges Market
Building & Construction Materials
Asia-Pacific Flanges Market
Building & Construction Materials
US Geosynthetics Market
Building & Construction Materials
Facade Anchor Systems Market
Building & Construction Materials
France Ceramic Tiles Market
Building & Construction Materials
Concrete Sealer Market
Building & Construction Materials
Concrete Aggregate Market
Building & Construction Materials
Residential and Commercial Smart Glass Market
Building & Construction Materials
Commercial Glazing Market
Building & Construction Materials
US Steel Merchant and Rebar Market