
 I-Joist Market | 2026-2036
I-Joist Market Size, Share, and Industry Trends Forecast 2026-2036
I-Joist Market Intelligence
Aftermarket service revenue for I-joist installation training and engineered-wood system design is tilting toward manufacturers with captive technical support networks. Weyerhaeuser Company leverages its nationwide distribution footprint to bundle specification services with material supply. Boise Cascade Company anchors its position through mill-direct relationships with large production builders. Georgia-Pacific LLC differentiates by controlling fiber supply from its timberlands through finished I-joist production.
An I-joist is a structural member comprising laminated veneer lumber or solid-sawn flanges joined by an oriented strand board or plywood web, engineered to carry floor and roof loads across longer spans with reduced weight versus conventional lumber. OSB-web configurations dominate residential volumes due to material efficiency and manufacturing throughput, while LVL-flange variants command premium positioning in commercial mid-rise applications where design loads intensify. Custom sizing segments capture disproportionate margin as architects and engineers specify project-specific depths and flange widths for complex spans.
The International Code Council publishes structural standards that govern I-joist allowable spans and fire-blocking requirements in U.S. jurisdictions, directly influencing product engineering and builder compliance costs. APA – The Engineered Wood Association operates third-party quality certification programs that manufacturers must maintain for code-recognized specification. Stakeholders must monitor evolving state-level amendments to the International Residential Code that restrict combustible construction in mid-rise buildings, as these provisions determine addressable market boundaries for wood-based floor systems.
Market Dynamics
The I-Joist market is being reshaped by intensifying pressure on builders to reduce on-site labor hours while meeting stricter span-performance requirements in mid-rise wood-frame construction. Engineered-wood systems now compete directly with light-gauge steel and concrete plank on total installed cost, forcing manufacturers to bundle design services with material supply.
Growth Catalysts
- International Residential Code amendments:U.S. jurisdictions are expanding allowable heights for combustible construction, extending addressable floor-area for wood I-joist systems in multi-family buildings.
- OSB-web manufacturing scale:Continuous pressing technology has cut web production costs by half versus plywood alternatives, accelerating substitution of solid-sawn joists in tract housing.
- Single-family housing density:Builders in Texas, Florida, and the Carolinas are specifying deeper I-joist depths for open-concept designs requiring longer clear spans without intermediate bearing walls.
Market Restraints
- Structural adhesive supply concentration:North American phenolic resin production concentrates among three chemical suppliers, exposing I-joist manufacturers to volatile input costs when energy prices spike.
- Substitution by light-gauge steel:Cold-formed steel joists capture share in mid-rise commercial podiums where insurance underwriters impose stricter fire-rating requirements on combustible assemblies.
- Dimensional lumber price volatility:Solid-sawn flange alternatives fluctuate with western Canadian harvest levels, compressing margins when SPF 2x10 prices spike above engineered alternatives.
Strategic Opportunities
- Mass timber hybrid construction:Cross-laminated timber buildings in British Columbia and Oregon require I-joist floor systems for secondary spans, creating specification pull from architects pursuing carbon-neutral structures.
- Direct-to-builder digital channels:Configurator platforms allowing production builders to specify custom depths and hole patterns are bypassing traditional two-step distribution in the southeastern United States.
- Inflation Reduction Act tax credits:U.S. incentives for low-carbon building materials are positioning engineered wood favorably in whole-building lifecycle assessments versus steel and concrete.
Industry Challenges
- Installation competency gaps:Field crews unfamiliar with web stiffener requirements and bearing-length minimums generate costly callback claims that erode manufacturer profitability.
- APA certification timeline compression:Third-party quality audits required for code-recognized product evaluation reports now face six-month backlogs, delaying new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | I-Joist Market |
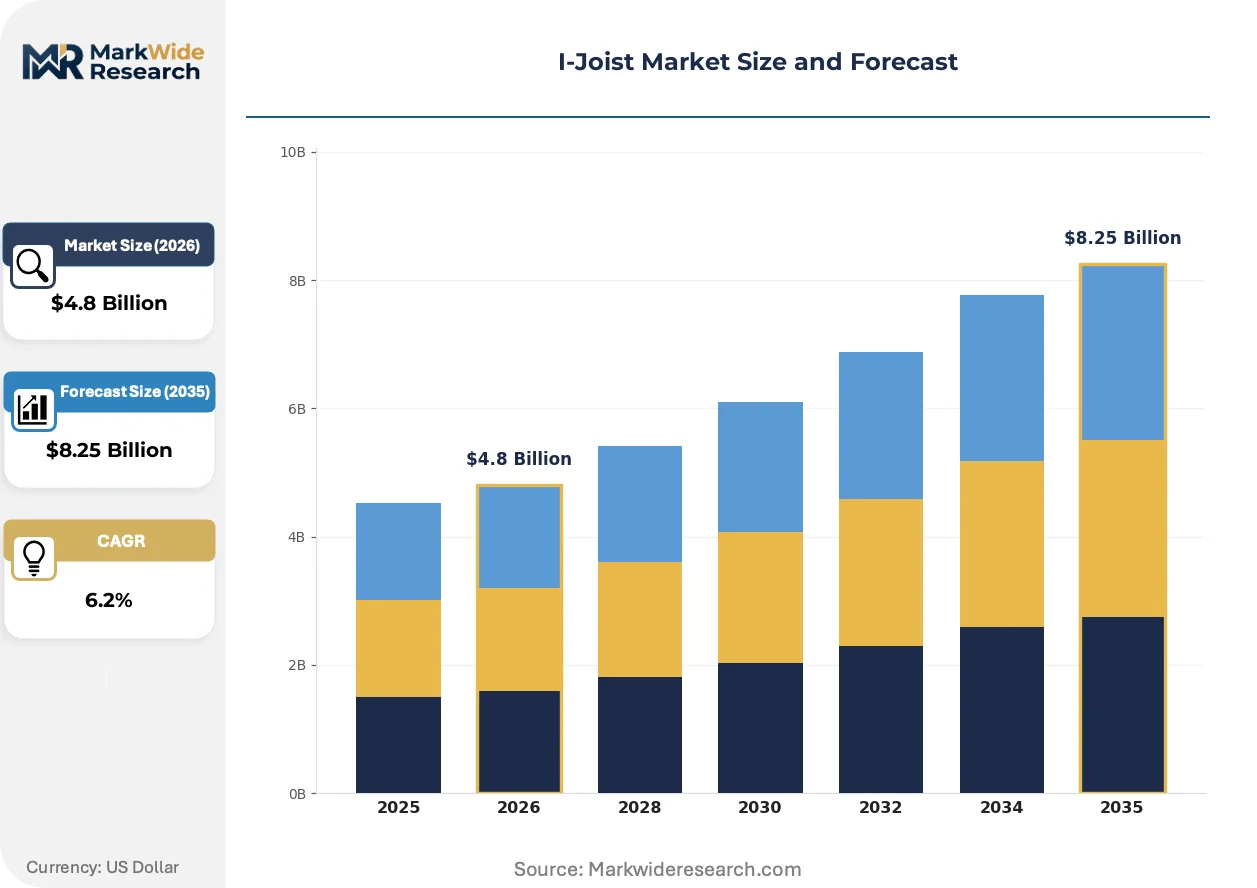
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plywood, OSB, LVL, Steel Application: Residential Construction, Commercial Buildings, Industrial Structures, Renovations End User: Contractors, Builders, Architects, Engineers Size: Standard, Custom, Small, Large |
| Companies Covered | Georgia-Pacific LLC, Roseburg Forest Products Co., Weyerhaeuser Company, Stark Truss Company, Inc., STEICO SE, Boise Cascade Company, Nordic Structures, Anthony Forest Products Co., Louisiana-Pacific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
I-Joist Market Strategic Shifts & Innovations
Digital fabrication and predictive design tools are compressing the specification-to-installation cycle for engineered-wood systems. Manufacturers now embed RFID tags in I-joist flanges to track moisture exposure and structural integrity through the build process.
Automated web hole-cutting systems using CNC routers are rendering obsolete manual field-notching practices that compromised web shear capacity. Production builders in Arizona and Nevada have adopted pre-cut electrical and plumbing penetrations on 90% of multi-family starts. The shift eliminates rework and accelerates rough-in schedules by two days per floor.
California's Title 24 energy code now mandates whole-building embodied carbon disclosure for commercial projects over 100,000 square feet. The regulation forces structural engineers to specify I-joist systems with Environmental Product Declarations over conventional steel. Architects in Sacramento and San Diego are prioritizing manufacturers with verified lifecycle data in competitive bid packages.
Consolidation among U.S. production builders has concentrated purchasing authority with national procurement teams. Regional distributors in the Midwest and Pacific Northwest now compete on value-added engineering support rather than inventory depth alone. The largest 25 builders command 60% of I-joist volume and negotiate mill-direct pricing with captive technical specification services.
I-Joist Market Segmentation
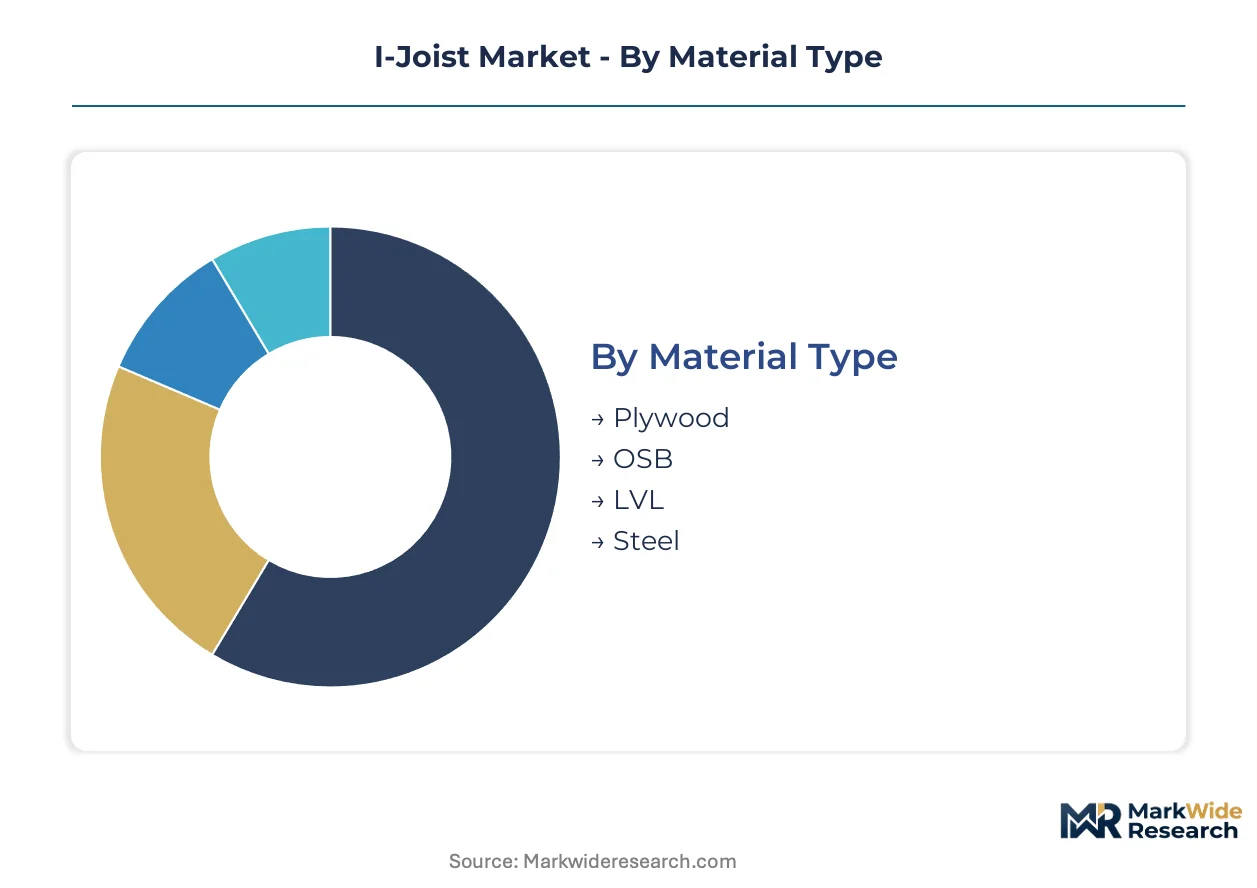
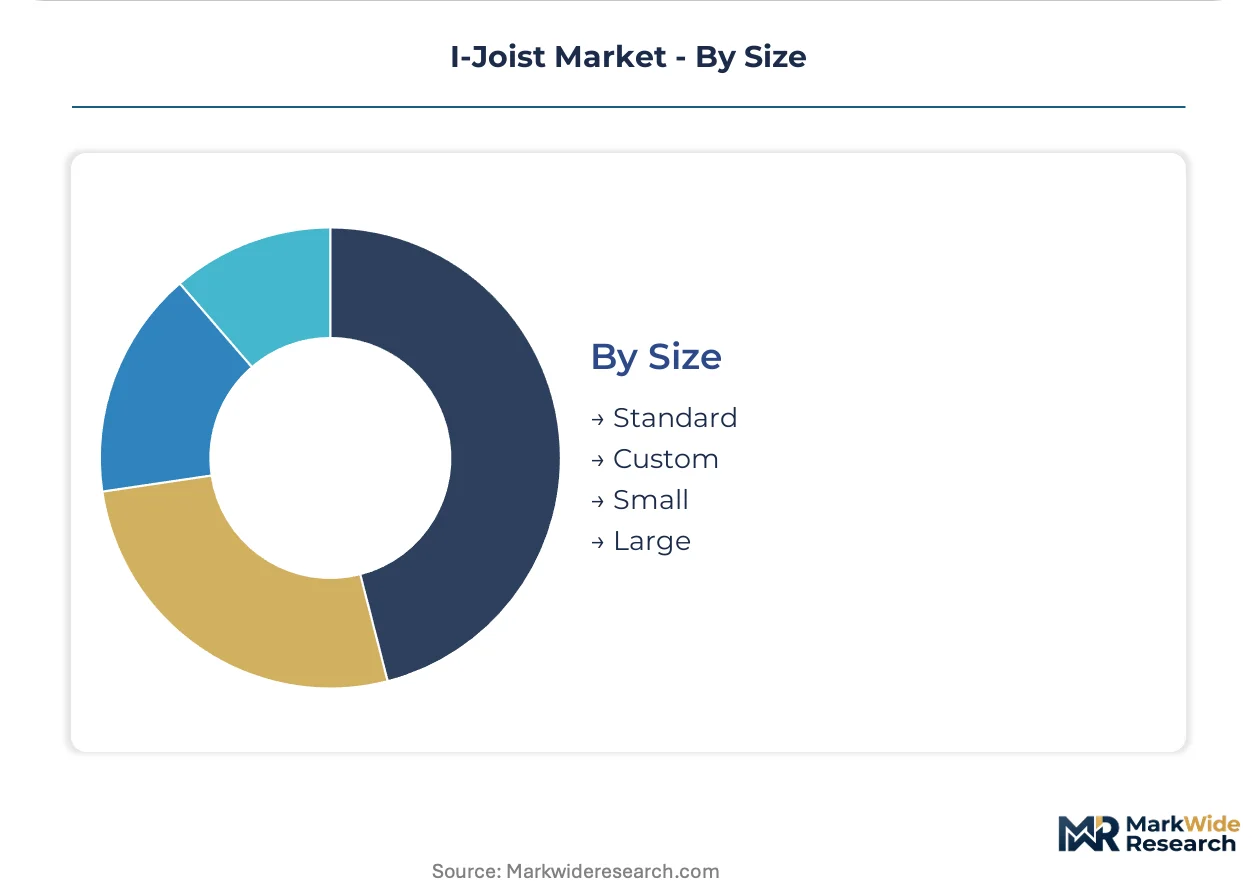
Segmentation in the I-Joist market reveals how material choices, application requirements, and specification authority shape procurement patterns. Manufacturers calibrate production mixes to the divergent technical and commercial priorities across residential, commercial, and renovation channels.
Material Type:
Cost tier determines competitive positioning across web and flange substrates, with manufacturing scale and fiber economics driving adoption curves.
- OSB:Oriented strand board webs dominate residential tract housing due to continuous pressing efficiency and material yield advantages. Builders in Texas and Florida specify OSB-web I-joists for single-family open-concept designs requiring cost-efficient long spans.
- LVL:Laminated veneer lumber flanges deliver superior stiffness-to-weight ratios for commercial mid-rise applications where design loads intensify. Pacific Northwest mass timber projects specify LVL-flange configurations for hybrid CLT floor systems pursuing carbon-neutral certifications.
- Plywood:Traditional web material retains specification in hurricane-prone coastal zones where building codes mandate enhanced moisture resistance during construction exposure.
- Steel:Metallic flange-web hybrids serve specialized industrial applications requiring extreme load-bearing capacity or fire-rating compliance beyond combustible assembly limits.
OSB commands the established base. The steepest expansion runs through LVL.
Application:
Volume concentration varies sharply by construction vertical, with code amendments and insurance underwriting reshaping addressable floor area.
- Residential Construction:Single-family and multi-family wood-frame buildings generate the bulk of I-joist consumption, with deeper joist depths gaining traction for open-concept layouts. The International Residential Code height amendments in U.S. jurisdictions extend combustible construction allowances, expanding specification opportunity in mid-rise multi-family.
- Commercial Buildings:Office, retail, and hospitality podiums increasingly specify engineered wood where whole-building lifecycle assessments favor low-carbon materials. California's Title 24 embodied carbon disclosure mandates drive structural engineers toward I-joist systems with verified Environmental Product Declarations.
- Industrial Structures:Warehousing and light manufacturing facilities adopt I-joists for roof assemblies where wide clear spans reduce column density and improve operational flexibility.
- Renovations:Existing building retrofits and adaptive reuse projects create demand for custom-depth I-joists matching legacy structural grids without full demolition.
Residential Construction anchors volume leadership. Commercial Buildings are climbing the fastest as code frameworks evolve.
End User:
Customer type dictates purchasing authority and specification influence, with consolidation concentrating decision-making among national procurement teams.
- Contractors:Installation crews prioritize product availability and technical support, with callback risk from improper bearing-length installation driving loyalty to manufacturers with field engineering networks.
- Builders:Production builders command mill-direct pricing and captive specification services, with the largest 25 U.S. builders controlling 60% of I-joist volume through centralized procurement.
- Architects:Design professionals specify custom depths and flange widths for complex spans, prioritizing manufacturers with digital configurators and verified lifecycle data.
- Engineers:Structural engineers translate load requirements into performance specifications, with APA-certified evaluation reports serving as gatekeepers for code-recognized product selection.
Builders command the established base. The steepest expansion runs through Architects as digital specification tools proliferate.
Size:
Manufacturing flexibility separates standard stock from engineered-to-order production, with margin structure favoring customization capabilities.
- Standard:Fixed-depth configurations in high-volume dimensions serve production builders with predictable span tables and rapid turnaround requirements.
- Custom:Project-specific depths and flange widths capture disproportionate margin as design-build contracts demand optimized material efficiency for irregular structural grids.
- Small:Compact dimensional ranges address renovation constraints and infill development where existing foundations limit load-bearing capacity.
- Large:Extended depths up to 24 inches and beyond serve commercial and industrial applications requiring maximum span capability without intermediate support.
Standard sizing commands the established base. Custom fabrication is climbing the fastest as architect-led design intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Builders in Texas and Florida exhibit the highest price elasticity, switching between solid-sawn lumber and engineered alternatives within weeks. Specifiers in British Columbia and Oregon prioritize carbon credentials over unit cost, locking in long-term supply agreements with verified EPD holders.
United States
Single-family housing starts in the Southeast and Southwest sustain the world's largest I-joist consumption base. The International Residential Code height amendments in multiple jurisdictions expand combustible construction allowances for mid-rise multi-family. Production builders in Dallas-Fort Worth and Atlanta specify deeper joist depths for open-concept designs requiring longer clear spans.
Canada
Mass timber hybrid construction in British Columbia creates specification pull for LVL-flange I-joists in CLT floor systems. The country's national building code maintains stringent fire-blocking requirements that favor engineered-wood assemblies with documented performance testing. Vancouver and Toronto metropolitan areas concentrate demand from architects pursuing carbon-neutral structures.
Germany
Multi-story residential construction in timber-frame systems drives steady demand for precision-engineered floor members. The EU Green Deal and national energy efficiency regulations position low-carbon building materials favorably in public procurement. Industrial clusters in Bavaria and Baden-Württemberg house fabricators supplying cross-laminated timber projects across Central Europe.
China
Rapid urbanization and prefabricated construction pilots expand addressable floor area for engineered-wood systems in mid-rise residential. The country's dual carbon goals and GB standards for green building materials create regulatory tailwinds for timber alternatives to steel and concrete. Yangtze River Delta manufacturing bases supply domestic projects and export markets with cost-competitive OSB-web configurations.
Australia
Multi-residential podiums and commercial mid-rise construction in timber-frame systems accelerate specification of engineered floor assemblies. The country's national construction code and state-level sustainability mandates drive structural engineers toward products with verified lifecycle assessments. Sydney and Melbourne metropolitan corridors concentrate demand from design-build firms pursuing rapid construction schedules.
I-Joist Market Key Industry Players
Vertically integrated forest products conglomerates and specialized engineered-wood fabricators split the market between scale-driven commodity supply and specification-intensive custom production. Three strategic archetypes dominate: captive timberland owners controlling fiber-to-finished-product pipelines, mill-direct specialists serving national production builders, and regional truss manufacturers bundling design services with material supply. Competitive moves concentrate on backward integration into resin and veneer supply, plus geographic expansion through distribution partnerships in high-growth Southeast U.S. corridors.
Among North American forest products conglomerates, Weyerhaeuser Company and Georgia-Pacific LLC exemplify the timberland-integrated archetype, while Boise Cascade Company occupies a position within the mill-direct specialist tier. STEICO SE represents European engineered-wood positioning with a manufacturing footprint anchored in Central European timber basins.
| Leading Market Players |
|---|
| Georgia-Pacific LLC |
| Roseburg Forest Products Co. |
| Weyerhaeuser Company |
| Stark Truss Company, Inc. |
| STEICO SE |
| Boise Cascade Company |
| Nordic Structures |
| Anthony Forest Products Co. |
| Louisiana-Pacific Corporation |
| Others |
Cost & Logistics Intelligence
Great Lakes freight corridors dictate landed cost spreads between Canadian veneer mills and southern U.S. distribution hubs, concentrating pricing power with manufacturers controlling captive barge fleets while forcing regional distributors to absorb terminal handling volatility through tiered service contracts.
Pricing Analysis
Aftermarket service revenue for installation training and engineered-wood system design anchors lifetime value capture for I-joist manufacturers. Three-tier pricing structure across premium LVL-flange, standard OSB-web, and economy solid-sawn alternatives reflects material grade and APA certification tier. Cost compression in standard OSB configurations intensifies as continuous pressing technology floods residential markets with undifferentiated volume. Production builders command the steepest discounts through mill-direct contracts, while custom fabrication for architect-led projects sustains premium positioning.
Supply Chain Analysis
Timberland holdings in the U.S. Pacific Northwest and Canadian interior British Columbia anchor fiber supply for laminated veneer lumber production. Phenolic resin adhesives draw from concentrated North American chemical suppliers, while oriented strand board feeds from southern pine plantations across Georgia and Alabama. Single-source vulnerability in structural adhesive production exposes manufacturers to energy-price volatility. Distribution runs through captive technical service networks for national builders and two-step wholesale channels for regional contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The I-Joist market operates as a regulatory entrenchment story, where APA certification requirements and International Building Code recognition create switching costs that lock speculators into established supply relationships.
For Market Incumbents: Build specification moats by embedding RFID tracking and predictive design tools into mill-direct contracts with the largest 25 U.S. production builders. Expand captive technical engineering teams in Texas and Florida to preempt callback claims from installation competency gaps. Backward integration into phenolic resin supply hedges against chemical supplier concentration.
For New Entrants and Emerging Players: Build out digital configurator platforms targeting mid-rise commercial podiums in California where Title 24 embodied carbon disclosure mandates favor verified EPD holders. Mass timber hybrid construction in Oregon and British Columbia offers the most penetrable specification channel. Lead with lifecycle assessment transparency to displace commodity OSB suppliers in carbon-neutral project bids.
For Investors and Strategic Acquirers: Regional truss manufacturers bundling design services with material supply represent the most defensible acquisition archetype, given consolidation pressure from national procurement teams. Long-term viability hinges on positioning for Inflation Reduction Act tax credit eligibility through low-carbon material certification. Watch APA audit backlogs as an inflection signal—six-month delays indicate capacity constraints that favor scaled incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive phenolic production insulates margin from energy-driven chemical price spikes. |
| Digital Configurator Platform Launch | Direct-to-builder specification tools bypass traditional distribution in southeastern U.S. corridors. |
| EPD Certification Investment | Verified lifecycle data unlocks California Title 24 compliance and IRA tax credit eligibility. |
| Technical Service Network Expansion | Field engineering teams reduce callback risk and lock in production builder loyalty. |
| Mass Timber Hybrid Partnership | CLT floor system collaboration captures specification pull from carbon-neutral architects. |
Research Approach
The analysis maps OSB-web, LVL-flange, plywood-web, and steel-hybrid configurations, each validated through production builder procurement directors, regional distributor sales managers, APA quality auditors, and structural engineering consultants. Primary interviews with these stakeholders combined with secondary validation from APA certification databases, International Code Council amendment records, and SEC filings from forest products conglomerates. Bottom-up volume triangulation across material type and application segments reconciled against top-down construction spending data.
Assumptions around single-family housing density, mid-rise combustible construction allowances, and mass timber adoption rates were held fixed across baseline scenarios while energy price volatility and adhesive supply disruptions were stress-tested. Segmentation modeling incorporated material type, application vertical, end-user purchasing authority, and sizing configuration. CAGRs were derived from regression analysis of housing start correlations and engineered-wood substitution elasticities, with input from continuous pressing capacity expansion schedules and CLT project pipeline databases.
Stress conditions across western Canadian harvest levels, phenolic resin input costs, and state-level fire-blocking amendments were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and acknowledge that APA certification timeline compression or sudden steel substitution in mid-rise commercial could materially revise trajectory. Cross-checking against U.S. Census Bureau housing start data and APA production statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Bamboo Engineered Wood Market
Building & Construction Materials
Cladding Systems Market
Building & Construction Materials
Spray Foam Market
Building & Construction Materials
Steel Wire Rope Products Market
Building & Construction Materials
US Retractable Roofing System Market
Building & Construction Materials
Europe Faucet Market
Building & Construction Materials
India Particle Board Market
Building & Construction Materials
Customized Shopfitting Materials Market
Building & Construction Materials
Polished Concrete Market
Building & Construction Materials
Asia-Pacific Flanges Market
Building & Construction Materials
Steel Rebar Market
Building & Construction Materials
US and Canada Corner Beads and Caps Market
Building & Construction Materials
Plumbing Fixtures and Fittings Manufacturing Market
Building & Construction Materials
Tile Grout Market
Building & Construction Materials
US Steel Merchant and Rebar Market
Building & Construction Materials
Saudi Arabia Sanitaryware Market