
 Europe Building Materials Market | 2026-2036
Europe Building Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Building Materials Market Analysis
German cement producers is restructuring capacity around clinker substitution and alternative fuels, shifting investment toward decarbonized kiln operations. HeidelbergCement leverages its Nordic biomass fuel integration to sustain cost advantages in carbon-intensive markets. Saint-Gobain Group anchors its European insulation portfolio through deep manufacturing scale in glass wool and stone wool substrates. CRH competes aggressively on ready-mix concrete logistics, controlling distribution density across British and Irish urban corridors.
Europe building materials encompass mineral-based and processed substances—portland cement with clinker factors below 0.65, soda-lime silica glass with iron oxide modulation, and engineered timber with laminated veneer lumber grades—fabricated for structural, envelope, and finish functions in built assets. Cement and aggregates retain volume dominance but face margin compression from carbon border adjustments, while glass segments capture premium positioning through thermal performance coatings. Wood-based materials represent the fastest-expanding structural category as cross-laminated timber gains multi-story approval across German and Austrian building codes. Metal applications in structural framing concentrate in commercial and infrastructure verticals where fire-rated steel assemblies command specification loyalty from contractors and developers.
The EU Green Deal and Energy Performance of Buildings Directive mandate near-zero whole-life carbon for new construction, forcing material producers to certify Environmental Product Declarations through ECHA-aligned frameworks. CE marking under the Construction Products Regulation governs market access, with national regulators in France and Italy enforcing stricter local performance derivations. Stakeholders must monitor evolving embodied carbon thresholds in public procurement rules and decide whether to front-load capital into low-carbon process retrofit or to acquire certified low-carbon supply through offtake partnerships.
Market Dynamics
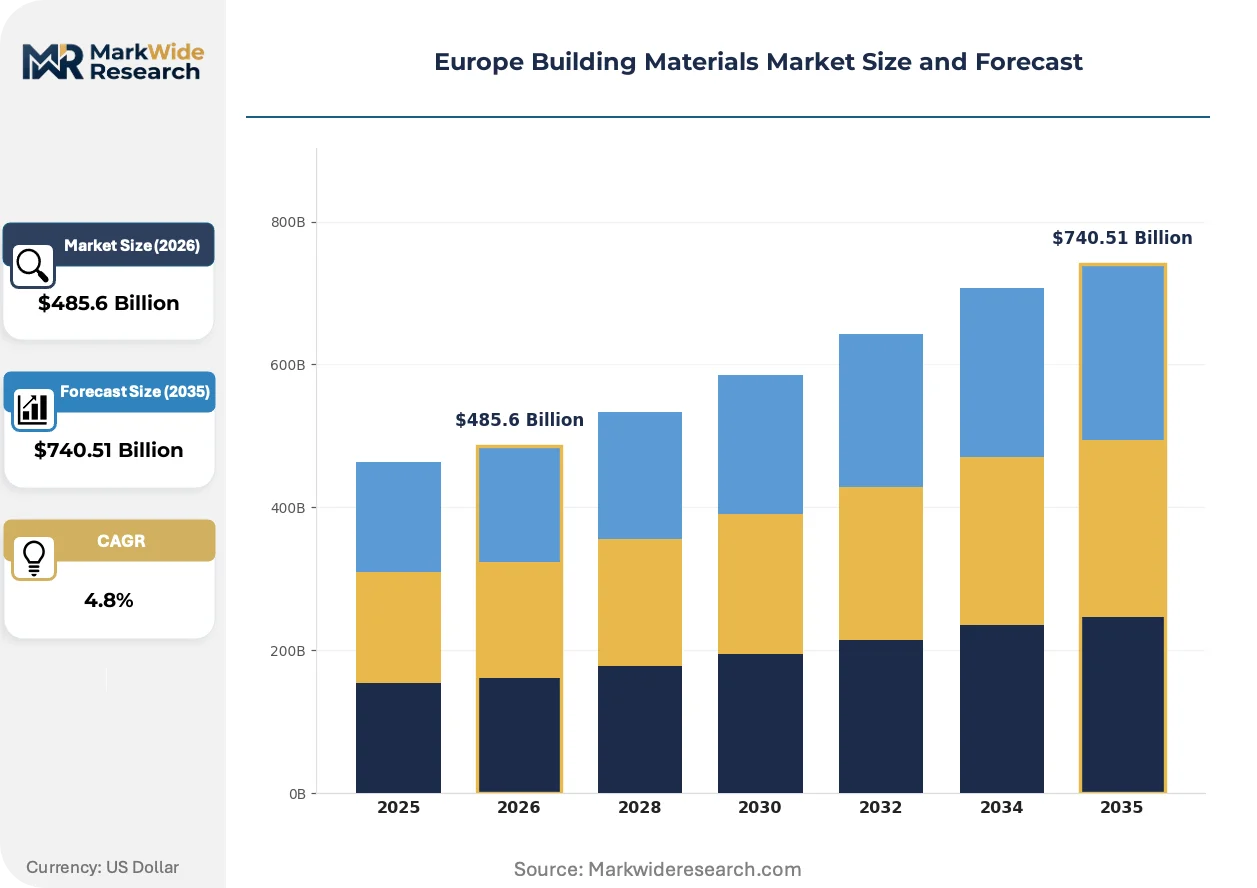
The EU Green Deal's embodied carbon benchmarks are compressing margins for conventional cement and steel producers while redirecting capital toward clinker substitution and mass timber certification infrastructure.
Growth Catalysts
- Residential retrofit mandates:Germany's Building Energy Act and France's RE2020 regulations are accelerating demand for low-carbon insulation and engineered wood products in existing housing stock.
- Mass timber code parity:Nordic building authorities have granted cross-laminated timber structural equivalence with steel and concrete for multi-story construction, unlocking new architectural applications.
- Carbon border adjustment mechanism:The phased implementation of CBAM on imported cement and steel is protecting domestic low-carbon production investments across EU member states.
Market Restraints
- Clinker feedstock concentration:High-purity limestone deposits concentrate in specific Mediterranean and Baltic regions, creating geographic supply vulnerability for cement decarbonization.
- Alternative fuel infrastructure gaps:Biomass and waste-derived fuel processing capacity remains underdeveloped in Eastern European kiln markets, limiting fuel-switching velocity.
- Silica sand quality depletion:Premium-grade silica reserves for soda-lime glass production face extraction restrictions in Benelux and Northern France, constraining float glass expansion.
Strategic Opportunities
- Polish and Romanian construction acceleration:EU cohesion fund disbursements are concentrating infrastructure investment in these underpenetrated markets, creating first-mover advantages for ready-mix concrete networks.
- Building-integrated photovoltaics convergence:Transparent and semi-transparent photovoltaic glass technologies are merging with conventional curtain wall specifications, opening premium facade markets.
- Digital product passport mandates:The Ecodesign for Sustainable Products Regulation will require granular material traceability, rewarding early investments in blockchain-enabled supply chain documentation.
Industry Challenges
- EPD certification bottlenecks:Environmental Product Declaration verification capacity through ECHA-aligned frameworks faces 12-18 month backlogs, delaying low-carbon product market entry.
- Kiln retrofit capital intensity:Oxyfuel combustion and carbon capture retrofits for cement production require sustained capex commitments amid volatile construction demand cycles.
- Cross-border regulatory fragmentation:French RE2020, German EnEV, and Italian CAM edilizia maintain divergent embodied carbon calculation methodologies, complicating pan-European product standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Building Materials Market |
| Market Size in 2026 | $485.6 Billion |
| Market Size in 2035 | $740.51 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cement, Aggregates, Bricks, Glass Application: Residential, Commercial, Industrial, Infrastructure Material: Wood, Metal, Concrete, Plastic End User: Contractors, Developers, Homeowners, Governments |
| Companies Covered | HeidelbergCement, Cemex, Saint-Gobain Group, Kingspan Group Plc, Knauf Gips KG, CRH, ArcelorMittal, BASF SE, Holcim, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Building Materials Market Emerging Trajectories
Material science advances and regulatory stringency are converging to restructure competitive advantage around verified carbon performance rather than scale economies alone.
Calcined clay and limestone filler technologies are unifying supplementary cementitious material supply chains with conventional clinker production. Major infrastructure contractors in the Netherlands and Denmark are specifying LC3 blends for marine and tunnel applications. This convergence is compressing the cost premium for low-carbon concrete to sub-15% levels in Nordic procurement markets.
REACH authorization processes for novel flame retardants in insulation substrates are tightening just as the Energy Performance of Buildings Directive mandates higher thermal efficiency. Stone wool manufacturers face reformulation timelines of 24-36 months to maintain CE marking compliance. German and Austrian regulators are accelerating alternative mineral wool chemistry approvals to prevent supply discontinuity.
Developer procurement teams are consolidating specification authority around whole-life carbon metrics rather than first-cost optimization. Engineering consultancies in London, Paris, and Frankfurt are embedding embodied carbon calculators into early-stage design workflows. This behavioral pivot is most visible in commercial office and logistics verticals where institutional investor ESG mandates drive material selection.
Europe Building Materials Market Segmentation
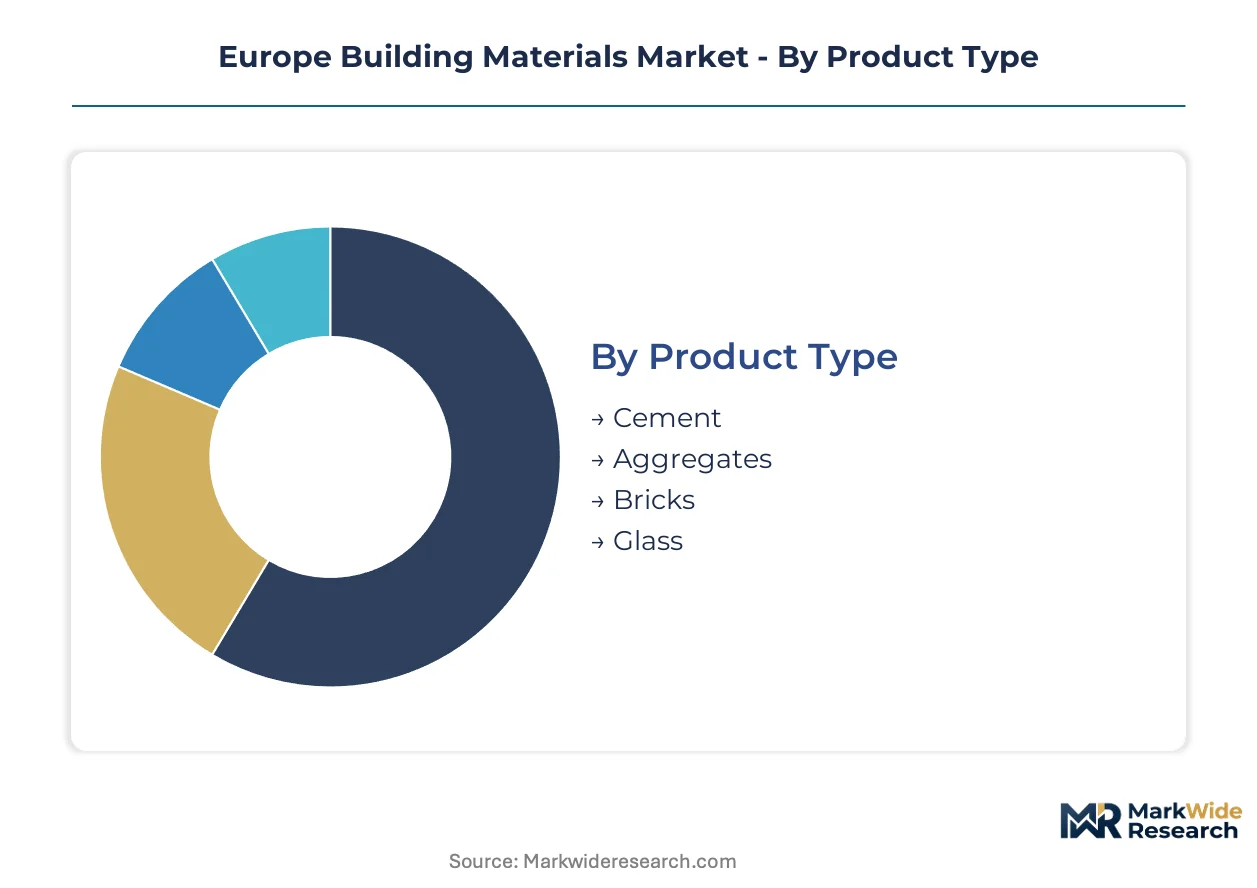
Segmentation reveals how carbon regulations and retrofit mandates are fragmenting demand across material grades and buyer types. Specification authority is shifting toward contractors with EPD certification capabilities and developers with institutional ESG mandates.
Product Type:
Cost tier separates commodity bulk materials from premium low-carbon certified grades commanding specification loyalty.
- Cement:Portland and blended formulations with clinker factors below 0.65 dominate volume. German and French retrofit programs are accelerating demand for LC3 and calcined clay blends as the EU Green Deal's embodied carbon benchmarks compress margins for conventional production.
- Aggregates:Crushed stone, sand, and gravel supply concrete production and road base. Nordic infrastructure investment and Polish cohesion fund disbursements are concentrating demand in Baltic Sea extraction corridors facing marine licensing constraints.
- Bricks:Fired clay masonry units serve traditional residential construction. Italian and Spanish producers face kiln electrification pressures under national CAM edilizia derivations.
- Glass:Soda-lime silica formulations with thermal performance coatings command premium positioning. Benelux silica sand depletion is constraining float glass expansion just as building-integrated photovoltaics create new facade applications.
Volume sits with cement and aggregates; growth tilts toward low-carbon certified cement and coated glass.
Application:
Project scale and carbon accountability intensity determine material specification workflows and procurement authority concentration.
- Residential:Single and multi-family housing drives insulation and engineered wood demand. Germany's Building Energy Act and France's RE2020 regulations mandate deep energy retrofits in existing housing stock, concentrating specification around cross-laminated timber and stone wool.
- Commercial:Office, retail, and logistics assets face institutional investor ESG mandates. Frankfurt, Paris, and London engineering consultancies embed embodied carbon calculators into early-stage design workflows, prioritizing whole-life metrics over first-cost.
- Industrial:Manufacturing facilities and warehouses require fire-rated assemblies. Steel framing dominates structural applications where contractor specification loyalty centers on certified fire performance.
- Infrastructure:Transport, water, and energy assets command long-durability material specifications. Dutch and Danish marine contractors specify LC3 concrete for tunnel and port applications where chloride resistance governs.
Residential captures absolute volume; commercial infrastructure delivers margin expansion through certified low-carbon procurement.
Material:
Supply chain maturity and carbon intensity separate established mineral-based systems from emerging biogenic alternatives.
- Wood:Cross-laminated timber, glulam, and laminated veneer lumber achieve structural equivalence with steel and concrete in German and Austrian building codes. Nordic mass timber code parity is unlocking multi-story applications fastest.
- Metal:Structural steel and aluminum framing concentrate in commercial and infrastructure verticals. Carbon border adjustment mechanism implementation is protecting domestic low-carbon steel investments against import competition.
- Concrete:Ready-mix and precast formulations incorporating supplementary cementitious materials dominate structural volume. CRH and HeidelbergCement compete on logistics density and clinker substitution capabilities respectively.
- Plastic:PVC, polycarbonate, and composite formulations serve piping, roofing, and insulation applications. REACH authorization timelines for novel flame retardants are tightening just as thermal efficiency mandates intensify.
Concrete retains structural volume dominance; wood-based materials gain share fastest through code approval expansion.
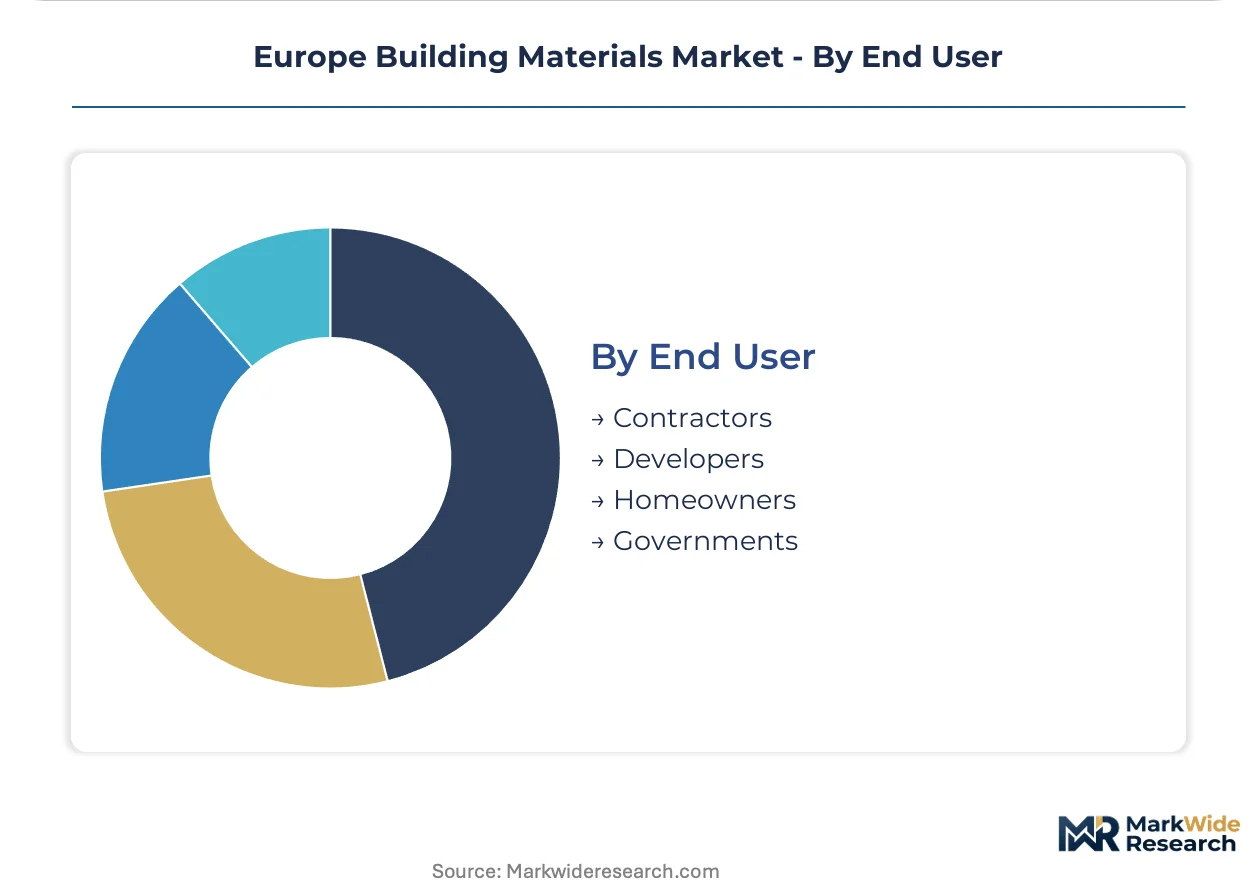
End User:
Technical capability and procurement scale separate specification-consolidating professionals from price-sensitive dispersed buyers.
- Contractors:General and specialty contractors with EPD certification capabilities control material selection on public and institutional projects. 12-18 month EPD verification backlogs through ECHA-aligned frameworks are favoring incumbents with established certification pipelines.
- Developers:Commercial and residential developers with institutional capital partnerships embed whole-life carbon clauses into procurement. Paris and Frankfurt developer procurement teams have consolidated specification authority around verified carbon performance.
- Homeowners:Individual residential property owners drive repair and maintenance demand. German and French retrofit subsidy programs are concentrating homeowner purchasing through certified contractor networks.
- Governments:National and municipal procurement authorities mandate embodied carbon thresholds in public construction. EU cohesion fund disbursements in Poland and Romania are accelerating infrastructure material demand.
Contractors and developers command specification authority; government procurement is expanding fastest through Green Deal implementation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity limestone deposits in the Mediterranean and Baltic regions anchor cement decarbonization efforts. Nordic biomass reserves and Benelux silica sand corridors shape raw-material access for low-carbon building materials.
Germany
Residential retrofit mandates and industrial decarbonization investments concentrate demand for low-carbon concrete and engineered wood. The Building Energy Act mandates deep energy retrofits in existing housing stock. The Rhine-Ruhr industrial corridor hosts clinker substitution pilot programs at major cement facilities.
France
Public procurement rules and institutional investor ESG mandates accelerate specification of certified low-carbon materials. The RE2020 regulations impose embodied carbon thresholds on new construction. The Paris metropolitan area anchors engineering consultancy clusters embedding whole-life carbon calculators into design workflows.
Poland
EU cohesion fund disbursements channel infrastructure investment into transport and energy assets. National procurement authorities mandate embodied carbon thresholds for public construction. The Silesian and Greater Poland voivodeships concentrate ready-mix concrete demand from highway and rail expansion.
Netherlands
Marine infrastructure specifications and circular economy mandates drive demand for LC3 concrete blends. Dutch environmental regulators enforce strict chloride resistance standards for tunnel and port applications. The Rotterdam port complex anchors biomass fuel import infrastructure serving regional cement kilns.
Sweden
Mass timber code parity and sustainable forestry certification unlock multi-story construction applications. Nordic building authorities granted cross-laminated timber structural equivalence with steel and concrete. The Stockholm-Uppsala corridor concentrates engineered wood manufacturing and architectural specification expertise.
Europe Building Materials Market Vendor Landscape
Global majors compete with regional champions across decarbonization technology and distribution density. The market structures around consolidated cement and glass sectors alongside fragmented specialty insulation and engineered wood niches. Three archetypes dominate: integrated building materials conglomerates with fuel-switching capabilities, national champions with logistics moats, and timber specialists with code-certification advantages. Competitive moves center on clinker substitution partnerships and mass timber certification infrastructure investments.
Within the integrated materials tier, HeidelbergCement and Holcim occupy positions anchored by Nordic biomass fuel integration and alternative fuel processing scale. Saint-Gobain Group exemplifies the premium insulation archetype through manufacturing depth in glass wool and stone wool substrates. CRH sits within the distribution-focused segment, competing on ready-mix concrete logistics density across British and Irish urban corridors.
| Leading Market Players |
|---|
| HeidelbergCement |
| Cemex |
| Saint-Gobain Group |
| Kingspan Group Plc |
| Knauf Gips KG |
| CRH |
| ArcelorMittal |
| BASF SE |
| Holcim |
| Others |
Supply Flow & Price Mechanics
Clinker substitution feedstock indices cascade through European cement supply chains, compressing margins for conventional producers while rewarding biomass-integrated kiln operators with cost advantages in carbon-intensive markets. LC3 blend premiums have compressed to sub-15% levels in Nordic procurement corridors where calcined clay supply chains unify with conventional production.
Pricing Analysis
Environmental Product Declaration certification bundling separates premium low-carbon grades from unbundled commodity supply. Three-tier pricing structure across certified low-carbon, transitional blended, and conventional clinker-heavy grades reflects clinker factor and EPD verification status. Price differentiation hinges on carbon border adjustment mechanism exposure and biomass fuel integration depth. Margins are tightening for Mediterranean producers facing limestone feedstock concentration vulnerability, while Nordic biomass-integrated operators maintain pricing power. Contractor procurement teams with institutional ESG mandates show least price sensitivity; dispersed homeowner repair segments remain most price-sensitive.
Supply Chain Analysis
CE marking and EPD verification gating through ECHA-aligned frameworks creates 12-18 month certification backlogs favoring incumbents with established documentation pipelines. Geographic supply concentration centers on Germany, France, and Poland for cement and ready-mix concrete, with Nordic corridors dominating mass timber manufacturing. Raw material dependencies include high-purity Mediterranean and Baltic limestone, Benelux silica sand reserves, and Nordic biomass fuel stocks. Single-source vulnerability concentrates in premium-grade silica extraction facing Benelux and Northern France licensing restrictions. Distribution runs through contractor-controlled specification networks and developer procurement consolidation in Paris, Frankfurt, and London.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPD verification capacity constraints prop pricing for certified low-carbon grades as 12-18 month backlogs limit qualified supply expansion. Material producers face capital allocation decisions between kiln retrofit commitments and offtake partnership structures.
For Market Incumbents: Hedge clinker substitution technology exposure through calcined clay partnership structures in Germany and France. Cement producers should anchor biomass fuel integration in Nordic corridors where alternative fuel infrastructure gaps in Eastern Europe limit competitor velocity. Defensive consolidation around EPD certification pipelines protects against emerging timber specialists capturing multi-story structural specifications. For New Entrants and Emerging Players: Cross-laminated timber fire-rating certification technology offers entry into German and Austrian multi-story construction codes where mass timber achieves structural equivalence with steel. White-space targets concentrate in Polish and Romanian infrastructure material supply where EU cohesion fund disbursements accelerate demand ahead of domestic production scale. Building-integrated photovoltaics facade integration provides a specification-led go-to-market angle in Benelux and Dutch marine infrastructure verticals. For Investors and Strategic Acquirers: Distressed-cycle entries favor biomass-integrated cement operators in Nordic markets where fuel-switching advantages compound carbon border adjustment protection. Long-term viability over the next decade rests on clinker substitution technology ownership and EPD certification infrastructure scale. Acquisition targets should demonstrate established verification pipelines and alternative fuel processing capabilities. Watch Nordic building code expansion for cross-laminated timber structural equivalence as the inflection signal for engineered wood manufacturing capacity valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Clinker Substitution Partnership | LC3 blend technology alliances with calcined clay suppliers compress low-carbon premium in German retrofit markets. |
| Biomass Fuel Integration | Nordic biomass import infrastructure at Rotterdam anchors cost advantages under EU carbon border adjustment mechanism. |
| Mass Timber Certification Investment | Cross-laminated timber fire-rating approvals unlock multi-story applications in German and Austrian building codes. |
| EPD Verification Pipeline Expansion | ECHA-aligned certification capacity investments overcome 12-18 month backlogs delaying low-carbon product market entry. |
| Ready-Mix Concrete Network Density | Urban corridor logistics control in British and Irish markets defends share against regional challengers. |
Methodological Framework
Document review covered EU Green Deal regulatory filings, ECHA construction product registration databases, and national CAM edilizia derivations, complemented by interviews with cement plant operations directors, engineered timber specification consultants, and public procurement officers in Germany, France, and Poland. Secondary validation drew from EU customs trade data, national building energy act implementations, and SEC disclosures from listed building materials conglomerates. Bottom-up demand modeling across retrofit program disbursements and top-down macro construction spend triangulation anchored volume estimates.
Segmented outputs across product type, application, material category, and end-user archetype fed into analytical frameworks spanning the projection horizon. Modeled dimensions included clinker factor tiers, EPD certification status, and regional regulatory cluster stringency. CAGRs derived from construction spend elasticity to GDP, retrofit mandate enforcement timelines, and mass timber code approval trajectories. Industry-specific inputs encompassed biomass fuel price indices, silica sand extraction licensing constraints, and alternative fuel infrastructure development rates.
Several conditions sit outside the modeled scope, including unannounced national CAM edilizia derivations, REACH authorization timeline shifts for flame retardants, and abrupt kiln retrofit capital commitment suspensions. Forecasts reflect documented assumptions on EU Green Deal embodied carbon threshold enforcement velocity and EPD verification capacity expansion. A model refresh is warranted upon material change in Nordic mass timber structural equivalence code adoptions or carbon border adjustment mechanism phase-in acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Asia-Pacific Ceramic Sanitary Ware Market
Building & Construction Materials
Europe Construction Chemicals Market
Building & Construction Materials
Cleanroom Flooring Market
Building & Construction Materials
Acoustic Insulation Market
Building & Construction Materials
North America Gypsum Board Market
Building & Construction Materials
Global Shotcrete/Sprayed Concrete Market
Building & Construction Materials
Russia Ceramic Tiles Market
Building & Construction Materials
Vegetal Concrete Market
Building & Construction Materials
Fiberglass Light Poles Market
Building & Construction Materials
Steel Casing Pipes Market
Building & Construction Materials
Spray Foam Market
Building & Construction Materials
Wood Shingles Market
Building & Construction Materials
Garage and Overhead Doors Market
Building & Construction Materials
Indonesia Cement Market
Building & Construction Materials
Precast Concrete Members Market
Building & Construction Materials
North America Ceiling Tiles Market