
 Street Cleaning Machine Market | 2026-2036
Street Cleaning Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Street Cleaning Machine Market Analysis
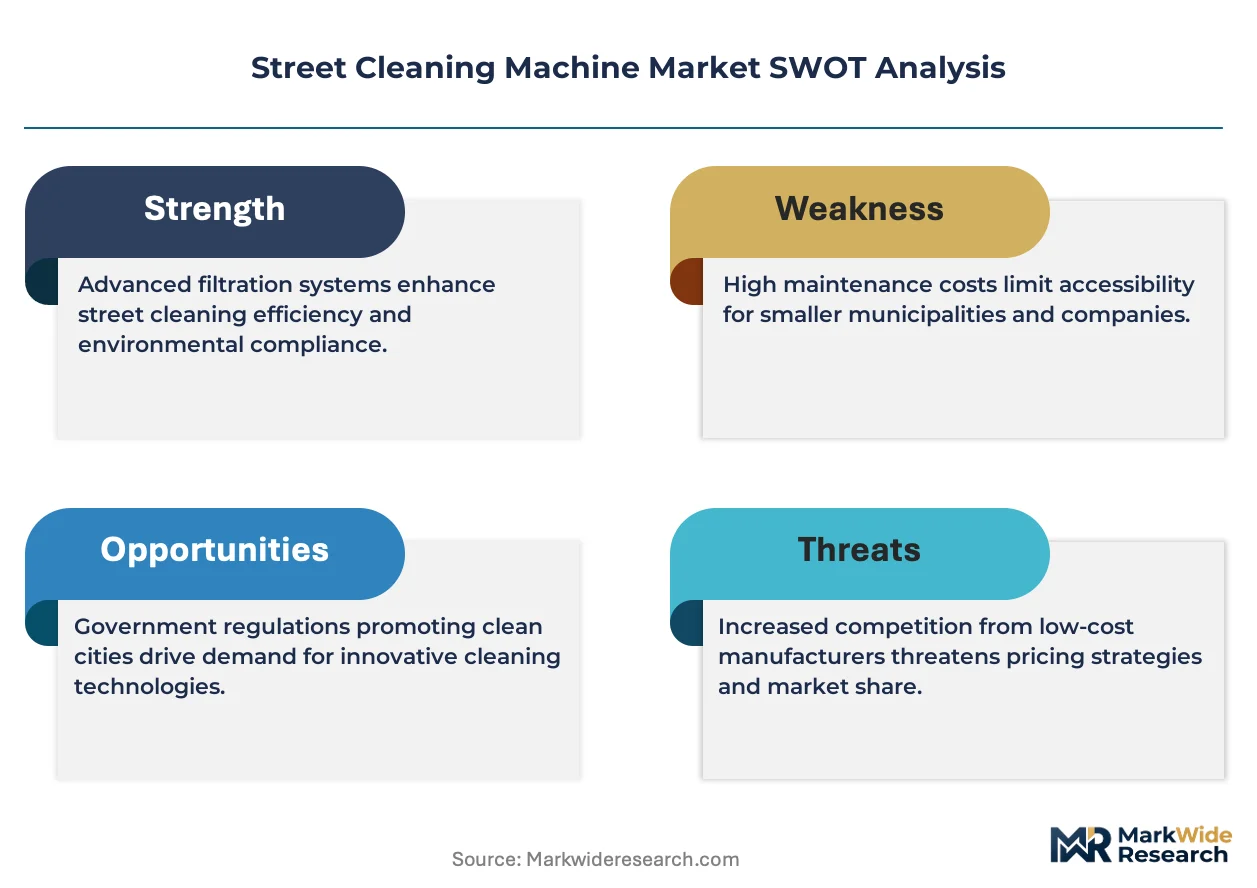
Asset-light municipal leasing is narrowing the competitive field for capital-intensive sweepers. Tennant leverages its direct municipal channel network to secure multi-year service contracts. Bucher Industries anchors European demand through specialized truck-mounted configurations. Federal Signal competes in North American emergency and infrastructure-adjacent cleaning segments.
Street cleaning machines are purpose-built surface debris collection vehicles, typically employing vacuum suction, mechanical brooms, or regenerative air systems to remove particulate matter from roadways and paved areas, with hopper capacities ranging from compact urban units to truck-mounted systems exceeding eight cubic meters. Their primary commercial purpose is compliance-driven urban hygiene maintenance and stormwater runoff prevention. Truck-mounted sweepers dominate municipal procurement budgets due to coverage efficiency, while electric power sources represent the fastest-expanding technology segment as cities phase out diesel fleets. Walk-behind units occupy stable margin pools in confined industrial and airport gate environments where maneuverability outweighs throughput.
The EPA enforces Tier 4 Final emissions standards that effectively bar non-compliant diesel sweepers from US public procurement, while the EU Green Deal and F-Gas Regulation accelerate electrification timelines across European municipal fleets. China's MEE implements dual carbon goals that restrict internal combustion engine registrations in tier-one city sanitation tenders. Stakeholders must monitor how battery supply constraints and charging infrastructure gaps reshape equipment availability in high-volume procurement windows.
Market Dynamics
Battery-electric drivetrain mandates from regulators in Germany, California, and China are forcing compressed replacement cycles across municipal fleets, while charging infrastructure gaps and battery supply constraints create procurement bottlenecks in high-volume tender windows.
Growth Catalysts
- EU Green Deal fleet electrification mandates:Municipalities across Germany, France, and the Netherlands must retire diesel sweepers by statutory deadlines, creating predictable replacement demand.
- China's dual carbon goals:MEE restrictions on internal combustion engine registrations in tier-one city sanitation tenders redirect procurement toward electric configurations.
- Stormwater runoff compliance:EPA Clean Water Act enforcement in the US is tightening particulate collection standards for municipal surface maintenance contracts.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack availability constrains electric sweeper production schedules during peak municipal procurement seasons.
- Charging infrastructure capital requirements:Depot electrical upgrades impose unbudgeted costs on municipalities with legacy diesel maintenance facilities.
- F-Gas Regulation refrigerant constraints:EU rules on hydrofluorocarbons complicate thermal management system sourcing for all-electric sweepers.
Strategic Opportunities
- Asset-light municipal leasing models:Service-based contracts replace capital purchases, opening recurring revenue streams for equipment providers with maintenance networks.
- India's Smart Cities Mission sanitation tenders:Metropolitan corridor contracts in Mumbai, Delhi, and Bangalore specify mechanized cleaning for urban hygiene targets.
- Autonomous navigation convergence:LiDAR and machine vision integration enables overnight operation in restricted traffic windows without labor cost escalation.
Industry Challenges
- High-voltage technician certification timelines:Municipal maintenance departments face 12-18 month training pipelines for safe electric drivetrain servicing.
- Legacy fleet integration complexity:Mixed diesel-electric operations require duplicate parts inventories and bifurcated technician specializations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Street Cleaning Machine Market |
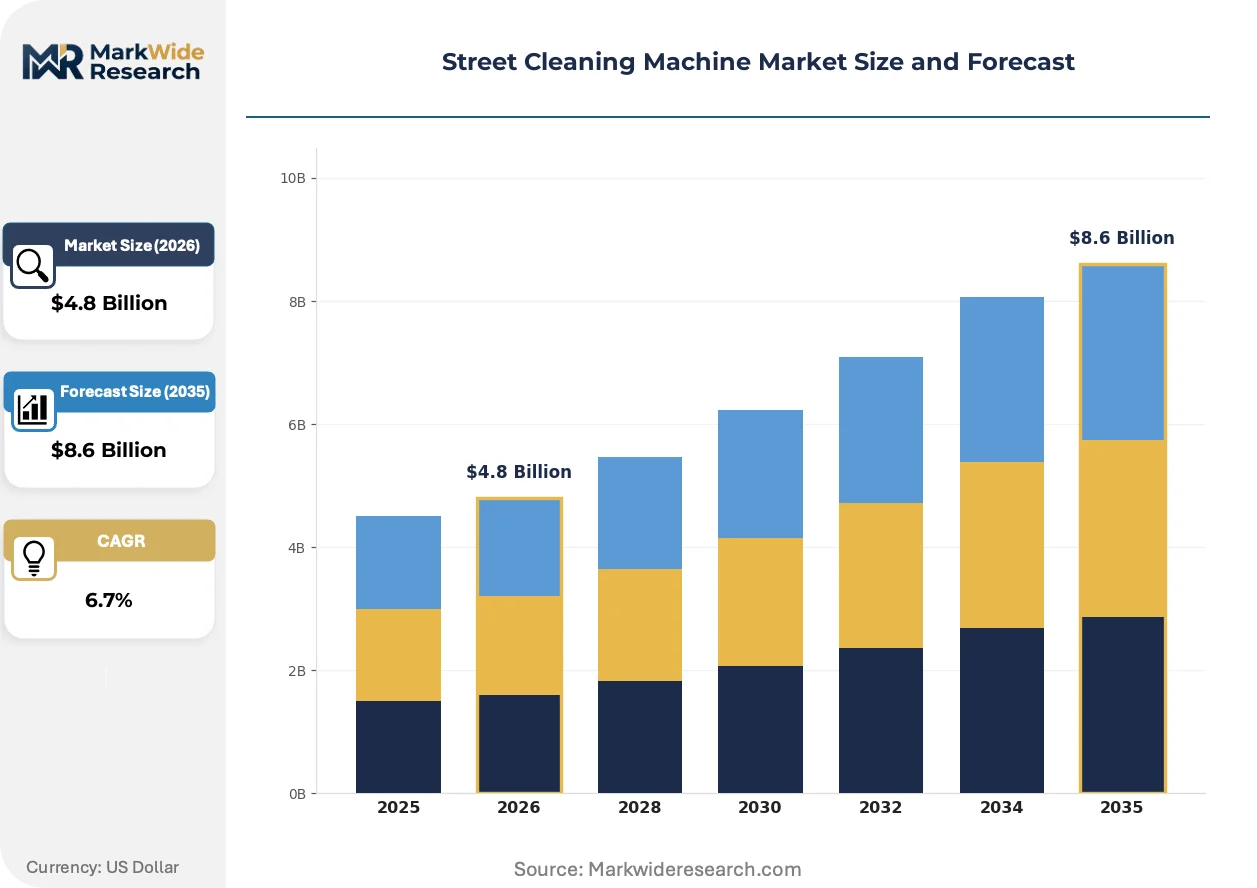
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Sweepers, Truck-mounted Sweepers, Ride-on Sweepers, Walk-behind Sweepers Technology: Vacuum, Mechanical, Regenerative Air, Waterless End User: Municipalities, Contractors, Industrial Facilities, Airports Power Source: Electric, Diesel, Hybrid, Gasoline |
| Companies Covered | Kärcher Municipal, Tennant, Elgin Sweeper Company, Bucher Industries, Hako, Victory Sweepers, Americhem, Federal Signal, XBroom by Nescon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Street Cleaning Machine Market Emerging Trajectories
Electrification is compressing product lifecycles while autonomous operation and data-driven fleet management reshape how municipalities contract for urban sanitation services.
Regenerative air suction systems with integrated particulate filtration are rendering obsolete conventional mechanical broom configurations in European municipal specifications. German and Dutch fleet operators specify these systems for superior fine-dust capture required by EU air quality directives. The technology is rendering obsolete vacuum-dominant designs that cannot meet PM10 compliance thresholds in urban centers.
The EU F-Gas Regulation is tightening refrigerant phase-down schedules that affect thermal management in battery-electric sweepers. Manufacturers must redesign cooling systems using natural refrigerants or face component sourcing restrictions. Truck-mounted configurations with larger battery packs face the steepest engineering redesign timelines.
Performance-based service contracts are displacing equipment ownership in Scandinavian and North American municipal procurement. Contractors assume fleet availability risk while municipalities pay per cleaned kilometer. This model concentrates most visibly in Stockholm, Copenhagen, and Vancouver where labor cost pressures favor outsourced sanitation operations.
Street Cleaning Machine Market Segmentation
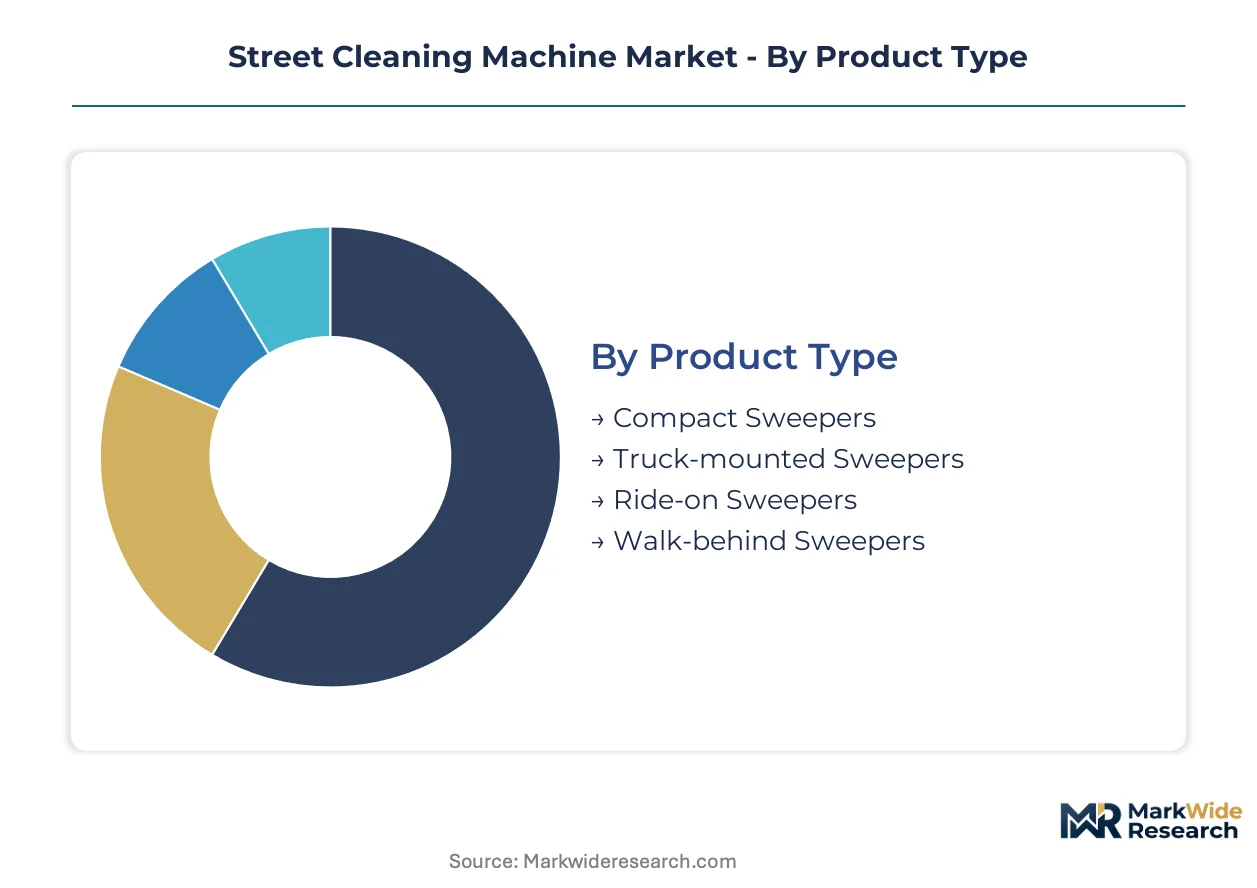
Street cleaning machine segmentation reflects divergent operational constraints across urban density gradients, regulatory environments, and capital deployment models. Equipment specifications vary sharply between high-throughput municipal corridors and confined industrial environments where maneuverability dominates procurement criteria.
Product Type:
Product configurations span the full operational spectrum from pedestrian-scale units to heavy-duty truck-mounted systems serving metropolitan arterial networks.
- Truck-mounted Sweepers:These chassis-integrated systems combine high-capacity hoppers exceeding eight cubic meters with highway-speed transit capability between cleaning zones. Municipal procurement in Germany and Japan concentrates here for coverage efficiency on urban arterial networks, though battery supply constraints compress delivery timelines during peak tender windows.
- Compact Sweepers:Purpose-built for narrow European city centers and historic districts where turning radius and curb access limit larger equipment. French and Dutch municipalities specify these units for UNESCO heritage zone maintenance where vehicle weight restrictions apply.
- Ride-on Sweepers:Mid-scale platforms serving industrial campuses and suburban commercial districts with operator-controlled brush and suction systems.
- Walk-behind Sweepers:Pedestrian-operated units dominating airport gate environments and manufacturing cleanrooms where debris volumes remain modest but precision matters.
Established volume favors truck-mounted configurations; emerging adoption favors compact sweepers as heritage zone regulations tighten.
Technology:
Debris collection mechanisms differentiate on particulate capture efficiency, water consumption, and compliance with municipal environmental standards.
- Regenerative Air:Closed-loop suction systems recirculate filtered air to maintain vacuum pressure while capturing sub-10-micron particulates. German fleet operators specify these for EU air quality directive compliance, with the technology displacing vacuum-dominant designs in Dutch municipal tenders.
- Vacuum:Conventional suction systems employing dedicated blowers and filter media for general-purpose debris collection. These units retain cost advantages in price-sensitive procurement across Indian Smart Cities Mission tenders where PM10 thresholds remain less stringent.
- Mechanical:Broom-and-conveyor configurations for heavy debris and construction site cleanup where abrasive materials degrade suction components.
- Waterless:Specialized systems eliminating spray suppression for drought-prone municipalities and water-restricted industrial environments.
Regulatory pressure favors regenerative air adoption; total cost considerations favor mechanical systems in emerging procurement markets.
End User:
Customer categories reflect fundamentally different procurement rhythms, contract structures, and equipment utilization patterns.
- Municipalities:Public sector buyers operating under statutory fleet electrification mandates from the EU Green Deal and California Air Resources Board. These entities drive volume through multi-unit tenders with 7-10 year replacement cycles, though charging infrastructure gaps delay electric fleet conversions.
- Contractors:Private service providers assuming fleet availability risk under performance-based contracts in Stockholm, Copenhagen, and Vancouver. Asset-light leasing models concentrate recurring revenue with OEMs maintaining direct service networks.
- Industrial Facilities:Manufacturing and logistics campuses with continuous cleanliness requirements tied to OSHA compliance and product contamination prevention.
- Airports:Gate and tarmac operators where FOD (foreign object debris) prevention drives specialized high-suction specifications.
Capital ownership concentrates in municipal procurement; service-based contracting gains fastest among contractor segments.
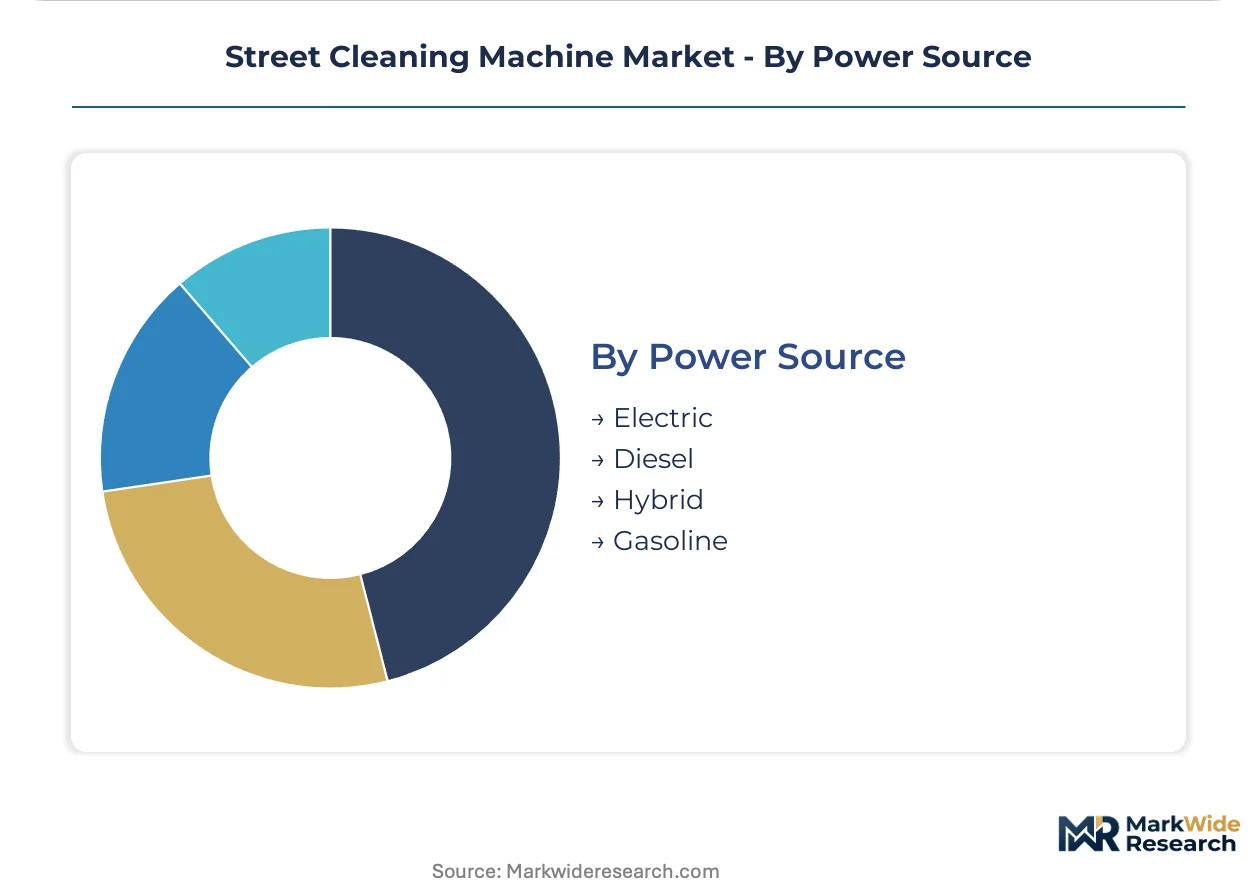
Power Source:
Propulsion systems face divergent regulatory timelines across major procurement markets, with electrification mandates compressing diesel phase-out schedules.
- Electric:Battery-electric drivetrains with lithium-ion packs sized for 8-12 hour shift operation. China's MEE restrictions on internal combustion engine registrations in tier-one city tenders redirect procurement toward these configurations, though cell supply concentration creates production bottlenecks.
- Diesel:Tier 4 Final compliant engines retaining cost and range advantages in markets without electrification mandates. Brazilian municipal fleets continue procurement where charging infrastructure remains undeveloped.
- Hybrid:Dual-mode systems offering electric operation in emission-restricted zones with diesel range extension.
- Gasoline:Compact engine options for walk-behind and light ride-on units where battery weight compromises maneuverability.
Regulatory mandates favor electric configurations; infrastructure reality favors diesel retention in secondary procurement markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German municipalities command 15-20% pricing premiums over Indian procurement for equivalent truck-mounted configurations, reflecting divergent regulatory compliance burdens and fleet electrification timelines across these markets.
Germany
KBA emissions enforcement and EU Green Deal fleet mandates drive compressed replacement cycles for diesel sweepers in municipal tenders. The F-Gas Regulation tightens refrigerant phase-down schedules affecting thermal management in battery-electric configurations. Procurement concentrates in North Rhine-Westphalia and Bavaria, where cities like Cologne and Munich specify regenerative air systems for PM10 compliance.
United States
EPA Tier 4 Final standards bar non-compliant diesel sweepers from public procurement, while California Air Resources Board mandates accelerate electric fleet conversions. Stormwater runoff enforcement under the Clean Water Act tightens particulate collection standards for surface maintenance contracts. Municipal demand clusters in California and the Northeast Corridor, where Los Angeles and New York Metro advance zero-emission sanitation fleet targets.
China
MEE restrictions on internal combustion engine registrations in tier-one city tenders redirect procurement toward battery-electric configurations. Dual carbon goals impose binding emissions reduction targets on municipal fleet operators. Equipment deployment concentrates in the Yangtze River Delta and Pearl River Delta, where Shanghai and Shenzhen specify mechanized cleaning for urban hygiene mandates.
India
Smart Cities Mission sanitation tenders in metropolitan corridors specify mechanized cleaning for urban hygiene targets. BIS certification requirements and PLI scheme incentives shape domestic manufacturing capacity expansion. Contract awards cluster in Maharashtra and Karnataka, where Mumbai and Bangalore issue multi-unit fleet procurement for corridor maintenance.
Brazil
Municipal fleet expansion proceeds without federal electrification mandates, preserving diesel cost advantages in undeveloped charging infrastructure markets. ANVISA environmental regulations focus on operational safety rather than emissions phase-out. Procurement concentrates in São Paulo and Rio de Janeiro, where metropolitan sanitation programs prioritize coverage efficiency over powertrain transition.
Street Cleaning Machine Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying drivetrains, suction systems, and filtration modules. The vendor base stratifies across three tiers: multinational equipment OEMs with direct municipal channels, regional fabricators serving price-sensitive procurement, and specialized subsystem suppliers. Strategic archetypes include full-lifecycle service providers, scale-driven manufacturers, and technology-focused electrification specialists. Competitive moves concentrate on asset-light leasing model expansion and charging infrastructure partnerships to secure recurring revenue streams.
Among European-headquartered platform integrators, Kärcher Municipal and Bucher Industries occupy positions anchoring municipal specification standards. Tennant represents the North American service-based contracting archetype, leveraging direct channel networks for multi-year fleet availability agreements. Elgin Sweeper Company exemplifies the specialized truck-mounted configuration segment, with municipal procurement concentration in infrastructure-adjacent cleaning applications.
| Leading Market Players |
|---|
| Kärcher Municipal |
| Tennant |
| Elgin Sweeper Company |
| Bucher Industries |
| Hako |
| Victory Sweepers |
| Americhem |
| Federal Signal |
| XBroom by Nescon |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese lithium-ion cell manufacturing is compressing battery pack pricing for electric sweeper OEMs while simultaneously eroding supplier margins and accelerating consolidation among Tier 2 drivetrain integrators serving European municipal fleets.
Pricing Analysis
Configured-to-order pricing for regenerative air truck-mounted sweepers commands substantial premiums over standard vacuum configurations in German municipal tenders. Three-tier pricing structure across premium, standard, and economy levels reflects divergent particulate filtration certification grades and after-sales service bundling. Cost compression in compact electric units is intensifying because battery supply bottlenecks during peak procurement windows force spot-market cell purchasing. Indian Smart Cities Mission contractors exhibit highest price sensitivity; Dutch heritage zone operators demonstrate lowest sensitivity due to UNESCO compliance mandates.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for battery-electric sweeper manufacturers. Manufacturing concentration centers on Germany for precision suction systems, China for lithium-ion packs and electric drivetrains, and Japan for compact hydraulic components. Raw material dependencies include lithium carbonate, rare-earth permanent magnets, and specialized filtration media. Single-source vulnerability persists for EU-compliant thermal management subassemblies subject to F-Gas Regulation phase-down schedules. Distribution runs through direct municipal procurement channels in developed markets and regional equipment distributors in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Street cleaning machine economics are shifting from equipment transaction to service-platform models as performance-based contracting and charging-infrastructure interoperability reshape how municipalities access fleet availability.
For Market Incumbents: Harden defensive positions by securing exclusive charging infrastructure partnerships in metropolitan corridor contracts before battery supply constraints ease. Deepen backward integration into lithium pack assembly to reduce exposure to cell spot-market volatility. Prioritize technician certification programs to accelerate municipal fleet conversion timelines and lock out service-competitor entry.
For New Entrants and Emerging Players: Build out asset-light leasing capabilities targeting mid-sized Indian municipalities where Smart Cities Mission tenders favor mechanized cleaning but capital budgets remain constrained. Establish service depots in secondary Brazilian cities where diesel retention persists and incumbent coverage gaps create white-space. Pursue autonomous navigation partnerships as the primary go-to-market angle for overnight operation contracts in restricted traffic windows.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among full-lifecycle service providers with direct municipal channel networks and captive maintenance infrastructure. Long-term viability over the projection horizon favors platforms with charging-infrastructure control and software-defined fleet management capabilities. Acquisition target archetype: regional fabricators with established municipal relationships and underutilized production capacity. Signal to watch: municipal RFP language shifting from equipment specifications to availability-guarantee terms.
| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Secures recurring revenue lock-in with municipalities facing depot electrical upgrade capital constraints. |
| Autonomous Navigation Integration | Enables overnight operation contracts in Los Angeles and New York Metro zero-emission fleet windows. |
| Regenerative Air Technology Licensing | Accelerates EU PM10 compliance adoption among price-sensitive Indian Smart Cities contractors. |
| Asset-Light Leasing Model Expansion | Concentrates recurring revenue with OEMs while transferring fleet availability risk from municipalities. |
| Technician Certification Program Buildout | Creates 12-18 month competitive moats against service entrants in high-voltage electric drivetrain maintenance. |
Methodological Framework
A spread of perspectives from municipal fleet managers, sanitation contracting executives, OEM platform engineers, and aftermarket service heads converged on the working assumptions driving this analysis. Primary interviews combined with secondary validation from SEC filings, EU tender databases, MEE registration records, and customs trade data established foundational inputs. Bottom-up equipment deployment modeling and top-down municipal budget allocation analysis were triangulated to constrain forecast variance.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product configuration, debris collection technology, end-user procurement structure, and powertrain architecture. CAGRs were derived from equipment replacement cycle analysis and regulatory mandate timeline alignment. Forecast inputs incorporated battery cell supply pipeline visibility and municipal charging infrastructure deployment schedules.
Stress conditions across lithium price volatility, charging infrastructure buildout delays, and technician certification pipeline bottlenecks were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and municipal budget continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Part Feeder Market
Construction Equipment
Snow Removal Market
Construction Equipment
Self-Drilling Screws Market
Construction Equipment
Asia Pacific Construction Equipment Market
Construction Equipment
Rotary Dryers Market
Construction Equipment
Stamping Machines Market
Construction Equipment
Electric and Hybrid Construction Equipment Market
Construction Equipment
Fully Automatic Metal Band Saw Machine Market
Construction Equipment
Sweden Construction Equipment Market
Construction Equipment
Draw Heat Setting Winder Market
Construction Equipment
Global Hydraulic Hammer Market
Construction Equipment
Asia-Pacific Road Marking Machine Market
Construction Equipment
Global Seam Welding Machine Market
Construction Equipment
Automatic Clay Brick Making Machine Market
Construction Equipment
Blanking Machine Market
Construction Equipment
Skid Steer Loader Market