
 Asia-Pacific Gypsum Board Market | 2026-2036
Asia-Pacific Gypsum Board Market Size, Share, and Industry Trends Forecast 2026-2036
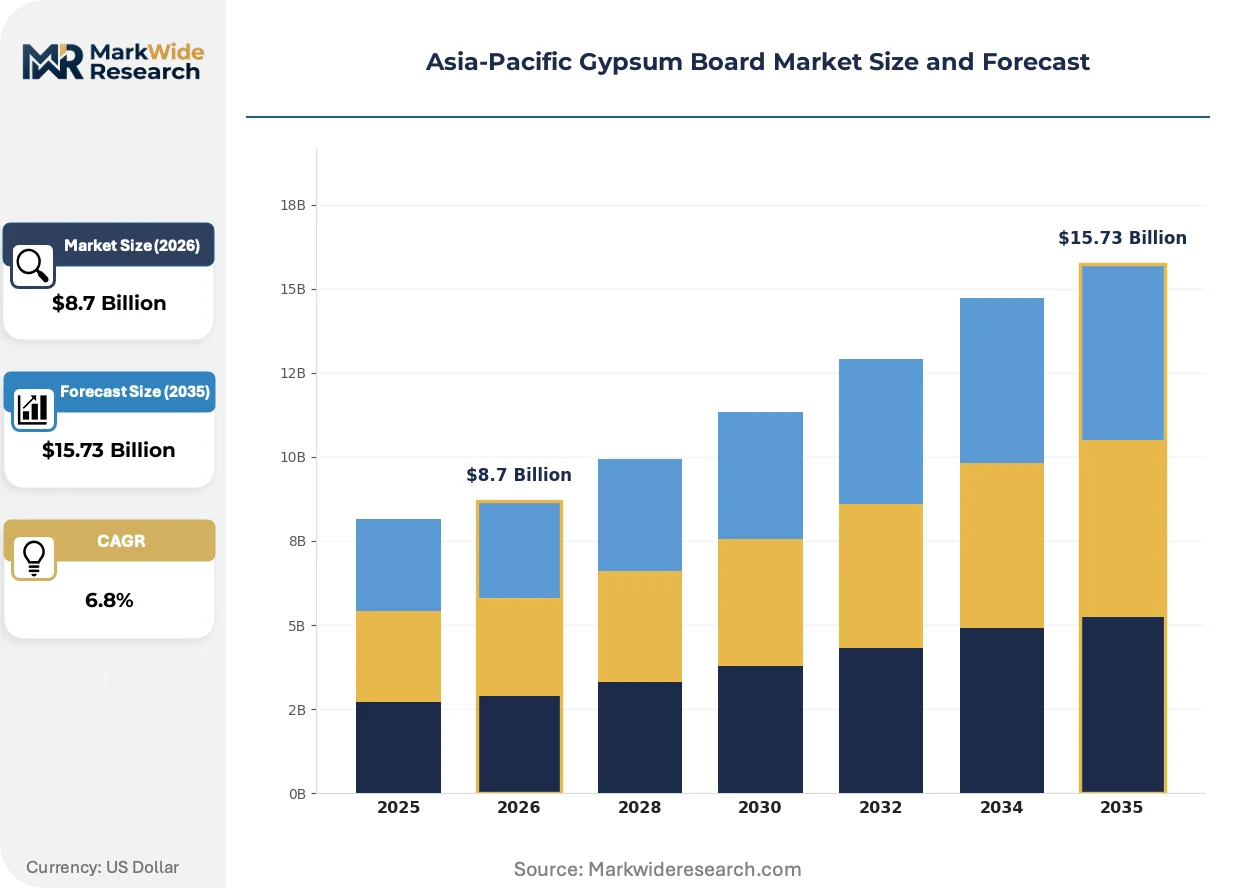
Asia-Pacific Gypsum Board Market Outlook
Lightweight core formulations and automated taper-edge processing are reshaping how gypsum boards achieve structural performance with reduced dead loads. BNBM leverages captive gypsum reserves and integrated paper liner production to sustain cost leadership across China's interior wall systems. Knauf Group anchors its Asia-Pacific position through localized manufacturing hubs that compete aggressively on delivery speed for commercial fit-out projects. Yoshino Gypsum specializes in high-precision moisture-resistant boards that dominate Japan's humid climate specifications.
Asia-Pacific gypsum board consists of a calcium sulfate dihydrate core pressed between paper facings, typically manufactured through continuous kiln drying at temperatures exceeding 150°C to achieve controlled density and flexural strength for non-load-bearing partition and ceiling systems. Fire-resistant board commands premium positioning in high-rise commercial applications across the region, while moisture-resistant variants capture expanding share in institutional kitchens, bathrooms, and tropical climate residential construction. Regular board retains volume leadership in cost-sensitive residential markets but faces margin compression as builders specify higher-performance grades.
China's GB standards and Ministry of Housing and Urban-Rural Development codes enforce fire-resistance ratings and formaldehyde emission limits that filter lower-grade imports from regional supply chains. Japan's METI building energy efficiency standards and JIS certification requirements for interior finishing materials create compliance barriers that Yoshino Gypsum and established domestic producers navigate with established testing protocols. India's BIS marking mandates for gypsum-based building materials are tightening, compelling suppliers to align product formulations with national construction quality benchmarks. Stakeholders must monitor how evolving green building certifications across these jurisdictions recalibrate material specifications and certification costs.
Market Dynamics
China's dual carbon goals are compressing energy-intensive kiln operations while India's BIS marking mandates filter substandard imports, forcing producers to reconfigure core formulations and certification protocols across the region.
Growth Catalysts
- GB Standards Enforcement:China's Ministry of Housing and Urban-Rural Development codes mandate fire-resistance ratings and formaldehyde emission limits, elevating specifications for interior wall systems in high-rise commercial construction.
- Urban Housing Expansion:India's metropolitan corridors absorb rising volumes of moisture-resistant and fire-rated panels as institutional kitchens and tropical climate residential projects multiply.
- Lightweight Core Formulations:Automated taper-edge processing reduces dead loads while maintaining flexural strength, enabling faster installation cycles in commercial fit-out projects.
Market Restraints
- Captive Gypsum Reserve Concentration:China's integrated paper liner producers control upstream supply chains, limiting raw material access for regional competitors without backward integration.
- Continuous Kiln Energy Intensity:Drying temperatures exceeding 150°C expose margins to electricity price volatility and carbon pricing mechanisms under tightening environmental compliance.
- Cement Board Substitution:Fiber-reinforced cement panels capture share in exterior sheathing and wet-area applications where gypsum's moisture susceptibility remains a technical limitation.
Strategic Opportunities
- Southeast Asian Residential Corridors:Vietnam, Indonesia, and Philippines present underpenetrated demand for fire-rated ceiling systems as building codes formalize multi-story residential construction standards.
- Green Building Certification Alignment:LEED and Green Star protocols across Australia and Singapore create specification pull for low-emission, recycled-content boards in premium commercial developments.
- Prefabricated Wall Module Integration:Off-site construction channels in Japan and South Korea demand dimensionally precise, moisture-resistant boards engineered for automated assembly lines.
Industry Challenges
- Fire-Resistance Testing Bottlenecks:JIS certification timelines in Japan and BIS laboratory capacity constraints in India delay product launches by 8-14 months for new formulations.
- Skilled Installation Labor Scarcity:Tapered-edge finishing and metal stud framing expertise concentrates in established urban markets, limiting quality deployment in secondary Indian and Indonesian cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Gypsum Board Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Board, Moisture-Resistant Board, Fire-Resistant Board, Soundproof Board Application: Residential, Commercial, Industrial, Institutional Distribution Channel: Direct Sales, Retail, Online, Wholesale End User: Builders, Architects, Contractors, Interior Designers |
| Companies Covered | Beijing New Building Material (BNBM), Saint-Gobain, Knauf Group, Yoshino Gypsum Co., Ltd., CSR Ltd, Etex Group, Georgia-Pacific Gypsum LLC, National Gypsum Company, USG Boral, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Gypsum Board Market Strategic Shifts
Automation in board finishing and regulatory tightening around embodied carbon are compressing traditional manufacturing economics while opening specification advantages for producers with certified low-emission processes.
Glass-fiber reinforced gypsum core technology is rendering obsolete conventional paper-faced regular board in high-traffic commercial ceilings. Property developers in Singapore and Australian office fit-out markets specify these panels for superior impact resistance and sag performance. The shift is compressing margin structures for commodity-grade producers while rewarding precision-engineered product lines.
METI building energy efficiency standards in Japan mandate thermal performance thresholds for interior finishing materials that filter uncertified imports from regional supply chains. Yoshino Gypsum and established domestic producers leverage pre-existing testing protocols while new entrants absorb compliance costs. The regulation most affects fire-resistant and moisture-resistant grades specified in institutional and healthcare construction.
Builder procurement is consolidating around direct mill relationships that bypass traditional distribution layers for large-scale residential developments. Volume contractors in India's National Capital Region and Bengaluru negotiate specification-grade pricing through annual framework agreements. The disintermediation is most visible in moisture-resistant board categories where project-scale demand justifies dedicated production runs.
Asia-Pacific Gypsum Board Market Segmentation
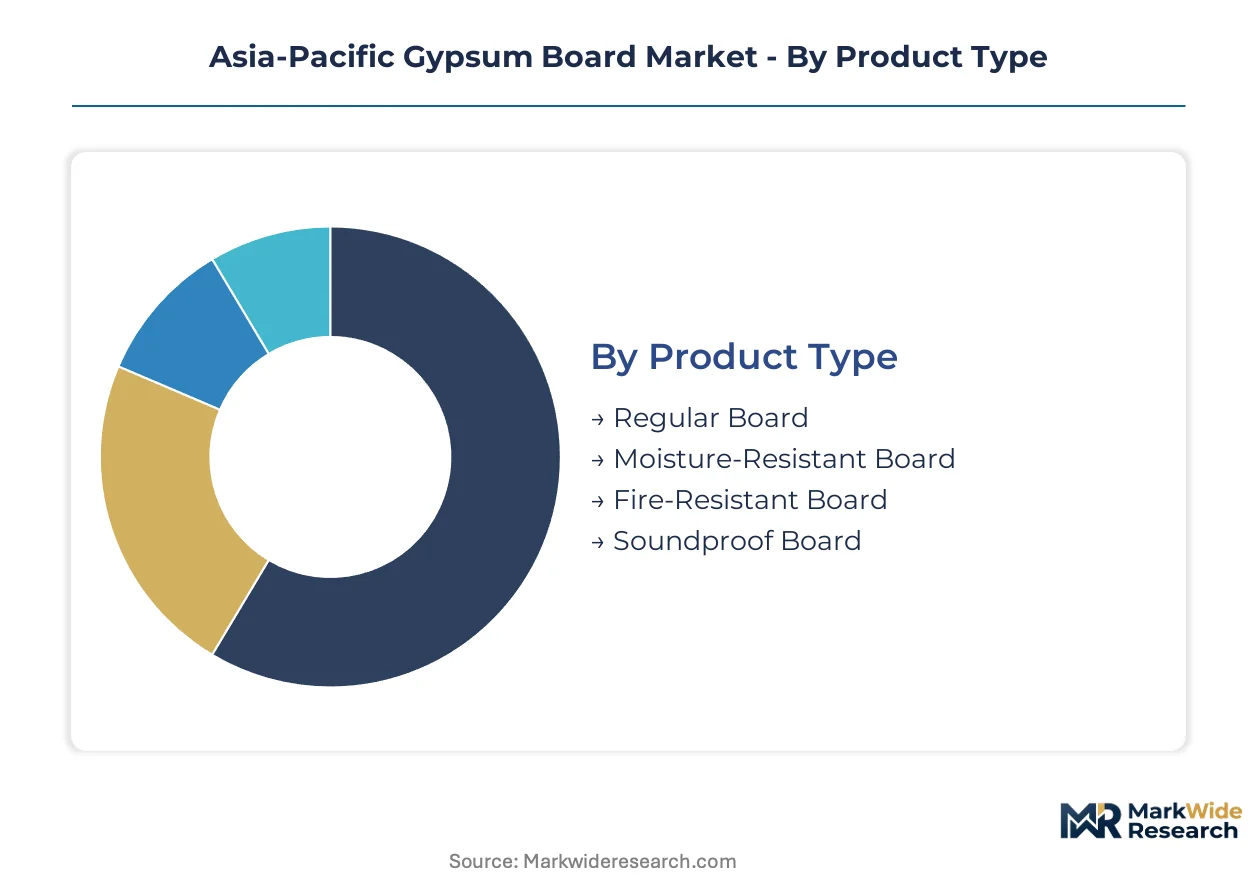
Segmentation in the Asia-Pacific gypsum board market reveals how specification-grade products command premium positioning while commodity volumes flow through distinct procurement channels. Understanding these divides exposes where margin compression concentrates and where certification barriers protect pricing power.
Product Type:
Fire-resistant and moisture-resistant grades turn inventory fastest in tropical commercial corridors, while regular board cycles slowly through cost-sensitive residential bulk purchasing.
- Regular Board:Standard calcium sulfate dihydrate core with paper facings serves non-load-bearing interior partitions in mass housing. India's National Capital Region and Bengaluru absorb the highest volumes as volume contractors negotiate annual framework agreements for project-scale deliveries.
- Moisture-Resistant Board:Silicone-treated core and green-tinted paper facing withstand humid conditions in institutional kitchens and tropical bathrooms. Vietnam and Philippines building codes are formalizing multi-story residential standards that mandate these specifications, accelerating specification pull.
- Fire-Resistant Board:Glass-fiber reinforced core achieves fire-resistance ratings under China's GB standards and Japan's JIS certification. High-rise commercial towers in Singapore and Australian office fit-outs specify these panels where compliance timelines extend 8-14 months.
- Soundproof Board:High-density core with viscoelastic damping layers addresses acoustic separation in healthcare and education construction. Japan's METI building energy efficiency standards filter uncertified imports, limiting supply to established domestic protocols.
Regular board anchors the volume base while moisture-resistant grades gain share at the steepest rate across Southeast Asian residential corridors.
Application:
Cost tier separation runs deepest between institutional specifications demanding certified performance and residential procurement optimizing per-square-meter material outlays.
- Residential:Multi-story housing across India's metropolitan corridors and Indonesia's urban expansion drives absorption of moisture-resistant and fire-rated panels. Tropical climate construction and formalizing building codes elevate performance requirements beyond commodity-grade specifications.
- Commercial:Office fit-out markets in Singapore and Australia specify glass-fiber reinforced boards for impact resistance and sag performance. Direct mill relationships bypass distribution layers as volume contractors consolidate procurement around annual framework agreements.
- Industrial:Manufacturing facilities and logistics warehouses utilize standard-grade partitions where fire-resistance ratings apply selectively to evacuation corridors and hazardous material storage zones.
- Institutional:Healthcare and education construction in Japan and South Korea demand dimensionally precise, moisture-resistant boards engineered for automated assembly lines in prefabricated wall modules.
Residential applications dominate volume throughput while institutional segments expand most quickly on green building certification alignment.
Distribution Channel:
Supply concentration favors direct channels where captive gypsum reserves and integrated paper liner production enable cost leadership, while fragmented retail and online layers serve spot purchasing.
- Direct Sales:Mill-direct relationships capture large-scale residential developments and commercial fit-out projects. Volume contractors in India's Bengaluru corridor negotiate specification-grade pricing through dedicated production runs that bypass traditional distribution markups.
- Retail:Builder merchants and construction supply yards serve renovation contractors and small-scale residential projects. Secondary Indian and Indonesian cities face skilled installation labor scarcity that limits quality deployment through this channel.
- Wholesale:Regional distributors aggregate demand from mid-tier contractors across Vietnam, Philippines, and Indonesia. Inventory cycles accelerate where building codes formalize multi-story residential fire-rated ceiling standards.
- Online:Digital procurement platforms emerge for standardized regular board specifications in cost-sensitive renovation markets. Logistics complexity and damage rates constrain penetration for moisture-resistant and fire-rated grades requiring careful handling.
Direct sales channels command the highest volume concentration while online platforms are climbing the fastest as procurement digitization penetrates secondary markets.
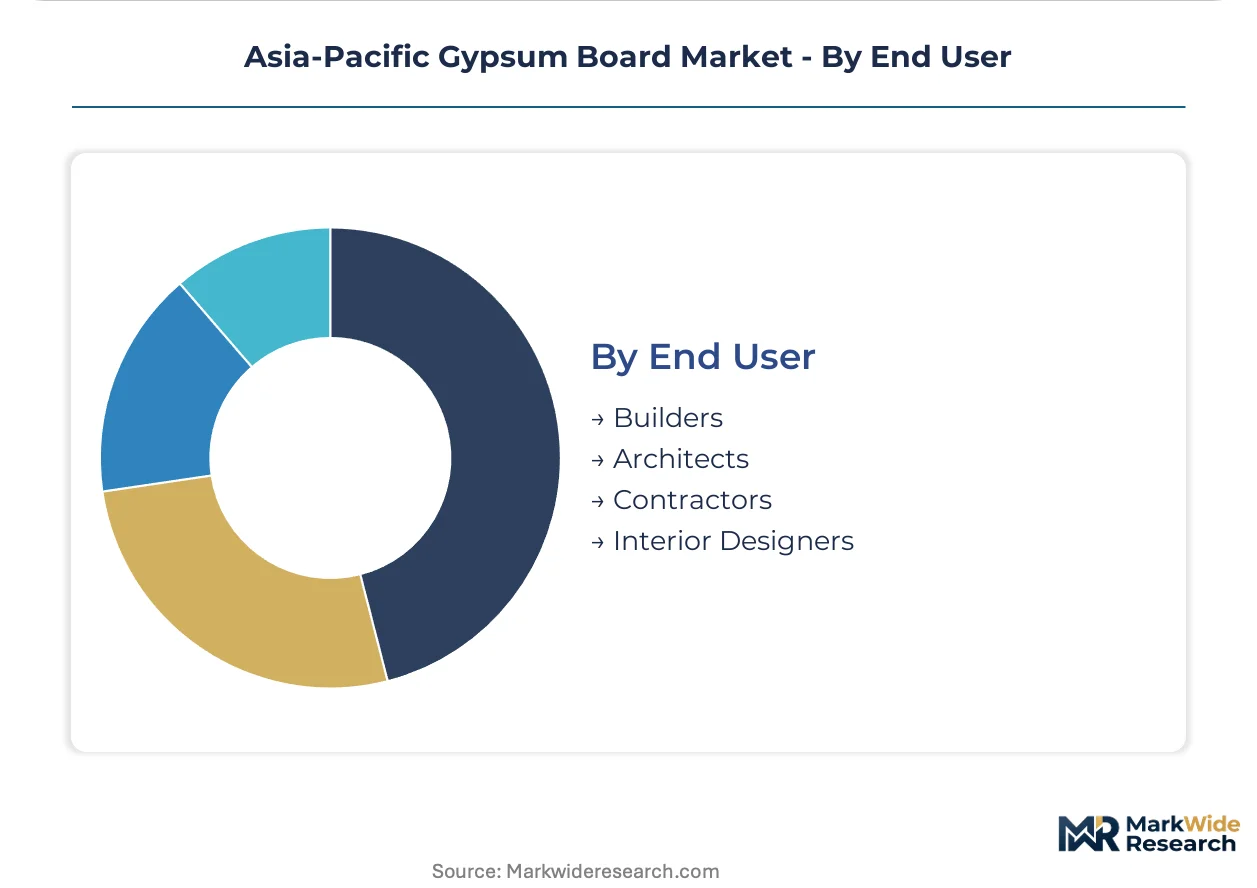
End User:
Customer type determines specification authority versus purchasing execution, with architects and interior designers setting performance standards that builders and contractors implement through procurement decisions.
- Builders:Volume developers in India's National Capital Region consolidate demand through annual framework agreements. Procurement disintermediation is most visible in moisture-resistant board categories where project scale justifies dedicated production runs.
- Contractors:Commercial fit-out specialists in Singapore and Australia source through localized manufacturing hubs competing on delivery speed. Tapered-edge finishing expertise concentrates in established urban markets.
- Architects:Specification authority in high-rise commercial and institutional projects mandates fire-resistance ratings and formaldehyde emission limits under China's GB standards and Japan's JIS certification. Green building certifications create pull for low-emission, recycled-content boards.
- Interior Designers:Premium commercial developments in Australian and Singaporean markets influence material selection for acoustic and aesthetic performance. Glass-fiber reinforced gypsum cores displace conventional paper-faced boards in high-traffic ceiling applications.
Builders anchor the volume base while architects gain influence at the steepest rate as green building certifications and energy efficiency standards tighten across the region.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports gypsum board production technology and surplus paper-faced panels to Southeast Asian construction corridors, while Japan and South Korea supply precision-engineered fire-rated systems to Australian commercial fit-out markets.
China
High-rise commercial towers in Shanghai and Shenzhen absorb fire-resistant panels as GB standards tighten formaldehyde emission limits. The Ministry of Housing and Urban-Rural Development enforces fire-resistance ratings that filter lower-grade imports. Yangtze River Delta manufacturers leverage captive gypsum reserves to dominate interior wall system supply chains.
Japan
Healthcare and education construction in Tokyo and Osaka demands dimensionally precise boards for prefabricated wall modules. METI building energy efficiency standards mandate thermal performance thresholds for interior finishing materials. Kanto region producers navigate JIS certification timelines that extend product launches for new formulations.
India
Metropolitan corridors in Bengaluru and the National Capital Region drive moisture-resistant board absorption for tropical climate residential projects. BIS marking mandates for gypsum-based building materials compel suppliers to align formulations with national construction quality benchmarks. Volume contractors negotiate annual framework agreements that bypass traditional distribution layers.
Vietnam
Multi-story residential construction in Ho Chi Minh City and Hanoi accelerates fire-rated ceiling system specifications as building codes formalize. The country's national construction regulator enforces emerging standards for high-rise fire safety. Southern manufacturing zones attract regional distributors aggregating demand from mid-tier contractors.
Australia
Premium commercial developments in Sydney and Melbourne specify low-emission, recycled-content boards aligned with Green Star certification protocols. State-level building energy codes elevate material specifications for interior finishing systems. Southeast Asian supply chains compete on delivery speed for large-scale office fit-out projects.
Asia-Pacific Gypsum Board Market Competitive Environment
On the supply side, the industry is consolidating around integrated manufacturers with captive raw material access and regional specialists competing on certification speed. State-linked building material conglomerates anchor volume production through backward integration into gypsum mining and paper liner manufacturing. European-headquartered multinationals deploy localized manufacturing hubs to compress delivery cycles for commercial fit-out markets. The dominant competitive moves involve capacity expansion in Southeast Asian growth corridors and strategic partnerships with prefabricated construction module integrators.
Among Asia-Pacific headquartered producers, Beijing New Building Material (BNBM) exemplifies the integrated conglomerate archetype through its position within China's state-affiliated building materials ecosystem. Yoshino Gypsum Co., Ltd. represents the precision-specialist tier, occupying a position shaped by decades of domestic regulatory navigation. Knauf Group anchors the European multinational vector, with its Asia-Pacific manufacturing footprint competing aggressively on logistics proximity for regional commercial projects.
| Leading Market Players |
|---|
| Beijing New Building Material (BNBM) |
| Saint-Gobain |
| Knauf Group |
| Yoshino Gypsum Co., Ltd. |
| CSR Ltd |
| Etex Group |
| Georgia-Pacific Gypsum LLC |
| National Gypsum Company |
| USG Boral |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta port congestion oscillations compress margin structures for moisture-resistant board shipments bound for Ho Chi Minh City and Jakarta, amplifying the spread between integrated producers with captive gypsum reserves and distributors absorbing demurrage costs in fragmented procurement channels.
Pricing Analysis
Glass-fiber reinforced core technology commands a generational premium over conventional paper-faced regular board, while silicone-treated moisture-resistant grades occupy a mid-tier position and commodity regular board faces persistent cost compression. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under China's GB standards and Japan's JIS protocols, with volume contractors in India's National Capital Region extracting project-scale discounts through annual framework agreements. Pricing pressure stems from cement board substitution in wet-area applications, eroding gypsum's specification share. Residential builders exhibit highest price sensitivity, while architects specifying high-rise commercial fire-rated systems prioritize compliance timelines over per-unit outlays.
Supply Chain Analysis
Integrated paper liner producers in China's Yangtze River Delta and Shandong corridor control upstream capacity, while regional distributors in Vietnam and Indonesia aggregate mid-tier contractor demand. Raw material dependencies center on natural gypsum deposits, synthetic gypsum from flue-gas desulfurization, and kraft paper liner supply. Logistics chokepoints at Shanghai and Ningbo ports expose just-in-time delivery schedules to vessel scheduling volatility. Distribution runs through direct mill relationships for large-scale developments, bypassing traditional wholesale markups in India's metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical installation services and certified finishing contractor networks expand faster than commodity board sales, as project developers outsource tapered-edge quality assurance to secure green building certification compliance.
For Market Incumbents: Build captive gypsum reserve moats through lease consolidation in China's Sichuan and Shandong mining belts. Defensive consolidation requires backward integration into synthetic gypsum processing to offset natural deposit depletion, while expanding JIS pre-certification testing capacity to compress Japan's 8-14 month compliance timelines. Channel control through direct mill relationships in India's Bengaluru corridor limits distributor margin extraction. For New Entrants and Emerging Players: Build out fire-rated ceiling system capabilities targeting Vietnam's formalizing multi-story residential codes before incumbent capacity locks in. The most penetrable white space sits in prefabricated wall module supply for Japan's healthcare construction automation pipelines. A specification-first go-to-market approach through architect engagement in Singapore's Green Star commercial developments bypasses commodity price competition. For Investors and Strategic Acquirers: Regional specialists with established BIS laboratory relationships and pre-certified product portfolios represent the priority acquisition archetype. Long-term viability hinges on positioning for Southeast Asian building code formalization and India's tightening construction quality benchmarks. Watch for inflection when Vietnam's national construction regulator mandates fire-resistance ratings in residential high-rises, triggering specification-grade inventory builds.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Gypsum Reserve Consolidation | Backward integration into Shandong and Sichuan deposits secures raw material cost leadership against import-dependent competitors. |
| JIS Pre-Certification Investment | Accelerated testing protocols in Kanto region facilities compress Japan's 8-14 month compliance timelines for new formulations. |
| Prefabricated Module Partnership | Engineering precision boards for Tokyo healthcare automation lines opens institutional specification channels with multi-year offtake visibility. |
| Direct Mill Relationship Expansion | Bypassing wholesale layers in India's National Capital Region captures margin compression from annual framework agreements. |
| Green Star Certification Alignment | Low-emission recycled-content positioning secures Sydney and Melbourne premium commercial specifications against Southeast Asian imports. |
Study Parameters
A spread of perspectives from gypsum board plant managers, procurement leads at Indian volume contractors, distribution channel partners in Vietnam, and technical R&D directors at Japanese precision manufacturers converged on the working assumptions underlying volume and value estimates. Primary interview insights triangulated against secondary validation from China's GB standards documentation, India's BIS marking protocols, Japan's METI building energy efficiency disclosures, and customs trade data tracking paper liner and synthetic gypsum flows. Bottom-up project pipeline analysis across Southeast Asian residential corridors combined with top-down construction spending forecasts to anchor demand-side modeling.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation dimensions spanning product type, application, distribution channel, and end-user specification authority. CAGRs derived from regression against historical construction completion data and forward-looking regulatory implementation schedules. Industry-specific forecast inputs included China's dual carbon policy enforcement trajectories and India's urban housing expansion pipeline under Smart Cities Mission allocations.
Sensitivities concentrate around building code formalization timelines in Vietnam and Philippines, BIS laboratory capacity constraints extending India product launches, and cement board substitution rates in wet-area specifications. Forecasts reflect documented assumptions on regulatory implementation speed and construction labor availability. Quarterly review of GB standards enforcement intensity, JIS certification queue lengths, and prefabricated construction module adoption in Japan is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Aerated Autoclaved Concrete (AAC) Market
Building & Construction Materials
Steel Roofing Market
Building & Construction Materials
North America Insulated Concrete Form (ICF) Market
Building & Construction Materials
US Steel Merchant and Rebar Market
Building & Construction Materials
China Marble Market
Building & Construction Materials
North America Oriented Strand Board Market
Building & Construction Materials
Outside Door Handle Market
Building & Construction Materials
North America Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Door Hinges Market
Building & Construction Materials
Thin Wall Mould Market
Building & Construction Materials
Cleanroom Flooring Market
Building & Construction Materials
US and Canada Corner Beads and Caps Market
Building & Construction Materials
GCC Concrete Blocks Market
Building & Construction Materials
US Metal Stadium Seating Market
Building & Construction Materials
Europe Building Materials Market
Building & Construction Materials
Door Canopy Market