
 Global Alopecia Market | 2026-2036
Global Alopecia Market Size, Share, and Industry Trends Forecast 2026-2036
Global Alopecia Market Intelligence
CE marking under the EU Medical Device Regulation is redrawing competitive boundaries for laser therapy devices and hair transplantation systems in Europe. Johnson & Johnson Services, Inc. leverages its dermatology heritage to sustain brand trust across prescription and device portfolios. Cipla Limited anchors its position through cost-engineered oral minoxidil and finasteride formulations. Pfizer Inc. competes via biologics pipelines targeting autoimmune-driven alopecia areata.
Alopecia encompasses pathological hair loss conditions ranging from androgenetic pattern baldness to autoimmune-mediated areata, diagnosed through trichoscopy, scalp biopsy, and hormonal assays, with treatments spanning pharmacologic modulation of dihydrotestosterone pathways to follicular unit extraction surgery. Oral medications command margin pools due to chronic dosing requirements and patent-protected JAK inhibitor entries, while laser therapy devices attract capital as home-use indications expand reimbursement discussions. Androgenetic alopecia dominates procedure volumes across dermatology clinics, though alopecia areata segments are accelerating fastest as IL-15 pathway biologics advance through regulatory stages.
FDA oversight shapes United States market access through dermatology drug approval pathways and 510(k) clearances for energy-based devices, while EMA MDR requirements in Europe enforce clinical evidence standards for hair transplantation systems. China's NMPA accelerates local biosimilar reviews for finasteride and minoxidil, compressing timelines for domestic manufacturers. Stakeholders must monitor JAK inhibitor safety signals and reimbursement decisions for biologic alopecia therapies across the FDA, EMA, and NMPA jurisdictions.
Market Dynamics
JAK inhibitor pipelines are compressing development timelines across autoimmune alopecia segments while dermatology clinics in the United States, Germany, and Japan absorb capacity constraints from rising patient volumes.
Growth Catalysts
- FDA Accelerated Approval Pathway:The FDA's breakthrough therapy designation for alopecia areata biologics compresses Phase III timelines from five years to under three, pulling forward revenue recognition for developers.
- Trichology Center Density:China and Japan now host over four thousand specialized hair restoration clinics combined, creating concentrated demand nodes that anchor regional pharmaceutical procurement.
- Home-Use Laser Devices:Low-level light therapy systems cleared under 510(k) pathways expand addressable patient populations beyond clinic-dependent treatments.
Market Restraints
- API Concentration Risk:Minoxidil and finasteride active pharmaceutical ingredients concentrate among Chinese and Indian contract manufacturers, exposing formulation supply to geopolitical friction.
- EMA MDR Compliance Burden:CE marking under the EU Medical Device Regulation demands clinical evidence portfolios that extend hair transplantation system approval timelines by eighteen to twenty-four months.
- Oral Therapy Side-Effect Profiles:Sexual dysfunction warnings on finasteride labels and cardiovascular monitoring requirements for oral minoxidil depress persistence rates in chronic dosing regimens.
Strategic Opportunities
- IL-15 Pathway Biologics:Next-generation monoclonal antibodies targeting the IL-15 signaling axis address treatment-resistant alopecia areata populations underserved by JAK inhibitors.
- Brazilian Regulatory Convergence:ANVISA alignment with FDA bioequivalence standards for topical solutions opens Latin America's largest pharmaceutical market to abbreviated new drug applications.
- Telemedicine Prescription Channels:Remote dermatology platforms in the United States and United Kingdom bypass geographic access constraints for oral therapy initiation.
Industry Challenges
- Trichoscopy Training Shortage:Diagnostic accuracy for early-stage androgenetic alopecia depends on operator proficiency in digital scalp imaging systems that require six-month certification programs.
- Biologics Cold-Chain Integrity:Temperature-controlled distribution for JAK inhibitor injectables strains last-mile logistics in emerging markets with limited refrigerated pharmacy infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Alopecia Market |
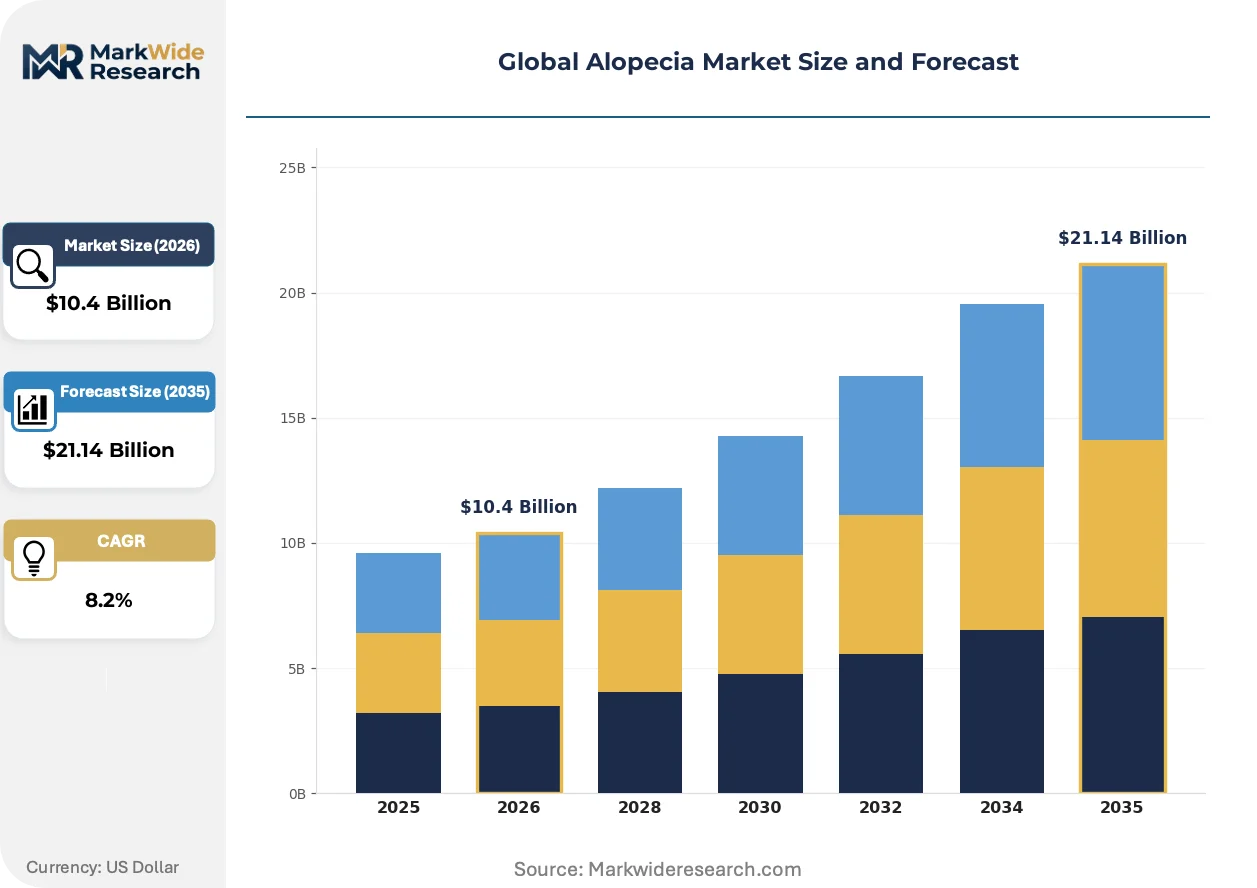
| Market Size in 2026 | $10.4 Billion |
| Market Size in 2035 | $21.14 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Solutions, Oral Medications, Laser Therapy Devices, Hair Transplantation Systems Therapy Area: Androgenetic Alopecia, Alopecia Areata, Cicatricial Alopecia, Telogen Effluvium End User: Dermatology Clinics, Trichology Centers, Hair Restoration Clinics, Beauty Salons Distribution Channel: Pharmacies, Online Retailers, Hospitals, Specialty Stores |
| Companies Covered | Merck & Co., Inc., Cipla Limited, Sun Pharmaceutical Industries Ltd., Dr. Reddy’s Laboratories Ltd., Johnson & Johnson Services, Inc., GlaxoSmithKline plc, Pfizer Inc., Viatris Inc., Lilly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Alopecia Market Strategic Shifts & Innovations
Regulatory convergence across FDA, EMA, and NMPA jurisdictions is standardizing clinical endpoint definitions while patient demand gravitates toward convenience-oriented delivery formats.
Low-level laser therapy devices are fragmenting the traditional clinic-centric treatment model. These semiconductor-based systems deliver photobiomodulation at specific wavelengths to stimulate follicular metabolism. Home-use adopters in the United States and Japan now represent the fastest-growing device purchaser segment. This shift is fragmenting revenue capture away from dermatology practices toward direct-to-consumer manufacturers and retail pharmacy channels.
EMA Medical Device Regulation enforcement is elevating clinical evidence thresholds for hair transplantation robotics. The 2017 MDR transition requires prospective clinical data for Class IIa mechanical surgical devices that previously cleared under self-certification. German and Swiss manufacturers are responding with registry-based post-market surveillance programs to satisfy notified body expectations.
Subscription-based oral therapy fulfillment is displacing traditional pharmacy dispensing in North American markets. Patients with chronic androgenetic alopecia now receive minoxidil and finasteride through vertically integrated telehealth platforms that bundle consultation, prescription, and delivery. This pattern concentrates most visibly in the United States, where direct primary care models bypass insurance prior authorization friction.
Global Alopecia Market Segmentation
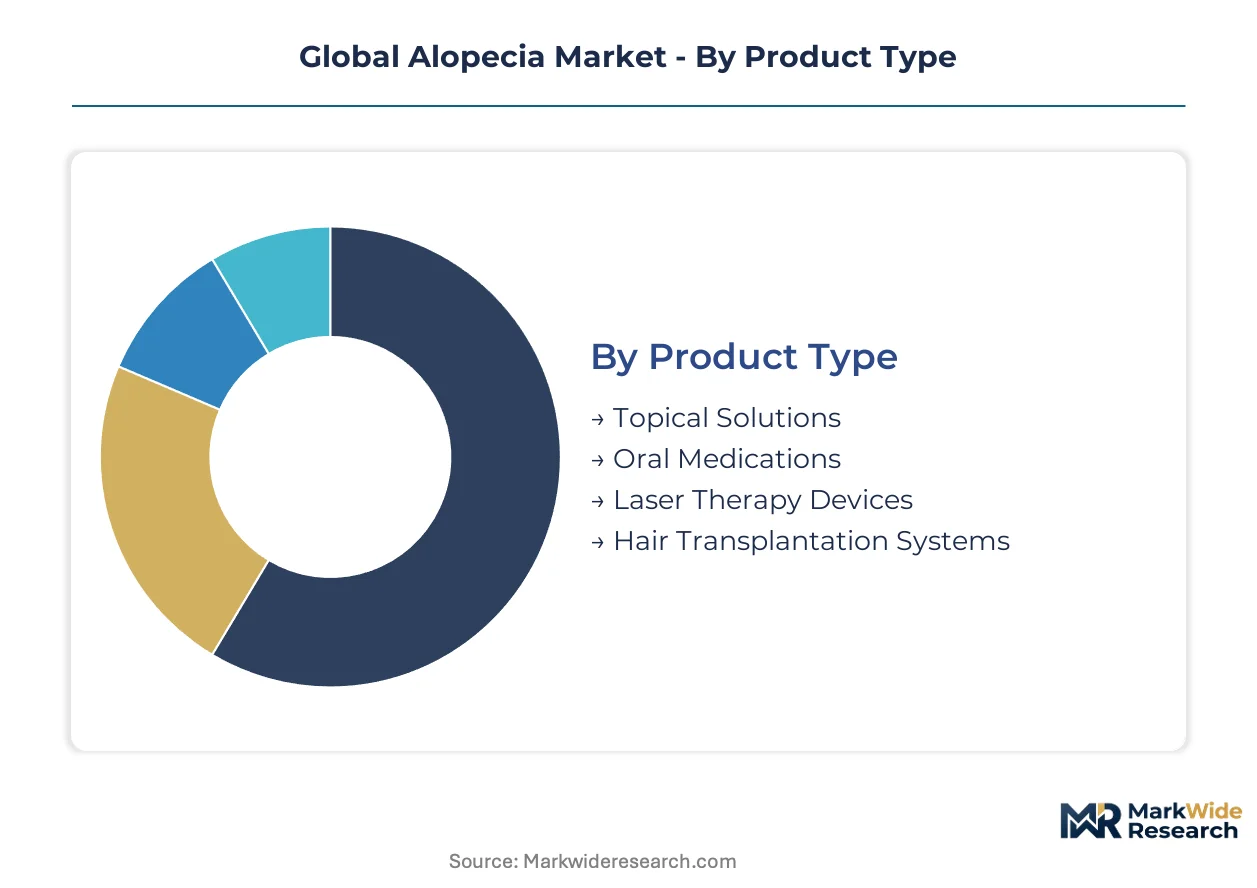
Alopecia treatment markets fragment across four distinct dimensions. Product type determines margin structure and regulatory pathway. Therapy area dictates patient population size and chronicity of demand.
Product Type:
Oral medications face the strongest substitution pressure from device-based alternatives and procedural solutions.
- Topical Solutions:Minoxidil-based foams and serums deliver vasodilation to follicular units through transdermal absorption. Dermatology clinics in the United States and Germany dispense these as first-line androgenetic alopecia interventions, though patient persistence suffers from application frequency requirements and scalp irritation profiles.
- Oral Medications:Systemic finasteride and minoxidil tablets modulate dihydrotestosterone pathways or potassium channel activity. China's NMPA accelerates biosimilar reviews for these molecules, compressing approval timelines for domestic manufacturers and intensifying price competition against originator formulations.
- Laser Therapy Devices:Low-level light systems cleared under FDA 510(k) pathways stimulate follicular metabolism through photobiomodulation.
- Hair Transplantation Systems:Robotic and manual follicular unit extraction platforms require EMA MDR clinical evidence portfolios.
Oral medications retain volume leadership; laser therapy devices hold the steepest expansion curve.
Therapy Area:
Cost tier stratification separates chronic maintenance conditions from acute autoimmune presentations.
- Androgenetic Alopecia:Pattern hair loss driven by dihydrotestosterone sensitivity in genetically predisposed follicles. Trichology centers in Japan and the United States concentrate procedure volumes here, with male patients dominating pharmaceutical procurement and female patients expanding aesthetic device adoption.
- Alopecia Areata:Autoimmune-mediated non-scarring hair loss involving T-cell attack on anagen follicles. FDA breakthrough therapy designations for JAK inhibitors pull forward revenue recognition for developers targeting treatment-resistant populations.
- Cicatricial Alopecia:Inflammatory scarring conditions destroying follicular stem cell niches.
- Telogen Effluvium:Diffuse shedding triggered by metabolic stress, hormonal shifts, or medication effects.
Androgenetic alopecia retains volume leadership; alopecia areata holds the steepest expansion curve.
End User:
Customer type determines reimbursement access and capital equipment purchasing authority.
- Dermatology Clinics:Board-certified practices integrating medical and cosmetic hair restoration services. German and Swiss clinics absorb EMA MDR compliance costs for hair transplantation robotics through registry-based post-market surveillance programs.
- Trichology Centers:Specialized facilities focused exclusively on scalp and hair disorders. China and Japan host over four thousand such centers combined, creating concentrated demand nodes that anchor regional pharmaceutical procurement.
- Hair Restoration Clinics:Surgical-focused practices emphasizing transplantation over medical management.
- Beauty Salons:Non-medical establishments offering aesthetic hair and scalp services.
Dermatology clinics retain volume leadership; trichology centers hold the steepest expansion curve.
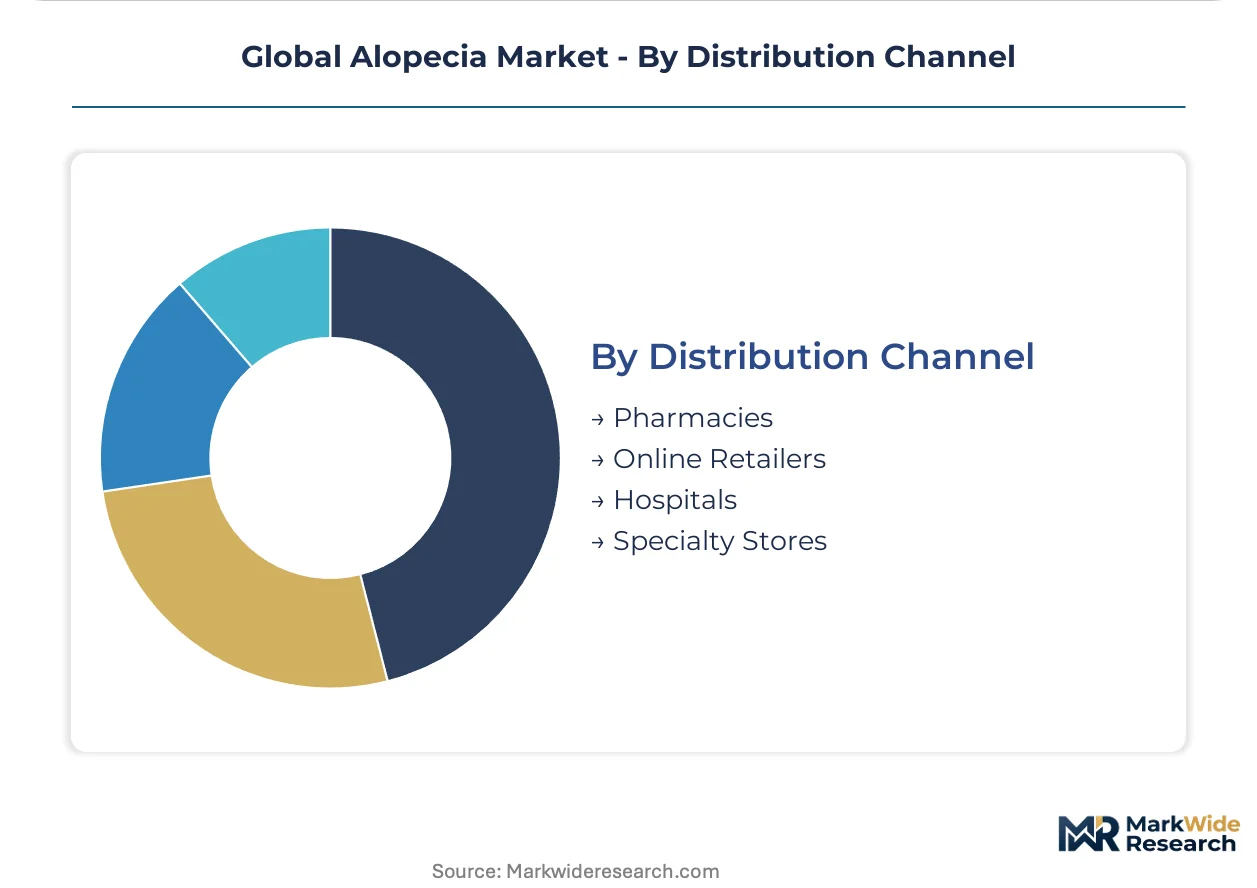
Distribution Channel:
Supply concentration shapes margin capture and patient access friction.
- Pharmacies:Traditional dispensing points for topical and oral alopecia therapies. United States retail chains face displacement pressure from telemedicine platforms bundling consultation, prescription, and delivery.
- Online Retailers:Direct-to-consumer channels capturing home-use laser device sales. Amazon and specialized wellness platforms fragment revenue away from clinic-dependent treatments in North American markets.
- Hospitals:Institutional settings managing severe or treatment-refractory cases.
- Specialty Stores:Beauty and wellness retailers offering over-the-counter solutions.
Pharmacies retain volume leadership; online retailers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways for alopecia areata biologics pull pharmaceutical investment toward the United States, while China's NMPA compresses biosimilar timelines for domestic manufacturers. Germany's EMA MDR enforcement elevates clinical evidence standards for transplantation devices. Japan's PMDA breakthrough designations and high trichology center density concentrate East Asian demand.
United States
Dermatology clinics in New York and Los Angeles absorb capacity constraints from rising patient volumes seeking JAK inhibitor therapies. FDA 510(k) clearances for low-level laser devices expand home-use indications beyond traditional clinic settings. The Boston-Cambridge corridor anchors biologics development pipelines targeting autoimmune alopecia segments.
Germany
EMA Medical Device Regulation compliance demands extend hair transplantation system approval timelines by eighteen to twenty-four months. German manufacturers respond with registry-based post-market surveillance programs to satisfy notified body expectations. Munich and Düsseldorf host specialized trichology centers that anchor regional pharmaceutical procurement for oral finasteride and minoxidil formulations.
China
NMPA accelerates local biosimilar reviews for finasteride and minoxidil, compressing timelines for domestic manufacturers against originator formulations. Shanghai and Beijing concentrate over two thousand specialized hair restoration clinics combined. API production for minoxidil concentrates among Zhejiang and Jiangsu contract manufacturers, exposing formulation supply to geopolitical friction.
Japan
PMDA breakthrough therapy designations for alopecia areata biologics mirror FDA pathways, pulling forward revenue recognition for developers. Tokyo and Osaka host the highest trichology center density in East Asia, creating concentrated demand nodes for pharmaceutical procurement. METI standards for medical device quality management shape laser therapy device market entry requirements.
Brazil
ANVISA alignment with FDA bioequivalence standards for topical solutions opens Latin America's largest pharmaceutical market to abbreviated new drug applications. São Paulo and Rio de Janeiro concentrate dermatology service capacity for androgenetic alopecia patients. Domestic manufacturers leverage regulatory convergence to expand minoxidil formulation production for regional export.
Global Alopecia Market Key Industry Players
Listed leaders compete with private specialists across prescription, device, and procedural segments. The vendor base separates into three tiers: multinational pharmaceutical conglomerates with dermatology heritage, cost-engineered generic manufacturers anchored in Indian and Chinese supply chains, and specialized device makers pursuing home-use laser indications. Strategic moves concentrate on telemedicine platform partnerships for oral therapy distribution and M&A activity targeting robotic transplantation capabilities.
Within the multinational pharmaceutical tier, Johnson & Johnson Services, Inc. and Pfizer Inc. exemplify divergent positioning archetypes. Johnson & Johnson leverages dermatology heritage to sustain brand trust across prescription and device portfolios. Pfizer occupies a biologics-focused position targeting autoimmune-driven alopecia areata through JAK inhibitor pipelines. Among cost-engineered manufacturers, Cipla Limited represents the generic formulation archetype, anchoring market position through oral minoxidil and finasteride production.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Cipla Limited |
| Sun Pharmaceutical Industries Ltd. |
| Dr. Reddy's Laboratories Ltd. |
| Johnson & Johnson Services, Inc. |
| GlaxoSmithKline plc |
| Pfizer Inc. |
| Viatris Inc. |
| Lilly |
| Others |
Cost & Logistics Intelligence
Home-use laser devices substituting clinic-dependent treatments redraws procurement geography toward direct-to-consumer channels while compressing margin capture for dermatology practices and elevating price transparency pressures across device manufacturers.
Pricing Analysis
Certification level creates the primary spread between premium FDA 510(k)-cleared laser systems and economy-tier unregulated imports. Subscription-based oral therapy fulfillment dominates pharmaceutical pricing models, bundling consultation and delivery through telehealth platforms. Price differentiation rests on regulatory grade and after-sales support depth, with telemedicine patients showing lowest sensitivity due to convenience premium while cash-pay clinic visitors exhibit highest elasticity.
Supply Chain Analysis
Inbound logistics costs through Shanghai and Ningbo ports strain API movement for minoxidil and finasteride active ingredients. Supply concentrates in Zhejiang and Jiangsu provinces of China alongside Indian contract manufacturers in Gujarat and Maharashtra. Raw material dependencies span minoxidil base compounds, finasteride intermediates, and semiconductor components for laser devices. Single-source vulnerability runs through Chinese API production, with distribution running through specialty pharmacy chains and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as the primary defensive moat, with FDA breakthrough therapy designations and EMA MDR compliance creating multi-year barriers to competitive replication.
For Market Incumbents: Consolidate robotic transplantation capabilities through targeted M&A to offset margin compression from home-use device fragmentation. Expand registry-based post-market surveillance programs to satisfy EMA notified body expectations and extend approval timelines for rival systems. Prioritize backward integration into API supply to mitigate geopolitical exposure from Chinese contract manufacturing concentration. For New Entrants and Emerging Players: ANVISA alignment with FDA bioequivalence standards offers the fastest certification pathway for topical solution entrants targeting Latin American expansion. Brazilian regulatory convergence creates white-space access for abbreviated new drug applications in minoxidil formulations. Telemedicine platform partnerships provide the most penetrable go-to-market angle for oral therapy distribution without clinic infrastructure investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed telehealth platforms bundling alopecia prescription fulfillment. Long-term viability favors vertically integrated players controlling both pharmaceutical procurement and patient acquisition channels. Watch JAK inhibitor safety signal developments as the critical inflection indicator for autoimmune alopecia segment valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Therapy Designation | Compresses Phase III timelines for alopecia areata biologics and accelerates revenue recognition. |
| EMA MDR Compliance Investment | Extends rival hair transplantation system approvals by eighteen to twenty-four months through evidence requirements. |
| Telemedicine Platform Partnership | Bypasses geographic access constraints and insurance prior authorization friction for oral therapy initiation. |
| API Backward Integration | Captive supply of minoxidil and finasteride intermediates mitigates geopolitical concentration risk. |
| IL-15 Pathway Pipeline Expansion | Addresses treatment-resistant alopecia areata populations underserved by first-generation JAK inhibitors. |
Research Approach
Cross-validation between dermatology clinic procurement data and pharmaceutical distribution records anchors the qualitative findings in this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and trichology center operators combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov, and hospital procurement databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation ensured consistency across estimation approaches.
Sensitivity analysis tested forecast robustness across alternative JAK inhibitor approval scenarios and biosimilar entry timing assumptions. Segmentation dimensions modeled include product type, therapy area, end user category, and distribution channel across the projection horizon. CAGRs derived from historical growth trajectory analysis and forward-looking prescription volume projections, with specific inputs capturing trichology center density expansion and telemedicine penetration rates.
Decision-makers should treat outputs as directional under stable regulatory approval timelines and intact API supply assumptions; material deviation would warrant model refresh. Forecasts reflect documented base-case assumptions regarding JAK inhibitor safety profiles and reimbursement decisions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Asia Pacific Liver Cancer Market
Specialty Medicine
Acute Lymphocytic-Lymphoblastic Leukemia (ALL) Therapeutics Market
Specialty Medicine
Cholangiocarcinoma (CCA) Therapeutics Market
Specialty Medicine
Hidradenitis Suppurativa (HS) Treatment Market
Specialty Medicine
Paronychia Treatment Market
Specialty Medicine
Ragweed Pollen Allergy Treatment Market
Specialty Medicine
Global Photodynamic Therapy Market
Specialty Medicine
GCC Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Selectin Blocker Market
Specialty Medicine
Cystic Fibrosis Therapeutics Market
Specialty Medicine
Acute Hepatic Porphyria (APH) Market
Specialty Medicine
Whipple's Disease Market
Specialty Medicine
Borderline Personality Disorder Market
Specialty Medicine
Barotrauma Market
Specialty Medicine
Alcoholic Liver Diseases Treatment Market
Specialty Medicine
Intestine (Small) Cancer Therapeutics Market