
 Borderline Personality Disorder Market | 2026-2036
Borderline Personality Disorder Market Size, Share, and Industry Trends Forecast 2026-2036
Borderline Personality Disorder Market Analysis
The Borderline Personality Disorder treatment landscape is rebalancing between premium biologic interventions and commodity generic psychotropics. Pfizer Inc. leverages its CNS franchise infrastructure to sustain formulary positioning across Medicaid and commercial plans. Johnson & Johnson Services, Inc. anchors its presence through Janssen's long-acting injectable expertise in mood stabilization. Otsuka Pharmaceutical Co., Ltd. differentiates through digital therapeutics integration alongside its established psychiatric portfolio.
Borderline Personality Disorder constitutes a severe Cluster B personality disorder marked by emotional dysregulation, interpersonal instability, and impulsivity, typically diagnosed via structured clinical interviews against DSM-5-TR criteria and treated through dialectical behavior therapy combined with mood stabilizers or atypical antipsychotics. Medications and Psychotherapy segments dominate current revenue pools, with Teletherapy and Online Platforms representing the fastest structural expansion as asynchronous digital delivery models reduce clinician burnout and extend rural access. Hospitalization retains stable inpatient economics while Support Groups capture marginal share through peer-recovery program integration.
The FDA governs psychiatric drug approvals through its Division of Psychiatry, while the DEA regulates controlled-substance prescribing patterns affecting benzodiazepine and stimulant adjunctive use in BPD symptom management. HIPAA compliance requirements shape teletherapy platform architecture and cross-state licensure barriers for digital providers. Stakeholders must monitor how the FDA's emerging guidance on digital biomarkers and remote therapeutic monitoring redefines evidentiary standards for reimbursement and formulary inclusion.
Market Dynamics
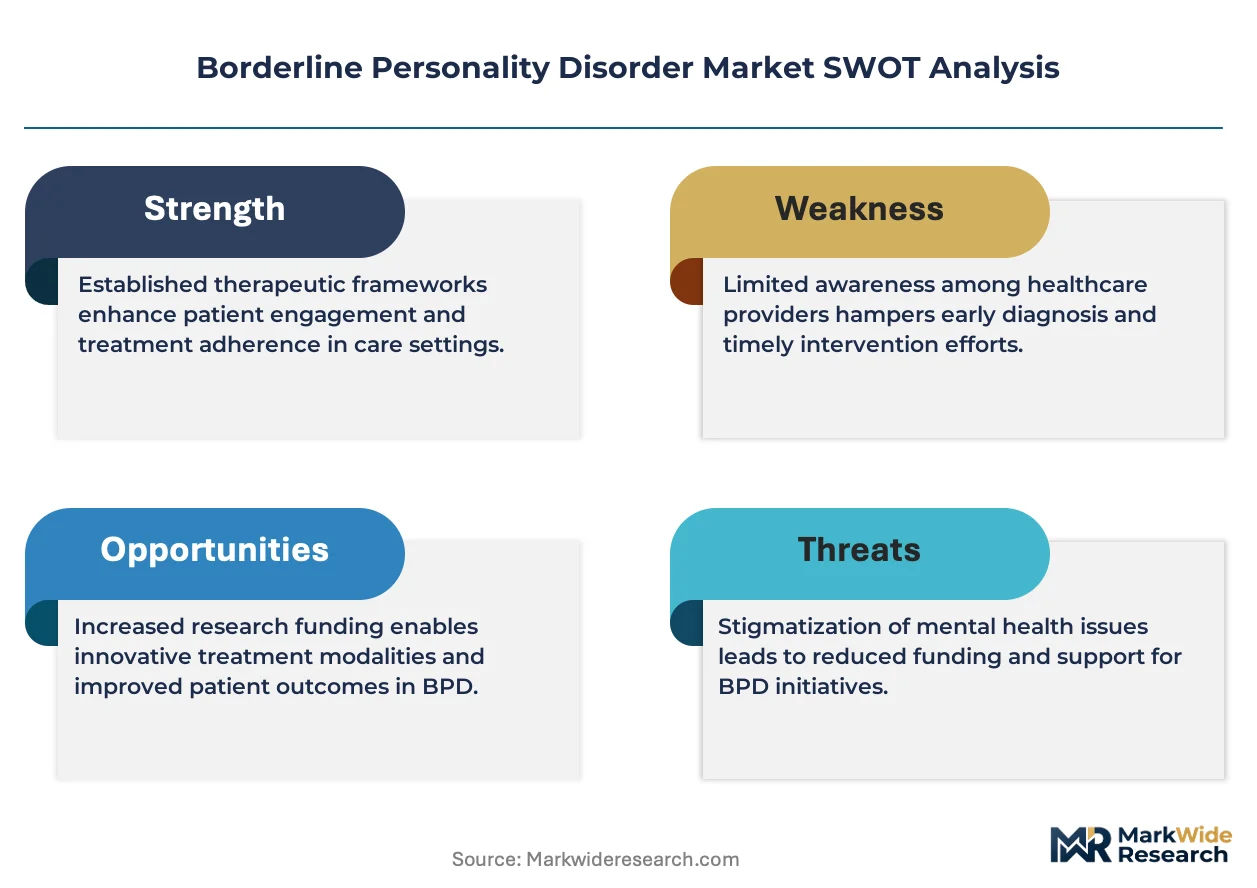
The FDA's accelerated approval pathways for psychiatric therapeutics are compressing development timelines and forcing developers to front-load digital biomarker evidence packages for BPD indications.
Growth Catalysts
- Medicaid expansion:Integrated care networks in the United States are extending formulary coverage for complex personality disorder management, expanding patient access to combination therapy protocols.
- Digital biomarker guidance:The FDA's emerging evidentiary standards for remote therapeutic monitoring are creating reimbursement pathways for asynchronous teletherapy platforms.
- Hospital infrastructure:Dedicated psychiatric unit construction is concentrating specialized clinical capacity for severe Cluster B presentations requiring multimodal intervention.
Market Restraints
- Controlled-substance prescribing limits:DEA regulations on benzodiazepine adjunctive use create formulary friction for symptom management protocols in acute crisis settings.
- Clinician supply concentration:Licensed dialectical behavior therapy practitioners cluster in urban academic medical centers, leaving rural and exurban markets underserved.
- HIPAA compliance architecture:Cross-state licensure barriers impose platform engineering costs that slow digital therapeutic deployment across fragmented regulatory jurisdictions.
Strategic Opportunities
- Peer-recovery program integration:Support group networks represent underpenetrated channels for sustaining long-term therapeutic engagement post-acute intervention.
- Asynchronous delivery models:Teletherapy platforms reduce clinician burnout while extending access to frontier markets lacking psychiatric specialty density.
- Long-acting injectable convergence:Mood stabilization protocols combining pharmacologic and psychosocial interventions open formulary positioning for integrated care contracts.
Industry Challenges
- Specialized practitioner training pipelines:Dialectical behavior therapy certification programs face capacity constraints that lag demand for evidence-based BPD treatment.
- Legacy EHR integration:Digital therapeutic platforms encounter interoperability friction with hospital system electronic health record architectures, delaying deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Borderline Personality Disorder Market |
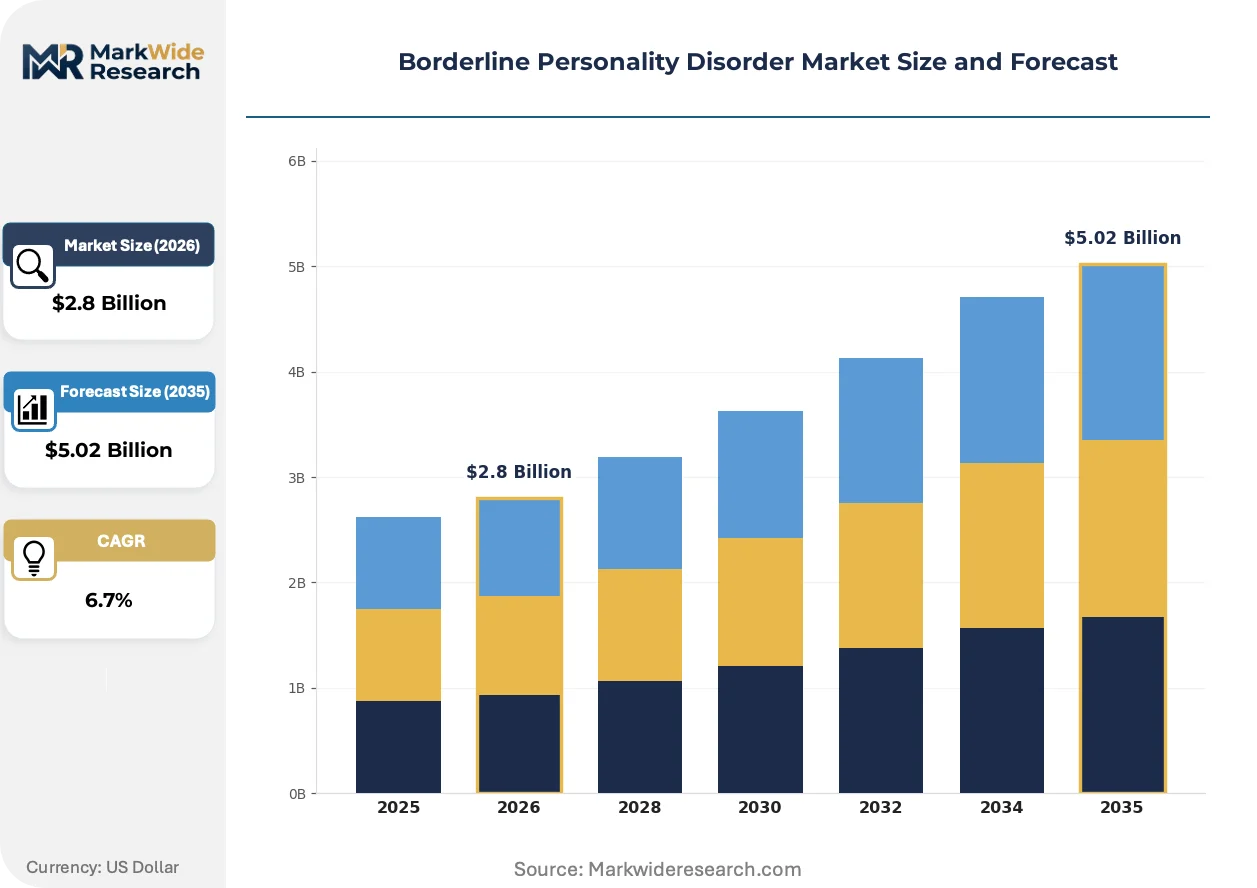
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Psychotherapy, Support Groups, Hospitalization Delivery Mode: In-person, Teletherapy, Group Sessions, Online Platforms End User: Patients, Clinics, Hospitals, Private Practices Therapy Area: Psychiatry, Psychology, Counseling, Behavioral Therapy |
| Companies Covered | GlaxoSmithKline plc, Johnson & Johnson Services, Inc., Pfizer Inc., Otsuka Pharmaceutical Co., Ltd., Novartis International AG, Eli Lilly and Company, Bristol Myers Squibb Company, Oryzon Genomics SA, AstraZeneca plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Borderline Personality Disorder Market Emerging Trajectories
Digital delivery architectures are displacing traditional session-based care models, while regulatory frameworks for remote monitoring reshape evidentiary requirements and reimbursement logic.
Machine learning-based digital phenotyping is rewriting how emotional dysregulation episodes are detected and intercepted. Academic medical centers in the United States are piloting passive sensor arrays for real-time affect monitoring in BPD patients. This capability is compressing the gap between symptom onset and clinical intervention, enabling just-in-time therapeutic dosing.
The FDA's guidance on software as a medical device is forcing digital therapeutic developers to structure randomized controlled trials around traditional pharmacologic endpoints. Psychiatric drug sponsors must now demonstrate non-inferiority to established interventions rather than novelty alone. This regulatory convergence most affects early-stage ventures targeting BPD symptom clusters without precedented trial designs.
Payers are unbundling after-hours crisis support from inpatient admission contracts, creating standalone reimbursement codes for telephonic and video-based de-escalation. Commercial plans in concentrated metropolitan markets are driving this shift, pressuring hospital systems to maintain 24/7 virtual psychiatric coverage or forfeit carve-out contracts to specialized vendors.
Borderline Personality Disorder Market Segmentation
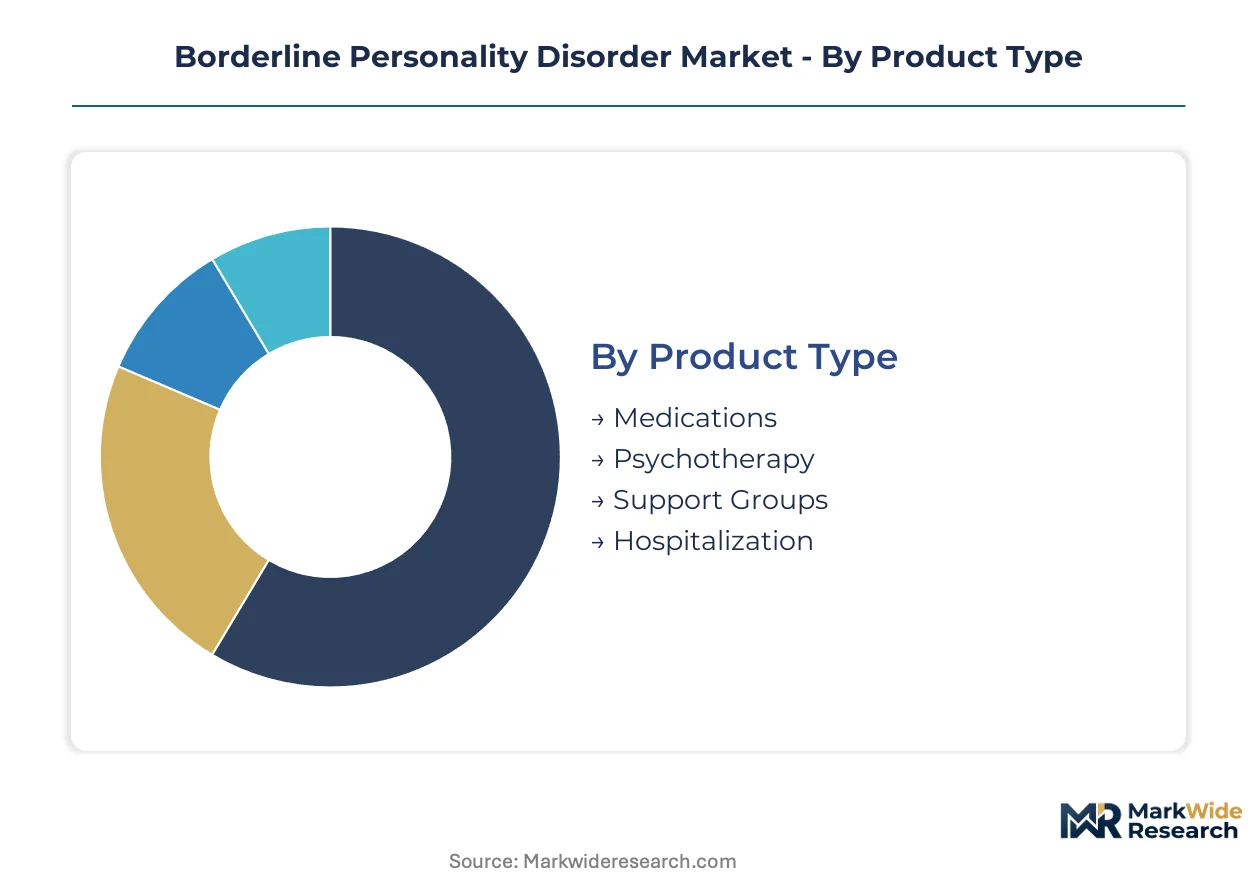
Borderline Personality Disorder treatment pathways diverge sharply between acute intervention modalities and longitudinal maintenance systems. Understanding segment integration depth clarifies where standalone therapeutic products command premium positioning versus embedded care protocols.
Product Type:
Standalone pharmaceutical interventions operate independently of care infrastructure, while psychotherapy and support services embed within broader clinical ecosystems.
- Medications:Mood stabilizers and atypical antipsychotics constitute the pharmacologic backbone of acute symptom management. Demand concentrates in United States Medicaid formularies where prior authorization pathways favor generic psychotropics over branded alternatives.
- Psychotherapy:Dialectical behavior therapy delivers structured skills training through individual and group formats requiring certified practitioner availability. United States urban academic medical centers capture the densest concentration of licensed clinicians, leaving rural markets structurally underserved.
- Support Groups:Peer-recovery networks sustain therapeutic gains post-acute intervention through moderated community engagement.
- Hospitalization:Dedicated psychiatric units manage crisis stabilization and safety planning for severe presentations.
Volume placements concentrate in Medications; the faster expansion belongs to Psychotherapy.
Delivery Mode:
Cost tier stratification separates high-touch synchronous delivery from scalable asynchronous platforms, with reimbursement parity still evolving.
- In-person:Traditional face-to-face therapeutic encounters maintain gold-standard status for complex diagnostic assessment and alliance formation. United States metropolitan markets sustain the highest session density, though practitioner supply constraints limit geographic reach.
- Teletherapy:Video-based synchronous delivery extends specialist access to frontier markets while reducing clinician travel burden. HIPAA-compliant platform architecture imposes engineering costs that slow vendor deployment across state licensure boundaries.
- Group Sessions:Cohort-based therapeutic formats achieve economies of scale in skills training delivery.
- Online Platforms:Asynchronous digital tools enable self-paced intervention and real-time symptom monitoring.
Revenue weighting favors In-person delivery; Online Platforms are gaining share fastest through payer carve-out contracts.
End User:
Customer type determines procurement sophistication, with institutional purchasers negotiating integrated care contracts distinct from individual patient out-of-pocket spending.
- Patients:Direct consumers navigate complex insurance authorization requirements and out-of-network cost burdens. United States commercial plan members face rising deductibles that shift first-dollar spending onto individuals.
- Clinics:Outpatient mental health facilities aggregate demand across payer panels and manage referral relationships with acute care settings.
- Hospitals:Inpatient psychiatric units capture the highest per-episode reimbursement through DRG-based payment structures.
- Private Practices:Solo and group practitioner entities maintain flexibility in treatment modality selection but face administrative burden from fragmented payer requirements.
Procurement volume clusters in Hospitals; Private Practices show the steepest expansion trajectory as independent practitioners adopt platform-enabled practice models.
Therapy Area:
Professional credential boundaries create segmentation by scope of practice, with prescriptive authority representing the critical differentiator.
- Psychiatry:Physician-led care combines diagnostic expertise with pharmacologic management authority. United States Medicaid programs increasingly require psychiatric consultation for complex personality disorder cases.
- Psychology:Doctoral-level practitioners deliver evidence-based psychotherapeutic interventions without prescribing privileges. Interstate compact legislation is gradually reducing licensure barriers to telepractice.
- Counseling:Master's-level clinicians provide supportive services and skills coaching within defined scope limitations.
- Behavioral Therapy:Specialized certification programs enable targeted intervention for specific symptom clusters.
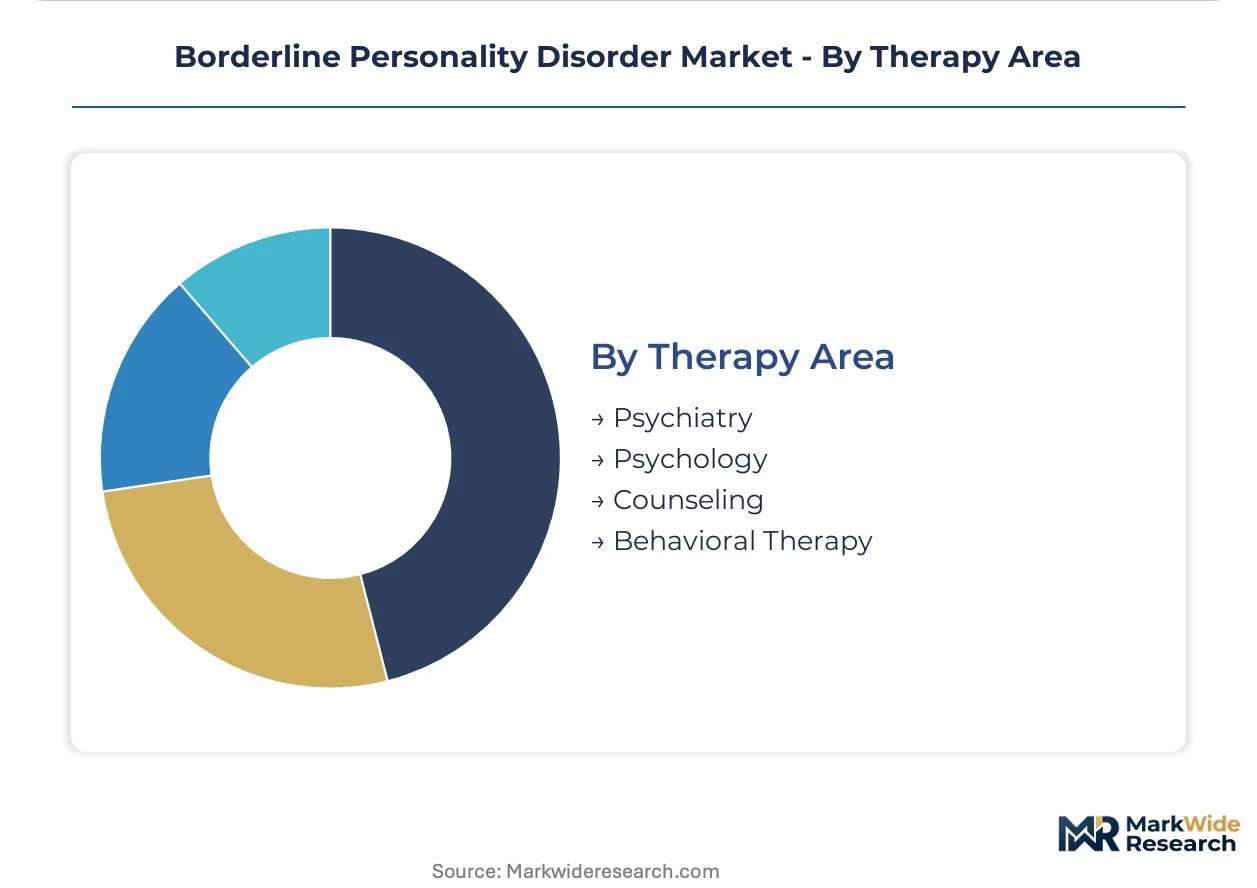
Service volume concentrates in Psychiatry; Behavioral Therapy demonstrates the most rapid credentialing expansion as training programs scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's academic medical corridor anchors North American psychiatric research density, with the Massachusetts General Hospital McLean Hospital cluster driving dialectical behavior therapy protocol development and digital biomarker validation studies.
United States
Integrated care networks in California and New York concentrate Medicaid formulary expansion for complex personality disorder management. The FDA's Division of Psychiatry governs accelerated approval pathways for novel psychiatric therapeutics. The Boston-Washington corridor sustains the densest concentration of certified dialectical behavior therapy practitioners and academic research centers.
Germany
Statutory health insurance funds in Bavaria and North Rhine-Westphalia are piloting bundled reimbursement for multimodal BPD treatment protocols. The Federal Joint Committee (G-BA) evaluates digital health applications for inclusion in standard care coverage. The Heidelberg-Mannheim medical region hosts Europe's largest cluster of personality disorder specialty clinics and research institutions.
United Kingdom
NHS England's Long Term Plan prioritizes community-based mental health services for personality disorders across Greater London and the Midlands. The National Institute for Health and Care Excellence (NICE) maintains updated guidelines for borderline personality disorder intervention pathways. The Maudsley Hospital in South London anchors national training capacity for evidence-based psychotherapeutic approaches.
Japan
Metropolitan Tokyo and Osaka prefectures are expanding outpatient psychiatric infrastructure to address historically low BPD diagnosis rates. The Pharmaceuticals and Medical Devices Agency (PMDA) is streamlining review processes for digital therapeutic submissions in mental health. The National Center of Neurology and Psychiatry in Kodaira coordinates nationwide clinical trial networks for novel psychiatric interventions.
Australia
Victoria and New South Wales are investing in telehealth parity legislation to extend specialist psychiatric access to rural and remote populations. The Therapeutic Goods Administration (TGA) aligns software-based medical device regulations with evolving international standards. The Melbourne-Parkville biomedical precinct houses the country's primary concentration of personality disorder research and clinical training programs.
Borderline Personality Disorder Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulary positioning and digital therapeutic integration depth. The psychiatric pharmaceutical segment exhibits consolidated characteristics among established CNS franchise operators, with mid-tier specialty biotechnology firms occupying niche indication spaces. Three archetypes dominate: legacy pharmaceutical conglomerates with Medicaid-commercial dual formulary strength, biotechnology specialists pursuing accelerated approval pathways for novel mechanisms, and digital therapeutic developers seeking software-as-medical-device clearance. Competitive dynamics center on strategic partnerships between drug developers and telehealth platforms, alongside vertical integration into patient monitoring infrastructure.
Within the legacy pharmaceutical tier, Pfizer Inc. and Johnson & Johnson Services, Inc. exemplify formulary anchoring strategies across United States payer systems. Otsuka Pharmaceutical Co., Ltd. occupies a distinct position through its integration of digital therapeutics with established psychiatric portfolios. These three entities represent contrasting approaches to the convergence of pharmacologic and technology-enabled care delivery models.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Johnson & Johnson Services, Inc. |
| Pfizer Inc. |
| Otsuka Pharmaceutical Co., Ltd. |
| Novartis International AG |
| Eli Lilly and Company |
| Bristol Myers Squibb Company |
| Oryzon Genomics SA |
| AstraZeneca plc |
| Others |
Supply Flow & Price Mechanics
Backward integration into long-acting injectable manufacturing anchors formulary positioning for Johnson & Johnson Services, Inc. and Pfizer Inc., concentrating supply-side leverage among CNS franchise operators who control both active pharmaceutical ingredient sourcing and finished dose production. This captive supply structure insulates premium pricing tiers from generic psychotropic commoditization pressures while imposing fixed cost burdens that smaller developers cannot replicate.
Pricing Analysis
Outcome-based pricing anchors Medicaid formulary negotiations, where prior authorization pathways reward documented symptom reduction in acute crisis episodes. Three-tier pricing structure across premium branded injectables, standard oral atypicals, and economy generic mood stabilizers stratifies access by payer type. Cost compression in the generic tier intensifies because of consolidated API sourcing from Indian and Chinese manufacturers. Medicaid programs exhibit highest price sensitivity; commercial plans with carve-out psychiatric vendors show lowest sensitivity to per-dose differentials.
Supply Chain Analysis
Single-source vulnerability sits with benzodiazepine API manufacturers concentrated in India and China, where environmental compliance enforcement and export licensing delays create intermittent supply interruptions. Finished dose production draws from United States, Ireland, and Puerto Rico facilities to satisfy FDA inspection requirements and DEA quota allocations. Tariff exposure on Chinese-sourced intermediates elevates cost volatility for generic psychotropic portfolios. Distribution runs through three-tier wholesaler networks reaching hospital systems, retail pharmacy chains, and specialty mental health clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dialectical behavior therapy certification pipeline constraints prop pricing power for credentialed practitioners, creating supply-side scarcity that sustains premium reimbursement rates against digital therapeutic alternatives.
For Market Incumbents: Lock in formulary positioning through Janssen-style long-acting injectable convergence with telehealth platform partnerships, defending against digital therapeutic entrants seeking software-as-medical-device clearance. Prioritize FDA Division of Psychiatry pre-submission meetings for novel mechanism candidates. Deepen backward integration into API manufacturing to offset Indian and Chinese supplier concentration risk. For New Entrants and Emerging Players: Telehealth platform vendors represent the most penetrable channel for asynchronous BPD intervention deployment, particularly in rural United States markets lacking certified DBT practitioner density. Target Medicaid managed care organization carve-out contracts in California and New York where integrated care network expansion creates procurement entry points. Pursue strategic licensing with academic medical centers for digital biomarker validation. For Investors and Strategic Acquirers: Exit pathways concentrate in biotechnology specialists with accelerated approval designations and validated digital therapeutic endpoints. Five-to-ten year viability hinges on demonstration of non-inferiority to established pharmacologic interventions rather than novelty alone. Monitor FDA guidance finalization on remote therapeutic monitoring as the critical inflection signal for reimbursement code unbundling.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Biomarker Validation | FDA Division of Psychiatry guidance on software-as-medical-device clearance reshapes evidentiary requirements for asynchronous teletherapy platforms. |
| DBT Certification Scale-Up | Academic medical center partnerships in the Boston-Washington corridor address practitioner supply constraints limiting rural market penetration. |
| Long-Acting Injectable Convergence | Mood stabilization protocols combining pharmacologic and psychosocial interventions open integrated care contract positioning for Medicaid formularies. |
| Medicaid MCO Carve-Out Capture | California and New York integrated care network expansion creates procurement entry points for specialized psychiatric vendors. |
| API Manufacturing Backward Integration | Captive supply of active pharmaceutical ingredients insulates against Indian and Chinese export licensing volatility affecting generic psychotropic portfolios. |
Methodological Framework
Independent corroboration across hospital formulary directors, Medicaid managed care organization executives, FDA regulatory affairs leads, and digital therapeutic platform engineers underwrites the qualitative findings. Primary interviews with dialectical behavior therapy certification program administrators and psychiatric unit medical directors combined with secondary validation from FDA Division of Psychiatry guidance documents, CMS Medicare Part D formulary databases, and DEA controlled substance quota publications. Bottom-up demand modeling across patient population segments triangulates against top-down pharmaceutical revenue aggregation.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end user archetype, and therapy area credential boundaries. CAGRs derive from multivariate regression incorporating FDA approval probability weightings, Medicaid expansion enrollment trajectories, and digital therapeutic reimbursement code adoption curves. Forecast inputs incorporate DEA scheduling decisions affecting benzodiazepine adjunctive use and interstate licensure compact expansion enabling telepractice reach.
Caveats apply where FDA digital biomarker guidance delays, DEA controlled-substance prescribing rule changes, or HIPAA cross-state licensure litigation could materially shift the outlook. Forecasts reflect assumptions about Medicaid formulary generosity and commercial payer carve-out willingness. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Cerebral Vasospasm Market
Specialty Medicine
Pleural Diseases Therapeutics Market
Specialty Medicine
Axillary Hyperhidrosis Treatment Market
Specialty Medicine
Nasal Polyposis Treatment Market
Specialty Medicine
Molybdenum Cofactor Deficiency Type-A (Mocod-A) Treatment Market
Specialty Medicine
Paget Disease Treatment Market
Specialty Medicine
Atopic Dermatitis Market
Specialty Medicine
Global Overactive Bladder Treatment Market
Specialty Medicine
Diverticulitis Disease Market
Specialty Medicine
Vesicoureteral Reflux Market
Specialty Medicine
Global Occupational Medicines Market
Specialty Medicine
Adult Malignant Glioma Therapeutics Market
Specialty Medicine
Ragweed Pollen Allergy Treatment Market
Specialty Medicine
Lung Cancer Therapeutics Market
Specialty Medicine
Intramedullary Osteosarcoma Treatment Market
Specialty Medicine
Global Allergy Vaccine Market