
 Cholangiocarcinoma (CCA) Therapeutics Market | 2026-2036
Cholangiocarcinoma (CCA) Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Cholangiocarcinoma (CCA) Therapeutics Market Outlook
Buyer concentration among oncology clinics is consolidating as specialized hepatobiliary treatment centers absorb patient flows from general hospitals. Incyte Corporation leverages its FGFR inhibitor portfolio to anchor position in molecularly defined CCA subsets. F. Hoffmann-La Roche Ltd. sustains competitive presence through broad oncology infrastructure and diagnostic-therapeutic integration. Merck & Co., Inc. competes via checkpoint inhibitor programs addressing unmet needs in frontline and relapsed settings.
Cholangiocarcinoma therapeutics comprise systemic and localized treatments targeting malignant epithelial tumors arising from bile duct epithelium, with molecular profiling now guiding selection of FGFR2 fusion inhibitors, IDH1 antagonists, and HER2-directed agents based on tumor genomic alterations. Targeted therapy segments command premium positioning due to biomarker-defined eligibility and durable response potential in FGFR-altered populations. Immunotherapy segments represent the fastest-expanding category as PD-1/PD-L1 combinations penetrate earlier treatment lines and expand addressable patient pools beyond chemotherapy-refractory cohorts.
FDA breakthrough therapy and orphan drug designations compress development timelines and incentivize CCA-focused R&D investment, while EMA's PRIME scheme and Japan's PMDA sakigake designation create parallel accelerated pathways across major pharmaceutical markets. Regulatory frameworks increasingly mandate companion diagnostic co-development, reshaping commercialization requirements and partnership structures for targeted agents. Stakeholders must monitor evolving biomarker definitions and payer evidence thresholds as molecular segmentation fragments addressable populations and complicates pricing and access negotiations.
Market Dynamics
Molecular profiling is fragmenting addressable patient populations into biomarker-defined subsets, forcing developers to pursue parallel regulatory pathways and companion diagnostic partnerships rather than broad chemotherapy indications.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Compressed approval timelines for FGFR and IDH1 inhibitors incentivize venture funding into rare oncology indications. Developers recoup R&D costs faster through accelerated market entry.
- Liquid Biopsy Adoption:Circulating tumor DNA testing enables real-time resistance monitoring without invasive tissue sampling. Community oncology practices expand molecular testing capacity.
- Japan PMDA Sakigake Pathway:Priority review status for innovative CCA therapies shortens time-to-reimbursement in the world's third-largest pharmaceutical market. Japanese hepatobiliary centers drive Asia-Pacific clinical trial enrollment.
Market Restraints
- Small Biomarker-Defined Populations:FGFR2 fusions occur in under fifteen percent of intrahepatic cases, limiting commercial scale for targeted monotherapies. Developers face portfolio concentration risk.
- Companion Diagnostic Co-Development Costs:Parallel FDA validation of tissue-based and liquid biopsy platforms doubles regulatory expenditure. Diagnostic partnerships consume thirty to forty percent of program budgets.
- Reimbursement Fragmentation Across Payers:Medicare, Medicaid, and commercial insurers apply inconsistent evidence thresholds for molecularly selected therapies. Prior authorization delays extend treatment initiation.
Strategic Opportunities
- First-Line Immunotherapy Combinations:PD-1/PD-L1 plus chemotherapy regimens in untreated advanced disease expand addressable pools beyond refractory settings. Regulators accept progression-free survival endpoints.
- HER2-Directed Expansion:Antibody-drug conjugates target an actionable subset previously excluded from precision trials. Academic medical centers build HER2 testing infrastructure.
- Decentralized Molecular Testing:Regional reference laboratories reduce sample transit time to centralized academic pathology. Community hospitals retain patients who previously transferred to tertiary centers.
Industry Challenges
- Biomarker Assay Harmonization:Discordant results between tissue NGS, FISH, and liquid biopsy platforms create treatment selection ambiguity. Pathology societies struggle to standardize reporting thresholds.
- Cross-Functional Talent Scarcity:Developers compete for hepatobiliary oncologists with translational research experience. Clinical trial design requires rare integration of genomic science and regulatory strategy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cholangiocarcinoma (CCA) Therapeutics Market |
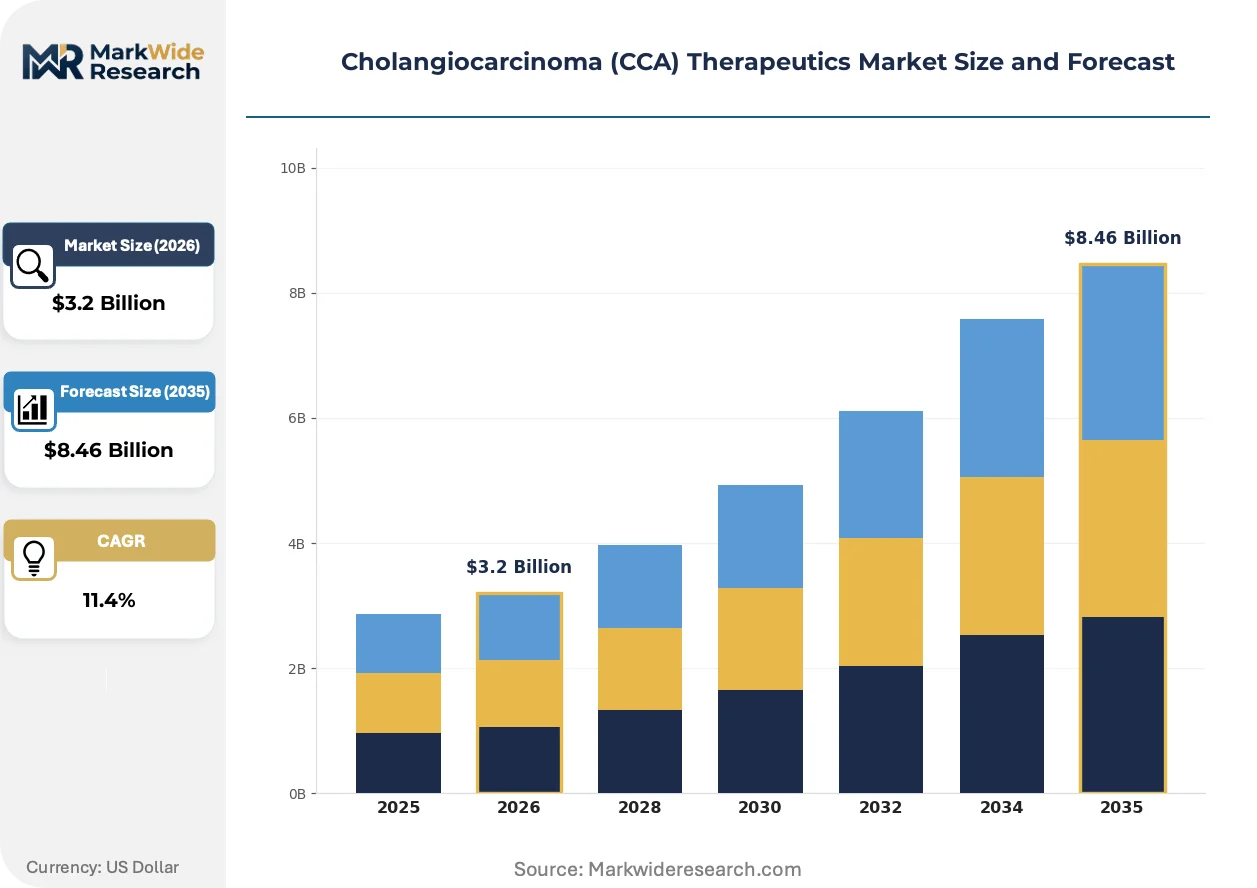
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $8.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Immunotherapy, Radiation Therapy End User: Hospitals, Oncology Clinics, Research Institutes, Home Care Therapy Area: Rare Cancers, Digestive Disorders, Hepatobiliary Diseases, Advanced Malignancies Delivery Mode: Intravenous, Oral, Subcutaneous, Localized |
| Companies Covered | Incyte Corporation, Eisai Co., Ltd., AstraZeneca, BridgeBio Pharma, F. Hoffmann-La Roche Ltd., Merck & Co., Inc., Eli Lilly and Company, Servier, Taiho Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cholangiocarcinoma (CCA) Therapeutics Market Strategic Shifts
Next-generation sequencing is compressing diagnostic timelines while artificial intelligence platforms reshape biomarker discovery, creating pressure to align therapeutic development with real-time tumor evolution tracking.
Liquid biopsy monitoring is decentralizing resistance surveillance from centralized academic pathology departments to community oncology laboratories. Regional hospitals now sequence circulating tumor DNA at point-of-care intervals. This shift compresses the window between progression detection and treatment modification.
EMA's PRIME scheme is mandating earlier patient-reported outcome integration into CCA trial design. Sponsors must submit quality-of-life data alongside efficacy endpoints at the marketing authorization application stage. European reimbursement authorities now condition positive health technology assessment on symptom burden documentation.
Oncology procurement at integrated delivery networks is consolidating formulary decisions under centralized pharmacy and therapeutics committees. Individual physician prescribing autonomy yields to protocol-driven pathways with pre-authorized biomarker requirements. This concentration is most advanced in United States multi-hospital systems where value-based contracts tie reimbursement to pathway compliance rates.
Cholangiocarcinoma (CCA) Therapeutics Market Segmentation
Molecular stratification fragments CCA into biomarker-defined subsets, forcing developers to align product portfolios with companion diagnostic requirements and reimbursement pathways. Each segmentation axis carries distinct pricing power, clinical trial design implications, and distribution channel dependencies.
Product Type:
Technology sophistication determines reimbursement tier and prescriber autonomy across treatment settings.
- Targeted Therapy:FGFR2 fusion inhibitors and IDH1 antagonists require tissue-based or liquid biopsy confirmation before initiation. United States oncology clinics concentrate demand for these premium agents due to prior authorization infrastructure and molecular tumor board capacity.
- Immunotherapy:PD-1/PD-L1 checkpoint inhibitors penetrate earlier treatment lines as first-line combination data mature. German hepatobiliary centers drive European adoption through academic trial networks and centralized molecular profiling.
- Chemotherapy:Gemcitabine-cisplatin regimens remain the backbone for biomarker-negative patients and resource-constrained settings.
- Radiation Therapy:External beam and selective internal radiation address localized disease and palliative indications.
Chemotherapy leads on scale; immunotherapy leads on momentum.
End User:
Site-of-care economics and prescriber specialization reshape patient flow patterns and procurement concentration.
- Oncology Clinics:Community and academic sites with molecular testing capability capture biomarker-directed therapy volumes. Japan's hepatobiliary centers concentrate FGFR inhibitor prescribing through PMDA sakigake pathway familiarity.
- Hospitals:General medical centers retain chemotherapy administration and radiation therapy infrastructure for decompensated patients.
- Research Institutes:Phase I units and early-phase trial sites enroll molecularly selected cohorts for novel mechanism exploration.
- Home Care:Oral targeted agents and subcutaneous immunotherapy enable administration outside institutional settings.
Hospitals lead on scale; oncology clinics lead on momentum.
Therapy Area:
Regulatory designation and unmet medical need intensity determine development priority and payer evidence thresholds.
- Rare Cancers:Orphan drug incentives compress development timelines and extend exclusivity periods for CCA-focused developers.
- Advanced Malignancies:Relapsed and refractory populations accept higher toxicity profiles for survival benefit.
- Hepatobiliary Diseases:Cross-disease expertise in liver cancer centers creates referral concentration for cholangiocarcinoma cases.
- Digestive Disorders:Gastroenterology referral pathways identify early-stage patients amenable to surgical and locoregional intervention.
Advanced malignancies lead on scale; rare cancers lead on momentum.
Delivery Mode:
Route of administration shapes site-of-care requirements, patient compliance, and manufacturing complexity.
- Intravenous:Infusion-dependent agents require institutional capacity and nursing supervision for hypersensitivity monitoring.
- Oral:Small-molecule inhibitors enable decentralized prescribing and adherence tracking through pharmacy benefit management.
- Subcutaneous:Self-administration potential reduces clinic burden for maintenance immunotherapy regimens.
- Localized:Hepatic arterial infusion and intratumoral delivery demand interventional radiology collaboration.
Intravenous leads on scale; oral leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States captures premium pricing for FGFR inhibitors while Japan accelerates regulatory review through PMDA's sakigake pathway, creating divergent commercial timelines across major pharmaceutical markets.
United States
FDA breakthrough therapy designations compress development timelines for molecularly targeted agents. Medicare and commercial insurers apply inconsistent prior authorization criteria for companion diagnostic-mandated therapies. MD Anderson Cancer Center and Memorial Sloan Kettering anchor clinical trial enrollment through specialized hepatobiliary programs.
Germany
Academic hepatobiliary centers in Heidelberg and Munich drive European adoption of biomarker-directed protocols. EMA's PRIME scheme mandates patient-reported outcome integration for marketing authorization. The German reference pricing system creates downward pressure on chemotherapy parity benchmarks for novel agents.
Japan
PMDA sakigake designation shortens time-to-reimbursement for innovative CCA therapies. National Cancer Center Hospital and Kyushu University Hospital concentrate Asia-Pacific trial enrollment. METI funding supports domestic biomarker assay development to reduce dependence on imported diagnostic platforms.
United Kingdom
NICE technology appraisals condition access on quality-adjusted life year thresholds below oncology norms. The NHS Genomic Medicine Service expands molecular profiling capacity into community settings. Royal Marsden and Christie Hospital anchor early-phase trial infrastructure for rare cancer indications.
Switzerland
Swissmedic accelerated assessment pathways align with EMA timelines for orphan oncology indications. University Hospital Zurich and Geneva University Hospitals concentrate French and Italian cross-border patient flows. Roche's Basel headquarters anchors diagnostic-therapeutic integration partnerships across European markets.
Cholangiocarcinoma (CCA) Therapeutics Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across molecularly defined patient segments. The market structure concentrates around three strategic tiers: large-cap pharmaceutical companies with broad oncology infrastructure, mid-cap biotechs with single-asset precision platforms, and emerging developers with novel mechanism assets. Dominant competitive moves include diagnostic-therapeutic partnership formation and biomarker assay co-development to secure regulatory approval and reimbursement access.
Within the precision oncology tier, Incyte Corporation and F. Hoffmann-La Roche Ltd. exemplify contrasting scale approaches to molecular segmentation, while Merck & Co., Inc. occupies a position emphasizing immunotherapy combination expansion across treatment lines. These three anchors represent distinct strategic postures: targeted monotherapy depth, diagnostic integration breadth, and checkpoint inhibitor platform leverage.
| Leading Market Players |
|---|
| Incyte Corporation |
| Eisai Co., Ltd. |
| AstraZeneca |
| BridgeBio Pharma |
| F. Hoffmann-La Roche Ltd. |
| Merck & Co., Inc. |
| Eli Lilly and Company |
| Servier |
| Taiho Pharmaceutical |
| Others |
Value Chain & Pricing Dynamics
Bifurcation between biomarker-directed premium therapies and commoditized chemotherapy regimens manifests in divergent margin structures and supply chain configurations across oncology procurement channels. FGFR2 fusion inhibitors command value-based pricing through companion diagnostic mandates in United States integrated delivery networks, while gemcitabine-cisplatin sourcing concentrates through generic API channels in India and China with compressed markups.
Pricing Analysis
Capacity additions in South Korean and Chinese biologics manufacturing are reshaping price floors for PD-1/PD-L1 checkpoint inhibitors. The market operates on a value-based contracting model tethered to progression-free survival benchmarks, with price differentiation driven by biomarker eligibility requirements and site-of-care administration costs. Pricing pressure stems from Medicare's inflation rebate provisions under the Inflation Reduction Act, which penalize price increases above CPI thresholds. Community oncology clinics exhibit highest price sensitivity due to thin prior authorization staffing, while academic medical centers with dedicated molecular tumor boards absorb premium pricing for targeted agents.
Supply Chain Analysis
Single-source vulnerability sits with Chinese API manufacturers for small-molecule chemotherapy backbones and with Swiss contract manufacturing organizations for biologic fill-finish operations. Active pharmaceutical ingredient production draws from China, India, and Italy, while sterile injectable formulation rests on capabilities in Switzerland, Germany, and Japan. Supply chain risk centers on FDA inspection backlogs at overseas API facilities that trigger import alerts without warning. Distribution runs through specialty pharmacy networks for oral targeted agents and through hospital-based oncology pharmacies for infusion-dependent immunotherapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cholangiocarcinoma therapeutics constitute a late-cycle quality story as patient stratification by FGFR2 fusion and IDH1 mutation status shifts demand toward molecularly validated premium agents with durable response profiles.
For Market Incumbents: Cement diagnostic-therapeutic integration partnerships to lock in companion diagnostic co-development pathways ahead of FDA validation requirements. Deepen backward integration into liquid biopsy platform capabilities to capture resistance monitoring revenue streams as community oncology expands molecular testing capacity. The priority lever centers on securing formulary placement at United States integrated delivery networks before pathway-driven prescribing consolidates under centralized pharmacy committees. For New Entrants and Emerging Players: FDA breakthrough therapy designation opens a window for mid-cap developers with FGFR2-selective inhibitors to secure accelerated approval timelines and orphan drug exclusivity. White-space targets include first-line immunotherapy combination slots in biomarker-negative populations and HER2-directed antibody-drug conjugate development for biliary tract subsets previously excluded from precision trials. The most penetrable entry point sits with decentralized molecular testing partnerships that reduce sample transit friction for regional reference laboratories. For Investors and Strategic Acquirers: Consolidation pressure builds where single-asset precision oncology developers face portfolio concentration risk as FGFR2 fusion prevalence caps addressable populations below commercial scale thresholds. Long-term viability favors platforms with multiplex biomarker capabilities spanning IDH1, HER2, and emerging KRAS G12C subsets. Acquisition target archetypes include developers with validated companion diagnostic partnerships and early-phase assets with EMA PRIME designation. The signal to watch is progression-free survival data from frontline PD-1/PD-L1 combination trials that could expand addressable pools beyond chemotherapy-refractory settings.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA mandates simultaneous validation of tissue and liquid biopsy platforms, doubling regulatory expenditure for targeted therapy sponsors. |
| First-Line Immunotherapy Combination Trials | PD-1/PD-L1 plus chemotherapy regimens in untreated advanced disease expand addressable pools beyond refractory settings. |
| Decentralized Molecular Testing Partnerships | Regional reference laboratories reduce sample transit time, enabling community hospitals to retain patients previously transferred to tertiary centers. |
| EMA PRIME Scheme Engagement | Early patient-reported outcome integration satisfies European reimbursement authorities conditioning positive health technology assessment on symptom burden documentation. |
| Japan PMDA Sakigake Pathway Utilization | Priority review status shortens time-to-reimbursement in the world's third-largest pharmaceutical market. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors at United States payers, and hepatobiliary oncologists at academic medical centers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored market size estimates.
Segment-weighting approaches applied differential growth assumptions across biomarker-defined patient subsets, treatment lines, administration routes, and regional regulatory clusters. CAGRs were derived from fitted adoption curves for FGFR inhibitor penetration rates and immunotherapy combination expansion trajectories. Forecast inputs incorporated companion diagnostic approval timelines, reimbursement pathway evolution, and hepatobiliary center capacity expansion across major markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under biomarker assay harmonization failures or FDA inspection delays at API manufacturing sites. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Wilms Tumor Treatment Market
Specialty Medicine
Breakthrough Therapy Designation Market
Specialty Medicine
Global Constipation Treatment Market
Specialty Medicine
Community Acquired Bacterial Pneumonia (CABP) Treatment Market
Specialty Medicine
Endometrial Cancer Treatment Market
Specialty Medicine
Stuttering Therapeutics Market
Specialty Medicine
Congenital Adrenal Hyperplasia Treatment Market
Specialty Medicine
Aldosteronism Treatment Market
Specialty Medicine
Lipoprotein Metabolism Disorders Treatment Market
Specialty Medicine
Asperger Syndrome Market
Specialty Medicine
Carcinoid Tumor Syndrome Management Market
Specialty Medicine
Paget Disease Treatment Market
Specialty Medicine
Diamond-Blackfan Anemia Syndrome Therapeutics Market
Specialty Medicine
Wet Age-Related Macular Degeneration (Wet AMD) Market
Specialty Medicine
Splenomegaly Therapeutics Market
Specialty Medicine
Pleurisy Market