
 Selectin Blocker Market | 2026-2036
Selectin Blocker Market Size, Share, and Industry Trends Forecast 2026-2036
Selectin Blocker Market Analytics
The capability gap between large-cap biopharmaceuticals with end-to-end biologics infrastructure and mid-tier developers reliant on contract manufacturing is redrawing competitive boundaries in selectin-targeted therapeutics. Roche leverages its integrated diagnostics-to-therapy platform to anchor clinical development pipelines across inflammatory and oncology indications. AbbVie sustains competitive positioning through deep immunology franchise expertise and established hospital access channels.
Selectin blockers comprise a class of therapeutic agents that inhibit cell-surface selectin proteins—E-selectin, P-selectin, and L-selectin—thereby disrupting leukocyte rolling and extravasation cascades central to inflammation and metastasis; these agents are manufactured through recombinant mammalian expression systems or synthetic carbohydrate mimetic chemistry, with purity specifications typically exceeding 95% for clinical-grade monoclonal antibodies. Monoclonal antibodies capture the dominant share of current revenue given validated manufacturing scale and regulatory familiarity, while fusion proteins represent the fastest-expanding category as developers engineer multivalent constructs with extended half-lives. Small molecules retain niche positioning in oral bioavailability applications where patient self-administration drives preference.
The FDA and EMA govern selectin blocker approval pathways through their respective biologics license application and centralized marketing authorization frameworks, with both agencies intensifying scrutiny of immunogenicity profiles and long-term cardiovascular safety signals. ISO 10993 biocompatibility standards and ICH Q5D guidelines on cell substrate qualification further constrain manufacturing flexibility and timeline predictability. Stakeholders must monitor evolving FDA guidance on accelerated approval endpoints for anti-inflammatory biologics and prepare for potential EMA adaptive pathway requirements that could compress post-market confirmatory study timelines.
Market Dynamics
Hospital formulary committees are tightening prior authorization protocols for biologic selectin blockers, forcing developers to demonstrate superior cost-effectiveness against established TNF-alpha inhibitors and IL-6 pathway antagonists already entrenched in rheumatology and oncology infusion centers.
Growth Catalysts
- ICH Q5D Cell Substrate Guidelines:Harmonized international standards for mammalian cell line qualification are reducing redundant validation studies, compressing IND-to-Phase-I timelines for recombinant selectin antagonists.
- Japan's immunology center density:Concentrated specialist infrastructure in Tokyo, Osaka, and Nagoya accelerates patient recruitment for P-selectin inhibitor trials in sickle cell vaso-occlusive crisis.
- Glycomimetic solid-phase synthesis:Automated carbohydrate chemistry platforms are cutting synthetic cycle times for small-molecule E-selectin antagonists, enabling oral bioavailability programs previously constrained by manufacturing complexity.
Market Restraints
- CHO cell culture media costs:Serum-free chemically defined media formulations for recombinant glycoprotein production have experienced input volatility linked to amino acid and lipid precursor supply chains.
- Single-source fill-finish capacity:Contract manufacturing organizations with validated aseptic processing for high-viscosity biologics concentrate in Switzerland and Germany, creating geographic supply concentration risk.
- Cardiovascular safety signal detection:FDA's heightened scrutiny of thromboembolic events in chronic selectin blockade requires extended exposure cohorts, extending Phase III duration and capital requirements.
Strategic Opportunities
- Brazil's ANVISA regulatory pathway:Accelerated review frameworks for rare disease biologics create first-mover positioning for P-selectin inhibitors targeting sickle cell populations underserved by existing standards of care.
- Subcutaneous formulation convergence:Combination of hyaluronidase-enabled delivery with half-life extension technologies is opening ambulatory administration models outside hospital infusion suites.
- ISO 10993-23 in vitro irritation testing:Updated biocompatibility standards permitting non-animal alternatives for device-drug combination products reduce toxicology study timelines and cost structures.
Industry Challenges
- Glycobiology specialist scarcity:Protein chemists with carbohydrate structure-function expertise remain concentrated in academic and national laboratory settings, constraining industrial R&D scaling.
- Legacy ELISA potency assay validation:Transition to surface plasmon resonance and cell-based binding assays for release testing requires extensive method bridging studies against established pharmacopeial standards.
- Cold chain distribution integrity:Temperature excursion management for frozen drug substance shipments demands redundant monitoring infrastructure across multi-site manufacturing networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Selectin Blocker Market |
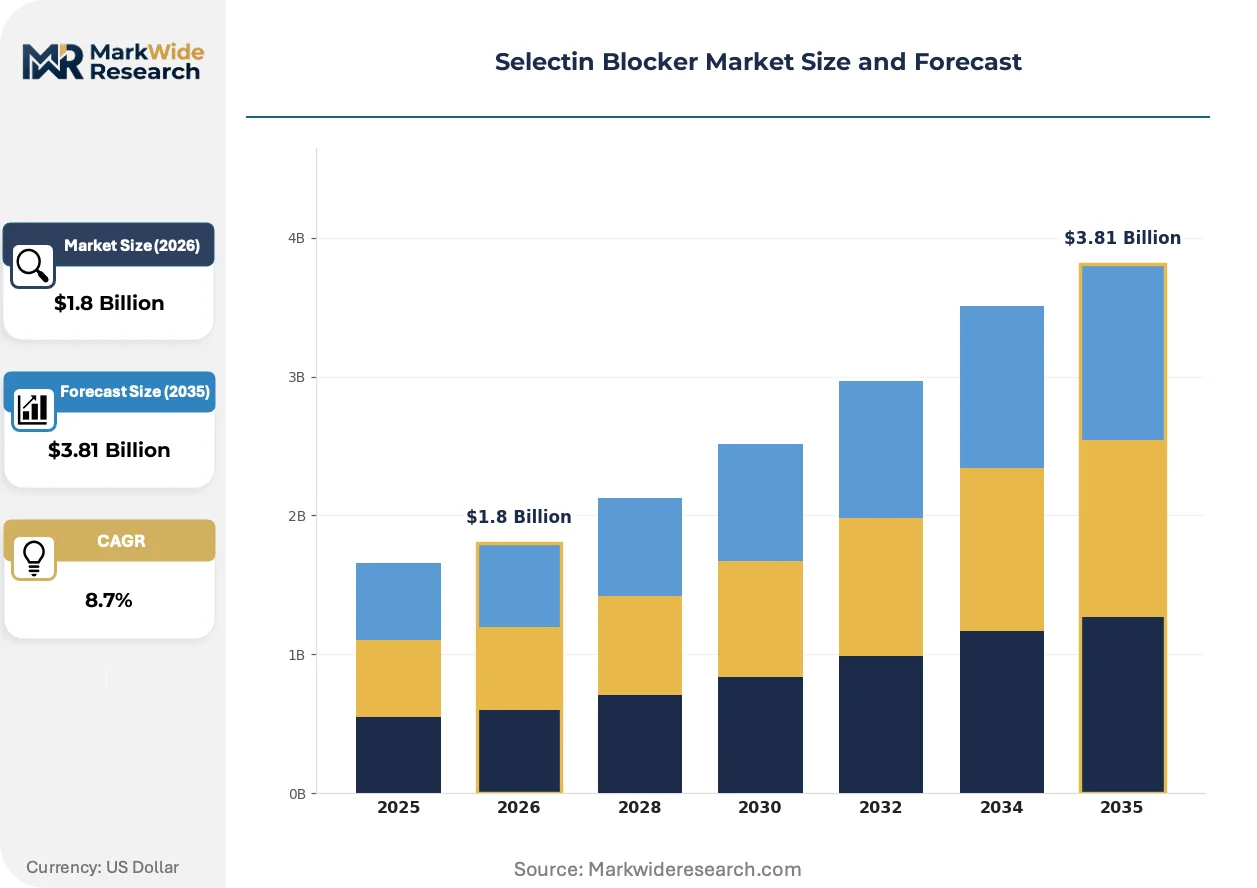
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecules, Monoclonal Antibodies, Fusion Proteins, Peptides End User: Hospitals, Laboratories, Research Institutions, Pharmaceutical Companies Application: Oncology, Inflammatory Disorders, Cardiovascular Diseases, Autoimmune Diseases Distribution Channel: Online Pharmacies, Retail Pharmacies, Hospital Pharmacies, Direct Sales |
| Companies Covered | Johnson & Johnson, Merck, AbbVie, Pfizer, Eli Lilly, Roche, Novartis, Amgen, Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Selectin Blocker Market Evolving Landscape
Multivalent scaffold engineering is collapsing the functional gap between monoclonal antibodies and smaller protein constructs, enabling developers to optimize for tissue penetration, manufacturing yield, and immunogenicity risk simultaneously rather than sequentially.
Bispecific selectin-targeting fusion proteins are decomposing the traditional antibody-dominant competitive landscape. Rheumatology-focused biopharmaceuticals are advancing these constructs through Phase II trials for inflammatory bowel disease. The technology is decomposing established revenue concentration in anti-TNF franchises by offering dual-pathway inhibition with reduced infusion frequency.
EMA's adaptive pathway framework for anti-inflammatory biologics is compressing confirmatory study timelines. Developers can now pursue conditional marketing authorization based on surrogate endpoints, with post-market efficacy commitments. Oncology and hematology indications for selectin blockers in metastasis and thrombosis modulation are responding fastest, with several sponsors restructuring protocols to align with these provisions.
Hospital procurement committees are consolidating biologic purchasing through centralized specialty pharmacy contracts. Academic medical centers in the United States are displacing traditional wholesaler relationships with direct manufacturer agreements that bundle drug, administration, and outcome monitoring. This consolidation is most visible in California and Massachusetts, where integrated delivery networks command sufficient volume to negotiate risk-sharing arrangements.
Selectin Blocker Market Segmentation
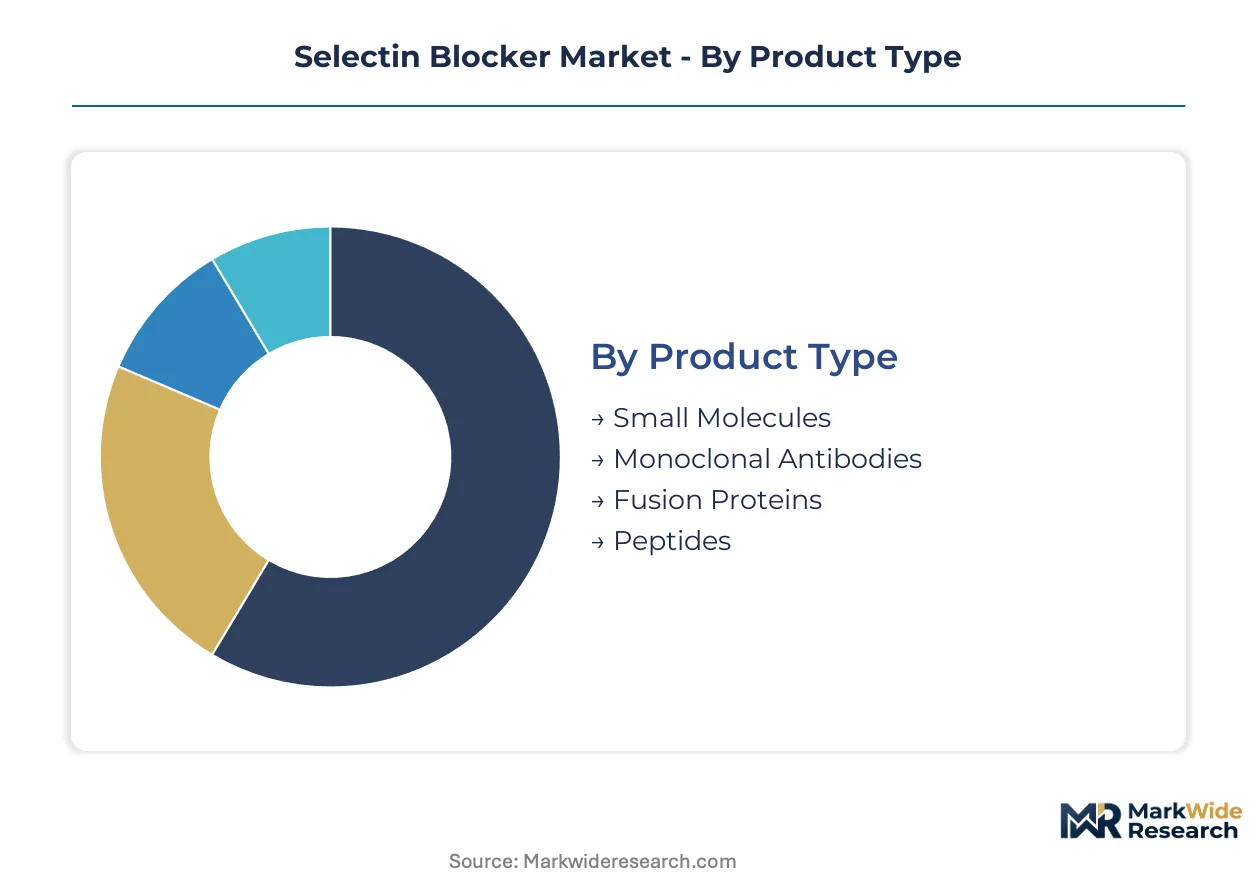
Selectin blocker commercialization pathways diverge sharply by molecular format, with biologics demanding cold-chain hospital infrastructure while small molecules leverage retail pharmacy networks. Channel economics and reimbursement complexity shape which segments capture volume versus margin.
Product Type:
Hospital infusion centers and specialty pharmacies handle distinct product categories based on storage requirements and administration protocols.
- Monoclonal Antibodies:Recombinant mammalian cell-derived immunoglobulins with validated glycosylation profiles dominate current revenue. Demand concentrates in United States academic medical centers where prior authorization expertise and infusion nursing capacity support biologic therapy uptake. Hospital formulary committees require head-to-head efficacy data against entrenched TNF-alpha inhibitors.
- Fusion Proteins:Engineered multivalent constructs combining selectin-binding domains with Fc or albumin moieties for half-life extension. German and Japanese immunology centers are expanding fastest as developers optimize subcutaneous delivery formats. Glycomimetic engineering advances are compressing manufacturing cycle times.
- Small Molecules:Synthetic carbohydrate mimetics enabling oral bioavailability and patient self-administration.
- Peptides:Short-chain amino acid sequences targeting selectin carbohydrate recognition domains with reduced immunogenicity risk.
By volume, monoclonal antibodies lead. By growth pace, fusion proteins are expanding most quickly.
End User:
Procurement authority and reimbursement pathways determine which customer types command pricing leverage versus volume commitment.
- Hospitals:Integrated delivery networks in California and Massachusetts negotiate direct manufacturer agreements bundling drug, administration, and outcome monitoring. Academic medical centers anchor Phase IV recruitment and real-world evidence generation for EMA adaptive pathway submissions.
- Pharmaceutical Companies:Mid-tier developers lacking captive biologics infrastructure rely on contract manufacturing organizations for clinical and commercial supply. Switzerland and Germany host concentrated fill-finish capacity for high-viscosity biologics.
- Research Institutions:Academic laboratories and national glycobiology centers drive early-stage target validation.
- Laboratories:Clinical and commercial testing facilities supporting pharmacokinetic and immunogenicity assay development.
By procurement scale, hospitals dominate. By margin contribution, pharmaceutical company partnerships yield the steepest expansion trajectory.
Application:
Regulatory scrutiny intensity and surrogate endpoint acceptability vary across therapeutic areas, compressing or extending development timelines.
- Inflammatory Disorders:Rheumatology and gastroenterology indications leverage established anti-TNF infrastructure. FDA's heightened cardiovascular safety signal detection requirements for chronic selectin blockade extend Phase III exposure cohorts. IBD-focused bispecific constructs are gaining share against infusion-frequency disadvantages of legacy antibodies.
- Oncology:Metastasis modulation and thrombosis management align with EMA adaptive pathway provisions for conditional marketing authorization. Surrogate endpoint frameworks accelerate hematology indications in sickle cell vaso-occlusive crisis.
- Autoimmune Diseases:Lupus and vasculitis programs target underserved populations with limited biologic options.
- Cardiovascular Diseases:Thromboembolic prevention applications face elevated FDA scrutiny of long-term safety signals.
By patient addressability, inflammatory disorders lead. By regulatory velocity, oncology is climbing the fastest.
Distribution Channel:
Cold chain integrity requirements and prior authorization complexity filter which channels handle which product formats.
- Hospital Pharmacies:Captive specialty pharmacy operations within integrated delivery networks manage biologic inventory and reimbursement navigation. Direct manufacturer agreements displace traditional wholesaler relationships in high-volume United States markets.
- Direct Sales:Manufacturer field forces engage hospital formulary committees and specialty physicians for biologic launches requiring infusion training and patient support programs.
- Retail Pharmacies:Oral small molecule selectin antagonists reach ambulatory patients through standard pharmacy networks.
- Online Pharmacies:Emerging channel for patient self-administered therapies with established safety profiles.
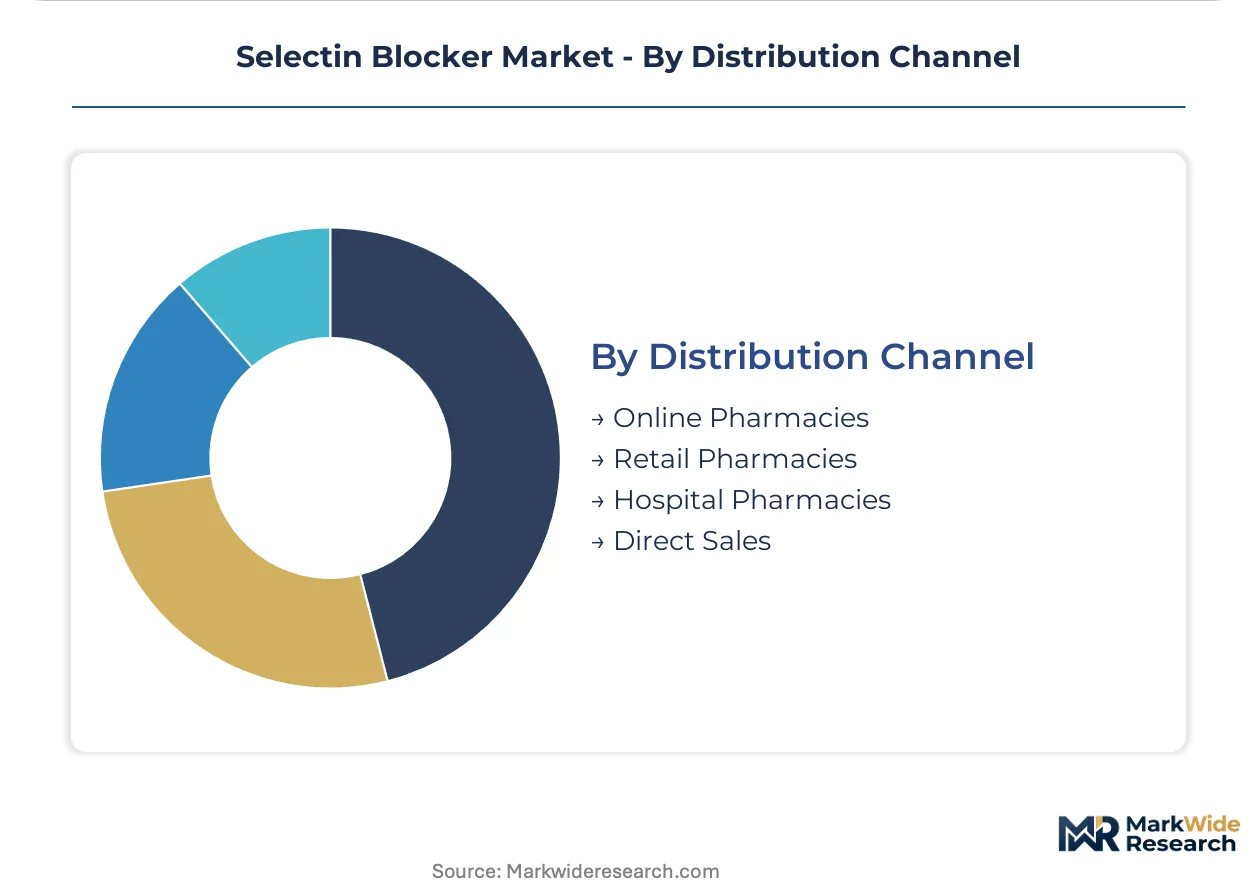
By biologic volume, hospital pharmacies lead. By channel expansion, direct sales is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing leverage concentrates in United States academic medical centers while procurement efficiency dominates German integrated delivery networks, creating a transatlantic asymmetry in value capture dynamics.
United States
Hospital formulary committees in California and Massachusetts demand head-to-head efficacy data against entrenched TNF-alpha inhibitors. FDA's accelerated approval pathway for anti-inflammatory biologics shapes trial design priorities. The Greater Boston cluster anchors Phase IV recruitment and real-world evidence generation for adaptive pathway submissions.
Germany
Specialized immunology centers in Munich and Hamburg expand patient access for subcutaneous fusion protein formats. EMA's centralized marketing authorization framework governs biologics license applications. The Rhine-Ruhr region concentrates contract manufacturing capacity for high-viscosity biologic fill-finish operations.
Japan
Tokyo, Osaka, and Nagoya host dense specialist infrastructure accelerating P-selectin inhibitor trials in sickle cell vaso-occlusive crisis. PMDA's review timelines for rare disease biologics compress development schedules. The Kanto region dominates glycobiology research coordination between academic and national laboratory settings.
Switzerland
Basel and Zurich anchor concentrated aseptic processing capacity for recombinant glycoprotein production. Swissmedic's alignment with EMA standards streamlines parallel submission strategies. The country's contract manufacturing organizations validate serum-free chemically defined media formulations for mammalian cell culture.
Brazil
ANVISA's accelerated review frameworks for rare disease biologics create first-mover positioning for sickle cell populations underserved by existing standards. São Paulo's academic medical centers drive clinical trial expansion in Latin America's largest addressable patient base. The Southeast region concentrates specialist hematology infrastructure for vaso-occlusive crisis management.
Selectin Blocker Market Competitive Landscape
Concentration sits with large-cap biopharmaceuticals possessing integrated diagnostics-to-therapy platforms and captive biologics infrastructure. Mid-tier developers reliant on contract manufacturing occupy a structurally disadvantaged position requiring strategic partnerships to access validated aseptic processing capacity. Three archetypes dominate: end-to-end integrated majors, immunology franchise specialists, and glycomimetic chemistry platform developers. Competitive moves center on subcutaneous formulation convergence combining hyaluronidase-enabled delivery with half-life extension technologies, and direct manufacturer agreements with integrated delivery networks displacing traditional wholesaler relationships.
Among United States-based integrated majors, Johnson & Johnson and Pfizer exemplify the diagnostics-to-therapy platform archetype with established hospital access channels. AbbVie occupies a position within the immunology franchise specialist tier, leveraging deep therapeutic area expertise. Roche anchors the European integrated major segment with end-to-end biologics infrastructure spanning clinical development through commercial manufacturing. These three companies represent distinct competitive positioning vectors rather than interchangeable market participants.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Merck |
| AbbVie |
| Pfizer |
| Eli Lilly |
| Roche |
| Novartis |
| Amgen |
| Teva Pharmaceutical Industries |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements for recombinant glycoprotein production lock in both supply access and price visibility for developers navigating volatile CHO cell culture media costs and single-source fill-finish dependencies concentrated in Switzerland and Germany. These contracts insulate biopharmaceutical manufacturers from amino acid and lipid precursor input volatility while securing validated aseptic processing capacity for high-viscosity biologics.
Pricing Analysis
The customization-premium spread between standard monoclonal antibody formats and engineered multivalent fusion proteins spans three-tier pricing structure across premium, standard, and economy levels based on glycosylation complexity and half-life extension engineering. Hospital formulary committees in United States academic medical centers command volume discounts against TNF-alpha inhibitor benchmarks, while mid-tier developers absorb margin compression from contract manufacturing premiums. Price differentiation hinges on immunogenicity profile validation and subcutaneous delivery format certification. Cost compression in standard antibody tiers is intensifying because of biosimilar readiness programs and entrenched anti-TNF competition.
Supply Chain Analysis
Inbound logistics costs for frozen drug substance shipments hinge on redundant temperature monitoring infrastructure across multi-site manufacturing networks, with cold chain integrity failures most acute on transatlantic trade lanes serving German fill-finish operations. Geographic supply concentration centers on Switzerland, Germany, and Japan for validated aseptic processing and glycobiology research coordination. Raw material dependencies draw from serum-free chemically defined media formulations, recombinant protein expression cell lines, and carbohydrate precursor libraries. Single-source vulnerability permeates high-viscosity biologic fill-finish capacity. Distribution runs through hospital specialty pharmacy operations and direct manufacturer agreements with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Selectin blocker commercialization sits in early-cycle expansion as hospital infusion protocols for autoimmune and inflammatory conditions broaden the addressable patient base beyond oncology metastasis applications.
For Market Incumbents: Fortify captive biologics infrastructure through backward integration into mammalian cell line development and serum-free media formulation capabilities. Deepen formulary committee relationships with head-to-head efficacy data against entrenched TNF-alpha inhibitors. Counter emerging bispecific fusion protein threats by accelerating subcutaneous formulation convergence programs. For New Entrants and Emerging Players: Anchor in Brazil's ANVISA accelerated review pathway for rare disease biologics targeting sickle cell populations underserved by existing standards of care. Exploit glycomimetic chemistry platform advantages in oral bioavailability segments where patient self-administration drives preference. Pursue white-space positioning in lupus and vasculitis indications with limited biologic options through academic medical center partnerships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among immunology franchise specialists with established hospital access channels and direct integrated delivery network agreements. Long-term viability over the next decade rests on adaptive pathway regulatory expertise and real-world evidence generation infrastructure. Target acquisition archetypes combine glycomimetic chemistry platforms with validated subcutaneous delivery technologies. Monitor EMA conditional marketing authorization submissions as inflection indicators for portfolio exposure timing.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | P-selectin inhibitor Phase III programs in sickle cell vaso-occlusive crisis accelerate patient recruitment through Japan's specialist center density. |
| Regulatory Approval Pathway | EMA adaptive pathway alignment compresses confirmatory study timelines for oncology and hematology indications. |
| Manufacturing Scale-Up | Serum-free chemically defined media validation at Swiss contract manufacturing organizations reduces CHO cell culture input volatility. |
| Pipeline Diversification | Bispecific selectin-targeting fusion proteins decompose anti-TNF revenue concentration through dual-pathway inhibition. |
| Strategic Partnership | Direct manufacturer agreements with California and Massachusetts integrated delivery networks displace traditional wholesaler relationships. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through primary interviews with drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists. Secondary validation drew from FDA biologics license application filings, EMA centralized marketing authorization submissions, ClinicalTrials.gov protocol databases, and hospital procurement contract repositories. Bottom-up patient population modeling and top-down revenue triangulation anchored market size estimation.
Across the analysis window, forecasting employed treatment line stratification, administration route differentiation, and regional regulatory cluster segmentation. CAGRs were derived from epidemiological trend extrapolation and therapy penetration curve analysis. Forecast inputs incorporated ICH Q5D guideline implementation timelines and glycomimetic solid-phase synthesis automation trajectories.
Material uncertainties — cardiovascular safety signal detection intensity, CHO cell culture media cost volatility, and glycobiology specialist labor scarcity — sit outside the modeled envelope. Forecasts reflect documented assumptions about EMA adaptive pathway uptake rates and hospital formulary committee prior authorization evolution. Practitioners should keep alternative scenarios live as FDA guidance on accelerated approval endpoints for anti-inflammatory biologics evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Urea Cycle Disorder Market
Specialty Medicine
South America Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Balantidiasis Treatment Market
Specialty Medicine
Global Amyotrophic Lateral Sclerosis (ALS) Treatment Market
Specialty Medicine
Eisenmenger Complex Management Market
Specialty Medicine
Animal Hormone Therapy Market
Specialty Medicine
Global Scleroderma Therapeutics Market
Specialty Medicine
Neuroendocrine Carcinoma Treatment Market
Specialty Medicine
Gingivostomatitis Market
Specialty Medicine
Diffuse Large B-Cell Lymphoma Therapeutics Market
Specialty Medicine
Cutaneous Fibrosis Treatment Market
Specialty Medicine
Global Postmenopausal Osteoporosis Market
Specialty Medicine
Global Calciphylaxis Treatment Market
Specialty Medicine
Non Small Cell Lung Cancer (NSCLC) Therapeutics Market
Specialty Medicine
HER2 Positive Gastric Cancer Market
Specialty Medicine
Cystic Fibrosis Market