
 Paronychia Treatment Market | 2026-2036
Paronychia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Paronychia Treatment Market Outlook
Multi-source API procurement for topical antifungals is realigning how manufacturers secure active pharmaceutical ingredients. Teva Pharmaceutical Industries leverages its generic manufacturing scale to compete on cost across oral antibiotic formulations. Galderma sustains premium positioning through dermatology-specialized channel control and physician education investments.
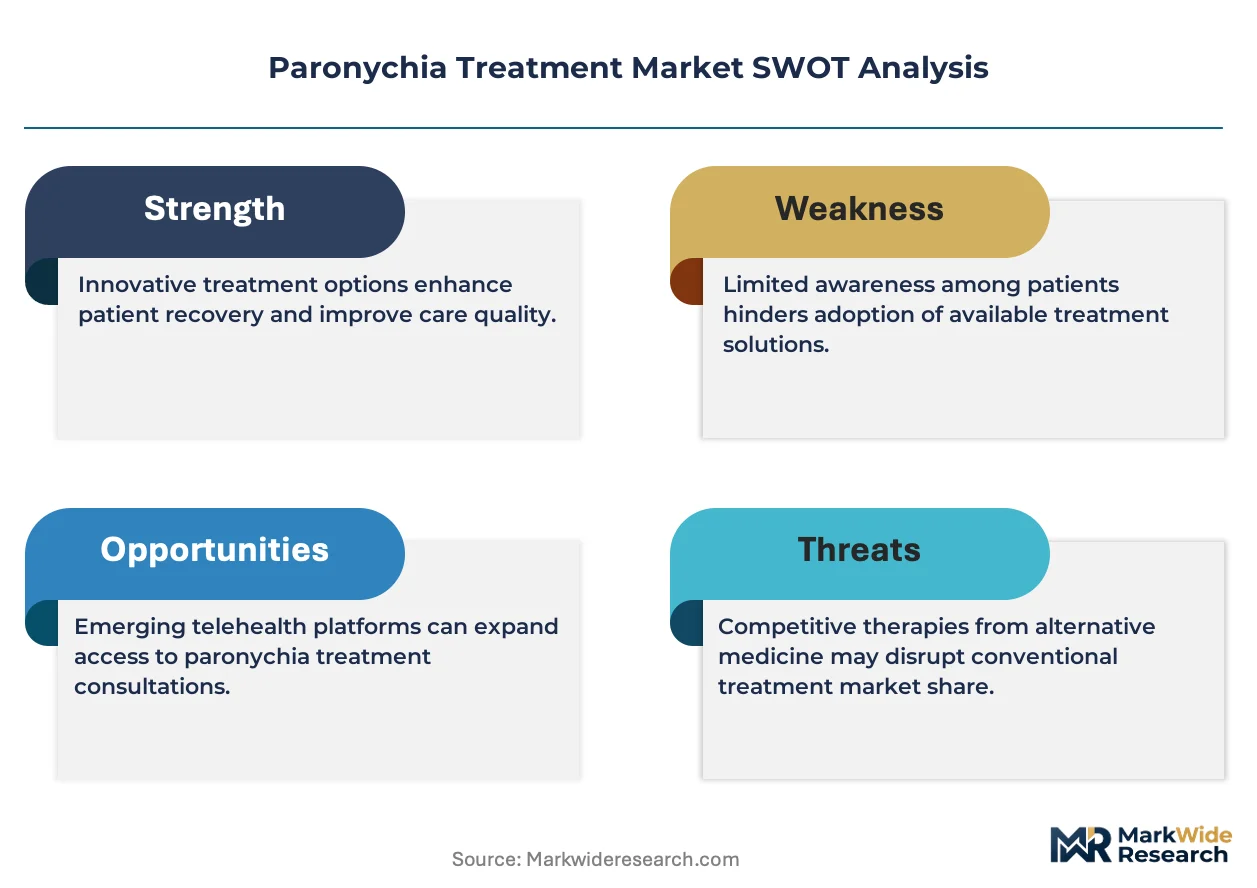
Paronychia treatment encompasses pharmacological and procedural interventions targeting periungual soft tissue infections, typically involving agents with minimum inhibitory concentrations calibrated against Staphylococcus aureus and Candida species to achieve microbial eradication. Topical antifungals occupy the largest revenue pool due to chronic paronychia recurrence patterns requiring extended therapy cycles. Surgical interventions represent the fastest-expanding segment as outpatient drainage procedures shift into dermatology practices and ambulatory surgical centers.
FDA antimicrobial development incentives and EPA topical antiseptic monograph standards shape product registration pathways and clinical evidence requirements for new entrants. The EU MDR and CE marking framework impose additional biocompatibility and sterility validation burdens on device-assisted surgical drainage systems. Stakeholders must monitor evolving FDA guidance on combination drug-device products, as topical corticosteroid-antifungal fixed-dose formulations face renewed scrutiny over resistance promotion risks.
Market Dynamics
Outpatient procedural migration is compressing hospital revenue for paronychia drainage while expanding ambulatory surgical center throughput. Teva Pharmaceutical Industries and Galderma are competing across divergent channel strategies—generic scale versus specialty dermatology control.
Growth Catalysts
- FDA Antimicrobial Development Incentives:Streamlined pathways for topical antifungals accelerate product registration timelines. Manufacturers prioritize fixed-dose corticosteroid-antifungal combinations under this framework.
- Ambulatory Surgical Center Expansion:Dermatology practices are building in-house procedural capacity for nail bed infections. This shift captures cases previously referred to hospital outpatient departments.
- Chronic Recurrence Patterns:Extended therapy cycles for Candida-associated paronychia sustain demand for topical antifungals. Patients require months of treatment rather than single-dose resolution.
Market Restraints
- API Supply Concentration:Multi-source procurement for topical antifungal actives faces geographic bottlenecks. Indian and Chinese API manufacturers control critical intermediate supply.
- EU MDR Compliance Burden:Biocompatibility and sterility validation requirements for surgical drainage devices extend certification timelines. Small device manufacturers lack resources for notified body engagement.
- Oral Antibiotic Substitution:Primary care physicians default to systemic antibiotics for acute bacterial paronychia. This bypasses topical and procedural alternatives despite resistance risks.
Strategic Opportunities
- Retail Clinic Channel Penetration:MinuteClinic and similar chains in the United States are adding dermatology services. These locations handle uncomplicated paronychia with standardized protocols.
- Combination Drug-Device Products:Topical corticosteroid-antifungal formulations paired with sterile drainage kits address complete care episodes. FDA guidance on these products remains favorable for innovators.
- Integrated Dermatology Networks:Private equity-backed practice consolidators are centralizing procurement. Volume commitments favor suppliers with national distribution infrastructure.
Industry Challenges
- Physician Education Requirements:Proper nail bed drainage technique demands hands-on training. Dermatology residency programs offer limited procedural exposure.
- Resistance Surveillance:Candida species with reduced azole susceptibility complicate treatment selection. Clinical laboratories lack standardized antifungal susceptibility testing for nail infections.
- Reimbursement Compression:Commercial payors are narrowing coverage for procedural paronychia management. Prior authorization requirements delay patient access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paronychia Treatment Market |
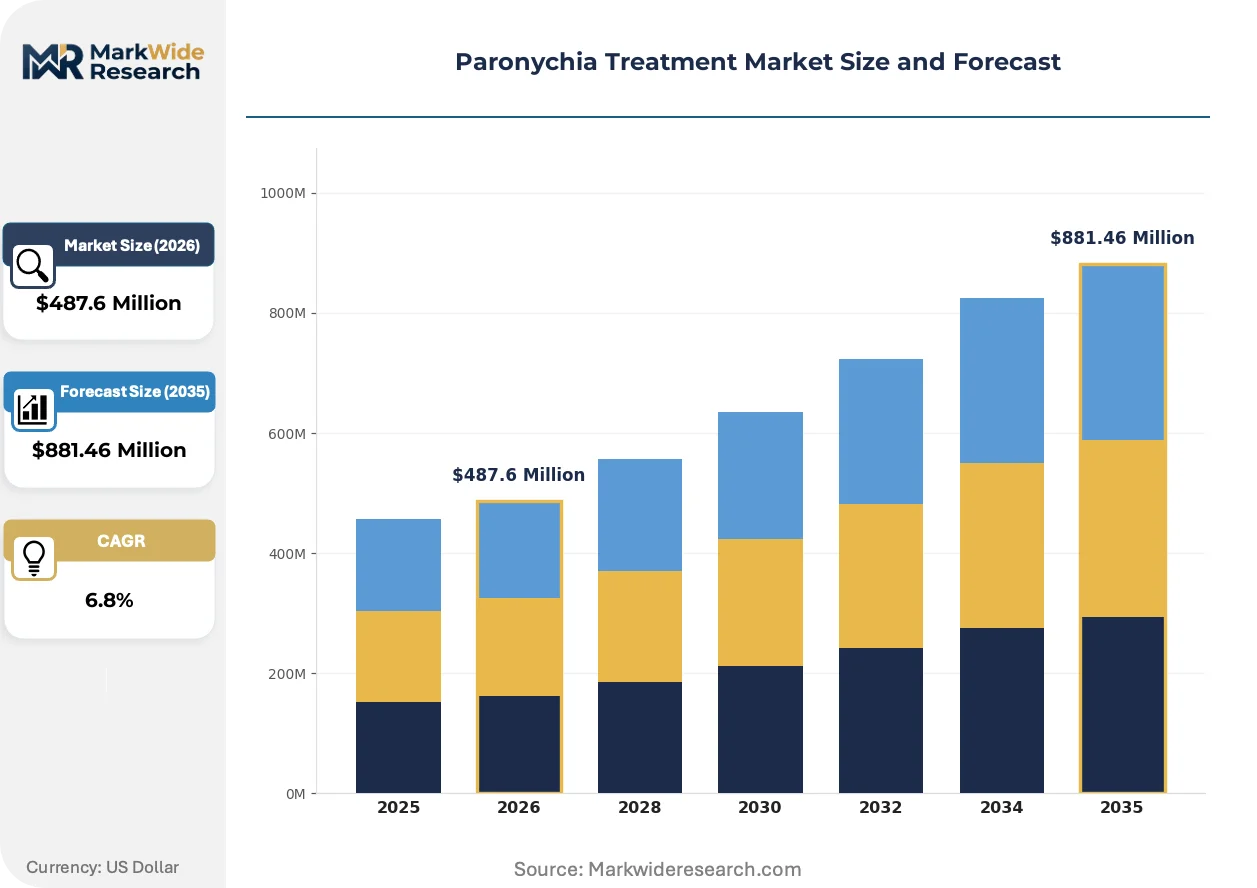
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Antifungals, Oral Antibiotics, Topical Corticosteroids, Surgical Interventions Application: Acute Paronychia, Chronic Paronychia, Nail Bed Infection, Soft Tissue Infection End User: Hospitals, Clinics, Homecare Settings, Dermatology Practices Treatment Modality: Conservative Management, Surgical Drainage, Pharmacological Intervention, Alternative Therapy |
| Companies Covered | Teva Pharmaceutical Industries Ltd., Johnson & Johnson, Pfizer Inc., Sanofi, Merck & Co., Inc., GlaxoSmithKline plc, Novartis AG, Galderma S.A., Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paronychia Treatment Market Strategic Shifts
Topical formulation science and procedural automation are reshaping how paronychia is managed across care settings. Regulatory scrutiny of combination products and resistance promotion risks is intensifying evidence requirements.
Polymer-based topical delivery systems are absorbing into dermatology practice workflows. These formulations extend drug residence time at the nail fold. Ambulatory centers adopt them to reduce dressing change frequency. The technology is absorbing hospital outpatient volume by enabling same-day discharge without follow-up nursing visits.
EPA Topical Antiseptic Monograph standards are tightening clinical evidence thresholds for new antiseptic claims. Manufacturers must submit additional safety data for active ingredients previously grandfathered under earlier frameworks. Surgical preparation products face the steepest compliance burden, with several antiseptic solutions requiring reformulation or indication restriction.
Primary care gatekeepers are fragmenting referral patterns for paronychia cases. Urgent care centers now handle initial presentation rather than routing directly to dermatology. This channel shift concentrates volume in retail-adjacent locations with limited specialist access. The United States exhibits the most pronounced pattern, where integrated delivery networks struggle to recapture diverted cases.
Paronychia Treatment Market Segmentation
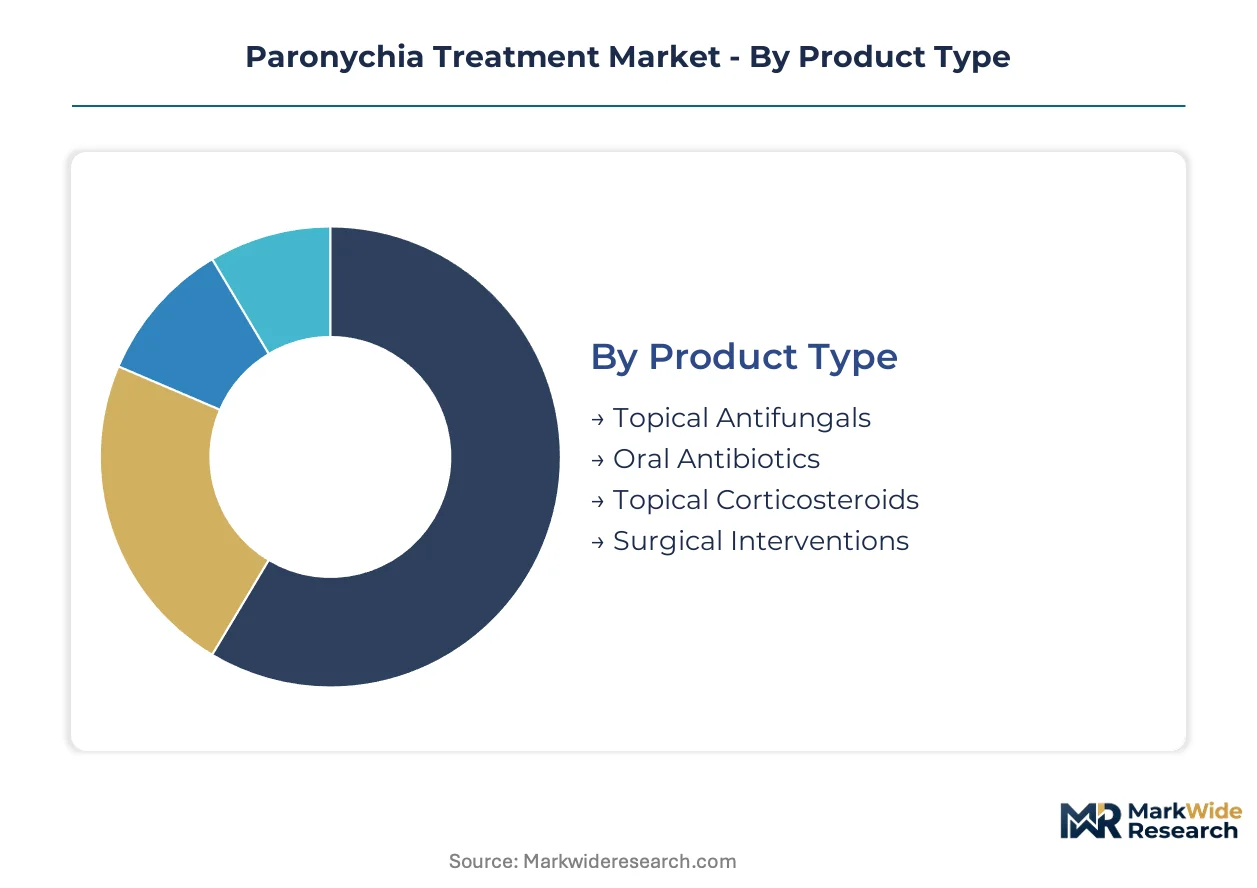
Paronychia treatment segmentation reveals divergent regulatory pathways across product categories. FDA antimicrobial incentives and EU MDR compliance burdens reshape where manufacturers allocate development resources.
Product Type:
Certification requirements split sharply across this category. Topical antifungals navigate FDA streamlined pathways, while surgical drainage devices face EU MDR biocompatibility validation.
- Topical Antifungals:Azole and allylamine formulations targeting Candida species dominate chronic case management. Demand concentrates in United States dermatology practices where extended therapy cycles sustain prescription volume. FDA development incentives accelerate registration timelines for fixed-dose combinations.
- Surgical Interventions:Outpatient drainage procedures and nail bed debridement techniques comprise this segment. Ambulatory surgical centers in the United States absorb cases previously routed to hospital outpatient departments. EU MDR sterility validation extends certification timelines for device manufacturers.
- Oral Antibiotics:Systemic agents for acute bacterial paronychia.
- Topical Corticosteroids:Anti-inflammatory adjuncts for mixed infectious presentations.
Gaining share fastest: Surgical Interventions. Leading by volume: Topical Antifungals.
Application:
Recurrence patterns determine treatment economics across patient presentations. Chronic cases generate recurring revenue streams absent from acute bacterial resolution.
- Chronic Paronychia:Persistent Candida-associated infections requiring months of antifungal therapy. United States integrated dermatology networks capture these cases through subscription-based care models. Recurrence sustains demand for polymer-based extended-release formulations.
- Acute Paronychia:Sudden-onset bacterial infections typically resolving with single-intervention therapy. Urgent care centers in the United States handle initial presentation, fragmenting referral patterns to dermatology. Primary care physicians default to oral antibiotics despite resistance risks.
- Nail Bed Infection:Deep tissue involvement requiring procedural intervention.
- Soft Tissue Infection:Periungual inflammation without nail matrix penetration.
Expanding most quickly: Chronic Paronychia. Dominating procedure counts: Acute Paronychia.
End User:
Channel migration redistributes volume across care settings. Retail clinic expansion and private equity practice consolidation reshape procurement concentration.
- Dermatology Practices:Specialized settings building in-house procedural capacity for nail bed infections. Private equity-backed consolidators in the United States centralize procurement across multi-site networks. Volume commitments favor suppliers with national distribution infrastructure.
- Clinics:Retail-adjacent locations including MinuteClinic chains adding standardized dermatology protocols. These sites handle uncomplicated paronychia with limited specialist access. Prior authorization requirements from commercial payors delay patient access.
- Hospitals:Traditional referral centers losing outpatient drainage volume to ambulatory settings.
- Homecare Settings:Post-procedural dressing management and extended topical therapy administration.
Climbing the fastest: Dermatology Practices. Retaining largest case base: Clinics.
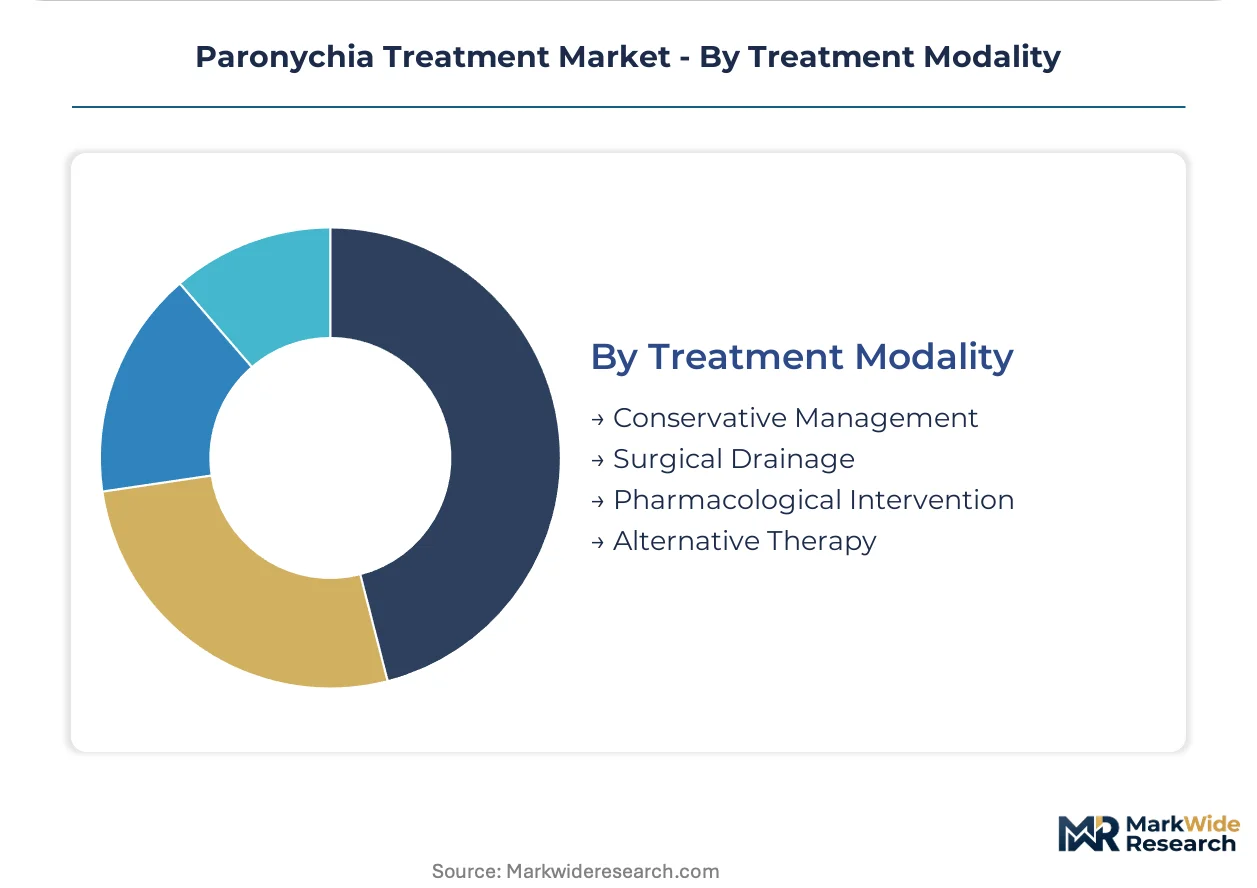
Treatment Modality:
Evidence requirements vary sharply across intervention philosophy. Pharmacological pathways face FDA antimicrobial scrutiny while surgical approaches confront device regulation.
- Pharmacological Intervention:Drug-based management spanning topical and systemic agents. EPA Topical Antiseptic Monograph standards tighten clinical evidence thresholds for new antiseptic claims. Manufacturers submit additional safety data for previously grandfathered active ingredients.
- Surgical Drainage:Incision and debridement procedures shifting into office-based settings. Dermatology residency programs offer limited procedural exposure, creating training gaps. Sterile drainage kits paired with topical formulations address complete care episodes.
- Conservative Management:Warm soaks and observation without pharmaceutical or procedural intervention.
- Alternative Therapy:Non-pharmacological approaches including laser and photodynamic modalities.
Steepest expansion trajectory: Surgical Drainage. Maintaining highest utilization: Pharmacological Intervention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian and Chinese API manufacturers control critical intermediate supply for topical antifungal actives, anchoring geographic concentration in paronychia treatment manufacturing. Demand-side volume concentrates in dermatology-specialized markets with integrated care networks and retail clinic infrastructure.
United States
Integrated dermatology networks and retail clinic chains drive procedural volume for nail bed infections. FDA antimicrobial development incentives accelerate topical antifungal registration timelines. Private equity-backed practice consolidators in Texas and Florida centralize procurement across multi-site networks.
Germany
EU MDR compliance capabilities and notified body proximity attract surgical drainage device manufacturers seeking CE marking efficiency. The country's national pharmaceutical regulator maintains stringent biocompatibility validation standards. Medical technology clusters in Baden-Württemberg host sterile device engineering specialists.
India
Multi-source API procurement for azole and allylamine actives flows through Mumbai and Hyderabad manufacturing hubs. CDSCO streamlined pathways for generic topical formulations reduce time-to-market for domestic producers. Gujarat-based chemical intermediates suppliers feed downstream formulation facilities.
China
NMPA oversight of combination drug-device products shapes registration strategy for corticosteroid-antifungal fixed-dose formulations. Yangtze River Delta chemical parks produce critical antifungal intermediates for export. Shanghai-based contract manufacturers serve multinational dermatology brands.
United Kingdom
NHS procurement frameworks for dermatology services influence prescribing patterns for chronic paronychia management. The country's national pharmaceutical regulator aligns with EMA standards for topical antimicrobial safety data. London-based integrated care systems pilot subscription models for extended antifungal therapy.
Paronychia Treatment Market Competitive Environment
Strategic partnerships dominate the current landscape as manufacturers seek combination product capabilities spanning pharmaceuticals and sterile devices. The vendor base separates into three tiers: multinational pharmaceutical conglomerates with dermatology divisions, mid-scale generic manufacturers competing on API cost, and specialized device fabricators focused on ambulatory surgical instruments. Two archetypes anchor positioning: premium-tier players controlling dermatology-specialized channels through physician education investments, and scale-driven competitors leveraging vertical integration into generic active pharmaceutical ingredient production. Portfolio diversification and geographic expansion through retail clinic channel penetration represent the dominant competitive moves.
Within the premium-tier archetype, Galderma S.A. exemplifies dermatology-specialized channel control, while Teva Pharmaceutical Industries Ltd. occupies a position representing generic manufacturing scale. Johnson & Johnson sits within the diversified healthcare conglomerate tier, anchoring a position that spans consumer health and professional surgical product lines. These three entities collectively represent the strategic positioning spectrum visible in the competitive set.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd. |
| Johnson & Johnson |
| Pfizer Inc. |
| Sanofi |
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Novartis AG |
| Galderma S.A. |
| Bayer AG |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up dermatology practice networks anchor pricing discipline through centralized procurement mandates that compress supplier margins while locking in multi-year formulary commitments. Their volume aggregation across Texas and Florida consolidations feeds directly into manufacturer rebate structures, reshaping how topical antifungal and surgical drainage kit suppliers compete for national account status.
Pricing Analysis
Warranty and service bundling separates premium-tier suppliers from commodity competitors in this market. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and physician education investment depth. Pricing pressure stems from integrated dermatology networks demanding standardized protocols that commoditize procedural kits. Retail clinic chains exhibit highest price sensitivity, while private-equity-backed practice consolidators trade margin for exclusive supply agreements.
Supply Chain Analysis
CE marking and FDA 510(k) clearance gates filter device manufacturers from pharmaceutical suppliers, creating divergent qualification pathways. API production concentrates in India and China, with formulation finishing in United States and German facilities. Critical inputs span azole intermediates, allylamine precursors, and sterile polymer delivery matrices. Single-source vulnerability runs through Mumbai and Hyderabad chemical hubs for antifungal actives. Distribution runs through specialized dermatology distributors and GPO contracts to ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU MDR biocompatibility validation and FDA combination product guidance erect barrier-to-entry moats that favor incumbent players with established regulatory affairs infrastructure.
For Market Incumbents: Deepen backward integration into API supply by acquiring Gujarat-based chemical intermediate producers or securing captive offtake agreements. Expand sterile device manufacturing capacity in Baden-Württemberg to exploit notified body proximity for CE marking efficiency. Generic substitution pressure from Teva Pharmaceutical Industries threatens premium positioning; defend through physician education investments that proceduralize brand loyalty. For New Entrants and Emerging Players: Polymer-based extended-release topical delivery systems offer a technology-first wedge into the chronic paronychia segment underserved by conventional formulations. Target ambulatory surgical centers in United States retail-adjacent locations where integrated dermatology networks have not yet consolidated procurement. Pursue FDA streamlined pathway submissions for fixed-dose corticosteroid-antifungal combinations as the fastest regulatory route to commercial presence. For Investors and Strategic Acquirers: FDA guidance publication on combination drug-device products is the leading indicator that regulatory clarity will trigger consolidation among sterile drainage kit manufacturers lacking pharmaceutical formulation capabilities. The five-to-ten year viability window favors platforms spanning both pharmacological and procedural modalities. Target mid-scale device fabricators with CE marking progress but underdeveloped United States distribution. Watch for CDSCO pathway acceleration in India as signal of API supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA streamlined antimicrobial incentives accelerate topical antifungal registration timelines for fixed-dose combinations. |
| Backward Integration | Captive API supply from Indian chemical hubs reduces exposure to geographic concentration in azole intermediate production. |
| Hospital System Partnership | Integrated dermatology network contracts in Texas and Florida centralize procurement across multi-site private-equity consolidations. |
| Manufacturing Scale-Up | Ambulatory surgical center throughput expansion demands sterile drainage kit production capacity in CE marking-efficient jurisdictions. |
| Reimbursement Strategy | Commercial payor prior authorization navigation determines patient access velocity for procedural paronychia management. |
Study Parameters
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, supplemented by customs records tracking API import flows and hospital procurement database extracts. Primary interviews with dermatology practice administrators, ambulatory surgical center procurement managers, sterile device engineering specialists, and GPO contracts managers validated demand-side assumptions. Bottom-up and top-down triangulation reconciled patient volume estimates with manufacturer shipment data across the analysis window.
Bottom-up modeling anchored volume projections to procedure counts in dermatology practices and retail clinic chains, while top-down validation cross-checked against pharmaceutical shipment reports and device import statistics. Segmentation dimensions spanned product type, application chronicity, end-user channel, and treatment modality philosophy. CAGRs derived from logistic curve fitting to adoption saturation patterns in integrated care networks. Forecast inputs incorporated FDA guidance timeline assumptions and EU MDR notified body capacity constraints.
Several conditions sit outside the modeled scope, including emergent Candida azole resistance surveillance gaps, commercial payor reimbursement policy reversals, and raw material tariff escalations affecting Indian API exports. Forecasts reflect documented assumptions about regulatory pathway stability and private-equity consolidation velocity. A model refresh is warranted upon material change in FDA combination product guidance or CDSCO generic topical formulation pathway acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Cat Scratch Disease (CSD) Treatment Market
Specialty Medicine
Disruptive Behavior Disorders Market
Specialty Medicine
Essential Thrombocythemia Market
Specialty Medicine
Americas Gerd and Nerd Treatment Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Non Small Cell Lung Cancer (NSCLC) Therapeutics Market
Specialty Medicine
SPINA Bifida and Hydrocephalus Market
Specialty Medicine
Axillary Hyperhidrosis Treatment Market
Specialty Medicine
Necrotizing Fasciitis Market
Specialty Medicine
Global Chronic Idiopathic Constipation Market
Specialty Medicine
Global Acquired Aplastic Anemia Market
Specialty Medicine
Global Lupus Market
Specialty Medicine
Abetalipoproteinemia Management Market
Specialty Medicine
Major Depressive Disorder (MDD) Treatment Market
Specialty Medicine
Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Hashimoto's Thyroiditis Therapeutics Market