
 Hidradenitis Suppurativa (HS) Treatment Market | 2026-2036
Hidradenitis Suppurativa (HS) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hidradenitis Suppurativa (HS) Treatment Market Foresight
Patient referral networks is broadening as community dermatology practices integrate with academic medical centers to manage moderate-to-severe HS cases. AbbVie leverages its immunology infrastructure to sustain Humira's position while navigating biosimilar transition dynamics. Novartis competes through Cosentyx's IL-17A blockade, positioning the therapy for patients who fail TNF-alpha inhibition. Eli Lilly and Company anchors its pipeline with selective IL-17 modulators targeting cytokine-driven inflammation pathways.
Hidradenitis suppurativa treatment encompasses pharmacologic and procedural interventions targeting chronic follicular occlusion, recurrent nodule formation, and tunneling sinus tracts in apocrine gland-bearing skin regions. Biologics dominate the product type landscape, with anti-TNF and IL-17 inhibitors commanding premium reimbursement due to their targeted mechanism and surgical-sparing outcomes. The treatment approach dimension shows combination therapy gaining traction as clinicians layer medical management with timed surgical intervention to reduce recurrence rates. Injectable administration routes lead in value contribution, though topical formulations address early-stage disease and maintenance protocols.
The FDA regulates HS biologics through its Center for Drug Evaluation and Research, requiring extensive Phase III programs with validated outcome measures such as the HiSCR response criterion. The EMA's Committee for Medicinal Products for Human Use applies analogous efficacy standards while facilitating parallel scientific advice for developers targeting both jurisdictions. Payer formularies on both sides of the Atlantic increasingly mandate documented antibiotic failure before authorizing biologic therapy, creating access friction that shapes prescribing behavior and commercial strategy. Stakeholders must monitor evolving endpoint requirements from regulators and the integration of patient-reported outcomes into coverage determinations.
Market Dynamics
Biologic infusion capacity expansion at dermatology clinics is compressing referral timelines while payer prior authorization reform restructures patient access economics across major markets.
Growth Catalysts
- FDA Breakthrough Therapy pathway:Accelerated review timelines for novel biologics targeting refractory HS compress development-to-commercialization cycles for developers.
- Academic medical center integration:Community dermatology practices linking with tertiary referral networks expand specialist capacity for moderate-to-severe case management.
- IL-17 inhibitor formulary expansion:Broadening payer coverage for cytokine-targeted therapies shifts treatment algorithms beyond TNF-alpha first-line protocols.
Market Restraints
- Biologic manufacturing concentration:Monoclonal antibody production clusters in contract manufacturing organizations create supply vulnerability for injectable therapies.
- Antibiotic failure documentation mandates:Payer formularies requiring documented tetracycline or clindamycin failure before biologic authorization introduce access friction.
- Surgical co-management costs:Timed procedural interventions for sinus tract excision add facility and anesthesia expenses to medical management.
Strategic Opportunities
- Topical JAK inhibitor development:Early-stage disease formulations targeting follicular inflammation without systemic immunosuppression address unmet maintenance needs.
- Patient-reported outcome integration:HiSCR response criteria supplemented with quality-of-life measures reshape coverage determination frameworks.
- Telemedicine triage protocols:Remote dermatology assessment channels reduce geographic access barriers for HS diagnosis and referral.
Industry Challenges
- Specialist workforce density:Board-certified dermatologists with HS expertise concentrate in urban academic centers, leaving rural and suburban markets underserved.
- Biosimilar transition complexity:Originators and follow-on biologics require distinct infusion protocols and monitoring standards that complicate pharmacy operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hidradenitis Suppurativa (HS) Treatment Market |
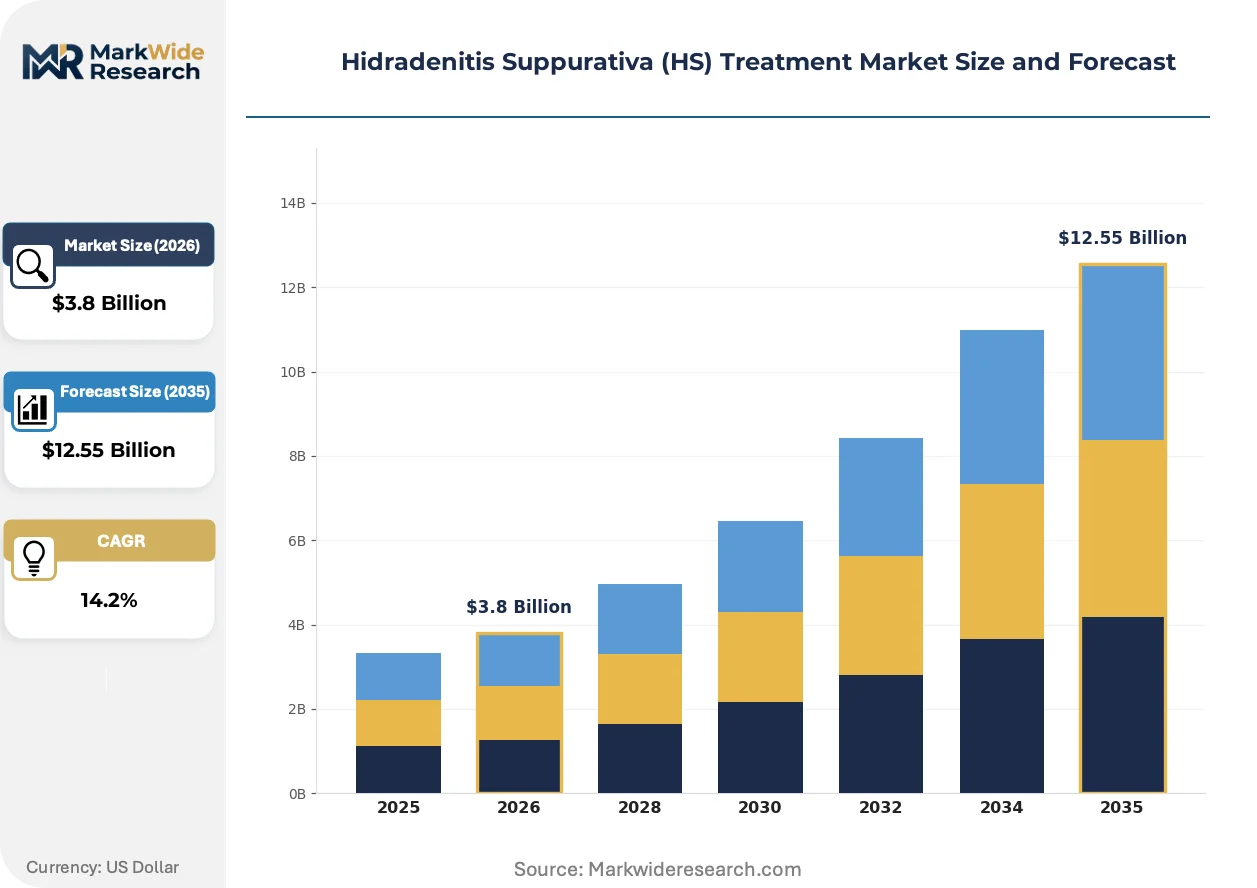
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Antibiotics, Corticosteroids, Immunosuppressants Treatment Approach: Medical Management, Surgical Intervention, Combination Therapy, Topical Treatments Administration Route: Injectable, Oral, Topical, Intralesional End User: Hospitals, Dermatology Clinics, Homecare Settings, Specialty Pharmacies |
| Companies Covered | AbbVie, Novartis, Eli Lilly and Company, Pfizer, Johnson & Johnson Private Limited, Sanofi, InflaRx, UCB, Incyte Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hidradenitis Suppurativa (HS) Treatment Market Shifts & Advancements
Digital pathology and AI-assisted lesion scoring are compressing diagnostic variability while biomarker stratification tools reshape trial design and patient selection protocols.
Machine learning algorithms analyzing sinus tract morphology and inflammatory biomarker panels are integrating into clinical decision support systems at major dermatology departments. Academic medical centers in Germany and the United States pilot these platforms to standardize HiSCR assessments across multi-site studies. The technology is integrating retrospective outcome databases with real-world evidence registries to refine responder prediction models.
EMA's PRIME scheme for priority medicines is accelerating scientific advice timelines for HS developers seeking parallel US-EU registration strategies. The framework compresses pre-submission consultation phases and enables rolling review of Phase III data packages. Developers targeting refractory populations are responding by embedding European sites earlier in global trial programs.
Specialist referral networks are unbundling traditional academic center monopolies as community-based infusion suites secure biologic administration certifications. Independent dermatology groups in Texas, Florida, and Ontario are displacing hospital outpatient departments for maintenance dosing. This channel shift is most visible in markets where prior authorization reform permits community site-of-service parity.
Hidradenitis Suppurativa (HS) Treatment Market Segmentation
Treatment modality selection in hidradenitis suppurativa hinges on disease staging, payer authorization pathways, and site-of-service capabilities. Segment boundaries blur as clinicians layer medical and procedural interventions, forcing manufacturers to position across multiple categories simultaneously.
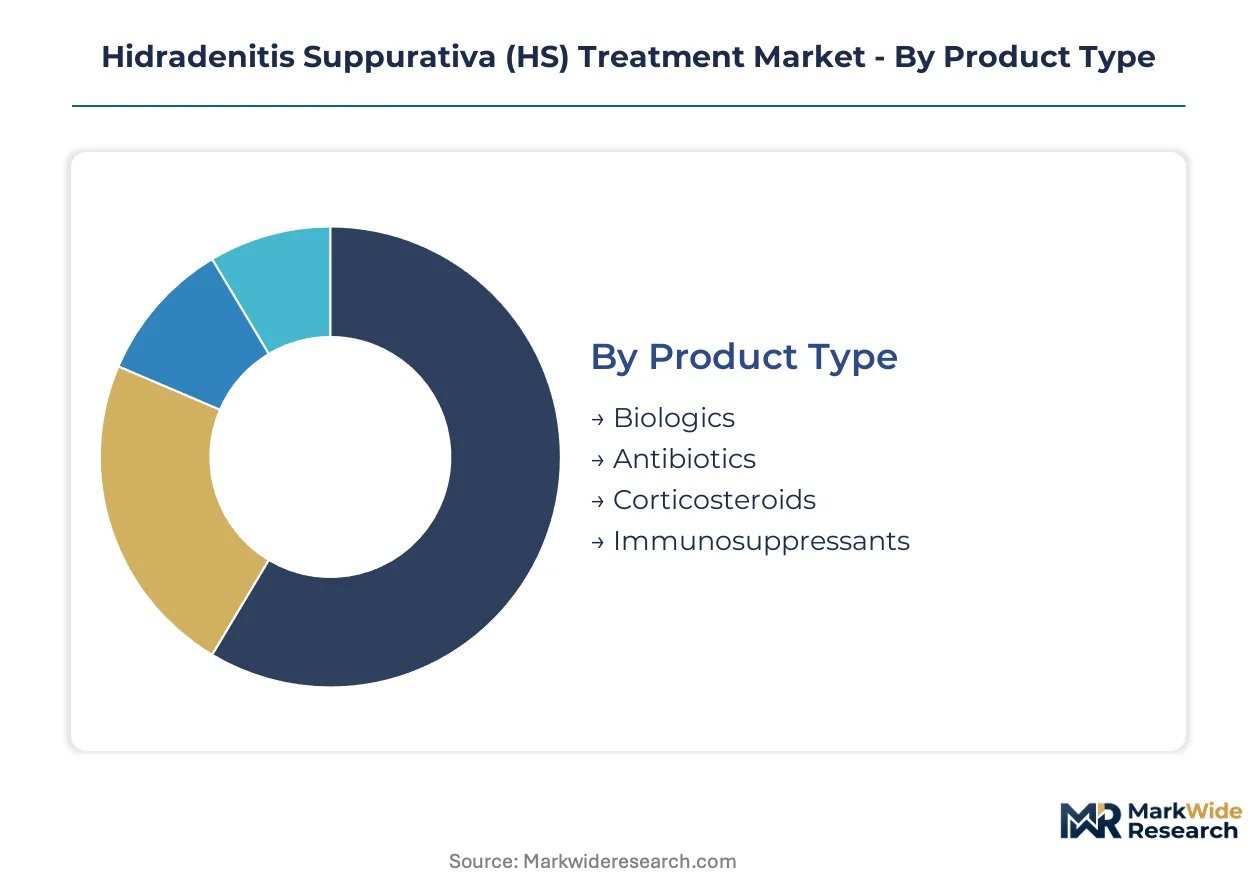
Product Type:
FDA's Center for Drug Evaluation and Research mandates distinct approval pathways for monoclonal antibodies versus small-molecule agents, creating divergent certification timelines and post-market surveillance obligations.
- Biologics:Monoclonal antibodies targeting IL-17A, TNF-alpha, and emerging cytokine pathways require REMS programs and specialized infusion infrastructure. Demand concentrates in academic dermatology centers across the United States and Germany where prior authorization reform has accelerated patient access.
- Antibiotics:Tetracycline derivatives and clindamycin combinations serve as mandatory first-line therapy under most payer formularies before biologic authorization. Prescribing clusters in community dermatology practices facing documentation burdens for failure criteria.
- Corticosteroids:Intralesional and systemic formulations address acute flares without disease-modifying claims.
- Immunosuppressants:Conventional systemic agents occupy niche positioning for patients with biologic contraindications.
Biologics sits at the top of the volume ranking, with antibiotics climbing the fastest as payer mandates extend treatment duration requirements.
Treatment Approach:
Reimbursement economics vary sharply across approaches, with combination protocols commanding facility fees that alter margin structures for site operators.
- Medical Management:Pharmacologic monotherapy or polypharmacy without procedural intervention dominates early-stage disease protocols. Adoption concentrates in United States commercial plans where step therapy requirements enforce extended medical trials.
- Surgical Intervention:Wide local excision, deroofing, and laser sinus tract destruction address Hurley Stage II-III disease. Volume localizes to tertiary referral centers in Boston, Berlin, and Toronto where multidisciplinary wound care infrastructure exists.
- Combination Therapy:Timed surgical intervention layered with biologic maintenance reduces recurrence rates in refractory populations.
- Topical Treatments:Early-stage maintenance and adjuvant care for limited disease distribution.
Medical management captures the largest patient population, though combination therapy gains share fastest as outcomes data accumulates.
Administration Route:
Site-of-service regulations and nursing scope-of-practice rules fragment distribution economics across delivery modes.
- Injectable:Subcutaneous and intravenous biologic delivery requires cold-chain logistics and adverse event monitoring protocols. Capacity expansion concentrates in community infusion suites across Texas, Florida, and Ontario displacing hospital outpatient departments.
- Oral:Small-molecule antibiotics and immunosuppressants enable pharmacy benefit management without medical benefit complexity. Prescribing concentrates in Medicare and Medicaid populations where site-of-service restrictions limit infusion access.
- Topical:Patient-administered formulations reduce total cost of care for maintenance protocols.
- Intralesional:Corticosteroid depot injections performed in-office for isolated nodule management.
Injectable leads absolute value contribution, with oral formulations expanding most quickly as payer cost-containment intensifies.
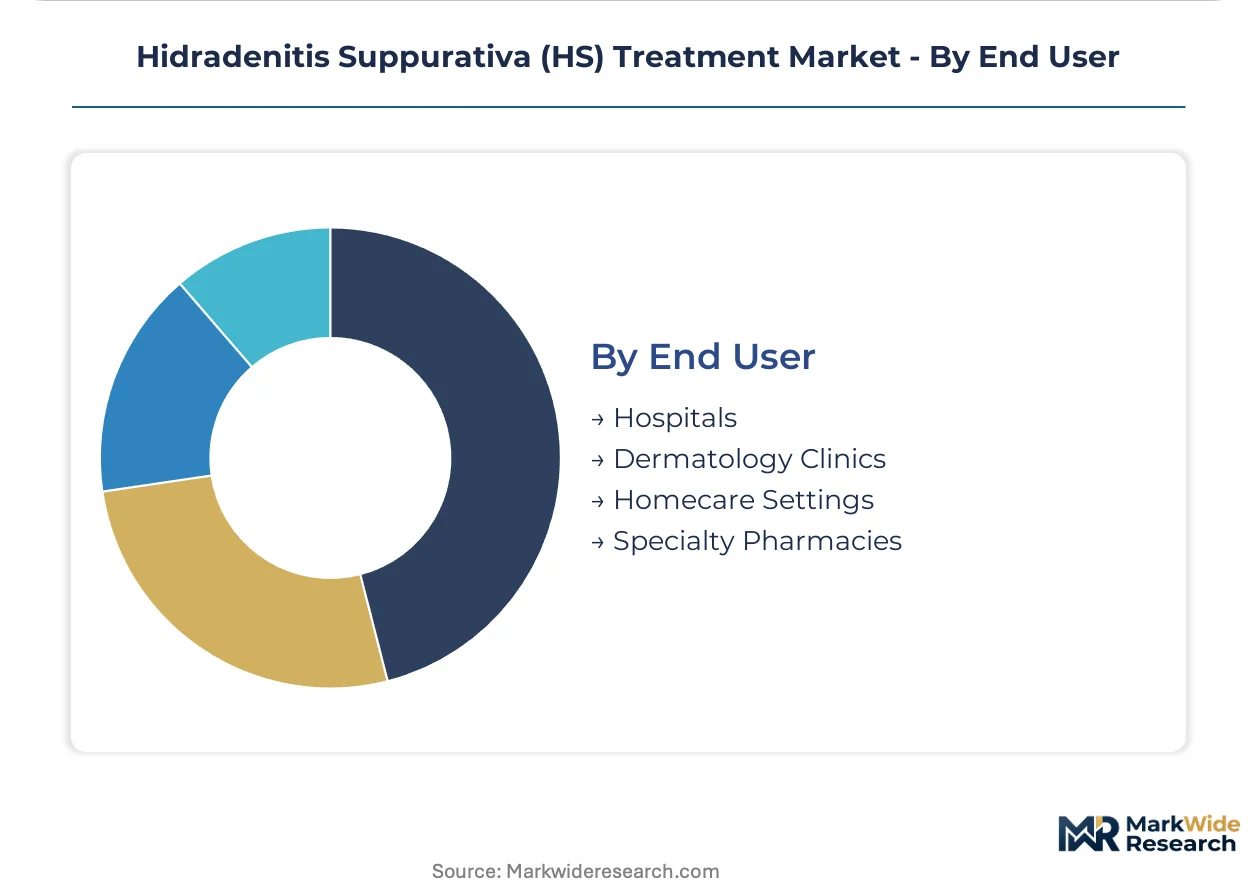
End User:
Facility certification requirements and biologic purchasing agreements reshape competitive dynamics across care settings.
- Dermatology Clinics:Independent and academic-affiliated practices with infusion certification capture maintenance dosing volume. Growth concentrates in suburban markets surrounding Cleveland Clinic, Mayo Clinic, and Charité Berlin referral networks.
- Hospitals:Tertiary centers retain complex surgical cases and biologic induction protocols where anesthesia and imaging support are required.
- Homecare Settings:Self-administered subcutaneous biologics shift volume from facility-based care.
- Specialty Pharmacies:Hub services manage prior authorization, patient assistance, and adherence monitoring for infused therapies.
Dermatology clinics sit at the top of the volume ranking, with homecare settings climbing the fastest as subcutaneous formulations proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States biologic reimbursement reform outpaces German formulary expansion, while Japanese regulatory timelines lag both markets for novel HS therapies.
United States
Prior authorization reform and specialist referral network expansion accelerate patient access to IL-17 and TNF-alpha inhibitors. FDA's Breakthrough Therapy designation compresses review timelines for refractory disease candidates. Cleveland Clinic and Mayo Clinic anchor multidisciplinary HS centers in Ohio and Minnesota.
Germany
EMA's PRIME scheme enables rolling review of Phase III data for developers targeting refractory populations. Charité Berlin and university hospitals in Munich pilot AI-assisted lesion scoring platforms for standardized HiSCR assessments. Outpatient biologic infusion capacity expands in North Rhine-Westphalia.
United Kingdom
NICE technology appraisals mandate cost-effectiveness thresholds that shape biologic access protocols for moderate-to-severe cases. London teaching hospitals retain complex surgical volumes while community dermatology practices in Greater Manchester secure infusion certifications. NHS England's prior authorization reform reduces referral delays.
Japan
PMDA review timelines for biologics trail FDA and EMA pathways, delaying market entry for novel cytokine inhibitors. Tokyo and Osaka academic centers concentrate specialist expertise for Hurley Stage III surgical management. Pharmaceutical and Medical Devices Agency consultation requirements extend pre-submission phases.
Canada
Health Canada aligns biologic approval standards with FDA and EMA while provincial formularies create access variation across Ontario, Quebec, and British Columbia. Toronto and Vancouver dermatology clinics displace hospital outpatient departments for maintenance dosing. CADTH reimbursement reviews introduce parallel economic evaluation requirements.
Hidradenitis Suppurativa (HS) Treatment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the HS treatment landscape, creating a tiered structure where scale advantages clash with therapeutic depth. Large-cap immunology franchises leverage existing infusion infrastructure and payer relationships to defend positioning against mid-cap biotech entrants. Three archetypes dominate: established biologic heavyweights with dermatology salesforces, emerging cytokine pathway specialists, and surgical device manufacturers layering procedural solutions. Consolidation activity concentrates on cytokine biology assets, while geographic expansion targets underserved Asia-Pacific markets.
Within the large-cap immunology tier, AbbVie and Novartis occupy positions shaped by legacy TNF-alpha dominance and IL-17A blockade respectively. Eli Lilly and Company anchors the emerging cytokine modulator segment with selective pathway targeting. These three entities exemplify competitive positioning strategies ranging from biosimilar transition management to novel mechanism first-mover advantage.
| Leading Market Players |
|---|
| AbbVie |
| Novartis |
| Eli Lilly and Company |
| Pfizer |
| Johnson & Johnson Private Limited |
| Sanofi |
| InflaRx |
| UCB |
| Incyte Corporation |
| Others |
Supply & Pricing Matrix
Cold-chain logistics costs for monoclonal antibody biologics cascade through three pricing tiers as product moves from contract manufacturing organizations in Switzerland and Ireland through specialty pharmacy hubs to dermatology infusion suites across Texas, Florida, and Ontario.
Pricing Analysis
Capacity additions in Germany and Switzerland are reshaping price floors for IL-17 and TNF-alpha inhibitors as biosimilar manufacturing expands. Three-tier pricing structure across originator biologics, biosimilars, and conventional systemic agents reflects FDA Breakthrough Therapy premium capture versus antibiotic failure documentation burdens. Pricing pressure stems from payer step-therapy mandates requiring extended tetracycline trials before biologic authorization. Medicare and Medicaid populations exhibit highest price sensitivity due to site-of-service restrictions, while commercial plans absorb premium positioning for surgical-sparing outcomes.
Supply Chain Analysis
Dual-sourcing requirements from FDA and EMA regulators mandate multi-supplier qualification for monoclonal antibody production, dispersing manufacturing across Switzerland, Ireland, and Singapore. Active pharmaceutical ingredients draw from specialized fermentation facilities, while fill-finish operations cluster in temperature-controlled European hubs. Single-source vulnerability concentrates in viral vector production for emerging gene therapies. Distribution runs through specialty pharmacy networks with REMS-compliant cold-chain monitoring to certified dermatology infusion sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hidradenitis suppurativa treatment market functions as a regulatory compounder where FDA Breakthrough Therapy and EMA PRIME designations accelerate commercial timelines and compress development risk for novel cytokine inhibitors.
For Market Incumbents: Anticipate biosimilar erosion in TNF-alpha franchises by anchoring IL-17A and selective cytokine modulator pipelines with differentiated mechanism claims. Defend formulary positioning through real-world evidence registries linking HiSCR response rates to surgical cost avoidance. Prioritize backward integration into diagnostic AI platforms to standardize patient selection and compress trial variability. For New Entrants and Emerging Players: Capture white-space in topical JAK inhibitor maintenance protocols for Hurley Stage I patients excluded from biologic eligibility. Target community dermatology practices in suburban markets surrounding Cleveland Clinic and Mayo Clinic referral networks where infusion certification expansion outpaces specialist supply. Deploy telemedicine triage partnerships to reduce geographic access friction and accelerate diagnosis-to-treatment intervals. For Investors and Strategic Acquirers: Consolidation pressure builds where cytokine biology assets lack commercial infrastructure to navigate payer prior authorization complexity. Long-term viability favors platforms with parallel FDA-EMA registration strategies and embedded European site networks. Target acquisition archetypes include Phase II-ready selective IL-17 modulators with biomarker-stratified responder data. Watch for inflection in community infusion suite certification velocity as signal of channel shift durability.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA Breakthrough Therapy designation compresses review timelines for refractory disease candidates. |
| Manufacturing Scale-Up | Biologic infusion capacity expansion at dermatology clinics reduces hospital outpatient dependency. |
| Pipeline Diversification | Topical JAK inhibitors address unmet maintenance needs without systemic immunosuppression burden. |
| Strategic Partnership | Academic medical center integration expands specialist referral networks for moderate-to-severe cases. |
| Reimbursement Strategy | Patient-reported outcome integration reshapes NICE and CMS coverage determination frameworks. |
Research Methodology
Bottom-up patient volume modeling reconciled against top-down biologic shipment tracking forms the analytical core of this study. Primary interviews with dermatology practice administrators, payer formulary directors, regulatory affairs specialists at biopharma developers, and hospital procurement managers combined with secondary validation from FDA filings, EMA assessment reports, ClinicalTrials.gov protocols, and commercial formulary databases. Cross-referencing prescription audit data with infusion site certification records enables triangulation of actual administration volume against manufacturer-reported sales.
Historical trendline analysis of biologic adoption curves across immunology indications informs projection elasticity for HS-specific penetration rates. Segmentation modeling spans product type, treatment approach, administration route, disease severity staging, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated to prior authorization reform velocity and specialist workforce expansion data across United States, German, and United Kingdom markets.
Underlying measurement precision varies by segment; biologic volume and infusion site capacity carry tighter precision than topical formulation adoption in early-stage maintenance. Forecasts reflect assumptions regarding payer step-therapy duration requirements and biosimilar entry timing. Deviation in FDA review timeline acceleration or EMA PRIME scheme eligibility criteria would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Parathyroid Disorders Market
Specialty Medicine
Klinefelter Syndrome Treatment Market
Specialty Medicine
Vertebral Radiculopathy Market
Specialty Medicine
Tularemia Therapeutics Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market
Specialty Medicine
Global Myopia and Presbyopia Treatment Market
Specialty Medicine
Global Appendicitis Market
Specialty Medicine
Tropical Spastic Paraparesis Market
Specialty Medicine
Fatty Liver Treatment Market
Specialty Medicine
Europe Precision Medicine Market
Specialty Medicine
Blastomycosis Treatment Market
Specialty Medicine
Global Primary Immunodeficiency Therapeutics Market
Specialty Medicine
Global Allergy Vaccine Market
Specialty Medicine
Chronic Myelogenous Leukemia Treatment Market
Specialty Medicine
Sports Medicine Market
Specialty Medicine
Medical Foods for Orphan Diseases Market