
 Alcoholic Liver Diseases Treatment Market | 2026-2036
Alcoholic Liver Diseases Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Alcoholic Liver Diseases Treatment Market Analytics
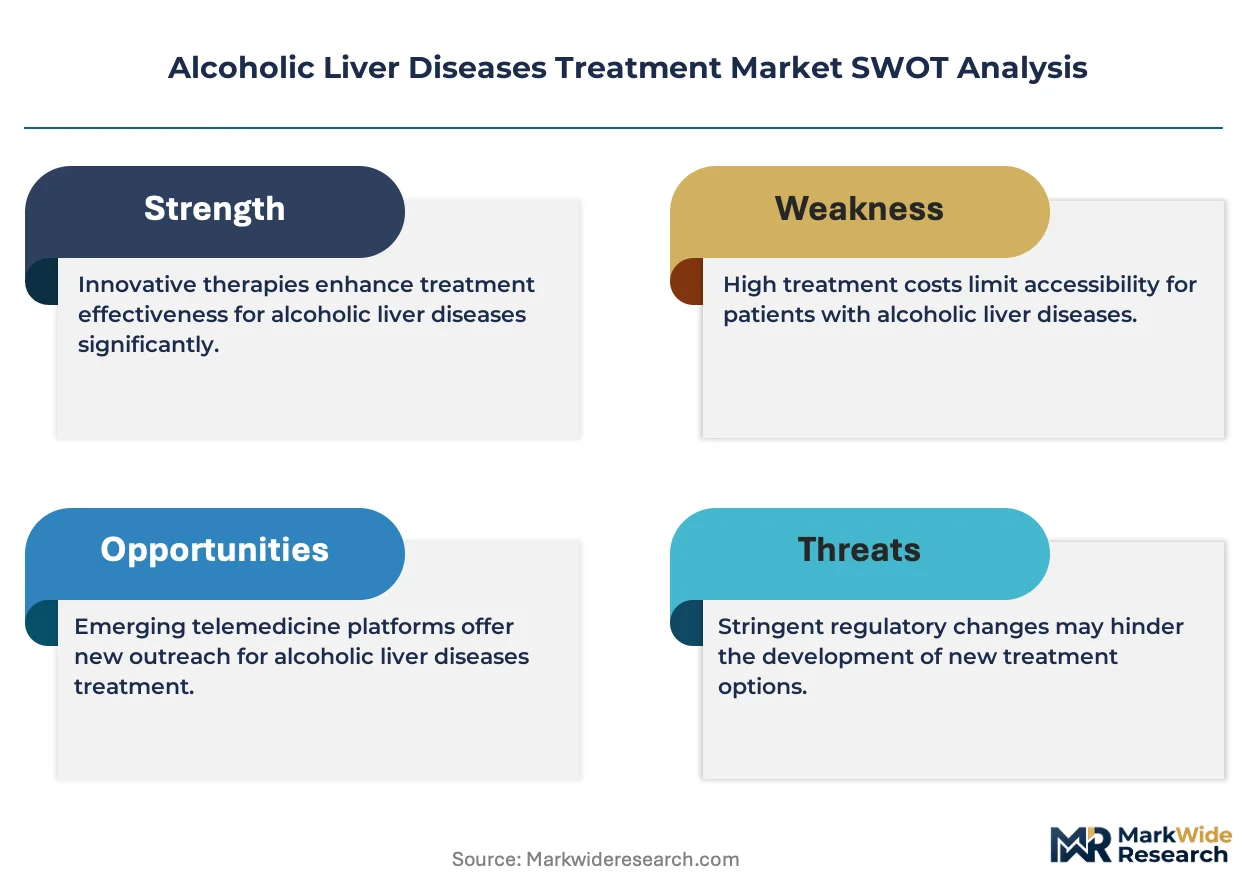
RNA-targeted therapeutics is tilting development pipelines away from traditional small-molecule approaches in alcoholic liver disease management. Gilead Sciences sustains one of the deepest hepatology portfolios through sustained investment in fibrosis-reversing modalities. Novartis AG competes on immunomodulatory mechanisms that address the inflammatory cascade driving ALD progression. Intercept Pharmaceuticals anchors its position in bile-acid pathway modulation, a niche that differentiates its clinical focus from broader metabolic rivals.
Alcoholic liver diseases treatment encompasses pharmacological interventions designed to halt or reverse alcohol-induced hepatic injury, ranging from corticosteroids for severe alcoholic hepatitis to biologics targeting tumor necrosis factor pathways and gut-liver axis modulators. These therapies aim to reduce mortality in acute-on-chronic liver failure and bridge patients to transplantation or sustained sobriety-based recovery. Biologics command attention as the fastest-expanding product category, driven by mechanistic specificity that corticosteroids cannot match. Hospitals remain the dominant end-user setting, absorbing high-acuity cases requiring intravenous administration and intensive monitoring that home care cannot replicate.
The FDA, EMA, and WHO collectively shape ALD therapy development through divergent evidentiary standards for liver-related endpoints and surrogate markers of clinical benefit. The FDA's breakthrough therapy designation streamlines access for novel biologics, while EMA's MDR-aligned post-market surveillance demands longer safety datasets for cirrhotic populations. Stakeholders must monitor how regulatory divergence across these jurisdictions influences trial design and commercial sequencing decisions for pipeline assets.
Market Dynamics
FDA breakthrough therapy designations for biologics targeting decompensated alcoholic hepatitis are compressing development timelines and forcing portfolio reallocation among hepatology-focused developers. This regulatory acceleration is restructuring competitive entry sequencing and reshaping capital deployment toward late-stage assets.
Growth Catalysts
- Specialty pharmacy networks:United States-based infusion centers now handle complex biologic administration for cirrhotic patients, expanding addressable patient populations beyond transplant centers.
- EMA MDR-aligned surveillance frameworks:Post-market safety datasets for cirrhotic populations are generating real-world evidence that supports label expansion into earlier disease stages.
- RNA-targeted platforms:Mechanistic specificity in fibrosis-reversing modalities is displacing corticosteroid protocols in severe alcoholic hepatitis treatment algorithms.
Market Restraints
- Biologic manufacturing concentration:Contract development and manufacturing organizations in Switzerland and Ireland control critical fill-finish capacity for parenteral ALD therapies, creating single-source vulnerability.
- Clinical endpoint heterogeneity:Divergent FDA and EMA evidentiary standards for liver-related surrogate markers force parallel trial designs that extend registration timelines by 18-24 months.
- Sobriety compliance requirements:Transplant listing criteria mandating six-month abstinence exclude substantial patient cohorts from biologic eligibility, constraining addressable markets.
Strategic Opportunities
- Japan's hepatology infrastructure:PMDA's orphan drug incentives for acute-on-chronic liver failure create favorable pricing corridors for breakthrough therapies in an aging demographic.
- Gut-liver axis modulation:Microbiome-targeted interventions combined with anti-inflammatory biologics represent unexploited mechanistic territory in ALD progression management.
- Home infusion channels:Subcutaneous formulation advances are enabling specialty pharmacy administration outside hospital settings, reducing cost per treatment episode.
Industry Challenges
- Hepatology trial recruitment:Competing studies for decompensated cirrhosis patients at major academic medical centers in the United States are extending enrollment timelines and inflating per-patient costs.
- Biomarker validation timelines:Liquid biopsy platforms for fibrosis staging lack standardized regulatory acceptance criteria, delaying surrogate endpoint qualification for accelerated approval pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alcoholic Liver Diseases Treatment Market |
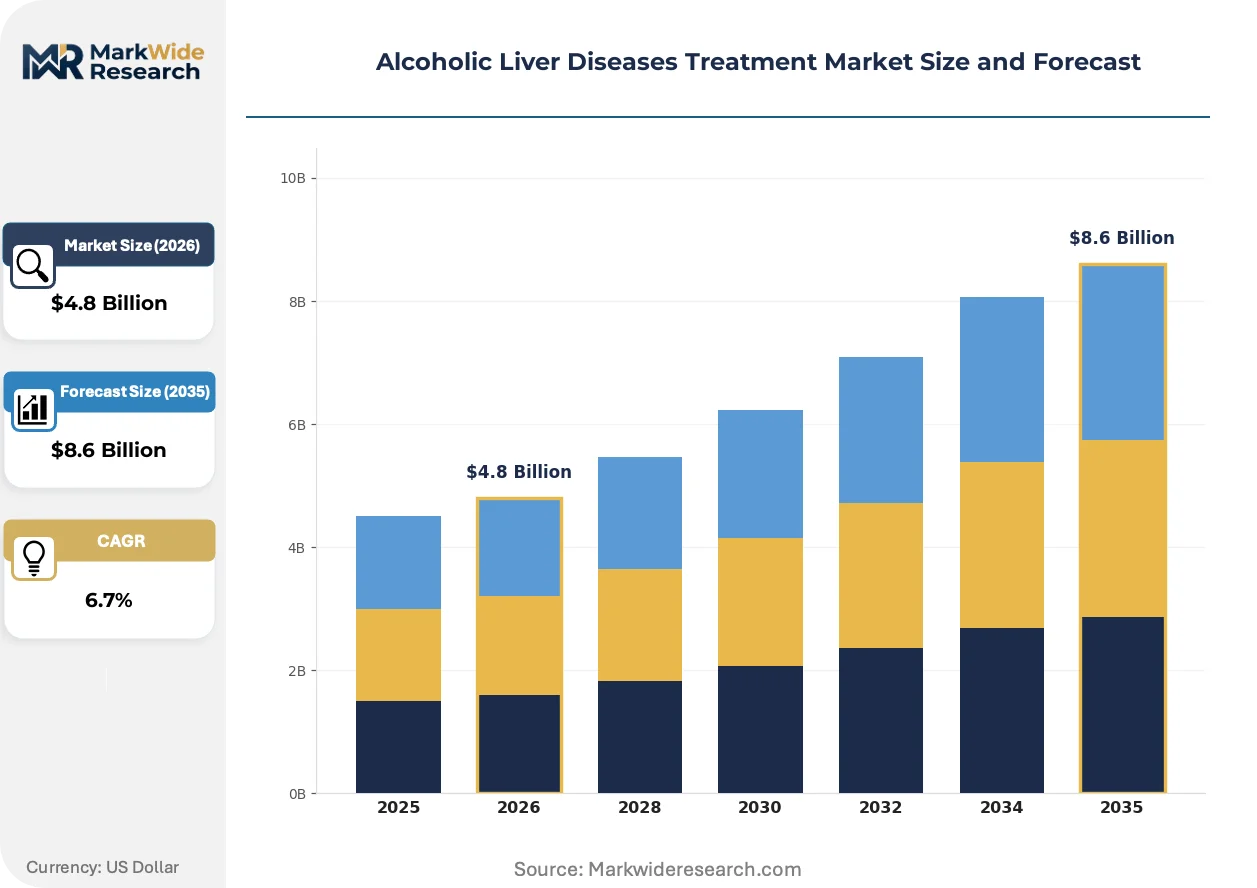
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antioxidants, Corticosteroids, Biologics, Antiviral Agents Administration Route: Oral, Intravenous, Topical, Subcutaneous End User: Hospitals, Clinics, Specialty Centers, Home Care Settings Distribution Channel: Pharmacies, Online Stores, Hospital Pharmacies, Drug Wholesalers |
| Companies Covered | Novartis AG, Gilead Sciences, DURECT Corporation, Johnson & Johnson, AbbVie, Intercept Pharmaceuticals, Sanofi, Pfizer Inc., GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alcoholic Liver Diseases Treatment Market Evolving Landscape
RNA interference platforms and non-invasive diagnostic convergence are dismantling traditional therapeutic hierarchies in alcoholic liver disease management. These shifts are compressing the interval between diagnosis and targeted intervention while redistributing value capture across the care continuum.
Small interfering RNA constructs targeting collagen deposition pathways are collapsing the efficacy gap between antifibrotic biologics and historical small-molecule approaches. Major transplant centers in the United States are integrating these modalities into bridge-to-transplant protocols. The technology is collapsing traditional staging-based treatment sequencing by enabling intervention at earlier fibrosis grades.
EMA's Medical Device Regulation alignment for companion diagnostics is mandating integrated biomarker-therapeutic development strategies. Liver stiffness measurement devices now require parallel clinical validation with drug candidates. European hepatology networks are responding by consolidating procurement around platform technologies that satisfy both diagnostic and therapeutic regulatory pathways.
Hospital systems are consolidating biologic purchasing through specialty pharmacy carve-outs that unbundle drug acquisition from infusion services. This procurement restructuring concentrates negotiating leverage among three national pharmacy benefit managers in the United States. The shift is most visible in academic medical centers where transplant volume determines formulary access for high-cost ALD therapies.
Alcoholic Liver Diseases Treatment Market Segmentation
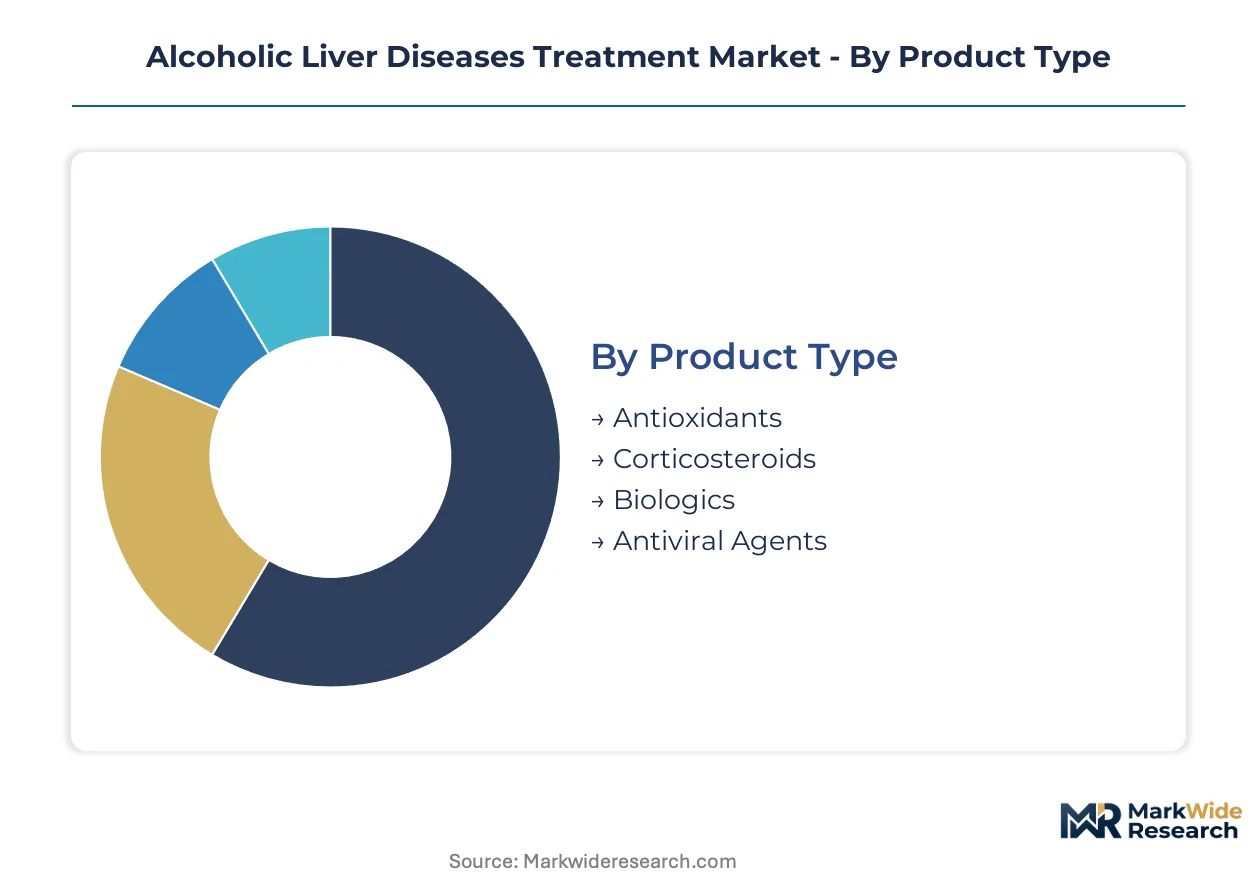
Segmentation in alcoholic liver disease therapeutics reveals how treatment complexity stratifies across clinical settings and patient acuity levels. Product innovation and administration convenience are redistributing value capture between hospital-based and outpatient care models.
Product Type:
Mature small-molecule categories coexist with emerging biologic platforms that command development investment and pricing premiums.
- Biologics:Monoclonal antibodies and recombinant proteins targeting TNF-alpha, IL-6, and gut-liver axis pathways deliver mechanistic precision unavailable to conventional immunosuppressants. Demand concentrates in United States transplant centers managing acute-on-chronic liver failure, driven by FDA breakthrough therapy designations that accelerate patient access.
- Corticosteroids:Prednisolone and methylprednisolone protocols remain the pharmacological backbone for severe alcoholic hepatitis despite infection risks and limited survival benefit in Maddrey discriminant function scores above 32. European hepatology networks in Germany and France still anchor first-line algorithms around these agents due to cost containment mandates.
- Antioxidants:N-acetylcysteine and vitamin E formulations address oxidative stress pathways in early-stage disease.
- Antiviral Agents:Direct-acting antivirals manage hepatitis C coinfection in alcoholic cirrhosis populations.
Corticosteroids retain volume leadership; biologics hold the steepest expansion curve.
Administration Route:
Route selection tracks disease severity progression and healthcare setting economics.
- Intravenous:Hospital-based infusion of biologics and high-dose corticosteroids serves decompensated patients with acute alcoholic hepatitis requiring intensive monitoring. United States specialty pharmacy networks in Boston and Houston are consolidating this channel through carve-out contracts with academic medical centers.
- Subcutaneous:Self-administered biologic formulations for maintenance therapy in compensated cirrhosis patients reduce treatment episode costs and enable home care migration. PMDA approvals in Japan are accelerating subcutaneous pipeline assets targeting aging populations with limited hospital access.
- Oral:First-line corticosteroid tapers and antioxidant protocols dominate outpatient management.
- Topical:Limited application for cutaneous manifestations of liver disease including pruritus management.
Oral administration retains volume leadership; subcutaneous delivery holds the steepest expansion curve.
End User:
Patient acuity and reimbursement complexity determine institutional capture of ALD therapy value.
- Hospitals:Academic medical centers with transplant designation absorb high-mortality acute alcoholic hepatitis cases requiring multidisciplinary hepatology, critical care, and addiction medicine coordination. Centers in Cleveland, Pittsburgh, and Los Angeles concentrate the most complex biologic administration due to hepatology fellowship training density.
- Specialty Centers:Dedicated liver disease clinics in London, Madrid, and Milan provide bridge-to-transplant care with integrated addiction psychiatry services. EMA MDR-aligned quality management systems at these sites generate real-world evidence supporting label expansion.
- Clinics:Community gastroenterology practices manage compensated cirrhosis surveillance and early fibrosis intervention.
- Home Care Settings:Emerging channel for stable patients on oral maintenance protocols or trained subcutaneous biologic self-administration.
Hospitals retain volume leadership; specialty centers hold the steepest expansion curve.
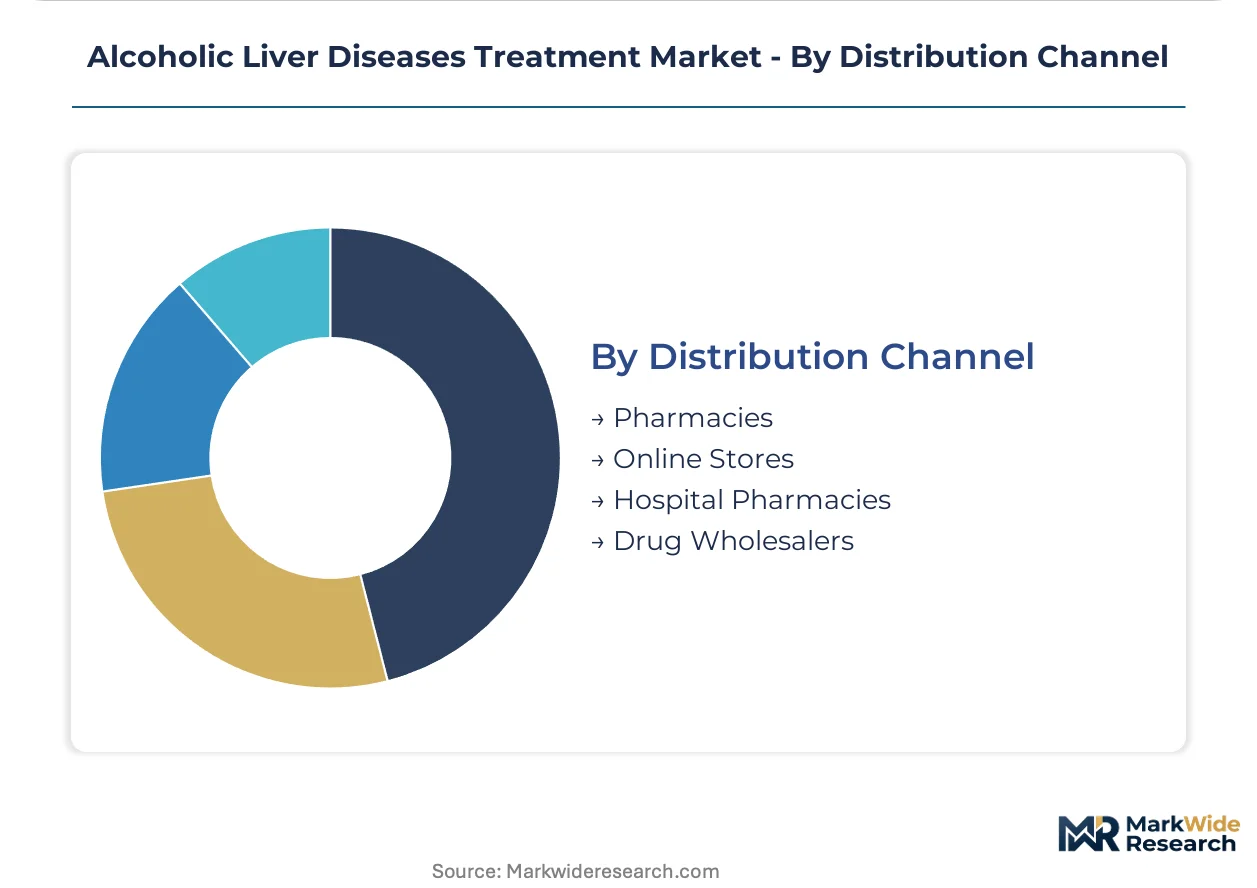
Distribution Channel:
Channel structure reflects the tension between biologic cold-chain requirements and cost containment pressures.
- Hospital Pharmacies:Captive distribution within transplant centers ensures controlled handling of temperature-sensitive biologics and supports 340B pricing for eligible patient populations. United States health systems in California and Texas are consolidating procurement through centralized hospital pharmacy networks.
- Drug Wholesalers:McKesson, AmerisourceBergen, and Cardinal Health control corticosteroid and antioxidant flow to retail and institutional channels, with distribution hubs in Illinois and Pennsylvania serving national demand.
- Pharmacies:Retail and specialty pharmacy locations handle oral maintenance therapies and patient education.
- Online Stores:Limited to over-the-counter supplements and patient support materials rather than prescription therapeutics.
Hospital pharmacies retain volume leadership; drug wholesalers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based specialty pharmacy networks export biologic administration protocols to transplant centers in Germany and Japan, establishing transnational standards for decompensated alcoholic hepatitis management.
United States
FDA breakthrough therapy designations accelerate patient access to novel biologics at Cleveland Clinic and UCLA Medical Center transplant programs. The 340B drug pricing program enables safety-net hospitals to acquire high-cost therapies at reduced rates. Hepatology fellowship density in Pittsburgh and Houston concentrates clinical trial recruitment for acute-on-chronic liver failure interventions.
Germany
EMA MDR-aligned post-market surveillance generates real-world evidence supporting label expansion for fibrosis-reversing modalities. Cost containment mandates at statutory health insurers maintain corticosteroid protocols as first-line therapy despite biologic efficacy advantages. Frankfurt and Munich academic medical centers coordinate multicenter hepatology networks across Baden-Württemberg and Bavaria.
Japan
PMDA orphan drug incentives create favorable pricing corridors for breakthrough therapies targeting acute-on-chronic liver failure in aging demographics. Subcutaneous formulation approvals accelerate home care migration for compensated cirrhosis patients. Tokyo and Osaka transplant centers integrate RNA-targeted platforms into bridge-to-transplant protocols.
Switzerland
Swissmedic regulatory frameworks attract contract development and manufacturing organizations controlling critical fill-finish capacity for parenteral biologics. Basel and Zurich clusters concentrate pharmaceutical production infrastructure serving European and Asian markets. The country's biologic manufacturing concentration creates single-source vulnerability for global ALD therapy supply.
United Kingdom
NICE technology appraisals determine National Health Service reimbursement for biologics in severe alcoholic hepatitis treatment algorithms. London and Birmingham liver disease clinics provide integrated addiction psychiatry services alongside hepatology care. Post-Brexit regulatory divergence from EMA standards extends registration timelines for pipeline assets seeking UK market access.
Alcoholic Liver Diseases Treatment Market Competitive Landscape
On the supply side, the industry is consolidating around hepatology-focused developers with sustained investment in fibrosis-reversing modalities and immunomodulatory mechanisms. Large-cap pharmaceutical companies anchor the premium tier through diversified therapeutic portfolios, while mid-cap specialists concentrate on RNA-targeted platforms and bile-acid pathway modulation. Competitive moves center on strategic partnerships for gut-liver axis research and geographic expansion into Japan's orphan drug corridors.
Within the large-cap diversified tier, Novartis AG and Gilead Sciences occupy positions exemplifying contrasting mechanistic approaches—immunomodulatory versus fibrosis-targeting. Intercept Pharmaceuticals sits within the specialization archetype, anchoring its market presence through differentiated focus on bile-acid pathway modulation rather than broader metabolic competition.
| Leading Market Players |
|---|
| Novartis AG |
| Gilead Sciences |
| DURECT Corporation |
| Johnson & Johnson |
| AbbVie |
| Intercept Pharmaceuticals |
| Sanofi |
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Others |
Value Network & Pricing Analysis
Swiss and Irish contract manufacturing clusters control critical fill-finish capacity for parenteral biologics, concentrating margin capture upstream while United States transplant centers and specialty pharmacy networks compete for downstream value in high-acuity ALD therapy administration.
Pricing Analysis
Next-generation RNA-targeted therapeutics command substantial premiums over corticosteroid protocols, while small-molecule antioxidants occupy economy positioning. Three-tier pricing structure across breakthrough biologics, established immunomodulators, and generic corticosteroids reflects mechanistic differentiation and regulatory exclusivity. Pricing pressure stems from 340B program utilization at safety-net hospitals acquiring biologics at reduced rates. Community gastroenterology practices exhibit highest price sensitivity; academic transplant centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
United States export controls on dual-use biomanufacturing equipment constrain technology transfer to contract development organizations in Switzerland and Ireland. Active pharmaceutical ingredient production draws from China and India, while fill-finish operations concentrate in Switzerland, Ireland, and the United States. Single-source vulnerability pervades cold-chain biologic handling capacity. Distribution runs through hospital pharmacy carve-outs and specialty pharmacy networks serving transplant centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of hepatology-trained clinical investigators and validated fibrosis biomarker platforms constrains pipeline velocity, creating asymmetric returns for organizations that secure these capabilities ahead of competitor entry.
For Market Incumbents: Harden biologic manufacturing resilience through captive fill-finish capacity or multi-source CDMO contracts to mitigate Swiss-Irish concentration risk. Deepen hepatology fellowship partnerships at Cleveland Clinic, UCLA, and Houston Methodist to secure clinical trial recruitment priority against emerging RNA-platform competitors. Lock in specialty pharmacy carve-out contracts before national PBM consolidation accelerates. For New Entrants and Emerging Players: Pursue Japan's orphan drug corridor through PMDA subcutaneous formulation pathways, where aging demographics and limited hospital access create favorable pricing corridors. Target home infusion channels for compensated cirrhosis maintenance therapy as the most penetrable segment bypassing transplant center gatekeepers. Lead with gut-liver axis modulation mechanisms to differentiate from crowded TNF-alpha and IL-6 competitive sets. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with validated RNA interference platforms and existing FDA breakthrough therapy designations, positioned for near-term regulatory inflection. Long-term viability hinges on bridging fibrosis-reversing modalities to commercial scale before corticosteroid protocols fully commoditize. Watch for EMA MDR-aligned post-market surveillance data releases as signals of label expansion potential and competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| RNA Platform Scale-Up | CDMO partnerships in Basel and Dublin secure fill-finish capacity for parenteral biologics ahead of competitor lock-in. |
| Breakthrough Therapy Designation | FDA accelerated pathway compresses development timelines for decompensated alcoholic hepatitis candidates at major transplant centers. |
| Specialty Pharmacy Carve-Out | Direct contracts with Houston and Boston infusion centers bypass PBM intermediaries and capture margin. |
| PMDA Orphan Drug Filing | Japan's pricing corridors for acute-on-chronic liver failure reward subcutaneous formulation innovation. |
| Gut-Liver Axis Partnership | Microbiome research alliances with European hepatology networks unlock mechanistic differentiation from TNF-alpha competitors. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, formulary directors at United States transplant centers, and payer access specialists; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient-flow modeling and top-down therapeutic class sizing were triangulated against manufacturer-reported pipeline advancement milestones.
Forecast inputs considered treatment line progression, administration route migration, patient population stratification by fibrosis stage, and regional regulatory clustering across FDA, EMA, PMDA, and Swissmedic jurisdictions. CAGRs were derived from segment-level growth rate synthesis across the projection horizon, incorporating RNA-platform penetration assumptions and corticosteroid protocol displacement curves specific to severe alcoholic hepatitis management.
Sensitivities concentrate around breakthrough therapy designation grant rates, EMA MDR-aligned surveillance timeline extensions, and PMDA orphan drug pricing corridor durability. Forecasts reflect assumptions regarding biologic manufacturing capacity expansion and hepatology trial recruitment velocity. Material shifts in FDA evidentiary standards for fibrosis surrogate endpoints or Swissmedic export control enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Pulmonary Arterial Hypertension (PAH) Market
Specialty Medicine
Rosacea Therapeutics Market
Specialty Medicine
Global Overactive Bladder Treatment Market
Specialty Medicine
Global Addison's Disease Treatment Market
Specialty Medicine
Global Acquired Aplastic Anemia Market
Specialty Medicine
Sporothrix Schenckii Infection Treatment Market
Specialty Medicine
Global Stroke Therapeutics Market
Specialty Medicine
Europe Precision Medicine Market
Specialty Medicine
United States Sports Medicine Market
Specialty Medicine
Barotrauma Market
Specialty Medicine
Enzyme Replacement Therapy Market
Specialty Medicine
Behcet's Syndrome Market
Specialty Medicine
Polyarticular Juvenile Idiopathic Market
Specialty Medicine
North America Gastric Cancer Market
Specialty Medicine
Hypertrophic Cardiomyopathy (HCM) Therapeutics Market
Specialty Medicine
Japan Idiopathic Pulmonary Fibrosis Treatment Market