
 Cystic Fibrosis Therapeutics Market | 2026-2036
Cystic Fibrosis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Cystic Fibrosis Therapeutics Market Analysis
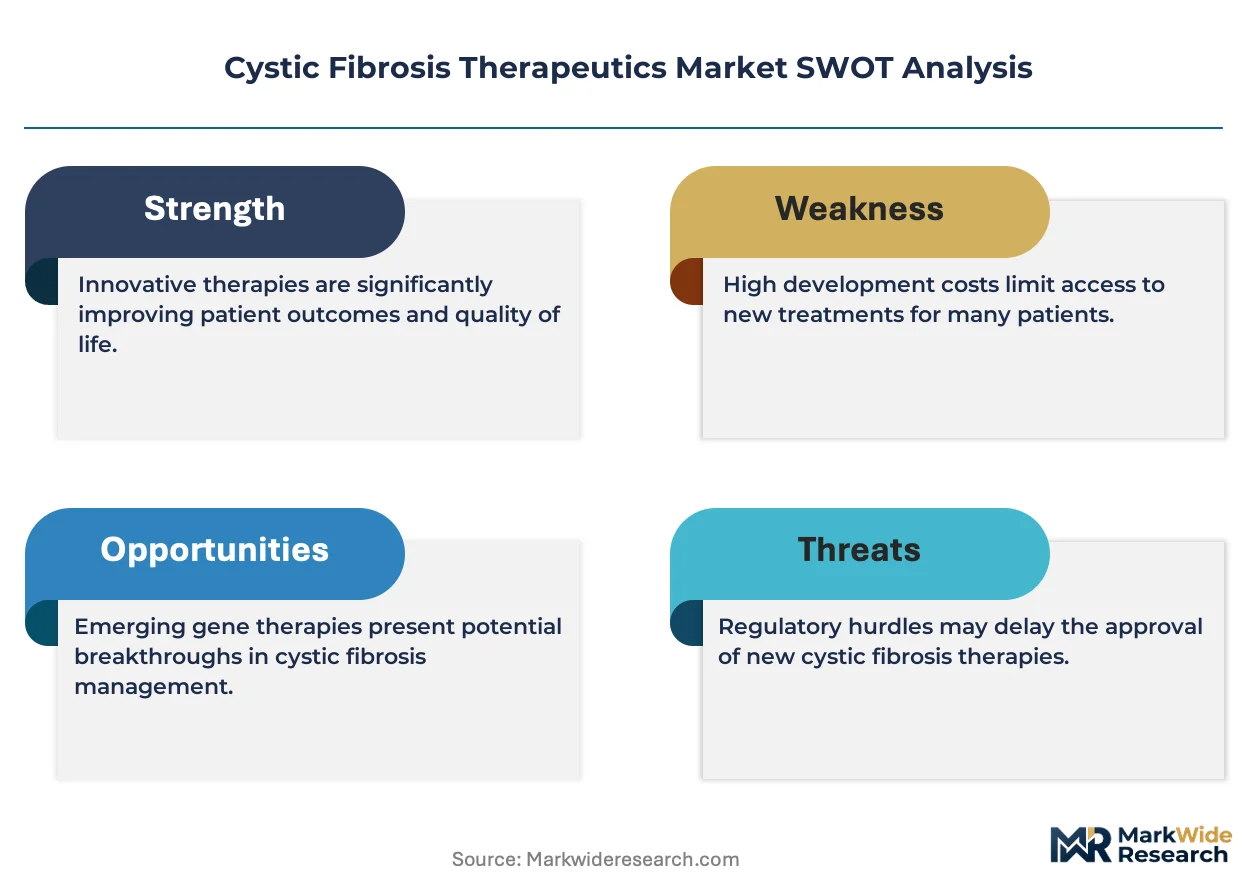
Specialty pharmacy distribution is reshaping how cystic fibrosis therapeutics reach patients, with hub services and patient-assistance programs now central to product access. Vertex Pharmaceuticals leverages its CFTR portfolio dominance across multiple mutation classes. AbbVie competes through antibiotic combinations targeting resistant Pseudomonas infections in hospitalized patients. Gilead Sciences anchors its position in antiviral prophylaxis for CF populations vulnerable to respiratory viral infections.
Cystic fibrosis therapeutics comprise pharmacological agents designed to correct defective CFTR protein function, clear mucus obstruction, combat chronic infection, and manage systemic complications of this autosomal recessive disorder. These formulations range from small-molecule correctors and potentiators targeting specific CFTR mutations to inhaled enzyme therapies and nebulized antibiotics, with efficacy measured by forced expiratory volume and pulmonary exacerbation frequency. Inhalation delivery mode dominates clinical practice due to direct airway targeting, though oral CFTR modulators command the largest margin pools through chronic daily dosing. Pediatric patients represent the fastest-growing end-user segment as newborn screening expands and early intervention protocols harden, while hospital settings concentrate acute antibiotic and mucolytic demand.
The FDA structures approval pathways through Breakthrough Therapy and Orphan Drug designations, while the EMA applies similar incentives under its orphan medicinal products framework, both accelerating development timelines for mutation-specific therapies. Reimbursement negotiations with national health technology assessment bodies determine market access velocity across European markets. Stakeholders must monitor emerging gene-editing regulatory classifications and payer evidence requirements for single-administration curative interventions.
Market Dynamics
CFTR modulator pipeline maturation is restructuring competitive positioning, with mutation-agnostic therapies threatening to obsolete existing genotype-limited portfolios and forcing incumbent developers to accelerate next-generation corrector combinations.
Growth Catalysts
- Expanded newborn screening mandates:State-level universal screening protocols in the United States and comparable national programs across European Union member states are enlarging the addressable patient pool before irreversible pulmonary damage occurs.
- EMA orphan medicinal products framework:Accelerated review timelines and market exclusivity provisions reduce regulatory friction for mutation-specific therapies entering European markets.
- Specialty pharmacy hub services:Integrated patient-assistance and adherence monitoring infrastructure is compressing time-to-therapy initiation and reducing prescription abandonment rates.
Market Restraints
- Active pharmaceutical ingredient concentration:Synthesis of complex heterocyclic CFTR modulator cores depends on a limited supplier base concentrated in coastal China and the Swiss-German chemical corridor.
- Biomarker validation bottlenecks:Sweat chloride testing infrastructure gaps in rural and underserved regions create diagnostic access inequities that limit addressable demand.
- Orphan drug pricing scrutiny:National health technology assessment bodies in Germany, France, and the United Kingdom are tightening incremental cost-effectiveness ratio thresholds for single-mutation therapies.
Strategic Opportunities
- Gene-editing regulatory tailwinds:The FDA's emerging framework for in vivo CRISPR therapeutics creates a pathway for single-administration curative interventions that would displace chronic small-molecule regimens.
- Antibiotic stewardship protocols:Hospital formulary shifts toward narrow-spectrum inhaled agents present white space for developers targeting multidrug-resistant Pseudomonas aeruginosa.
- Pediatric early intervention:Presymptomatic treatment initiation in infants identified through expanded screening is creating a new clinical segment with distinct efficacy endpoints and pricing dynamics.
Industry Challenges
- CFTR protein structural biology expertise:The specialized skill set required for high-throughput screening of mutation-specific correctors remains concentrated among a small cohort of academic and industrial research groups.
- Combination therapy patent thickets:Overlapping intellectual property claims on corrector-potentiator pairings complicate freedom-to-operate analyses and licensing negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cystic Fibrosis Therapeutics Market |
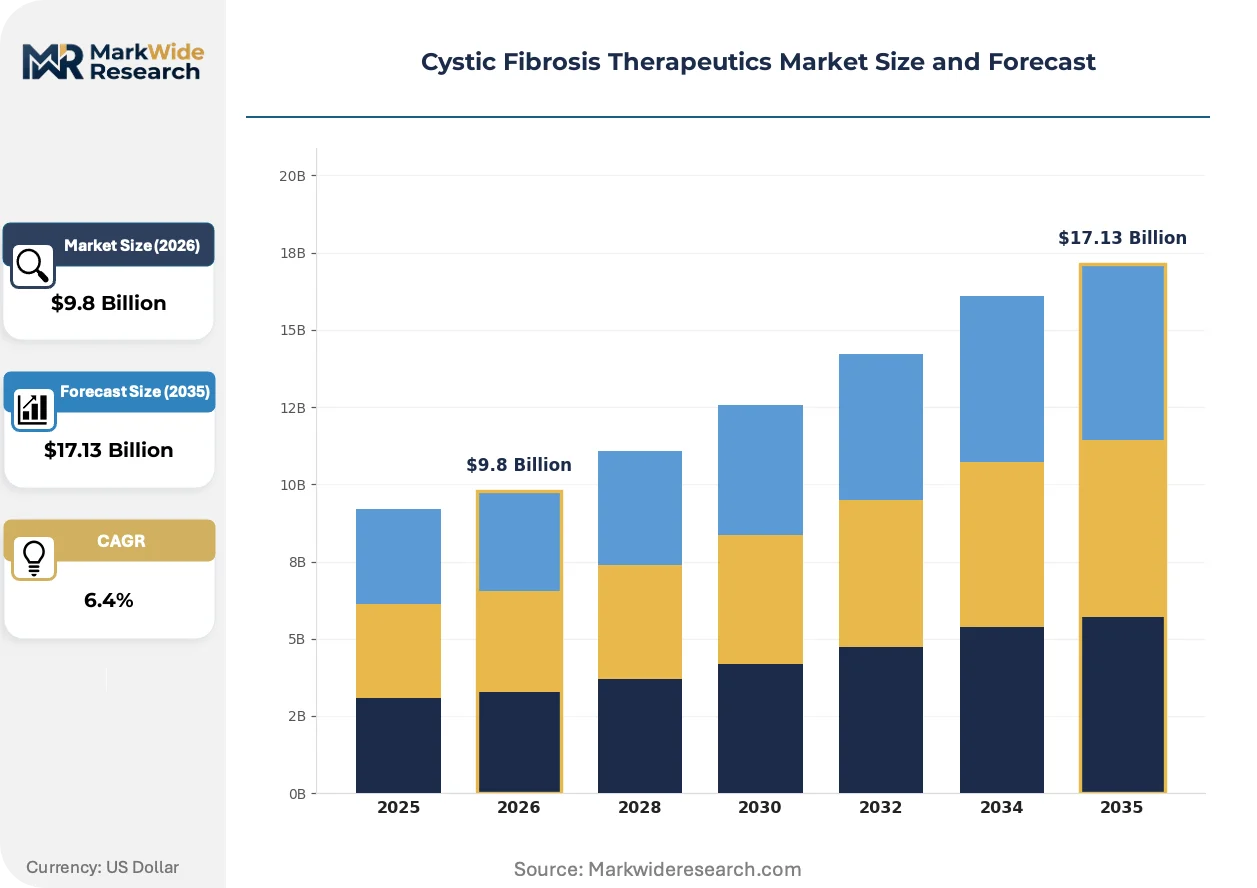
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Replacement Therapy, Antiviral Agents, Antibiotics, Mucolytics Delivery Mode: Inhalation, Oral, Intravenous, Topical End User: Pediatric Patients, Adult Patients, Hospitals, Clinics Formulation: Syrup, Capsule, Powder, Injectable |
| Companies Covered | Vertex Pharmaceuticals, AbbVie, Gilead Sciences, Novartis AG, F. Hoffmann-La Roche Ltd, Teva Pharmaceutical Industries Ltd, AstraZeneca, Sionna Therapeutics, ReCode Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cystic Fibrosis Therapeutics Market Emerging Trajectories
Next-generation sequencing integration and inhaled delivery platform advances are compressing development timelines and expanding addressable mutation classes beyond the most common variants.
Next-generation CFTR correctors incorporating deuterium substitution and allosteric binding optimization are collapsing the efficacy gap between homozygous and heterozygous F508del patients. Adult treatment centers in the United States and Germany are adopting these agents as first-line therapy. The technology is collapsing historical segmentation between mutation-class markets and creating pressure for portfolio breadth over depth.
The FDA's Breakthrough Therapy designation pathway is compressing Phase II-to-approval timelines for novel corrector mechanisms by permitting surrogate endpoint acceptance and rolling review. This regulatory flexibility is accelerating competitive entry for second-generation modulators. Small-cap developers with single-asset pipelines are leveraging this framework to challenge established portfolios.
Hospital procurement committees are consolidating antibiotic purchasing through centralized formulary management and therapeutic interchange protocols. Specialty pharmacy distribution for outpatient CFTR modulators is displacing traditional retail channels in the United States. This channel consolidation is most pronounced in integrated delivery networks across California, Texas, and the Northeast corridor.
Cystic Fibrosis Therapeutics Market Segmentation
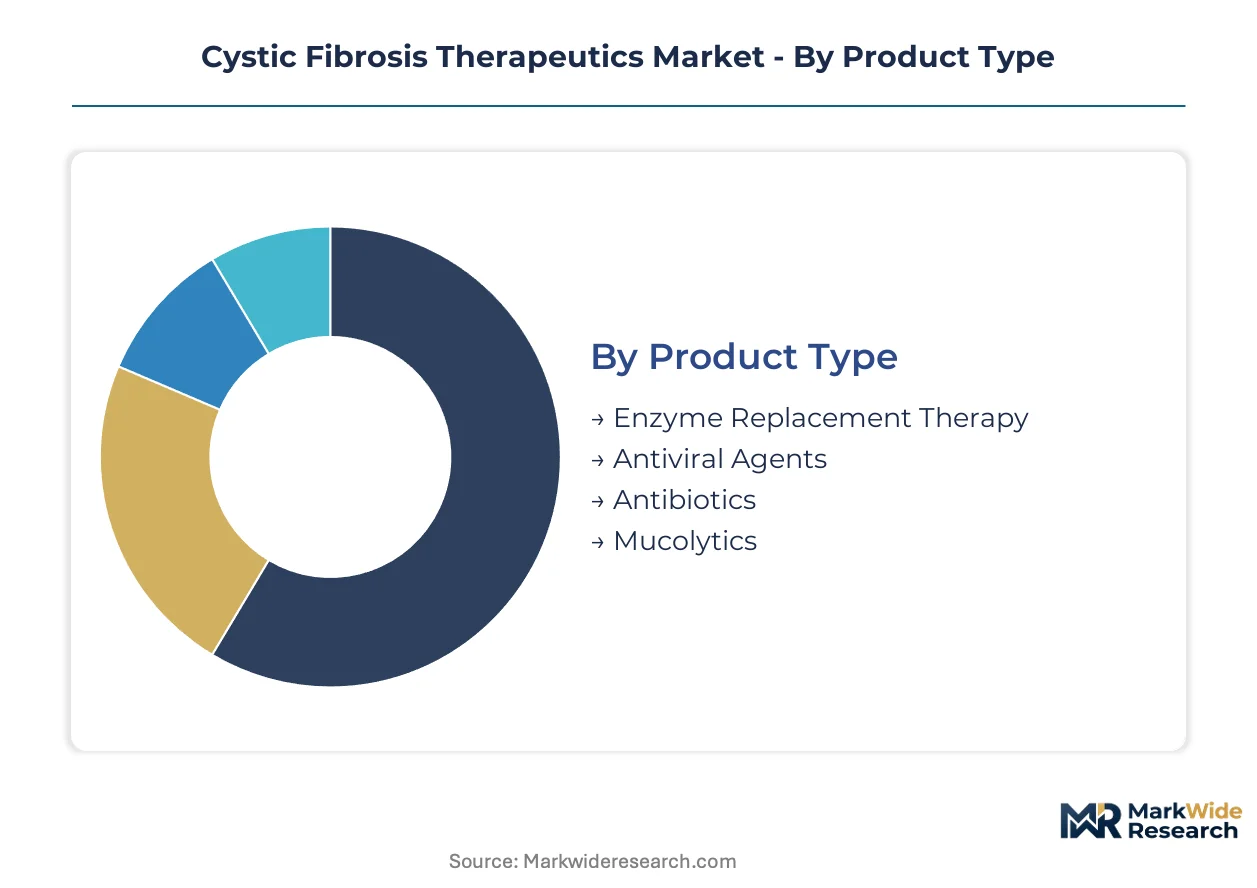
Mutation-specific efficacy profiles and delivery infrastructure requirements fragment cystic fibrosis therapeutics into distinct commercial segments. Each dimension carries unique reimbursement codes, distribution protocols, and prescriber specialization patterns that determine go-to-market economics.
Product Type:
Cost tier stratification separates chronic maintenance therapies from acute rescue interventions, with pricing power concentrated in mutation-targeted small molecules versus commoditized antibiotics.
- Enzyme Replacement Therapy:Recombinant pancreatic enzymes address malabsorption in pancreatic-insufficient patients. Demand concentrates in pediatric gastroenterology practices across the United States, where nutritional failure protocols mandate early initiation.
- Antiviral Agents:Neuraminidase inhibitors and emerging RSV prophylaxis target viral exacerbation prevention in lung-transplant candidates. United States transplant centers in Pittsburgh, Houston, and Cleveland drive procurement volume through seasonal prophylaxis protocols.
- Antibiotics:Inhaled tobramycin and aztreonam lysine suppress chronic Pseudomonas colonization.
- Mucolytics:Dornase alfa and hypertonic saline solutions cleave extracellular DNA in airway secretions.
Enzyme replacement holds installed capacity. Antiviral agents are rotating up the share rankings.
Delivery Mode:
Application context determines route selection, with outpatient adherence patterns favoring oral administration while acute exacerbations require intravenous escalation.
- Inhalation:Nebulized and dry-powder devices deliver agents directly to bronchial epithelium, maximizing local concentration while minimizing systemic exposure. Adult treatment centers in Germany and the United States standardize compressor-based nebulization for mucolytic and antibiotic administration.
- Oral:CFTR modulators in tablet and granule formulations enable chronic daily dosing outside clinical settings. Specialty pharmacy networks across California, Texas, and Florida manage distribution through hub-and-spoke models with embedded adherence monitoring.
- Intravenous:Reserved for refractory pulmonary exacerbations requiring hospital admission.
- Topical:Limited to sinus disease and cutaneous manifestations of CF.
Inhalation delivery holds installed capacity. Oral administration is rotating up the share rankings.
End User:
Customer type segmentation reflects divergent clinical protocols, with pediatric early intervention creating distinct efficacy endpoints and pricing dynamics versus adult maintenance regimens.
- Pediatric Patients:Newborn screening expansion identifies presymptomatic infants, enabling CFTR modulator initiation before irreversible bronchiectasis develops. United States state Medicaid programs and European national health services in France, Germany, and the United Kingdom increasingly cover mutation-agnostic therapy for this segment.
- Adult Patients:Established disease burden drives combination therapy complexity and transplant evaluation referrals. United States academic medical centers in Boston, Philadelphia, and Seattle anchor specialist care networks managing this population.
- Hospitals:Concentrate intravenous antibiotic and intensive care demand.
- Clinics:Outpatient settings handle stable maintenance therapy monitoring.
Adult patients hold installed capacity. Pediatric patients are climbing the fastest.
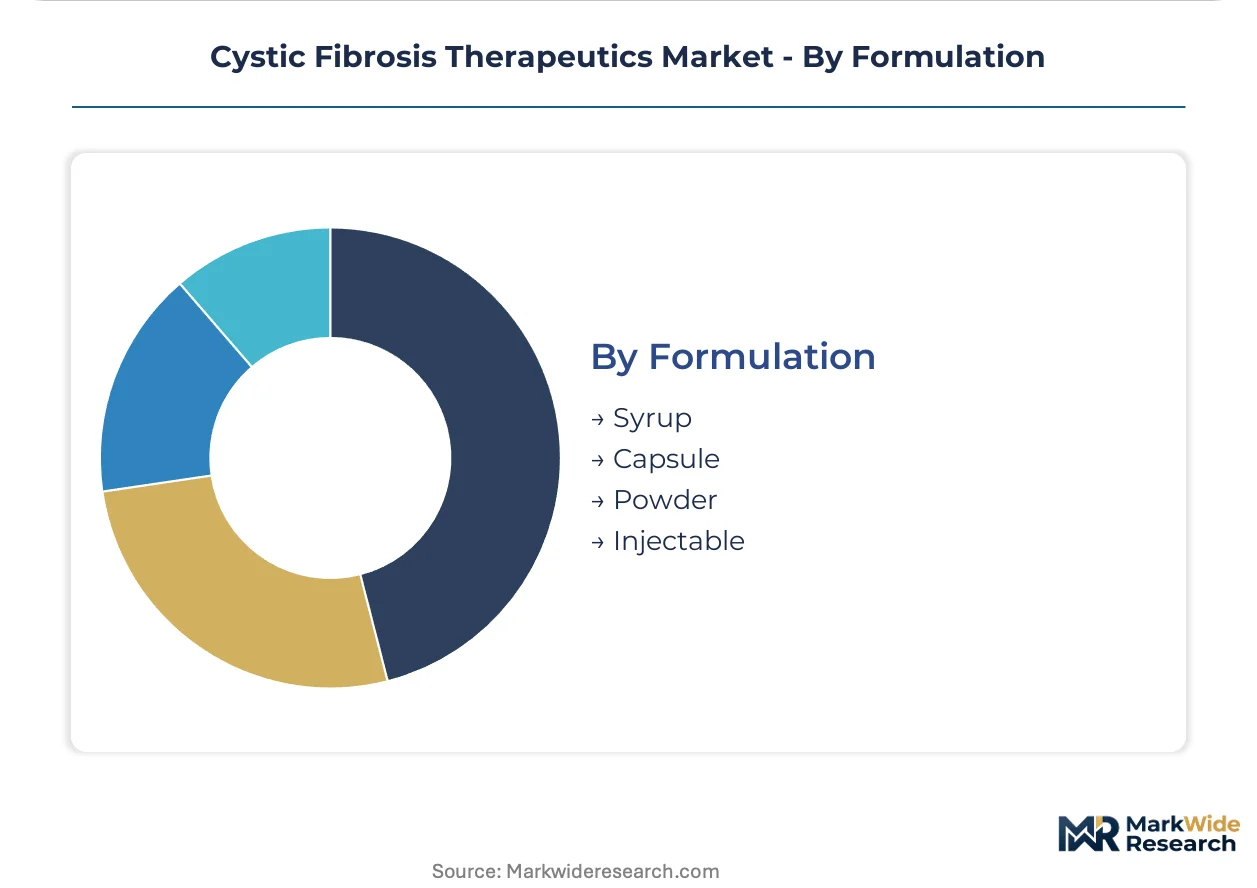
Formulation:
Supply concentration in active pharmaceutical ingredient synthesis and finished dose manufacturing shapes availability across dosage forms, with powder inhalation devices requiring specialized fill-finish capabilities.
- Syrup:Liquid formulations enable dose titration in infants and patients with swallowing dysfunction. European hospital pharmacies in Paris, London, and Milan compound or procure these preparations for nasogastric administration.
- Capsule:Hard gelatin and HPMC capsules protect acid-labile enzymes and deliver precise CFTR modulator doses. United States specialty pharmacies dispense these through mail-order channels with temperature-controlled logistics.
- Powder:Dry-powder inhalers require sophisticated particle engineering for lung deposition.
- Injectable:Intravenous antibiotics and biologics demand aseptic manufacturing.
Capsule formulation holds installed capacity. Powder delivery is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in cystic fibrosis therapeutics concentrates in the United States while European markets extract steeper discounts through health technology assessment negotiations. Germany and France secure substantial rebates on CFTR modulators through IQWiG and HAS evaluations. Emerging markets remain peripheral due to diagnostic infrastructure gaps and limited reimbursement for orphan-priced biologics.
United States
Specialist care networks in Boston, Philadelphia, and Seattle anchor the world's largest CF patient management infrastructure. The FDA's Breakthrough Therapy designation pathway accelerates approval timelines for novel correctors, enabling rapid commercialization of mutation-agnostic candidates. Vertex Pharmaceuticals dominates outpatient prescribing through specialty pharmacy hubs concentrated in California, Texas, and Florida.
Germany
Academic medical centers in Munich and Heidelberg drive adoption of next-generation CFTR modulators through early-access programs. IQWiG assessments impose stringent incremental cost-effectiveness thresholds that compress net pricing for single-mutation therapies. The country's chemical corridor around Basel and Ludwigshafen supplies active pharmaceutical ingredients for heterocyclic modulator synthesis.
United Kingdom
NHS England's specialized commissioning framework centralizes CF care in London, Manchester, and Birmingham treatment centers. NICE technology appraisals have historically restricted access to premium CFTR modulators pending outcome-based pricing agreements. Scottish newborn screening expansion in Glasgow and Edinburgh clinics is enlarging the pediatric presymptomatic treatment pool.
France
Parisian hospital pharmacies compound liquid enzyme formulations for nasogastric administration in pediatric patients. HAS evaluations apply differential pricing pressure based on clinical benefit ratings, with ASMR scores determining reimbursement levels. The Lyon-Grenoble corridor hosts contract manufacturing organizations supporting European fill-finish capacity for inhaled powder devices.
Switzerland
Swissmedic's accelerated access pathway benefits Basel-area biotech clusters developing gene-editing candidates. The country's pricing negotiation framework references German and French benchmarks while permitting earlier patient access. Zurich and Geneva treatment centers participate in multinational clinical trials for CRISPR-based curative interventions.
Cystic Fibrosis Therapeutics Market Vendor Landscape
CFTR portfolio specialists and diversified antibiotic developers split the market between chronic maintenance and acute rescue segments. The competitive structure tilts toward consolidation in oral modulators while fragmenting across inhaled anti-infectives. Three archetypes dominate: mutation-specific corrector developers, broad-spectrum antibiotic manufacturers, and gene-editing platform builders. Incumbent players defend position through next-generation combination patenting while challengers pursue regulatory arbitrage via Breakthrough Therapy designation.
Within the CFTR modulator tier, Vertex Pharmaceuticals exemplifies portfolio breadth across mutation classes. AbbVie and Gilead Sciences occupy positions in adjacent therapeutic vectors targeting resistant infection and viral prophylaxis respectively. Novartis AG and Roche represent European-based diversified pharmaceutical conglomerates with historical presence in respiratory and orphan disease portfolios.
| Leading Market Players |
|---|
| Vertex Pharmaceuticals |
| AbbVie |
| Gilead Sciences |
| Novartis AG |
| F. Hoffmann-La Roche Ltd |
| Teva Pharmaceutical Industries Ltd |
| AstraZeneca |
| Sionna Therapeutics |
| ReCode Therapeutics |
| Others |
Supply Flow & Price Mechanics
Coastal China and the Swiss-German chemical corridor concentrate heterocyclic CFTR modulator synthesis, anchoring margin capture in oral corrector portfolios while compressing pricing flexibility for inhaled antibiotics facing therapeutic interchange protocols. Specialty pharmacy hub services in California, Texas, and Florida extract service fees that redistribute value from manufacturers to distribution intermediaries.
Pricing Analysis
Configured-to-order pricing for mutation-specific CFTR modulators commands substantial premiums over standard antibiotic regimens. Three-tier pricing structure across premium, standard, and economy levels stratifies by CFTR mutation class and prescriber specialization, with FDA Breakthrough Therapy designation conferring additional pricing leverage. Cost compression in the inhaled antibiotic tier is intensifying because hospital formulary consolidation favors narrow-spectrum agents. Pediatric patients identified through newborn screening exhibit lowest price sensitivity due to Medicaid coverage mandates, while adult maintenance patients in high-deductible plans face greatest out-of-pocket exposure.
Supply Chain Analysis
Upstream feedstock for heterocyclic modulator cores draws from specialized chemical manufacturers concentrated in China, Switzerland, and Germany. Active pharmaceutical ingredient synthesis rests on fluorinated intermediates and chiral catalysts sourced through long-term offtake agreements. Single-source vulnerability in coastal Chinese suppliers creates exposure to regulatory inspection delays and environmental compliance shutdowns. Distribution runs through specialty pharmacy networks with temperature-controlled logistics and embedded patient-assistance infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through FDA Breakthrough Therapy and EMA orphan designation creates durable barriers against generic substitution.
For Market Incumbents: Entrench portfolio breadth across mutation classes rather than depth within single genotypes, as next-generation correctors threaten to obsolete genotype-limited franchises. Accelerate backward integration into heterocyclic API synthesis to reduce dependence on coastal Chinese suppliers facing environmental compliance scrutiny. Patent thicket construction around corrector-potentiator combinations remains essential as freedom-to-operate disputes intensify. For New Entrants and Emerging Players: Pursue regulatory arbitrage via Breakthrough Therapy designation for mutation-agnostic mechanisms that collapse efficacy gaps between homozygous and heterozygous patients. Pediatric early intervention represents the most penetrable segment, with presymptomatic treatment protocols creating distinct efficacy endpoints and pricing dynamics. Gene-editing platform differentiation offers the clearest go-to-market angle against entrenched small-molecule portfolios. For Investors and Strategic Acquirers: Capital is best deployed toward platform-stage gene-editing developers with Swissmedic or FDA pre-IND engagement rather than single-asset corrector candidates facing combination therapy patent thickets. Long-term viability across the projection horizon hinges on curative intervention displacement of chronic regimens. The signal to watch is reimbursement precedent for single-administration CRISPR therapies in European health technology assessment proceedings.| Strategic Initiative | Industry Significance |
|---|---|
| Gene-Editing Regulatory Pathway Advancement | FDA's emerging CRISPR framework accelerates single-administration curative candidates toward approval. |
| Next-Generation CFTR Corrector Combination | Deuterium substitution and allosteric optimization collapse efficacy gaps across mutation classes. |
| Specialty Pharmacy Hub Service Expansion | Integrated adherence monitoring in California, Texas, and Florida compresses time-to-therapy initiation. |
| Antibiotic Stewardship Protocol Alignment | Narrow-spectrum inhaled agents targeting multidrug-resistant Pseudomonas secure hospital formulary placement. |
| Pediatric Early Intervention Protocol Development | Presymptomatic treatment in infants identified through expanded screening creates new clinical segments. |
Methodological Framework
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and payer access specialists converged on the working assumptions underpinning this analysis. Primary interviews with hospital procurement managers and specialty pharmacy network operators were cross-validated against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation were reconciled across the analysis window.
Demand-supply-balance framing anchored the forecast framework, with segmentation across treatment line, dosage form, administration route, and patient population modeled throughout the projection horizon. CAGRs were derived from mutation-class penetration curves and pricing elasticity assumptions calibrated to health technology assessment precedent. Forecast inputs incorporated newborn screening expansion timelines and gene-editing clinical advancement rates without year-specific milestones.
Sensitivities concentrate around regulatory classification of gene-editing therapeutics and payer evidence requirements for single-administration interventions. Cross-checking against IQWiG and HAS reimbursement precedent for orphan-priced biologics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Plasma Protease C1 Inhibitor Treatment Market
Specialty Medicine
Global Interstitial Cystitis Market
Specialty Medicine
Hashimoto's Thyroiditis Therapeutics Market
Specialty Medicine
Gingivostomatitis Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Treatment Market
Specialty Medicine
Frontotemporal Dementia Management Market
Specialty Medicine
Non-Alcoholic Fatty Liver Disease (NAFLD) Market
Specialty Medicine
Bipolar Disorders Treatment Market
Specialty Medicine
Overt Hepatic Encephalopathy Market
Specialty Medicine
Veno-Occlusive Hepatic Disease Therapeutics Market
Specialty Medicine
Post-Traumatic Stress Disorder Treatment Market
Specialty Medicine
Psoriatic Arthritis (Psa) Treatment Market
Specialty Medicine
Amino Acid Metabolism Disorders Treatment Market
Specialty Medicine
Nerve Entrapment Syndrome Therapeutics Market
Specialty Medicine
Carcinoid Syndrome Diarrhea Treatment Market
Specialty Medicine
Cryoglobulinemia Treatment Market