
 Acute Lymphocytic-Lymphoblastic Leukemia (ALL) Therapeutics Market | 2026-2036
Acute Lymphocytic-Lymphoblastic Leukemia (ALL) Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Acute Lymphocytic-Lymphoblastic Leukemia (ALL) Therapeutics Market Outlook
Companion diagnostic and biomarker-driven patient stratification is rewriting how value accrues across the ALL treatment continuum. Novartis leverages its CAR-T manufacturing infrastructure to anchor premium positioning in relapsed pediatric cases. Pfizer sustains broad chemotherapy portfolios that compete on hospital formulary access. Amgen specializes in bispecific antibody platforms that differentiate its pipeline from conventional kinase inhibitors.
Acute Lymphocytic-Lymphoblastic Leukemia therapeutics encompass pharmaceutical and biologic interventions designed to eliminate malignant lymphoblasts from bone marrow, peripheral blood, and extramedullary sites, with treatment protocols stratified by immunophenotype (B-cell versus T-cell lineage) and cytogenetic risk profiles. These agents serve the primary purpose of achieving complete remission, preventing central nervous system relapse, and enabling curative intent in pediatric and adult patient populations. Immunotherapy, particularly CAR-T cell constructs and bispecific T-cell engagers, commands the fastest expansion as manufacturing scale improves and outpatient administration protocols mature. Chemotherapy remains the volume backbone during induction and consolidation phases, though margin pools are migrating toward targeted therapy segments where oral tyrosine kinase inhibitors address Philadelphia chromosome-positive subtypes.
FDA breakthrough therapy designation and EMA priority medicines pathways compress regulatory review timelines for novel ALL modalities, while FDA's Risk Evaluation and Mitigation Strategies govern CAR-T distribution through certified treatment centers. These frameworks shape demand by restricting high-complexity therapies to accredited institutions with intensive care capabilities. Stakeholders must monitor how CMS and national health technology assessment bodies calibrate reimbursement for curative-intent cell therapies against lifetime cost offsets.
Market Dynamics
CAR-T manufacturing scale-up and FDA Risk Evaluation and Mitigation Strategies are compressing treatment access to certified centers, concentrating patient flows into oncology networks with intensive care capabilities while fragmenting regional availability.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Accelerated review pathways compress development timelines for novel immunotherapies, enabling faster commercialization of bispecific antibodies and cell-based constructs.
- Philadelphia Chromosome-Positive Subtyping:Biomarker-driven stratification expands addressable populations for oral tyrosine kinase inhibitors, pulling margin pools away from conventional chemotherapy protocols.
- Japan's Hematologic Referral Networks:Dense specialist infrastructure in Tokyo and Osaka accelerates adoption of outpatient CAR-T administration, reducing hospitalization requirements.
Market Restraints
- Vein-to-Vein Manufacturing Timelines:Autologous cell therapy production cycles create treatment gaps that allow disease progression in aggressive ALL subtypes.
- Cytokine Release Syndrome Management:ICU bed requirements and tocilizumab inventory obligations restrict therapy distribution to tertiary centers, excluding community oncology practices.
- EMA Priority Medicines Variability:Divergent national health technology assessment timelines across Germany, France, and Italy delay reimbursement harmonization for curative-intent therapies.
Strategic Opportunities
- Allogeneic CAR-T Platforms:Off-the-shelf cell therapies eliminate manufacturing delays, opening community hospital channels currently blocked by autologous logistics.
- Central Nervous System Prophylaxis Protocols:Intrathecal delivery innovations for T-cell engagers address extramedullary sanctuary sites underserved by systemic chemotherapy.
- CMS New Technology Add-On Payments:Transitional reimbursement mechanisms for cell therapies create pricing headroom during evidence generation phases.
Industry Challenges
- Vector Manufacturing Bottlenecks:Lentiviral and retroviriral vector production capacity constraints throttle pipeline expansion for late-stage CAR-T candidates.
- Cross-Border Patient Triage Complexity:REMS-certified center capacity imbalances force interstate and international patient transfers, complicating care coordination and outcome tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acute Lymphocytic-Lymphoblastic Leukemia (ALL) Therapeutics Market |
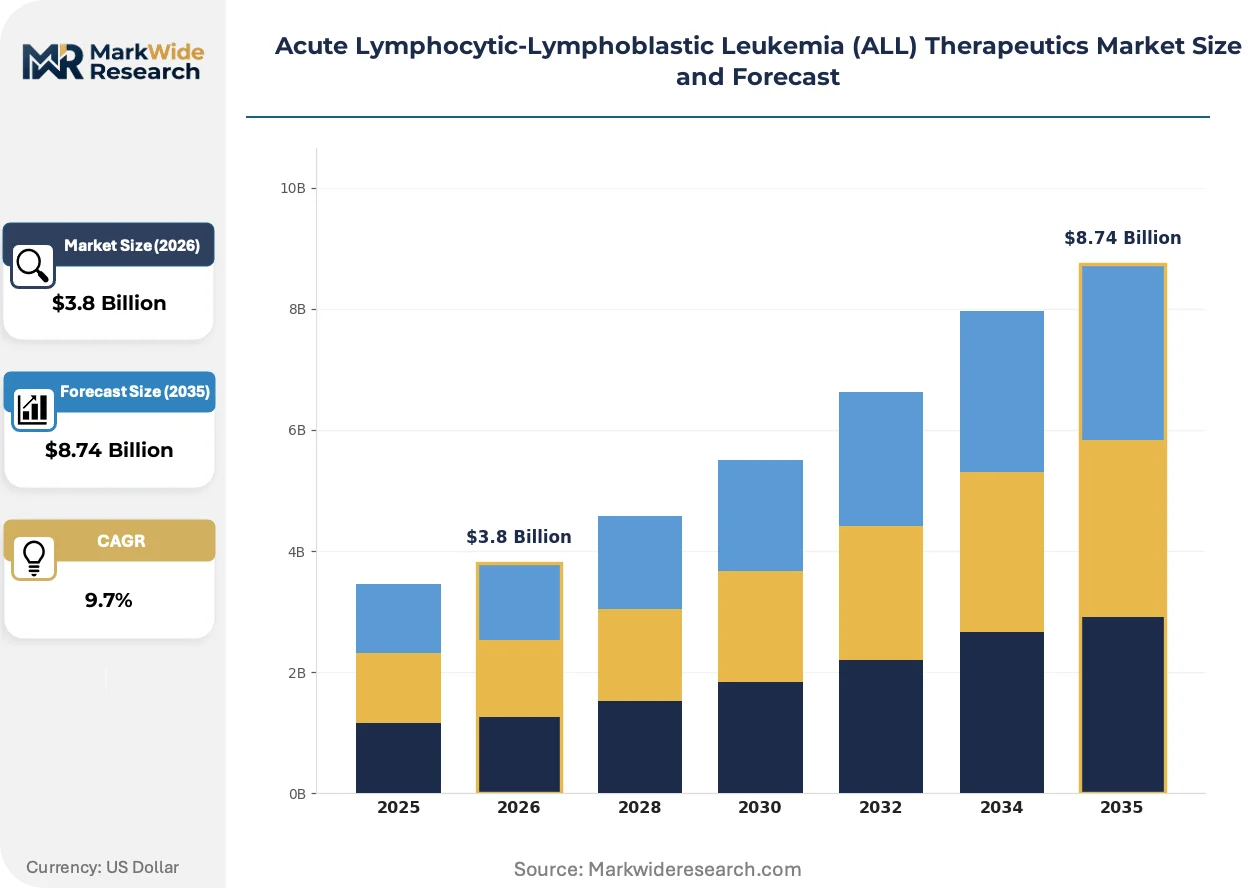
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Immunotherapy, Stem Cell Transplant Administration Route: Intravenous, Oral, Subcutaneous, Intrathecal End User: Hospitals, Oncology Clinics, Research Institutions, Homecare Settings Treatment Stage: Induction, Consolidation, Maintenance, Relapse |
| Companies Covered | Novartis AG, Pfizer Inc., Amgen Inc., Bristol-Myers Squibb Company, F. Hoffmann-La Roche Ltd, Gilead Sciences, Sanofi, Takeda Pharmaceutical Company, Jazz Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acute Lymphocytic-Lymphoblastic Leukemia (ALL) Therapeutics Market Strategic Shifts
Treatment protocols are virtualizing across the ALL continuum, with digital biomarker monitoring and decentralized manufacturing coordination displacing hospital-centric care models.
Next-generation sequencing panels are virtualizing risk stratification workflows, enabling real-time minimal residual disease tracking during maintenance phases. Community oncology practices in the United States adopt cloud-based molecular tumor boards to access academic center expertise without patient transfer. This distributed diagnostic infrastructure is virtualizing referral patterns, compressing the geographic advantage of established transplant centers.
EMA's adaptive pathway framework accelerates conditional approvals for pediatric ALL indications, compressing traditional phase III timelines through real-world evidence commitments. German and French health technology assessment bodies now require parallel economic modeling alongside clinical submissions, shifting sponsor preparation strategies. Manufacturers respond by embedding health economists within development teams earlier than historical oncology benchmarks.
Hospital formulary committees now demand total cost-of-ownership analyses that incorporate toxicity management and readmission risk, displacing simple per-dose price comparisons. Pediatric centers in Japan negotiate outcomes-based arrangements for CAR-T therapies, tying reimbursement thresholds to sustained remission milestones. This contractual evolution is most visible in Germany's university hospital networks, where integrated care organizations aggregate purchasing leverage across multiple malignancy indications.
Acute Lymphocytic-Lymphoblastic Leukemia (ALL) Therapeutics Market Segmentation
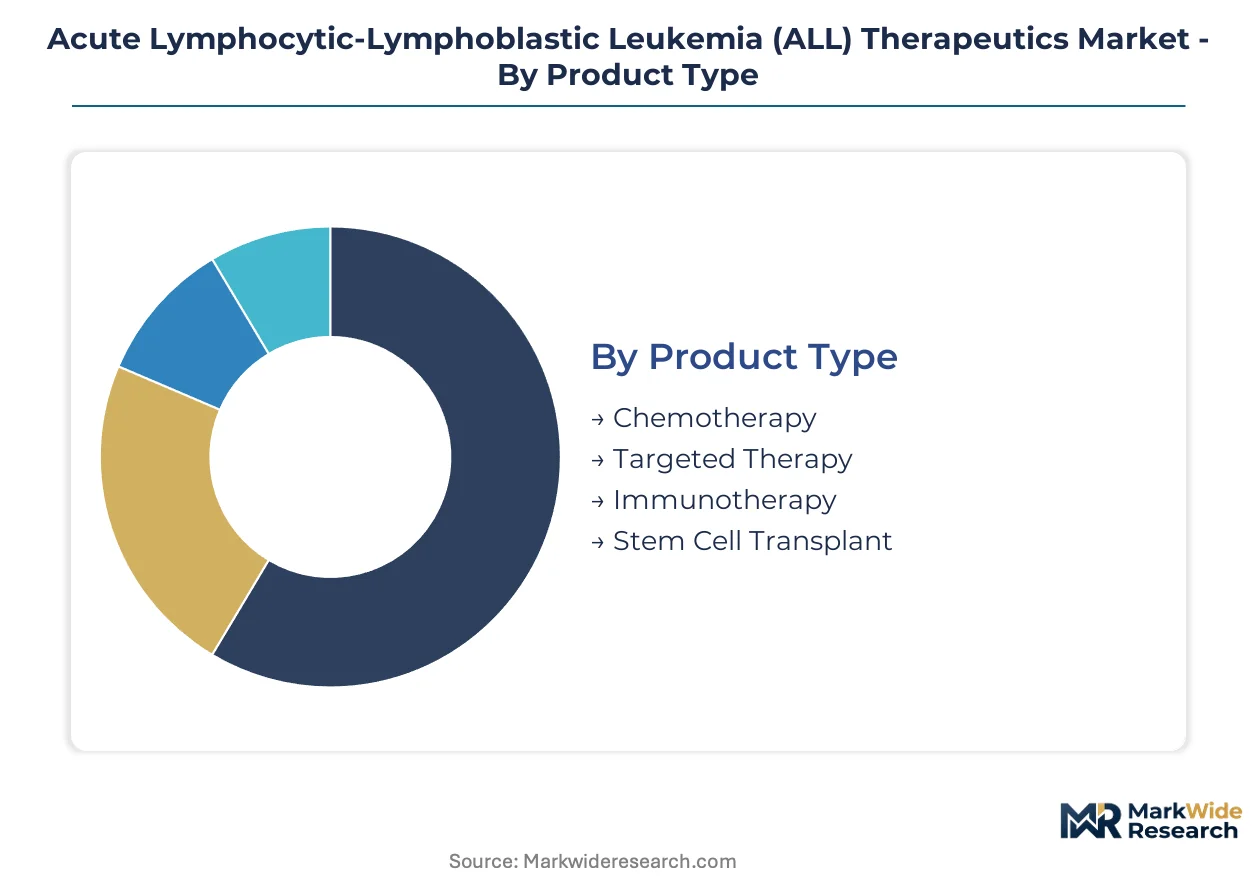
Patient stratification by immunophenotype and cytogenetic risk profiles demands precise therapeutic matching. Treatment protocols vary sharply across pediatric versus adult populations, Philadelphia chromosome status, and prior therapy exposure. Segmentation clarity enables manufacturers to align manufacturing investments with addressable patient pools.
Product Type:
Use-case spectrum spans curative-intent induction through salvage therapy for multiply relapsed disease, with modality selection driven by prior treatment history and molecular subtype.
- Chemotherapy:Anthracycline-vincristine-corticosteroid combinations form the induction backbone for B-cell and T-cell ALL protocols. Demand concentrates in pediatric centers across the United States, Germany, and Japan where established referral networks manage high-volume induction phases. Margin compression from generic substitution limits sponsor investment in novel cytotoxic formulations.
- Immunotherapy:CAR-T cell constructs and bispecific T-cell engagers redirect patient immune systems against CD19 and CD22 targets. Adoption accelerates in REMS-certified tertiary centers with ICU capabilities for cytokine release syndrome management. Novartis and Amgen manufacturing scale determines regional availability.
- Targeted Therapy:Tyrosine kinase inhibitors address Philadelphia chromosome-positive subtypes with oral dosing convenience.
- Stem Cell Transplant:Allogeneic transplantation remains reserved for high-risk cytogenetics or second remission salvage.
The dominant share belongs to Chemotherapy, while Immunotherapy is closing the gap fastest.
Administration Route:
Cost tier stratification separates hospital-based infusion services from outpatient oral regimens and emerging subcutaneous alternatives.
- Intravenous:Continuous infusion protocols for asparaginase and anthracyclines require central line placement and infusion center capacity. Demand clusters at academic medical centers in the United States and Japan where nursing protocols support multi-day infusion schedules. Hospital reimbursement frameworks favor bundled payment models for induction phases.
- Oral:Tyrosine kinase inhibitors for Philadelphia chromosome-positive ALL enable maintenance phase administration outside infusion centers. Germany's outpatient oncology networks leverage oral protocols to reduce hospital bed utilization during prolonged maintenance periods. Patient adherence monitoring via digital platforms supports therapy persistence.
- Subcutaneous:Emerging delivery route for bispecific antibodies seeking administration flexibility.
- Intrathecal:Methotrexate and cytarabine injections target central nervous system sanctuary sites.
Intravenous delivery commands current volume leadership, though Oral administration is expanding most quickly as maintenance protocols lengthen.
End User:
Customer type fragmentation reflects therapy complexity tiers, from intensive induction requiring inpatient capacity through maintenance phases manageable in community settings.
- Hospitals:Tertiary academic centers manage induction phases, CAR-T administration, and transplant conditioning. Capacity concentrates in the United States, Germany, and Japan where REMS certification and ICU bed availability restrict eligible sites. CMS new technology add-on payments flow through hospital billing systems.
- Oncology Clinics:Outpatient infusion centers handle consolidation and maintenance phases for standard-risk patients. Japan's hematologic referral networks in Tokyo and Osaka pioneer same-day CAR-T discharge protocols. Clinic accreditation standards vary across national jurisdictions.
- Research Institutions:Early-phase clinical trial enrollment for novel immunotherapy constructs.
- Homecare Settings:Oral maintenance therapy with remote monitoring support.
Hospitals retain the dominant share, while Oncology Clinics are gaining share fastest through outpatient administration innovations.
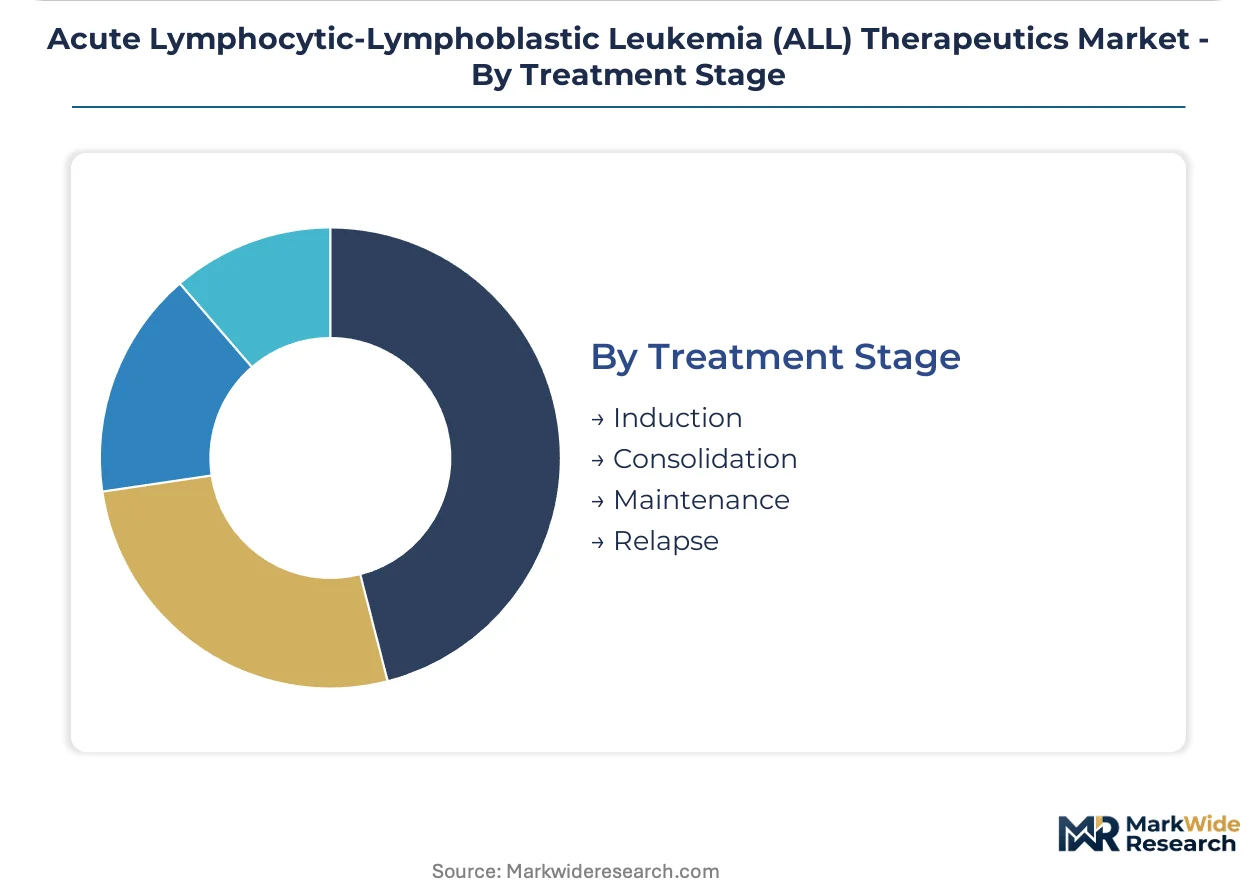
Treatment Stage:
Maturity gradient separates established induction protocols from emerging relapse salvage modalities where immunotherapy pipelines concentrate.
- Induction:Intensive multi-agent chemotherapy achieves morphologic complete remission within four weeks. Protocol standardization across COG and EORTC guidelines limits product differentiation opportunity. Volume concentrates in pediatric referral networks with established stem cell transplant bridges.
- Relapse:Salvage therapy for multiply relapsed disease drives CAR-T and bispecific antibody demand. FDA breakthrough therapy designations cluster in this stage where unmet need justifies accelerated review. Manufacturing slot allocation becomes the binding constraint for patient access.
- Consolidation:Intensification phases reduce minimal residual disease burden post-remission.
- Maintenance:Prolonged oral chemotherapy and immunosuppression prevent late recurrence.
Induction captures the dominant share, while Relapse therapy is climbing the fastest as immunotherapy approvals accumulate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell therapy manufacturing capacity and REMS-certified treatment centers concentrate in the United States, Germany, and Japan, creating tiered access patterns that fragment regional availability for advanced ALL modalities.
United States
FDA breakthrough therapy designations and CMS new technology add-on payments accelerate commercialization of CAR-T constructs and bispecific antibodies. The Risk Evaluation and Mitigation Strategies framework restricts high-complexity therapies to accredited tertiary centers with ICU capabilities. Philadelphia chromosome-positive subtyping protocols at Memorial Sloan Kettering and MD Anderson drive biomarker-driven patient stratification.
Germany
Dense hematologic referral networks and university hospital consortia aggregate purchasing leverage across multiple malignancy indications. EMA priority medicines pathways compress review timelines, though divergent national health technology assessment procedures across Germany, France, and Italy delay reimbursement harmonization. Heidelberg and Munich treatment centers pioneer outpatient CAR-T administration protocols.
Japan
PMDA accelerated approval pathways and dense specialist infrastructure in Tokyo and Osaka enable rapid adoption of novel immunotherapies. METI industrial policy supports domestic vector manufacturing scale-up to reduce import dependence. Japanese pediatric centers negotiate outcomes-based reimbursement arrangements tying payment to sustained remission milestones.
United Kingdom
NICE technology appraisals and Cancer Drugs Fund coverage decisions shape access to premium-priced cell therapies. The NHS England specialized commissioning framework concentrates ALL treatment at designated tertiary centers in London, Birmingham, and Manchester. Real-world evidence generation requirements under MHRA adaptive licensing compress traditional phase III timelines.
Switzerland
Swissmedic expedited review procedures and proximity to German and French markets position Basel and Zurich as early-access hubs for novel modalities. Private insurance reimbursement frameworks offer pricing headroom during evidence generation phases. Roche's headquarters presence anchors clinical trial infrastructure for biomarker-driven protocols.
Acute Lymphocytic-Lymphoblastic Leukemia (ALL) Therapeutics Market Competitive Environment
CAR-T specialists and broad oncology portfolios split the market into distinct capability tiers. Large-cap pharmaceutical conglomerates with cell therapy manufacturing infrastructure compete against mid-size biotechs with bispecific antibody platforms. Three strategic archetypes dominate: integrated cell therapy manufacturers with captive vector supply, kinase inhibitor specialists with oral formulation expertise, and chemotherapy portfolio managers with hospital formulary access. Competitive intensity centers on manufacturing slot allocation for autologous products and REMS certification expansion into community oncology settings.
Within the integrated cell therapy tier, Novartis AG and Gilead Sciences exemplify archetypes built on lentiviral vector manufacturing scale and certified treatment center networks. Among broad oncology incumbents, Pfizer Inc. and Bristol-Myers Squibb Company occupy positions anchored by hospital formulary relationships across induction and consolidation protocols. Amgen Inc. represents the bispecific antibody specialist archetype, with Takeda Pharmaceutical Company and Sanofi competing on geographic diversification into Asia-Pacific markets. F. Hoffmann-La Roche Ltd anchors the companion diagnostic integration model, while Jazz Pharmaceuticals sits within the salvage therapy and CNS prophylaxis specialization segment.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| Amgen Inc. |
| Bristol-Myers Squibb Company |
| F. Hoffmann-La Roche Ltd |
| Gilead Sciences |
| Sanofi |
| Takeda Pharmaceutical Company |
| Jazz Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Boston's vector manufacturing cluster anchors lentiviral production capacity, and its slot allocation dynamics directly shape downstream pricing power for CAR-T therapies across United States oncology networks. Contract structures for autologous cell therapies bundle manufacturing fees with ICU standby costs, compressing margin flexibility for community hospitals lacking certified treatment centers.
Pricing Analysis
CMS New Technology Add-On Payments dictate the pricing tier structure for cell-based ALL therapies in the United States, creating three-tier pricing stratification across academic medical centers, oncology clinic networks, and research institutions. Price differentiation hinges on REMS certification status and ICU bed availability, with certified centers commanding premium reimbursement rates. Cost compression in the chemotherapy backbone intensifies as generic anthracyclines and vincristine formulations expand hospital formulary access. Pediatric referral networks exhibit highest price sensitivity due to bundled Medicaid reimbursement frameworks, while private oncology clinics in Japan demonstrate lowest sensitivity under outcomes-based contracting arrangements.
Supply Chain Analysis
Extended payment terms from vector manufacturers to contract development organizations now stretch 90-120 days, straining working capital across the CAR-T production ecosystem. Manufacturing inputs concentrate in the United States, Germany, and Switzerland, with lentiviral vector production anchored in Boston and Basel facilities. Raw material dependencies center on fetal bovine serum, synthetic growth media, and cryopreservation solutions. Single-source vulnerability for GMP-grade plasmid DNA creates bottleneck exposure for late-stage pipeline candidates. Distribution runs through REMS-certified tertiary centers with validated cold-chain logistics, excluding community oncology practices from direct product access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in the ALL therapeutics market concentrate on cytokine release syndrome management protocols and outpatient monitoring platforms, both expanding faster than drug product revenue as administration shifts toward decentralized settings.
For Market Incumbents: Pre-empt allogeneic CAR-T disruption by securing exclusive vector manufacturing partnerships with CDMOs possessing dual-site redundancy. Lock in long-term supply agreements for GMP-grade plasmid DNA before capacity constraints tighten. Expand REMS certification into select community oncology networks in Germany and Japan to defend channel control against off-the-shelf platform entrants.
For New Entrants and Emerging Players: Pursue bispecific T-cell engager development for multiply relapsed adult ALL, a segment underserved by pediatric-optimized CAR-T constructs. Target outpatient administration protocols in Japan's Tokyo-Osaka corridor where same-day discharge innovations reduce hospitalization requirements. Anchor go-to-market strategy through outcomes-based reimbursement pilots with German integrated care organizations.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among bispecific antibody platforms with subcutaneous formulation potential, offering maintenance-phase dosing advantages over infusion-dependent cell therapies. Long-term viability across the analysis window favors manufacturers with captive vector supply and diversified immunophenotype coverage beyond CD19. Signal to monitor: PMDA and EMA conditional approval timelines for allogeneic platforms, which would compress autologous manufacturing premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| REMS Certification Expansion | Opens community hospital channels currently blocked by autologous logistics constraints in the United States. |
| Allogeneic Platform Development | Eliminates vein-to-vein manufacturing delays that allow disease progression in aggressive ALL subtypes. |
| Companion Diagnostic Integration | Locks in biomarker-driven patient stratification workflows with next-generation sequencing panel partners. |
| Outpatient Administration Protocols | Reduces ICU bed requirements and tocilizumab inventory obligations that restrict therapy distribution. |
| Vector Manufacturing Scale-Up | Addresses lentiviral production bottlenecks throttling pipeline expansion for late-stage CAR-T candidates. |
Study Parameters
Initial hypotheses were tested against primary input from CAR-T manufacturing executives, hospital formulary directors, regulatory affairs specialists, and payer access managers, then refined through secondary validation across FDA filings, EMA submission documents, ClinicalTrials.gov records, and CMS reimbursement databases. Bottom-up patient flow modeling from induction through relapse salvage phases was triangulated against top-down pharmaceutical revenue disclosures and hospital procurement database extracts.
Demand-supply balance framing anchored the forecast framework, with patient volume projections across B-cell and T-cell immunophenotypes, Philadelphia chromosome status, and prior therapy exposure segments modeled throughout the forecast period. CAGRs were derived from treatment adoption curves for novel immunotherapies and chemotherapy protocol persistence rates. Industry-specific inputs incorporated REMS-certified center capacity expansion timelines and vector manufacturing slot allocation constraints.
Sensitivities concentrate around allogeneic CAR-T approval timelines, CMS reimbursement recalibration for cell therapies, and cross-border patient triage complexity from REMS capacity imbalances. Forecasts reflect documented assumptions regarding manufacturing scale-up trajectories and regulatory pathway harmonization across the United States, Germany, and Japan. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Nuclear Medicine Therapeutics Market
Specialty Medicine
Toxic Shock Syndrome Treatment Market
Specialty Medicine
Chromoblastomycosis Treatment Market
Specialty Medicine
Cutaneous B-Cell Lymphoma Treatment Market
Specialty Medicine
Global Actinic Keratosis Treatment Market
Specialty Medicine
Medical Foods for Orphan Diseases Market
Specialty Medicine
Tinnitus Management Market
Specialty Medicine
Mucous Membrane Pemphigoid Treatment Market
Specialty Medicine
Enzyme Replacement Therapy Market
Specialty Medicine
Epistaxis Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Pigmented Villonodular Synovitis Treatment Market
Specialty Medicine
Carcinoid Tumor Syndrome Management Market
Specialty Medicine
Gaucher and Pompe Diseases Enzyme Replacement Therapy (ERT) Market
Specialty Medicine
Klinefelter Syndrome Treatment Market
Specialty Medicine
Pseudobulbar Treatment Market