
 Asia Pacific Liver Cancer Market | 2026-2036
Asia Pacific Liver Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Liver Cancer Market Outlook
A widening R&D infrastructure gap between multinational pharmaceutical conglomerates and mid-sized biotechnology firms is unwinding competitive parity across the Asia Pacific liver cancer landscape. Bayer AG leverages its integrated diagnostics-to-therapeutics platform to sustain dominance in hepatocellular carcinoma drug development. F. Hoffmann-La Roche Ltd. anchors its regional position through companion diagnostic capabilities that pair with targeted therapy portfolios.
Asia Pacific liver cancer encompasses the clinical management of primary hepatic malignancies, predominantly hepatocellular carcinoma and cholangiocarcinoma, through systemic pharmacological intervention, localized radiation, surgical resection, and interventional radiology procedures with therapeutic endpoints measured by overall survival and progression-free intervals. Immunotherapy segments are capturing accelerated prescriber preference as checkpoint inhibitors demonstrate durable responses in advanced-stage patients previously refractory to sorafenib-based protocols. Hospitals command the dominant end-user channel, while oncology clinics represent the fastest-growing delivery site as ambulatory infusion capacity expands across metropolitan India and Southeast Asian healthcare networks.
China's NMPA operates accelerated review pathways for breakthrough oncology therapies, while Japan's PMDA maintains stringent pharmacovigilance requirements that extend market access timelines for novel agents. India's CDSCO balances abbreviated approval routes for essential medicines against post-marketing surveillance obligations that manufacturers must navigate for commercial distribution. Stakeholders must monitor evolving reimbursement negotiations between national health authorities and immunotherapy developers, as pricing determinations in China and Japan will cascade across Asia Pacific market access strategies.
Market Dynamics
China's NMPA accelerated review pathways are compressing competitive entry timelines for novel hepatocellular carcinoma therapies, forcing incumbent developers to recalibrate clinical trial investments and regional launch sequencing against domestic biotechnology challengers.
Growth Catalysts
- Checkpoint inhibitor protocols:Oncology centers across China and Japan are expanding infusion capacity for PD-1 and PD-L1 regimens in advanced hepatocellular carcinoma patients previously refractory to tyrosine kinase inhibitors.
- NMPA breakthrough therapy designation:The pathway grants priority review to novel agents demonstrating substantial improvement over existing sorafenib-based standards, shortening approval cycles for immunotherapy developers.
- Tier-one hospital concentration:Patient volume gravity in Beijing, Shanghai, and Guangzhou oncology centers concentrates demand for premium targeted therapies with favorable reimbursement formulary placement.
Market Restraints
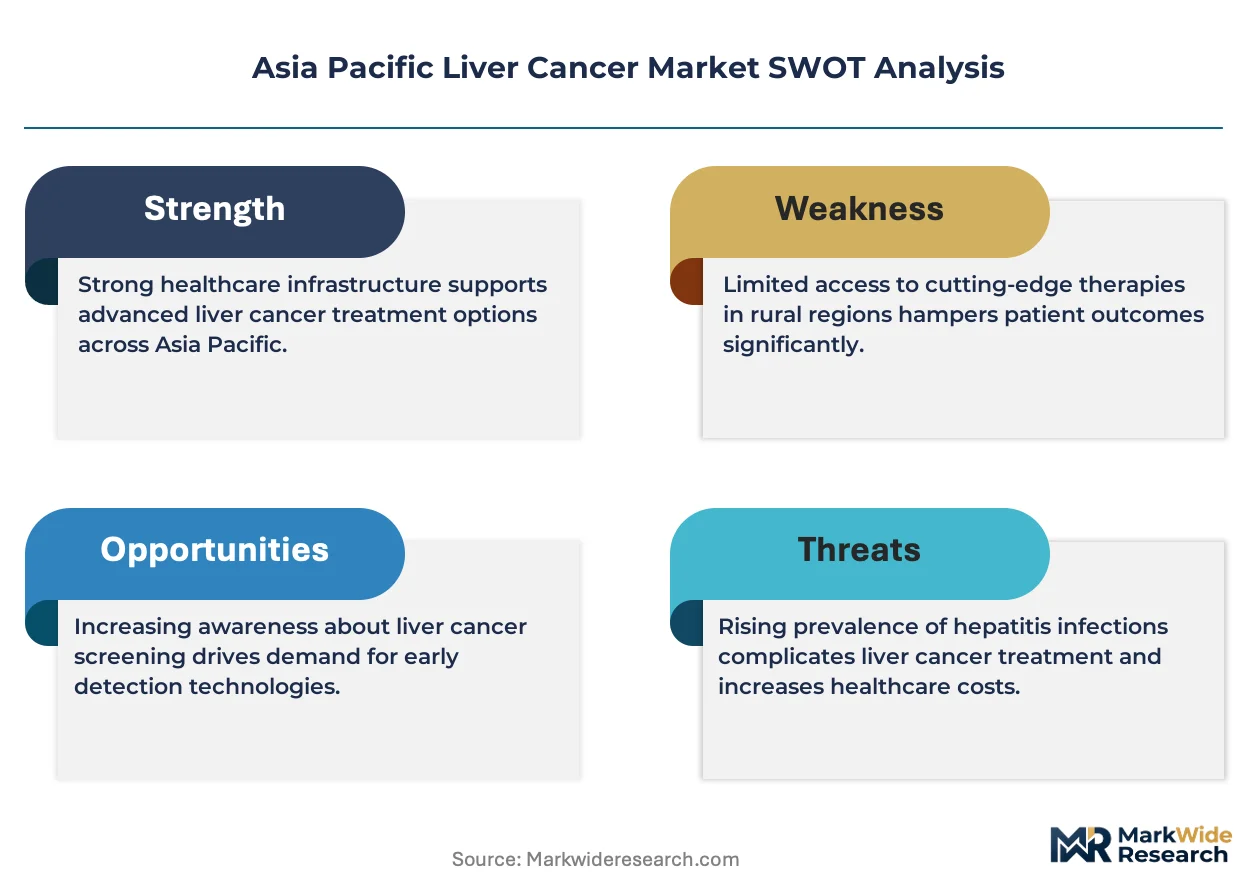
- Biomarker testing infrastructure gaps:Companion diagnostic penetration remains uneven across India's CDSCO-regulated laboratories, limiting patient identification for precision therapy candidacy.
- Reimbursement negotiation compression:China's national health security administration exerts substantial price pressure during volume-based procurement rounds for oncology therapeutics.
- Cold chain distribution constraints:Temperature-sensitive biologics face last-mile integrity risks across Southeast Asian archipelago geographies with fragmented logistics networks.
Strategic Opportunities
- India's ambulatory infusion expansion:Metropolitan oncology clinics in Mumbai, Delhi, and Bangalore are building dedicated immuno-oncology suites to capture patient volumes migrating from inpatient settings.
- Combination therapy white space:Pairing anti-angiogenic agents with checkpoint inhibitors in front-line hepatocellular carcinoma protocols remains underexplored relative to monotherapy benchmarks.
- Japan's PMDA Sakigake designation:The early approval framework offers reduced data requirements for regenerative medicines and breakthrough oncology products, accelerating commercial timelines for qualified sponsors.
Industry Challenges
- Interventional radiology skill scarcity:Transarterial chemoembolization and radioembolization procedures require specialized training that outpaces fellowship program output across Asia Pacific tertiary centers.
- Real-world evidence generation complexity:Post-marketing surveillance obligations under India's CDSCO and Japan's PMDA demand substantial pharmacovigilance infrastructure that mid-sized developers struggle to operationalize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Liver Cancer Market |
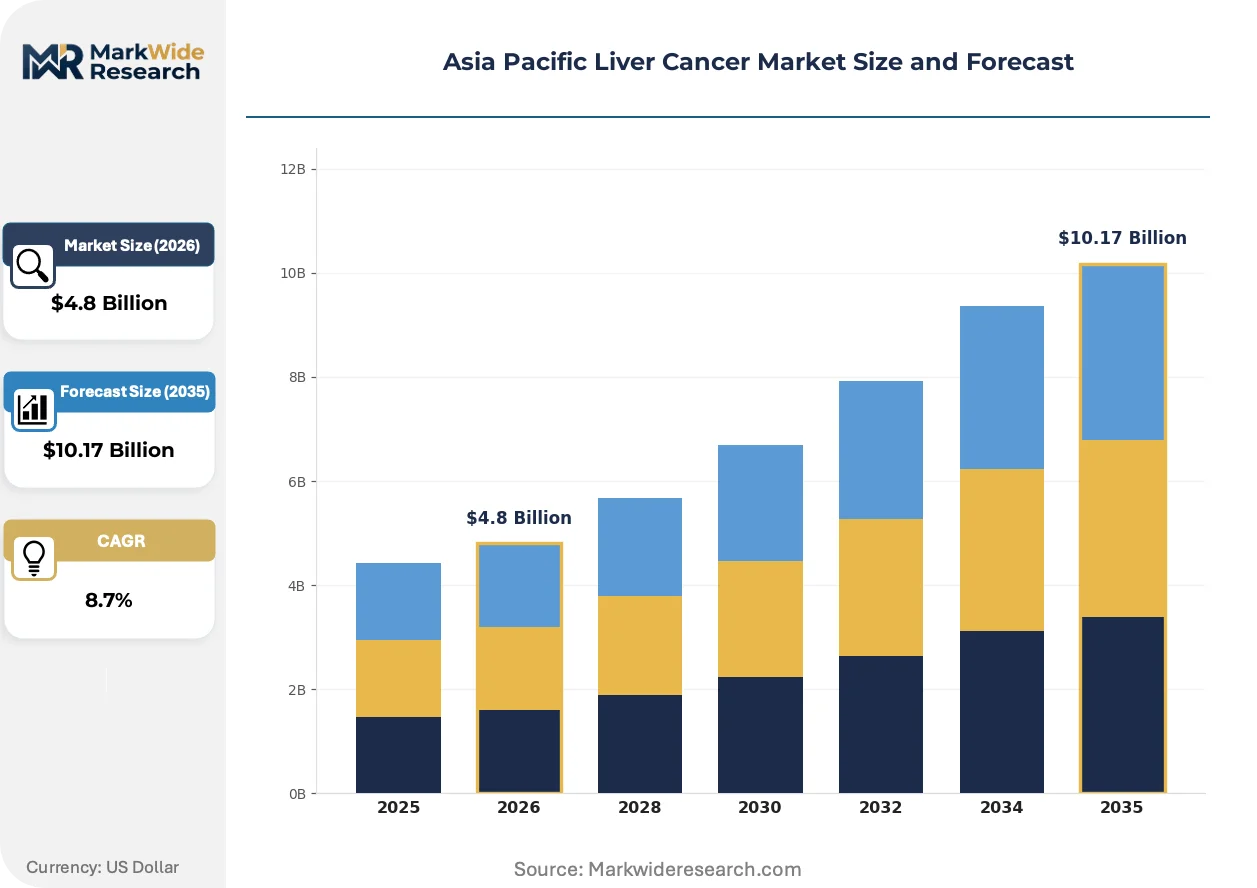
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Targeted Therapy, Chemotherapy, Immunotherapy, Radiotherapy End User: Hospitals, Oncology Clinics, Research Institutes, Diagnostic Centers Delivery Mode: Intravenous, Oral, Topical, Injectable Application: Treatment, Diagnosis, Research, Screening |
| Companies Covered | Bayer AG, Novartis AG, F. Hoffmann-La Roche Ltd., Merck & Co. Inc., Abbott Laboratories, Exelixis Inc., Boston Scientific Corporation, Siemens Healthineers GmbH, Eli Lilly and Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Liver Cancer Market Strategic Shifts
Immunotherapy protocol personalization is displacing one-size-fits-all sorafenib regimens across Asia Pacific hepatocellular carcinoma management, with biomarker-driven patient stratification emerging as the central organizing principle for clinical investment and prescriber education.
Artificial intelligence-enabled imaging analysis is fragmenting traditional radiology workflows in hepatocellular carcinoma diagnosis. Tier-one oncology centers in China and Japan are deploying machine learning algorithms for lesion characterization and treatment response prediction. The technology is compressing diagnostic timelines while creating parallel competency requirements for radiology departments.
Japan's PMDA revised its regenerative medicine approval framework to streamline cell therapy commercialization timelines for oncology indications. The regulatory revision reduces pre-approval clinical data requirements for products demonstrating early efficacy signals. Hepatocellular carcinoma cell therapy developers are repositioning Japan as their Asia Pacific launch priority ahead of China NMPA pathways.
Hospital procurement committees are consolidating vendor relationships for immuno-oncology portfolios, replacing fragmented single-agent purchasing with integrated formulary contracts. China's tier-one oncology centers are negotiating multi-product agreements spanning diagnostics and therapeutics. The concentration trend is visible across Shanghai and Beijing hospital networks seeking operational efficiency in infusion scheduling and inventory management.
Asia Pacific Liver Cancer Market Segmentation
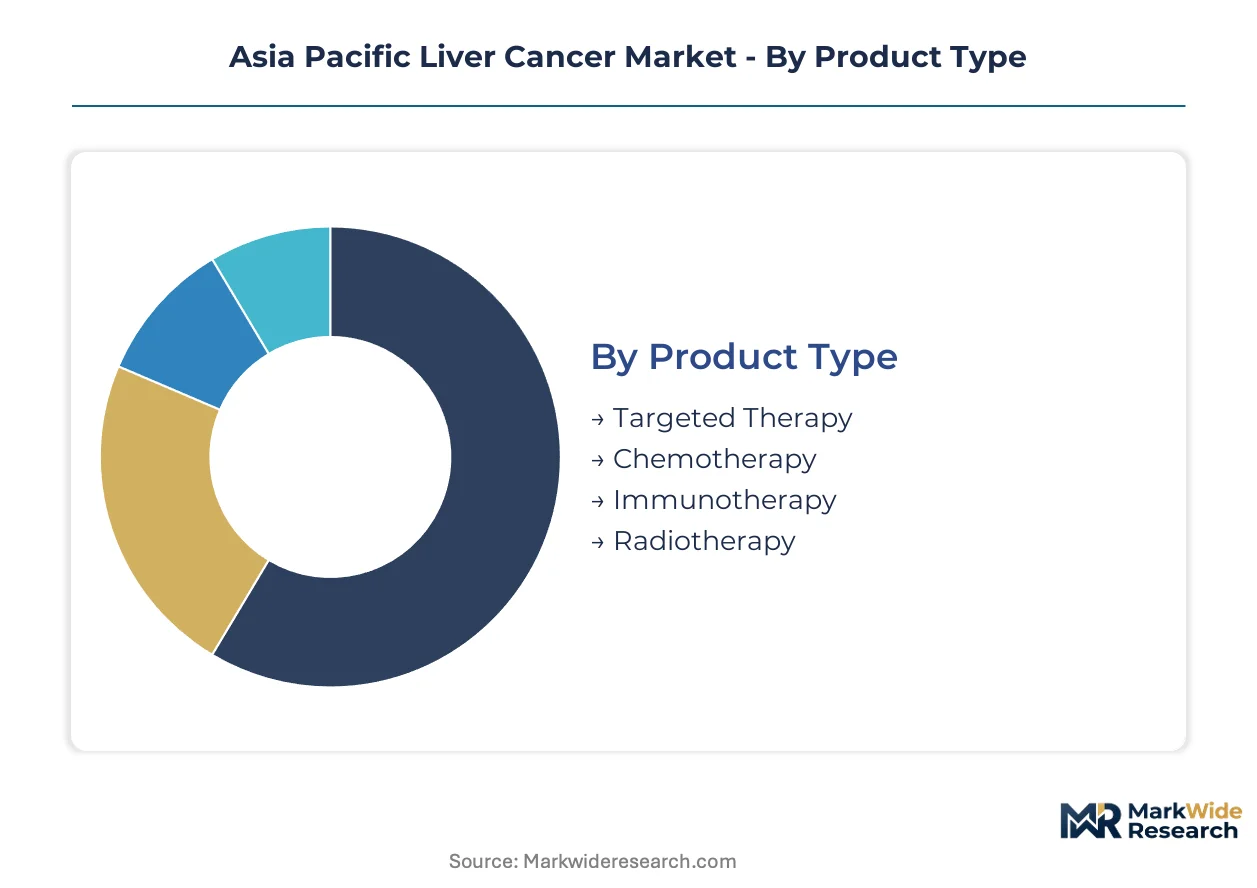
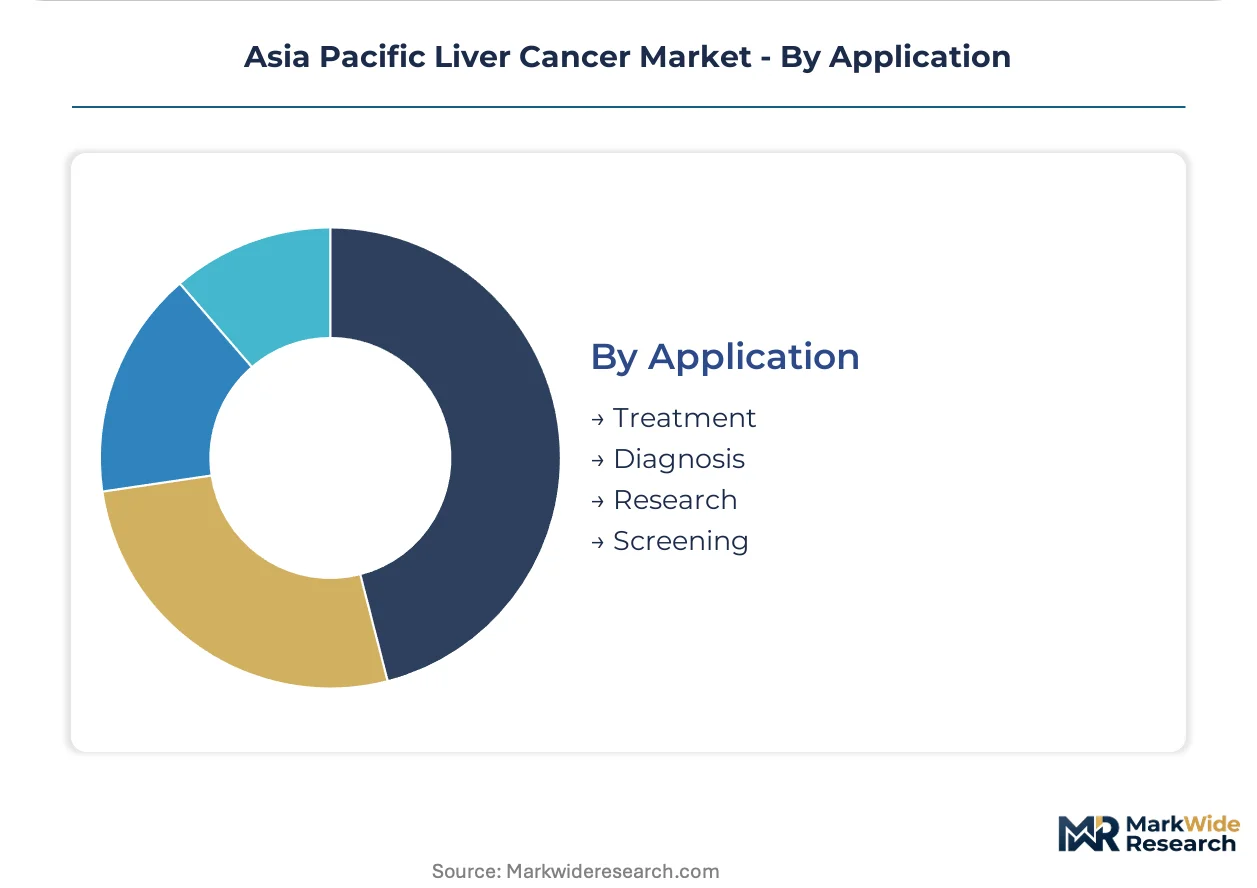
Segmentation reveals how treatment modality preferences diverge across Asia Pacific's heterogeneous healthcare infrastructure. China's tier-one oncology centers drive premium therapy uptake while India's ambulatory networks reshape delivery economics.
Product Type:
Domestic manufacturing capacity concentrates in China and India for small-molecule agents, while imported biologics dominate immunotherapy supply.
- Targeted Therapy:Tyrosine kinase inhibitors and multi-kinase blockers constitute the clinical backbone for intermediate-stage hepatocellular carcinoma management. China's NMPA has approved multiple domestic sorafenib biosimilars, compressing pricing in Beijing and Shanghai hospital procurement. The established reimbursement pathway anchors volume concentration.
- Immunotherapy:Checkpoint inhibitors targeting PD-1 and PD-L1 pathways command premium positioning in advanced-stage protocols previously refractory to kinase inhibition. Japan's PMDA Sakigake designation accelerates commercial timelines for qualified sponsors, drawing regional launch sequencing toward Tokyo and Osaka oncology networks.
- Chemotherapy:Cytotoxic regimens retain utility in cholangiocarcinoma subtypes with limited targeted vulnerability.
- Radiotherapy:External beam and selective internal radiation therapy address localized tumor burden.
Targeted therapy commands the established base. The steepest expansion runs through immunotherapy.
End User:
Facility type determines reimbursement tier, infusion infrastructure investment, and patient volume capture.
- Hospitals:Tertiary oncology centers in China, Japan, and South Korea concentrate surgical resection capacity, interventional radiology suites, and multidisciplinary tumor boards. China's tier-one hospitals in Beijing, Shanghai, and Guangzhou negotiate integrated formulary contracts spanning diagnostics and therapeutics.
- Oncology Clinics:Ambulatory infusion centers in Mumbai, Delhi, and Bangalore are building dedicated immuno-oncology capacity to capture patient volumes migrating from inpatient settings. The capital-light model accelerates prescriber access outside hospital procurement committees.
- Research Institutes:Academic medical centers in Singapore and Australia generate clinical trial evidence for regional regulatory submissions.
- Diagnostic Centers:Imaging and biomarker testing facilities support patient stratification for precision therapy candidacy.
Hospitals retain the volume anchor. Oncology clinics are gaining share fastest.
Delivery Mode:
Route of administration shapes cold chain requirements, nursing labor intensity, and patient compliance profiles.
- Intravenous:Infusion-dependent biologics require temperature-controlled logistics and specialized nursing supervision. Southeast Asian archipelago geographies present last-mile integrity risks for temperature-sensitive checkpoint inhibitors.
- Oral:Small-molecule tyrosine kinase inhibitors enable ambulatory management without infusion infrastructure. India's CDSCO has accelerated abbreviated approval routes for oral oncology generics, expanding access beyond metropolitan hospital networks.
- Injectable:Subcutaneous formulations reduce administration time versus intravenous protocols.
- Topical:Limited application in cutaneous metastases or procedural adjuvant settings.
Intravenous delivery anchors biologic revenue. Oral administration is climbing the fastest.
Application:
Clinical purpose determines pricing architecture, regulatory pathway, and stakeholder reimbursement negotiation.
- Treatment:Curative-intent surgical adjuvant and palliative systemic therapy represent the revenue concentration. China's national health security administration exerts substantial price pressure during volume-based procurement rounds for oncology therapeutics.
- Diagnosis:Imaging and biomarker testing infrastructure enables patient identification for precision therapy candidacy. Japan's PMDA maintains stringent companion diagnostic validation requirements that extend market access timelines.
- Screening:Ultrasound and AFP surveillance programs target high-risk cirrhotic populations.
- Research:Clinical trial supply and investigator-initiated studies support pipeline development.
Treatment commands the established base. Diagnosis is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across Asia Pacific liver cancer markets. China's volume-based procurement exerts severe compression on tyrosine kinase inhibitors, while Japan's premium reimbursement tier sustains checkpoint inhibitor margins. India's out-of-pocket payment dominance creates acute sensitivity to oral generic pricing.
China
NMPA breakthrough therapy designations compress approval timelines for hepatocellular carcinoma immunotherapies. Volume-based procurement rounds under the national health security administration slash prices for sorafenib biosimilars. Beijing and Shanghai tier-one oncology centers concentrate demand for premium PD-1 regimens with favorable formulary placement.
Japan
PMDA Sakigake designation accelerates commercial entry for qualified oncology sponsors with reduced clinical data requirements. Stringent pharmacovigilance obligations extend post-marketing surveillance timelines for novel agents. Tokyo and Osaka hospital networks anchor regional demand for companion diagnostic-linked targeted therapies.
India
CDSCO abbreviated approval routes expand access to oral oncology generics beyond metropolitan hospital networks. Post-marketing surveillance obligations demand pharmacovigilance infrastructure that mid-sized developers struggle to operationalize. Mumbai, Delhi, and Bangalore oncology clinics build dedicated immuno-oncology suites for ambulatory infusion expansion.
South Korea
MFDS fast-track review pathways prioritize novel agents for unmet hepatocellular carcinoma indications. National health insurance reimbursement negotiations determine commercial viability for premium biologics. Seoul capital area tertiary centers concentrate interventional radiology capacity and multidisciplinary tumor board infrastructure.
Australia
TGA priority review pathways accelerate market access for breakthrough oncology therapies with substantial clinical benefit. Pharmaceutical Benefits Scheme pricing negotiations cap reimbursement for immunotherapy combinations. Sydney and Melbourne academic medical centers generate clinical trial evidence for regional regulatory submissions.
Asia Pacific Liver Cancer Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in Asia Pacific liver cancer therapeutics. Multinational pharmaceutical conglomerates leverage companion diagnostic capabilities and integrated diagnostics-to-therapeutics platforms. Mid-sized biotechnology firms compete on accelerated regulatory pathways and combination therapy white space. Dominant competitive moves include strategic partnerships for biomarker co-development and geographic launch sequencing optimization.
Within the integrated diagnostics-to-therapeutics tier, Bayer AG and F. Hoffmann-La Roche Ltd. exemplify platform consolidation strategies. Roche anchors its regional position through companion diagnostic pairing with targeted therapy portfolios. Among mid-sized oncology specialists, Exelixis Inc. occupies a position defined by kinase inhibitor focus. These archetypes represent divergent competitive bets on precision medicine infrastructure versus single-agent clinical differentiation.
| Leading Market Players |
|---|
| Bayer AG |
| Novartis AG |
| F. Hoffmann-La Roche Ltd. |
| Merck & Co. Inc. |
| Abbott Laboratories |
| Exelixis Inc. |
| Boston Scientific Corporation |
| Siemens Healthineers GmbH |
| Eli Lilly and Company |
| Others |
Value Chain & Pricing Dynamics
Checkpoint inhibitor substitution for sorafenib-based regimens is redrawing procurement geography across Asia Pacific oncology networks, compressing price premiums in Chinese tier-one hospitals while elevating cold chain logistics costs through temperature-sensitive biologic handling requirements.
Pricing Analysis
After-sales revenue from companion diagnostic testing and patient monitoring services drives lifetime value capture for immunotherapy developers in hepatocellular carcinoma. Three-tier pricing structure across premium PD-L1 inhibitors, standard PD-1 agents, and economy-positioned biosimilars stratifies Beijing and Shanghai hospital procurement. Cost compression in the tyrosine kinase inhibitor tier is intensifying because China's volume-based procurement rounds force steep discounts on sorafenib equivalents. Oncology clinics in Mumbai and Delhi demonstrate highest price sensitivity due to out-of-pocket payment dominance, while Japanese tertiary centers show lowest sensitivity under premium reimbursement tiers.
Supply Chain Analysis
Just-in-time inventory preferences dominate checkpoint inhibitor distribution to tier-one oncology centers, though strategic stockpiling of oral tyrosine kinase inhibitors buffers against CDSCO approval delays in Indian metropolitan markets. Manufacturing concentration centers on China for small-molecule active pharmaceutical ingredients, Switzerland for biologic drug substance, and Singapore for regional fill-finish operations. Cold chain distribution draws from specialized logistics providers with validated temperature monitoring, resting on liquid nitrogen storage nodes and refrigerated transport fleets. Single-source vulnerability in monoclonal antibody production creates exposure to facility contamination events. Distribution runs through hospital procurement committees in China and Japan, direct-to-clinic channels in India, and GPO contracts in Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific liver cancer therapeutics occupy an early-cycle expansion phase, with checkpoint inhibitor penetration in front-line hepatocellular carcinoma protocols representing substantial runway before market maturation.
For Market Incumbents: Fortify formulary positioning through integrated diagnostic-therapeutic bundling that locks out standalone competitors. Deepen backward integration into companion diagnostic development to preserve margin capture against biosimilar erosion. Expand infusion capacity partnerships with Mumbai and Bangalore oncology clinics to intercept patient volume migration from hospital settings.
For New Entrants and Emerging Players: Anchor in combination therapy white space pairing anti-angiogenic agents with checkpoint inhibitors, where clinical data gaps limit incumbent dominance. Target India's ambulatory infusion expansion as the most penetrable delivery channel, leveraging abbreviated CDSCO approval routes for oral generics to establish prescriber relationships ahead of biologic launches.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-cap biotechnology firms possessing Phase II hepatocellular carcinoma pipelines but lacking pharmacovigilance infrastructure for post-marketing surveillance. Long-term viability hinges on regulatory navigation capabilities across NMPA, PMDA, and CDSCO pathways. Watch Japan's PMDA Sakigake designation awards as the inflection signal for accelerated commercial timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Pairs targeted therapy launches with biomarker testing infrastructure across Beijing and Shanghai hospital networks. |
| Regional Fill-Finish Capacity Expansion | Reduces cold chain exposure for temperature-sensitive biologics distributed across Southeast Asian archipelago geographies. |
| Ambulatory Infusion Suite Partnerships | Captures patient volumes migrating from inpatient settings in Mumbai, Delhi, and Bangalore oncology markets. |
| NMPA Breakthrough Therapy Pursuit | Compresses approval timelines relative to standard review pathways for novel hepatocellular carcinoma agents. |
| Real-World Evidence Generation Programs | Satisfies post-marketing surveillance obligations under Japan's PMDA and India's CDSCO regulatory frameworks. |
Study Parameters
A standing panel of drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists provided ongoing calibration against secondary validation from NMPA filings, PMDA submissions, ClinicalTrials.gov records, and hospital formulary databases. Primary interviews with oncology center pharmacy directors and infusion clinic operators combined with bottom-up prescription volume modeling and top-down market sizing triangulation.
Consistency checks validated outputs against external benchmarks across the analysis window, with segmentation modeling spanning treatment line, administration route, regional regulatory cluster, and patient population stratification. CAGRs derived from patient volume projections, therapy penetration curves, and pricing trajectory assumptions, incorporating NMPA approval velocity and Japan reimbursement negotiation timelines as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained checkpoint inhibitor efficacy data and stable regulatory pathway timelines; material deviation would warrant model refresh. Revision becomes warranted when NMPA breakthrough therapy designation velocity or volume-based procurement intensity crosses thresholds that alter competitive entry economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Asia-Pacific Sports Medicine Market
Specialty Medicine
Secondary Progressive Multiple Sclerosis (SPMS) Treatment Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Overt Hepatic Encephalopathy Market
Specialty Medicine
Non-Alcoholic Fatty Liver Disease (NAFLD) Market
Specialty Medicine
Pigmentosa Treatment Market
Specialty Medicine
Abetalipoproteinemia Management Market
Specialty Medicine
Avascular Necrosis Market
Specialty Medicine
Global Childhood Absence Epilepsy Treatment Market
Specialty Medicine
Global Addison's Disease Treatment Market
Specialty Medicine
Infantile Spasms Therapeutics Market
Specialty Medicine
Bartonellosis Therapeutics Market
Specialty Medicine
Urinary Retention Market
Specialty Medicine
Mental Retardation Treatment Market
Specialty Medicine
Advance Renal Cell Carcinoma Therapeutics Market
Specialty Medicine
Rhabdomyosarcoma Treatment Market