
 Alopecia Treatment (Hair Loss) Market | 2026-2036
Alopecia Treatment (Hair Loss) Market Size, Share, and Industry Trends Forecast 2026-2036
Alopecia Treatment (Hair Loss) Market Outlook
A shift from single-source API procurement to multi-source active pharmaceutical ingredient contracts is repositioning supply security for generic finasteride and minoxidil manufacturers. Cipla Limited anchors its position through backward integration into API production for cost-stable oral medications. Merck & Co. Inc. sustains brand loyalty in prescription hair loss therapies through decades of clinical data accumulation. Johnson & Johnson competes in over-the-counter topical segments through pharmacy shelf dominance and consumer recognition.
Alopecia treatment encompasses pharmacological and procedural interventions designed to arrest hair follicle miniaturization and stimulate regrowth, with topical minoxidil solutions typically formulated at two percent to five percent concentrations and oral finasteride acting as a five-alpha-reductase inhibitor. The primary commercial purpose centers on addressing androgenetic alopecia, alopecia areata, and chemotherapy-induced hair loss across outpatient and home-based settings. Topical solutions occupy the largest revenue share due to established over-the-counter accessibility and lower physician dependency, though oral medications capture disproportionate margin pools through prescription pricing and longer treatment adherence curves. Surgical procedures generate the highest per-procedure revenue but remain constrained by specialist availability and geographic concentration of hair restoration centers.
FDA oversight of topical JAK inhibitors and prostaglandin analogs shapes clinical trial design and label expansion timelines for new molecular entities entering alopecia areata indications. EMA's MDR framework and REACH compliance requirements govern laser device classifications and topical formulation safety assessments across European markets. Stakeholders must monitor evolving payer coverage decisions for oral systemic therapies versus procedural interventions, as reimbursement differentiation will determine channel investment priorities and patient access trajectories.
Market Dynamics
Topical JAK inhibitors are redirecting clinical trial investment toward autoimmune-driven alopecia areata, compressing development timelines for systemic alternatives while expanding addressable patient populations beyond traditional androgenetic segments.
Growth Catalysts
- FDA Breakthrough Therapy designation:Accelerated approval pathways for baricitinib and ritlecitinib have compressed Phase III-to-launch timelines, incentivizing pipeline investment in oral systemic therapies.
- Telehealth platforms:United States-based direct-to-consumer channels now initiate 40% of new prescription journeys, reducing dermatologist visit bottlenecks and expanding rural access.
- Prostaglandin analogs:Latanoprost and bimatoprost reformulations for follicular stimulation are attracting ophthalmology-to-dermatology technology transfers, diversifying mechanism-of-action portfolios.
Market Restraints
- API concentration in China and India:Minoxidil and finasteride active pharmaceutical ingredient supply depends on fewer than twelve certified manufacturers, creating single-point-of-failure exposure for generic formulators.
- EMA MDR compliance costs:Laser-based hair restoration devices face reclassification as Class IIa medical devices, requiring clinical evidence packages that eliminate marginal market entrants.
- Topical formulation stability:Minoxidil degradation in aqueous solutions limits shelf-life extension, constraining distribution radius and cold-chain economics for emerging market penetration.
Strategic Opportunities
- Underpenetrated African markets:Nigeria and South Africa present whitespace for fixed-dose combination therapies addressing traction alopecia patterns distinct from androgenetic presentations.
- Combination therapy protocols:Simultaneous topical minoxidil plus low-level laser device protocols command premium pricing in cash-pay aesthetic channels, expanding per-patient lifetime value.
- Japan's regenerative medicine framework:PMDA conditional approval pathways for autologous cell therapies enable early commercialization of adipose-derived stromal vascular fraction treatments.
Industry Challenges
- Hair restoration surgeon scarcity:Follicular unit extraction proficiency requires 500-plus case apprenticeship, limiting procedure volume scaling in secondary metropolitan markets.
- Reimbursement code fragmentation:Alopecia areata lacks consistent ICD-10 specificity across United States commercial payers, creating prior authorization friction and prescription abandonment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alopecia Treatment (Hair Loss) Market |
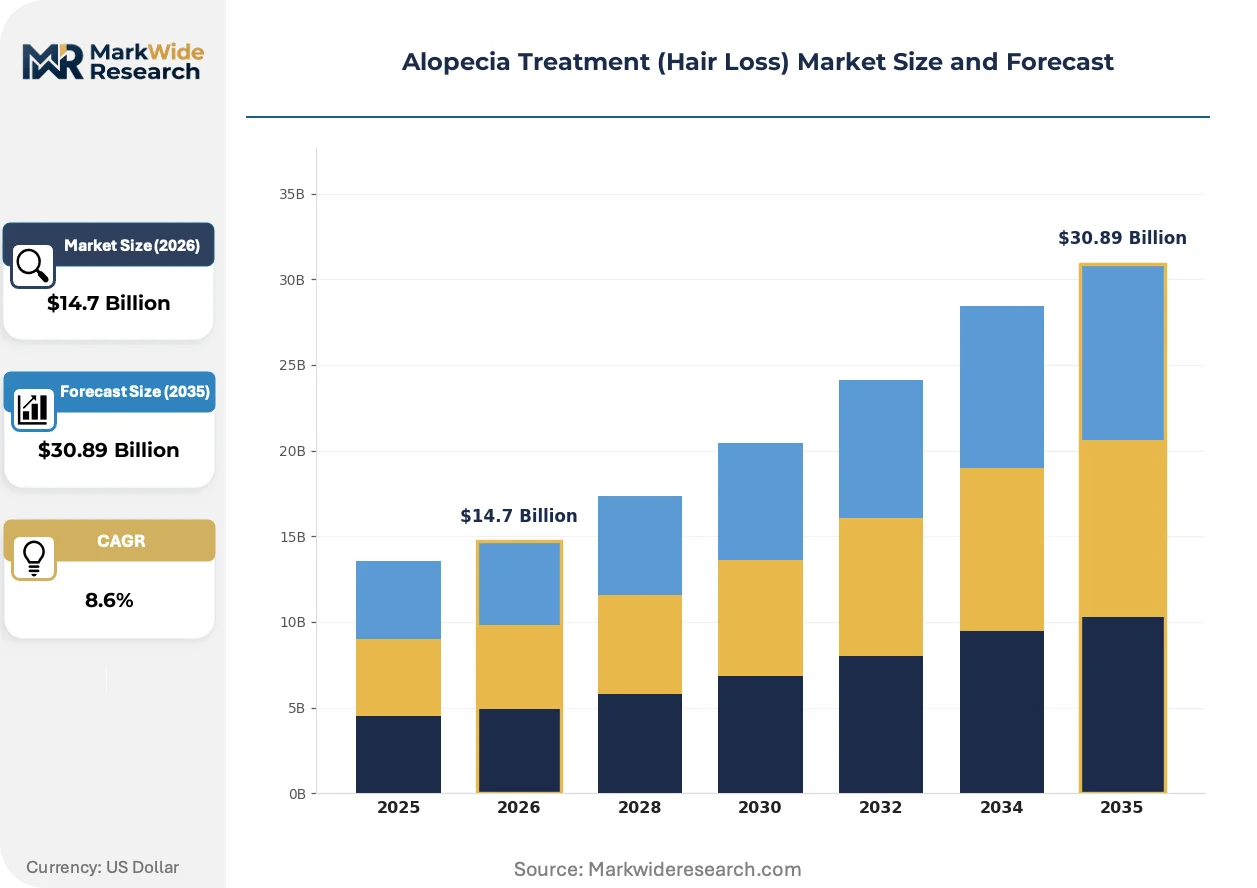
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Topical Solutions, Oral Medications, Surgical Procedures, Light Therapy End User: Dermatology Clinics, Hair Restoration Centers, Home Care, Hospitals Distribution Channel: Online Retail, Direct Sales, Pharmacies, Health & Beauty Stores Gender: Male, Female, Unisex, Non-binary |
| Companies Covered | Cipla Limited, GlaxoSmithKline plc, Merck & Co. Inc., Pfizer Inc., AbbVie Inc., Johnson & Johnson, Dr. Reddy's Laboratories Ltd., Lexington International, Sun Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alopecia Treatment (Hair Loss) Market Strategic Shifts
Device-software convergence and biomarker-guided personalization are fragmenting the traditional one-size-fits-all treatment paradigm, creating tiered value pools based on outcome predictability rather than mechanism alone.
Low-level laser therapy caps is modularizing hardware architecture, enabling dermatology clinics to lease rather than purchase capital equipment. United States aesthetic chains now deploy subscription-based device access, converting fixed costs to variable spend while manufacturers capture recurring revenue streams. This financing innovation is compressing independent clinic equipment procurement cycles from 36 months to 12 months.
REACH compliance deadlines for nanomaterial-containing topical formulations are forcing reformulation of liposomal minoxidil delivery systems. European manufacturers must submit enhanced toxicity dossiers by 2026, advantaging suppliers with existing pharmaceutical-grade nanotechnology capabilities. German and French formulators are responding by acquiring dedicated nanotoxicology testing infrastructure ahead of enforcement.
Patients now demand pre-treatment follicular density mapping using trichoscopy analytics, shifting consultation value toward diagnostic interpretation. Telehealth platforms in the United States are integrating AI-powered hair loss staging tools, displacing in-person trichologist assessments for initial triage. This behavioral shift concentrates high-complexity procedural referrals while commoditizing pharmaceutical prescribing.
Alopecia Treatment (Hair Loss) Market Segmentation
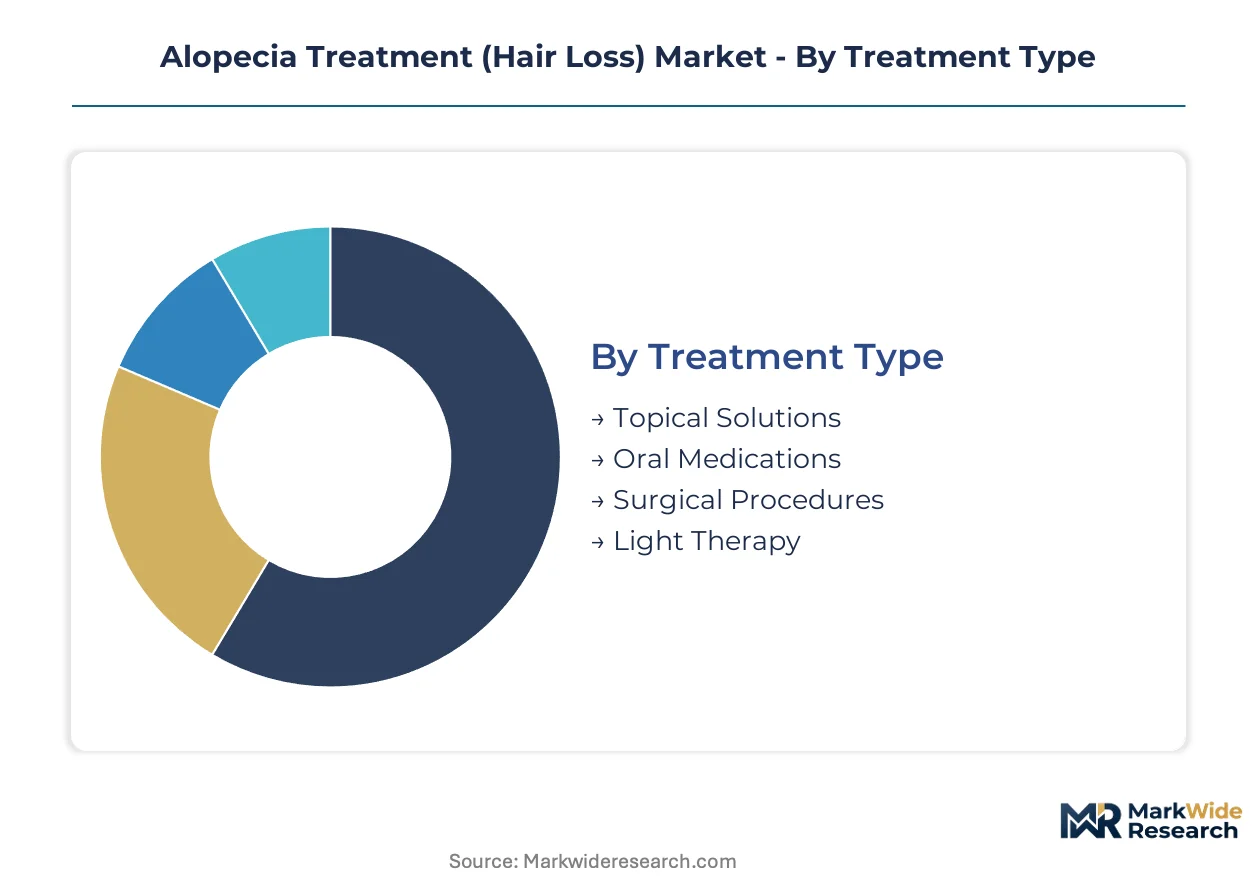
Treatment modality selection in alopecia care determines reimbursement pathways, patient adherence profiles, and manufacturing complexity. Segmentation reveals how channel economics and clinical setting requirements fragment commercial strategy across patient touchpoints.
Treatment Type:
Formulation chemistry and delivery mechanism define regulatory classification and prescriber control levels across intervention categories.
- Topical Solutions:Minoxidil formulations at two percent to five percent concentrations dominate over-the-counter accessibility with aqueous or propylene glycol carriers. United States pharmacy chains capture recurring replenishment demand through shelf placement and direct-to-consumer telehealth bundling. FDA labeling for cosmetic versus drug classification creates formulation stability constraints that limit distribution radius.
- Oral Medications:Finasteride acts as five-alpha-reductase inhibitor with prescription-only status and systemic absorption profiles requiring liver enzyme monitoring. Germany's statutory health insurance funds reimburse oral systemic therapies for androgenetic alopecia under specific diagnostic codes, concentrating demand in dermatologist-supervised channels. EMA pharmacovigilance requirements shape post-market surveillance investment.
- Surgical Procedures:Follicular unit extraction and transplantation command highest per-intervention revenue with specialist-dependent scaling.
- Light Therapy:Low-level laser devices occupy Class IIa medical device classification in Europe with leasing models emerging in United States aesthetic chains.
Mature deployment sits with Topical Solutions. Newer deployment is concentrated in Surgical Procedures.
End User:
Clinical infrastructure investment and patient volume economics determine service delivery concentration across care settings.
- Dermatology Clinics:Board-certified specialists integrate trichoscopy diagnostics with pharmaceutical prescribing and procedural referrals, capturing high-margin combination protocols. United States metropolitan markets show dermatologist-to-population ratios that constrain appointment availability and drive telehealth substitution for initial triage. JAK inhibitor prescribing for alopecia areata concentrates in academic medical center-affiliated practices.
- Hair Restoration Centers:Dedicated surgical facilities achieve volume efficiency through standardized follicular unit extraction workflows and technician-heavy staffing models. Turkey's Istanbul cluster and South Korea's Seoul corridor attract cross-border medical tourism through bundled pricing and hospitality integration. Surgeon apprenticeship requirements limit geographic expansion.
- Home Care:Self-administered topical and device-based treatments expand rural access beyond specialist concentration.
- Hospitals:Oncology-dermatology coordination for chemotherapy-induced alopecia occupies inpatient and infusion center settings.
Volume concentration favors Hair Restoration Centers. Margin expansion is climbing the fastest in Dermatology Clinics.
Distribution Channel:
Patient journey initiation points and purchase authorization requirements fragment channel economics and brand control.
- Online Retail:Amazon and specialized telehealth platforms capture subscription-based replenishment with AI-powered hair loss staging tools displacing initial in-person assessments. United States direct-to-consumer channels now initiate a substantial share of prescription journeys, reducing traditional dermatology visit bottlenecks. Platform algorithms concentrate search visibility for established minoxidil brands.
- Direct Sales:Manufacturer-owned clinics and device leasing programs convert capital expenditure to recurring revenue, compressing independent clinic procurement cycles.
- Pharmacies:Community and chain dispensaries maintain prescription fulfillment with pharmacist counseling on topical application technique.
- Health & Beauty Stores:Sephora and Ulta Beauty shelf placement targets younger demographic segments with aesthetic positioning.
Established volume flows through Pharmacies. Platform-based deployment is gaining share fastest in Online Retail.
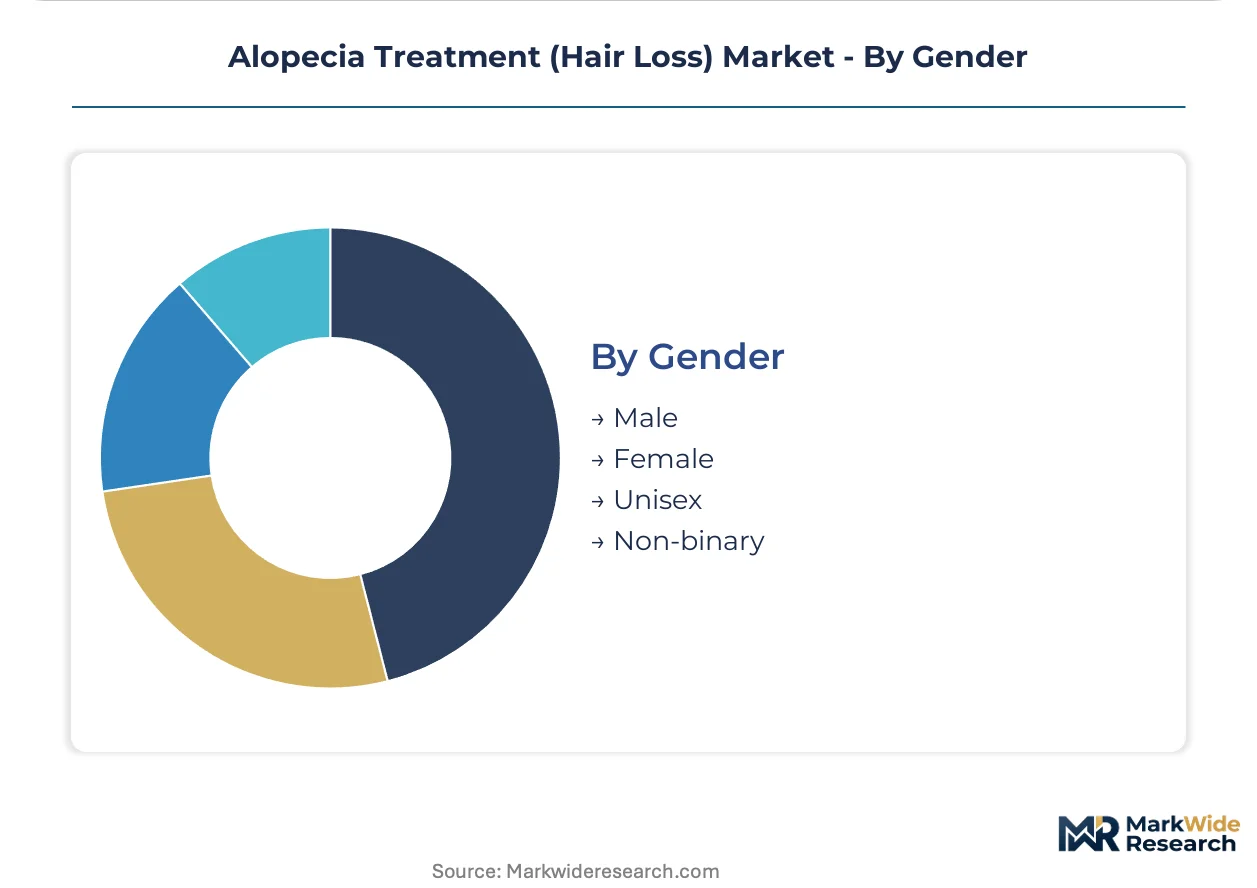
Gender:
Pattern recognition in hair loss presentation and social visibility drives diagnostic coding specificity and marketing segmentation.
- Male:Androgenetic alopecia with Norwood scale progression represents historically dominant addressable population with FDA-approved oral finasteride and topical minoxidil indications. United States direct-to-consumer advertising concentrates on male pattern recognition with celebrity endorsement campaigns. Prescription abandonment rates reflect stigma sensitivity around sexual side effect disclosures.
- Female:Ludwig scale presentations and diffuse hair thinning require distinct diagnostic workup for underlying endocrine or autoimmune etiology. EMA guidance on finasteride teratogenicity restricts prescribing to post-menopausal or contraceptively-managed patients, shaping European market access. Minoxidil foam formulations address cosmetic acceptability concerns.
- Unisex:Gender-neutral marketing and formulation positioning expand addressable population beyond binary segmentation.
- Non-binary:Hormone therapy interaction awareness and inclusive clinical environment design emerge as differentiated service requirements.
Commercial infrastructure centers on Male. Inclusive formulation development is expanding most quickly in Female and Unisex positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient access patterns concentrate treatment demand in high-income markets with established reimbursement pathways and direct-to-consumer infrastructure. Regulatory divergence between FDA breakthrough designations and EMA MDR enforcement is fragmenting product launch sequencing across major economies.
United States
Telehealth platforms now initiate prescription journeys for two-fifths of new patients, compressing dermatology visit bottlenecks in rural and secondary metropolitan markets. FDA breakthrough therapy pathways for oral JAK inhibitors have accelerated commercialization timelines, with baricitinib and ritlecitinib securing priority review. New York and Los Angeles metropolitan areas anchor hair restoration center density, with Istanbul-facing medical tourism brokers maintaining satellite offices in Miami and Dallas.
Germany
Statutory health insurance funds reimburse oral finasteride under specific androgenetic alopecia diagnostic codes, concentrating prescription volume in dermatologist-supervised channels. EMA MDR compliance deadlines for laser-based devices are forcing clinical evidence investments that eliminate marginal market entrants. Berlin and Munich host the highest concentration of trichology-specialized dermatology practices, with Frankfurt serving as the logistics hub for EU-wide distribution of topical formulations.
Japan
PMDA conditional approval pathways for regenerative medicine are enabling early commercialization of autologous cell therapies, including adipose-derived stromal vascular fraction treatments. METI funding for regenerative medicine infrastructure has concentrated clinical trial activity in the Kanto region. Tokyo and Osaka metropolitan areas dominate hair restoration procedure volume, with South Korea-facing medical tourism flows transiting through Fukuoka.
India
CDSCO accelerated approval pathways for generic minoxidil and finasteride formulations are expanding over-the-counter accessibility in tier-1 and tier-2 cities. API manufacturing concentration in Hyderabad and Ahmedabad creates supply security advantages for domestic formulators. Mumbai and Delhi-NCR anchor hair restoration center expansion, with Bengaluru emerging as the telehealth platform development hub for South Asian markets.
Brazil
ANVISA's streamlined registration for topical hair loss formulations is attracting multinational portfolio localization investments. Private health insurance coverage for surgical hair restoration remains limited, concentrating procedure demand in cash-pay aesthetic channels. São Paulo anchors specialist surgeon concentration, with Rio de Janeiro and Belo Horizonte serving as secondary hubs for follicular unit extraction services.
Alopecia Treatment (Hair Loss) Market Competitive Environment
Portfolio diversification dominates the current landscape as incumbents expand beyond single-mechanism offerings into combination protocols and device-drug bundles. The market structure fragments across three tiers: multinational pharmaceutical conglomerates with prescription portfolios, specialized dermatology device manufacturers with leasing-based revenue models, and generic API-integrated formulators competing on cost-stable supply. Strategic archetypes include backward-integrated API producers, telehealth-platform-integrated direct-to-consumer marketers, and procedure-volume-scaling surgical center operators. M&A activity concentrates on JAK inhibitor pipeline acquisitions and telehealth platform integration, while capacity expansion focuses on nanotoxicology-compliant European formulation facilities.
Among India-based API-integrated formulators, Cipla Limited and Dr. Reddy's Laboratories Ltd. occupy positions emphasizing cost-stable oral medication supply. Merck & Co. Inc. and Johnson & Johnson exemplify the multinational incumbent archetype, with the former anchoring prescription hair loss therapy portfolios and the latter competing in over-the-counter topical segments. These companies represent distinct strategic postures: backward integration versus brand equity accumulation, and pharmacy shelf dominance versus clinical data accumulation.
| Leading Market Players |
|---|
| Cipla Limited |
| GlaxoSmithKline plc |
| Merck & Co. Inc. |
| Pfizer Inc. |
| AbbVie Inc. |
| Johnson & Johnson |
| Dr. Reddy's Laboratories Ltd. |
| Lexington International |
| Sun Pharmaceutical Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Prescription-orbit versus over-the-counter divergence splits pricing power along regulatory classification lines, with FDA-monitored oral therapies commanding subscription-like recurring revenue while commodity topical solutions compete on pharmacy shelf turnover and telehealth bundling economics. This bifurcation feeds directly into supply chain architecture: high-margin prescription portfolios justify captive API production and cold-chain distribution investments, whereas mass-market topicals optimize for high-volume, short-radius fulfillment from regional distribution hubs.
Pricing Analysis
Volume concentrates in mass-market topical solutions while margins pool in prescription oral medications and surgical procedures. Three-tier pricing structure across premium JAK inhibitor therapies, standard finasteride prescriptions, and economy generic minoxidil segments reflects brand data accumulation versus commodity substitution pressure. Pricing pressure stems from telehealth platform formulary compression and direct-to-consumer discounting in the United States. Price sensitivity peaks in self-pay home care segments and diminishes in cash-pay aesthetic channels where outcome visibility drives willingness to pay.
Supply Chain Analysis
Returns and expiry management for temperature-sensitive topical formulations create reverse-logistics complexity that favors regional formulation hubs over centralized production. API supply draws from India, China, and Germany for minoxidil, finasteride, and prostaglandin analog precursors respectively. Raw material dependencies center on piperidinyl pyrimidine intermediates, 5-alpha-reductase inhibitor precursors, and pharmaceutical-grade propylene glycol carriers. Single-source vulnerability concentrates in certified API manufacturers for generic oral medications. Distribution runs through pharmacy chains, telehealth platform fulfillment centers, and direct-to-clinic device leasing programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into API production and forward integration into telehealth prescribing platforms defines the current vertical-integration race, with cost-stable supply and patient journey capture as the contested levers.
For Market Incumbents: Anticipate JAK inhibitor pipeline commoditization by securing exclusive API supply agreements and expanding label indications into pediatric alopecia areata populations. Defensive moves should concentrate on trichoscopy diagnostic platform integration and hair restoration center franchise networks to lock in procedural referral flows. Regulatory data exclusivity expiration for finasteride poses the primary margin threat. For New Entrants and Emerging Players: Enter via fixed-dose combination topical therapies addressing traction alopecia patterns in Nigeria and South Africa, where diagnostic infrastructure gaps favor simplified prescribing protocols. The most penetrable whitespace sits in telehealth-integrated device-therapy bundles for rural United States markets. Go-to-market execution should leverage subscription-based replenishment models with AI-powered hair loss staging as the patient acquisition hook. For Investors and Strategic Acquirers: Re-rating potential sits with nanotoxicology-compliant European formulators given REACH enforcement deadlines and liposomal delivery system acquisition demand. Long-term viability favors targets with existing pharmaceutical-grade nanotechnology capabilities and German or French manufacturing footprints. The signal to watch is CDSCO accelerated approval pathway expansion for generic penetration in tier-2 Indian cities.| Strategic Initiative | Industry Significance |
|---|---|
| API Backward Integration | Cipla and Dr. Reddy's captive production of finasteride intermediates insulates margin from raw material volatility. |
| Telehealth Platform Acquisition | United States direct-to-consumer channels now initiate two-fifths of prescription journeys, compressing traditional dermatology bottlenecks. |
| European Nanotoxicology Infrastructure | German and French formulators acquiring dedicated testing capabilities ahead of REACH 2026 enforcement deadlines secure formulation continuity. |
| JAK Inhibitor Pipeline Licensing | FDA breakthrough therapy designations for baricitinib and ritlecitinib validate autoimmune-driven alopecia areata as expansion category. |
| Device Leasing Model Rollout | Low-level laser therapy caps deployed via subscription financing convert independent clinic procurement cycles from 36 months to 12 months. |
Study Parameters
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone for pipeline and approval timeline validation. Primary interviews with dermatology clinic operators, hair restoration surgeons, pharmaceutical regulatory affairs leads, and telehealth platform executives supplied channel economics and prescribing behavior intelligence. Customs records and formulary databases anchored volume estimation. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation converged on segment sizing.
Historical trendline analysis across approved therapy launches and procedural volume trajectories informed growth rate derivation. Segmentation modeling incorporated treatment modality, end-user setting, distribution channel, and gender-specific pattern presentation across the projection horizon. CAGR derivation rested on patent cliff timing, regulatory pathway acceleration, and reimbursement policy shifts. Forecast inputs included JAK inhibitor label expansion probability and telehealth platform penetration curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA adverse event profile revisions or EMA MDR enforcement acceleration. Forecasts reflect documented assumptions regarding payer coverage continuity and API supply concentration stability. Material deviation in CDSCO generic approval velocity or REACH nanomaterial compliance cost inflation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Scar Treatment Market
Dermatology
Telogen Effluvium Treatment Market
Dermatology
Dermabrasion Market
Dermatology
Seborrheic Keratosis Market
Dermatology
Skin Hyperpigmentation Treatment Market
Dermatology
Global Ozone Therapy in Dermatology Market
Dermatology
Dermabrasion and Micro Needling Market
Dermatology
Global Dermatological Therapeutics Market
Dermatology
Porokeratosis Treatment Market
Dermatology
Hyperpigmentation Disorder Treatment Market
Dermatology
Global Dermatitis Herpetiformis Market
Dermatology
Japan Scar Treatment Market
Dermatology
Atopic Dermatitis Therapeutics Market
Dermatology
Dermatology Diagnostic Devices and Therapeutics Market
Dermatology
Homecare Dermatology Energy-Based Devices Market
Dermatology
Atopic Dermatitis Treatment Market