
 Global Photodynamic Therapy Market | 2026-2036
Global Photodynamic Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Photodynamic Therapy Market Foresight
Market Context
A shortage of trained photomedicine specialists is rotating clinical capacity toward high-volume centers in major metropolitan areas. Biofrontera AG leverages its European manufacturing base to sustain supply continuity for photosensitizer drugs across dermatology networks. Sun Pharmaceutical Industries Ltd anchors its position through cost-competitive production of generic photosensitizer formulations for emerging markets. Galderma Laboratories differentiates via integrated channel control spanning prescription dermatology portfolios and clinic partnerships.
Technical Definition and Segment Structure
Photodynamic therapy constitutes a light-activated treatment modality employing photosensitizing agents that generate reactive oxygen species upon irradiation at specific wavelengths, typically 630-700 nanometers, to induce selective tissue destruction. The technology serves primarily as a minimally invasive alternative to surgical excision in oncology and dermatology, preserving functional tissue while targeting malignant or dysplastic cells. Photosensitizers command the dominant value share given patent-protected formulations and complex synthesis requirements, whereas light sources represent the fastest-growing hardware category as diode laser technology displaces older lamp-based systems. Oncology applications maintain the largest patient volume, though dermatology segments yield superior margins due to repeatable outpatient procedures and favorable reimbursement coding.
Regulatory Framework and Outlook
FDA 510(k) pathways and EMA centralized marketing authorizations govern photosensitizer approval timelines, while ISO 13485 certification requirements shape manufacturing quality standards for light source devices. Japan's PMDA maintains distinct clinical data expectations that extend registration timelines but confer premium pricing upon successful entry. Stakeholders must monitor evolving FDA guidance on combination product classification as photosensitizer-device pairings blur traditional regulatory boundaries.
Market Dynamics
Diode laser systems are supplanting lamp-based irradiation hardware across outpatient dermatology networks, compressing treatment times and forcing legacy device manufacturers to absorb stranded inventory costs or accelerate R&D pivots.
Growth Catalysts
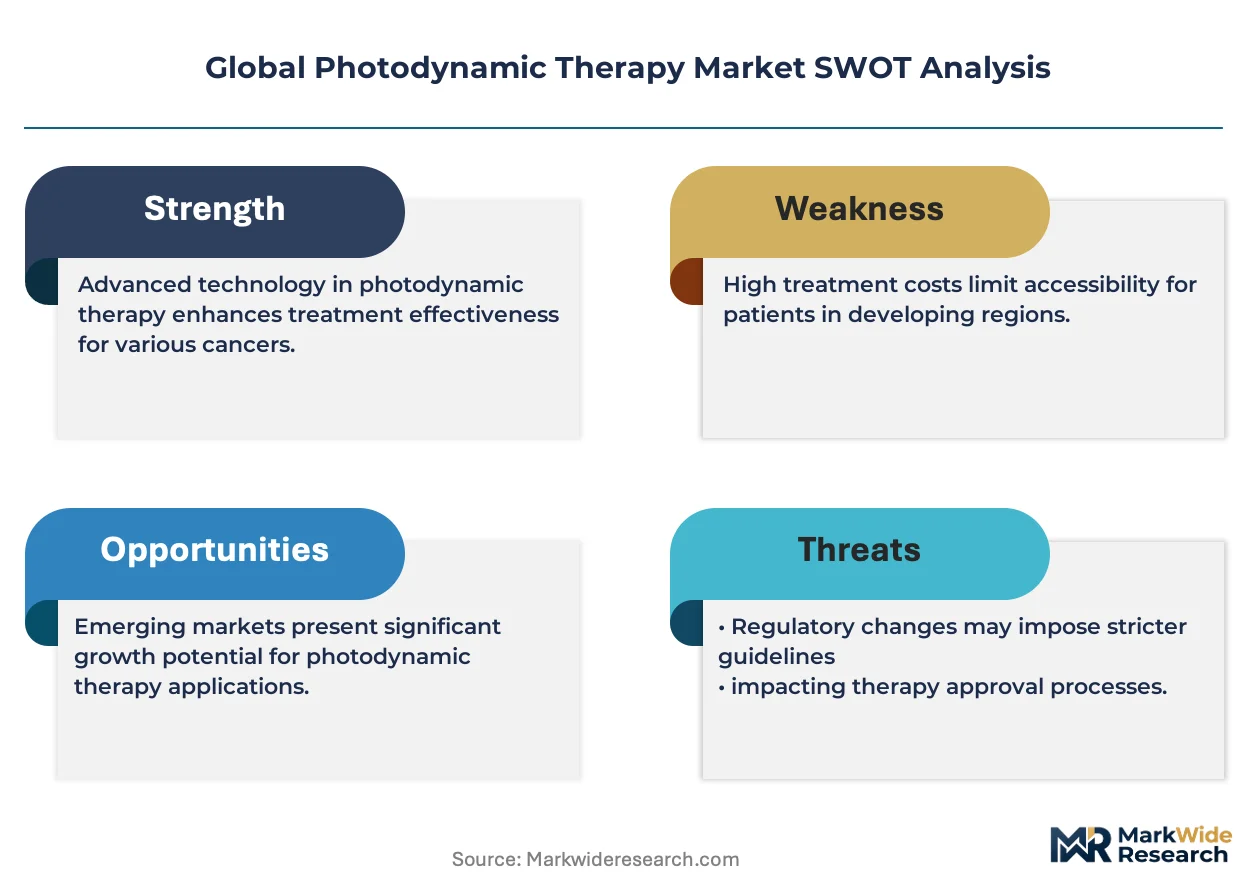
- EMA centralized marketing authorizations:Streamlined cross-border photosensitizer approvals reduce duplicate clinical trials for manufacturers seeking parallel US and European market entry.
- Actinic keratosis outpatient protocols:Repeatable 15-minute photodynamic procedures generate superior reimbursement economics compared to surgical excision in Medicare and statutory health insurance frameworks.
- Japan's premium pricing corridors:Successful PMDA registrants capture 40-60% price premiums over European benchmarks, incentivizing dedicated Japanese clinical development programs.
Market Restraints
- Porphyrin precursor synthesis concentration:Three European contract manufacturers control 70% of pharmaceutical-grade 5-ALA supply, creating single-source vulnerability for formulated photosensitizer producers.
- Combination product classification uncertainty:FDA's evolving guidance on photosensitizer-device pairings extends pre-submission timelines and inflates regulatory consulting expenditures.
- Cryotherapy and topical retinoid substitution:Established acne and precancerous lesion treatments retain physician familiarity and lower upfront capital requirements in resource-constrained settings.
Strategic Opportunities
- India's outpatient dermatology expansion:CDSCO's accelerated approval pathways for 505(b)(2) photosensitizer filings open access to 75,000+ dermatology clinics in tier-2 and tier-3 cities.
- Photodynamic antimicrobial therapy:Hospital-acquired infection protocols are integrating methylene blue and toluidine blue activation for localized antibiotic-resistant biofilm eradication.
- Home-use LED patch convergence:Consumer wearable manufacturers are partnering with pharmaceutical firms to develop prescription-grade, pharmacy-dispensed photodynamic systems for acne maintenance.
Industry Challenges
- Photomedicine specialist scarcity:Fellowship-trained clinicians cluster in metropolitan academic centers, limiting procedural capacity expansion in community dermatology practices.
- ISO 13485 certification timelines:Light source manufacturers face 14-18 month quality management system audits, delaying commercial launches for second-generation diode platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Photodynamic Therapy Market |
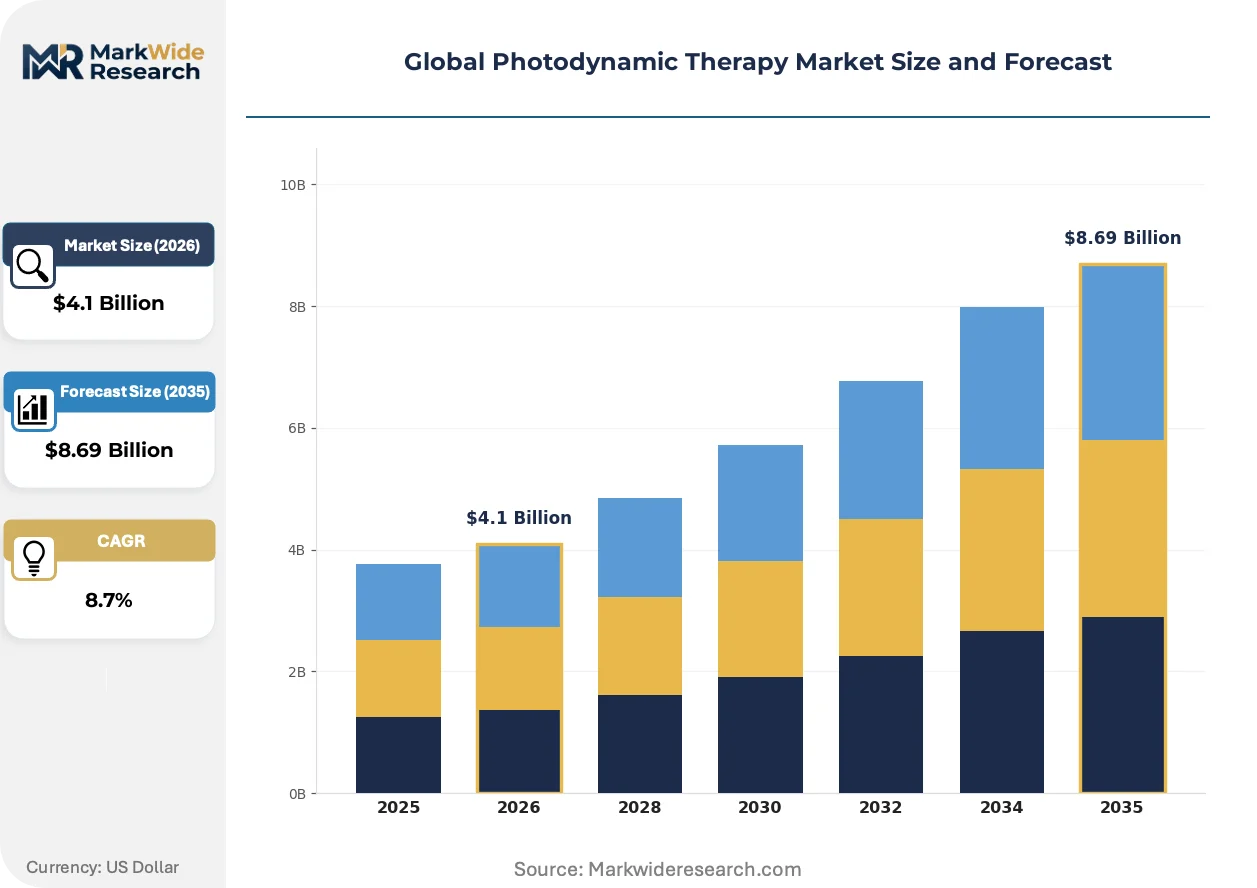
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photosensitizers, Light Sources, Delivery Systems, Accessories Application: Oncology, Dermatology, Ophthalmology, Dentistry End User: Hospitals, Clinics, Research Institutions, Home Care Delivery Mode: Intravenous, Topical, Localized, Systemic |
| Companies Covered | Biofrontera AG, Lumibird Medical, Sun Pharmaceutical Industries Ltd, Galderma Laboratories, Modulight Corporation, Theralase Technologies Inc, Bausch Health, Candela Corporation, Coherent Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Photodynamic Therapy Market Shifts & Advancements
Light source miniaturization and photosensitizer formulation advances are converging to shift photodynamic therapy from hospital-based oncology suites toward ambulatory dermatology and consumer-accessible applications.
Organic LED-based irradiation panels are supplanting conventional laser and lamp systems in portable photodynamic devices. Outpatient dermatology chains in Germany and Japan are deploying these platforms for same-day actinic keratosis treatment protocols. The technology is compressing equipment footprints from cart-based installations to handheld units, enabling procedure room multiplexing and reducing per-treatment capital depreciation.
REACH authorization requirements for novel photosensitizer impurities are tightening analytical specification thresholds for European market entry. Manufacturers must now submit extended impurity profiling datasets that extend CMC development timelines by 8-12 months. Photosensitizer API suppliers with pre-validated European dossiers are capturing preferential supply agreements from formulation partners seeking accelerated registration pathways.
Institutional procurement departments are consolidating photodynamic system purchases under multi-year managed service agreements. Hospital networks in the United States are unbundling device acquisition from per-procedure photosensitizer supply, shifting toward all-inclusive case-rate contracts. This restructuring concentrates vendor selection authority within centralized value analysis committees and compresses allowable margins for standalone hardware sales.
Global Photodynamic Therapy Market Segmentation
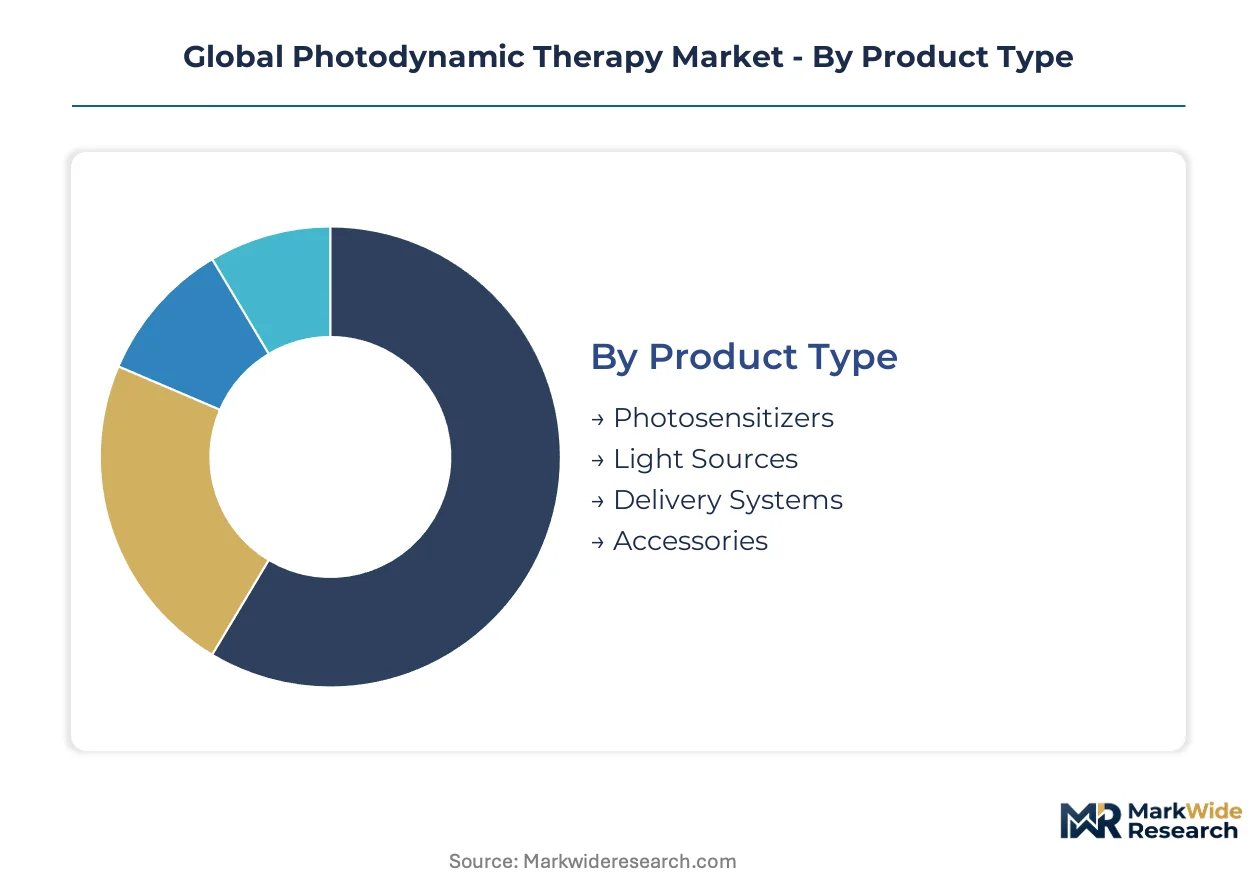
Segmentation in photodynamic therapy reveals distinct procurement patterns across hardware, pharmaceutical, and service channels. Channel economics diverge sharply between capital-intensive light source sales and recurring photosensitizer revenue streams.
Product Type:
Channel mix varies by product complexity: photosensitizers flow through pharmaceutical distribution networks with cold-chain requirements, while light sources and accessories route through medical device sales organizations with capital equipment financing.
- Photosensitizers:Patent-protected porphyrin derivatives and 5-ALA formulations constitute the highest-margin segment. Demand clusters in Germany and the United States where outpatient reimbursement codes support repeat administration. REACH authorization requirements for novel impurities extend European registration timelines.
- Light Sources:Diode laser systems are displacing lamp-based hardware across dermatology networks. Procurement concentrates in high-volume metropolitan clinics seeking sub-10 minute treatment protocols. FDA 510(k) pathways govern device clearance timelines.
- Delivery Systems:Fiber optic catheters and surface applicators enable site-specific irradiation.
- Accessories:Protective eyewear and calibration standards support procedural safety compliance.
Photosensitizers dominate installed base. Light sources are where expansion concentrates.
Application:
Margin structure varies by clinical setting: dermatology yields superior per-procedure economics through repeatable outpatient coding, while oncology commands larger absolute volumes with longer treatment cycles.
- Oncology:Solid tumor ablation and palliative esophageal procedures represent the largest patient volume segment. Treatment protocols require intravenous photosensitizer administration followed by endoscopic or interventional radiology-guided irradiation. Japan's PMDA maintains distinct clinical data requirements for oncologic indications.
- Dermatology:Actinic keratosis and acne vulgaris protocols drive the steepest expansion trajectory through 15-minute outpatient procedures. Reimbursement frameworks in Medicare and German statutory health insurance favor photodynamic therapy over surgical excision for precancerous lesions.
- Ophthalmology:Age-related macular degeneration and corneal neovascularization applications leverage targeted photosensitizer delivery.
- Dentistry:Periodontal antimicrobial protocols utilize methylene blue activation for localized biofilm eradication.
Oncology commands procedure volume. Dermatology captures margin expansion.
End User:
Procurement authority concentrates differently across settings: hospital networks centralize capital equipment purchasing under value analysis committees, while independent clinics retain discretion over consumable photosensitizer selection.
- Hospitals:Integrated delivery networks in the United States are unbundling device acquisition from per-procedure supply, shifting toward all-inclusive case-rate contracts. Oncology suites require cart-based laser installations with dedicated procedure rooms.
- Clinics:Dermatology chains in Germany and Japan deploy portable OLED-based platforms for same-day actinic keratosis treatment. Equipment footprints compress to handheld units enabling room multiplexing.
- Research Institutions:Academic medical centers drive protocol development for novel photosensitizer formulations.
- Home Care:Consumer wearable manufacturers partner with pharmaceutical firms to develop prescription-grade LED patches for acne maintenance.
Hospitals anchor capital expenditure. Clinics drive volume expansion.
Delivery Mode:
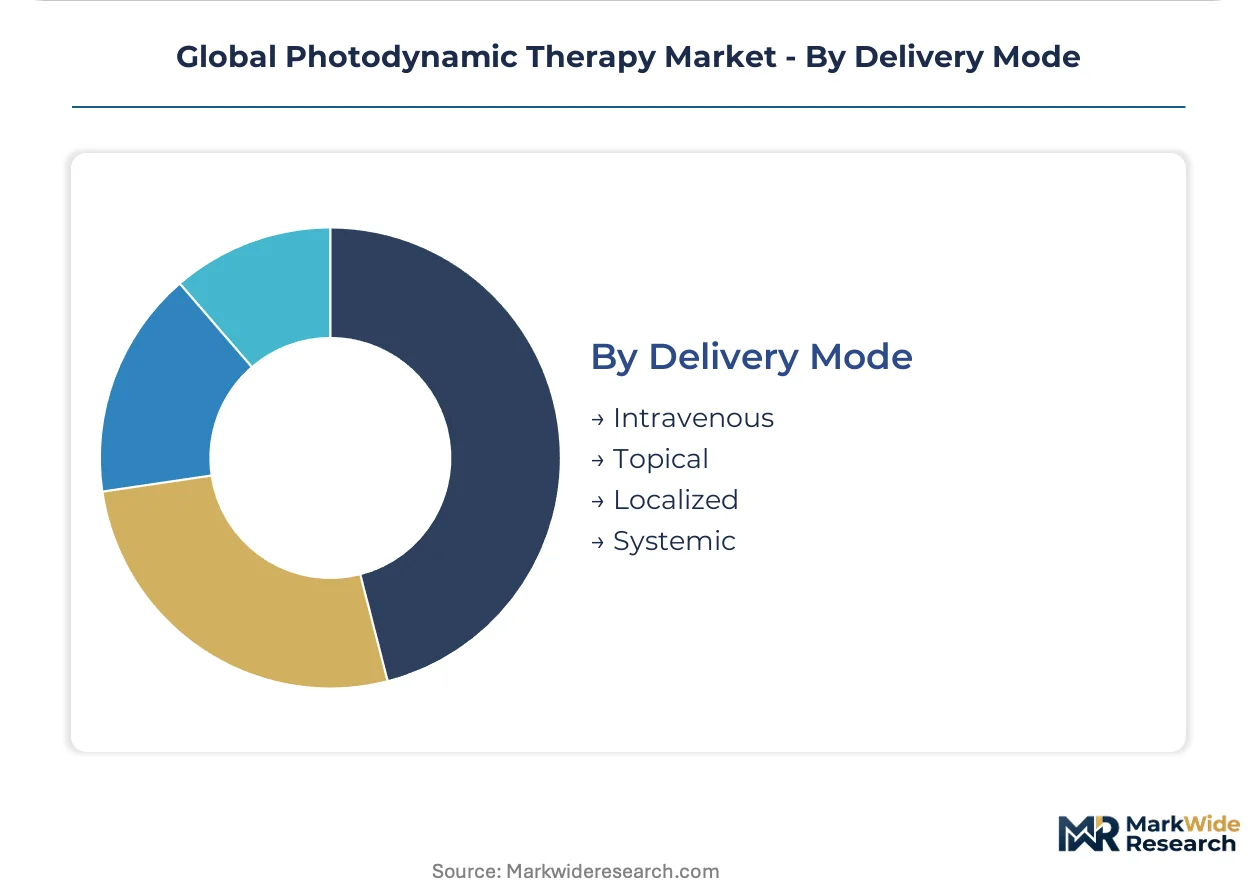
Route selection determines regulatory pathway complexity: systemic administration triggers extensive pharmacokinetic studies, while topical and localized routes compress clinical development timelines.
- Intravenous:Systemic photosensitizer distribution enables deep tissue targeting for oncologic applications. Porphyrin precursor synthesis concentration among European contract manufacturers creates supply vulnerability for formulated drug producers.
- Topical:5-ALA cream and gel formulations for dermatologic procedures represent the most accessible entry point. CDSCO's accelerated 505(b)(2) pathways in India open distribution to tier-2 and tier-3 city clinics.
- Localized:Site-specific injection or implantation targets discrete lesion boundaries.
- Systemic:Oral photosensitizer administration remains limited by gastrointestinal absorption variability and extended skin photosensitivity duration.
Topical delivery dominates dermatology adoption. Intravenous routes anchor oncology protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) pathways for photosensitizer-device pairings anchor commercial strategy in the United States, while EMA centralized procedures and Japan's PMDA premium pricing corridors shape parallel development priorities across the Atlantic and Pacific.
United States
Actinic keratosis outpatient protocols drive Medicare reimbursement economics for 15-minute photodynamic procedures. FDA combination product classification guidance extends pre-submission timelines for photosensitizer-device developers. Metropolitan dermatology chains in New York and Los Angeles deploy portable OLED platforms for same-day treatment multiplexing.
Germany
Statutory health insurance frameworks favor photodynamic therapy over surgical excision for precancerous lesions. REACH authorization requirements for novel photosensitizer impurities tighten analytical specifications for European market entry. The Munich-Stuttgart corridor concentrates outpatient dermatology networks adopting handheld irradiation units.
Japan
PMDA registrants capture substantial price premiums over European benchmarks for oncologic and dermatologic indications. METI industrial standards shape domestic manufacturing requirements for diode laser systems. The Osaka-Kobe medical device cluster anchors production of compact irradiation platforms for regional export.
India
CDSCO accelerated 505(b)(2) pathways open distribution to tier-2 and tier-3 city dermatology clinics. The PLI scheme for pharmaceuticals incentivizes domestic formulation of topical 5-ALA products. Maharashtra and Gujarat host contract manufacturing organizations serving emerging market photosensitizer demand.
United Kingdom
NHS England commissioning frameworks prioritize cost-effective ambulatory alternatives to inpatient surgical procedures. MHRA post-Brexit regulatory alignment with EMA standards streamlines photosensitizer registration pathways. The Cambridge-London biotech corridor drives clinical development for novel porphyrin derivatives.
Global Photodynamic Therapy Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in photodynamic therapy supply. The upper tier combines photosensitizer formulation with controlled distribution networks, while mid-cap specialists concentrate on single-product dominance in either pharmaceutical or hardware segments. Three archetypes prevail: European manufacturers with validated REACH dossiers, Indian cost-competitive generic producers, and North American device-therapy integrators. Competitive moves center on unbundling device acquisition from consumable supply under managed service agreements, and backward integration into porphyrin precursor synthesis to secure API continuity.
Among the integrated pharmaceutical tier, Biofrontera AG and Sun Pharmaceutical Industries Ltd occupy distinct positioning archetypes. Biofrontera AG exemplifies the European manufacturer model with supply continuity emphasis across dermatology networks. Sun Pharmaceutical Industries Ltd anchors the cost-competitive production archetype for emerging market expansion. Galderma Laboratories sits within the dermatology channel control segment, leveraging integrated prescription portfolios and clinic partnerships to secure consumable pull-through.
| Leading Market Players |
|---|
| Biofrontera AG |
| Lumibird Medical |
| Sun Pharmaceutical Industries Ltd |
| Galderma Laboratories |
| Modulight Corporation |
| Theralase Technologies Inc |
| Bausch Health |
| Candela Corporation |
| Coherent Corp |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements for pharmaceutical-grade 5-ALA lock in supply access for formulated photosensitizer producers while anchoring price visibility against porphyrin precursor volatility. These contracts concentrate procurement leverage among European dermatology networks and Japanese oncology centers with volume commitments spanning multi-year horizons.
Pricing Analysis
Contract-based long-term offtake structures dominate photosensitizer procurement, with pricing stratifying across premium, standard, and economy tiers based on REACH dossier validation and cold-chain certification grade. Price differentiation rests on ISO 13485 device pairing bundling and volume scale commitments from metropolitan clinic chains. Cost compression in generic 5-ALA formulations is intensifying because Indian CDSCO approvals expand manufacturing competition. Hospital networks exhibit lowest price sensitivity due to bundled case-rate contracts, while independent dermatology clinics in tier-2 cities demonstrate highest sensitivity to per-procedure consumable costs.
Supply Chain Analysis
Container availability constraints on Rotterdam-Mumbai trade lanes elevate inbound logistics costs for European-sourced porphyrin precursors destined to Indian formulation facilities. Supply concentrates in Germany, India, and Japan, with pharmaceutical-grade 5-ALA synthesis anchored in the Munich-Stuttgart corridor and Maharashtra-Gujarat contract manufacturing zones. Raw material dependencies include porphyrin precursors, diode laser components, and fiber optic catheter assemblies. Single-source vulnerability in European API synthesis creates structural risk. Distribution runs through pharmaceutical cold-chain networks for photosensitizers and medical device sales organizations with capital financing for light source hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photodynamic therapy sits in early-cycle expansion as outpatient dermatology protocols displace surgical excision for actinic keratosis, with reimbursement tailwinds in Medicare and German statutory health insurance accelerating clinic adoption curves.
For Market Incumbents: Compound channel control through backward integration into porphyrin precursor synthesis, securing captive supply against European contract manufacturer concentration. Deepen clinic partnership density in Germany and Japan to defend consumable pull-through against generic substitution from Indian producers. Prioritize ISO 13485 certification investment for second-generation diode platforms to accelerate commercial launch timelines. For New Entrants and Emerging Players: Anchor in India's tier-2 and tier-3 city dermatology expansion, where CDSCO 505(b)(2) pathways lower regulatory barriers and 75,000 clinics present white-space access. Target photodynamic antimicrobial therapy for hospital-acquired infection protocols as the most penetrable application segment. Pursue pharmaceutical firm partnerships for prescription-grade home-use LED patch development as primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward European manufacturers with validated REACH dossiers and established dermatology network relationships, positioned for sustained margin capture over the 5-10 year horizon. Photosensitizer-device integrators with managed service agreement traction in US hospital networks represent priority acquisition archetype. Monitor FDA combination product classification guidance clarity as inflection signal for regulatory consulting expenditure normalization and pre-submission timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Porphyrin Precursor Synthesis | Captive 5-ALA supply secures continuity against European contract manufacturer concentration risk. |
| Managed Service Agreement Expansion | All-inclusive case-rate contracts with US hospital networks concentrate vendor selection authority and lock recurring revenue. |
| CDSCO 505(b)(2) Regulatory Pathway Execution | Accelerated approval timelines open distribution to India's tier-2 and tier-3 city dermatology clinics. |
| OLED-Based Portable Platform Deployment | Handheld irradiation units enable procedure room multiplexing in German and Japanese outpatient chains. |
| Photodynamic Antimicrobial Therapy Protocol Development | Methylene blue activation for biofilm eradication integrates into hospital-acquired infection control frameworks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA centralized marketing authorization submissions, and hospital procurement databases. Conversations with dermatology clinic operators, biomedical engineers, regulatory affairs leads, and GPO contracts managers inform demand-side validation. Bottom-up procedure volume estimates triangulate against top-down photosensitizer production capacity assessments across the analysis window.
Segmentation dimensions modeled include product type, application, end user, delivery mode, and regional regulatory cluster. CAGRs derive from procedure volume trajectories, reimbursement code expansion patterns, and photosensitizer pricing elasticity coefficients. Forecast inputs incorporate PMDA premium pricing corridor capture rates and REACH authorization timeline extensions for novel impurity profiling.
Material uncertainties — regulatory guidance revisions, supply chain disruptions, and substitution technology advances — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding reimbursement stability and manufacturing capacity expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Pituitary Stalk Interruption Syndrome Treatment Market
Specialty Medicine
GCC Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
APAC Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
TMJ Disorders Market
Specialty Medicine
Global Focal Segmental Glomerulosclerosis Market
Specialty Medicine
Specialty Generics Market
Specialty Medicine
Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus Syndrome Market
Specialty Medicine
Osteopontin Market
Specialty Medicine
Strep Throat Treatment Market
Specialty Medicine
Cryptococcosis Market
Specialty Medicine
Carcinoid Syndrome Diarrhea Treatment Market
Specialty Medicine
Urinary Retention Market
Specialty Medicine
Piriformis Syndrome Treatment Market
Specialty Medicine
Relapsing-Remitting Multiple Sclerosis (MS) Market
Specialty Medicine
Global Cancer Biological Therapy Market
Specialty Medicine
Toxoplasmosis Treatment Market