
 Intestine (Small) Cancer Therapeutics Market | 2026-2036
Intestine (Small) Cancer Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Intestine (Small) Cancer Therapeutics Market Foresight
FDA's accelerated approval pathway is decoupling traditional phase-three requirements from commercial launch timelines, lowering capital barriers for novel small intestine cancer agents. Pfizer Inc leverages its oncology infrastructure to sustain clinical trial density across rare gastrointestinal indications. Bristol-Myers Squibb Company anchors its immuno-oncology portfolio in checkpoint inhibitor combinations that compete directly in this underserved histology.
Intestine (small) cancer therapeutics comprise pharmaceutical interventions targeting malignant neoplasms of the duodenum, jejunum, and ileum, encompassing cytotoxic agents, monoclonal antibodies, kinase inhibitors, and immune modulators administered via oral, intravenous, or subcutaneous routes to inhibit tumor proliferation, angiogenesis, or immune evasion in neuroendocrine carcinomas, adenocarcinomas, and sarcomas of the small bowel. Chemotherapy retains the largest patient volume share while immunotherapy captures the fastest growth trajectory as PD-1/PD-L1 inhibitors demonstrate durable responses in MSI-high subsets. Targeted therapy concentrates margin pools where biomarker-selected populations command premium positioning against standard-of-care regimens.
The FDA, EMA, and NMPA each enforce distinct evidentiary standards for orphan oncology indications, with the FDA's breakthrough therapy designation creating the most rapid commercialization corridor and China's NMPA reforming priority review to accelerate innovative drug access. These regulatory divergences force developers to architect parallel submission strategies rather than sequential geographic rollouts. Stakeholders must monitor how real-world evidence requirements evolve across agencies to determine where post-approval commitment burdens will reshape lifecycle economics.
Market Dynamics
The FDA's accelerated approval pathway is compressing phase-three requirements into earlier commercial launch windows, enabling novel small intestine cancer agents to reach prescribers before traditional confirmatory trials conclude. This regulatory decoupling is reshaping capital deployment timelines across oncology portfolios.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA's expedited review framework shortens development cycles for MSI-high adenocarcinoma subsets, reducing time-to-market for molecularly guided regimens by bypassing conventional endpoint requirements.
- Academic Medical Center Density:NCI-designated cancer centers in the United States concentrate prescribing volume for rare gastrointestinal malignancies, creating clustered adoption corridors for novel immunotherapy combinations.
- Companion Diagnostic Convergence:Liquid biopsy platforms enabling real-time biomarker detection are expanding eligible patient pools for targeted kinase inhibitors across neuroendocrine carcinoma subtypes.
Market Restraints
- Orphan Indication Economics:Small patient populations across duodenal, jejunal, and ileal malignancies limit trial enrollment velocity, stretching fixed clinical development costs across fewer evaluable subjects.
- Reimbursement Compression:Medicare's parallel pathway review for breakthrough therapies creates pricing uncertainty during provisional coverage periods, constraining revenue recognition for newly approved agents.
- Histological Heterogeneity:Diverse tumor microenvironments across small bowel adenocarcinomas, sarcomas, and neuroendocrine carcinomas fragment addressable markets, complicating pivotal trial design.
Strategic Opportunities
- China's Priority Review Reform:The NMPA's accelerated innovative drug access pathway enables parallel submission strategies, reducing sequential geographic rollout delays for developers with global portfolios.
- Biomarker-Selected Populations:PD-L1 expression and tumor mutational burden thresholds create premium positioning opportunities against standard cytotoxic regimens in defined molecular subsets.
- Real-World Evidence Integration:Post-approval commitment structures leveraging electronic health record networks are enabling label expansion without additional randomized controlled trials.
Industry Challenges
- Specialized Oncology Talent Scarcity:Principal investigators with small intestine malignancy expertise concentrate at NCI-designated centers, creating site activation bottlenecks for multi-regional trials.
- Cross-Agency Evidence Divergence:The FDA, EMA, and NMPA maintain non-aligned standards for surrogate endpoint acceptability, forcing redundant clinical package construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intestine (Small) Cancer Therapeutics Market |
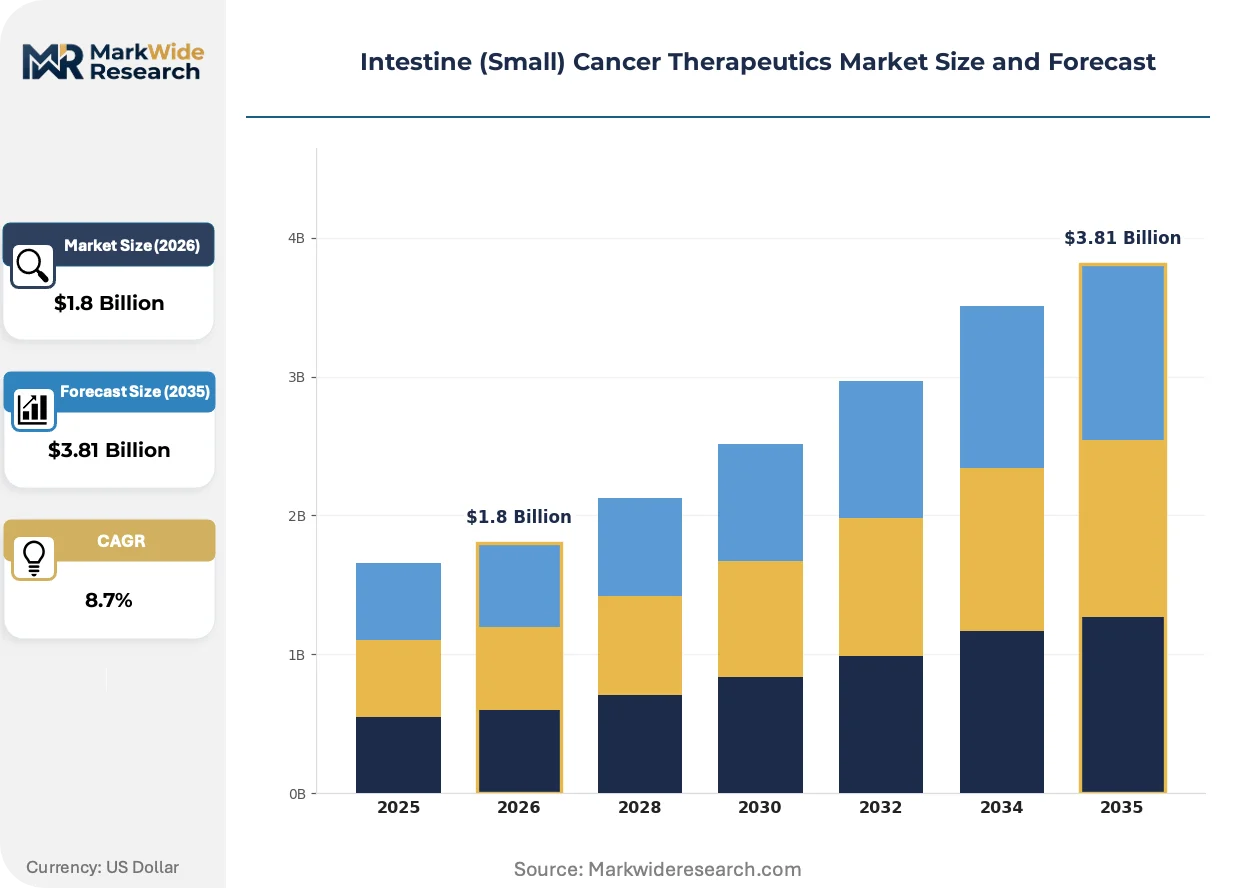
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Immunotherapy, Hormonal Therapy Treatment Stage: Early Stage, Locally Advanced, Metastatic, Recurrence Administration Route: Oral, Intravenous, Subcutaneous, Topical Patient Demographics: Pediatric, Adult, Geriatric, Others |
| Companies Covered | Johnson & Johnson Private Limited, Cipla Inc., Abbott, AbbVie Inc., Merck KGaA, Sun Pharmaceutical Industries Ltd., Pfizer Inc, Bristol-Myers Squibb Company, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intestine (Small) Cancer Therapeutics Market Shifts & Advancements
Next-generation sequencing platforms are automating molecular profiling workflows, compressing turnaround times for treatment-naive patients and enabling point-of-care therapeutic selection. Three developments are restructuring competitive positioning in small intestine oncology.
Artificial intelligence-driven pathology platforms are automating histological subtyping and biomarker quantification, reducing inter-observer variability in MSI-high determination. Academic pathology departments at Mayo Clinic and Memorial Sloan Kettering are deploying these tools for prospective patient stratification. This automation is compressing diagnostic timelines from weeks to days, accelerating treatment initiation windows for aggressive small bowel adenocarcinomas.
The European Medicines Agency's PRIME designation is aligning scientific advice and accelerated assessment timelines, creating a synchronized regulatory corridor for developers targeting rare gastrointestinal indications. This framework is enabling parallel EMA-FDA submission strategies that reduce geographic launch gaps. Oncology divisions at Roche and Novartis are restructuring European regulatory teams to exploit this convergence.
Academic medical centers are consolidating procurement authority for molecularly guided regimens under centralized pharmacy and therapeutics committees, displacing individual physician autonomy in agent selection. This committee-driven purchasing is concentrating contract negotiation leverage at NCI-designated centers in the United States. Manufacturers now face formulary access hurdles that prioritize evidence hierarchies over traditional representative detailing.
Intestine (Small) Cancer Therapeutics Market Segmentation
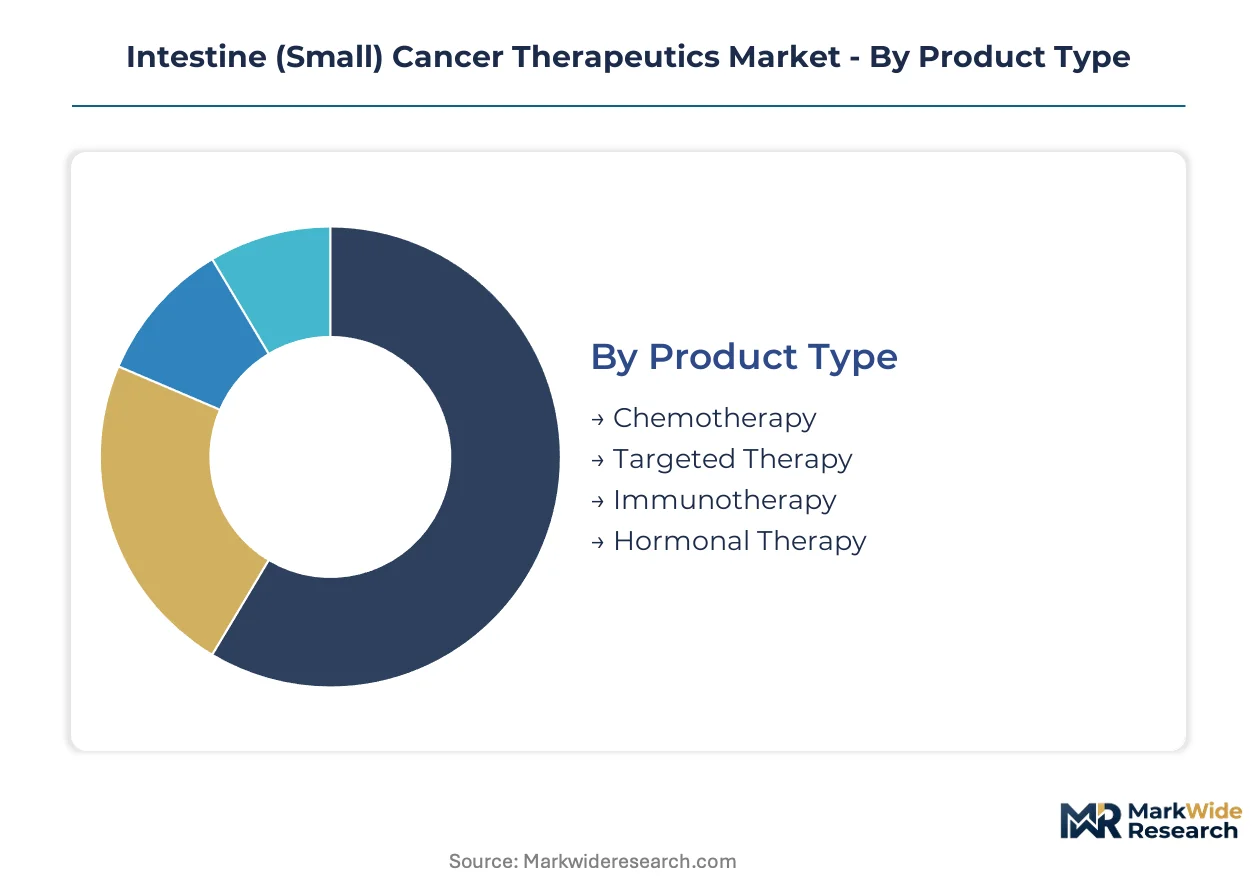
Segmentation in small intestine cancer therapeutics reveals how treatment selection stratifies across molecular profiles, disease progression states, and patient physiology. Each axis governs distinct reimbursement pathways, clinical trial eligibility, and prescriber decision frameworks that manufacturers must navigate.
Product Type:
Technology differentiation in mechanism of action separates agents by their molecular targets and therapeutic index profiles.
- Chemotherapy:Cytotoxic alkylating agents and antimetabolites remain the backbone for adenocarcinoma protocols where biomarker-guided alternatives remain unavailable. Demand concentrates in community oncology practices across the United States where infusion infrastructure and Medicare reimbursement stability sustain prescribing volume for platinum-taxane combinations.
- Immunotherapy:PD-1 and PD-L1 checkpoint inhibitors demonstrate durable responses in MSI-high and TMB-elevated subsets, with pembrolizumab and nivolumab securing accelerated approvals. NCI-designated cancer centers in Boston, Houston, and New York drive concentrated adoption where molecular profiling turnaround times compress treatment initiation windows.
- Targeted Therapy:Kinase inhibitors and anti-angiogenic agents address neuroendocrine carcinoma subtypes through mTOR and VEGF pathway inhibition.
- Hormonal Therapy:Somatostatin analogs manage hormone-secreting neuroendocrine tumors through receptor-mediated growth suppression.
Chemotherapy leads on scale; immunotherapy leads on momentum.
Treatment Stage:
Disease progression status determines curative intent versus palliative strategy, reshaping clinical endpoint requirements and regulatory submission pathways.
- Metastatic:Systemic therapy dominates as surgical resection becomes non-curative, with overall survival and progression-free survival as primary endpoints. The FDA's accelerated approval pathway has compressed development timelines for agents targeting this population, enabling earlier commercial access contingent on confirmatory trial completion.
- Early Stage:Adjuvant chemotherapy following surgical resection aims to eradicate micrometastatic disease. Academic medical centers with high-volume hepatopancreatobiliary surgical programs in the United States concentrate enrollment for adjuvant trials where disease-free survival serves as the regulatory standard.
- Locally Advanced:Neoadjuvant protocols attempt downstaging for margin-negative resection in borderline resectable cases.
- Recurrence:Second-line and beyond regimens face diminishing response rates and heightened reimbursement scrutiny.
Metastatic settings command the largest addressable population; early-stage adjuvant applications are climbing the fastest.
Administration Route:
Delivery modality shapes site-of-care economics, patient adherence profiles, and pharmacy benefit versus medical benefit reimbursement routing.
- Intravenous:Infusion-dependent agents require oncology clinic infrastructure and nursing supervision, concentrating utilization at hospital outpatient departments where buy-and-bill reimbursement models sustain margin capture for high-cost biologics.
- Oral:Small-molecule kinase inhibitors enable home administration and reduced clinic burden, though specialty pharmacy distribution and prior authorization requirements create access friction. Medicare Part D coverage gaps and copay accumulator programs constrain patient affordability.
- Subcutaneous:Self-administered injections bridge convenience and bioavailability for select immunotherapy and hormonal agents.
- Topical:Limited applicability in small intestine malignancies given anatomical inaccessibility.
Intravenous delivery dominates current revenue; oral formulations are gaining share fastest.
Patient Demographics:
Age-stratified physiology alters drug metabolism, toxicity tolerance, and trial eligibility criteria across the therapeutic lifecycle.
- Geriatric:Patients over 65 years constitute the majority incidence burden for small intestine adenocarcinomas, with comorbidity-adjusted protocols and reduced-intensity regimens gaining traction at Memorial Sloan Kettering and MD Anderson. Polypharmacy interactions and frailty indices reshape dosing algorithms.
- Adult:The core clinical trial population between 18 and 64 years establishes standard-of-care evidence bases that extrapolate to adjacent age brackets.
- Pediatric:Rare pediatric small intestine malignancies require dedicated orphan disease frameworks with modified toxicity thresholds.
- Others:Pregnant patients and those with severe organ dysfunction represent excluded populations requiring compassionate access protocols.
Geriatric patients anchor volume; adult subpopulations show the steepest expansion trajectory as screening detection improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States pioneered modern oncology therapeutics development through NCI-designated cancer centers established in the 1970s, creating the institutional foundation for rare gastrointestinal malignancy research that now spans multiple continents.
United States
Medicare reimbursement stability and dense NCI-designated center networks concentrate prescribing volume for advanced small intestine malignancies. The FDA's breakthrough therapy designation compresses development timelines for molecularly guided regimens. Memorial Sloan Kettering, MD Anderson, and Dana-Farber anchor clinical trial density in Boston, Houston, and New York metropolitan corridors.
Germany
Universal healthcare coverage and centralized oncology reference centers sustain access to novel immunotherapy combinations for neuroendocrine carcinoma subtypes. The EMA's PRIME designation aligns accelerated assessment timelines with scientific advice frameworks. Heidelberg and Munich academic medical centers drive biomarker-selected protocol enrollment across Baden-Württemberg and Bavaria.
China
Rising incidence of small bowel adenocarcinomas and expanding commercial insurance coverage for innovative oncology drugs are enlarging addressable patient pools. The NMPA's priority review reform enables parallel submission strategies with Western regulators. Beijing and Shanghai tertiary hospitals concentrate molecular profiling capacity and immuno-oncology trial activation.
Japan
Aging demographics and elevated small intestine cancer incidence among geriatric populations sustain demand for reduced-intensity regimens. The PMDA's sakigake designation system accelerates access to breakthrough therapies for rare malignancies. Tokyo and Osaka metropolitan clusters host high-volume hepatopancreatobiliary surgical programs with integrated oncology divisions.
United Kingdom
NHS England's specialized commissioning framework concentrates rare cancer treatment at designated supra-regional centers. The MHRA's post-Brexit regulatory autonomy enables accelerated access partnerships with FDA-aligned evidence standards. London's Royal Marsden and Manchester's Christie Hospital anchor neuroendocrine tumor expertise and clinical trial infrastructure.
Intestine (Small) Cancer Therapeutics Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with established oncology infrastructure. Large-cap developers dominate through checkpoint inhibitor portfolios and kinase inhibitor pipelines that address biomarker-defined subsets. Three archetypes populate the landscape: Big Pharma oncology divisions with immuno-oncology platforms, mid-cap targeted therapy specialists, and generic manufacturers supplying cytotoxic backbones. Portfolio diversification through rare indication expansion and geographic licensing agreements represent the dominant competitive moves.
Within the Big Pharma tier, Pfizer Inc and Bristol-Myers Squibb Company exemplify scale-driven oncology positioning, while Novartis AG occupies a Swiss-based diversified pharmaceutical position. Johnson & Johnson Private Limited represents the healthcare conglomerate archetype with pharmaceutical subsidiary structures. These entities anchor competitive dynamics through clinical trial density and regulatory submission velocity rather than product-specific claims.
| Leading Market Players |
|---|
| Johnson & Johnson Private Limited |
| Cipla Inc. |
| Abbott |
| AbbVie Inc. |
| Merck KGaA |
| Sun Pharmaceutical Industries Ltd. |
| Pfizer Inc |
| Bristol-Myers Squibb Company |
| Novartis AG |
| Others |
Supply & Pricing Matrix
Active pharmaceutical ingredient procurement costs for checkpoint inhibitors and kinase inhibitors cascade through tiered reimbursement structures, with Medicare buy-and-bill rates for infused biologics in hospital outpatient departments sustaining premium capture while oral specialty pharmacy channels face prior authorization compression and accumulator program erosion.
Pricing Analysis
Value-based contracting with integrated delivery networks anchors pricing for immuno-oncology agents, with outcomes guarantees and risk-sharing provisions differentiating premium positioning against standard cytotoxic backbones. Cost compression in oral kinase inhibitors stems from Medicare Part D coverage gap exposure and copay accumulator adoption by commercial payers. Community oncology practices demonstrate highest price sensitivity due to infusion reimbursement volatility, while NCI-designated centers command formulary leverage through committee-driven procurement authority.
Supply Chain Analysis
Direct-to-hospital channels handle high-cost biologic distribution for infused checkpoint inhibitors, with cold-chain logistics concentrated through specialty distributors in the United States, Germany, and Switzerland. API manufacturing for small-molecule kinase inhibitors draws from India and China, with finished dose production anchored in Ireland and Puerto Rico. Single-source vulnerability in sterile injectable capacity creates supply continuity exposure for platinum-taxane combinations. Distribution runs through limited-distribution specialty pharmacy networks for oral targeted therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The small intestine cancer therapeutics market compounds steadily as biomarker-guided regimen expansion at academic medical centers sustains pricing power and trial enrollment velocity for molecularly selected populations.
For Market Incumbents: Cement formulary positioning at NCI-designated cancer centers through real-world evidence generation partnerships and companion diagnostic co-development agreements. Deepen backward integration into biomarker testing infrastructure to capture diagnostic-to-therapeutic workflow control. Defensive priorities center on MSI-high and TMB-elevated population access against emerging PD-1/PD-L1 competitors. For New Entrants and Emerging Players: Specialty pharmacy benefit managers represent the most penetrable channel for oral kinase inhibitors seeking bypass of hospital outpatient buy-and-bill concentration. White-space targets include second-line neuroendocrine carcinoma regimens and adjuvant applications in high-risk adenocarcinoma subsets. Go-to-market execution should leverage outcomes-based contracting with regional integrated delivery networks lacking immuno-oncology depth. For Investors and Strategic Acquirers: Consolidation pressure builds where clinical trial infrastructure scarcity concentrates principal investigator access at Memorial Sloan Kettering, MD Anderson, and Dana-Farber. Long-term viability favors developers with parallel FDA-EMA-NMPA submission capabilities and biomarker-selected pipeline assets. Acquisition target archetype: mid-cap firms with phase II MSI-high data and companion diagnostic partnerships. Signal to watch: breakthrough therapy designation velocity for novel checkpoint combinations.| Strategic Initiative | Industry Significance |
|---|---|
| Breakthrough Therapy Designation Pursuit | FDA accelerated approval compresses time-to-market for molecularly guided regimens in MSI-high subsets. |
| Companion Diagnostic Co-Development | Liquid biopsy platform partnerships expand eligible patient pools for targeted kinase inhibitors across neuroendocrine subtypes. |
| Real-World Evidence Infrastructure | Electronic health record network integration enables label expansion without additional randomized controlled trials. |
| Parallel Regulatory Submission | Simultaneous FDA-EMA-NMPA filings reduce geographic launch gaps and capture priority review benefits. |
| Academic Medical Center Partnership | NCI-designated center alliances concentrate trial activation and formulary access for novel immunotherapy combinations. |
Research Methodology
Direct dialogue with oncology clinical trial investigators, regulatory affairs directors at pharmaceutical developers, hospital pharmacy and therapeutics committee chairs, and payer access specialists grounded qualitative insights, cross-referenced with FDA breakthrough therapy designation databases, ClinicalTrials.gov enrollment records, Medicare Part B claims extracts, and EMA PRIME designation tracking. Secondary validation drew from SEC oncology division disclosures, NCI cancer center annual reports, and formulary decision databases. Bottom-up patient flow modeling and top-down revenue reconciliation triangulated market sizing.
Segment-level projections across chemotherapy, immunotherapy, targeted therapy, and hormonal therapy modalities incorporated administration route economics, treatment line positioning, and regional regulatory cluster adoption curves. Patient epidemiology, biomarker prevalence, and protocol penetration rates fed cohort-based forecasting. CAGRs derived from longitudinal reimbursement trajectory analysis and clinical pipeline probability-adjusted revenue modeling. Forecast inputs included FDA approval velocity assumptions, companion diagnostic commercialization timelines, and Medicare coverage determination patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to confirmatory trial failure rates, biosimilar entry timing, and real-world evidence regulatory acceptance evolution. Forecasts reflect documented assumptions regarding biomarker testing expansion, breakthrough therapy designation retention, and Medicare reimbursement stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Ovarian Cancer Therapeutics Market
Specialty Medicine
Systemic Lupus Erythematosus (SLE) Market
Specialty Medicine
Malignant Glioma Therapeutics Market
Specialty Medicine
Osteogenesis Imperfecta Treatment Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
Listeriosis Treatment Market
Specialty Medicine
Eisenmenger Complex Management Market
Specialty Medicine
Global Lung Transplant Therapeutics Market
Specialty Medicine
Bronchiectasis Market
Specialty Medicine
Geographic Atrophy Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market
Specialty Medicine
Primary Ciliary Dyskinesia Market
Specialty Medicine
Low-Grade Glioma Therapeutics Market
Specialty Medicine
Tinnitus Management Market
Specialty Medicine
Combined Immune Deficiency (CID) Market
Specialty Medicine
Whipple's Disease Market