
 Energy-Based Aesthetic Devices Market | 2026-2036
Energy-Based Aesthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Energy-Based Aesthetic Devices Market Intelligence
Clinical-grade platform specifications are rotating toward higher-energy, multi-modality configurations that integrate cooling and real-time skin monitoring. Alma Lasers leverages its vertically integrated manufacturing in Israel to control component costs across laser and light therapy lines. Sciton, Inc. anchors the premium segment in North America through tunable wavelength architectures that physicians customize per patient phenotype. Candela Corporation competes on brand heritage and installed base density across dermatology clinics in Japan and South Korea.
Energy-based aesthetic devices deploy electromagnetic radiation, acoustic waves, or thermal energy to modify skin, adipose tissue, or follicular structures through selective photothermolysis, impedance heating, or cavitation mechanisms, typically operating at wavelengths between 500 nm and 10,600 nm or frequencies between 1 MHz and 40 MHz for tissue-specific targeting. Laser Systems dominate installed base value due to capital intensity and consumable attachment streams, while Radiofrequency Devices capture expanding share in body contouring as physicians seek non-ablative alternatives with shorter recovery profiles. Combination Therapies command premium pricing by collapsing multiple treatment sessions into single-visit protocols that medical spas market as efficiency differentiators.
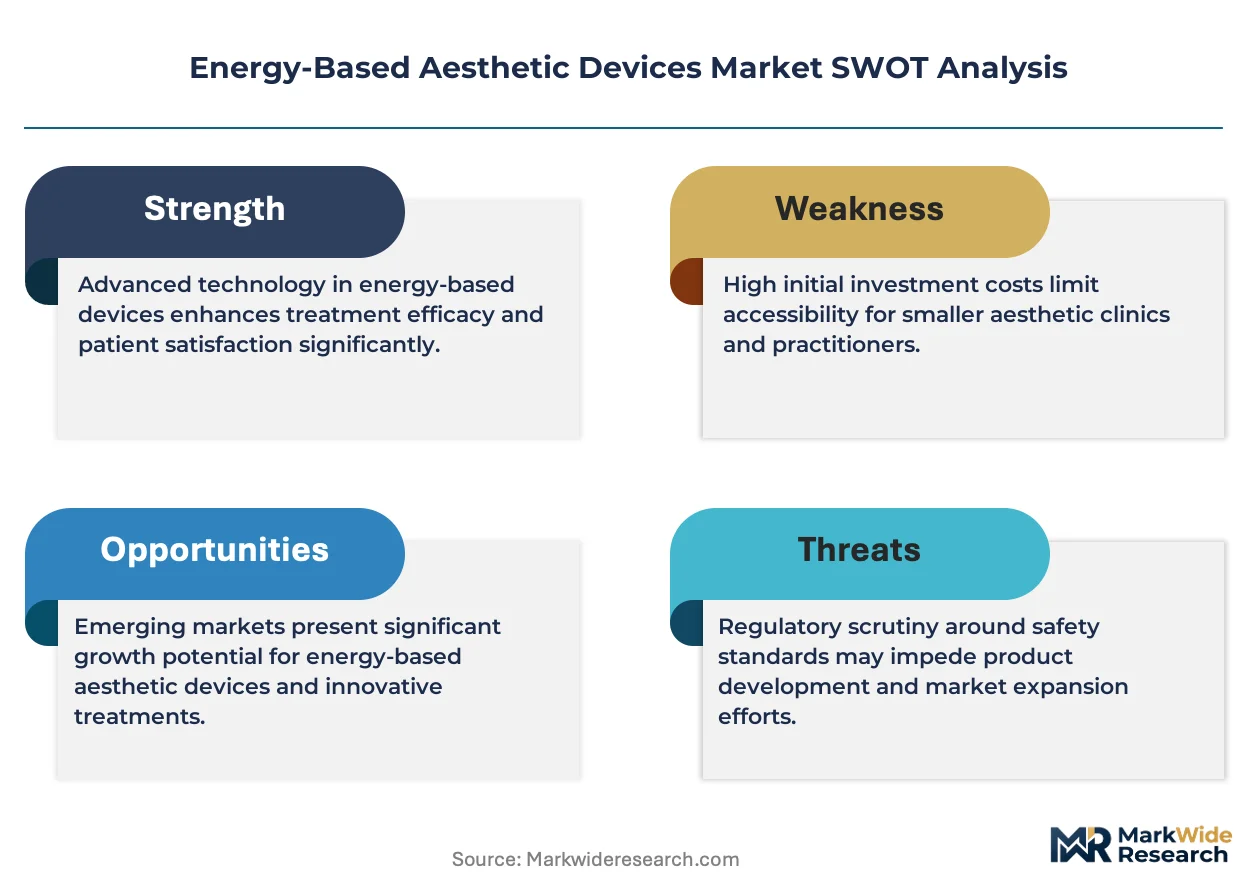
FDA 510(k) clearance requirements shape product development timelines and clinical trial investment for devices entering the United States, while the EU Medical Device Regulation (MDR) imposes stricter post-market surveillance and notified body scrutiny across European markets. Japan's PMDA enforces unique electrical safety and biological compatibility standards that delay foreign manufacturer entry but protect domestic incumbents. Stakeholders must monitor how regulatory divergence between FDA streamlined pathways and MDR clinical evidence demands fragments product launch sequencing and service model design across major markets.
Market Dynamics
Multi-modality platform integration is compressing treatment protocols from multiple visits into single sessions, forcing capital equipment refresh cycles and reconfiguring service revenue models across dermatology practices and medical spas.
Growth Catalysts
- FDA 510(k) Streamlining:Accelerated clearance pathways for laser and radiofrequency systems reduce time-to-market for device manufacturers targeting the United States, compressing clinical trial investment recovery periods.
- Minimally Invasive Preference:Patient demand for shorter recovery profiles drives physician adoption of non-ablative alternatives, expanding the addressable base beyond traditional cosmetic surgery candidates.
- Combination Therapy Platforms:Single-device integration of multiple energy modalities collapses per-patient visit counts, improving medical spa throughput metrics and capital utilization rates.
Market Restraints
- Optical Component Supply Concentration:Precision laser crystal and fiber-optic sourcing concentrates among German and Japanese specialty suppliers, exposing device manufacturers to input cost volatility and extended lead times.
- EU MDR Clinical Evidence Demands:Stricter post-market surveillance and notified body scrutiny across European markets elongate product launch sequencing and inflate regulatory compliance overhead.
- Elective Procedure Sensitivity:Macroeconomic pressure on discretionary healthcare spending compresses patient willingness-to-pay for non-reimbursable aesthetic treatments during contraction cycles.
Strategic Opportunities
- Men's Aesthetic Segment:Underpenetrated male patient demographics in body contouring and hair restoration applications offer expansion vectors beyond historically female-skewed device marketing.
- Home-Use Device Channel:Lower-energy consumer-grade systems distributed through e-commerce and retail dermatology partnerships capture maintenance-phase patients between clinical treatments.
- Japan PMDA Localization Incentives:Domestic electrical safety and biological compatibility standards protect foreign entrants who establish local manufacturing or joint venture structures, creating defensible market positions.
Industry Challenges
- Clinical Training Bandwidth:Safe operation of tunable wavelength and multi-modality systems demands specialized physician and technician certification, constraining rollout velocity in expanding practice networks.
- Software-Hardware Integration Complexity:Real-time skin monitoring and cooling subsystem coordination requires firmware development capabilities that legacy device manufacturers must build or acquire.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy-Based Aesthetic Devices Market |
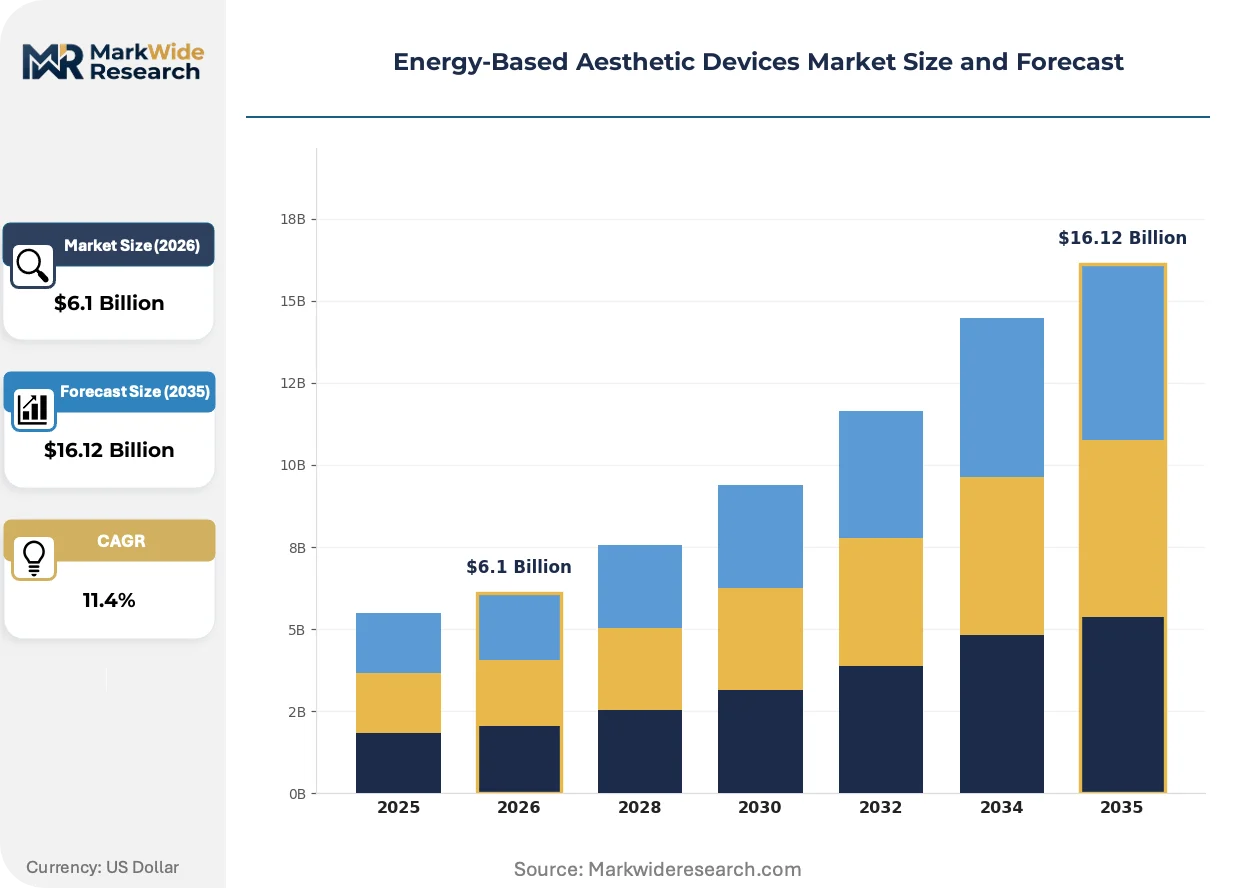
| Market Size in 2026 | $6.1 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Laser Systems, Radiofrequency Devices, Ultrasound Devices, Light Therapy Systems Application: Skin Rejuvenation, Hair Removal, Body Contouring, Acne Treatment End User: Dermatology Clinics, Medical Spa, Hospitals, Home Care Technology: Non-invasive Techniques, Minimally Invasive Techniques, Ablative Methods, Combination Therapies |
| Companies Covered | Candela Corporation, Lumenis Ltd., Cynosure, Alma Lasers, Cutera, Merz Pharma GmbH & Co. KGaA, Bausch Health Companies Inc., InMode Ltd., Sciton, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy-Based Aesthetic Devices Market Strategic Shifts & Innovations
Device architecture is converging around intelligent energy delivery systems that adjust parameters mid-treatment based on tissue feedback, collapsing the historical trade-off between efficacy and safety margins.
Picosecond and femtosecond pulse-duration lasers are fragmenting the tattoo removal and pigmentation correction segments by reducing thermal diffusion to surrounding tissue, enabling faster treatment of darker skin phenotypes previously excluded from laser protocols. Dermatology clinics in the United States and South Korea are replacing nanosecond systems at accelerated refresh cycles. This technology compression is fragmenting the installed base value concentration that longer-pulse systems historically commanded.
The EU Medical Device Regulation imposes stricter clinical evidence requirements for high-risk aesthetic devices, forcing manufacturers to maintain post-market surveillance infrastructure that smaller competitors cannot sustain. Notified body capacity constraints in Germany and the Netherlands elongate certification timelines by eight to fourteen months. Premium platform manufacturers with established European clinical trial networks capture share from mid-tier competitors retreating from the market.
Physician procurement is consolidating around outcome-guaranteed service contracts that bundle device placement, consumable supply, and maintenance into per-treatment fees rather than capital purchase structures. Medical spa chains and dermatology group practices in the United States increasingly reject traditional equipment financing in favor of vendor-managed utilization models. This shift compresses manufacturer working capital requirements while transferring volume risk to device suppliers.
Energy-Based Aesthetic Devices Market Segmentation
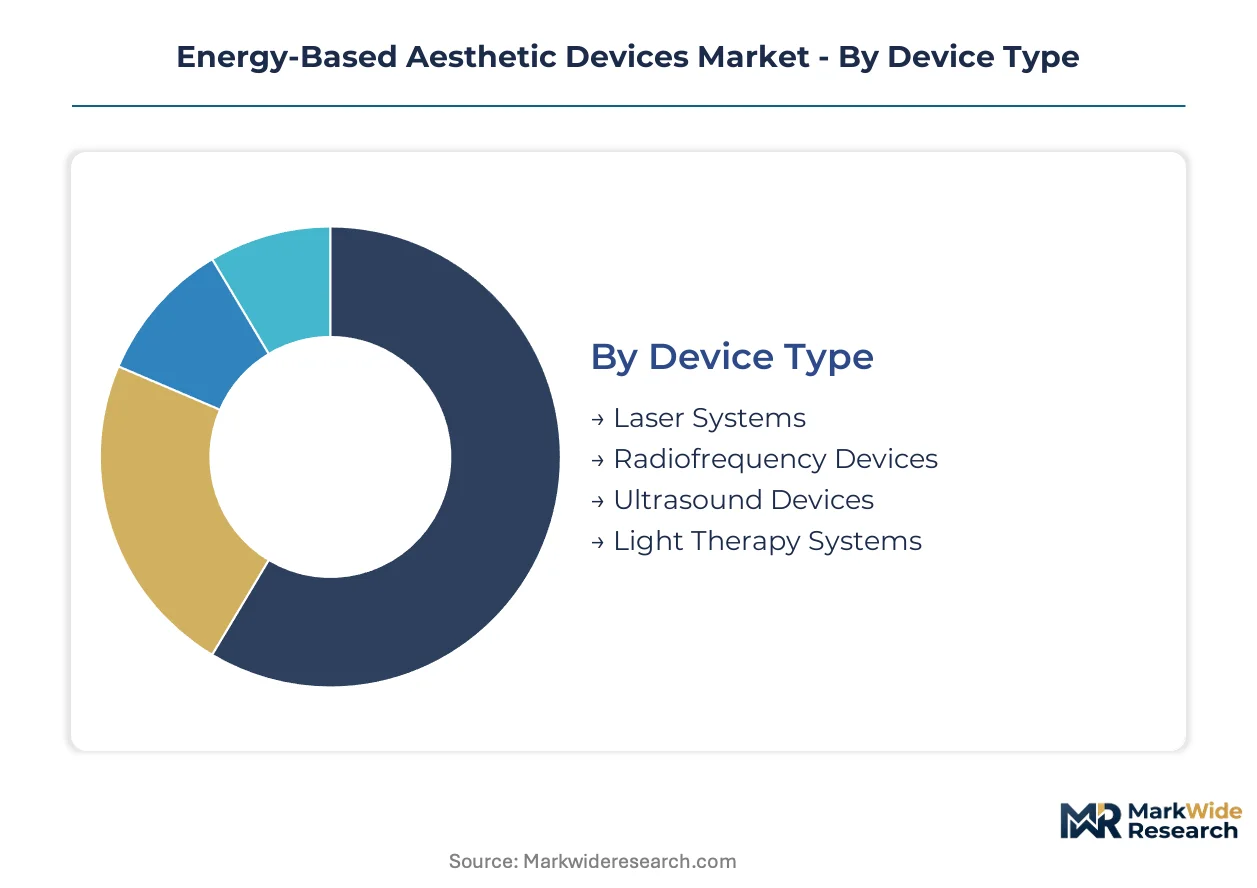
Energy-based aesthetic devices fragment across four structural dimensions that determine pricing power, channel access, and regulatory pathway complexity. Device manufacturers align R&D portfolios and sales force deployment to the specific margin profiles and certification requirements of each segment cluster.
Device Type:
Capital equipment flows through distinct channel architectures: laser and radiofrequency systems deploy through direct sales to dermatology clinics, while ultrasound and light therapy units penetrate medical spa chains via distributor networks.
- Laser Systems:These platforms operate at wavelengths between 500 nm and 10,600 nm, employing selective photothermolysis to target chromophores in skin and follicular structures. Demand concentrates in United States dermatology clinics seeking FDA 510(k) cleared platforms with tunable wavelength architectures that physicians customize per patient phenotype. Capital intensity and consumable attachment streams sustain premium pricing.
- Radiofrequency Devices:Systems deliver thermal energy through impedance heating at frequencies between 1 MHz and 40 MHz for tissue-specific targeting. Expansion concentrates in body contouring applications across medical spas in South Korea and Japan as physicians seek non-ablative alternatives with shorter recovery profiles. The segment captures expanding share through non-ablative positioning.
- Ultrasound Devices:Acoustic wave platforms induce cavitation or thermal coagulation in adipose tissue layers. Medical spa chains in the United States procure these systems for fat reduction protocols.
- Light Therapy Systems:Broad-spectrum or filtered light sources address surface-level dermatological conditions. Home-use channels and retail dermatology partnerships drive volume.
Laser Systems dominate installed base. Radiofrequency Devices is where expansion concentrates.
Application:
Procedure volume and reimbursement exposure vary sharply across indication areas, with skin rejuvenation and hair removal commanding premium per-session fees while body contouring scales through package pricing.
- Skin Rejuvenation:Collagen remodeling and photodamage correction procedures utilize fractional laser and intense pulsed light platforms. United States dermatology clinics prioritize devices with real-time skin monitoring and integrated cooling subsystems. Patient willingness-to-pay remains elevated for physician-delivered protocols.
- Hair Removal:Laser and light-based follicular destruction represents the most penetrated aesthetic indication globally. Demand saturates in mature markets while climbing fastest in urban medical spa networks across South Korea.
- Body Contouring:Non-invasive fat reduction and skin tightening applications deploy radiofrequency, ultrasound, or cryolipolysis technologies. Medical spa chains favor per-treatment fee structures over capital purchase.
- Acne Treatment:Blue light and photodynamic therapy systems target sebaceous gland activity. Adoption concentrates in adolescent and young adult demographics.
Skin Rejuvenation commands the highest per-procedure pricing. Body Contouring is climbing the fastest as medical spa throughput metrics improve.
End User:
Procurement authority and technical sophistication diverge across customer types, with dermatology clinics demanding clinical evidence packages and home care channels prioritizing safety interlocks and simplified protocols.
- Dermatology Clinics:Board-certified practices in the United States and Japan drive adoption of multi-modality platforms with tunable parameters. These customers require extensive clinical training bandwidth and outcome-guaranteed service contracts.
- Medical Spa:Corporate-owned chains and franchise networks concentrate purchasing power, favoring vendor-managed utilization models that bundle device placement with consumable supply. United States-based chains increasingly reject traditional equipment financing.
- Hospitals:Academic medical centers and plastic surgery departments integrate aesthetic devices into broader reconstructive portfolios. Procurement follows institutional capital budgeting cycles.
- Home Care:Lower-energy consumer-grade systems distributed through e-commerce capture maintenance-phase patients between clinical treatments. Regulatory clearance pathways differ from clinical-grade devices.
Dermatology Clinics anchor premium platform demand. Medical Spa is where procurement consolidation is accelerating.
Technology:
Clinical evidence requirements and recovery profile positioning determine technology selection, with non-invasive and combination approaches compressing traditional ablative market share.
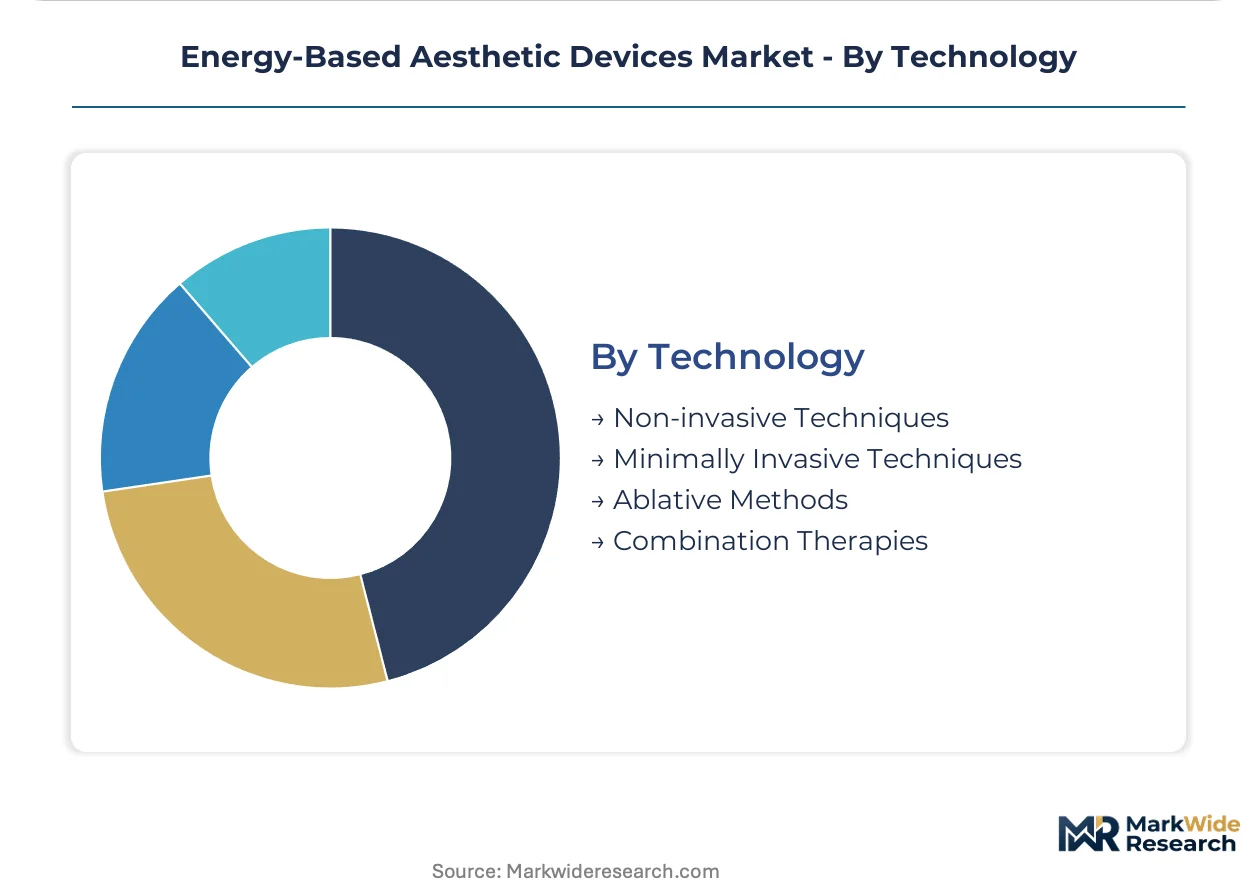
- Non-invasive Techniques:Surface-level energy delivery without epidermal breach addresses patient demand for zero-downtime protocols. Radiofrequency and low-level laser platforms dominate this category.
- Minimally Invasive Techniques:Micro-needle radiofrequency and fractional laser systems create controlled thermal injury with limited recovery windows. United States medical spas market these as efficiency differentiators.
- Ablative Methods:Full-thickness epidermal removal through CO2 or erbium lasers delivers maximal efficacy for severe photodamage. Demand concentrates in plastic surgery practices with sedation capabilities.
- Combination Therapies:Single-platform integration of multiple energy modalities collapses per-patient visit counts. Premium pricing reflects improved medical spa throughput metrics and capital utilization rates.
Non-invasive Techniques hold the largest procedure volume base. Combination Therapies is gaining share fastest through single-visit protocol compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israeli and German component suppliers dominate precision laser crystal and fiber-optic sourcing, while United States dermatology clinics and South Korean medical spas anchor demand for installed systems. Regulatory divergence between FDA streamlined pathways and EU MDR clinical evidence demands fragments product launch sequencing across major markets.
United States
Dermatology clinics in California and New York Metro expand device portfolios as FDA 510(k) clearance pathways streamline market entry for laser and radiofrequency systems. The FDA's accelerated review timelines compress clinical trial investment recovery periods for manufacturers. Boston-area academic medical centers drive adoption of multi-modality platforms with tunable wavelength architectures.
Germany
Precision laser crystal suppliers in Bavaria and Baden-Württemberg expose device manufacturers to input cost volatility and extended lead times. The EU Medical Device Regulation imposes stricter post-market surveillance and notified body scrutiny, elongating certification timelines by eight to fourteen months. Notified body capacity constraints in Munich and Stuttgart fragment product launch sequencing.
Japan
Medical spas in Tokyo and Osaka drive demand for non-ablative body contouring alternatives with shorter recovery profiles. PMDA enforces unique electrical safety and biological compatibility standards that delay foreign manufacturer entry but protect domestic incumbents. Kanto-region dermatology clinics prioritize devices with real-time skin monitoring and integrated cooling subsystems.
South Korea
Urban medical spa networks in Seoul and Busan scale body contouring procedures through package pricing models. MFDS regulatory frameworks align with international standards while maintaining domestic testing requirements. Seoul Capital Area clinics replace nanosecond laser systems with picosecond platforms at accelerated refresh cycles.
Israel
Vertically integrated manufacturing clusters in Tel Aviv and Haifa control component costs across laser and light therapy lines. Israeli device manufacturers leverage captive supply chains to manage optical component sourcing concentration risks. Tel Aviv-area R&D centers develop intelligent energy delivery systems that adjust parameters mid-treatment.
Energy-Based Aesthetic Devices Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the energy-based aesthetic devices sector. The vendor base organizes into three tiers: premium platform manufacturers with established clinical trial networks, mid-tier competitors retreating from EU MDR compliance burdens, and vertically integrated specialists controlling upstream component supply. Dominant competitive moves include vendor-managed utilization models that transfer volume risk to device suppliers, and accelerated refresh cycles compressing installed base value concentration.
Among Israel-based vertically integrated manufacturers, Alma Lasers exemplifies the captive supply chain archetype through control of laser and light therapy component costs. United States premium platform specialists Sciton, Inc. and Candela Corporation occupy positions in the North American installed base, with Candela leveraging brand heritage across Japanese and South Korean dermatology clinics. These three companies represent the geographic and strategic diversification patterns visible across the competitive set.
| Leading Market Players |
|---|
| Candela Corporation |
| Lumenis Ltd. |
| Cynosure |
| Alma Lasers |
| Cutera |
| Merz Pharma GmbH & Co. KGaA |
| Bausch Health Companies Inc. |
| InMode Ltd. |
| Sciton, Inc. |
| Others |
Cost & Logistics Intelligence
Picosecond laser crystal substitution for nanosecond architectures simultaneously shifts procurement geography toward Israeli and German specialty suppliers and compresses pricing premiums previously commanded by legacy pulse-duration systems. This input transition reshapes cost structures across United States dermatology clinics and South Korean medical spa chains as device manufacturers absorb optical component volatility.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across clinical-grade platforms, separating premium multi-modality systems with real-time monitoring from standard single-wavelength units and economy-grade distributor-sold alternatives. Price differentiation rests on certification level and after-sales service bundling, with outcome-guaranteed per-treatment contracts commanding premiums over capital purchase models. Pricing pressure stems from EU MDR compliance overhead inflating European launch costs. Medical spa chains exhibit highest price sensitivity through vendor-managed utilization preferences, while academic medical centers prioritize performance over cost.
Supply Chain Analysis
Bavarian and Baden-Württemberg precision optics clusters create chokepoint exposure for laser crystal and fiber-optic sourcing across device manufacturers. Supply geography concentrates in Germany, Japan, and Israel for critical components. Raw material dependencies span neodymium-doped yttrium aluminum garnet crystals, specialty fiber-optic bundles, and radiofrequency generator subassemblies. Single-source vulnerability from concentrated German and Japanese suppliers elevates lead time risk. Distribution runs through direct sales forces for dermatology clinics and distributor networks for medical spa chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Elective procedure demand cyclicality positions this market for recovery as macroeconomic pressure on discretionary healthcare spending moderates. Patient willingness-to-pay compression during contraction cycles creates pent-up procedure backlog.
For Market Incumbents: Secure captive supply arrangements for precision laser crystals to mitigate German and Japanese supplier concentration risk. Accelerate software-hardware integration capabilities through firmware development acquisitions that address real-time skin monitoring demands. Defend against mid-tier competitors retreating from EU MDR compliance burdens by maintaining established European clinical trial networks.
For New Entrants and Emerging Players: Lead with home-use device channels targeting maintenance-phase patients between clinical treatments, where regulatory pathways differ and capital requirements compress. Target underpenetrated male patient demographics in body contouring applications as the most penetrable expansion vector. Pursue e-commerce and retail dermatology partnerships as the primary go-to-market angle for lower-energy consumer-grade systems.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier device manufacturers lacking EU MDR post-market surveillance infrastructure. Long-term viability across the analysis window favors premium platform specialists with installed base density and consumable attachment streams. Monitor notified body capacity constraints in Germany and the Netherlands as the signal for certification timeline inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined clearance pathways compress time-to-market for laser and radiofrequency systems targeting United States dermatology clinics. |
| Multi-Modality Platform Integration | Single-device combination therapies collapse per-patient visit counts and improve medical spa throughput metrics. |
| Vendor-Managed Utilization Contracts | Per-treatment fee structures transfer volume risk to device suppliers while reducing customer working capital requirements. |
| EU MDR Clinical Evidence Investment | Post-market surveillance infrastructure captures share from mid-tier competitors retreating from European compliance burdens. |
| Home-Use Device Channel Development | Lower-energy consumer-grade systems distributed through e-commerce capture maintenance-phase patients between clinical treatments. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, EU MDR notified body documentation, and hospital procurement records. Interviews with dermatology clinic physicians, medical spa chain procurement directors, biomedical engineers, and GPO contracts managers inform demand-side dynamics. Secondary sources include SEC filings from publicly traded device manufacturers, PMDA submission records, and customs data on optical component trade flows. Bottom-up procedure volume estimates triangulate against top-down capital equipment shipment data.
Segmentation dimensions modeled span device type, application, end user, and technology across the projection horizon. The analytical framework derives CAGRs from installed base refresh cycles, regulatory approval timelines, and procedure volume elasticity to pricing. Forecast inputs incorporate FDA clearance velocity assumptions, EU notified body capacity constraints, and medical spa chain expansion trajectories.
The analysis sits within stated boundaries; outcomes outside assumed macroeconomic stabilization and regulatory pathway continuity would require recalibration. Forecasts reflect documented assumptions regarding patient willingness-to-pay recovery and optical component supply stability. Practitioners should keep alternative scenarios live as EU MDR enforcement intensity and elective procedure demand cyclicality evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Non-Invasive Fat Reduction Market
Aesthetic Medicine
Professional Beauty Services Market
Aesthetic Medicine
Body Contouring Market
Aesthetic Medicine
Global Cellulite Treatment Market
Aesthetic Medicine
Photorejuvenation Market
Aesthetic Medicine
Medical Aesthetic Dermal Filler Market
Aesthetic Medicine
North America Aesthetic Dermatology Market
Aesthetic Medicine
Asia-Pacific Aesthetic Dermatology Market
Aesthetic Medicine
Global Aesthetic Threads Market
Aesthetic Medicine
Global Facial Fat Transfer Market
Aesthetic Medicine
North America Medical Aesthetic Devices Market
Aesthetic Medicine
Asia Pacific Aesthetics Market
Aesthetic Medicine
Aesthetic Lasers and Energy Devices Market
Aesthetic Medicine
Global Aesthetic Fillers Market
Aesthetic Medicine
Asia-Pacific Facial Aesthetics Market
Aesthetic Medicine
Facial Rejuvenation Market