
 Global Aircraft Heat Exchanger Market | 2026-2036
Global Aircraft Heat Exchanger Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Heat Exchanger Market Intelligence
The substitution of traditional nickel alloys with advanced lightweight aluminum and titanium composites is restructuring the cost-benefit equation for thermal management systems. This shift prioritizes fuel efficiency gains through weight reduction. Honeywell International Inc. leverages its extensive R&D in materials science to lead this transition. Safran S.A. specializes in integrated engine and nacelle systems that incorporate these advanced exchangers. Meanwhile, RTX Corporation competes on the basis of its broad portfolio covering both commercial and military platforms.
An aircraft heat exchanger is a critical device designed to transfer thermal energy between two or more fluids within an aircraft's mechanical systems. These components utilize high-conductivity materials and complex internal geometries, such as plate-fin or microchannel designs, to achieve maximum heat transfer in a minimal-weight, compact package. Their primary purpose is to regulate temperatures in vital systems, including engine oil, hydraulics, and cabin air. Plate fin heat exchangers dominate the market due to their superior efficiency-to-weight ratio. The engine cooling application remains the highest value segment, driven by extreme performance requirements.
Component design and market access are governed by stringent airworthiness regulations. The Federal Aviation Administration (FAA) in the United States and the European Union Aviation Safety Agency (EASA) mandate rigorous testing and certification for all flight-critical components, including heat exchangers, under frameworks like Part 25 and CS-25. These rules dictate material traceability, performance validation, and manufacturing quality control. Suppliers must continuously innovate to meet rising thermal loads from next-generation avionics and propulsion systems without compromising on certified safety and reliability standards.
Market Dynamics
The aircraft heat exchanger market is defined by the engineering imperative to manage escalating thermal loads from next-generation propulsion and avionics within strict weight and volume constraints, a conflict that advanced materials and manufacturing methods are resolving.
Growth Catalysts
- Additive Manufacturing:This fabrication process enables the creation of highly complex and lightweight heat exchanger geometries, such as microchannel and plate-fin designs, that are impossible with traditional methods, improving thermal efficiency.
- Military Modernization Programs:Fleet upgrades and new platform developments, particularly within United States and European Union defense forces, require components capable of handling the extreme heat generated by advanced electronic warfare and engine systems.
- Fuel Efficiency Mandates:The push for reduced fuel consumption and emissions, driven by operational economics and frameworks like the EU Green Deal, necessitates lighter components, making advanced aluminum and titanium exchangers highly attractive.
Market Restraints
- Material Cost Volatility:The high and fluctuating costs of aerospace-grade titanium and specialized aluminum alloys create significant price uncertainty for manufacturers and can delay the adoption of these superior materials in cost-sensitive segments.
- Stringent Certification Cycles:The extensive and costly testing and validation processes mandated by airworthiness authorities like the FAA and EASA slow the market introduction of innovative designs and materials, creating a barrier to entry.
- Consolidated Raw Material Supply:The supply chain for high-purity titanium sponge and aerospace-grade composites is concentrated among a few global suppliers, creating potential bottlenecks and pricing power that impacts component manufacturers.
Strategic Opportunities
- Urban Air Mobility (UAM):The emerging market for eVTOL aircraft presents a new frontier, requiring novel, compact, and lightweight thermal management solutions for battery packs, electric motors, and power electronics. *Digital Twin Integration: Developing heat exchangers with embedded sensors that feed data to a digital twin allows for predictive maintenance, performance optimization, and failure analysis, creating new service-based revenue streams.
- Aftermarket Services for Aging Fleets:Providing certified replacement and upgraded heat exchangers for the large global fleet of aging commercial and military aircraft offers a stable and recurring revenue opportunity distinct from new aircraft programs.
Industry Challenges
- Specialized Talent Scarcity:A shortage of engineers with combined expertise in thermodynamics, advanced materials science, and additive manufacturing processes constrains the pace of innovation and product development for many suppliers.
- Legacy System Integration:Designing new, high-performance heat exchangers that can be retrofitted into the tight spatial and systemic constraints of older aircraft platforms without requiring extensive and costly modifications is a significant engineering hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Heat Exchanger Market |
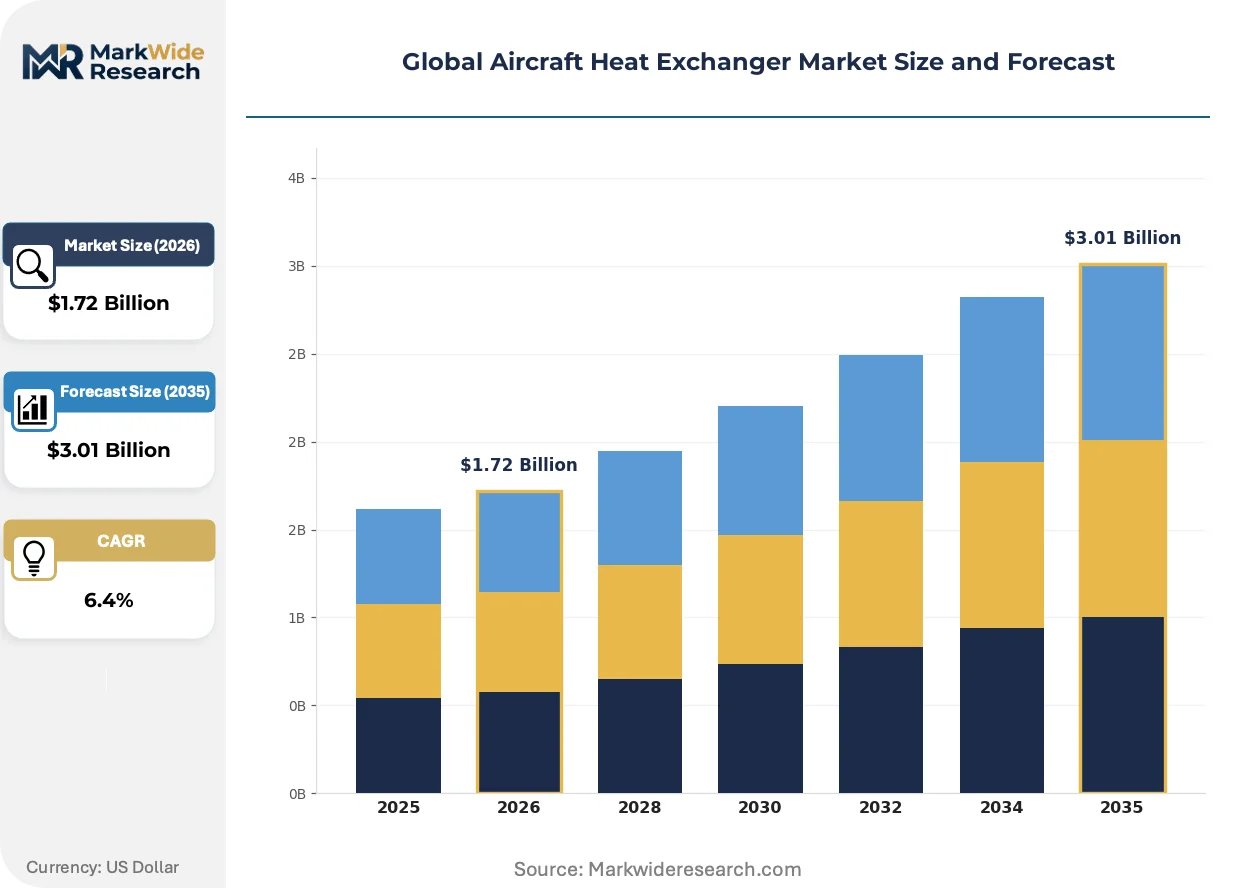
| Market Size in 2026 | $1.72 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plate Heat Exchanger, Shell & Tube Heat Exchanger, Air Cooled Heat Exchanger, Radiator, Plate Fin Heat Exchanger Technology: Welded, Brazed, Mechanical Bonded, Spiral Heat Exchanger, Lamella Heat Exchanger Application: Engine Cooling, Hydraulic Cooling, Cabin Environmental Control, Fuel Cooling, Oil Cooling End User: Airlines, Maintenance Repair Organizations, Aircraft Manufacturers, Military Aviation, Business Jet Operators |
| Companies Covered | Honeywell International Inc., RTX Corporation, Liebherr Group, Parker Hannifin Corp., Safran S.A., Triumph Group, Meggitt PLC, General Electric Company, Boyd Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Heat Exchanger Market Strategic Shifts & Innovations
The core tension in the market involves managing higher thermal densities from electrified systems and powerful engines while simultaneously reducing component weight for fuel efficiency. This dynamic is forcing a rapid evolution in materials, design philosophies, and supplier business models.
Additive manufacturing enables the production of heat exchangers with optimized internal geometries that maximize surface area for heat transfer. Military and advanced commercial aviation segments are accelerating adoption for performance-critical applications like engine and avionics cooling. This technology is modularizing thermal management, allowing designers to create bespoke units that integrate seamlessly into specific airframe locations rather than relying on standardized, less-efficient components.
Heightened regulatory focus from bodies like the FAA and EASA on the entire component lifecycle is reshaping manufacturing protocols. These agencies now demand exhaustive traceability for materials like titanium composites and detailed process validation for methods such as additive manufacturing. This primarily affects component suppliers, who must invest heavily in quality control and documentation systems to maintain certifications like Part 25 and CS-25.
Airlines and original equipment manufacturers are increasingly sourcing integrated thermal management subsystems instead of discrete components. This shift disrupts the traditional model of procuring individual heat exchangers, favoring suppliers who can design, validate, and deliver a complete system package. This trend is most pronounced in new commercial aircraft programs originating in the United States and France, where system integration simplifies assembly and accountability.
Global Aircraft Heat Exchanger Market Segmentation
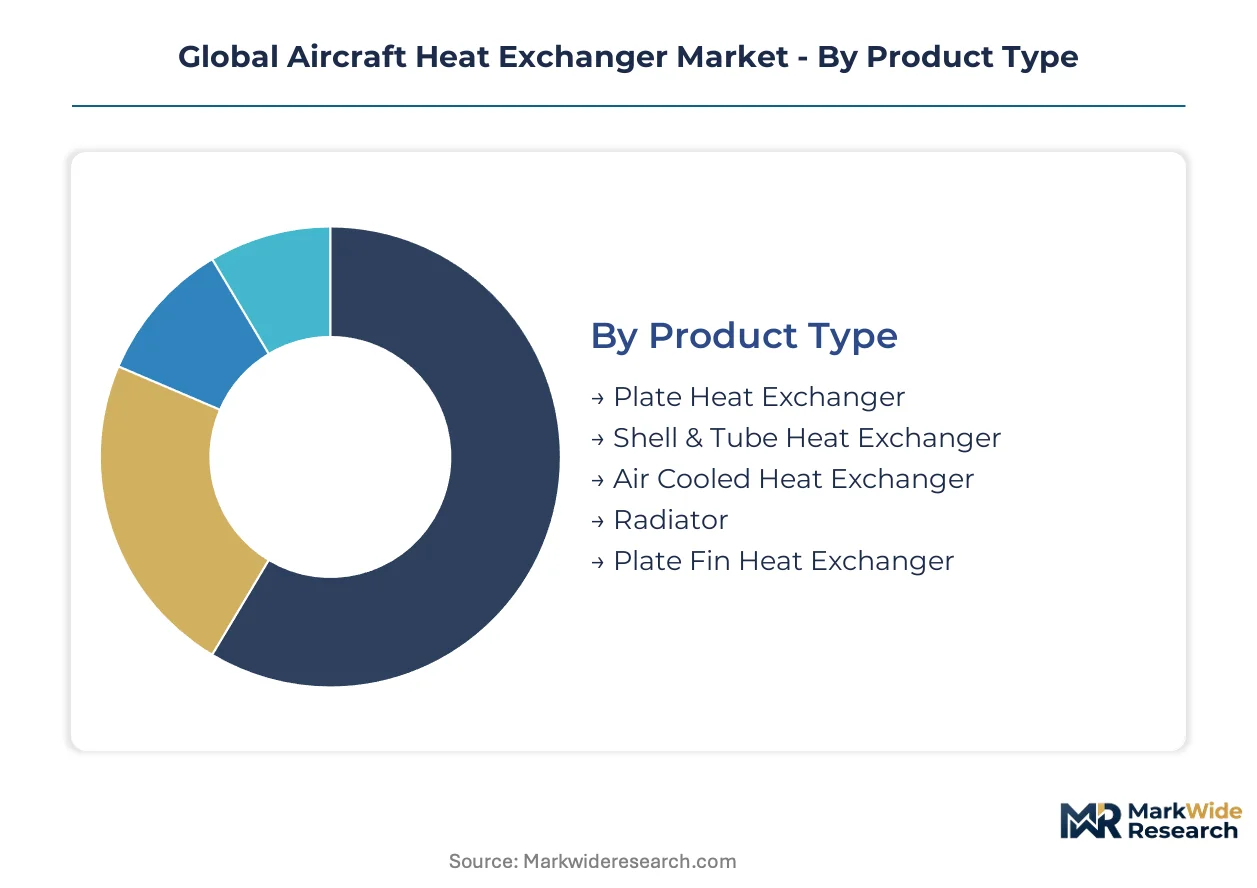
Understanding the Global Aircraft Heat Exchanger Market through its segmentation provides clarity on where engineering efforts and investment capital are concentrating. Distinct product types, technologies, applications, and end-user demands shape the competitive landscape for thermal management solutions. This detailed breakdown highlights specific opportunities and challenges.
Product Type:
The upgrade and replacement cycles for aircraft components heavily influence demand across various heat exchanger product types, driving innovation towards more efficient designs.
- Plate Fin Heat Exchanger:Plate fin heat exchangers integrate corrugated fins between parallel plates, maximizing surface area for heat transfer. Demand concentrates in advanced military aircraft and commercial jets, driven by stringent weight and performance requirements.
- Shell & Tube Heat Exchanger:Shell and tube heat exchangers consist of a bundle of tubes housed within a larger shell, facilitating heat exchange between two fluids. These robust units find extensive use in engine oil cooling, common across commercial and military platforms.
- Plate Heat Exchanger:Plate heat exchangers feature multiple thin, corrugated plates, offering high thermal efficiency for hydraulic systems.
- Air Cooled Heat Exchanger:Air cooled heat exchangers dissipate heat into ambient air, commonly used for auxiliary power unit cooling in smaller aircraft.
- Radiator:Radiators manage coolant temperatures for various aircraft systems, particularly in propeller-driven and older jet aircraft.
Plate Fin Heat Exchanger sits at the top of the volume ranking, with Shell & Tube Heat Exchanger climbing the fastest.
Technology:
The specific application requirements for heat exchangers dictate the suitability and adoption rate of different manufacturing technologies.
- Brazed:Brazed heat exchangers join components using a filler metal, creating strong, leak-tight bonds suitable for high-pressure systems. Demand is strong in engine cooling, where material integrity and thermal performance are paramount.
- Welded:Welded heat exchangers offer superior structural integrity and resistance to extreme temperatures and pressures for critical aerospace applications. These units are specified for hydraulic fluid cooling in military fighter jets, where durability under harsh conditions is essential.
- Mechanical Bonded:Mechanical bonded exchangers use physical joining methods without filler material, often for lower pressure tasks.
- Spiral Heat Exchanger:Spiral heat exchangers feature concentric spiral flow paths, offering efficient heat transfer for viscous fluids.
- Lamella Heat Exchanger:Lamella heat exchangers use parallel corrugated plates for high thermal efficiency in compact installations.
Welded technology commands a premium due to its performance, while Brazed solutions offer a balanced cost-efficiency profile.
Application:
The volume of heat generated by various aircraft systems directly influences the design and deployment of specialized heat exchanger applications.
- Engine Cooling:Engine cooling heat exchangers manage high thermal loads from aircraft engines, regulating oil and fuel temperatures for optimal operational performance. This segment represents the highest value due to extreme performance requirements and critical safety implications.
- Cabin Environmental Control:Cabin environmental control systems rely on heat exchangers to regulate air temperature and humidity for passenger comfort and avionics cooling. Demand is robust in commercial airliners and business jets, driven by passenger experience and complex cabin electronics.
- Hydraulic Cooling:Hydraulic cooling heat exchangers dissipate heat from hydraulic fluids, preventing overheating in flight control and landing gear systems.
- Fuel Cooling:Fuel cooling applications manage fuel temperature, often cooling other systems while preventing fuel from exceeding critical limits.
- Oil Cooling:Oil cooling heat exchangers maintain optimal lubricant temperatures for gearboxes and other mechanical components.
Engine Cooling applications represent the most mature segment, with Cabin Environmental Control exhibiting significant innovation.
End User:
Different end-user types exhibit distinct procurement patterns and performance priorities for aircraft heat exchangers.
- Military Aviation:Military aviation operators require heat exchangers capable of extreme performance under harsh conditions, including high G-forces and rapid temperature fluctuations. Procurement is concentrated in the United States and France, driven by fleet modernization and electronic warfare system integration.
- Aircraft Manufacturers:Aircraft manufacturers integrate heat exchangers into new airframe designs, demanding compact, lightweight, and highly efficient units. This segment focuses on initial certification and seamless integration into complex airframe architectures for commercial and defense programs.
- Airlines:Airlines primarily procure replacement and MRO heat exchangers, prioritizing reliability, cost-effectiveness, and safety standards.
- Maintenance Repair Organizations:Maintenance Repair Organizations (MROs) service and overhaul existing heat exchangers, offering repair and certification for various aircraft fleets.
- Business Jet Operators:Business jet operators seek compact, high-performance heat exchangers for cabin comfort and avionics cooling, emphasizing reliability.
Military Aviation procurement is highly concentrated among specialized suppliers, while Airlines spread demand across multiple MRO providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States aerospace manufacturing cluster drives significant demand for advanced aircraft heat exchangers. This demand stems from extensive military modernization programs and the robust commercial aviation sector. Airworthiness regulations from agencies such as the Federal Aviation Administration (FAA) govern component certification across all regions.
United States
Military modernization programs and the demand for next-generation commercial aircraft components propel the United States market. The Federal Aviation Administration (FAA) mandates rigorous testing and certification for all flight-critical components. Aerospace hubs in California, including those around Los Angeles, concentrate advanced materials research and specialized manufacturing for these critical thermal management systems.
France
Major aircraft manufacturing and defense procurement initiatives fuel demand for high-performance heat exchangers in France. The European Union Aviation Safety Agency (EASA) sets stringent standards for aerospace component design and production. Toulouse serves as a primary center for commercial aircraft assembly, integrating sophisticated thermal management solutions into new airframes.
United Kingdom
Defense fleet upgrades and a significant commercial aircraft MRO sector sustain the market for aircraft heat exchangers in the United Kingdom. The UK Civil Aviation Authority (CAA) enforces strict airworthiness requirements for component suppliers. Bristol's aerospace cluster supports advanced manufacturing and research for engine and airframe thermal systems.
Germany
Germany's strong focus on commercial aircraft component manufacturing and advanced materials research supports its heat exchanger market. The European Union Aviation Safety Agency (EASA) ensures compliance with safety and performance standards for all aerospace parts. Hamburg's aerospace industry integrates complex thermal management units into large commercial aircraft.
Japan
Domestic defense procurement and the production of commercial aircraft sub-components generate consistent demand for aircraft heat exchangers in Japan. The Japan Civil Aviation Bureau (JCAB) oversees safety and quality regulations for aviation components. Nagoya's aerospace cluster, anchored by major heavy industries, develops and manufactures specialized thermal solutions.
Global Aircraft Heat Exchanger Market Key Industry Players
Technological innovation dominates the current landscape, with manufacturers constantly developing lighter and more efficient thermal management solutions. The market exhibits a tiered structure, encompassing large, diversified aerospace conglomerates alongside specialized component manufacturers and MRO providers. Key strategic archetypes include integrated system suppliers, material science innovators, and aftermarket service specialists. Companies pursue strategic partnerships and portfolio diversification to enhance their market position.
On the premium-tier vector, Honeywell International Inc. represents a global leader, leveraging extensive research and development in materials science and thermal engineering. Safran S.A. exemplifies an integrated systems approach, specializing in engine and nacelle systems that incorporate advanced heat exchangers for both commercial and military platforms. RTX Corporation occupies a position with a broad portfolio, covering diverse commercial and military applications across its various business units.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| RTX Corporation |
| Liebherr Group |
| Parker Hannifin Corp. |
| Safran S.A. |
| Triumph Group |
| Meggitt PLC |
| General Electric Company |
| Boyd Corporation |
| Others |
Cost & Logistics Intelligence
Heightened regulatory focus from bodies like the Federal Aviation Administration (FAA) and European Union Aviation Safety Agency (EASA) on component lifecycle traceability is forcing heat exchanger suppliers to invest in quality control, which in turn influences pricing for certified parts. This dynamic also shapes the procurement patterns of aircraft manufacturers and Maintenance, Repair, and Overhaul (MRO) organizations.
Pricing Analysis
Input costs for aerospace-grade titanium and specialized aluminum alloys are directly passed through to component manufacturers, influencing final heat exchanger prices. The dominant pricing model involves long-term, contract-based offtake agreements, particularly for OEM integration into new aircraft programs. Price differentiation stems from certification level, such as FAA Part 25 or EASA CS-25, and the degree of customization required for specific airframes. Pricing softness runs through the aftermarket segment due to intense competition among MRO providers, making airlines the most price-sensitive buyers compared to aircraft manufacturers.
Supply Chain Analysis
Logistics costs for high-value, specialized aerospace components impact the delivered price of heat exchangers to manufacturing hubs. Supply concentration for critical raw materials, like high-purity titanium sponge and advanced aluminum composites, centers in the United States, Japan, and certain European producers. This reliance on a few global suppliers creates single-source vulnerability, potentially leading to bottlenecks. Distribution of finished heat exchangers primarily runs through direct channels to aircraft OEMs and through authorized MRO networks for aftermarket support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Aircraft Heat Exchanger Market offers a geographic-arbitrage play, where lower manufacturing costs in certain Asian regions can offset the higher material and certification expenses prevalent in Western aerospace hubs. This creates opportunities for strategic sourcing.
For Market Incumbents: Anticipate continued material science innovation to counter rising thermal loads from next-generation avionics, a persistent threat. Reinforce market position through strategic acquisitions of specialized additive manufacturing firms, securing advanced fabrication capabilities. Invest heavily in certification processes for new lightweight composites to maintain a competitive edge against emerging material alternatives. Control over critical raw material supply chains acts as a lever against cost volatility. For New Entrants and Emerging Players: Enter via niche applications within the Urban Air Mobility (UAM) sector, which requires novel, compact thermal management solutions. Target battery cooling systems for eVTOL aircraft, a segment currently under-served by legacy suppliers. A go-to-market angle focusing on rapid prototyping and agile certification for specific UAM platforms offers a pathway to market penetration. Specialize in advanced materials that reduce weight for these nascent platforms. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized component manufacturers possessing proprietary additive manufacturing techniques and strong intellectual property in thermal engineering. Long-term viability extends through the next 5-10 years, driven by continuous fleet modernization and the emergence of UAM. Acquisition targets include mid-sized firms with established certification pedigrees and strong R&D pipelines in advanced materials. The signal to watch is the acceleration of large-scale commercial contracts for UAM thermal solutions.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Additive Manufacturing Specialist | Secures proprietary technology for complex, lightweight heat exchanger geometries, enhancing product performance. |
| Investment in Advanced Materials R&D | Develops next-generation aluminum and titanium composites, reducing component weight for fuel efficiency. |
| Expansion into Urban Air Mobility (UAM) Thermal Solutions | Captures demand from emerging eVTOL aircraft for compact battery and motor cooling systems. |
| Certification of New Composite Materials | Ensures compliance with stringent FAA and EASA airworthiness standards, enabling market access. |
| Long-term Supply Agreements for Raw Materials | Mitigates material cost volatility and ensures consistent supply of aerospace-grade alloys. |
Research Approach
Coverage spans the United States, Europe, and Asia-Pacific, with primary inputs from each region. The methodology combined in-depth interviews with aerospace engineers, procurement managers at OEMs, MRO specialists, and regulatory officials. Secondary validation drew from FAA and EASA airworthiness directives, aerospace OEM financial filings, and trade association publications. Bottom-up and top-down triangulation ensured data integrity.
Volume and value outputs were modeled at a granular level across product type, technology, application, end-user, and material type dimensions. The analytical framework projected market evolution over the forecast period, deriving compound annual growth rates from historical trends and future demand drivers. Key industry-specific forecast inputs included global aircraft delivery forecasts and defense spending budgets for fleet modernization programs. This approach captured market shifts effectively.
Inputs from major aerospace OEMs and regulatory bodies were available through the study window; gaps in specific material cost data introduce uncertainty bands. Forecasts reflect assumptions concerning technological advancements and regulatory stability. Material cost volatility and unforeseen certification delays are specific risk factors that could revise these projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Jack Market
Aircraft
Aircraft Window Frame Market
Aircraft
Search and Rescue Helicopter Market
Aircraft
Active Air Deflector Market
Aircraft
Aircraft Wheels Brakes Market
Aircraft
Aircraft Autopilot System Market
Aircraft
Global Electronic Flight Bag Market
Aircraft
Winglets Market
Aircraft
Military Rotorcraft Market
Aircraft
Europe Attack Helicopter Market
Aircraft
Latin America Business Jet Market
Aircraft
Helicopter Wheels Market
Aircraft
Air Starter Market
Aircraft
Middle-East and Africa Commercial Aircraft Market
Aircraft
Supersonic Jet Market
Aircraft
Commercial Aircraft in-Seat Power System Market