
 Air Transport Modifications Market | 2026-2036
Air Transport Modifications Market Size, Share, and Industry Trends Forecast 2026-2036
Air Transport Modifications Market Outlook
Composite materials is decoupling airframe modification economics from traditional aluminum-reliant cost structures. Boeing Company leverages its integrated engineering and modification centers to control large commercial retrofit programs. AAR Corp specializes in narrow-body cargo conversions, sustaining aftermarket revenue through long-term operator contracts. Honeywell International dominates avionics upgrade roadmaps, extending its influence across flight-deck modernization mandates.
Air transport modifications encompass structural, interior, avionics, and exterior alterations to certified aircraft, typically involving supplemental type certificates, engineering change orders, and compliance with fatigue-life extension protocols to extend operational utility or adapt airframes to new missions. Interior modifications and avionics retrofits capture expanding margin pools as airlines prioritize passenger experience differentiation and next-generation navigation compliance. Composite materials and additive manufacturing segments accelerate as OEM-approved repair schemes and 3D-printed cabin components reduce lead times for obsolete part replacement.
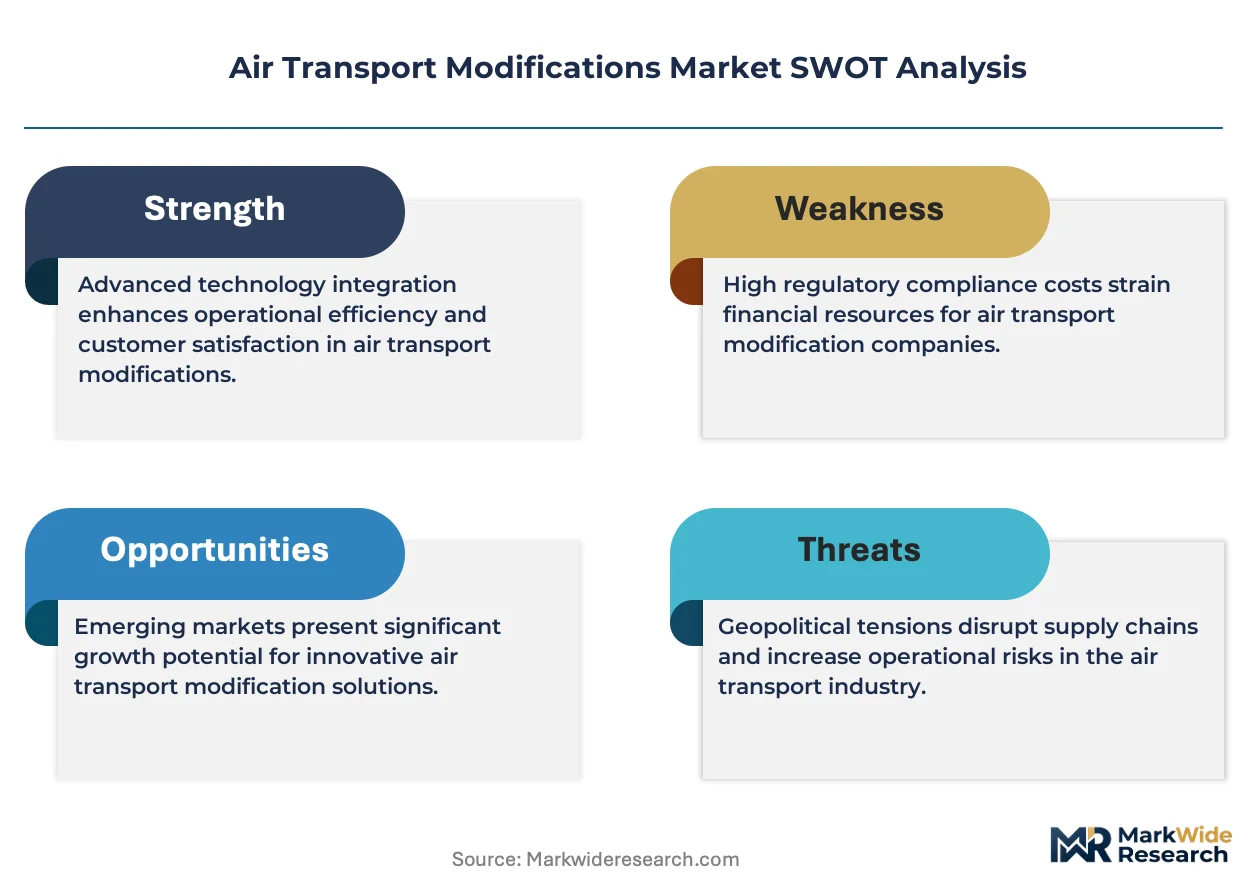
FAA airworthiness directives, EASA certification standards, and ICAO annex provisions shape modification demand by mandating structural inspections, avionics upgrades, and emissions-related retrofit timelines. Regulatory compliance costs filter directly into operator procurement decisions, favoring modification providers with bilateral approval capabilities across multiple jurisdictions. Stakeholders must monitor evolving sustainability-linked certification requirements and position engineering resources against anticipated mandates for noise-reduction and emissions-control retrofits.
Market Dynamics
Fleet age demographics and emissions compliance deadlines are compressing modification timelines, forcing operators to bundle avionics, structural, and interior upgrades into single downtime windows rather than sequential retrofit campaigns.
Growth Catalysts
- FAA Airworthiness Directives:Mandatory structural inspection intervals for aging narrow-body fleets are generating predictable modification demand from US-based carriers.
- Sustainable Aviation Fuel compatibility:Engine and fuel system retrofits to accommodate SAF blends are accelerating as European operators face EU Green Deal emissions trajectories.
- Additive manufacturing:OEM-approved 3D-printed cabin components and obsolete part reproduction are reducing lead times from months to weeks for interior modification programs.
Market Restraints
- Titanium and aerospace-grade aluminum volatility:Input cost swings compress margins on structural modification contracts with fixed-price terms.
- Supplemental Type Certificate backlog:FAA and EASA certification queues extend program timelines, freezing capital in work-in-progress inventory.
- Certified technician scarcity:A&P mechanics with composite repair and avionics integration skills command wage premiums that inflate labor cost structures.
Strategic Opportunities
- India domestic fleet expansion:Low-cost carriers operating leased mid-life aircraft create demand for rapid cabin reconfiguration and connectivity upgrades.
- Freighter conversion surge:E-commerce logistics operators are sourcing passenger-to-cargo modification slots years in advance, securing long-term revenue visibility for conversion centers.
- Flight deck modernization mandates:Next-generation navigation requirements under ICAO Annex 10 are forcing avionics architecture replacements that bundle connectivity and surveillance upgrades.
Industry Challenges
- Legacy system integration complexity:New avionics suites must interface with analog-era wiring harnesses, requiring custom engineering that defies standardization.
- Certification timeline unpredictability:Engineering change order approvals from national aviation authorities vary by jurisdiction, complicating multi-fleet operator scheduling.
- Supply chain reconfiguration friction:Post-pandemic parts distribution networks remain fragmented, causing kitting delays that cascade through modification hangar schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Transport Modifications Market |
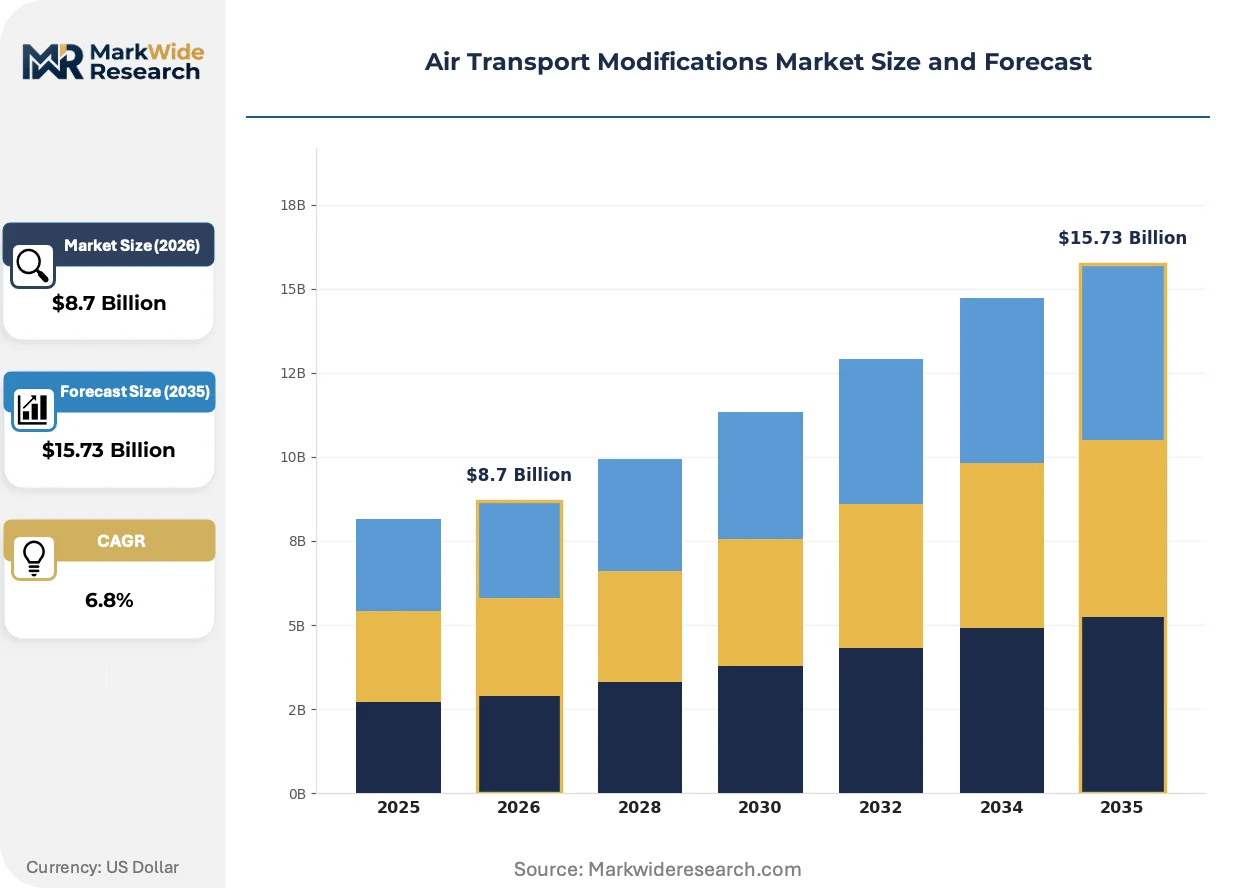
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
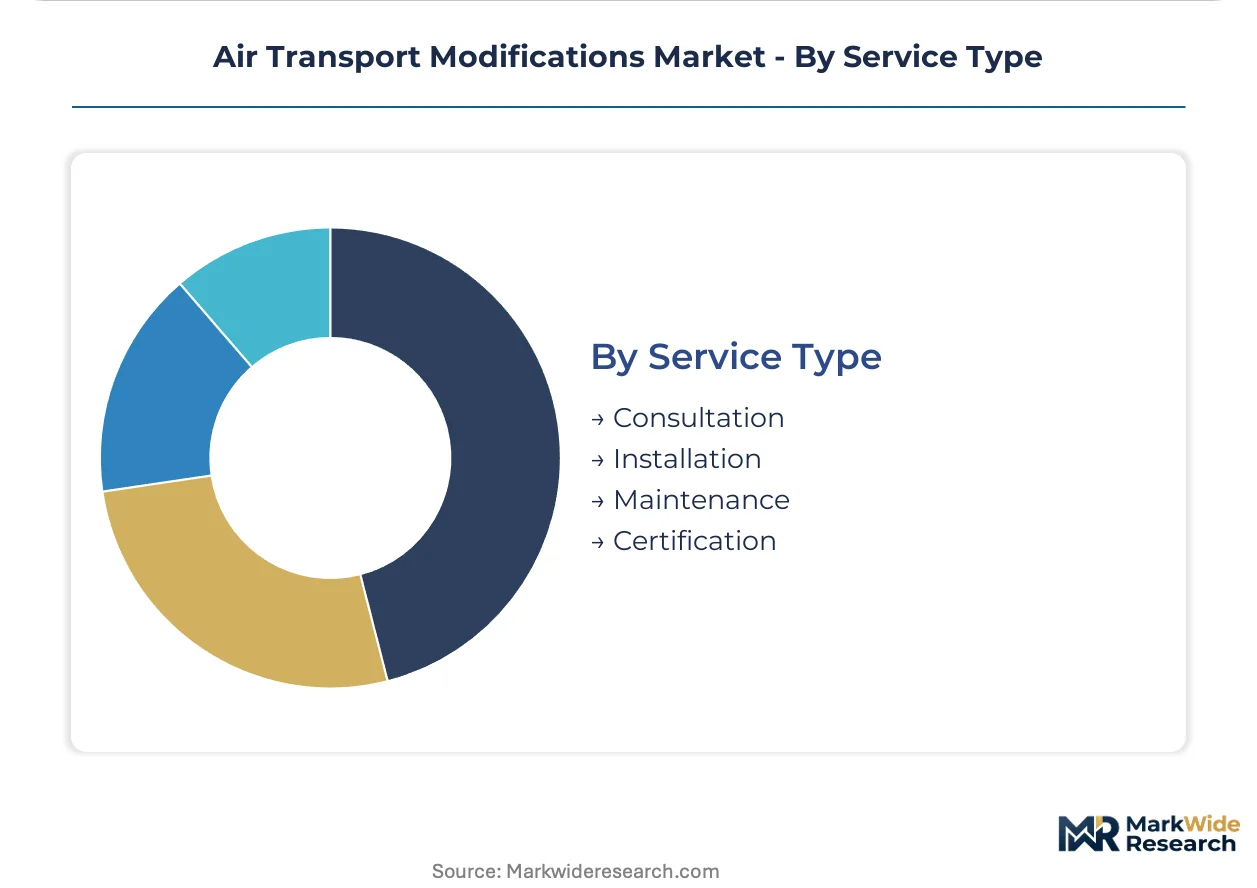
| Segmentation | Modification Type: Interior, Exterior, Avionics, Structural End User: Commercial Airlines, Cargo Operators, Private Jets, Government Agencies Technology: 3D Printing, Composite Materials, Additive Manufacturing, Retrofit Solutions Service Type: Consultation, Installation, Maintenance, Certification |
| Companies Covered | Air France-KLM, Cobham, Boeing Company, Commuter Air Technology, Textron, AAR Corp, Deutsche Lufthansa Aktiengesellschaft, Hawker Pacific, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Transport Modifications Market Strategic Shifts
Digital thread technologies and predictive maintenance platforms are merging with physical modification workflows, collapsing the traditional separation between engineering design, certification documentation, and shop floor execution.
Structural health monitoring systems using fiber-optic strain sensors are integrating into wing and fuselage modification packages. Regional carriers adopting these retrofits are compressing inspection intervals from calendar-based to condition-based maintenance cycles. This integration is enabling operators to extend airframe service life beyond original design limits while maintaining FAA fatigue-life extension protocol compliance.
EASA's CS-25 regulatory updates on electrical system safety are mandating arc-fault circuit protection retrofits for aging transport category aircraft. European modification centers report expanded backlogs for power distribution system overhauls. Narrow-body operators with significant intra-European exposure are prioritizing these programs to avoid operational restrictions during peak summer scheduling.
Power-by-the-hour maintenance contracts are displacing traditional time-and-material invoicing for avionics upgrade programs. Lessors and asset managers now bundle modification costs into lease rate factors, transferring technical risk to OEM-affiliated service providers. This restructuring is most visible in Ireland and Singapore, where aircraft leasing concentration has created specialized modification financing vehicles.
Air Transport Modifications Market Segmentation
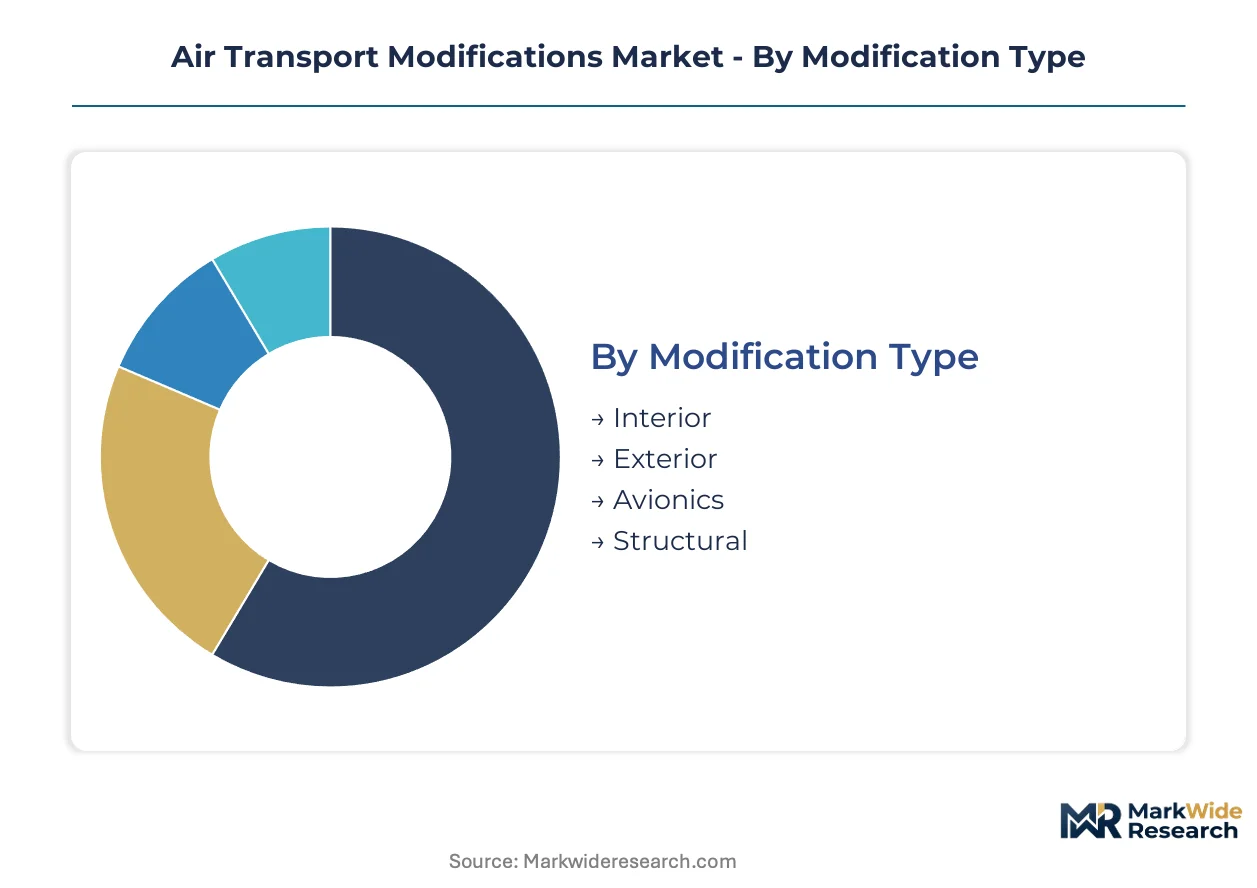
Modification program economics vary sharply across aircraft systems and operator profiles. Segment-specific procurement patterns determine which engineering capabilities capture margin and which face commoditization pressure.
Modification Type:
Technical complexity and certification burden diverge substantially across airframe systems, creating tiered supplier specialization.
- Structural:Wing box reinforcements, fuselage frame repairs, and fatigue-life extension protocols demand FAA fatigue-life extension protocol compliance. Demand concentrates in Wichita modification centers serving US narrow-body operators facing mandatory inspection intervals. Titanium and aerospace-grade aluminum input costs compress margins on fixed-price contracts.
- Avionics:Flight deck modernization encompasses navigation system replacements, connectivity upgrades, and surveillance architecture overhauls. European operators under EASA mandates are bundling these programs to meet ICAO Annex 10 next-generation navigation deadlines. Honeywell International dominates upgrade roadmaps through integrated system architectures.
- Interior:Cabin reconfiguration programs address passenger experience differentiation and obsolete part replacement. Additive manufacturing is reducing lead times for 3D-printed cabin components from months to weeks.
- Exterior:Livery modifications, winglets, and aerodynamic fairings address fuel efficiency and branding requirements. Programs typically coordinate with scheduled maintenance windows.
Mature deployment sits with Structural modifications. Newer deployment is concentrated in Avionics as regulatory mandates accelerate replacement cycles.
End User:
Procurement scale and contract structure vary by operator business model and fleet ownership patterns.
- Commercial Airlines:Full-service and low-cost carriers retrofit aging fleets for fuel efficiency and passenger experience differentiation. US-based carriers generate predictable demand from FAA airworthiness directives on narrow-body fleets. Power-by-the-hour contracts are displacing time-and-material invoicing for avionics programs.
- Cargo Operators:E-commerce logistics operators are sourcing passenger-to-cargo modification slots years in advance. AAR Corp specializes in narrow-body conversions, sustaining aftermarket revenue through long-term operator contracts.
- Private Jets:Customization requirements and shorter modification timelines characterize this segment. Demand centers on connectivity upgrades and interior reconfiguration.
- Government Agencies:Military transport and special mission aircraft modifications follow defense procurement protocols with extended certification timelines.
Volume leadership rests with Commercial Airlines. Steepest expansion trajectory belongs to Cargo Operators as freighter conversion demand outstrips hangar capacity.
Technology:
Material and process innovation is decoupling modification economics from traditional manufacturing constraints.
- Composite Materials:Carbon fiber reinforced polymers and advanced laminates enable weight reduction and corrosion resistance in structural repairs. OEM-approved repair schemes are accelerating adoption across MRO networks.
- Additive Manufacturing:3D printing of cabin components and obsolete part reproduction collapses lead times. Boeing Company leverages integrated engineering centers to control certification of printed airframe elements.
- 3D Printing:Distinct from broader additive manufacturing, this segment focuses on polymer-based cabin interior components and non-structural elements with shorter qualification paths.
- Retrofit Solutions:Integrated modification packages bundle multiple systems into single downtime windows, reducing operational disruption for time-sensitive operators.
Certification maturity favors Composite Materials. Fastest capability buildout is occurring in Additive Manufacturing as OEMs establish approved supplier networks.
Service Type:
Value capture migrates toward integrated program delivery rather than discrete task execution.
- Installation:Physical modification execution in hangar environments requires A&P mechanics with composite repair and avionics integration skills. Certified technician scarcity inflates labor cost structures.
- Certification:Supplemental Type Certificate acquisition and engineering change order approval from FAA and EASA determine program timelines. Backlog in national aviation authority queues extends capital commitment periods.
- Consultation:Front-end engineering and regulatory strategy services help operators bundle upgrades into optimal downtime windows.
- Maintenance:Post-modification support and condition-based monitoring sustain airworthiness through extended service life.
Revenue concentration aligns with Installation. Emerging value creation is shifting toward Certification as regulatory complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modification demand concentrates where aging narrow-body fleets intersect with stringent regulatory mandates. The United States anchors volume through FAA airworthiness directives on legacy aircraft. European operators face EASA emissions deadlines. Asian carriers retrofit leased mid-life assets for fuel efficiency.
United States
FAA airworthiness directives on Boeing 737 and Airbus A320 fleets generate predictable structural modification demand. Wichita, Kansas hosts dense clusters of MRO infrastructure and OEM modification centers serving domestic carriers. Pacific Northwest engineering hubs specialize in composite repair schemes and fatigue-life extension protocols.
Germany
Lufthansa Technik drives avionics modernization across European narrow-body and wide-body fleets. EASA CS-25 electrical system safety mandates are accelerating arc-fault circuit protection retrofits. Hamburg modification centers report expanded backlogs for power distribution overhauls ahead of peak summer scheduling windows.
India
Low-cost carriers operating leased mid-life aircraft create demand for rapid cabin reconfiguration and connectivity upgrades. DGFT import policies on aviation components influence modification kit sourcing timelines. Bangalore and Hyderabad MRO clusters are building composite repair capabilities to serve domestic fleet expansion.
Singapore
Aircraft leasing concentration has created specialized modification financing vehicles bundling upgrade costs into lease rate factors. Power-by-the-hour contracts dominate avionics procurement for lessor-managed fleets. Seletar Aerospace Park hosts engineering centers executing freighter conversion programs for e-commerce logistics operators.
United Kingdom
Heathrow and Gatwick proximity drives demand for quick-turn interior modifications minimizing aircraft downtime. CAA alignment with EASA certification standards streamlines supplemental type certificate approvals for European-registered aircraft. Southwest England engineering clusters specialize in military transport modifications following defense procurement protocols.
Air Transport Modifications Market Competitive Environment
Capacity expansion dominates the current landscape as conversion centers add hangar slots to capture freighter modification backlogs. The vendor base separates into three tiers: OEM-affiliated service providers with integrated engineering and certification capabilities, independent MRO specialists executing discrete structural and interior programs, and leasing-affiliated modifiers bundling upgrades into asset management contracts. M&A activity concentrates on acquiring supplemental type certificate portfolios. Geographic expansion into India and Southeast Asia represents the second dominant competitive move.
Within the OEM-integrated tier, Boeing Company and Airbus SE exemplify players controlling large commercial retrofit programs through captive engineering centers. AAR Corp occupies a position among narrow-body cargo conversion specialists sustaining aftermarket revenue through long-term operator contracts. Honeywell International sits within the avionics architecture tier, anchoring flight-deck modernization roadmaps through integrated system offerings that bundle connectivity and surveillance upgrades.
| Leading Market Players |
|---|
| Air France-KLM |
| Cobham |
| Boeing Company |
| Commuter Air Technology |
| Textron |
| AAR Corp |
| Deutsche Lufthansa Aktiengesellschaft |
| Hawker Pacific |
| Honeywell International |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up modification specialists in Wichita and the Pacific Northwest have consolidated hangar capacity and engineering talent pools, tightening supply discipline and supporting pricing power for structural retrofit programs serving FAA-mandated narrow-body fleets.
Pricing Analysis
Volume leadership in structural modifications compresses margins on fixed-price contracts for aging narrow-body fleets, while avionics modernization programs capture premium pricing through Honeywell's integrated system architectures and power-by-the-hour contract structures. Price differentiation hinges on certification tier—FAA supplemental type certificate holders command 15-25% premiums over non-certified competitors—and geographic proximity to operator bases, with Wichita-based providers pricing below Pacific Northwest peers due to lower labor cost structures. Pricing pressure stems from titanium and aerospace-grade aluminum volatility inflating input costs on locked contracts. Cargo operators exhibit lowest price sensitivity, securing conversion slots years in advance, while regional carriers leasing mid-life aircraft remain most price-sensitive, prioritizing rapid turnaround over capability breadth.
Supply Chain Analysis
Titanium and aerospace-grade aluminum supply rests on Russian VSMPO-AVISMA, Chinese Baoji Titanium, and US-based ATI, creating concentrated dependency for structural modification programs. Carbon fiber reinforced polymers draw from Japanese Toray, US Hexcel, and German SGL Carbon, while avionics components source from Honeywell's domestic fabrication and European Thales production. Single-source vulnerability in Russian titanium following sanctions exposure has forced supply chain reconfiguration toward alternative producers. Distribution runs through OEM-affiliated service centers in Wichita, Hamburg, and Singapore, with independent MRO specialists competing on kitting speed and certification breadth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air transport modifications sector sits in a technology-transition phase where additive manufacturing and composite repair schemes are displacing traditional aluminum-dependent fabrication and obsolete part sourcing.
For Market Incumbents: Extend engineering center capabilities into digital thread technologies and predictive maintenance platforms to defend against independent MRO specialists acquiring STC portfolios. Backward integration into additive manufacturing certification—following Boeing's captive control of printed airframe element approvals—creates durable differentiation as lead time compression becomes table stakes for interior modification programs. For New Entrants and Emerging Players: Leasing company technical teams in Ireland and Singapore represent the most penetrable channel partner type, as power-by-the-hour contract restructuring transfers modification procurement decisions from operators to asset managers. Target India's domestic low-cost carrier fleet expansion, where DGFT import policy friction creates demand for rapid cabin reconfiguration capabilities that bypass traditional kitting delays. For Investors and Strategic Acquirers: Distressed-cycle entries favor narrow-body cargo conversion specialists with multi-year e-commerce logistics operator backlogs in the United States and Singapore. Long-term viability hinges on positioning against SAF compatibility retrofit demand acceleration under EU Green Deal trajectories. Watch FAA supplemental type certificate queue lengths as the inflection indicator—backlog compression signals margin expansion opportunity, while extension warns of capital freeze risk.| Strategic Initiative | Industry Significance |
|---|---|
| STC Portfolio Acquisition | Engineering change order backlogs at FAA and EASA compress timelines for organic certification investment. |
| Additive Manufacturing Certification | OEM-approved 3D-printed cabin components reduce lead times from months to weeks for obsolete part replacement. |
| Freighter Conversion Capacity Expansion | E-commerce logistics operators are sourcing passenger-to-cargo modification slots years in advance. |
| Power-by-the-Hour Contract Structuring | Lessor-managed fleets in Ireland and Singapore now bundle modification costs into lease rate factors. |
| Composite Repair Capability Buildout | FAA fatigue-life extension protocol compliance demands specialized A&P mechanics with carbon fiber expertise. |
Study Parameters
Document review covered FAA airworthiness directive filings, EASA certification databases, and ICAO Annex 10 regulatory updates, complemented by interviews with modification center operations directors, MRO procurement managers, airline fleet planning executives, and aircraft leasing technical asset managers. Secondary validation drew from OEM service bulletins, STC holder registries, and customs data on titanium and composite material imports. Bottom-up triangulation across individual program economics and top-down validation against fleet age demographics and regulatory mandate timelines anchored market sizing.
Historical modification program volumes were cross-referenced against panel input from engineering directors at Wichita, Hamburg, and Singapore modification centers to establish baseline demand patterns across the projection horizon. Segmentation modeling incorporated modification type, end-user operator profile, material technology tier, and service delivery structure. CAGRs were derived from regression analysis of fleet retirement schedules, regulatory compliance deadlines, and SAF retrofit adoption curves, with sensitivity testing against titanium price volatility and certified technician wage inflation.
Several conditions sit outside the modeled scope, including unilateral trade restrictions on Russian titanium, accelerated ICAO emissions mandates beyond current Annex 16 trajectories, and breakthrough advances in structural health monitoring that could compress inspection-based modification demand. Forecasts reflect documented assumptions on regulatory timeline adherence and supply chain reconfiguration speed. A small set of named triggers warrants ongoing watch: FAA supplemental type certificate queue dynamics, EU Green Deal SAF mandate enforcement intensity, and India DGFT aviation component import policy revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Mobility
North America Offshore Helicopter Services Market
Air Mobility
Air Crane Helicopter Market
Air Mobility
Flying Jetpacks Market
Air Mobility
Advanced Aerial Mobility Market
Air Mobility
Middle East and Africa General Aviation Market
Air Mobility
Air Transport USM Market
Air Mobility
Urban Air Mobility (UAM) Market
Air Mobility
Urban Autonomous Air Mobility Market
Air Mobility
Off-Shore Helicopters Market
Air Mobility
Global Aerial Firefighting Market
Air Mobility
Helicopter-Based Transportation Market
Air Mobility
Airborne Pods Market
Air Mobility
Global Aerodynamics Market
Air Mobility
Global Flying Cars Market
Air Mobility
Flying Motorbikes Market
Air Mobility
Asia-Pacific Charter Jet Service Market