

Aircraft Flap Track Fairing Retrofit Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Flap Track Fairing Retrofit Kits Market Insights
Multi-source procurement for composite aerostructures is shifting toward vertically integrated supply arrangements among top-tier aerostructure houses. Spirit AeroSystems leverages its Wichita manufacturing complex to control raw carbon fiber conversion through final fairing assembly. FACC AG sustains Austrian engineering leadership in resin-transfer-molded flap track components for European retrofit programs. Lufthansa Technik anchors the aftermarket channel through Hamburg-based MRO facilities that bundle fairing replacement with heavy-check intervals.
Aircraft flap track fairing retrofit kits are aerodynamic surface enclosures installed over flap support mechanisms, typically fabricated from carbon fiber-epoxy prepregs or titanium sheet assemblies measuring 1.5–3.2 meters in length, designed to reduce drag and protect control linkages from debris and corrosion. Carbon fiber kits dominate current retrofit volume due to weight savings of forty percent versus legacy aluminum equivalents, though titanium-based kits retain preference on military platforms where ballistic tolerance and heat resistance outweigh mass considerations. Commercial jets absorb the majority of application demand as operators pursue fuel-burn reductions to offset volatile jet-fuel economics, while unmanned aerial vehicles represent a nascent but technically distinct segment requiring scaled fairing geometries.
FAA airworthiness directives and EASA certification standards jointly govern material qualification, lightning-strike protection, and fatigue-life documentation for retrofit installations, creating compliance barriers that favor established suppliers with prior type-certificate amendments. The EPA's National Emission Standards for Hazardous Air Pollutants additionally pressure airlines toward drag-reduction retrofits as part of broader fuel-efficiency and emissions-compliance strategies. Stakeholders must monitor evolving OEM service-bulletin harmonization between Boeing and Airbus platforms, as divergence in fastener patterns and interface geometries directly influences kit interoperability and inventory carrying costs across distributed MRO networks.
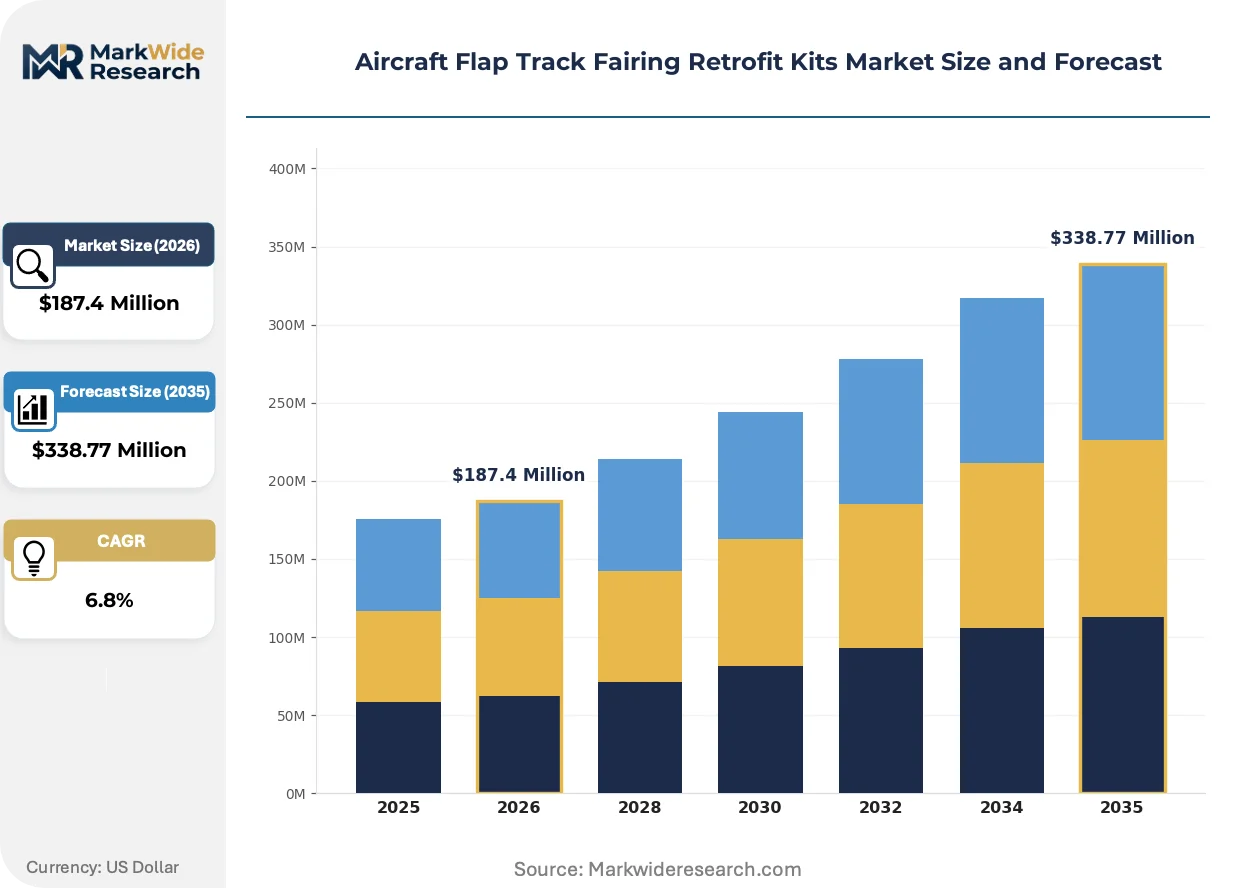
Market Dynamics
FAA airworthiness directives mandating structural fatigue inspections on aging narrow-body fleets are forcing accelerated replacement cycles for flap track fairing components, compressing procurement timelines from scheduled heavy checks to reactive retrofit campaigns.
Growth Catalysts
- Composite Material Substitution:Carbon fiber-epoxy prepregs deliver forty percent weight reduction versus legacy aluminum assemblies, compelling fuel-cost-conscious operators to prioritize kit upgrades during C-check intervals.
- EPA National Emission Standards for Hazardous Air Pollutants:Regulatory pressure on airlines to demonstrate fuel-efficiency improvements is channeling capital toward drag-reduction retrofits as compliance documentation.
- Narrow-Body Fleet Concentration in the United States:The installed base of Boeing 737 and Airbus A320 family aircraft generates sustained retrofit volume as these platforms age through critical fatigue-life thresholds.
Market Restraints
- Raw Carbon Fiber Price Volatility:Prepreg material costs fluctuate with aerospace-grade fiber supply constraints, compressing kit margins for converters without backward integration into fiber production.
- Supplier Concentration in Wichita and Hamburg:Aerostructure assembly and MRO bundling capabilities cluster at dominant manufacturing complexes, creating single-source vulnerability for distributed airline procurement.
- Type-Certificate Amendment Burden:FAA and EASA certification standards require extensive fatigue-life documentation and lightning-strike protection validation, extending qualification timelines for new kit entrants.
Strategic Opportunities
- Unmanned Aerial Vehicle Platform Expansion:Scaled fairing geometries for military and commercial drones represent technically distinct design requirements with limited incumbent competition.
- European Green Deal Aviation Decarbonization Incentives:EU funding mechanisms for fleet modernization are subsidizing drag-reduction retrofits on A320 family aircraft operated by flag carriers.
- Resin-Transfer-Molding Process Convergence with Automated Fiber Placement:Hybrid manufacturing techniques are reducing labor content in complex fairing geometries while maintaining structural performance.
Industry Challenges
- Composite Repair Technician Scarcity:Airlines and MRO facilities face pipeline constraints for certificated personnel capable of inspecting and repairing carbon fiber-epoxy damage in flap track fairing installations.
- Legacy Fastener Pattern Divergence:Boeing and Airbus platform interface geometries lack harmonization, forcing kit suppliers to maintain discrete inventory stocks and complicating interoperability across mixed fleets.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Flap Track Fairing Retrofit Kits Market Trends and Innovations
Automated manufacturing processes and regulatory harmonization pressures are compressing kit development cycles while reshaping how airlines bundle retrofit procurement with scheduled maintenance events.
Thermoplastic resin systems are overtaking thermoset epoxies in next-generation flap track fairing designs due to improved damage tolerance and weldability. Regional operators in Southeast Asia are adopting these materials at accelerated pace to reduce MRO turnaround times. This transition is overtaking traditional repair-station business models that relied on adhesive bonding expertise and extended cure cycles.
REACH regulation amendments on persistent organic pollutants are restricting certain flame-retardant chemistries previously standard in fairing interiors. European kit suppliers are reformulating resin systems to maintain EASA certification while eliminating restricted substances. Narrow-body retrofit programs in Germany and France are absorbing these compliance costs earliest, creating a phased regulatory burden across the continent.
Airline engineering departments are consolidating vendor relationships from multi-source procurement to sole-source framework agreements with aerostructure houses. This consolidation is displacing independent distributors who previously stocked interchangeable hardware kits. The United States exhibits the most pronounced concentration, where major carriers now contract directly with Wichita-based manufacturers for fleet-wide retrofit campaigns.
Aircraft Flap Track Fairing Retrofit Kits Market Segmentation
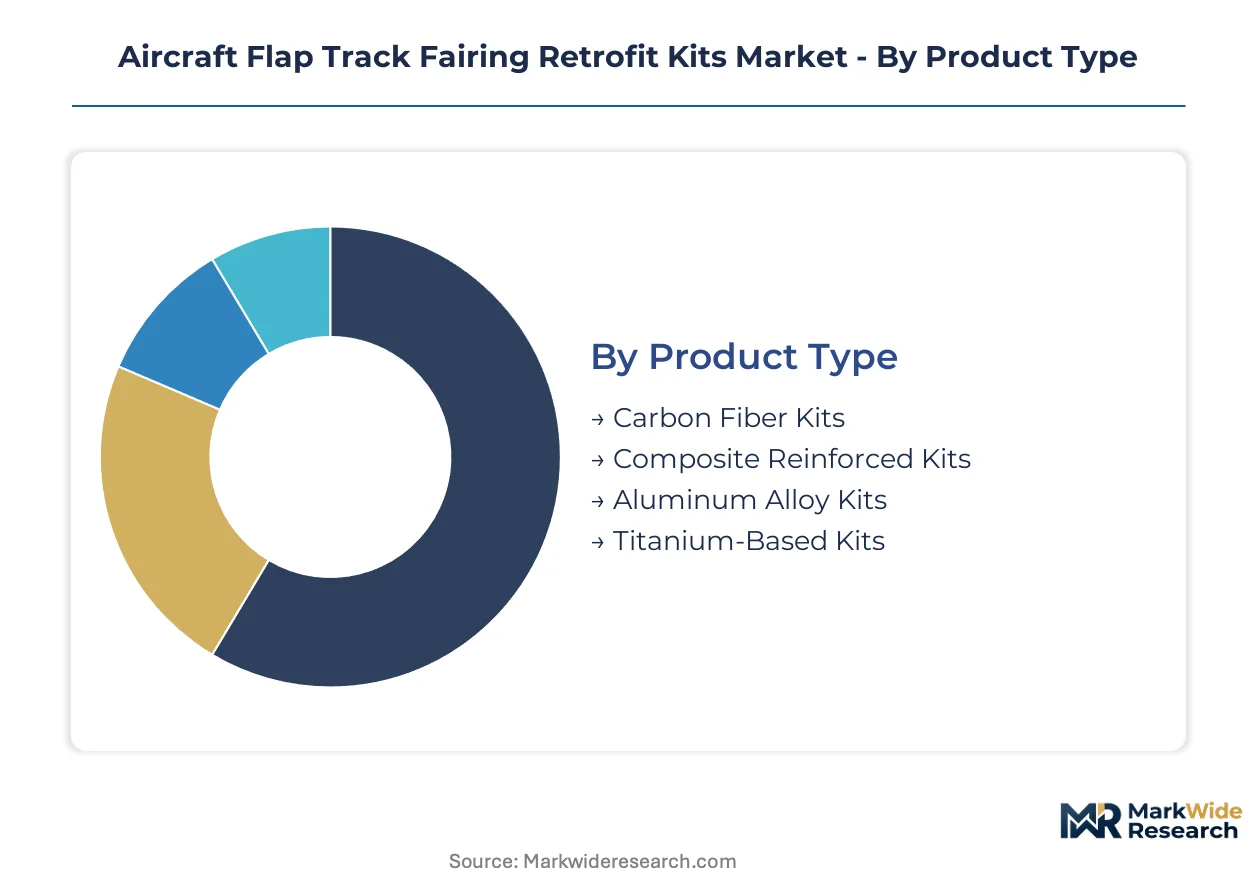
Retrofit kit procurement varies sharply by material class, manufacturing method, and downstream channel. Each segmentation dimension carries distinct capital requirements, certification burdens, and margin profiles that shape supplier positioning and airline sourcing strategy.
Product Type:
Capital intensity escalates dramatically from legacy metals to aerospace-grade composites, with prepreg autoclave curing demanding the steepest upfront tooling investment.
- Carbon Fiber Kits:Fabricated from carbon fiber-epoxy prepregs in 1.5–3.2 meter lengths, these assemblies achieve forty percent weight reduction versus aluminum equivalents. Commercial airlines in the United States prioritize these kits during C-check intervals to capture fuel-burn savings under volatile jet-fuel economics.
- Titanium-Based Kits:Sheet titanium assemblies retain preference on military platforms where ballistic tolerance and heat resistance outweigh mass considerations. Defense procurement channels in the United States sustain demand despite higher per-unit material costs and specialized machining requirements.
- Composite Reinforced Kits:Hybrid laminates combining carbon fiber with glass or aramid layers balance cost and performance for regional operators.
- Aluminum Alloy Kits:Legacy 2024-T3 and 7075-T6 sheet metal constructions persist in price-sensitive retrofit campaigns on aging narrow-body fleets.
Carbon fiber kits absorb the bulk of installed capacity; titanium-based kits are expanding most quickly in defense applications.
Technology:
Process innovation is compressing qualification timelines and reshaping which manufacturing approaches airlines specify in fleet-wide retrofit contracts.
- Automated Assembly:Robotic fiber placement and automated drilling reduce labor content in complex fairing geometries while maintaining FAA fatigue-life documentation standards. Wichita-based aerostructure houses deploy these systems to meet compressed procurement timelines from reactive retrofit campaigns.
- Aerodynamic Design Enhancements:Computational fluid dynamics-optimized profiles reduce form drag by refining fairing-to-wing interface contours. European retrofit programs on A320 family aircraft absorb these design iterations earliest under EU Green Deal aviation decarbonization incentives.
- 3D Printing:Selective laser sintering of titanium and polymer composites enables low-volume production of bracketry and interface fittings.
- Advanced Coatings:Polyurethane and fluoropolymer topcoats extend service intervals through improved UV and erosion resistance.
Automated assembly dominates current retrofit volume; aerodynamic design enhancements are climbing the fastest as operators pursue incremental drag reduction.
Application:
Platform scale and operational tempo determine kit specification, with wide-body and narrow-body fleets presenting divergent interface geometries and replacement cycles.
- Commercial Jets:Boeing 737 and Airbus A320 family aircraft generate sustained retrofit volume as these platforms age through critical fatigue-life thresholds. FAA airworthiness directives mandating structural fatigue inspections force accelerated replacement cycles, compressing procurement from scheduled heavy checks to reactive campaigns.
- Unmanned Aerial Vehicles:Scaled fairing geometries for military and commercial drones represent technically distinct design requirements with limited incumbent competition. These platforms demand abbreviated lead times and geometric flexibility absent from manned aircraft certification pathways.
- Military Aircraft:Tactical airlifters and tankers prioritize damage tolerance and field repairability over weight minimization.
- Business Aviation:Corporate jet operators pursue aesthetic and performance upgrades during scheduled refurbishment intervals.
Commercial jets command the largest share of retrofit expenditure; unmanned aerial vehicles are gaining share fastest as defense and logistics applications proliferate.
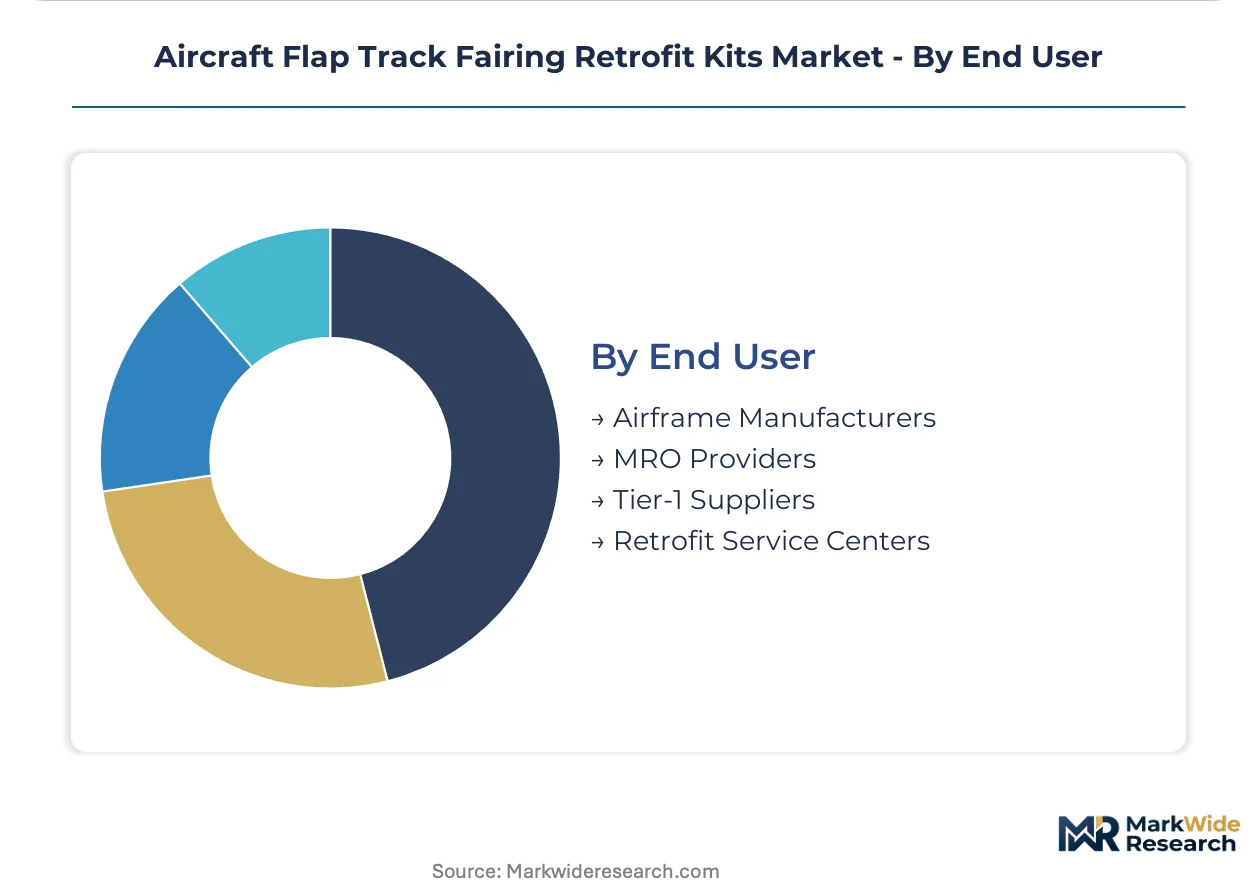
End User:
Channel structure is consolidating from fragmented distributor networks toward direct OEM and tier-1 relationships, altering pricing transparency and inventory risk allocation.
- MRO Providers:Lufthansa Technik and comparable facilities bundle fairing replacement with heavy-check intervals, capturing aftermarket value through Hamburg-based technical capabilities. These operators increasingly specify kit content through sole-source framework agreements rather than multi-source procurement.
- Airframe Manufacturers:Spirit AeroSystems leverages Wichita manufacturing complexes to control raw carbon fiber conversion through final fairing assembly, displacing independent distributors who previously stocked interchangeable hardware.
- Tier-1 Suppliers:Subcontractors to Boeing and Airbus maintain captive production for original equipment, extending into retrofit channels.
- Retrofit Service Centers:Independent stations perform kit installation under DER-approved repairs, serving operators outside major carrier maintenance networks.
MRO providers handle the majority of installed retrofit volume; airframe manufacturers are deepening their aftermarket presence fastest through vertical integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon fiber feedstock availability near Wichita anchors North American retrofit kit production, while Hamburg and Toulouse clusters concentrate European MRO bundling capabilities.
United States
The installed base of Boeing 737 and Airbus A320 family aircraft generates sustained retrofit volume as aging narrow-bodies pass critical fatigue-life thresholds. FAA airworthiness directives mandating structural inspections compress procurement timelines from scheduled heavy checks to reactive campaigns. Wichita-based manufacturing complexes control raw carbon fiber conversion through final fairing assembly.
Germany
Lufthansa Technik's Hamburg facilities anchor the aftermarket channel by bundling fairing replacement with heavy-check intervals for A320 family operators. EU Green Deal aviation decarbonization incentives subsidize drag-reduction retrofits on flag carrier fleets. REACH regulation amendments on persistent organic pollutants force resin system reformulations for EASA certification compliance.
France
Aerodynamic design enhancements for A320 family retrofit programs absorb computational fluid dynamics-optimized profiles earliest under fleet modernization mandates. EASA certification standards govern material qualification and lightning-strike protection validation. Toulouse-area technical centers coordinate with Hamburg MRO networks on cross-border kit interoperability.
Austria
FACC AG sustains engineering leadership in resin-transfer-molded flap track components for European retrofit programs. The country's specialized aerostructure supply base serves German and French airline procurement channels. Regional production concentrates on automated fiber placement techniques for complex fairing geometries.
United Kingdom
Derby and Bristol engineering clusters support composite repair technician training pipelines for carbon fiber-epoxy damage inspection. The Civil Aviation Authority enforces harmonized standards with EASA on fatigue-life documentation. MRO facilities at London Gatwick and Manchester bundle retrofit campaigns with C-check scheduling.
Aircraft Flap Track Fairing Retrofit Kits Market Competitive Landscape
Backward integration into raw carbon fiber conversion dominates the current landscape among top-tier aerostructure houses. The vendor base concentrates around three manufacturing complexes in Wichita, Hamburg, and Ried im Innkreis. Two strategic archetypes prevail: vertically integrated composite converters controlling prepreg supply chains, and MRO-anchored bundlers capturing aftermarket value through heavy-check integration. Capacity expansion and sole-source framework agreements constitute the dominant competitive moves as airlines consolidate procurement relationships.
Among Wichita-based manufacturers, Spirit AeroSystems exemplifies the integrated converter archetype through captive carbon fiber processing. FACC AG occupies a comparable position within the Austrian engineering tier. Lufthansa Technik represents the MRO-bundler model, anchoring aftermarket channel control through Hamburg-based technical capabilities. These three entities collectively illustrate how geographic clustering and supply chain positioning shape competitive differentiation in retrofit kit procurement.
| Leading Market Players |
|---|
| Aero Design Labs |
| Aviation Partners Boeing |
| Vortex Control Technologies |
| SACS Aerospace |
| ALOFT AeroArchitects |
| The NORDAM Group |
| Lufthansa Technik |
| FACC AG |
| Spirit AeroSystems |
| Others |
Pricing and Supply Chain Analysis
EPA National Emission Standards for Hazardous Air Pollutants compliance documentation gates both qualified carbon fiber prepreg supply and premium-tier pricing access for commercial airlines retrofitting Boeing 737 and Airbus A320 family aircraft. Operators lacking bundled heavy-check procurement frameworks face compressed margins as raw aerospace-grade fiber volatility feeds through kit converters without backward integration.
Pricing Analysis
Warranty and fatigue-life documentation bundling separates premium kit suppliers from unbundled hardware distributors in commercial retrofit procurement. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with FAA type-certificate amendment holders commanding brand premiums. Cost compression in standard tiers is intensifying because raw carbon fiber supply constraints compress converter margins. Regional operators in Southeast Asia exhibit highest price sensitivity, while United States flag carriers prioritize fuel-burn documentation over per-unit kit economics.
Supply Chain Analysis
Regional distribution centers in Wichita, Hamburg, and Ried im Innkreis anchor hub-and-spoke patterns for carbon fiber-epoxy prepreg feedstock and finished fairing assemblies. Manufacturing draws from United States, Germany, and Austria production clusters, with raw material sourcing resting on Toray and Hexcel aerospace-grade fiber supply. Single-source vulnerability concentrates at Spirit AeroSystems Wichita complex and Lufthansa Technik Hamburg MRO bundling operations. Distribution runs through sole-source framework agreements displacing independent distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic resin systems are displacing thermoset epoxies in next-generation flap track fairing designs, creating asymmetric opportunity windows across incumbent converter and new entrant positioning.
For Market Incumbents: To counter thermoplastic process convergence from Austrian and Southeast Asian competitors, Spirit AeroSystems and FACC AG should deepen captive carbon fiber conversion capacity at Wichita and Ried im Innkreis manufacturing complexes. Certification investment in EASA REACH-compliant resin systems for A320 retrofit programs provides defensive moat against regulatory fragmentation. For New Entrants and Emerging Players: MRO-anchored bundlers in underpenetrated Southeast Asian markets present the most penetrable channel partner type for scaled fairing geometries targeting unmanned aerial vehicle platforms. Direct contracting with flag carriers outside Lufthansa Technik's Hamburg network offers white-space access. Technical differentiation through abbreviated lead times for drone-specific geometries provides go-to-market angle absent from manned aircraft certification pathways. For Investors and Strategic Acquirers: FAA airworthiness directive acceleration on aging narrow-body fleets is the leading indicator that reactive retrofit campaign volume will sustain above scheduled maintenance replacement rates. Five-to-ten year viability hinges on converter archetypes with backward fiber integration and Hamburg or Wichita geographic clustering. Thermoplastic capability acquisition at European tier-2 aerostructure houses signals inflection toward next-generation material qualification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Conversion | Captive prepreg supply at Wichita manufacturing complexes insulates Spirit AeroSystems from raw material volatility. |
| EASA REACH-Compliant Resin Reformulation | FACC AG maintains European retrofit program access as persistent organic pollutant restrictions tighten. |
| MRO Bundling with Heavy-Check Intervals | Lufthansa Technik Hamburg facilities capture aftermarket value through sole-source framework agreements. |
| Thermoplastic Process Capability Investment | Southeast Asian regional operators reduce MRO turnaround times through weldable damage-tolerant fairing designs. |
| Unmanned Aerial Vehicle Platform Expansion | Scaled fairing geometries for military drones access technically distinct procurement with limited incumbent competition. |
Research Methodology
Independent corroboration across FAA airworthiness directive filings, EASA certification databases, and EPA emissions compliance records underwrites the qualitative findings in this study. Primary interviews with airline engineering directors, MRO procurement leads at Lufthansa Technik and comparable facilities, aerostructure manufacturing executives at Wichita and Austrian complexes, and composite repair technician training program administrators combined with secondary validation from SEC 10-K filings of publicly traded aerostructure houses, customs trade data on carbon fiber prepreg imports, and OEM service bulletin repositories. Bottom-up kit volume estimates triangulated against top-down narrow-body fleet age profiles and heavy-check interval scheduling.
Comparable-period anchoring to historical FAA directive issuance rates and EASA certification timeline distributions established the forecast window baseline. Across the analysis window, segmentation dimensions modeled include material class (carbon fiber, titanium, hybrid composite), manufacturing technology (automated assembly, resin-transfer-molding), platform application (commercial jets, unmanned aerial vehicles), and end-user channel (MRO bundlers, airframe manufacturers, independent retrofit centers). CAGRs derived from fleet retirement projections cross-referenced with fatigue-life threshold penetration curves. Industry-specific inputs encompass Boeing 737 and Airbus A320 family installed base depreciation schedules and EU Green Deal aviation decarbonization incentive allocation patterns.
Caveats apply where raw carbon fiber supply disruption, REACH regulation amendment acceleration, or thermoplastic qualification timeline compression could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.