
 Military Rotorcraft Market | 2026-2036
Military Rotorcraft Market Size, Share, and Industry Trends Forecast 2026-2036
Military Rotorcraft Market Outlook
South Korea is tilting its defense industrial base toward rotorcraft self-sufficiency through Korea Aerospace Industries. Leonardo S.p.A. leverages its vertically integrated AgustaWestland heritage to dominate European naval helicopter niches. Lockheed Martin Corporation anchors the U.S. heavy-lift segment through its Sikorsky lineage and sustained Army Black Hawk modernization contracts.
Military rotorcraft encompass powered-lift aircraft employing single or multiple main rotors for vertical takeoff, landing, and hover, with turboshaft engines typically delivering 1,500 to 3,000 shaft horsepower and main rotor diameters spanning 40 to 80 feet depending on payload class. These platforms serve tactical mobility, close air support, and expeditionary logistics roles where fixed-wing runway dependency is operationally prohibitive. Attack Helicopters command the premium margin pool due to integrated targeting systems and armor survivability requirements, while Utility Helicopters represent the volume base with broad tri-service applicability. Reconnaissance Helicopters are gaining technology share through unmanned teaming interfaces and reduced radar cross-section shaping.
The U.S. Army's Future Vertical Lift program operates under FAA airworthiness coordination and DoD acquisition regulation, while European procurement aligns with EASA military certification standards and EU defense fund eligibility criteria. Turkey's indigenous programs navigate national export licensing under SAMR-equivalent oversight as its rotorcraft sector matures. Stakeholders must weigh sovereign production incentives against interoperability standards when positioning for next-generation platform selections.
Market Dynamics
The Future Vertical Lift initiative is compressing development cycles for next-generation platforms while forcing legacy system obsolescence across NATO inventories. This program is reshaping supplier qualification requirements and propulsion architecture standards simultaneously.
Growth Catalysts
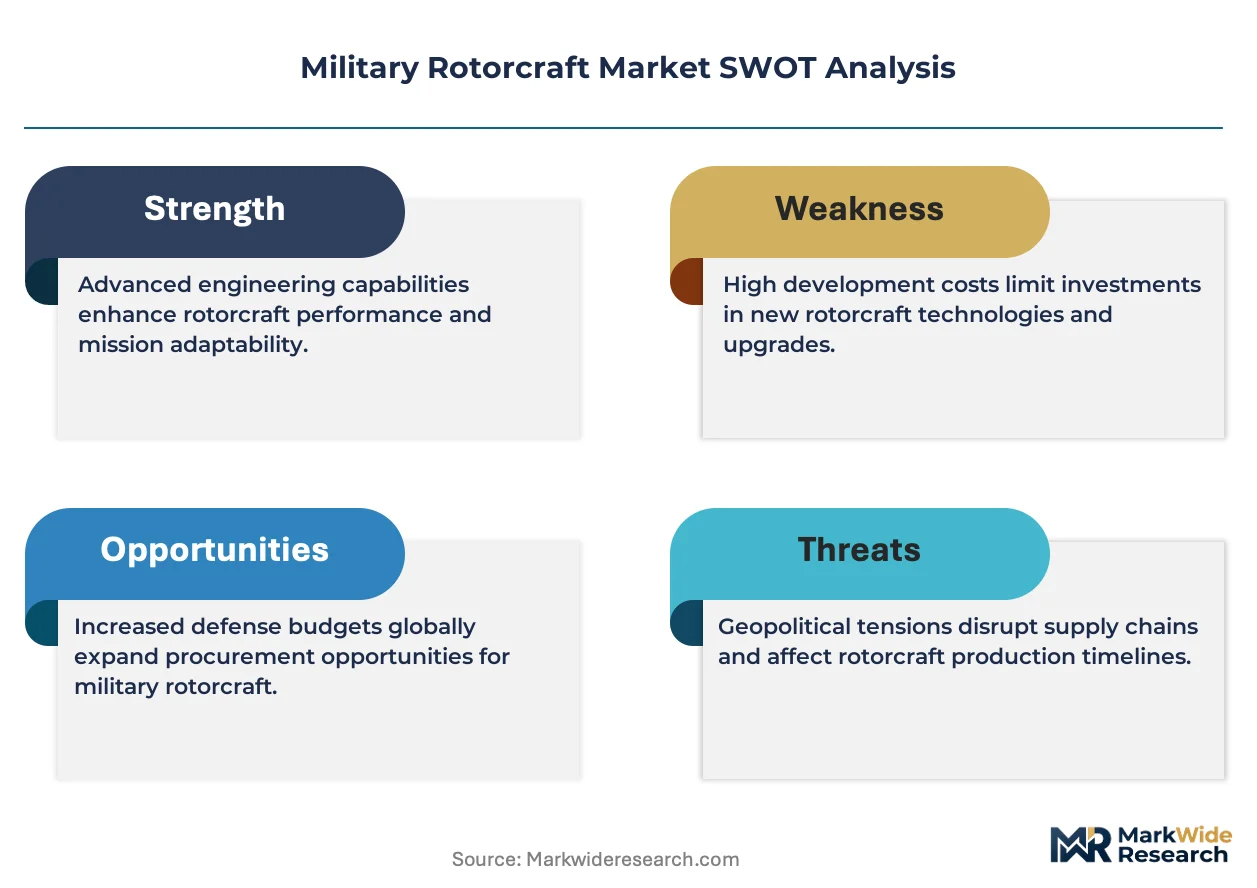
- Future Vertical Lift procurement acceleration:The U.S. Army's FLRAA and FARA pathways are creating dual-track demand for compound rotorcraft and advanced turboshaft systems. Platform selections will lock in supplier ecosystems for two decades.
- EASA military certification harmonization:Standardized airworthiness frameworks across EU member states are reducing bilateral duplication costs. This regulatory convergence enables cross-border maintenance networks and pooled fleet procurement.
- Unmanned teaming interface proliferation:Manned-unmanned teaming protocols are expanding mission envelope capabilities for reconnaissance and attack helicopter segments. Sensor fusion architectures now require interoperable datalink standards.
Market Restraints
- Titanium and nickel superalloy supply concentration:Specialty metallurgical inputs for hot-section components face sourcing bottlenecks from limited qualified foundries. Price volatility in aerospace-grade alloys directly impacts engine manufacturing economics.
- Long-cycle type certification requirements:FAA and EASA military certification pathways demand 5-7 year validation timelines for new airframe designs. These procedural durations deter platform innovation from non-incumbent suppliers.
- Fixed-wing tactical transport substitution:Tiltrotor and STOL-capable turboprop alternatives are capturing medium-lift mission profiles previously assigned to utility helicopters. V-22 and emerging eVTOL concepts erode traditional rotorcraft addressable demand.
Strategic Opportunities
- Turkish indigenous manufacturing maturation:TAI's rotorcraft programs under SAMR-equivalent oversight are creating secondary supply hub capacity. Export licensing frameworks position Turkey as a regional platform source for non-NATO buyers.
- Fly-by-wire architecture retrofits:Legacy analog flight control systems in existing fleets present upgrade pathways for handling quality improvements and reduced pilot workload. Digital control law implementation extends platform service life.
- South Korean defense industrial base expansion:KAI's Surion derivative programs and KF-X adjacent rotorcraft investments build captive design competence. Indigenous content requirements under DAPA procurement rules guarantee domestic volume allocation.
Industry Challenges
- Flight control law software certification backlog:Complex embedded systems verification for fly-by-wire architectures strains qualified engineering workforce availability. DO-178C compliance documentation demands specialized avionics software expertise that outstrips supply.
- Legacy platform obsolescence management:Sustaining engineering for analog-era Black Hawk and Apache variants requires reverse-engineering components no longer in production. Parts provenance documentation gaps complicate airworthiness continuity.
- Interoperability standard fragmentation:National datalink encryption and communications protocols prevent seamless coalition operations. STANAG implementation gaps force expensive mission-specific integration engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Rotorcraft Market |
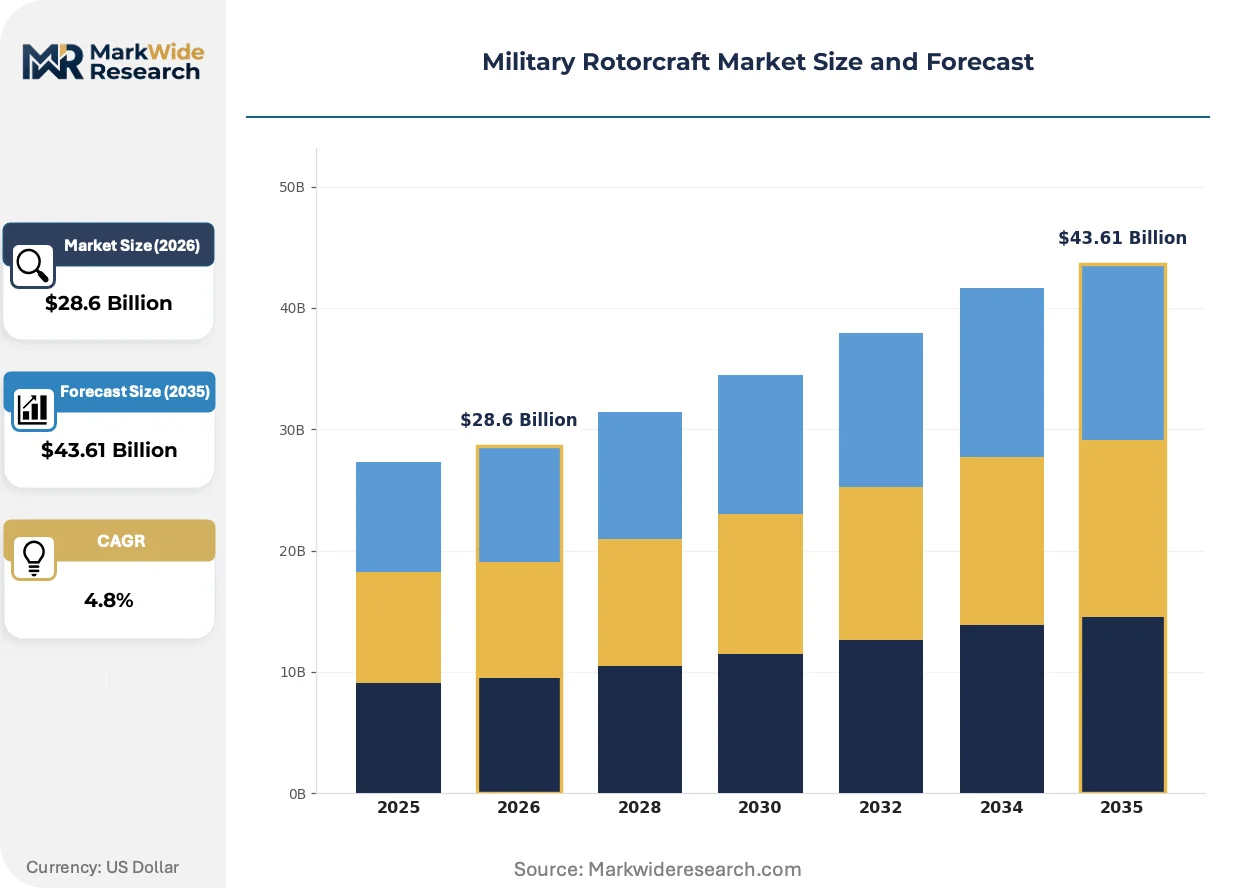
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Attack Helicopters, Utility Helicopters, Transport Helicopters, Reconnaissance Helicopters Technology: Fly-by-Wire, Avionics Suite, Turboshaft Engines, Advanced Rotor Systems End User: Army, Navy, Air Force, Special Operations Application: Combat Operations, Search and Rescue, Medical Evacuation, Surveillance |
| Companies Covered | Leonardo S.p.A., Bell Textron Inc., Lockheed Martin Corporation, Korea Aerospace Industries, Hindustan Aeronautics Limited, The Boeing Company, Russian Helicopters, Turkish Aerospace Industries, Airbus Helicopters, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Rotorcraft Market Strategic Shifts
Active electronically scanned array radar integration and open systems architecture mandates are redefining sensor and avionics procurement specifications across attack and reconnaissance helicopter segments. Platform electronics now follow consumer-sector refresh cycles rather than airframe lifespans.
Fly-by-wire flight control systems are digitizing pilot-vehicle interfaces across new-generation military rotorcraft. The U.S. Army's FLRAA competitors and European next-generation platforms are eliminating mechanical linkages entirely. Handling qualities standardization across multiple flight regimes is compressing training pipeline duration and expanding operational envelope accessibility for less-experienced pilots.
EU defense fund eligibility criteria and the European Defence Industrial Strategy are redirecting procurement toward continental sourcing minimums. Member state joint procurement mechanisms are consolidating previously fragmented national requirements into block orders. This policy architecture favors suppliers with established EU-based manufacturing footprints and penalizes sole-source non-European platform selections.
Performance-based logistics contracts are displacing traditional spare parts and hourly service agreements in military rotorcraft sustainment. Operator-buyers in the United States and United Kingdom are transferring availability risk to prime contractors through fixed-cost-per-flight-hour structures. This contracting evolution concentrates aftermarket revenue with platform OEMs and marginalizes third-party maintenance providers.
Military Rotorcraft Market Segmentation
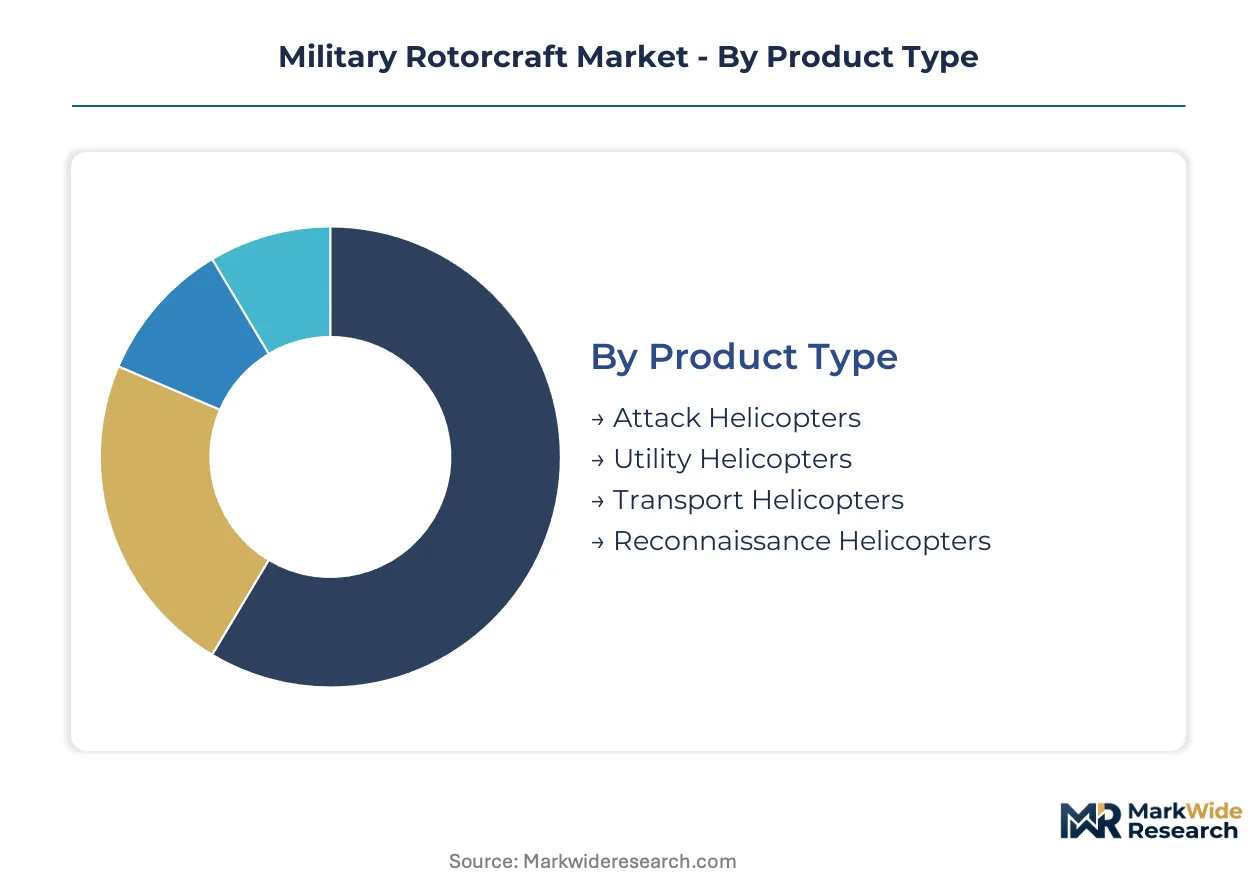
Segmentation reveals how procurement priorities diverge across mission profiles and force structures. Attack platforms command premium unit economics while utility fleets drive volume. Technology architecture choices now lock in supplier ecosystems for multi-decade service lives.
Product Type:
Application dictates airframe configuration, engine sizing, and survivability architecture across military rotorcraft categories.
- Attack Helicopters:These platforms integrate armor protection, tandem crew seating, and hardpoint-mounted precision munitions. The U.S. Army's FARA pathway concentrates demand for next-generation armed reconnaissance variants with reduced radar signatures. Hot-section metallurgy and integrated targeting systems sustain premium margin structures.
- Utility Helicopters:Single-main-rotor designs with cabin volumes exceeding 200 cubic feet dominate tactical mobility missions. Black Hawk modernization contracts across NATO member states sustain production throughput for medium-lift configurations. Volume procurement spreads fixed development costs across extended manufacturing runs.
- Transport Helicopters:Heavy-lift platforms with payload capacities above 10,000 pounds serve expeditionary logistics requirements.
- Reconnaissance Helicopters:Light airframes with mast-mounted sensors and unmanned teaming interfaces are gaining technology share through reduced observability shaping.
Attack Helicopters hold installed capacity. Reconnaissance Helicopters are rotating up the share rankings.
Technology:
Propulsion and control architectures determine platform performance ceilings and operational envelope accessibility.
- Fly-by-Wire:Digital flight control laws replace mechanical linkages with triple-redundant electrical signaling. FLRAA competitors and European next-generation platforms are eliminating hydromechanical systems entirely. Handling qualities standardization compresses training pipeline duration for less-experienced pilots.
- Turboshaft Engines:Axial-centrifugal compressors delivering 1,500 to 3,000 shaft horsepower power main rotors spanning 40 to 80 feet. Hot-section component sourcing from qualified foundries faces titanium and nickel superalloy supply concentration. Engine manufacturing economics directly track aerospace-grade alloy price volatility.
- Avionics Suite:Integrated sensor and communications packages follow consumer-sector refresh cycles rather than airframe lifespans.
- Advanced Rotor Systems:Coaxial and compound configurations are expanding speed and range envelopes beyond conventional articulated rotor limits.
Turboshaft Engines hold installed capacity. Fly-by-Wire is rotating up the share rankings.
End User:
Customer type shapes procurement scale, mission specification, and interoperability requirements.
- Army:Ground force integration demands tactical mobility and close air support platforms with expeditionary basing capability. The U.S. Army's Future Vertical Lift initiative compresses development cycles while forcing legacy system obsolescence. Platform selections will lock in supplier ecosystems for two decades.
- Special Operations:Low-observable insertion and extraction missions require modified airframes with enhanced range and reduced acoustic signatures. NATO member state fleet modernization programs are expanding demand for mission-specific configurations. Customization requirements sustain premium pricing for limited-production variants.
- Navy:Maritime operations drive corrosion-resistant materials and deck-landing handling qualities.
- Air Force:Combat search and rescue roles prioritize speed and all-weather recovery capability.
Army holds installed capacity. Special Operations is rotating up the share rankings.
Application:
Mission profile determines sensor payload, weapons integration, and crew configuration requirements.
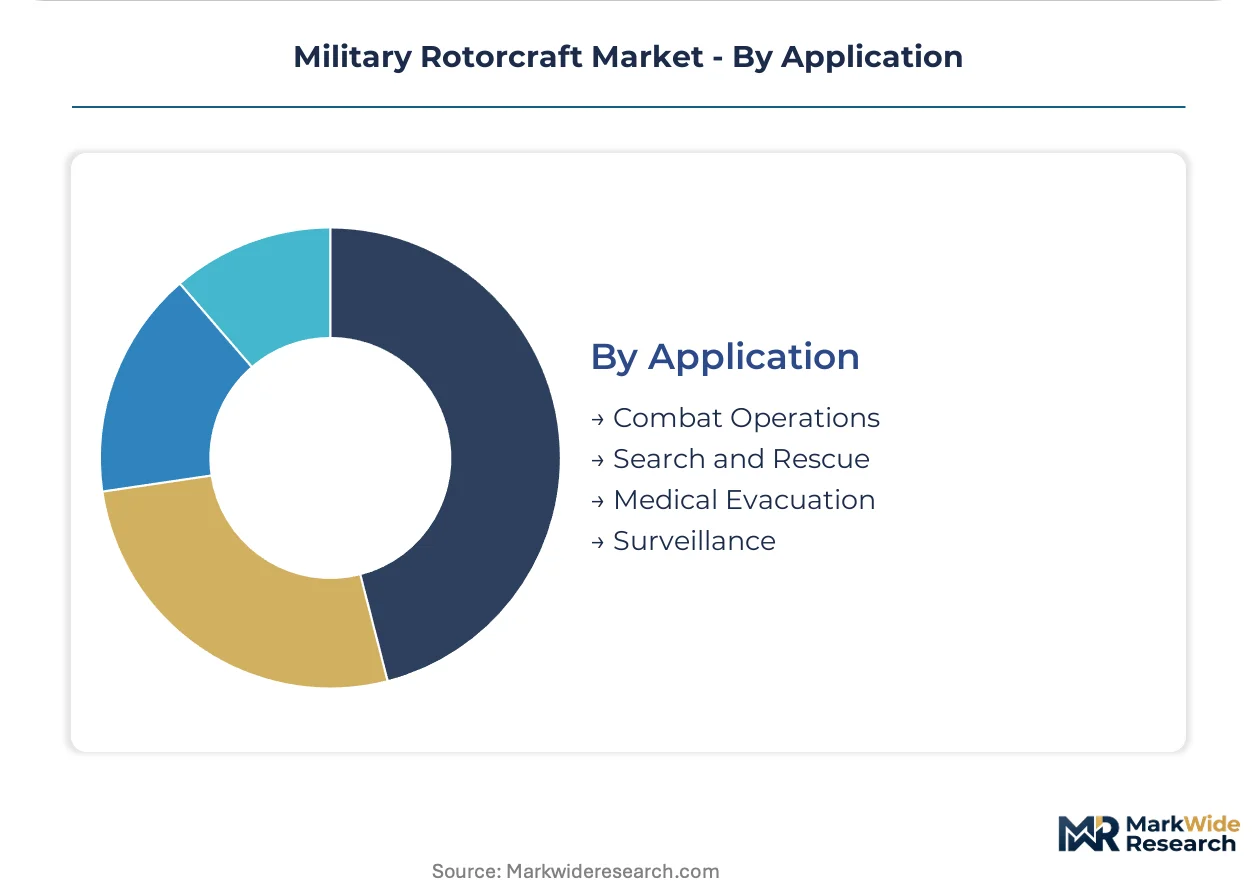
- Combat Operations:Armed engagement missions integrate fire control systems, armor protection, and precision munitions delivery. Attack helicopter segments command premium margin pools through targeting system complexity and survivability engineering. Active electronically scanned array radar integration is redefining sensor procurement specifications.
- Medical Evacuation:Casualty transport configurations prioritize cabin accessibility, life support equipment integration, and rapid loading geometries. Utility helicopter volume base sustains tri-service applicability across NATO inventories. Performance-based logistics contracts are transferring availability risk to prime contractors.
- Search and Rescue:All-weather recovery missions require hoist systems and enhanced navigation capability.
- Surveillance:Intelligence collection platforms emphasize sensor persistence and datalink interoperability.
Combat Operations holds installed capacity. Medical Evacuation is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. The United States prioritizes next-generation platform development through multi-billion-dollar modernization programs. European states emphasize pooled procurement frameworks and cross-border interoperability standards. Asian defense industrial bases are accelerating indigenous manufacturing capabilities to reduce import dependency.
United States
The U.S. Army's Future Vertical Lift initiative drives demand for compound rotorcraft and advanced turboshaft systems. FAA airworthiness coordination with DoD acquisition regulation shapes platform certification pathways. Sikorsky's Connecticut operations and Boeing's Philadelphia rotorcraft facilities anchor domestic heavy-lift and attack helicopter production.
Germany
Bundeswehr fleet modernization concentrates on naval helicopter replacements and heavy-lift capacity gaps. EASA military certification standards and EU defense fund eligibility criteria redirect procurement toward continental sourcing minimums. Airbus Helicopters' Donauwörth facility dominates European naval helicopter assembly with vertically integrated supply chains.
South Korea
DAPA procurement rules mandate indigenous content thresholds for utility and attack helicopter variants. KF-X adjacent rotorcraft investments under national industrial policy build captive design competence. Korea Aerospace Industries' Sacheon complex manufactures Surion derivatives with progressive localization of critical subsystems.
Turkey
TAI's rotorcraft programs under SAMR-equivalent oversight mature export licensing frameworks for non-NATO buyers. National defense industrial strategies prioritize attack helicopter self-sufficiency and unmanned teaming interfaces. Turkish Aerospace Industries' Ankara facilities integrate avionics suites with reduced foreign dependency.
United Kingdom
Performance-based logistics contracts transfer availability risk to prime contractors through fixed-cost-per-flight-hour structures. Ministry of Defence procurement aligns with NATO interoperability standards while preserving sovereign maintenance capabilities. Leonardo's Yeovil facility sustains Wildcat and Merlin production lines with specialized naval mission system integration.
Military Rotorcraft Market Competitive Environment
Capability concentration sits with heritage airframe integrators possessing decades of military certification experience; scale advantage sits with diversified aerospace conglomerates with captive engine and avionics supply. The supplier base organizes around three archetypes: legacy helicopter specialists with naval domain expertise, diversified defense primes with multi-domain portfolios, and emerging national champions serving captive domestic demand. Consolidation pressure intensifies through platform selection lock-in effects and long-cycle type certification barriers. Strategic moves center on fly-by-wire architecture licensing partnerships and sovereign production joint ventures.
Within the heritage specialist tier, Leonardo S.p.A. and Lockheed Martin Corporation occupy positions shaped by vertically integrated manufacturing legacies and sustained military modernization contracts. Leonardo leverages its AgustaWestlin heritage across European naval niches, while Lockheed Martin anchors U.S. heavy-lift demand through Sikorsky lineage. Korea Aerospace Industries exemplifies the emerging national champion archetype, building rotorcraft self-sufficiency under DAPA procurement rules. These three entities represent distinct competitive positioning vectors: continental European naval specialization, U.S. Army platform dominance, and Asian defense industrial base maturation.
| Leading Market Players |
|---|
| Leonardo S.p.A. |
| Bell Textron Inc. |
| Lockheed Martin Corporation |
| Korea Aerospace Industries |
| Hindustan Aeronautics Limited |
| The Boeing Company |
| Russian Helicopters |
| Turkish Aerospace Industries |
| Airbus Helicopters |
| Others |
Value Chain & Pricing Dynamics
Undercapacity at qualified titanium and nickel superalloy foundries in the United States and Europe simultaneously elevates input costs and extends supplier lead times, compressing margins for engine OEMs while concentrating pricing power among metallurgical specialists with FAA-certified hot-section component qualifications.
Pricing Analysis
Long-term fixed-price contracts with escalation clauses dominate attack helicopter and utility platform procurement, insulating prime contractors from near-term alloy volatility while transferring risk to engine suppliers exposed to spot-market titanium pricing. Price differentiation separates fly-by-wire equipped next-generation platforms from analog-legacy variants through performance-based logistics bundling. Pricing pressure stems from South Korean and Turkish indigenous manufacturing maturation eroding Western OEM volume premiums. National defense ministries exhibit lowest price sensitivity for special operations configurations, while standard utility fleet replacements face rigorous cost-per-flight-hour benchmarking.
Supply Chain Analysis
Extended payment terms from prime contractors to Tier 2 suppliers have compressed working capital availability across the aerospace-grade alloy processing tier, accelerating consolidation among qualified foundries. Hot-section component manufacturing concentrates in the United States, United Kingdom, and Germany, with precision forging capacity drawing from titanium sponge feedstock anchored in Japan and Russia. Single-source vulnerability permeates the 5-7 axis CNC machining segment for turbine disk production. Distribution runs through military procurement channels governed by DoD acquisition regulation and DAPA indigenous content mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across unmanned teaming interface subsystems, where manned-unmanned protocol standardization has yet to consolidate around dominant architectures, creating entry points for specialized datalink and sensor fusion providers.
For Market Incumbents: Pre-empt Turkish and South Korean indigenous manufacturing expansion through sovereign production joint ventures that preserve technology access while conceding final assembly localization. Lock in fly-by-wire architecture licensing partnerships with emerging national champions before captive design competence matures. Vertical integration into hot-section component recycling extends alloy supply security against qualified foundry capacity constraints. For New Entrants and Emerging Players: Establish a beachhead in reconnaissance helicopter unmanned teaming interface modules, where STANAG implementation gaps prevent seamless coalition operations and mission-specific integration engineering commands premium pricing. Target European naval helicopter sensor refresh cycles following open systems architecture mandates. Pursue EASA military certification pre-qualification to access pooled EU defense fund procurement mechanisms. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier avionics specialists possessing DO-178C compliant software certification capabilities and established military airworthiness documentation trails. Long-term viability hinges on positioning within FLRAA and FARA supplier ecosystems before platform selections crystallize. Monitor Turkish SAMR-equivalent export licensing framework expansion as signal of regional supply hub emergence.| Strategic Initiative | Industry Significance |
|---|---|
| Fly-by-Wire Architecture Licensing | Captures recurring revenue from legacy fleet retrofits and next-generation platform integration. |
| Sovereign Production Joint Venture | Preserves market access under DAPA and SAMR-equivalent indigenous content mandates. |
| Hot-Section Component Recycling | Mitigates titanium and nickel superalloy supply concentration through closed-loop material recovery. |
| EASA Military Certification Pre-Qualification | Enables participation in EU defense fund consolidated block procurement mechanisms. |
| Unmanned Teaming Interface Development | Addresses STANAG fragmentation through proprietary datalink standard adoption. |
Study Parameters
A standing panel of rotorcraft program managers, turboshaft engine procurement leads, military airworthiness certification specialists, and defense ministry acquisition officers provided ongoing calibration against secondary validation from FAA airworthiness directives, EASA military certification standards, DoD budget justification documents, and DAPA procurement announcements. Bottom-up platform-level demand aggregation triangulated against top-down defense expenditure macro trends.
Scenario-bracketing around Future Vertical Lift program acceleration timelines, EU defense fund allocation trajectories, and Turkish export licensing framework maturation bounded projection uncertainty across the analysis window. Segmentation modeling incorporated product type, propulsion architecture, end-user service branch, and mission application dimensions. CAGRs derived from fleet replacement cycle analysis and modernization program budget visibility.
Stress conditions across titanium alloy price volatility, type certification timeline extension, and tiltrotor substitution penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts assume documented program continuity; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Asia-Pacific Freighter Aircraft Market
Aircraft
Autonomous Aircraft Propulsion Systems Market
Aircraft
Aircraft Galley Equipment Market
Aircraft
Middle East and Africa Aviation Market
Aircraft
UK Aviation Market
Aircraft
Air Starter Market
Aircraft
Global Aircraft De-Icing Market
Aircraft
Manned Evtol Crafts Market
Aircraft
Fixed Wing Turbine Aircraft Market
Aircraft
Military Transport Aircraft Market
Aircraft
Aircraft Container & Pallet Loader Market
Aircraft
Aircraft Aerostructures Market
Aircraft
Global Commercial Aircraft Seat Actuation Market
Aircraft
Latin America Business Jet Market
Aircraft
Helicopter Flight Control Systems Market
Aircraft
Crashworthy Aircraft Seats Market