
 Aircraft Wiring Harness Market | 2026-2036
Aircraft Wiring Harness Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Wiring Harness Market Analytics
EU Green Deal aviation decarbonization targets is expanding the addressable market for lightweight wiring harnesses as airframers pursue fuel efficiency gains. TE Connectivity leverages its sensor integration expertise to bundle data and power transmission within single harness architectures. Safran S.A. anchors European supply through its specialized aerostructures division with dedicated harness production lines. Amphenol Corporation differentiates via high-density interconnect solutions purpose-built for next-generation avionics bays.
An aircraft wiring harness is an organized bundle of wires, cables, and connectors routed through an airframe to transmit electrical power, data signals, and control commands between subsystems, typically engineered to withstand temperature extremes from minus 55 to 200 degrees Celsius and vibration loads exceeding 20 g. Its primary purpose is to consolidate complex electrical pathways into protected, maintainable assemblies that reduce installation time and fault risk across critical flight systems. Custom harnesses command premium margins as OEMs specify unique routing geometries for each airframe program, while optical wiring harnesses represent the fastest-growing product type as fiber optic protocols displace copper for high-bandwidth avionics networks. Military aviation deployment sustains durable demand through Mil-Spec certification requirements that limit supplier pools and protect incumbent positions.
FAA airworthiness directives and EASA CS-25 certification standards govern flame resistance, smoke toxicity, and electrical fault containment in harness materials, effectively raising barriers for uncertified suppliers seeking OEM qualification. REACH restrictions on halogenated flame retardants are forcing reformulation of wire insulation compounds across European supply chains. Stakeholders must monitor evolving electromagnetic compatibility thresholds as fly-by-wire architectures and electric propulsion systems multiply signal density throughout the airframe.
Market Dynamics
Commercial fleet renewals are compressing qualification timelines for harness suppliers as Boeing and Airbus accelerate narrow-body production rates to clear order backlogs exceeding 13,000 aircraft.
Growth Catalysts
- FAA electromagnetic interference mandates:Stricter shielding requirements for fly-by-wire systems are compelling material upgrades across wire insulation and connector specifications.
- Electric propulsion architectures:Hybrid-electric and all-electric aircraft programs are multiplying power distribution nodes, expanding harness complexity per airframe.
- Sensor fusion integration:Bundled data-power harnesses for health monitoring systems are penetrating next-generation avionics bays.
Market Restraints
- Copper price volatility:Raw material swings compress margins for harness assemblers locked into long-term OEM supply agreements.
- Mil-Spec certification pools:Military aviation's qualified supplier lists limit new entrants to defense programs regardless of technical capability.
- Optical substitution pressure:Fiber optic protocols for high-bandwidth avionics networks threaten copper harness volumes in cockpit and communication systems.
Strategic Opportunities
- EU Green Deal aviation targets:Lightweight harness materials qualify for fuel efficiency credits, creating procurement preference for composite-sheathed assemblies.
- Urban air mobility platforms:eVTOL manufacturers require modular, rapid-install harness architectures absent legacy certification burdens.
- Blockchain-enabled traceability:Digital thread documentation for wire provenance is opening premium pricing tiers in aftermarket channels.
Industry Challenges
- Skilled harness technician scarcity:Manual assembly expertise for complex routing geometries is retiring faster than apprenticeship programs replenish capacity.
- Multi-standard certification overlap:Simultaneous FAA, EASA, and CAAC qualification requirements extend program entry timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Wiring Harness Market |
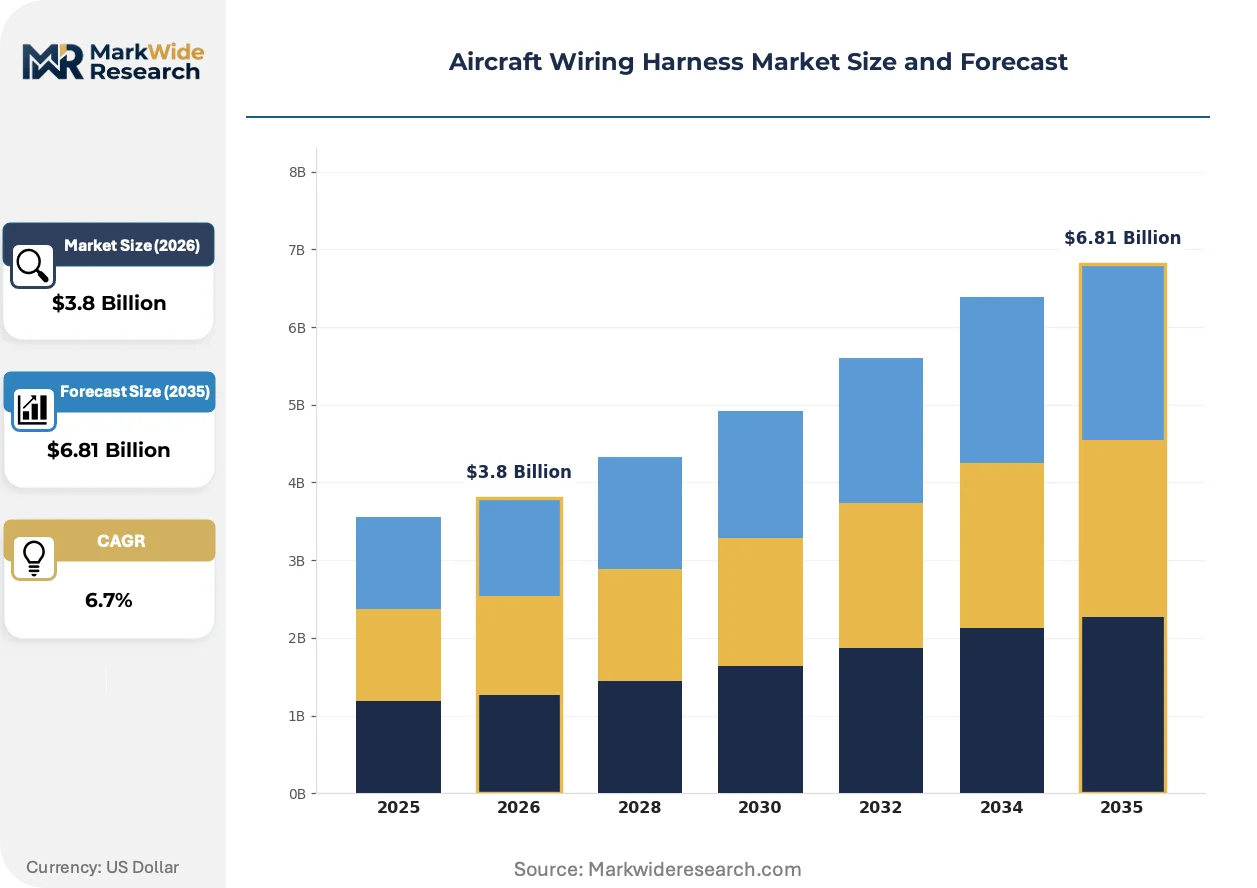
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Custom Harnesses, Standard Harnesses, Mil-Spec Harnesses, Optical Wiring Harnesses Material: Copper, Aluminum, Polyethylene, Teflon Deployment: Commercial Aviation, Military Aviation, General Aviation, Business Jets End User: Aircraft Manufacturers, MRO Providers, Aircraft OEMs, Aftermarket Suppliers |
| Companies Covered | Safran S.A., TE Connectivity, Amphenol Corporation, Collins Aerospace, GKN Aerospace, Latécoère, Glenair, Yazaki Corporation, Carlisle Interconnect Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Wiring Harness Market Evolving Landscape
Three interconnected shifts are restructuring how electrical interconnection systems are engineered, qualified, and procured across civil and military aviation programs.
Optical wiring harnesses are decentralizing signal routing architecture across modern airframes by replacing copper bundles with fiber optic assemblies for high-data-rate avionics networks. Regional jet OEMs and business aircraft manufacturers are adopting these assemblies fastest, driven by weight reduction targets and electromagnetic immunity requirements. This shift is decentralizing the traditional harness value chain as optical component specialists capture margin previously held by wire-centric assemblers.
EASA CS-25 flame resistance standards are tightening smoke toxicity thresholds for wire insulation materials used in passenger cabin zones. European suppliers are reformulating halogen-free compounds to maintain certification eligibility under REACH chemical restrictions. Narrow-body programs with dense cabin electronics are absorbing the highest compliance costs, accelerating consolidation among compound formulators.
Long-term service agreements are displacing transactional spare parts purchasing for harness maintenance in mature commercial fleets. Airlines with Boeing 737 MAX and Airbus A320neo fleets are bundling line-replaceable unit provisioning with predictive analytics subscriptions. This pattern is most advanced among North American and Middle Eastern carriers operating large single-aisle fleets with centralized maintenance operations.
Aircraft Wiring Harness Market Segmentation
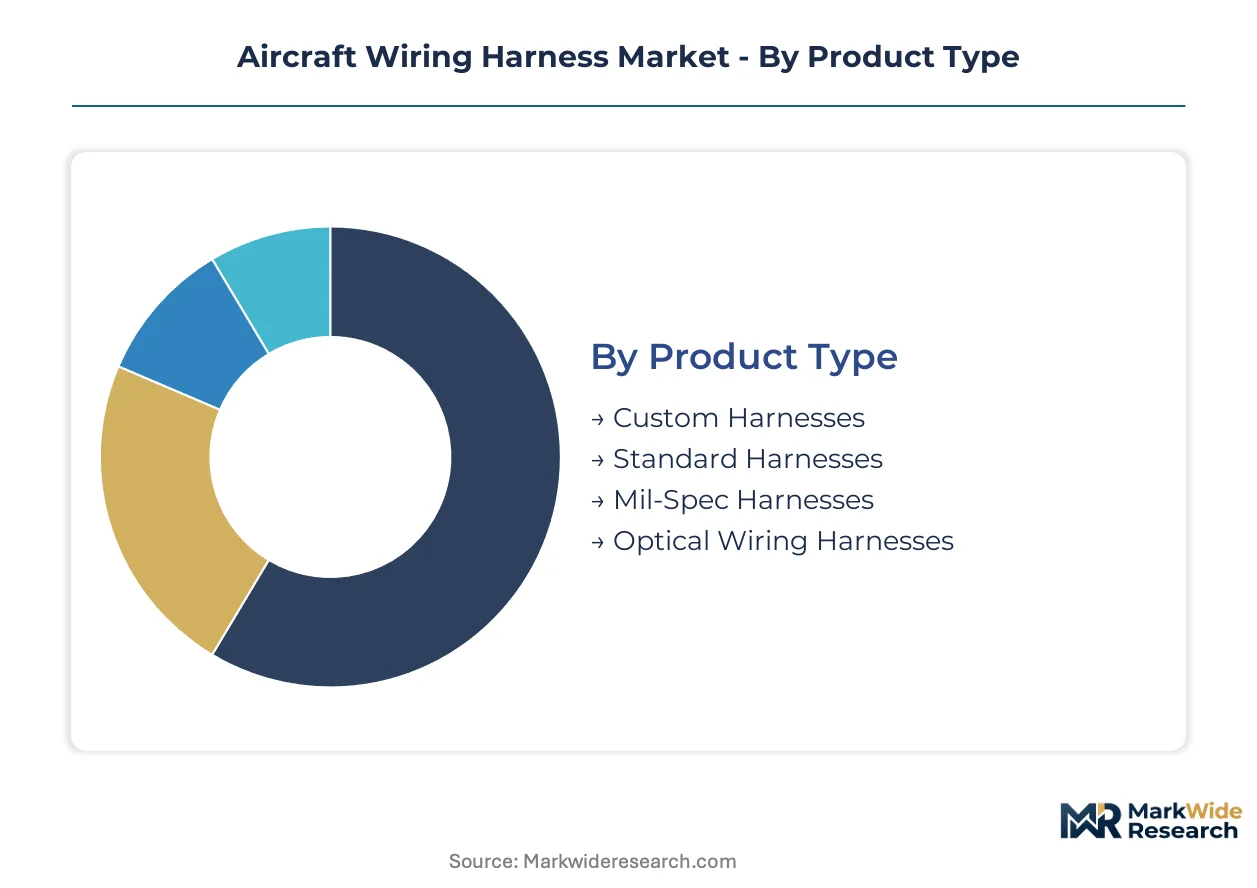
Segmentation in the aircraft wiring harness market reflects divergent certification burdens and performance thresholds across aviation platforms. Each category channels procurement toward suppliers with specialized qualification portfolios, creating distinct competitive arenas with limited overlap.
Product Type:
FAA and EASA certification requirements vary sharply across harness architectures, with optical and Mil-Spec variants demanding specialized testing protocols that lock out generalist assemblers.
- Custom Harnesses:Engineered to unique routing geometries specified by Boeing, Airbus, or Bombardier for individual airframe programs. These command premium margins due to program-specific qualification investments and low-volume production runs that resist automation.
- Standard Harnesses:Off-the-shelf assemblies for maintenance and retrofit applications. Demand concentrates among MRO providers in the United States and Germany seeking rapid turnaround on aging narrow-body fleets without OEM lead times.
- Mil-Spec Harnesses:Built to MIL-DTL-22520 and MIL-DTL-38999 specifications with radiation-hardened insulation and redundant shielding. US Department of Defense procurement sustains a closed supplier pool where incumbents hold decade-long positions.
- Optical Wiring Harnesses:Fiber optic assemblies for high-bandwidth avionics networks. Regional jet OEMs in Brazil and Canada are adopting these fastest to meet electromagnetic immunity mandates while shedding copper weight.
Custom Harnesses sit at the top of the volume ranking, with Optical Wiring Harnesses climbing the fastest.
Material:
Material selection directly determines flame resistance certification pathways under EASA CS-25 and FAA fireworthiness standards, with REACH chemical restrictions forcing European supply chain reformulation.
- Copper:Dominant conductor material with established termination techniques and repair protocols. Boeing 737 MAX and Airbus A320neo production rates sustain demand despite price volatility that compresses assembler margins on fixed-price contracts.
- Aluminum:Lightweight alternative gaining traction in electric propulsion architectures where every kilogram translates to range. Amphenol and TE Connectivity are qualifying aluminum-to-copper transition connectors for hybrid power distribution nodes.
- Polyethylene:Common insulation compound for cabin zone wiring. REACH restrictions on halogenated flame retardants are forcing European compounders toward phosphorus-based alternatives that maintain smoke toxicity thresholds.
- Teflon:High-performance fluoropolymer insulation for engine nacelle and APU zones. Its temperature tolerance from minus 60 to 260 degrees Celsius protects signal integrity in the harshest thermal environments.
Copper maintains dominant share by installed base, while Aluminum is expanding most quickly in next-generation electric aircraft programs.
Deployment:
Deployment mode shapes harness complexity through flight-hour intensity, environmental exposure, and regulatory surveillance density.
- Commercial Aviation:Narrow-body and wide-body production drives the largest absolute volumes. Fleet renewal programs at American Airlines, Delta, and United are accelerating procurement of next-generation harness assemblies with integrated health monitoring sensors.
- Military Aviation:Fighter and transport programs sustain demand through Mil-Spec certification requirements. Lockheed Martin F-35 production and European Future Combat Air System development protect incumbent supplier positions.
- General Aviation:Light aircraft and rotorcraft with simpler electrical architectures. Cirrus Aircraft and Piper in the United States specify reduced-shielding harnesses that trade electromagnetic protection for weight and cost.
- Business Jets:Gulfstream and Dassault Falcon programs demand premium harness customization for cabin entertainment and connectivity systems. These platforms absorb optical fiber adoption fastest due to passenger experience differentiation priorities.
Commercial Aviation anchors procurement volumes, with Business Jets showing the steepest expansion trajectory for optical interconnect adoption.
End User:
End user category determines contract structure, with OEMs demanding long-term qualification investments and aftermarket channels rewarding rapid fulfillment flexibility.
- Aircraft Manufacturers:Boeing, Airbus, and Embraer specify harness architectures during airframe design and lock suppliers into program-exclusive production agreements. These relationships require 18-24 month qualification timelines before first article acceptance.
- MRO Providers:Lufthansa Technik, ST Engineering, and AAR Corp drive line-replaceable unit demand through fleet maintenance contracts. Their procurement prioritizes availability over customization, favoring distributors with regional stocking positions.
- Aircraft OEMs:Airframers with captive harness production like Safran and Leonardo integrate electrical systems vertically. Their sourcing decisions balance in-house capacity against specialized supplier expertise for optical and high-temperature applications.
- Aftermarket Suppliers:Independent distributors and PMA holders serving aging fleets outside OEM service networks. Blockchain-enabled traceability documentation is opening premium pricing tiers for wire provenance verification.
Aircraft Manufacturers command the largest contract values, with MRO Providers gaining share fastest as fleet age extends and long-term service agreements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The aircraft wiring harness industry traces its modern origins to post-war American aerospace manufacturing, where Boeing and Douglas established the first large-scale electrical integration facilities. European and Asian production centers emerged subsequently through defense partnerships and commercial offset agreements.
United States
Boeing's 737 MAX and 777X production lines in Washington and South Carolina drive the largest harness procurement volumes globally. FAA airworthiness directives on electromagnetic compatibility compel material upgrades across supplier networks. Wichita's aviation cluster hosts specialized harness assemblers serving Textron Aviation and Bombardier business jet programs.
France
Airbus final assembly in Toulouse anchors European demand for custom harness architectures on A320neo and A350 programs. EASA CS-25 flame resistance standards tighten smoke toxicity thresholds for cabin zone wiring materials. Safran's specialized aerostructures division operates dedicated harness production lines near Bordeaux.
Germany
Lufthansa Technik's maintenance operations in Hamburg create substantial aftermarket demand for line-replaceable harness units. REACH restrictions on halogenated flame retardants force reformulation of wire insulation compounds across German supply chains. Bavaria's aerospace corridor concentrates sensor-integrated harness development for next-generation avionics.
Japan
Mitsubishi Heavy Industries and Subaru's aircraft divisions sustain precision harness demand for regional jet programs. METI's aerospace industrial policy supports domestic supplier qualification for international OEM partnerships. Nagoya's manufacturing belt hosts specialized connector producers serving both commercial and defense applications.
Canada
Bombardier's business jet and regional aircraft programs in Montreal specify premium harness customization for cabin systems. Transport Canada's adoption of FAA and EASA harmonized standards streamlines certification for cross-border suppliers. Toronto's aerospace cluster includes optical fiber specialists capturing margin from copper displacement trends.
Aircraft Wiring Harness Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the aircraft wiring harness sector. The supplier base concentrates around three tiers: diversified electrical interconnect conglomerates, specialized aerostructures divisions of major airframers, and niche Mil-Spec certification holders. Strategic differentiation runs through qualification portfolio breadth, optical fiber integration capability, and aftermarket service network density. Consolidation pressures intensify as OEMs reduce supplier counts to simplify program management.
Within the diversified electrical interconnect tier, TE Connectivity and Amphenol Corporation exemplify scale-driven positioning through high-density interconnect solutions and sensor integration expertise. Safran S.A. anchors European supply through its specialized aerostructures division with dedicated harness production lines. These three represent distinct archetypes: the global electrical specialist, the airframer-captive integrator, and the regional defense-qualified incumbent.
| Leading Market Players |
|---|
| Safran S.A. |
| TE Connectivity |
| Amphenol Corporation |
| Collins Aerospace |
| GKN Aerospace |
| Latécoère |
| Glenair |
| Yazaki Corporation |
| Carlisle Interconnect Technologies |
| Others |
Value Network & Pricing Analysis
Copper price volatility on the London Metal Exchange cascades through aircraft wiring harness supply chains, compressing margins for assemblers locked into fixed-price OEM contracts while amplifying cost differentials between commodity copper conductors and premium optical fiber alternatives. Long-term qualification investments by Boeing and Airbus tier-one suppliers insulate pricing power for custom harness architectures, but spot-market copper swings force rapid repricing in standard aftermarket assemblies.
Pricing Analysis
Program-exclusive contracting with 18-24 month qualification timelines anchors pricing for Boeing and Airbus supply chains, while aftermarket channels operate on spot availability premiums. Price differentiation stems from FAA/EASA certification tier and routing geometry complexity, with Mil-Spec harnesses commanding sustained premiums due to radiation-hardening requirements. Cost compression in standard harness tiers is intensifying because MRO providers consolidate procurement through distributor networks. Regional airlines and aging fleet operators exhibit highest price sensitivity, whereas Gulfstream and Dassault business jet programs prioritize electromagnetic immunity over unit cost.
Supply Chain Analysis
FAA airworthiness directives and EASA CS-25 certification standards gate supplier entry, concentrating qualified production in the United States, France, and Germany where Boeing, Airbus, and Safran anchor demand. Raw material flows draw from Chilean copper cathode, Japanese fluoropolymer resin for Teflon insulation, and German phosphorus-based flame retardants reformulated under REACH restrictions. Single-source vulnerability concentrates in specialized connector families qualified to MIL-DTL-38999 specifications. Distribution runs through OEM captive production lines for new aircraft programs and regional distributor networks for aftermarket line-replaceable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft wiring harness market functions as a regulatory compounder where FAA electromagnetic interference mandates and EASA flame resistance standards continuously expand addressable demand for upgraded material architectures.
For Market Incumbents: Anticipate optical fiber substitution by accelerating sensor-integrated harness development for health monitoring applications, while consolidating regional distributor relationships to defend aftermarket channel control against PMA entrants. Lockheed Martin F-35 and European Future Combat Air System programs protect Mil-Spec positions, but eVTOL manufacturers threaten copper volume with modular rapid-install architectures absent legacy certification burdens. Backward integration into specialized connector production secures margin capture currently lost to Glenair and Yazaki component suppliers. For New Entrants and Emerging Players: The gap between premium custom harness margins and economy standard aftermarket pricing creates entry space for blockchain-enabled traceability documentation that commands premium tiers in independent distributor channels. Urban air mobility platforms in Brazil and Canada offer the most penetrable geography due to reduced certification burdens and optical fiber adoption urgency. Target health monitoring system integration as the go-to-market angle, bundling predictive analytics subscriptions with hardware provisioning to mirror long-term service agreement structures proliferating among North American carriers. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized optical fiber harness assemblers positioned for regional jet and business aircraft penetration, where electromagnetic immunity requirements and weight reduction targets accelerate copper displacement. Long-term viability over the next decade hinges on qualification portfolio breadth spanning FAA, EASA, and CAAC standards rather than single-market concentration. Watch for inflection in eVTOL manufacturer procurement volumes as certification pathways stabilize and production scales beyond prototype quantities.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Fiber Integration Investment | Captures margin from copper displacement in avionics networks as regional jet OEMs accelerate adoption. |
| Blockchain Traceability Documentation | Opens premium pricing tiers in aftermarket channels through wire provenance verification demanded by MRO providers. |
| Sensor-Integrated Harness Development | Bundles data and power transmission for health monitoring systems penetrating next-generation avionics bays. |
| REACH-Compliant Compound Reformulation | Maintains EASA CS-25 certification eligibility as halogenated flame retardants face European chemical restrictions. |
| Long-Term Service Agreement Structuring | Mirrors predictive analytics subscriptions proliferating among American Airlines and Delta fleet maintenance contracts. |
Research Methodology
Coverage spans the United States, France, Germany, Japan, and Canada, with primary inputs from each region combining interviews with harness engineering directors, OEM procurement leads at Boeing and Airbus, MRO operations managers at Lufthansa Technik and AAR Corp, and regulatory affairs specialists navigating FAA and EASA certification pathways. Secondary validation draws from FAA airworthiness directive filings, EASA CS-25 amendment records, REACH chemical restriction updates, and customs trade data for copper and fluoropolymer resin flows. Bottom-up build-ups of program-specific harness demand triangulate against top-down aerospace production forecasts.
Rate-of-change decomposition separates volume drivers from value drivers across the projection horizon, modeling segmentation dimensions including harness architecture type, conductor material, deployment platform, and end-user contract structure. CAGRs derive from fitted growth curves applied to OEM production rate announcements and fleet renewal backlogs. Industry-specific forecast inputs incorporate Boeing 737 MAX and Airbus A320neo delivery schedules, F-35 production ramp projections, and eVTOL manufacturer certification timelines.
Caveats apply where copper price volatility, REACH chemical restriction amendments, or electromagnetic compatibility threshold revisions could materially shift the outlook for material cost structures and supplier qualification burdens. A model refresh is warranted upon material change in FAA or EASA regulatory mandates affecting shielding requirements or flame resistance standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Global Aircraft Windows and Windshields Market
Aircraft and Aerospace Components
Aerospace Couplers Market
Aircraft and Aerospace Components
Spain Rotor Blade Market
Aircraft and Aerospace Components
Asia Pacific Commercial Aircraft Aerostructures Market
Aircraft and Aerospace Components
Europe Passive Electronic Components in Aerospace and Defense Market
Aircraft and Aerospace Components
Aviation Electro Optical Systems Market
Aircraft and Aerospace Components
Europe Rotor Blade Market
Aircraft and Aerospace Components
Commercial Aircraft Turbine Blades and Vanes Market
Aircraft and Aerospace Components
Impact-Resistant Composite Radome Structures for High-Bandwidth Antennas Market
Aircraft and Aerospace Components
Aerospace Parts Manufacturing Market
Aircraft and Aerospace Components
Cold Gas Thrusters Market
Aircraft and Aerospace Components
Aerospace Nuts Market
Aircraft and Aerospace Components
North America Rotor Blade Market
Aircraft and Aerospace Components
Global Aircraft Seat Actuation System Market
Aircraft and Aerospace Components
Composite Wing-to-Body Fairing Structures for Wide-Body Aircraft Market
Aircraft and Aerospace Components
Aircraft Tube and Duct Assemblies Market