
 Helicopter Wheels Market | 2026-2036
Helicopter Wheels Market Size, Share, and Industry Trends Forecast 2026-2036
Helicopter Wheels Market Foresight
Composite material integration is tilting manufacturing toward lighter, thermally resilient wheel architectures. Safran Landing Systems leverages its integrated landing gear platform to anchor European defense and civil helicopter programs. Collins Aerospace sustains broad aerospace portfolio synergies that extend into wheel and brake subsystems for military operators.
Helicopter wheels are load-bearing rotating assemblies, typically forged from aluminum alloy or carbon fiber reinforced structures, designed to support static and dynamic loads during ground taxi, takeoff, and landing operations while accommodating rotorcraft weight distributions and high sink-rate impacts. Lightweight wheels command premium positioning across EMS services and VIP transport configurations where payload sensitivity dictates component selection. Heavy-duty wheels occupy the military and search and rescue segments, where MIL-STD certification requirements and abrasive-field tolerance create defensible margin pools.
FAA Part 27 and Part 29 airworthiness standards govern civil rotorcraft wheel design, while EASA CS-29 shapes European market access and product qualification pathways. The EU AI Act and CSRD reporting frameworks increasingly influence supply chain transparency requirements for aerospace tier-one suppliers. Stakeholders must monitor evolving military specification revisions and dual-use export control harmonization between the United States and European defense procurement frameworks.
Market Dynamics
Forged aluminum wheel architectures face displacement pressure from carbon fiber reinforced polymer assemblies, as rotorcraft operators prioritize payload recovery and thermal performance in high-sink-rate landing profiles.
Growth Catalysts
- MIL-STD-1290 Revision Pressure:United States military fleet modernization programs mandate upgraded wheel assemblies for abrasive-field tolerance, pulling demand through defense contractor supply chains concentrated in the southwestern United States.
- EMS Payload Sensitivity:Emergency medical services operators in Germany and France specify lightweight wheel configurations to recover cabin weight for critical care equipment, creating specification-driven replacement cycles.
- Thermal Resilience Demand:Search and rescue missions in high-temperature operating environments require thermally stable wheel materials, accelerating composite material qualification timelines.
Market Restraints
- Aluminum Alloy Input Volatility:Aerospace-grade aluminum pricing fluctuations compress margin pools for forged wheel manufacturers serving price-sensitive civil operators.
- Defense Procurement Concentration:United States Department of Defense contracting concentration creates single-customer dependency risk for suppliers without diversified civil portfolios.
- Certification Timeline Friction:FAA Part 27 and Part 29 airworthiness validation cycles extend 18-24 months, freezing design iterations for new market entrants.
Strategic Opportunities
- Urban Air Mobility Integration:eVTOL air taxi programs in the United Arab Emirates and Saudi Arabia require adapted wheel assemblies for vertiport operations, opening adjacent specification channels.
- EU CSRD Supply Chain Disclosure:Corporate Sustainability Reporting Directive mandates create first-mover advantage for suppliers with transparent carbon fiber sourcing and lifecycle documentation.
- Aftermarket Service Unbundling:Independent maintenance, repair, and overhaul providers in Australia and Brazil seek direct wheel sourcing relationships outside OEM captive distribution.
Industry Challenges
- Composite Repair Technician Scarcity:Carbon fiber wheel damage assessment and field repair capabilities lag fleet deployment, constraining operator turnaround times.
- Dual-Use Export Control Navigation:United States and European defense procurement framework harmonization gaps create licensing complexity for wheel assemblies with military-civil dual applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helicopter Wheels Market |
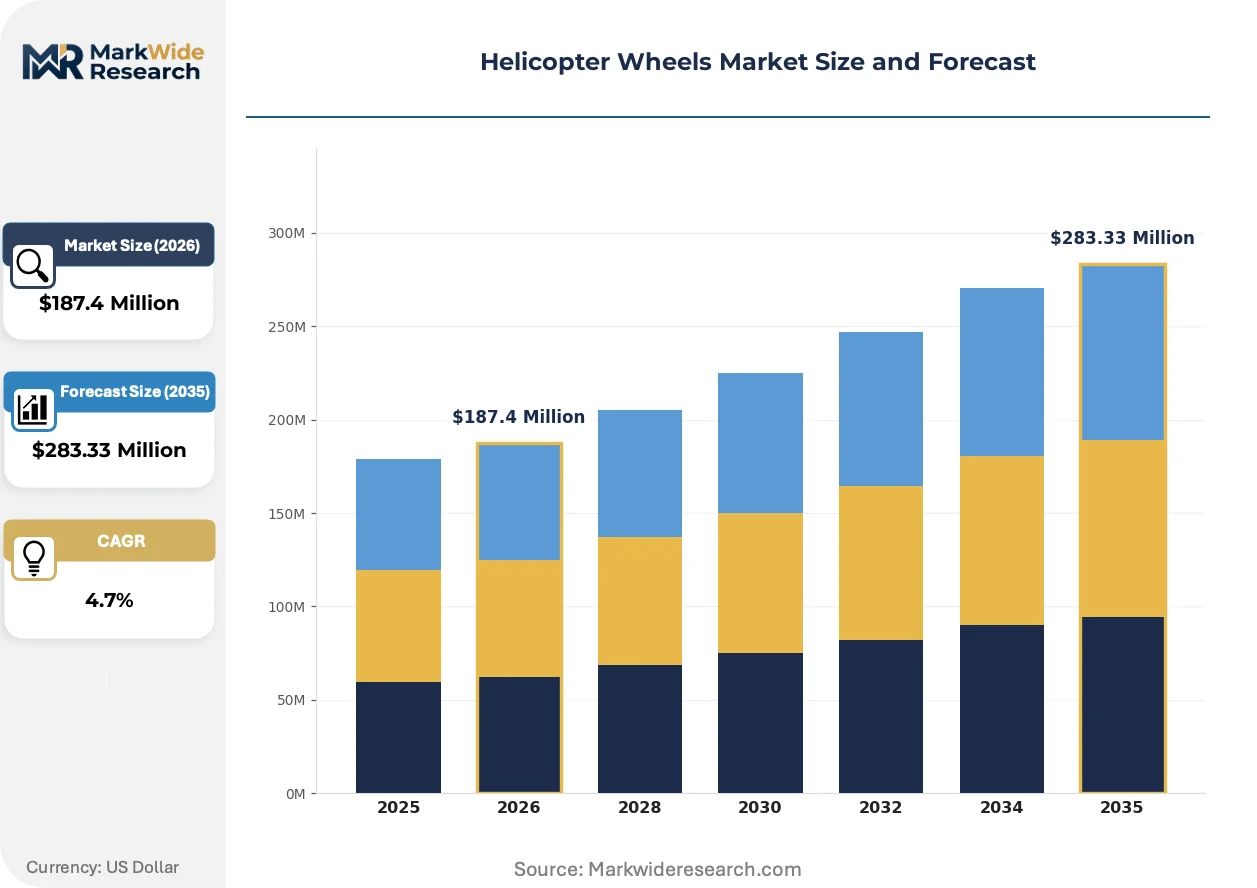
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $283.33 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lightweight Wheels, Heavy-Duty Wheels, Retractable Wheels, Fixed Wheels Material: Aluminum Alloy, Carbon Fiber, Steel, Composite Materials End User: Military Operators, Commercial Aviation, EMS Services, Private Owners Application: Search and Rescue, Transport Operations, VIP Transport, Aerial Surveying |
| Companies Covered | Aero Wheel and Brake Service Corporation, Safran Landing Systems, Collins Aerospace, Beringer Aero, Honeywell Aerospace, Lico Stahl, AAR Corp, AMETEK Inc, TP Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helicopter Wheels Market Shifts & Advancements
Material science advances and regulatory disclosure mandates are compressing traditional manufacturing cycles while opening specification channels previously controlled by integrated landing gear platforms.
Carbon fiber reinforced polymer wheel architectures are collapsing the weight-performance tradeoff that historically favored forged aluminum in heavy-lift military applications. United States Army and Marine Corps operators are specifying hybrid material wheels for next-generation rotorcraft, enabling payload recovery equivalent to two additional passenger positions. This material transition is collapsing the historical segmentation between lightweight civil configurations and heavy-duty military standards.
The EU AI Act and CSRD reporting frameworks are mandating supply chain transparency down to tier-three suppliers, forcing wheel manufacturers to document carbon fiber provenance and energy intensity. European aerospace tier-one suppliers are restructuring qualification protocols to capture compliance documentation at the component level. Military and civil programs with European certification pathways face the steepest documentation burden, accelerating supplier consolidation around integrated platform providers.
After-sales service unbundling is fragmenting the traditional OEM-captive distribution model for wheel and brake subsystems. Independent MRO operators in Australia and Southeast Asia are establishing direct procurement relationships with specialized wheel manufacturers, bypassing landing gear system integrators. This channel disintermediation is most visible in the offshore oil and gas support segment, where fleet operators prioritize turnaround speed over manufacturer-authorized service networks.
Helicopter Wheels Market Segmentation
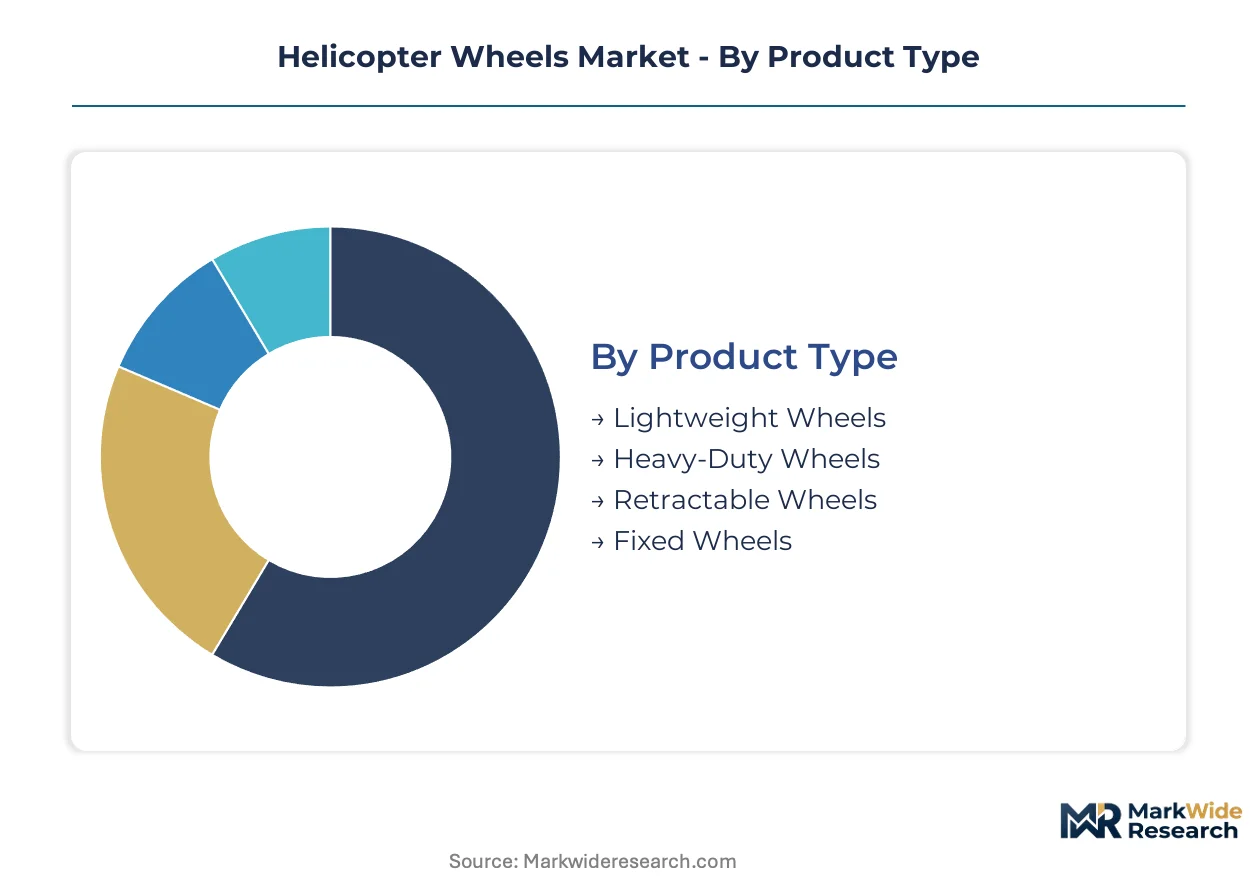
Helicopter wheel procurement cycles vary dramatically across segment categories. Military operators replace heavy-duty assemblies on abrasive-field schedules measured in hundreds of landings, while commercial fleets stretch lightweight wheel service intervals across thousands of cycles. Understanding these replacement rhythms shapes inventory positioning and aftermarket capture strategies.
Product Type:
Replacement velocity diverges sharply across wheel architectures, with mission-critical military configurations turning over fastest and fixed civil installations running longest.
- Lightweight Wheels:Forged aluminum or carbon fiber reinforced structures optimized for payload-sensitive operations. EMS operators in Germany and France drive specification demand where cabin weight recovery enables additional critical care equipment.
- Heavy-Duty Wheels:Reinforced assemblies engineered for high-sink-rate impacts and unimproved surface operations. United States Army and Marine Corps fleet modernization programs mandate MIL-STD-1290 compliant configurations for next-generation rotorcraft.
- Retractable Wheels:Mechanically complex stowable assemblies with higher maintenance burden and shorter inspection intervals.
- Fixed Wheels:Simplified permanent-mount designs with extended service lives and lower total ownership cost profiles.
Heavy-duty wheels dominate installed base. Lightweight wheels are where expansion concentrates.
Material:
Cost tier stratification separates premium composite qualification from commodity aluminum procurement, with thermal performance and field repairability driving specification divergence.
- Aluminum Alloy:Conventional forged aerospace-grade structures with established supply chains and mature repair protocols. Price volatility in aerospace-grade aluminum inputs compresses margin pools for manufacturers serving cost-sensitive civil operators.
- Carbon Fiber:Advanced polymer matrix composites collapsing the weight-performance tradeoff historically favoring metal in heavy-lift applications. United States military operators specify hybrid material wheels enabling payload recovery equivalent to additional passenger positions.
- Steel:Legacy structural material retained in select heavy-lift and training aircraft configurations.
- Composite Materials:Hybrid engineered material systems combining fiber reinforcement with metallic load-bearing elements.
Aluminum alloy retains volume leadership. Carbon fiber is climbing the fastest.
End User:
Customer type determines procurement authority structure, with defense concentration creating single-buyer dependency risk against fragmented civil demand pools.
- Military Operators:United States Department of Defense contracting concentration pulls demand through southwestern United States manufacturing clusters and defense contractor supply chains.
- Commercial Aviation:Fleet operators with scheduled replacement programs and manufacturer-authorized service network dependencies.
- EMS Services:Payload-sensitive operators specifying lightweight configurations to recover cabin weight for medical equipment.
- Private Owners:Price-conscious individual operators with extended replacement cycles and independent maintenance preferences.
Military operators anchor procurement volume. EMS services are gaining share fastest.
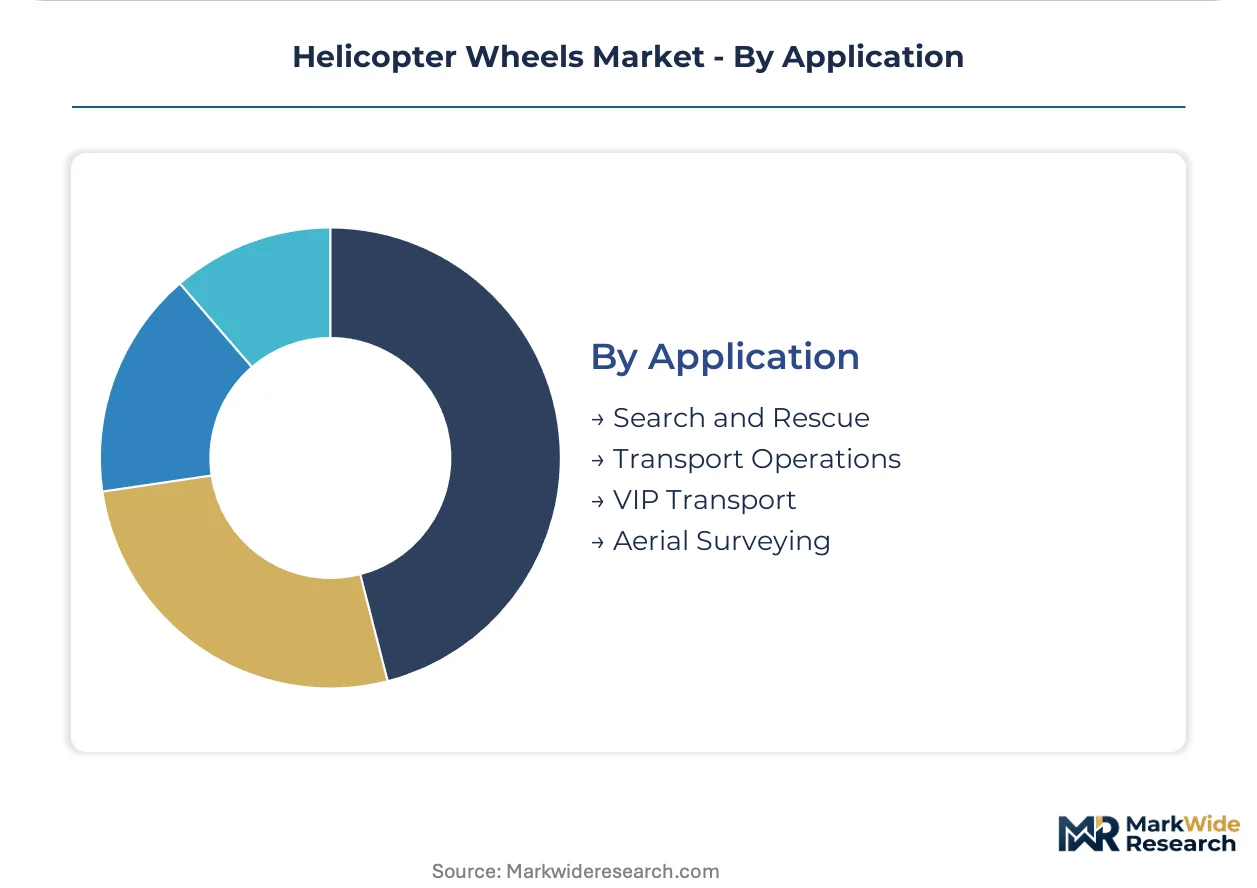
Application:
Operating environment severity shapes material specification, with thermal resilience and abrasive-field tolerance creating premium tier separation.
- Search and Rescue:Thermally demanding missions in high-temperature environments requiring stable wheel materials and accelerated composite qualification timelines.
- Transport Operations:High-cycle commercial utilization with standardized maintenance protocols and predictable replacement scheduling.
- VIP Transport:Payload-optimized configurations where weight sensitivity dictates premium component selection and rapid turnaround requirements.
- Aerial Surveying:Specialized low-altitude operations with unique landing surface exposure and extended field deployment patterns.
Transport operations hold the broadest installed base. Search and rescue shows the steepest specification upgrade trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States manufacturers export helicopter wheel assemblies to European defense programs and Middle Eastern civil operators, creating a transatlantic procurement corridor shaped by FAA-EASA certification reciprocity agreements.
United States
Military fleet modernization and EMS payload optimization drive specification demand. FAA Part 27 and Part 29 airworthiness standards govern civil qualification pathways. Southwestern manufacturing clusters in Arizona and Texas host dense defense contractor supply chains serving Army and Marine Corps rotorcraft programs.
Germany
EMS operators specify lightweight wheel configurations to recover cabin weight for critical care equipment. EASA CS-29 certification shapes European market access requirements. Bavaria's aerospace engineering corridor concentrates tier-one supplier engineering centers and composite material qualification facilities.
France
VIP transport and search and rescue fleets prioritize thermal resilience and rapid turnaround specifications. EU AI Act and CSRD reporting frameworks mandate supply chain transparency documentation. Toulouse's aerospace cluster anchors integrated landing gear platform development for civil and dual-use programs.
United Arab Emirates
eVTOL air taxi programs and offshore oil and gas support operations create adjacent specification channels for vertiport-adapted wheel assemblies. MOHAP aviation safety oversight applies to commercial rotorcraft registration. Dubai's logistics hub concentrates independent MRO providers seeking direct sourcing relationships.
Australia
Search and rescue missions in high-temperature operating environments accelerate composite material qualification timelines. TGA equipment certification applies to medical service rotorcraft configurations. Queensland and Western Australia host offshore oil and gas fleet operators prioritizing turnaround speed over manufacturer-authorized service networks.
Helicopter Wheels Market Competitive Landscape
Channel-controlling players compete with product-specialist players across military and civil procurement pathways. The vendor base organizes around three tiers: integrated landing gear platforms, wheel-specific manufacturers, and aftermarket service providers. Strategic archetypes include defense-focused system integrators, civil aviation specialists, and independent MRO distributors. Dominant competitive moves center on composite material qualification acceleration and aftermarket channel disintermediation.
Within the integrated platform tier, Safran Landing Systems and Collins Aerospace exemplify the landing gear system integrator archetype, anchoring European and United States defense procurement channels respectively. Beringer Aero occupies a position among specialized wheel manufacturers serving payload-sensitive civil operators. These three companies represent the structural segmentation between platform-integrated and component-specialist competitive positions.
| Leading Market Players |
|---|
| Aero Wheel and Brake Service Corporation |
| Safran Landing Systems |
| Collins Aerospace |
| Beringer Aero |
| Honeywell Aerospace |
| Lico Stahl |
| AAR Corp |
| AMETEK Inc |
| TP Aerospace |
| Others |
Supply & Pricing Matrix
Trans-Pacific freight corridors from East Asian carbon fiber manufacturing hubs to southwestern United States defense contractor clusters impose cost volatility that amplifies price differentiation between forged aluminum and composite wheel tiers, concentrating margin recovery among suppliers with captive material sourcing or long-term offtake agreements.
Pricing Analysis
Technology-generation pricing gaps separate legacy forged aluminum configurations from emerging carbon fiber reinforced polymer assemblies and developmental hybrid material systems. Three-tier pricing structure across premium composite, standard aluminum, and economy steel configurations dominates procurement, with certification grade under FAA Part 27 and Part 29 standards and volume scale driving differentiation. Cost compression in aluminum alloy inputs intensifies margin pressure on commodity-tier manufacturers serving price-sensitive civil operators. Private owners exhibit highest price sensitivity, while United States Department of Defense contracting channels absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from tier-one landing gear integrators are restructuring working capital requirements for specialized wheel manufacturers serving aftermarket channels. Geographic concentration centers on the United States, Germany, and Japan, with aerospace-grade aluminum forging capacity anchored in domestic mills and carbon fiber pre-preg sourcing feeding from Japanese Toray facilities and German SGL Carbon operations. Raw material dependencies rest on aerospace aluminum billet, carbon fiber tow, and high-temperature resin systems. Single-source vulnerability in carbon fiber qualification creates structural risk for military program timelines. Distribution runs through OEM-authorized service networks, though independent MRO disintermediation is accelerating in Australia and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon fiber wheel architectures threaten to displace established aluminum forging incumbents, forcing defensive repositioning around qualification timelines and aftermarket channel control.
For Market Incumbents: Entrench composite material qualification leadership by accelerating MIL-STD-1290 certification cycles and securing exclusive carbon fiber supply agreements with Toray or Hexcel. Backward integration into pre-preg manufacturing in Arizona or Texas manufacturing corridors defends margin pools against emerging Asian composite specialists. For New Entrants and Emerging Players: Independent MRO direct-sourcing relationships in Queensland and Western Australia represent the most penetrable entry point, bypassing Safran and Collins captive distribution networks. Urban air mobility vertiport wheel specifications in Dubai and Riyadh offer specification-influence opportunities before standards crystallize. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified aerospace conglomerates with undermonetized wheel and brake subsystem portfolios. Long-term viability hinges on composite repair technician training infrastructure buildout. Watch for FAA-EASA harmonization on carbon fiber damage tolerance standards as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Qualification Acceleration | MIL-STD-1290 certification timelines determine military program access for next-generation rotorcraft. |
| Aftermarket Channel Disintermediation | Direct sourcing relationships with Australian and Brazilian MROs fragment traditional OEM distribution control. |
| Carbon Fiber Supply Security | Long-term offtake agreements with Japanese and German pre-preg manufacturers anchor thermal performance specifications. |
| EU CSRD Compliance Documentation | Supply chain transparency mandates from Brussels restructure tier-three supplier qualification protocols. |
| Urban Air Mobility Specification Capture | Vertiport-adapted wheel architectures in UAE and Saudi programs open adjacent certification channels. |
Research Methodology
A standing panel of rotorcraft fleet managers, landing gear system engineers, defense procurement officers, and aftermarket MRO directors provided ongoing calibration across primary interview cycles, cross-referenced with FAA airworthiness directive filings, EASA certification databases, United States Department of Defense contract award records, and aerospace trade customs data. Bottom-up build from individual program specifications and top-down validation against fleet modernization budgets ensured triangulation integrity.
Scenario-bracketing around military fleet replacement schedules and civil EMS payload optimization trends structured the analytical framework across the projection horizon. Segmentation dimensions modeled include wheel architecture type, material grade tier, end-user procurement authority, and regional regulatory cluster. CAGRs derived from replacement cycle velocity differentials between abrasive-field military operations and high-cycle commercial transport, with composite material adoption curves and certification timeline friction as industry-specific forecast inputs.
Practitioners should monitor MIL-STD specification revision drafts and carbon fiber supply allocation announcements from Japanese manufacturers for early signals of forecast deviation. Macroeconomic contraction in defense appropriations, regulatory divergence between FAA and EASA on composite damage tolerance, or breakthroughs in ceramic matrix composite wheel architectures would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
North America Aircraft Manufacturing Market
Aircraft
Civil Helicopter Market
Aircraft
Middle-East and Africa Freighter Aircraft Market
Aircraft
UK Military Aviation Market
Aircraft
Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market
Aircraft
Europe Helicopters Market
Aircraft
Europe Aircraft Engines Market
Aircraft
Europe Business Jet Market
Aircraft
Commercial Aircraft Lighting Market
Aircraft
South Korea Aviation Market
Aircraft
Asia-Pacific Helicopters Market
Aircraft
Global Aircraft Electric Brake Control System Market
Aircraft
Aircraft Band Clamps Market
Aircraft
UK Aviation Market
Aircraft
Military Helicopters Market
Aircraft
GCC General Aviation Market