
 Latin America Business Jet Market | 2026-2036
Latin America Business Jet Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Business Jet Market Foresight
CE-560 type rating certification is rotating the competitive landscape as smaller operators struggle to meet recurrent training mandates. Embraer SA leverages its São Paulo manufacturing base to anchor regional supply. Gulfstream Aerospace Corporation sustains premium positioning through long-range cabin systems. Bombardier Inc. competes on fractional ownership program penetration across Mexican corporate accounts.
A business jet denotes a fixed-wing aircraft with maximum takeoff weight below 100,000 pounds, pressurized cabin, and turbofan or turboprop propulsion designed for on-demand executive transport rather than scheduled airline service. Light Jets dominate transaction volume across Latin America due to lower operating costs and runway flexibility at secondary airports. Heavy Jets capture disproportionate margin pools from ultra-high-net-worth individuals and government fleets. Charter Services within the End User dimension is expanding fastest as asset-light models displace full ownership among mid-tier corporations.
Brazil's ANAC imposes stringent crew qualification and maintenance intervals that filter out undercapitalized charter operators. Mexico's DGAC coordinates with FAA bilateral agreements to streamline type certificate validation for imported aircraft. EASA-aligned safety management system requirements are spreading across Argentine and Chilean registries. Stakeholders must monitor regulatory divergence between Mercosur and Pacific Alliance aviation frameworks when configuring fleet deployment strategies.
Market Dynamics
CE-560 type rating certification mandates are filtering operator viability across Latin America, forcing capital deployment toward recurrent training infrastructure and displacing undercapitalized charter competitors from active duty rosters.
Growth Catalysts
- ANAC Crew Qualification Standards:Brazil's aviation regulator imposes rigorous pilot certification intervals that elevate safety benchmarks and consolidate market share among compliant operators with dedicated training budgets.
- Secondary Airport Runway Expansion:Infrastructure investment across Mexico's central corridor and Colombia's Andean foothills unlocks point-to-point routing that bypasses congested commercial hubs.
- Sustainable Aviation Fuel Mandates:Emerging regulatory frameworks in São Paulo state and Mexico City create procurement obligations that favor operators with early supply chain positioning in biofuel distribution networks.
Market Restraints
- Turbofan Engine Overhaul Cycles:Powerplant maintenance intervals impose predictable but substantial capital drains that compress operating margins for mid-size charter fleets.
- US Dollar Denominated Aircraft Financing:Currency mismatch between revenue peso/real streams and dollar-denominated lease obligations exposes operators to exchange rate volatility.
- EASA-Aligned SMS Adoption Costs:Argentine and Chilean registry requirements for safety management system documentation impose administrative burdens without immediate operational return.
Strategic Opportunities
- Colombia's Pacific Coast Corridor:Underdeveloped charter penetration between Cali and Buenaventura offers first-mover positioning for operators configuring light jets on short-field runways.
- FAA-DGAC Bilateral Streamlining:Mexico's accelerated type certificate validation for imported aircraft compresses fleet renewal timelines versus legacy import certification pathways.
- Intermodal Executive Ground Transport Integration:Partnership models linking fixed-wing arrival with helicopter transfer to remote mining and energy installations capture premium pricing from resource sector clients.
Industry Challenges
- Simulator-Based Recurrent Training Access:Limited CE-560 full-flight simulator availability across São Paulo and Mexico City forces costly crew rotation to US-based training centers.
- Legacy Avionics Retrofit Certification:ADS-B Out and FANS 1/A compliance deadlines impose hardware upgrade timelines that ground aircraft during peak charter demand windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Business Jet Market |
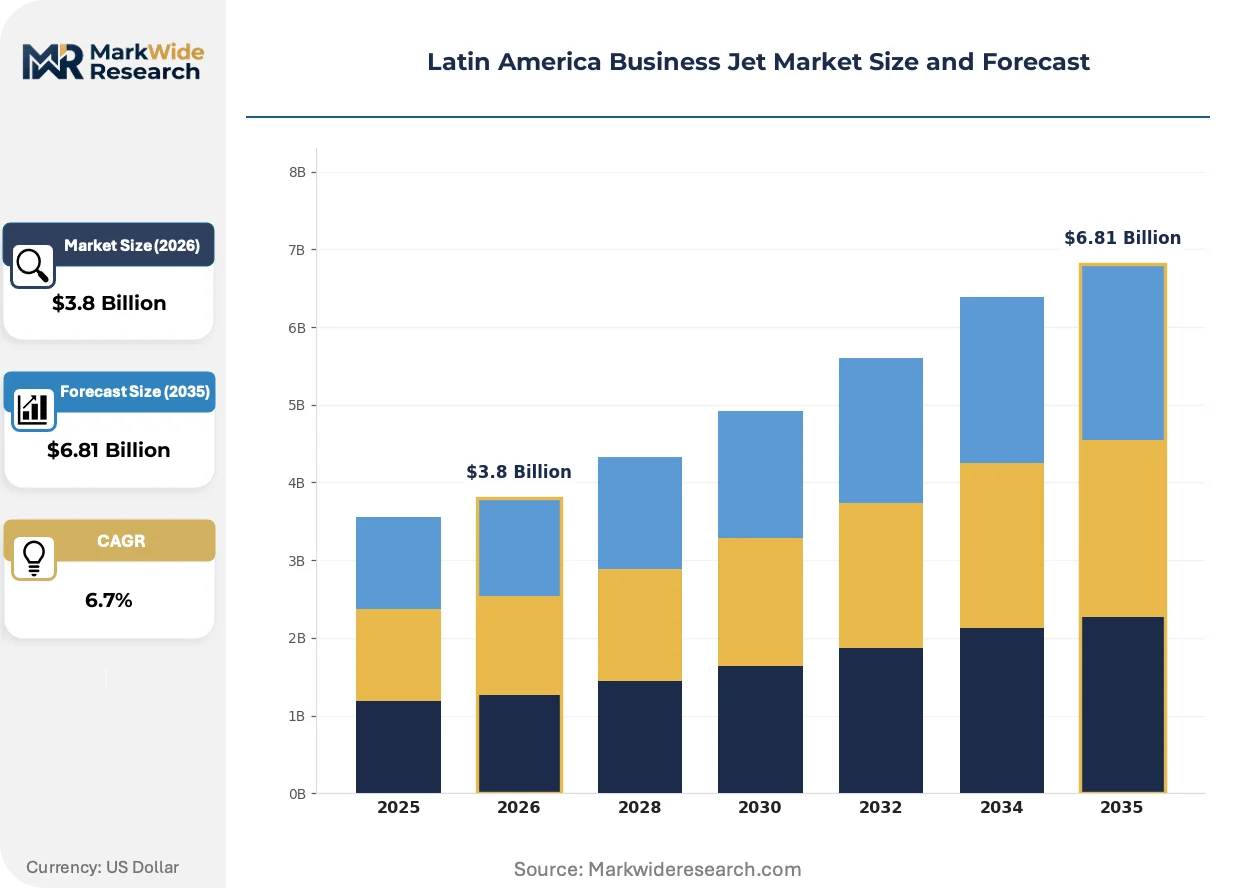
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Light Jets, Midsize Jets, Heavy Jets, Ultra-Long-Range Jets End User: Corporate, Government, Charter Services, Individuals Service Type: Fractional Ownership, Full Ownership, Charter, Leasing Market Segment: Private Aviation, Commercial Aviation, Military Aviation, Cargo Transport |
| Companies Covered | Gulfstream Aerospace Corporation, Honda Aircraft Company, Textron Inc., JetAviva, The Boeing Company, Dassault Aviation, Embraer SA, Jet Luxe, Bombardier Inc., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Business Jet Market Shifts & Advancements
Avionics modernization and propulsion efficiency gains are compressing operating cost structures while regulatory pressure on emissions intensifies fleet turnover decisions across Latin American operators.
Next-generation flight management systems with integrated synthetic vision and runway awareness capabilities are displacing legacy analog instrumentation in light jet retrofits. Charter operators serving Mexico's secondary cities adopt these platforms to reduce minimums at non-precision approach airports. The technology is displacing reliance on ground-based navigation aids and expanding all-weather serviceability for thin-route economics.
ANAC's impending carbon offset requirements for charter operations exceeding defined annual flight hours will reshape fleet composition toward newer, more efficient airframes. Operators anticipate compliance through verified emission reduction credit purchases or fleet renewal toward reduced fuel burn profiles. Heavy jet segments face disproportionate exposure given higher per-flight-hour emission baselines and limited current sustainable aviation fuel availability at Brazilian FBOs.
Asset-light access models are fragmenting traditional full-ownership concentration among mid-tier corporate accounts. Fractional membership programs and dynamic charter brokerage platforms capture travel budgets previously allocated to dedicated aircraft capital expenditure. Mexico's central corridor exhibits the most pronounced behavioral shift, where manufacturing and logistics executives prioritize per-trip variable cost structures over fixed asset carrying costs.
Latin America Business Jet Market Segmentation
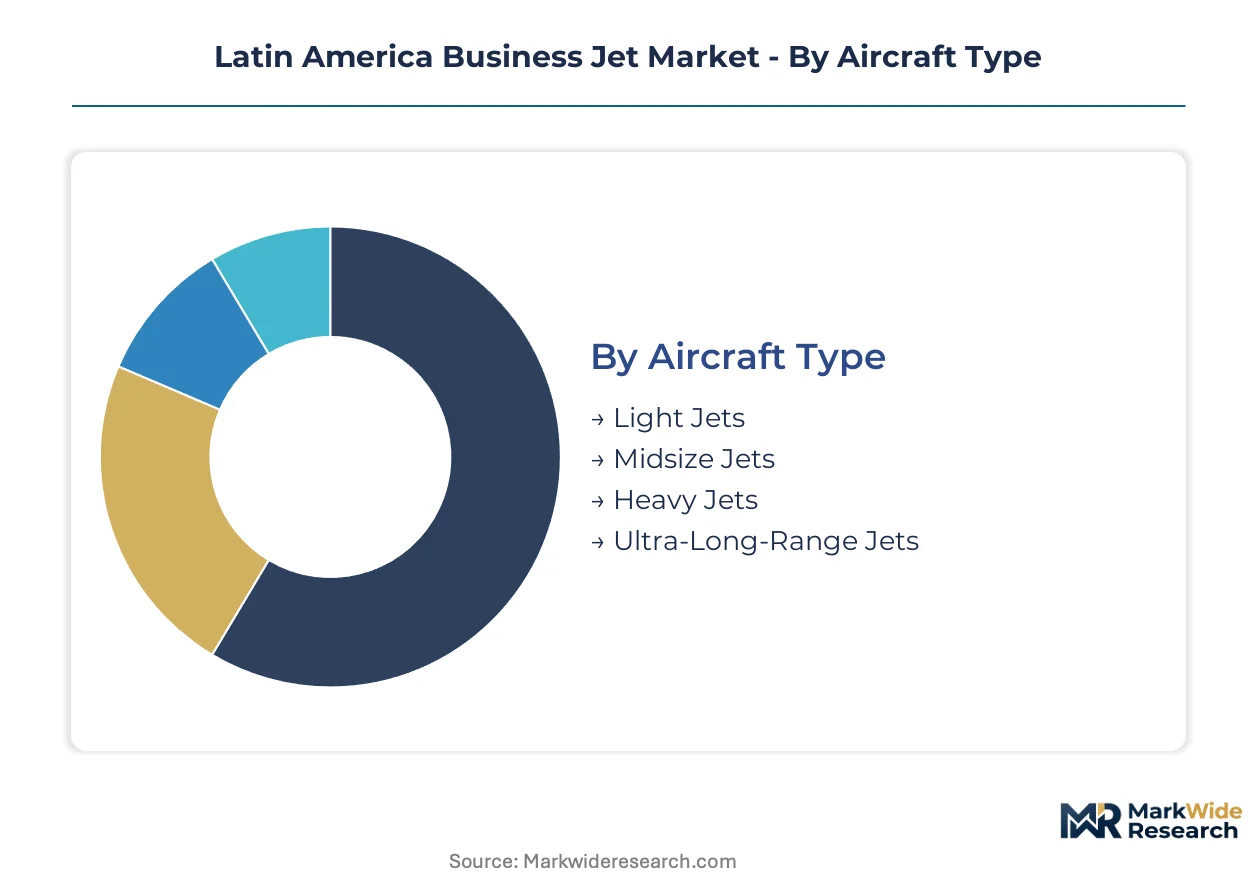
Segmentation in Latin America's business jet market reveals distinct procurement patterns across operator types and regulatory environments. Fleet composition decisions hinge on runway infrastructure, crew certification costs, and the dollar-denominated financing structures prevalent across Brazilian and Mexican operator balance sheets.
Aircraft Type:
Domestic charter demand concentrates in lighter airframes with secondary airport compatibility, while export-linked corporate fleets favor longer-range platforms connecting São Paulo and Mexico City to Miami and New York.
- Light Jets:Maximum takeoff weight below 20,000 pounds with single-pilot certification capability. Demand clusters among Colombian charter operators serving Andean foothill airports with abbreviated runways, where CE-560 type ratings dominate crew qualification pools.
- Midsize Jets:Pressurized cabins accommodating 7-9 passengers with transcontinental range. Brazilian fractional ownership programs deploy these across São Paulo state's manufacturing corridor, balancing acquisition cost against ANAC maintenance interval requirements.
- Heavy Jets:Ultra-high-net-worth individuals and government fleets in Mexico's central corridor favor these for intercontinental reach.
- Ultra-Long-Range Jets:Limited penetration outside sovereign wealth and energy sector principals requiring nonstop Pacific crossings.
Light Jets command the established base across active charter rosters. The steepest expansion runs through Midsize Jets as fractional programs displace full ownership among mid-tier corporate accounts.
End User:
Cost tier stratification separates capital-intensive full-ownership models from variable-cost charter access, with regulatory compliance burdens filtering operator viability across each tier.
- Corporate:Dedicated flight departments with in-house maintenance capabilities. Mexican manufacturing conglomerates in Querétaro and Guadalajara maintain these fleets under DGAC-FAA bilateral streamlined import pathways.
- Charter Services:Asset-light operators offering on-demand access without ownership burden. Brazil's ANAC crew qualification standards consolidate market share among compliant operators with dedicated simulator training budgets.
- Government:Federal and state-level executive transport with sovereign immunity from commercial financing constraints.
- Individuals:Ultra-high-net-worth principals prioritizing schedule autonomy over cost efficiency.
Corporate accounts retain the largest installed base. Charter Services is climbing the fastest as mid-tier executives abandon fixed asset carrying costs for per-trip variable structures.
Service Type:
Application patterns diverge between flight-hour-intensive operators seeking depreciation advantages and capital-constrained users prioritizing balance sheet flexibility.
- Full Ownership:Complete asset control with direct maintenance oversight. Brazilian agribusiness conglomerates favor this model for irregular scheduling across remote Mato Grosso operations.
- Charter:Per-flight-hour access without residual value exposure. Colombia's Pacific coast corridor shows underdeveloped penetration, offering first-mover positioning for light jet operators.
- Fractional Ownership:Depreciable asset interest with guaranteed hourly access. Mexican corporate accounts exhibit pronounced behavioral shift toward this model.
- Leasing:Operating lease structures preserving capital for dollar-denominated revenue streams.
Full Ownership retains dominance among legacy fleet operators. Fractional Ownership is expanding most quickly as asset-light models capture travel budgets previously allocated to dedicated aircraft expenditure.
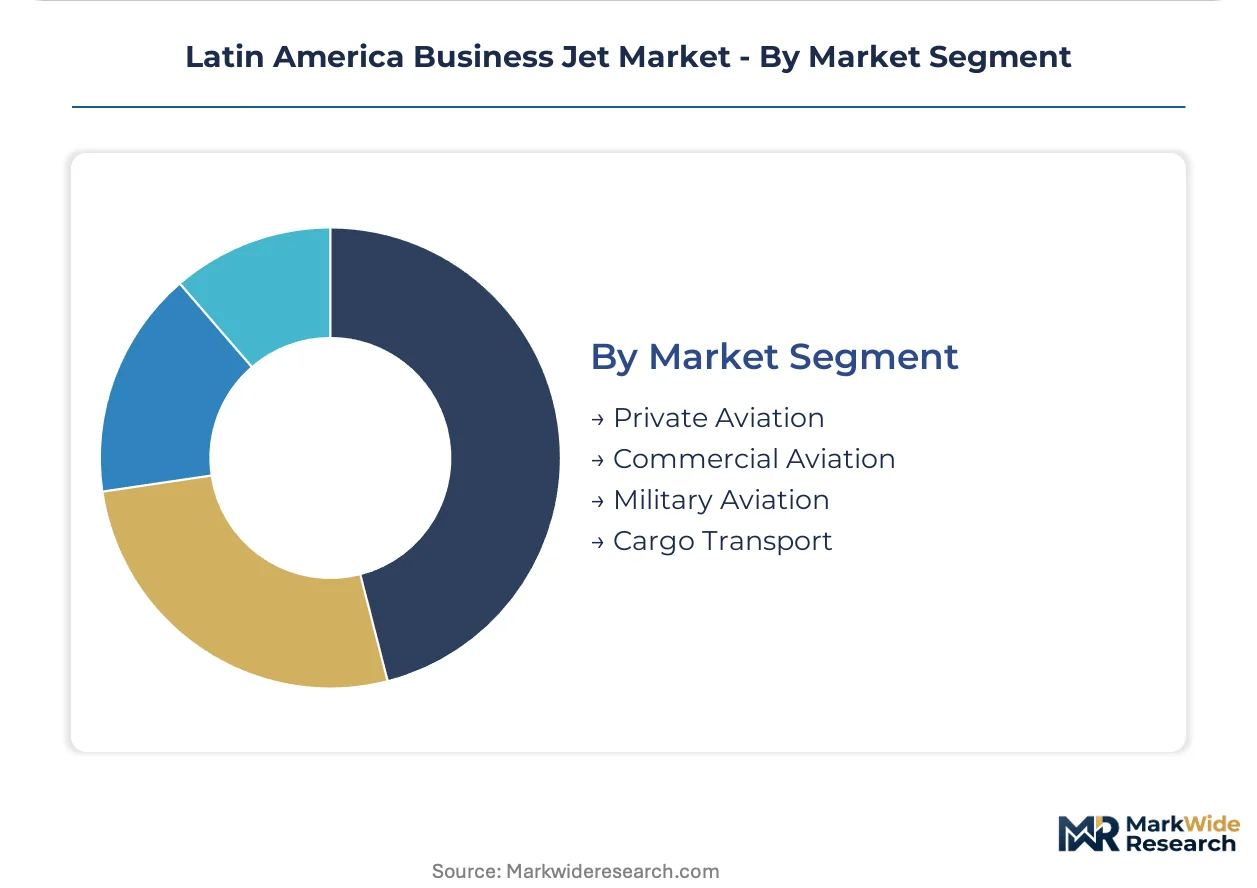
Market Segment:
Volume concentration in executive transport contrasts with thin penetration in specialized mission profiles, reflecting infrastructure constraints and regulatory specialization requirements.
- Private Aviation:On-demand executive transport excluding scheduled airline service. São Paulo state's FBO network anchors regional supply for this segment.
- Commercial Aviation:Supplemental charter capacity during peak commercial hub congestion.
- Military Aviation:Limited specialized transport and surveillance configurations.
- Cargo Transport:Express parcel and time-critical logistics applications.
Private Aviation commands the established revenue base. Cargo Transport shows the steepest expansion trajectory as e-commerce fulfillment demands compress delivery windows across Andean distribution networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The São Paulo-Guarulhos International Airport corridor anchors Latin America's business jet infrastructure, hosting the densest concentration of fixed-base operators and maintenance facilities south of the equator.
Brazil
ANAC's crew qualification standards filter operator viability toward capitalized players with dedicated simulator training budgets. São Paulo state's manufacturing corridor generates concentrated demand from agribusiness conglomerates requiring irregular scheduling across remote Mato Grosso operations. Embraer SA leverages its São José dos Campos manufacturing base to anchor regional supply chain integration.
Mexico
DGAC-FAA bilateral agreements compress type certificate validation timelines for imported aircraft versus legacy import pathways. Mexico City's Toluca International Airport hosts the region's second-largest FBO cluster serving manufacturing executives in Querétaro and Guadalajara. The central corridor exhibits pronounced behavioral shift toward fractional ownership models among mid-tier corporate accounts.
Colombia
Andean foothill airports with abbreviated runways concentrate light jet demand among charter operators holding CE-560 type ratings. The Pacific coast corridor between Cali and Buenaventura shows underdeveloped charter penetration, offering first-mover positioning for short-field capable operators. Bogotá's El Dorado International coordinates with civil aviation authorities on EASA-aligned safety management system adoption.
Argentina
EASA-aligned SMS documentation requirements impose administrative burdens on registry operators without immediate operational return. Buenos Aires metropolitan demand concentrates among ultra-high-net-worth individuals prioritizing schedule autonomy over cost efficiency. The country's national aviation regulator maintains stringent maintenance interval standards that elevate compliance costs for mid-size charter fleets.
Chile
Santiago's Arturo Merino Benítez International serves as the primary gateway for mining sector executive transport to remote Atacama and Antofagasta installations. The civil aviation directorate implements EASA-parallel safety frameworks that filter undercapitalized operators from active duty rosters. Intermodal ground transport integration linking fixed-wing arrival with helicopter transfer captures premium pricing from resource sector clients.
Latin America Business Jet Market Competitive Landscape
Listed leaders compete with private specialists across certification infrastructure and manufacturing scale. The vendor base fragments across three tiers: legacy airframe manufacturers with integrated propulsion capabilities, specialist completion centers serving regional retrofit demand, and asset-light charter platforms disintermediating traditional ownership models. Dominant competitive moves include vertical integration into avionics retrofit certification and strategic partnerships with sustainable aviation fuel distributors.
Within the integrated manufacturing tier, Embraer SA and Gulfstream Aerospace Corporation exemplify contrasting geographic anchoring strategies. Embraer SA occupies a position as the São Paulo-based regional incumbent with manufacturing proximity to Brazil's ANAC regulatory framework. Gulfstream Aerospace Corporation sits within the premium long-range segment, leveraging cabin system differentiation. Bombardier Inc. represents the fractional ownership program archetype penetrating Mexican corporate accounts.
| Leading Market Players |
|---|
| Gulfstream Aerospace Corporation |
| Honda Aircraft Company |
| Textron Inc. |
| JetAviva |
| The Boeing Company |
| Dassault Aviation |
| Embraer SA |
| Jet Luxe |
| Bombardier Inc. |
| Others |
Supply & Pricing Matrix
Ninety-day airframe component lead times from São Paulo suppliers concentrate pricing power among Embraer SA and Gulfstream Aerospace Corporation service networks, while dollar-denominated lease obligations force Brazilian and Mexican operators into hedging structures that compress charter rate flexibility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments Latin American business jet access by certification grade and after-sales bundling intensity. Premium tiers attach dedicated flight crew and ANAC-compliant maintenance packages, while economy positioning strips out simulator training guarantees. Pricing pressure stems from fractional ownership programs displacing full-ownership economics among Mexican manufacturing executives. Corporate flight departments exhibit lowest price sensitivity given sovereign-immunity-equivalent scheduling autonomy, whereas mid-tier charter brokers face acute margin compression from dynamic brokerage platform disintermediation.
Supply Chain Analysis
Strategic stockpiling of turbofan engine cores and avionics retrofit kits dominates operator inventory strategy given twelve-week overhaul cycle unpredictability. Manufacturing concentrates in Brazil, USA, and Canada, with Embraer SA's São José dos Campos facility anchoring regional airframe assembly. Supply chains draw from Pratt & Whitney Canada turboprop powerplants, Honeywell avionics suites, and composite material streams from Mexican maquiladora networks. Single-source vulnerability runs through CE-560 full-flight simulator availability concentrated in São Paulo and Mexico City. Distribution runs through fixed-base operators at Toluca International and Guarulhos International coordinating with regional maintenance facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among mid-tier corporate accounts abandoning fixed asset ownership for asset-light charter access, fragmenting demand across fractional membership programs and dynamic brokerage platforms.
For Market Incumbents: Consolidate simulator training infrastructure in São Paulo and Mexico City to capture CE-560 recurrent certification demand filtering undercapitalized competitors. Deepen backward integration into avionics retrofit certification capabilities ahead of ADS-B Out compliance deadlines. ANAC's impending carbon offset requirements threaten heavy jet residual values, making fleet renewal toward efficient airframes the priority lever. For New Entrants and Emerging Players: Colombia's Pacific coast corridor between Cali and Buenaventura offers first-mover positioning for light jet operators configuring short-field capable aircraft on underdeveloped routes. Intermodal executive ground transport integration linking fixed-wing arrival with helicopter transfer to remote mining installations captures premium pricing from Chilean resource sector clients. Go-to-market execution should anchor in DGAC-FAA bilateral streamlined import pathways compressing fleet renewal timelines versus legacy certification. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance-arbitrage play because ANAC and EASA-aligned SMS mandates continuously filter undercapitalized operators from active duty rosters, consolidating market share among compliant players with dedicated training budgets. Acquisition targets should exhibit captive simulator access and established biofuel distribution relationships positioning ahead of São Paulo state sustainable aviation fuel mandates. Watch CE-560 type rating certification rotation rates as inflection indicator for operator viability consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Simulator Infrastructure Expansion | Captures ANAC-mandated recurrent training demand filtering undercapitalized charter competitors from active rosters. |
| Avionics Retrofit Certification | Secures ADS-B Out and FANS 1/A compliance revenue ahead of regulatory deadlines grounding non-compliant aircraft. |
| Sustainable Aviation Fuel Partnership | Positions operator compliance advantage under emerging São Paulo state and Mexico City biofuel procurement mandates. |
| Fractional Ownership Program Launch | Captures mid-tier corporate travel budgets shifting from full-ownership capital expenditure to per-trip variable structures. |
| Intermodal Ground Transport Integration | Links fixed-wing arrival with helicopter transfer to capture premium pricing from Chilean mining and energy sector principals. |
Research Methodology
A standing panel of charter operations directors, ANAC certification specialists, FBO facility managers, and corporate flight department procurement leads provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation against ANAC regulatory filings, DGAC type certificate validation records, and São Paulo state environmental agency sustainable aviation fuel policy documents. Bottom-up transaction volume modeling triangulated against top-down fleet registry analysis from Brazilian and Mexican civil aviation authorities.
Consistency checks validated volume and value outputs against external benchmarks including OEM delivery disclosures and fractional ownership program membership filings. The analytical framework segmented across aircraft type, end user category, service model, and geographic regulatory cluster throughout the forecast period. CAGRs were derived from installed base turnover rates, import certification velocity, and charter utilization intensity by operator tier. Industry-specific inputs included ANAC crew qualification standard compliance costs and EASA-aligned SMS adoption expenditure profiles.
Forecasts assume regulatory continuity in ANAC, DGAC, and EASA-aligned Argentine and Chilean frameworks; material policy shifts would require re-modeling. Specific risk factors include exchange rate volatility between peso/real revenue streams and dollar-denominated aircraft financing, plus sustainable aviation fuel supply chain disruptions affecting compliance cost projections. Revision becomes warranted when CE-560 simulator capacity constraints or carbon offset requirement implementations cross thresholds altering operator viability filters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Southeast Asia Aviation Market
Aircraft
Wireless in-Flight Entertainment Market
Aircraft
Global Commercial Aircraft Windows and Windshields Market
Aircraft
Middle East and Africa Aviation Market
Aircraft
Asia-Pacific Commercial Aircraft Market
Aircraft
Global Aircraft De-Icing Market
Aircraft
Airplane Brackets Market
Aircraft
Wind Tunnel Market
Aircraft
Aviation Market
Aircraft
Water Bomber Market
Aircraft
Commercial Aircraft Lavatory System Market
Aircraft
Australia Aviation Market
Aircraft
Commercial Aircraft Leasing Market
Aircraft
Aircraft Cargo Winches Market
Aircraft
North America Business Jet Market
Aircraft
Aircraft Aerostructures Market