
 Middle-East and Africa Commercial Aircraft Market | 2026-2036
Middle-East and Africa Commercial Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Commercial Aircraft Market Analytics
ICAO CORSIA is rebalancing the cost-of-entry calculus for Middle-East and Africa carriers by imposing carbon-offset liabilities on older fleet vintages. Airbus leverages its A350 and A320neo families to anchor market presence across Gulf-based full-service airlines. Boeing sustains competitiveness through its 787 Dreamliner platform, which dominates ultra-long-haul routes from Dubai and Doha. Dubai Aerospace Enterprise controls a significant leased-aircraft portfolio, positioning lessors as gatekeepers for capital-constrained African operators.
Commercial aircraft are fixed-wing machines engineered for revenue passenger and cargo transport, typically featuring turbofan propulsion, pressurized aluminum or composite fuselages, and maximum takeoff weights exceeding 5,700 kilograms. Their primary purpose is to enable scheduled and non-scheduled air service across domestic and international route networks. Narrow-body aircraft occupy the volume core of Middle-East and Africa deliveries, driven by point-to-point expansion across secondary African cities and intra-Gulf shuttle frequencies. Wide-body platforms concentrate margin pools on premium long-haul segments connecting the Gulf hubs to Europe, Asia, and North America. Regional jets serve thinner routes where runway limitations or traffic density preclude larger equipment, particularly across East and West African markets.
The General Civil Aviation Authority of the UAE enforces stringent airworthiness and operational standards that de facto filter which aircraft platforms gain market access across Emirates and Etihad networks. South Africa's Civil Aviation Authority and Nigeria's NCAA impose type-certification and noise-compliance requirements that shape fleet-renewal timelines for sub-Saharan operators. Stakeholders must monitor how SAF mandates and bilateral air-service agreements evolve, as these instruments will determine which aircraft technologies and financing structures prevail across the region's heterogeneous regulatory environments.
Market Dynamics
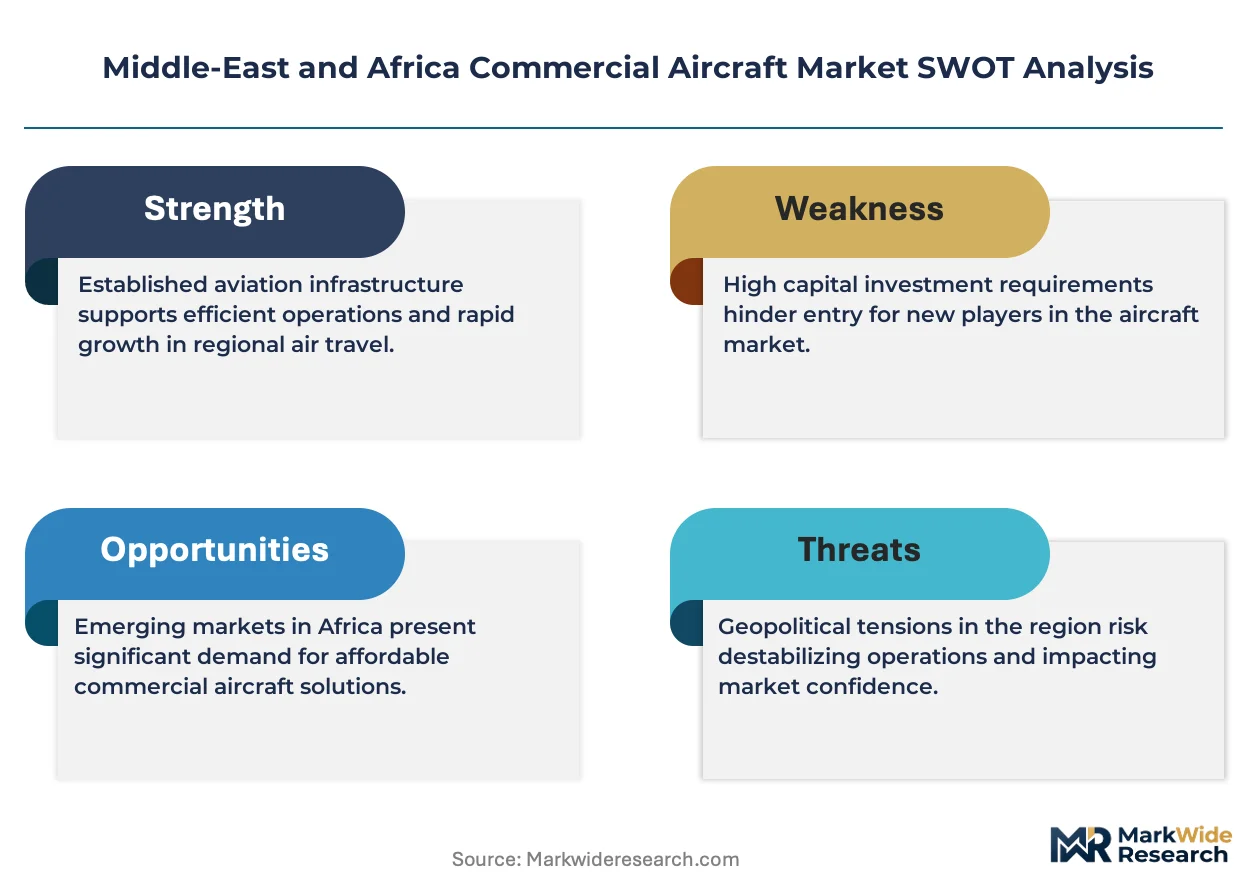
ICAO CORSIA carbon-offset liabilities are restructuring fleet-renewal economics for Gulf and African operators, penalizing older-generation aircraft with higher fuel burn and redirecting capital toward next-generation platforms.
Growth Catalysts
- Sixth-freedom traffic capture:Gulf Cooperation Council full-service carriers are expanding long-haul fleets to intercept Asia-Europe flows through Dubai and Doha hubs.
- SAF mandate preparation:The General Civil Aviation Authority of the UAE is advancing sustainable aviation fuel readiness standards that favor new-technology engine platforms.
- Point-to-point African expansion:Secondary city connectivity across East and West Africa is stimulating narrow-body demand for thin-route economics.
Market Restraints
- USD-denominated financing exposure:African operators face foreign-exchange volatility against dollar-denominated lease payments and manufacturer obligations.
- Lessor market concentration:Dubai Aerospace Enterprise and similar lessors control significant leased-aircraft portfolios, limiting negotiating leverage for capital-constrained carriers.
- Runway infrastructure limitations:Shortened or unpaved strips across sub-Saharan markets restrict aircraft type-certification and payload-range performance.
Strategic Opportunities
- Nigeria NCAA fleet modernization:Noise-compliance deadlines are creating replacement demand for regional jet and narrow-body platforms among Lagos-based operators.
- Intra-Gulf shuttle frequency growth:Business travel between Riyadh, Dubai, and Doha is expanding premium-configured narrow-body deployment.
- Carbon credit monetization:Early CORSIA compliance is generating transferable offset assets for carriers with advanced-technology fleets.
Industry Challenges
- Technical crew certification pipelines:Simulator capacity and type-rating instructor availability are constraining pilot conversion rates for new-generation flight decks.
- Bilateral air-service agreement complexity:Route access negotiations between Gulf hubs and African states are extending fleet-deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Commercial Aircraft Market |
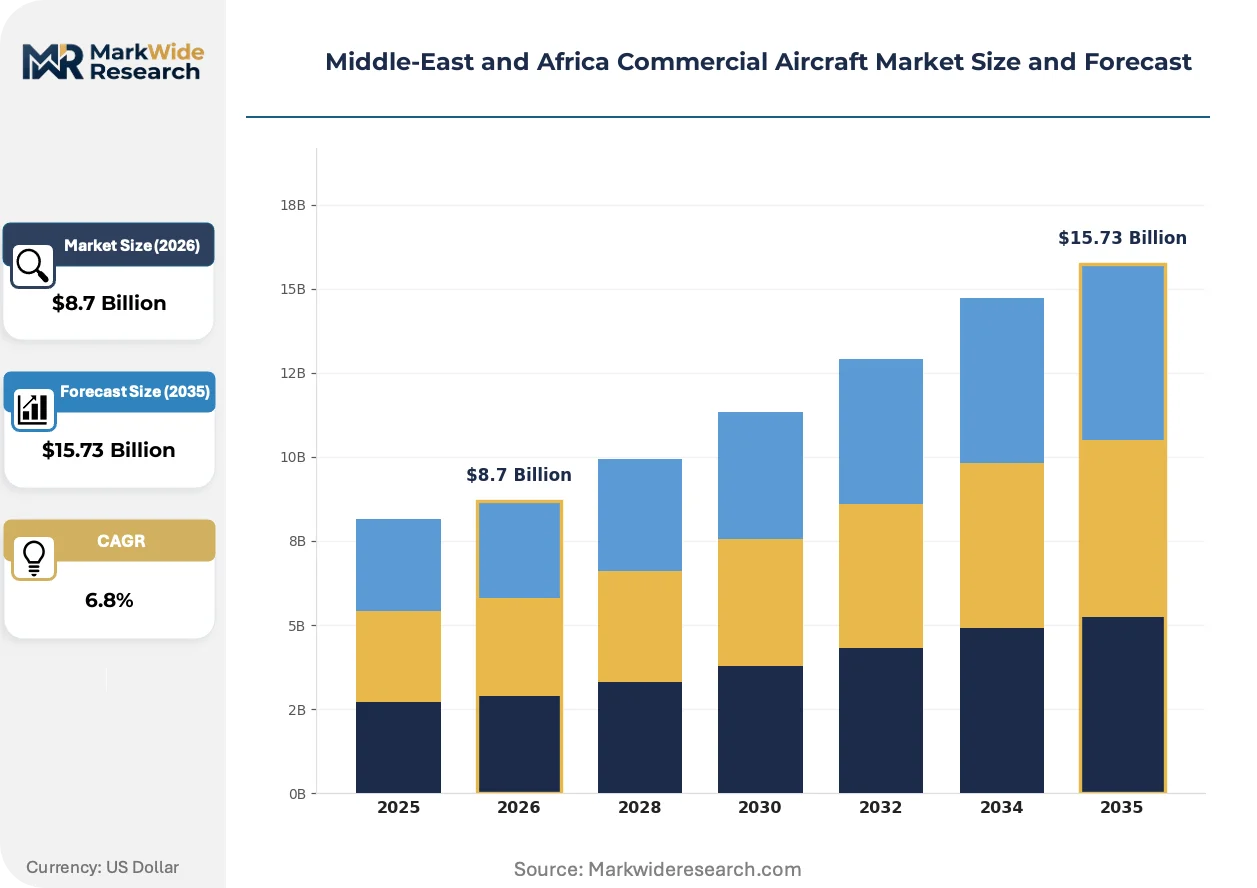
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Narrow-Body, Wide-Body, Regional Jets, Cargo Aircraft End User: Airlines, Charter Services, Freight Operators, Government Agencies Delivery Mode: New Aircraft, Used Aircraft, Leased Aircraft, Refurbished Aircraft Technology: Conventional, Fly-By-Wire, Hybrid, Electric |
| Companies Covered | Boeing, Airbus, Embraer, Commercial Aircraft Corporation of China, ATR, Mitsubishi Heavy Industries, Rostec, Dubai Aerospace Enterprise, AerCap Holdings, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Commercial Aircraft Market Evolving Landscape
Propulsion technology and regulatory carbon-accounting are converging to reshape aircraft selection criteria across Middle-East and Africa networks, with operational data transparency becoming a competitive differentiator.
Geared turbofan architectures are decentralizing engine maintenance economics across narrow-body fleets. African point-to-point operators are adopting Pratt & Whitney GTF and CFM LEAP-1A platforms at accelerated replacement cycles. The technology is decentralizing MRO value chains from traditional hub concentrations toward distributed line-station capabilities.
ICAO CORSIA monitoring, reporting, and verification protocols are mandating granular emissions tracking for international flights. Operators must now install certified fuel-monitoring systems and submit verified carbon data to national authorities. Wide-body fleets serving Europe-Asia sixth-freedom routes face the steepest compliance investments.
Power-by-the-hour contracts are displacing traditional direct-purchase maintenance models among capital-constrained African carriers. Lessors and MRO providers are bundling flight-hour guarantees with lease agreements, transferring utilization risk from operators to service integrators. East African regional jet operators are leading this transition.
Middle-East and Africa Commercial Aircraft Market Segmentation
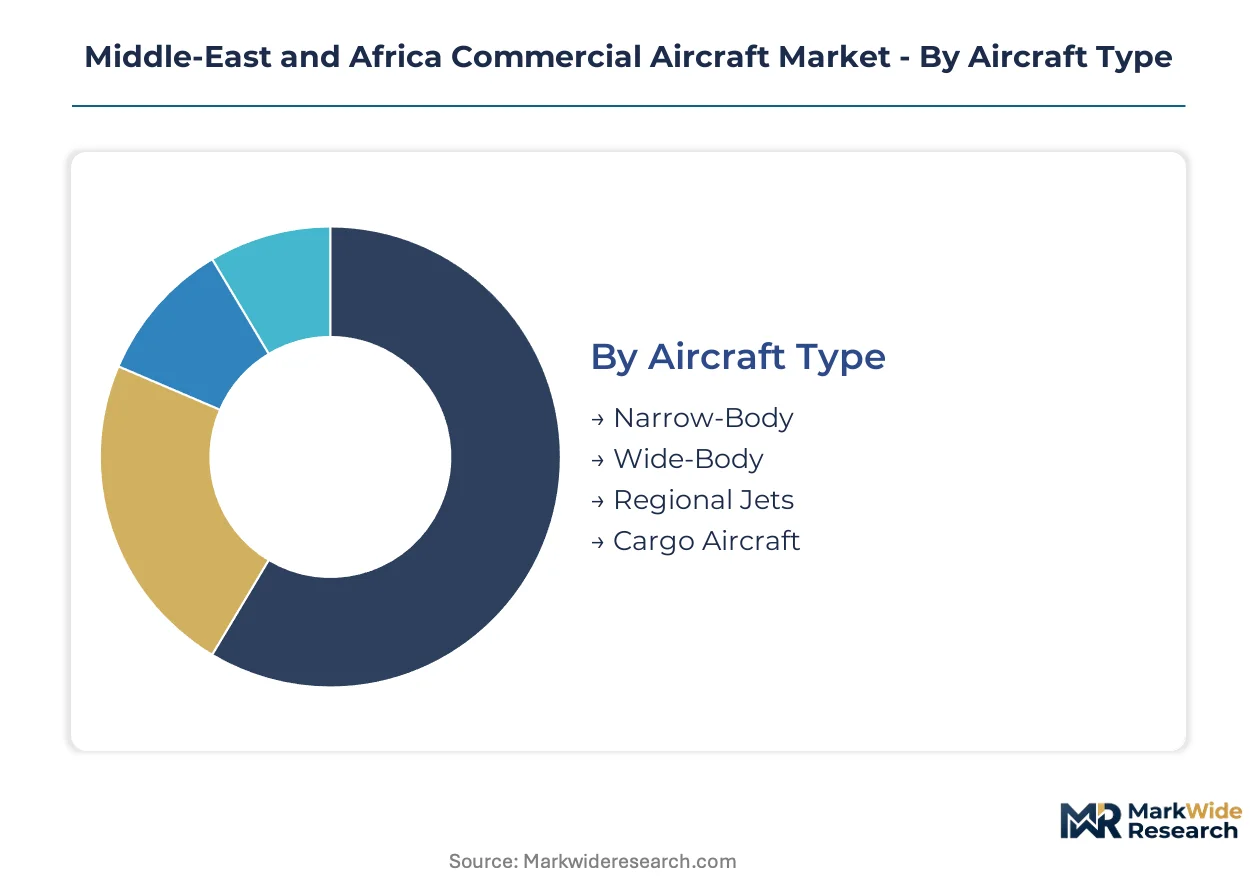
Aircraft segmentation across the Middle-East and Africa reveals divergent capital strategies between Gulf hub operators and sub-Saharan carriers. Fleet composition directly reflects route economics, regulatory pressure from the General Civil Aviation Authority of the UAE, and access to dollar-denominated financing.
Aircraft Type:
Narrow-body platforms dominate unit volume across the region, while wide-body equipment captures premium long-haul margins.
- Narrow-Body:Single-aisle configurations with 100-240 seats serve intra-Gulf shuttle frequencies and African point-to-point expansion. Emirates and Etihad deploy Airbus A320neo and Boeing 737 MAX variants on routes under six hours, while Ethiopian Airlines and Royal Air Maroc utilize these platforms for thin-route economics across secondary African cities.
- Wide-Body:Twin-aisle aircraft with 250-550 seats anchor sixth-freedom traffic capture between Asia and Europe. Dubai and Doha hubs concentrate Airbus A350 and Boeing 787 deployments on ultra-long-haul segments exceeding twelve hours, where fuel efficiency under ICAO CORSIA compliance generates measurable carbon credit advantages.
- Regional Jets:50-100 seat turbofans operate from constrained runways across East and West African markets where traffic density precludes larger equipment.
- Cargo Aircraft:Dedicated freighter platforms serve e-commerce fulfillment and perishable exports from Nairobi and Johannesburg.
Mature deployment sits with wide-body platforms at Gulf hubs. Newer deployment is concentrated in narrow-body fleets across African point-to-point operators.
End User:
Full-service network carriers command capital access, while freight operators and government agencies follow distinct procurement patterns.
- Airlines:Scheduled passenger carriers across the Gulf Cooperation Council and major African capitals drive fleet renewal programs. Qatar Airways and Saudia anchor wide-body orders, while Air Arabia and Flydubai concentrate narrow-body acquisitions for low-cost network density.
- Charter Services:Non-scheduled operators serving pilgrimage traffic and corporate travel require flexible fleet configurations with rapid reconfiguration capability.
- Freight Operators:Dedicated cargo carriers including Ethiopian Cargo and Emirates SkyCargo prioritize payload-range performance over passenger amenity.
- Government Agencies:State transport and military transport commands acquire VIP-configured platforms through sovereign procurement channels.
Airlines represent the dominant procurement volume. Charter services are gaining share fastest among non-state end users.
Delivery Mode:
Capital availability determines whether operators acquire assets outright or access capacity through intermediaries.
- New Aircraft:Factory-fresh platforms from Airbus and Boeing deliver full manufacturer warranties and CORSIA-compliant efficiency ratings. Gulf full-service carriers dominate this channel, leveraging sovereign wealth backing and export credit agency support.
- Used Aircraft:Pre-owned equipment from retiring fleets enters African markets through secondary trading platforms, offering lower unit acquisition costs with higher maintenance burden.
- Leased Aircraft:Operating leases from Dubai Aerospace Enterprise and AerCap transfer residual value risk while preserving balance sheet capacity for route expansion.
- Refurbished Aircraft:Cargo conversion programs and passenger-to-freighter modifications extend economic life for older wide-body airframes.
Leased aircraft dominate African operator access. New aircraft acquisition concentrates among Gulf-based full-service carriers with sovereign backing.
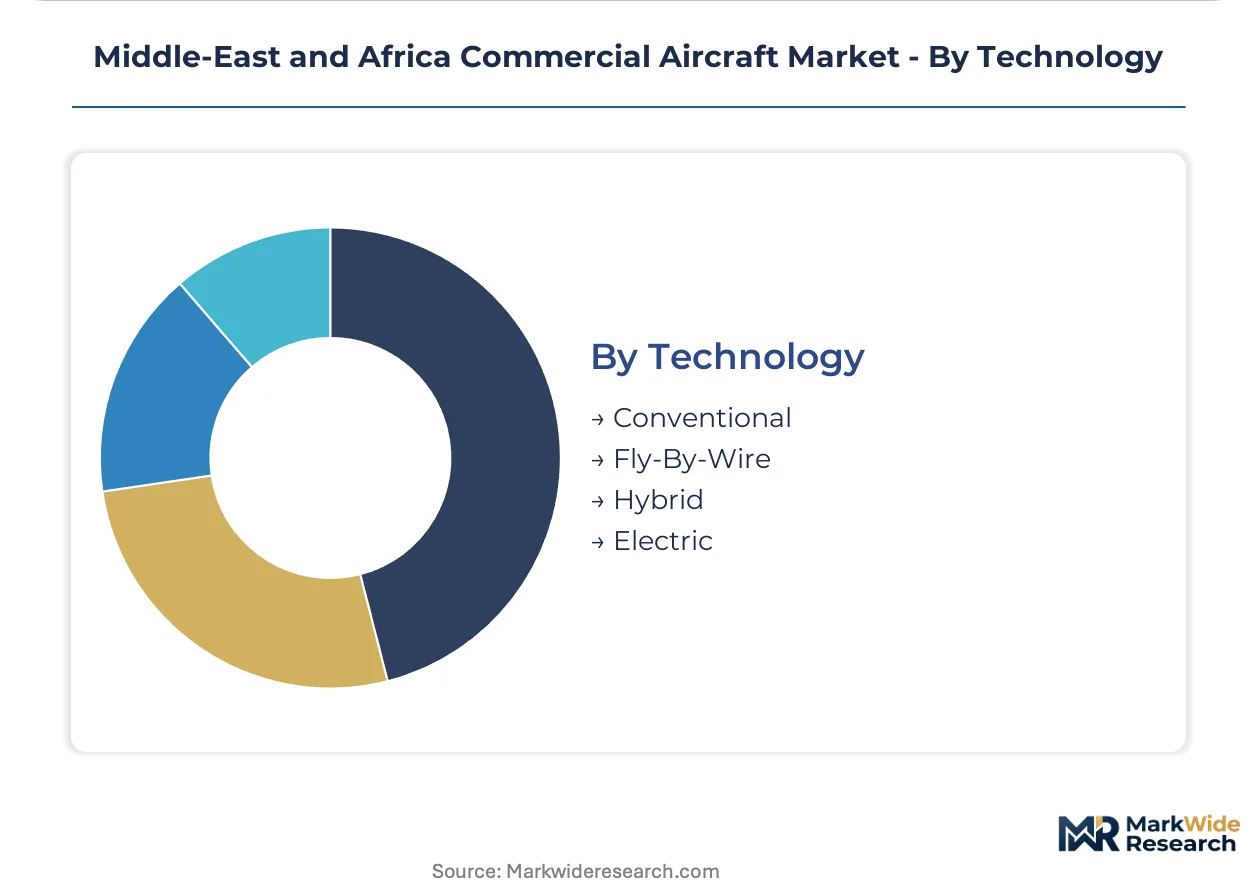
Technology:
Flight control architecture and propulsion systems differentiate compliance-ready platforms from legacy equipment facing carbon-offset penalties.
- Conventional:Hydromechanical flight controls and previous-generation turbofans populate African secondary fleets where capital constraints delay replacement cycles.
- Fly-By-Wire:Digital flight control systems with full-authority engine management dominate new deliveries across Gulf networks, enabling precision fuel management and emissions reporting for CORSIA verification.
- Hybrid:Auxiliary electric systems for ground taxi and hotel power are entering trial deployment with Etihad and Saudia on narrow-body platforms.
- Electric:Battery-electric propulsion remains developmental for commercial scale, with regional demonstrations planned for short-haul African routes under fifty nautical miles.
Fly-by-wire platforms anchor current fleet renewal. Hybrid technology is expanding most quickly among sustainability-focused Gulf operators preparing for SAF mandate phases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai South's Aviation District and Abu Dhabi's Khalifa Industrial Zone anchor aerospace manufacturing incentives across the Gulf. These zones concentrate MRO infrastructure, lessor headquarters, and assembly partnerships that shape fleet deployment patterns throughout the region.
United Arab Emirates
Dubai International and Abu Dhabi International drive sixth-freedom traffic expansion with Emirates and Etihad fleet orders. The General Civil Aviation Authority enforces SAF readiness standards that accelerate A350 and 787 acquisitions. Dubai Aerospace Enterprise headquarters in Dubai South control leased-aircraft portfolios for African operator access.
Saudi Arabia
Saudia and Riyadh Air expansion programs stimulate wide-body demand for Asia-Europe connectivity. The General Authority of Civil Aviation aligns with ICAO CORSIA monitoring protocols for verified emissions reporting. King Abdulaziz International in Jeddah and King Khalid International in Riyadh concentrate new-technology engine deployments.
South Africa
Johannesburg OR Tambo and Cape Town International anchor sub-Saharan fleet renewal for SAA and Airlink networks. The Civil Aviation Authority imposes noise-compliance deadlines that filter regional jet and narrow-body acquisitions. Gauteng province concentrates MRO capabilities and pilot training infrastructure for southern African operators.
Nigeria
Lagos-based carriers face NCAA fleet modernization mandates for noise and emissions compliance. The Nigerian Civil Aviation Authority type-certification requirements shape replacement timelines for 737 and A320 family aircraft. Murtala Muhammed International serves as the West African hub for leased-aircraft transitions from Dubai lessors.
Ethiopia
Ethiopian Airlines anchors East African point-to-point expansion with Addis Ababa Bole International as the regional hub. The Ethiopian Civil Aviation Authority coordinates with ICAO on CORSIA verification for intra-African routes. The Addis Ababa industrial zone concentrates cargo conversion capabilities for perishable export logistics.
Middle-East and Africa Commercial Aircraft Market Competitive Landscape
European and North American producers anchor the wide-body tier; Gulf-based lessors and Asian state-backed manufacturers hold secondary positions. The market structures around three tiers: sovereign-backed full-service carriers with direct manufacturer relationships, capital-constrained African operators dependent on lease intermediaries, and state aerospace conglomerates offering alternative sourcing. Archetypes include hub-dominant network carriers, fleet aggregators, and technology licensors. Competitive moves concentrate on strategic partnerships for SAF development and geographic expansion into African secondary markets.
Within the manufacturer tier, Boeing and Airbus exemplify the dual-oligopoly structure governing new-aircraft supply. Dubai Aerospace Enterprise occupies a position as the dominant lessor archetype for capital-constrained African operators. Among state-backed alternatives, Commercial Aircraft Corporation of China represents the emerging competitor archetype seeking market entry through price-competitive narrow-body offerings.
| Leading Market Players |
|---|
| Boeing |
| Airbus |
| Embraer |
| Commercial Aircraft Corporation of China |
| ATR |
| Mitsubishi Heavy Industries |
| Rostec |
| Dubai Aerospace Enterprise |
| AerCap Holdings |
| Others |
Value Network & Pricing Analysis
Wide-body premium versus narrow-body commodity divergence separates Gulf hub operators from African point-to-point carriers in both acquisition economics and supplier access. Emirates and Qatar Airways command manufacturer priority allocation through sovereign-backed direct purchases, while Ethiopian Airlines and Airlink face Dubai Aerospace Enterprise lease pricing that embeds foreign-exchange risk premiums and residual value uncertainty.
Pricing Analysis
Short lead-time premiums for factory-fresh A350 and 787 deliveries from Airbus and Boeing command pricing power over spot secondary-market inventory from retiring Gulf fleets. Contract-based long-term offtake agreements with export credit agency backing anchor Gulf carrier procurement, while African operators absorb higher unit economics through operating leases with flight-hour guarantee bundling. Price differentiation rests on CORSIA compliance certification tier and engine technology generation, with fly-by-wire platforms carrying material premiums over conventional flight control alternatives. Capital-constrained sub-Saharan carriers exhibit acute price sensitivity, whereas Emirates and Etihad prioritize fuel efficiency and carbon credit generation over acquisition cost minimization.
Supply Chain Analysis
ICAO CORSIA qualification gating restricts engine and airframe platform eligibility for international route access, filtering supplier pools to certified next-generation turbofan manufacturers. Manufacturing concentration centers on France and Germany for Airbus final assembly, the United States for Boeing production, and the United Kingdom for Rolls-Royce propulsion systems. Raw material dependencies span aerospace-grade aluminum from Russia, carbon fiber composites from Japan and the United States, and titanium forgings from Ukraine and China. Single-source vulnerability for LEAP and GTF engine variants creates delivery bottleneck exposure. Distribution runs through Dubai South lessor hubs for African operator access and direct manufacturer channels for Gulf full-service carriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ICAO CORSIA compliance costs construct a barrier-to-entry moat that advantages carriers with early next-generation fleet transitions, penalizing operators with legacy equipment exposure across the forecast window.
For Market Incumbents: Deepen vertical integration into MRO capabilities at Dubai South and Addis Ababa industrial zones to capture servicing margins from leased narrow-body fleets. Anchor long-term engine maintenance contracts with Pratt & Whitney and CFM International to lock in Geared Turbofan and LEAP-1A availability against emerging Commercial Aircraft Corporation of China price competition. Fortify sixth-freedom hub positioning through bilateral air-service agreement expansion into underserved West African markets. For New Entrants and Emerging Players: Capital-constrained regional operators in Nigeria and Kenya represent the most penetrable buyer archetype for alternative narrow-body sourcing through secondary trading platforms. Target NCAA and KCAA noise-compliance deadline windows to position pre-owned A320ceo and 737NG equipment at discount to factory-fresh alternatives. Deploy power-by-the-hour contract bundling to transfer utilization risk and overcome balance sheet limitations. For Investors and Strategic Acquirers: Re-rating potential sits with Dubai Aerospace Enterprise and AerCap given CORSIA-driven fleet renewal acceleration across sub-Saharan markets. Long-term viability hinges on lessor ability to monetize carbon credit generation from advanced-technology lease portfolios. Monitor Ethiopian Airlines and Royal Air Maroc order conversion rates as inflection indicators for African point-to-point demand durability.| Strategic Initiative | Industry Significance |
|---|---|
| Sustainable Aviation Fuel Partnership | Etihad and Saudia co-investment with ADNOC positions Gulf carriers ahead of General Civil Aviation Authority mandate phases. |
| Regional Jet Fleet Renewal | Airlink and RwandAir Embraer E2 acquisitions unlock thin-route economics across East African constrained airfields. |
| Cargo Conversion Capability | Ethiopian Airlines MRO expansion at Addis Ababa Bole International captures perishable export logistics demand from Nairobi and Johannesburg. |
| Simulator Training Infrastructure | Emirates Flight Training Academy capacity expansion addresses technical crew certification pipeline constraints for A350 and 787 flight decks. |
| Bilateral Route Expansion | Qatar Airways air-service negotiations with NCAA and KCAA extend sixth-freedom network density into West and East African secondary cities. |
Research Methodology
Document review covered manufacturer order backlogs, ICAO CORSIA implementation guidelines, and General Civil Aviation Authority regulatory filings, complemented by interviews with fleet planning executives at Gulf Cooperation Council carriers, procurement directors at Dubai Aerospace Enterprise, and technical crew training managers at Ethiopian Airlines. Secondary validation drew from ICAO emissions monitoring protocols, IATA traffic data, and national civil aviation authority type-certification records. Bottom-up aircraft delivery forecasts triangulated against top-down regional traffic growth projections.
Cross-referencing historical delivery patterns against expert panel input on fleet renewal timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include aircraft type, end-user category, delivery mode, and technology tier, with additional granularity on propulsion architecture and CORSIA compliance status. CAGRs derived from log-linear trend fitting adjusted for regulatory inflection points and sovereign wealth fund availability cycles. Industry-specific inputs incorporated engine maintenance cost curves and lease rate factor movements.
Revisions become necessary when ICAO CORSIA phase-in schedules accelerate, SAF mandate deadlines shift, or foreign-exchange volatility disrupts dollar-denominated lease economics. Forecasts reflect assumptions on bilateral air-service agreement expansion rates and MRO infrastructure buildout timelines. A model refresh is warranted upon material change in sovereign carrier capital commitment levels or emerging manufacturer certification progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Global Aircraft Towbars Market
Aircraft
Aircraft Wheels Brakes Market
Aircraft
Asia-Pacific Attack Helicopter Market
Aircraft
Europe Light and Very Light Jets Market
Aircraft
Electric VTOL (Evtol) Aircraft Market
Aircraft
North America Helicopters Market
Aircraft
Commercial Aircraft Overhead Stowage Bins Market
Aircraft
North America Commercial Aircraft Market
Aircraft
Aircraft Flight Control Computers Market
Aircraft
Tanker Aircraft Market
Aircraft
Evtol (Electric Vertical Takeoff and Landing) Airplane Market
Aircraft
Europe General Aviation Market
Aircraft
Asia-Pacific Heavy-Lift Helicopter Market
Aircraft
North America Turboprop Aircraft Market
Aircraft
Aircraft Radome Market
Aircraft
Australia Aviation Market