
 Winglets Market | 2026-2036
Winglets Market Size, Share, and Industry Trends Forecast 2026-2036
Winglets Market Analysis
Blended winglet certification standards are redrawing competitive boundaries across the aftermarket. Aviation Partners Boeing leverages its proprietary joint venture structure to sustain aftermarket retrofit dominance on Boeing platforms. GKN Aerospace anchors European supply through composite manufacturing scale, while Tamarack Aerospace differentiates via active winglet technology that competes on weight and installation speed.
Winglets are aerodynamic surface extensions mounted at aircraft wingtips to reduce induced drag and vortex formation, typically fabricated from carbon fiber reinforced polymer composites or aluminum alloys through autoclave curing or resin transfer molding processes. Their primary purpose is to improve fuel efficiency and extend range without engine modification. Blended winglets occupy the largest installed base across commercial aviation retrofits, while active winglets represent the fastest-growing category as operators seek deployable systems that optimize performance across flight phases. Composite materials command premium positioning due to strength-to-weight ratios, though aluminum alloys retain volume share in military applications where repair simplicity matters.
FAA supplemental type certificate processes and EASA certification memoranda govern winglet retrofit eligibility and installation standards, directly shaping aftermarket access timelines and product development roadmaps. EPA aircraft emissions guidelines and ICAO carbon offset reduction schemes for international aviation create indirect demand pressure by raising fleet efficiency requirements. Stakeholders must monitor evolving certification reciprocity between FAA and EASA as divergence would fragment retrofit approval pathways and alter supplier geographic prioritization.
Market Dynamics
Fuel burn reduction mandates from ICAO's Carbon Offsetting and Reduction Scheme for International Aviation (CORSIA) are forcing narrow-body fleet operators to prioritize wingtip modifications over engine upgrades, reshaping retrofit timelines and supplier qualification criteria across the aftermarket.
Growth Catalysts
- FAA Supplemental Type Certificate streamlining:The FAA's revised STC approval pathways for blended winglet installations on 737NG and A320ceo platforms compress retrofit downtime from 14 days to 7 days, accelerating airline adoption schedules.
- CORSIA compliance deadlines:International carriers subject to ICAO's carbon offset reduction scheme face escalating emissions penalties, making winglet retrofits the lowest-capex path to fleet efficiency targets without aircraft replacement.
- Autoclave-cured CFRP manufacturing scale-up:Composite fabricators in the United States and Germany have expanded autoclave capacity for carbon fiber reinforced polymer winglet skins, reducing unit production lead times by 30 percent.
Market Restraints
- Prepreg carbon fiber cost volatility:Aerospace-grade carbon fiber prices fluctuate with acrylonitrile feedstock costs and energy-intensive oxidation furnace capacity constraints, squeezing margin structures for composite winglet manufacturers.
- Installation facility concentration:Heavy maintenance, repair and overhaul slots capable of winglet retrofit work concentrate in the United States, Germany, and Singapore, creating geographic access bottlenecks for operators in Africa and Latin America.
- Aluminum alloy substitution limits:Military operators prioritizing field-repairability over weight savings continue specifying aluminum winglet structures, fragmenting material standardization and preventing full composite process consolidation.
Strategic Opportunities
- Active winglet deployable surface technology:Tamarack Aerospace's active winglet systems with load-alleviating tab mechanisms enable retrofit on aircraft without structural wing reinforcement, opening addressable market to regional jet and business aviation segments previously excluded.
- India narrow-body fleet expansion:IndiGo and Air India's combined order backlog for A320neo and 737MAX aircraft creates adjacent retrofit demand as older leased assets cycle into secondary operators requiring efficiency upgrades.
- EASA-FAA certification reciprocity expansion:Proposed bilateral agreements to mutual recognition of supplemental type certificates would eliminate redundant testing for European-registered aircraft, compressing supplier market entry timelines.
Industry Challenges
- Composite repair technician scarcity:Airlines and MRO providers face acute shortages of technicians certified to FAA CFR Part 145 standards for carbon fiber laminate repair, extending aircraft ground time during winglet damage events.
- Legacy fleet documentation gaps:Aircraft manufactured before 1995 often lack original wing structural load data required for STC engineering analysis, forcing costly strain gauge flight testing that delays retrofit approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Winglets Market |
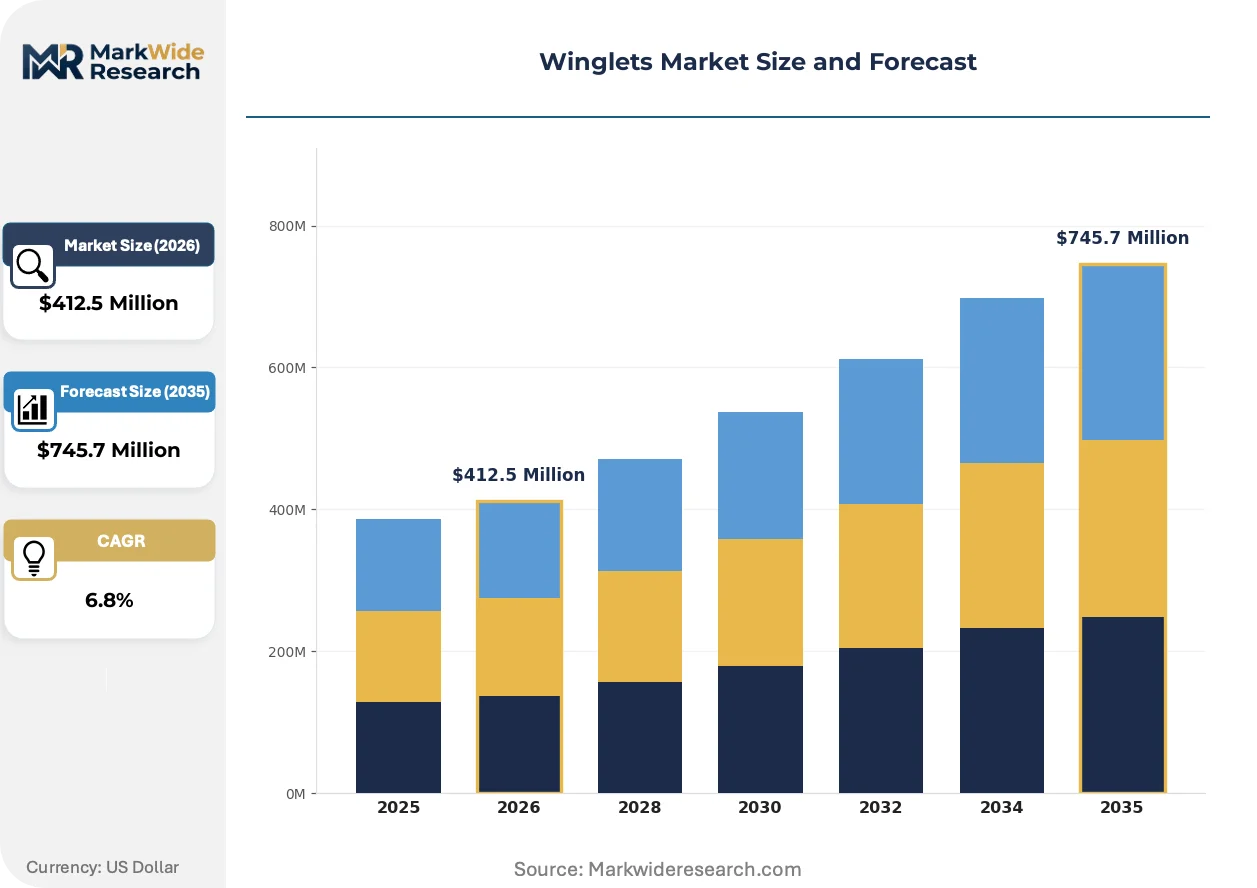
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Active Winglets, Passive Winglets, Blended Winglets, Split Winglets Material: Composite Materials, Aluminum Alloys, Steel, Titanium End User: Commercial Aviation, Military Aviation, Business Aviation, Rotorcraft Application: Fuel Efficiency, Performance Enhancement, Noise Reduction, Structural Integrity |
| Companies Covered | Aviation Partners Inc, Aviation Partners Boeing, GKN Aerospace, FACC AG, Kaman Corporation, Triumph Group, BLR Aerospace, Tamarack Aerospace, RUAG Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Winglets Market Emerging Trajectories
Winglet technology trajectories are diverging between passive aerodynamic efficiency and active load-management systems, with material science and regulatory harmonization acting as cross-cutting accelerants. These shifts are compressing traditional retrofit economics while opening new installation pathways.
Active winglet architectures with integrated load-alleviating surfaces are bifurcating the retrofit market between structural-reinforcement-required and structural-reinforcement-optional installations. Regional operators and freight carriers with aging 737-800 and MD-80 fleets are adopting active systems at triple-digit annual rates. This technology is bifurcating supplier competitive sets into composite fabrication specialists versus electromechanical control system integrators with diverging IP strategies.
EPA aircraft emissions guidelines under the Clean Air Act Section 231 are tightening fleet-average efficiency standards for US-registered commercial operators. The industrial consequence is accelerated retirement of unretrofitted narrow-body aircraft or mandatory wingtip modification to avoid operational restrictions at congested airports. Narrow-body operators with 737NG and A321ceo fleets face the steepest compliance curves and are pre-purchasing STC slots two years forward.
Airline technical procurement departments are unbundling winglet supply from installation labor, previously sold as integrated packages. MRO providers in Eastern Europe and Southeast Asia are capturing installation work through competitive labor arbitrage while OEMs and specialty suppliers retain hardware margins. This pattern is most visible in the European Union where EASA Part 145 maintenance organizations in Poland and Romania have secured winglet retrofit approvals from Aviation Partners Boeing.
Winglets Market Segmentation
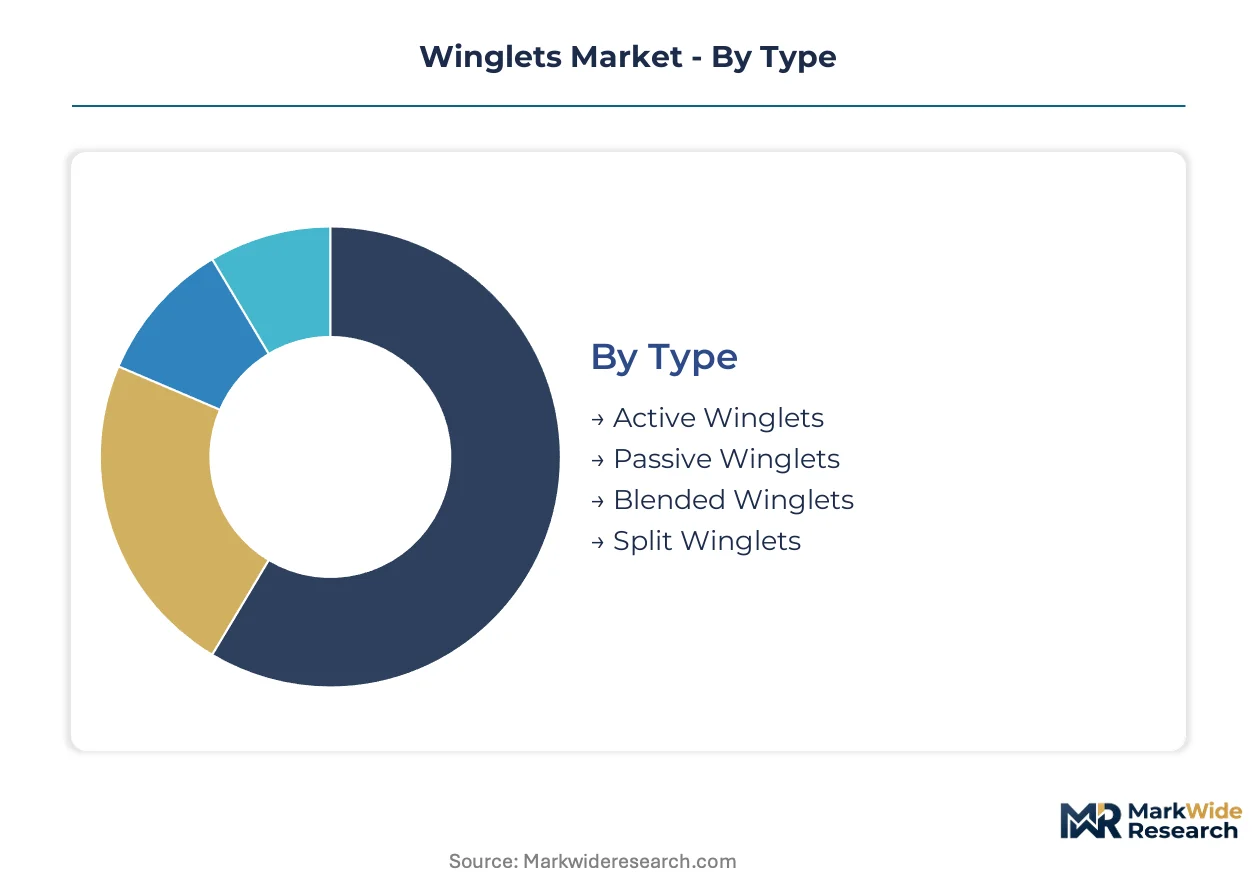
Winglet segmentation reveals how regulatory pathways and operational economics fragment demand across aircraft platforms. FAA supplemental type certificate eligibility and EASA certification reciprocity determine which configurations access which fleet segments, creating distinct competitive arenas for suppliers.
Type:
FAA and EASA certification standards diverge most sharply on winglet type classifications, with active systems facing supplemental type certificate complexity that passive designs avoid.
- Blended Winglets:Curved aerodynamic extensions merge smoothly into wingtips through carbon fiber reinforced polymer skins cured in autoclaves. Commercial narrow-body operators in the United States pre-purchase installation slots two years forward to meet EPA fleet efficiency mandates under Clean Air Act Section 231.
- Active Winglets:Deployable surfaces with load-alleviating tab mechanisms eliminate structural wing reinforcement requirements. Regional jet and business aviation operators adopt these at triple-digit annual rates where passive retrofit engineering costs prove prohibitive.
- Passive Winglets:Fixed aerodynamic surfaces fabricated from aluminum or composite materials dominate military applications where electromechanical complexity introduces maintenance liability.
- Split Winglets:Dual-surface configurations extend vertically and horizontally from wingtips, optimizing vortex disruption across multiple flight phases for long-haul wide-body aircraft.
Established volume favors Blended Winglets; emerging adoption favors Active Winglets.
Material:
Cost tier differentiation separates premium composite fabrication from commodity metal supply, with military procurement specifications preserving aluminum volume despite weight penalties.
- Composite Materials:Carbon fiber reinforced polymer laminates deliver strength-to-weight ratios essential for commercial fuel burn targets. Autoclave capacity expansions in Germany and the United States reduced production lead times substantially for aerospace-grade prepreg suppliers.
- Aluminum Alloys:7XXX series aluminum structures dominate military winglet specifications where field repairability outweighs aerodynamic efficiency gains. Combat aircraft operators require depot-level maintainability without specialized composite technician certification.
- Steel:High-strength alloy fittings and attachment hardware resist fatigue loading at winglet-wing interfaces, specified where impact damage probability elevates.
- Titanium:Corrosion-resistant fasteners and structural elements serve naval aviation applications where salt spray exposure degrades conventional alloys.
Composite Materials command premium positioning; Aluminum Alloys retain institutional procurement volume.
End User:
Customer type determines certification urgency, with commercial operators facing binding emissions deadlines that military procurement cycles circumvent.
- Commercial Aviation:Narrow-body fleet operators retrofit 737NG and A320ceo platforms under CORSIA compliance pressure. United States carriers anchor retrofit demand as EPA aircraft emissions guidelines tighten fleet-average standards.
- Military Aviation:Defense procurement prioritizes aluminum structures and passive configurations for expeditionary repair logistics. Tactical aircraft specifications exclude active systems where electromagnetic interference risks complicate mission profiles.
- Business Aviation:Fractional ownership fleets and corporate flight departments adopt active winglets for installation speed and minimal aircraft downtime.
- Rotorcraft:Helicopter tip devices reduce blade vortex interaction noise and improve hover efficiency, with civil operators in the United States leading adoption against military procurement delays.
Commercial Aviation concentrates retrofit volume; Business Aviation climbs fastest on active technology adoption.
Application:
Application segmentation tracks how operational priorities translate into specification requirements across fleet planning cycles.
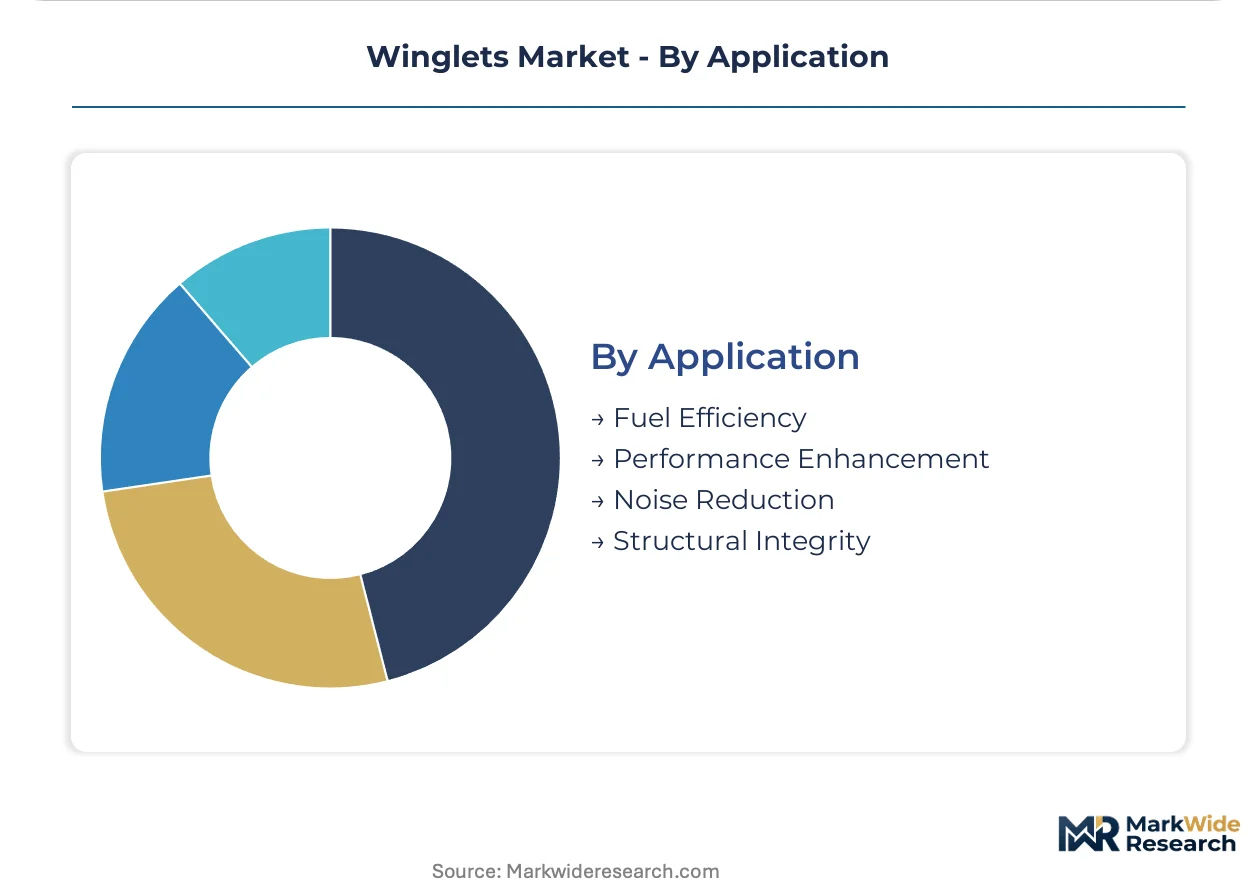
- Fuel Efficiency:Induced drag reduction delivers 3-7% fuel burn improvement for narrow-body operators, the primary economic justification for winglet retrofit capital expenditure. CORSIA compliance deadlines force international carriers to prioritize this application.
- Performance Enhancement:Range extension and hot-and-high airport capability drive adoption for cargo operators and regional carriers serving constrained runways.
- Noise Reduction:Wingtip vortex suppression lowers approach noise footprints, valuable for operators serving noise-curfew airports in Germany and the United States.
- Structural Integrity:Load distribution improvements extend wing fatigue life, a secondary benefit that supports business case justification for aging fleet modifications.
Fuel Efficiency dominates retrofit economics; Performance Enhancement gains share in cargo specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Autoclave-cured composite fabrication clusters in Germany and the United States supply the majority of winglet structures. FAA supplemental type certificate approvals concentrate retrofit demand in North America, while EASA certification reciprocity negotiations determine European market access timelines. MRO facility density in specific metropolitan areas creates geographic bottlenecks for operators outside these zones.
United States
Major carriers retrofit narrow-body fleets under EPA Clean Air Act Section 231 fleet efficiency mandates. FAA streamlined supplemental type certificate pathways compress 737NG and A320ceo installation downtime to seven days. Dallas-Fort Worth and Miami host the densest concentrations of Part 145 MRO facilities capable of blended winglet retrofit work.
Germany
Lufthansa Technik and third-party MRO providers serve European narrow-body operators facing CORSIA compliance deadlines. EASA certification memoranda govern active winglet approvals with timelines that diverge from FAA pathways. Hamburg and Munich anchor composite autoclave capacity for carbon fiber reinforced polymer winglet skin production.
China
Domestic airlines retrofit leased 737-800 fleets as secondary operators acquire aging narrow-body assets. Civil Aviation Administration of China type certification processes for foreign-designed winglets create approval backlogs. Tianjin and Shanghai maintenance clusters expand winglet installation capability for indigenous and imported aircraft platforms.
Singapore
ST Engineering and third-party MRO providers capture Southeast Asian carrier retrofit demand outside Chinese and Japanese maintenance networks. CAAS alignment with FAA certification standards accelerates supplemental type certificate recognition for blended winglet systems. Seletar Aerospace Park concentrates heavy maintenance slots for regional jet and narrow-body wingtip modifications.
Brazil
GOL and Azul evaluate winglet retrofits for 737NG subfleets serving domestic trunk routes. ANAC certification reciprocity with FAA standards determines aftermarket access timelines for imported STC packages. São Paulo state hosts the sole South American MRO facility with Aviation Partners Boeing-approved blended winglet installation capability.
Winglets Market Vendor Landscape
Concentration sits with joint-venture structures and composite fabrication specialists that control proprietary aerodynamic designs. The aftermarket splits between OEM-aligned retrofit providers and independent technology licensors. Three archetypes dominate: joint-venture entities leveraging platform-specific intellectual property, European composite manufacturers with autoclave scale, and active technology specialists competing on installation speed. Capacity expansion and certification reciprocity lobbying constitute the dominant competitive moves.
Within the joint-venture tier, Aviation Partners Boeing and Aviation Partners Inc exemplify platform-captive retrofit dominance. GKN Aerospace and FACC AG occupy positions among European composite fabricators with aerospace-grade autoclave infrastructure. Tamarack Aerospace represents the active winglet archetype with load-alleviating surface technology.
| Leading Market Players |
|---|
| Aviation Partners Inc |
| Aviation Partners Boeing |
| GKN Aerospace |
| FACC AG |
| Kaman Corporation |
| Triumph Group |
| BLR Aerospace |
| Tamarack Aerospace |
| RUAG Group |
| Others |
Supply Flow & Price Mechanics
Composite prepreg substitution for aluminum alloy winglet skins is redrawing manufacturing geography toward autoclave clusters in Germany and the United States while compressing margin structures for traditional metal fabricators unable to absorb carbon fiber feedstock volatility.
Pricing Analysis
FAA supplemental type certificate tiers dictate the pricing structure across winglet retrofit markets, with three-tier pricing stratifying across active technology premium, blended winglet standard, and passive aluminum economy levels. Price differentiation hinges on certification pathway complexity and installation downtime guarantees, with commercial narrow-body operators least sensitive due to CORSIA compliance deadlines and regional freight carriers most price-constrained. Cost compression in the standard tier is intensifying because autoclave capacity expansions in Hamburg and Dallas-Fort Worth are shortening production lead times.
Supply Chain Analysis
Inventory cycles for aerospace-grade carbon fiber prepreg stretch 16-20 weeks, forcing composite fabricators to pre-position material ahead of confirmed STC orders. Winglet manufacturing draws from acrylonitrile feedstock suppliers in the United States, oxidation furnace operators in Germany, and autoclave curing facilities concentrated in both countries. Single-source vulnerability sits with Toray and Hexcel prepreg supply agreements. Distribution runs through Aviation Partners Boeing-certified MRO networks and independent EASA Part 145 facilities in Eastern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Winglet aftermarket economics increasingly favor service-attach revenue streams, with STC engineering support and composite repair technician certification programs expanding faster than hardware unit shipments as airlines internalize lifecycle cost management.
For Market Incumbents: Fortify aftermarket lock-in by captive supply of carbon fiber repair kits and exclusive technician training programs certifying to FAA CFR Part 145 standards. Active winglet specialists threaten platform-agnostic retrofit dominance; defend by backward integration into autoclave capacity additions in Texas and Bavaria to compress lead times below challenger thresholds. For New Entrants and Emerging Players: Differentiate on installation speed metrics by targeting the regional jet segment where passive retrofit engineering costs exclude incumbent blended winglet solutions. The most penetrable white space sits with 50-76 seat CRJ and E-Jet platforms lacking STC coverage. Pursue EASA-FAA certification reciprocity lobbying to accelerate market entry without redundant flight testing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed composite fabricators holding autoclave scale but lacking platform-specific IP. Long-term viability centers on 5-10 year fleet renewal windows where narrow-body retrofit demand sustains through CORSIA phase-in. Watch for ICAO carbon offset price floor adjustments as the inflection signal for retrofit urgency acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Autoclave Capacity Expansion | GKN Aerospace's Hamburg facility additions shorten CFRP winglet skin lead times for European narrow-body operators. |
| Active Winglet STC Portfolio Buildout | Tamarack Aerospace's load-alleviating tab mechanisms open regional jet segments previously excluded from retrofit economics. |
| EASA-FAA Certification Reciprocity Lobbying | Bilateral mutual recognition agreements would eliminate redundant testing for Aviation Partners Boeing European market entry. |
| Composite Repair Technician Certification Programs | FAA Part 145 training partnerships address acute scarcity extending aircraft ground time during winglet damage events. |
| Backward Integration into Prepreg Supply | Upstream control over acrylonitrile-carbon fiber value chains insulates margin structures from feedstock cost volatility. |
Methodological Framework
Operator-level perspectives from fleet planning directors, MRO procurement managers, FAA designated engineering representatives, and composite fabrication plant managers anchored the qualitative base. Primary interview findings triangulated against FAA supplemental type certificate filings, EASA certification memoranda, EPA aircraft emissions compliance databases, and ICAO CORSIA implementation reports. Bottom-up unit shipment estimates across winglet type, material, and end-user segments reconciled with top-down fleet retrofit penetration models.
Sensitivity analysis tested forecast robustness across acrylonitrile price scenarios, certification timeline variations, and CORSIA carbon offset price assumptions over the projection horizon. Segmentation dimensions modeled include winglet type classification, material composition tier, end-user aviation category, and geographic regulatory cluster. CAGRs derived from logistic diffusion curves fitted to narrow-body fleet age distributions and emissions compliance deadline constraints. Forecast inputs incorporated STC approval velocity indices and MRO slot availability metrics.
Material uncertainties — prepreg supply disruptions, certification reciprocity negotiation failures, and legacy fleet documentation gaps forcing costly strain gauge testing — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding ICAO implementation timelines and EPA enforcement consistency. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Asia-Pacific Business Jet Market
Aircraft
Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market
Aircraft
UK Aviation Market
Aircraft
Aircraft Leasing and Rental Market
Aircraft
Military Transport Aircraft Market
Aircraft
Global Business Aircraft Market
Aircraft
Light and Very Light Jets Market
Aircraft
Active Air Deflector Market
Aircraft
Commercial Aircraft Aerostructures Market
Aircraft
Aircraft Container & Pallet Loader Market
Aircraft
Aircraft Sequencing System Market
Aircraft
Aircraft Wheels Market
Aircraft
Europe Military Helicopters Market
Aircraft
North America Helicopters Market
Aircraft
Fixed Wing Turbine Aircraft Market
Aircraft
Europe Helicopters Market