
 Active Air Deflector Market | 2026-2036
Active Air Deflector Market Size, Share, and Industry Trends Forecast 2026-2036
Active Air Deflector Market Outlook
The active air deflector market is rebalancing as premium electro-mechanical systems pull away from commodity mechanical alternatives in pricing and performance specifications. Robert Bosch GmbH leverages its sensor-integration expertise to anchor the high-value tier with intelligent deflector controls. Magna International Inc. sustains manufacturing scale across North American and European assembly lines. Plastic Omnium competes through vertical integration into composite materials and aerodynamic module assembly.
An active air deflector is a dynamically adjustable aerodynamic surface, typically constructed from glass-reinforced nylon or thermoplastic composites, that modulates airflow across vehicle exteriors or HVAC intakes to reduce drag coefficient or optimize thermal exchange. Electro-mechanical variants now lead technology adoption as automakers demand programmable angle adjustment with real-time feedback, while mechanical systems retain share in cost-sensitive commercial vehicle segments. Application demand concentrates in automotive platforms, where active grille shutters and hood deflectors integrate with powertrain thermal management, though aerospace retrofit programs represent a faster-growing margin pool.
NHTSA fuel economy regulations and EPA greenhouse gas standards shape automotive OEM procurement thresholds for aerodynamic components in the United States. ECE R10 electromagnetic compatibility requirements and EU type-approval frameworks govern electro-mechanical deflector deployment across European vehicle platforms. Stakeholders must monitor how battery-electric vehicle thermal architectures redefine deflector duty cycles and whether hybrid propulsion systems sustain dual-mode aerodynamic strategies.
Market Dynamics
Electro-mechanical active air deflectors are displacing mechanical systems as automakers redesign thermal architectures for battery-electric platforms, creating a bifurcation between premium programmable systems and cost-optimized alternatives.
Growth Catalysts
- EPA greenhouse gas standards:NHTSA fuel economy regulations in the United States mandate aerodynamic efficiency improvements that active grille shutters directly address.
- Glass-reinforced nylon composites:Material advances reduce component weight while maintaining thermal stability under hood temperatures exceeding 120°C.
- German premium OEM procurement:Stuttgart and Munich-based automakers anchor electro-mechanical deflector demand through integrated thermal management modules.
Market Restraints
- Actuator motor cost volatility:Rare earth magnet price swings in Chinese processing facilities compress margins on electro-mechanical variants.
- Sensor integration complexity:ECE R10 electromagnetic compatibility testing extends European type-approval timelines by four to six months.
- Mechanical system substitution:Commercial vehicle fleets in cost-sensitive segments retain passive aerodynamic solutions.
Strategic Opportunities
- Aerospace retrofit programs:Aftermarket aerodynamic optimization for regional jet fleets creates margin pools above automotive benchmarks.
- EU Green Deal procurement incentives:Carbon border adjustments reward suppliers with verified lifecycle emissions reductions.
- Sensor-fusion convergence:Integration of lidar and thermal imaging with active deflector control enables predictive angle adjustment.
Industry Challenges
- Embedded software certification:ISO 26262 functional safety compliance for automotive deflector control systems demands specialized engineering talent.
- Legacy thermal architecture integration:Hybrid powertrains require dual-mode aerodynamic strategies that complicate control logic development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Air Deflector Market |
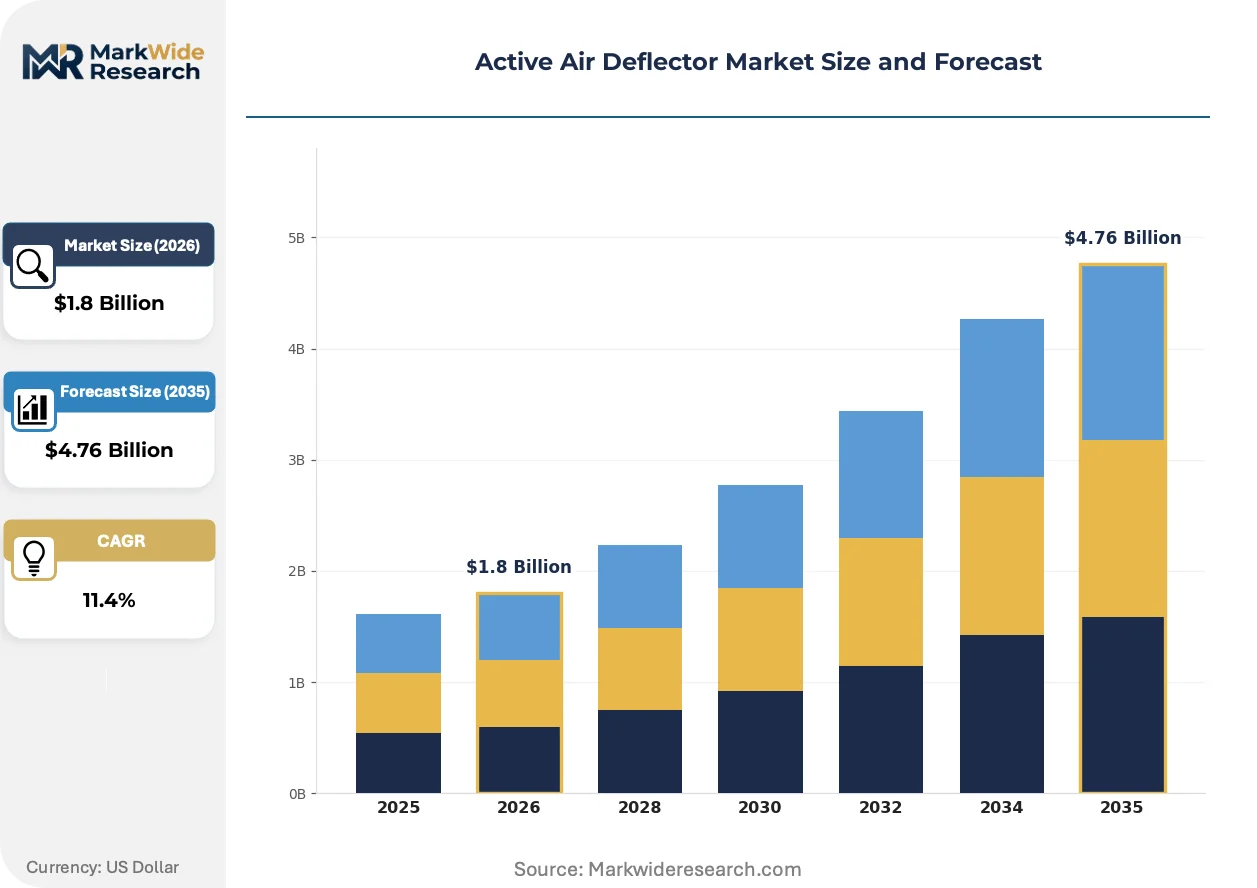
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Mechanical, Electro-mechanical, Pneumatic, Hybrid Application: Aerospace, Automotive, HVAC systems, Marine End User: Manufacturers, Service Providers, Consumers, Contractors Feature: Adjustable Angle, Energy Efficiency, Noise Reduction, Durability |
| Companies Covered | Lund International, Airodyne Industries Inc., Robert Bosch GmbH, Stampede Automotive Accessories, Climair UK Ltd, Magna International Inc., Plastic Omnium, WeatherTech, Röchling SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Air Deflector Market Strategic Shifts
Digital twin simulation and real-time airflow modeling are compressing development cycles while enabling predictive maintenance contracts that extend supplier revenue streams beyond hardware shipment.
Shape-memory alloy actuators are rewriting the competitive economics of active deflector systems by eliminating motor assemblies and reducing part counts by sixty percent. BMW and Mercedes-Benz development programs have validated nickel-titanium mechanisms for production deployment. This actuator architecture is compressing the cost gap between electro-mechanical and purely mechanical alternatives.
EU type-approval frameworks for electromagnetic compatibility are tightening testing protocols for electro-mechanical deflectors deployed across European vehicle platforms. ECE R10 revision 6 imposes stricter emission limits on switched-mode power supplies driving actuator motors. German KBA certification delays have prompted suppliers to front-load compliance engineering in Stuttgart and Wolfsburg technical centers.
Fleet procurement contracts now bundle active aerodynamic hardware with performance guarantees tied to verified fuel economy improvements. Large commercial vehicle operators in North America negotiate outcome-based agreements where suppliers retain ownership of deflector assets. This model is compressing traditional component supplier margins while extending contract durations to seven-year terms.
Active Air Deflector Market Segmentation
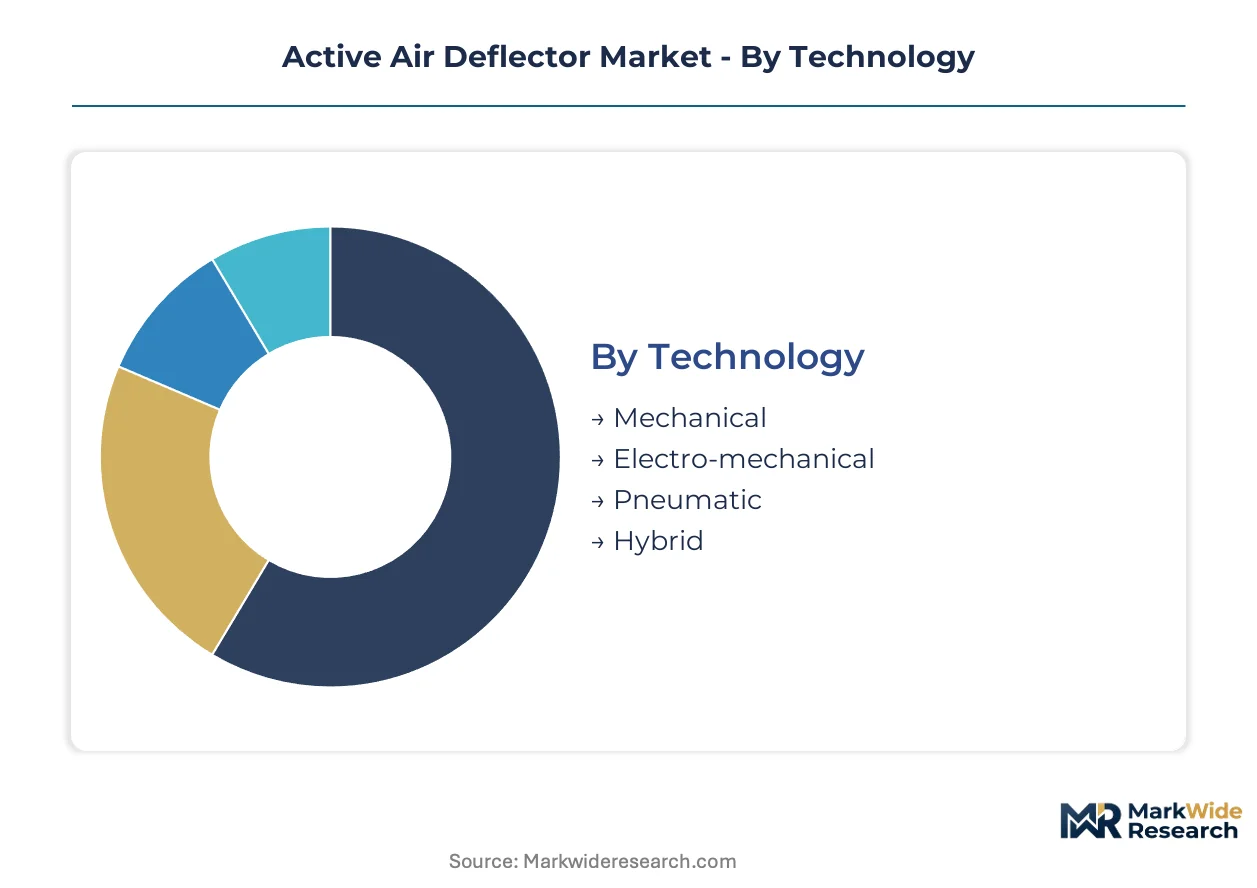
Active air deflector procurement splits across four structural dimensions that reshape supplier qualification requirements and certification pathways. Technology type determines whether ISO 26262 functional safety compliance or simpler mechanical validation applies. Application context governs whether ECE R10 electromagnetic testing, FAA airworthiness directives, or marine classification society rules frame supplier entry barriers.
Technology:
ISO 26262 ASIL ratings and ECE R10 electromagnetic compatibility protocols create divergent compliance burdens across technology tiers, with electro-mechanical variants facing the heaviest certification load.
- Electro-mechanical:Programmable actuator systems with real-time angle adjustment and sensor feedback loops. German premium OEMs in Stuttgart and Munich anchor procurement through integrated thermal management modules for battery-electric platforms. ECE R10 revision 6 testing extends European type-approval timelines.
- Mechanical:Passive spring-loaded or manually adjustable deflector architectures constructed from glass-reinforced nylon. Cost-sensitive commercial vehicle fleets in North America retain this technology where programmable control offers marginal fuel economy returns.
- Pneumatic:Compressed-air actuated systems deployed in heavy-duty applications requiring high force-to-weight ratios.
- Hybrid:Combined electro-pneumatic architectures emerging in aerospace retrofit programs demanding redundant actuation.
Leading the category by volume: Mechanical. Growing fastest: Electro-mechanical.
Application:
End-use context restructures pricing power, with aerospace retrofit contracts commanding margin premiums three to four times above automotive hardware.
- Automotive:Active grille shutters and hood deflectors integrating with powertrain thermal management. EPA greenhouse gas standards and NHTSA fuel economy regulations mandate aerodynamic efficiency improvements that OEM procurement thresholds enforce.
- Aerospace:Aftermarket aerodynamic optimization for regional jet fleets. Outcome-based contracts with performance guarantees tied to verified fuel economy improvements create margin pools above automotive benchmarks.
- HVAC systems:Building climate control applications optimizing intake airflow and thermal exchange efficiency.
- Marine:Vessel superstructure deflectors reducing wind resistance and stabilizing bridge aerodynamics.
Automotive generates the largest absolute revenue base. Aerospace climbs the fastest on margin expansion.
End User:
Contracting authority determines whether procurement flows through centralized fleet negotiations or fragmented individual transactions.
- Manufacturers:Tier 1 automotive suppliers and airframe OEMs procuring deflectors as integrated aerodynamic modules. Long-term supply agreements with seven-year contract durations are compressing traditional component margins.
- Service Providers:Maintenance, repair, and overhaul operations managing aftermarket replacement cycles.
- Consumers:Individual vehicle owners accessing deflector hardware through retail channels.
- Contractors:Fleet operators negotiating outcome-based agreements where suppliers retain asset ownership.
Manufacturers dominate procurement volume. Service providers are expanding fastest on aerospace retrofit demand.
Feature:
Performance specifications segment into functional priorities that align with distinct customer willingness-to-pay profiles.
- Adjustable Angle:Programmable positioning with real-time feedback enabling dynamic aerodynamic optimization. Sensor-fusion convergence with lidar and thermal imaging enables predictive adjustment in premium automotive platforms.
- Energy Efficiency:Drag coefficient reduction translating to measurable fuel economy gains. Fleet procurement contracts now bundle hardware with verified performance guarantees.
- Noise Reduction:Acoustic damping properties for cabin comfort and regulatory compliance.
- Durability:Thermal stability under hood temperatures exceeding 120°C and UV resistance for extended service life.
Adjustable angle leads feature prioritization. Energy efficiency is gaining share fastest on regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors electro-mechanical deflector engineering as German premium OEMs integrate programmable aerodynamic systems into battery-electric platforms. Detroit, Wolfsburg, and Shanghai form the dominant design-to-production triangle for active grille shutter deployment.
United States
NHTSA fuel economy regulations and EPA greenhouse gas standards mandate aerodynamic efficiency thresholds that OEM procurement contracts enforce. Detroit-based engineering centers coordinate thermal management integration for next-generation electric truck platforms. Michigan suppliers cluster around Tier 1 assembly operations serving Ford and General Motors.
Germany
KBA certification requirements under ECE R10 revision 6 extend type-approval timelines for electro-mechanical deflector systems. Stuttgart and Munich automakers anchor demand through integrated thermal management modules. Wolfsburg technical centers front-load compliance engineering to preempt regulatory delays.
China
MIIT new energy vehicle mandates accelerate domestic OEM adoption of active aerodynamic components. Shanghai and Shenzhen battery-electric platforms integrate intelligent grille shutter systems for thermal optimization. Yangtze River Delta suppliers scale glass-reinforced nylon composite production for cost-competitive electro-mechanical variants.
Japan
METI carbon neutrality roadmaps push automakers toward drag-reduction technologies across hybrid and electric lineups. Nagoya-area engineering clusters develop shape-memory alloy actuator prototypes for production validation. Toyota and Honda procurement specifications prioritize thermal stability under extended hood-temperature cycles.
South Korea
Ministry of Environment emission standards tighten aerodynamic compliance requirements for domestic vehicle exports. Seoul Capital Area suppliers coordinate with Hyundai-Kia thermal engineering teams on active deflector integration. Busan-Ulsan manufacturing corridors scale composite component output for regional OEM demand.
Active Air Deflector Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology certification and sensor-integration capabilities. The supplier base stratifies into three tiers: integrated module specialists with full aerodynamic system responsibility, component fabricators delivering actuator or composite subassemblies, and aftermarket distributors serving retrofit and replacement cycles. Dominant competitive moves include backward integration into composite materials and strategic partnerships for sensor-fusion development.
Within the integrated module tier, Robert Bosch GmbH and Magna International Inc. exemplify the sensor-control convergence archetype, while Plastic Omnium occupies a position reflecting materials-to-systems vertical scope. Lund International and WeatherTech represent aftermarket-focused positioning with retail channel density. Airodyne Industries Inc. and Climair UK Ltd sit within specialist fabricator categories serving regional OEM programs.
| Leading Market Players |
|---|
| Lund International |
| Airodyne Industries Inc. |
| Robert Bosch GmbH |
| Stampede Automotive Accessories |
| Climair UK Ltd |
| Magna International Inc. |
| Plastic Omnium |
| WeatherTech |
| Röchling SE & Co. KG |
| Others |
Value Chain & Pricing Dynamics
Rare earth magnet pricing volatility in Chinese processing facilities cascades through electro-mechanical deflector manufacturing, compressing margins on premium programmable systems while mechanical alternatives retain cost advantage in fleet procurement.
Pricing Analysis
Outcome-based contracts with verified fuel economy guarantees anchor value-based pricing in fleet procurement, separating premium electro-mechanical systems with sensor-fusion capabilities from commodity mechanical alternatives. Price differentiation rests on ISO 26262 ASIL certification tier and ECE R10 electromagnetic compliance grade. Cost compression in electro-mechanical tiers is intensifying because rare earth magnet supply instability feeds actuator motor pricing swings. Commercial vehicle fleets exhibit highest price sensitivity; German premium OEMs demonstrate lowest sensitivity due to integrated thermal module bundling.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Stuttgart and Munich automakers, while aftermarket distributors serve regional retrofit programs. Manufacturing concentrates in Germany, China, and the United States. Glass-reinforced nylon composites, rare earth magnets, and sensor assemblies constitute critical input dependencies. Single-source vulnerability in Chinese rare earth processing creates structural exposure. Distribution runs through Tier 1 module integrators with seven-year contract structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active air deflector manufacturing is becoming a vertical-integration race as suppliers pursue captive control over glass-reinforced nylon composite production to defend margin structures against raw material volatility.
For Market Incumbents: Deepen backward integration into thermoplastic composite manufacturing to offset rare earth magnet cost volatility. Secure long-term supply agreements with Yangtze River Delta polymer processors. Shape-memory alloy actuator R&D represents the priority capability investment against electro-mechanical substitution risk. For New Entrants and Emerging Players: Begin with aerospace retrofit programs where outcome-based contracts command margin premiums three to four times above automotive benchmarks. Regional jet fleet operators present the most penetrable buyer segment. Sensor-fusion integration partnerships with lidar developers offer the clearest go-to-market differentiation. For Investors and Strategic Acquirers: KBA certification delays exceeding six months for ECE R10 revision 6 compliance is the leading indicator that regulatory engineering capabilities are becoming the scarcest asset in supplier valuation. Targets with Stuttgart or Wolfsburg technical center presence and established electromagnetic testing protocols offer strongest acquisition logic. Shape-memory alloy production validation by BMW or Mercedes-Benz engineering programs signals technology inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Composite Materials | Captive supply of glass-reinforced nylon insulates margins from polymer price volatility in Yangtze River Delta. |
| Sensor-Fusion Control System Development | Lidar and thermal imaging integration enables predictive angle adjustment for premium OEM procurement. |
| ECE R10 Revision 6 Compliance Engineering | Front-loaded Stuttgart technical center investment preempts KBA certification timeline extensions. |
| Shape-Memory Alloy Actuator Scale-Up | Nickel-titanium mechanisms validated by BMW and Mercedes-Benz eliminate motor assemblies and reduce part counts. |
| Outcome-Based Fleet Contracting | Performance guarantees tied to verified fuel economy improvements extend contract durations to seven-year terms. |
Study Parameters
Trade databases, automotive production registries, and electromagnetic compatibility testing records formed the secondary backbone, supplemented by primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and KBA certification specialists. Bottom-up volume estimates triangulated against top-down OEM procurement budget analysis across the analysis window.
Historical trendline analysis of active grille shutter content per vehicle informed the projection framework across vehicle class, propulsion architecture, and regional production cluster dimensions. CAGRs were derived from segment-level growth rate reconciliation. Battery-electric vehicle thermal architecture duty cycles and hybrid dual-mode aerodynamic strategies served as industry-specific forecast inputs throughout the modeling period.
Underlying measurement precision varies by segment; electro-mechanical technology and aerospace application data carry tighter precision than mechanical alternatives and HVAC end-uses. Forecasts reflect assumptions about EPA regulatory trajectory and EU Green Deal procurement incentive durability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Commercial Aircraft Aerostructures Market
Aircraft
Aircraft Autopilot System Market
Aircraft
Australia Aviation Market
Aircraft
Commercial Aircraft Market
Aircraft
Aircraft Seals Market
Aircraft
Europe Aircraft Engines Market
Aircraft
Maritime Patrol Aircraft Market
Aircraft
Asia-Pacific Freighter Aircraft Market
Aircraft
Attack Helicopter Market
Aircraft
Asia-Pacific Attack Helicopter Market
Aircraft
Military Multirole Aircraft Market
Aircraft
Evtol (Electric Vertical Takeoff and Landing) Airplane Market
Aircraft
Search and Rescue Helicopter Market
Aircraft
Aircraft Landing Gear Market
Aircraft
Aircraft Wheels Brakes Market
Aircraft
Aircraft Manufacturing Market