
 Global Advanced Marine Power Supply Market | 2026-2036
Global Advanced Marine Power Supply Market Size, Share, and Industry Trends Forecast 2026-2036
Global Advanced Marine Power Supply Market Intelligence
DNV-ST-0038 certification for maritime battery safety is bifurcating the competitive landscape between qualified and non-qualified suppliers. ABB Ltd leverages its integrated vessel electrification portfolio to dominate cruise and ferry segments. Wärtsilä anchors its position through captive control over fuel cell integration engineering. Schneider Electric SE differentiates via shore-to-ship power compatibility and digital energy management platforms.
Advanced marine power supply denotes engineered electricity generation, conversion, and storage systems purpose-built for saltwater environments, typically operating at 400-690 VAC with IP56 minimum ingress protection and active thermal management to mitigate corrosion-induced degradation. These systems deliver propulsion, auxiliary load, and dynamic positioning power for vessels and offshore structures. Battery Systems and Fuel Cells command the deepest margin pools as electrification displaces conventional diesel-generator architectures, while Power Converters represent the fastest-growing category as vessel architectures shift toward DC distribution buses. Lithium-Ion technology leads installed base, though Solid Oxide fuel cells are gaining traction in long-range commercial shipping applications.
FDA marine equipment guidelines, EPA vessel emissions standards, and IEC 60092 electrical installation codes collectively shape product qualification timelines and market access thresholds for suppliers. The EU Green Deal's FuelEU Maritime initiative tightens carbon intensity benchmarks for vessels calling at European ports. Stakeholders must monitor how classification society rule evolutions for hydrogen storage and ammonia fuel compatibility redirect R&D allocation across the supplier base.
Market Dynamics
Vessel electrification is compressing the conventional diesel-generator supply chain as offshore platform operators and ferry fleets demand integrated battery-fuel cell hybrid architectures with DC distribution buses.
Growth Catalysts
- FuelEU Maritime:The EU Green Deal's carbon intensity benchmarks for vessels calling at European ports are forcing technology substitution across coastal shipping fleets.
- DNV-ST-0038:Maritime battery safety certification is creating qualified supplier preference among Norwegian offshore operators procuring dynamic positioning systems.
- Solid Oxide fuel cells:Long-range commercial shipping applications in Japan's coastal lanes are accelerating adoption of high-temperature fuel cell architectures for auxiliary power.
Market Restraints
- Lithium supply concentration:Cathode material dependency on limited geographies creates input cost volatility for battery system manufacturers.
- Hydrogen storage certification:Classification society rule uncertainty around cryogenic and compressed hydrogen bunkering is extending product qualification timelines.
- Shore power infrastructure gaps:Inadequate high-voltage connection capacity at major port clusters limits shore-to-ship power utilization rates.
Strategic Opportunities
- Ammonia fuel compatibility:Early mover engineering capability for ammonia-compatible fuel cell systems opens positioning in zero-carbon deep-sea shipping.
- Digital energy management:Vessel operators in Norway's offshore energy corridor are procuring platform-agnostic power optimization software.
- Japan coastal retrofit:Aging short-sea shipping fleets present white space for modular battery container swap systems.
Industry Challenges
- Marine electrical systems integration:Shortage of naval architects with DC microgrid design expertise is compressing project execution timelines.
- Multi-technology certification:Parallel IEC 60092 electrical codes and EPA vessel emissions standards create overlapping compliance documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Advanced Marine Power Supply Market |
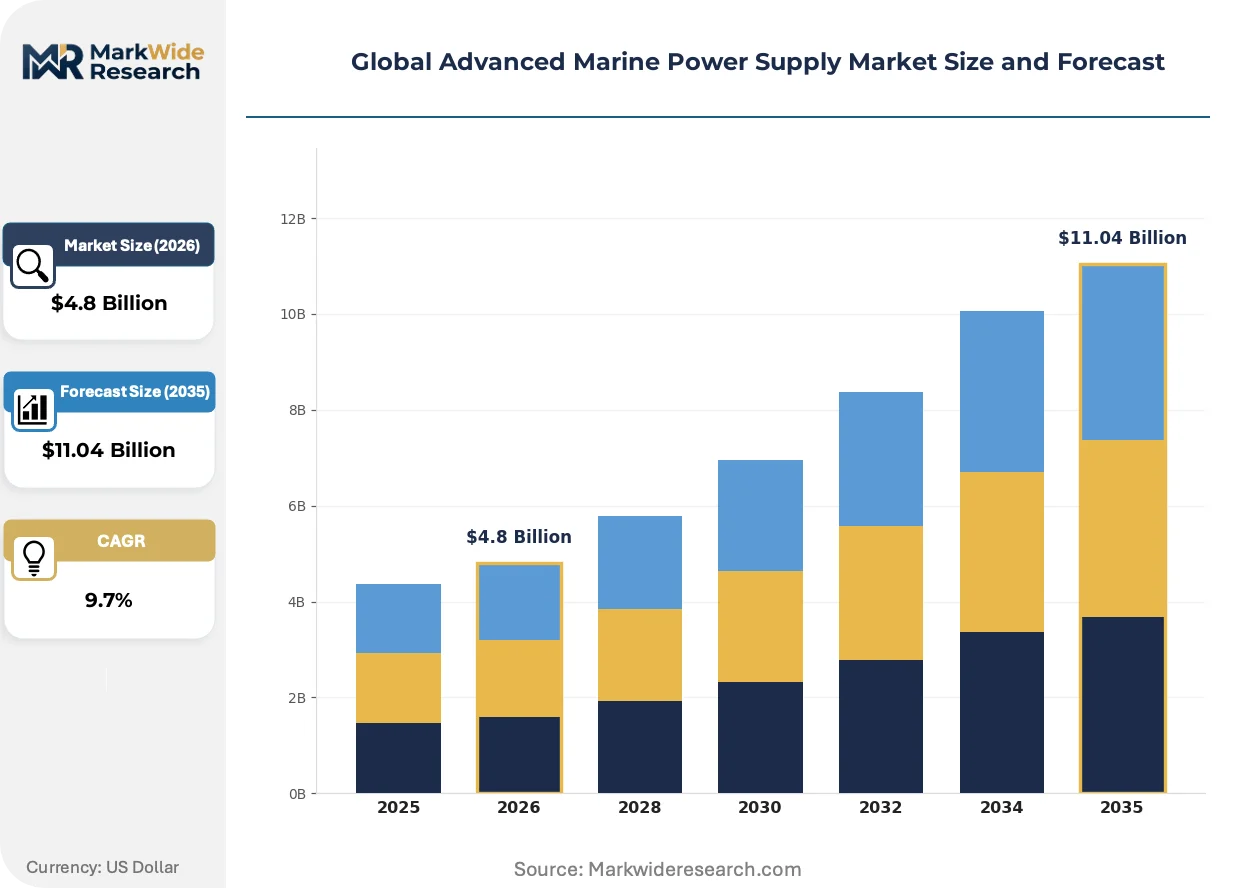
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Systems, Fuel Cells, Solar Panels, Power Converters, Marine Generators Technology: Lithium-Ion, Lead-Acid, Solid Oxide, Proton Exchange Membrane, Zinc-Air Application: Commercial Vessels, Military Ships, Offshore Platforms, Research Submersibles End User: Shipbuilders, Equipment Integrators, Marine OEMs, Vessel Operators |
| Companies Covered | ABB Ltd, Schneider Electric SE, Emerson Electric Company, Eaton Corporation Plc, Wärtsilä, Rolls-Royce, Powerbox International AB, ENAG, Marine Electric Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Advanced Marine Power Supply Market Strategic Shifts & Innovations
DC distribution bus architectures are reconfiguring how marine power is generated, stored, and consumed across vessel classes. Three concurrent developments are compressing legacy AC infrastructure investment cycles.
Solid-state DC circuit breakers with active arc suppression are displacing conventional air-break contactors in 690V marine switchboards. Offshore supply vessel operators in the North Sea are specifying these devices for fault-current limitation in battery-hybrid propulsion systems. The technology is displacing electromechanical protection schemes that cannot clear faults fast enough to prevent thermal runaway in lithium-ion installations.
EPA vessel emissions standards for Category 3 marine engines are tightening particulate matter and nitrogen oxide thresholds for ships operating in US coastal waters. Engine manufacturers are responding with exhaust after-treatment systems that increase auxiliary electrical load requirements. Battery system suppliers are capturing this incremental demand with hybrid integration packages for harbor craft and tugs.
Integrated power-as-a-service contracting is replacing capital-heavy equipment purchases among European ferry operators facing FuelEU Maritime compliance deadlines. Vessel owners in the Baltic and Mediterranean are leasing battery-fuel cell systems with guaranteed availability clauses. Norway's Color Line and Germany's ferry consortia represent the most advanced procurement model adoption.
Global Advanced Marine Power Supply Market Segmentation
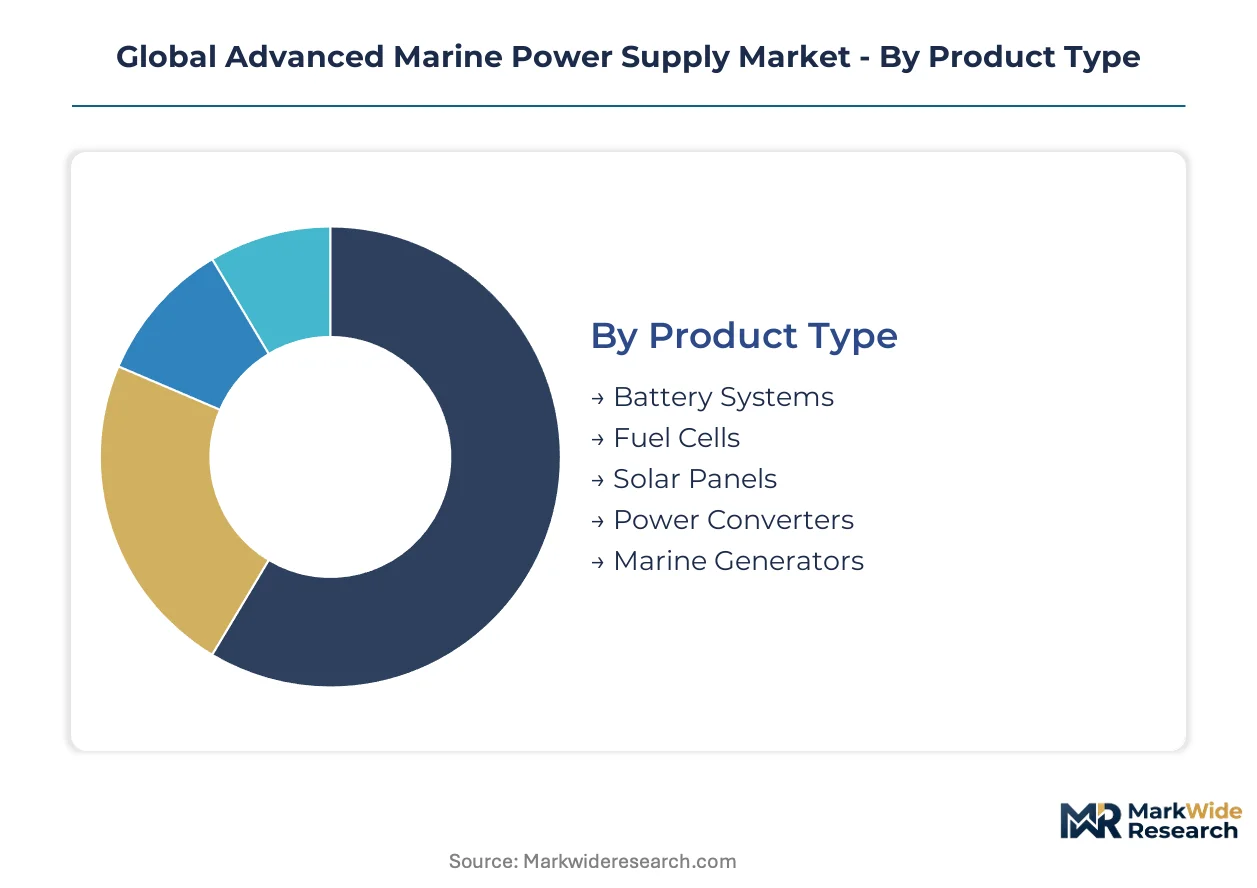
Segmentation in marine power supply reveals how margin pools concentrate in electrification hardware versus conventional generation. Procurement patterns diverge sharply between newbuild yards retrofitting legacy fleets and offshore operators specifying integrated hybrid architectures.
Product Type:
Margin pools concentrate in energy storage and conversion hardware as diesel-generator architectures lose share to battery-fuel cell hybrids.
- Battery Systems:Lithium-ion racks with active thermal management and IP56 ingress protection dominate ferry and offshore supply vessel specifications. Norwegian platform operators in the North Sea corridor are procuring these for dynamic positioning redundancy under DNV-ST-0038 certification requirements.
- Fuel Cells:Solid oxide and proton exchange membrane stacks deliver auxiliary and propulsion power for long-range commercial shipping. Japan's coastal shipping lanes are accelerating adoption of high-temperature architectures as METI pushes hydrogen bunkering infrastructure.
- Solar Panels:Marine-grade photovoltaic arrays with salt-mist corrosion resistance serve auxiliary loads on cruise vessels and yachts.
- Power Converters:AC-DC and DC-DC units enable DC distribution bus architectures across vessel classes.
- Marine Generators:Conventional diesel-electric sets retain share in military and ice-class applications requiring redundant prime movers.
Battery Systems hold installed capacity. Fuel Cells are rotating up the share rankings.
Technology:
Technology selection tracks vessel duty cycles and regulatory exposure, with electrification-ready chemistries commanding premium pricing over legacy alternatives.
- Lithium-Ion:Nickel-manganese-cobalt and lithium-iron-phosphate cells dominate maritime battery installations with energy densities exceeding 200 Wh/kg. EU Green Deal FuelEU Maritime deadlines are forcing coastal fleet operators toward this chemistry for harbor maneuvering and shore power buffering.
- Solid Oxide:High-temperature ceramic electrolyte fuel cells operate at 600-1000°C for auxiliary power in long-range shipping. Japanese deep-sea operators are piloting these for ammonia fuel compatibility in zero-carbon route planning.
- Lead-Acid:Flooded and valve-regulated designs persist in cost-sensitive harbor craft with limited cycling requirements.
- Proton Exchange Membrane:Low-temperature hydrogen fuel cells serve short-range ferry applications with rapid cold-start capability.
- Zinc-Air:Metal-air batteries with aqueous electrolytes are emerging for stationary offshore platform storage with lower fire risk profiles.
Lithium-Ion dominates vessel electrification. Solid Oxide is gaining share in deep-sea auxiliary power.
Application:
Application segmentation tracks regulatory intensity and vessel utilization patterns, with coastal fleets facing tighter emissions deadlines than military or research assets.
- Commercial Vessels:Container ships, tankers, and bulk carriers constitute the deepest addressable market for fuel cell retrofits and battery-hybrid newbuilds. Baltic and Mediterranean ferry operators are leasing power-as-a-service packages to meet FuelEU Maritime carbon intensity benchmarks.
- Offshore Platforms:Drillships, production vessels, and accommodation units require dynamic positioning power with redundancy mandates. Norway's offshore energy corridor is procuring integrated battery-fuel cell systems for station-keeping reliability.
- Military Ships:Naval combatants and auxiliary vessels prioritize acoustic signature reduction and battle damage resilience over emissions compliance.
- Research Submersibles:Manned and unmanned underwater vehicles demand pressure-compensated power systems for deep-ocean operations.
Commercial Vessels carry the largest order backlog. Offshore Platforms are expanding fastest on electrification mandates.
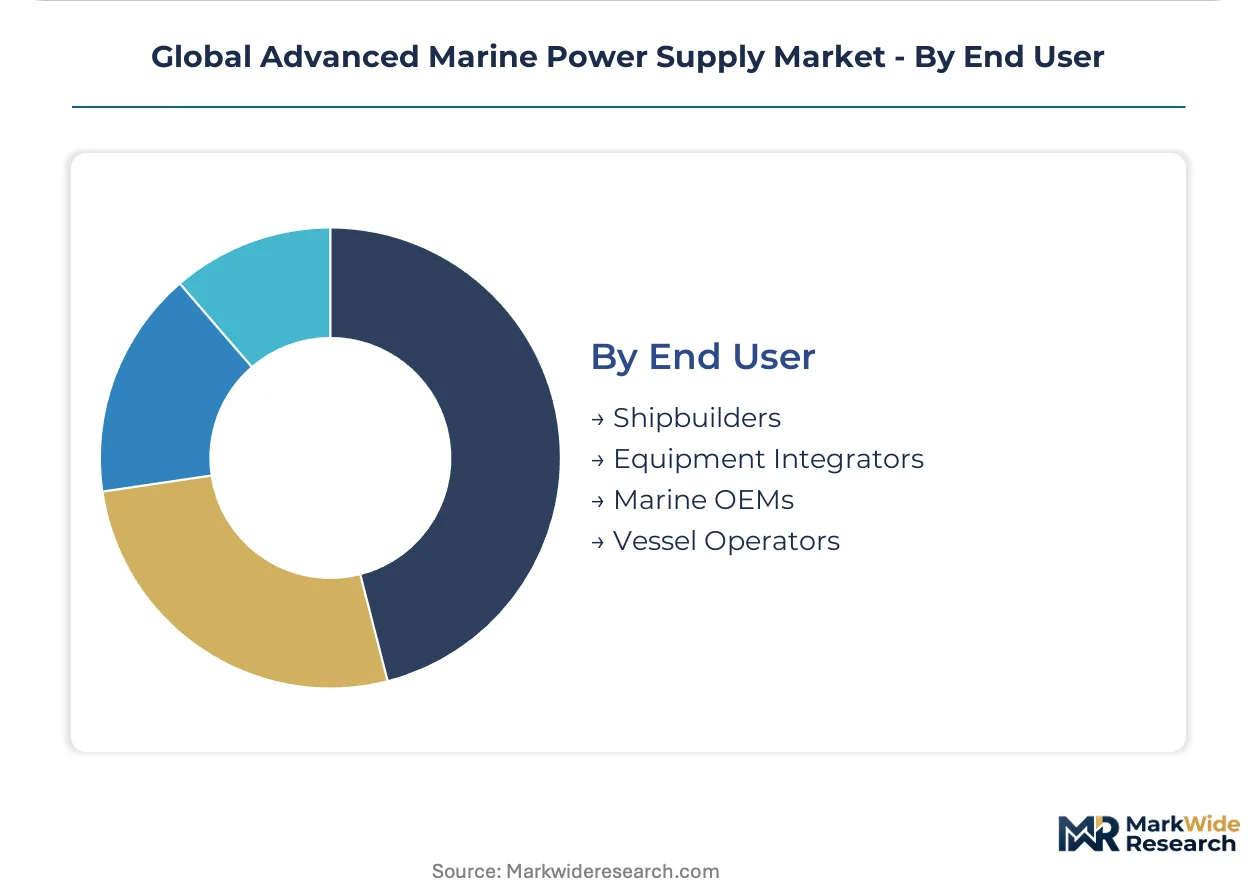
End User:
End user segmentation reveals procurement authority fragmentation between vessel owners, builders, and system integrators with divergent technical risk appetites.
- Shipbuilders:Korean and Chinese newbuild yards are specifying integrated power architectures early in design phases to secure classification society approval. These yards face compressed delivery timelines as owners front-load orders ahead of regulatory deadlines.
- Vessel Operators:European ferry consortia and Japanese coastal shipping lines are driving outcome-based contracting with guaranteed availability clauses. Norway's Color Line exemplifies this shift from capital purchase to leased power system models.
- Equipment Integrators:Specialist firms bundle batteries, fuel cells, and power electronics into turn-key hybrid packages for retrofit installations.
- Marine OEMs:Engine and propulsion manufacturers are backward integrating into electrification hardware to defend position in shrinking diesel markets.
Shipbuilders control newbuild specification. Vessel Operators are rotating up the influence rankings through leasing models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's FuelEU Maritime initiative is redirecting procurement budgets toward electrification hardware across European coastal fleets. Norway's offshore corridor and Japan's coastal shipping lanes are establishing parallel demand centers for battery-fuel cell hybrid systems.
Norway
Offshore platform operators in the North Sea energy corridor are procuring integrated battery systems for dynamic positioning redundancy. DNV-ST-0038 maritime battery safety certification is creating qualified supplier preference among Norwegian drillship and production vessel owners. Stavanger and Bergen anchor this procurement activity, with Color Line ferry consortia pioneering power-as-a-service leasing models.
Japan
METI hydrogen bunkering infrastructure investments are accelerating solid oxide fuel cell adoption for coastal shipping auxiliary power. The country's short-sea shipping lanes face aging fleet replacement deadlines that favor modular battery container swap systems. Osaka-Kobe and Nagoya port clusters are piloting high-temperature fuel cell architectures for zero-carbon route planning.
Germany
Baltic and Mediterranean ferry operators are leasing battery-fuel cell hybrid packages to meet FuelEU Maritime carbon intensity benchmarks. German yards are specifying integrated power architectures early in design phases to secure classification society approval. Hamburg and Bremerhaven control newbuild specification authority for European container and cruise segments.
United States
EPA vessel emissions standards for Category 3 marine engines are tightening particulate matter thresholds for ships operating in coastal waters. Harbor craft and tug operators are procuring hybrid integration packages to manage increased auxiliary electrical loads from exhaust after-treatment systems. Gulf Coast and Pacific Northwest port clusters represent the deepest retrofit addressable markets.
South Korea
Korean newbuild yards are front-loading orders ahead of regulatory deadlines for integrated power architectures with DC distribution buses. Shipbuilders face compressed delivery timelines as vessel owners accelerate electrification specifications. Ulsan and Geoje shipbuilding complexes dominate global order backlogs for battery-hybrid container vessels and LNG carriers.
Global Advanced Marine Power Supply Market Key Industry Players
Player mix skews toward diversified industrial electrification specialists with captive marine engineering capabilities. The competitive structure concentrates around integrated system providers capable of certifying complete power architectures under IEC 60092 and DNV-ST-0038 simultaneously. Two strategic archetypes dominate: full-stack vessel electrification platforms and fuel cell integration engineering specialists. Capacity expansion in battery system manufacturing and strategic partnerships for shore-to-ship power compatibility represent the dominant competitive moves.
Among European-based integrated power specialists, ABB Ltd, Schneider Electric SE, and Wärtsilä occupy distinct positioning vectors. ABB Ltd exemplifies the full-stack vessel electrification archetype through its integrated portfolio spanning generation, conversion, and distribution hardware. Schneider Electric SE represents the digital energy management tier with shore-to-ship power compatibility specialization. Wärtsilä anchors the fuel cell integration engineering segment with captive control over hybrid system architecture design. These three firms collectively illustrate how qualification barriers and certification complexity are concentrating competitive position around vertically integrated engineering capabilities rather than component-level supply.
| Leading Market Players |
|---|
| ABB Ltd |
| Schneider Electric SE |
| Emerson Electric Company |
| Eaton Corporation Plc |
| Wärtsilä |
| Rolls-Royce |
| Powerbox International AB |
| ENAG |
| Marine Electric Systems Inc. |
| Others |
Cost & Logistics Intelligence
Lithium-ion cathode chemistry substitution for conventional diesel-generator architectures is redrawing raw material procurement geography while compressing margin structures across battery system tiers. Norwegian offshore operators and Japanese coastal fleets now face divergent input cost exposures as nickel-manganese-cobalt and lithium-iron-phosphate supply chains concentrate in distinct production corridors.
Pricing Analysis
Certification level under DNV-ST-0038 and IEC 60092 creates the primary spread between qualified and non-qualified supplier tiers. Three-tier pricing structure across certified premium, pending-standard, and uncertified economy levels dominates battery system procurement. Cost compression in standard-tier power converters is intensifying because Korean and Chinese newbuild yards are consolidating purchase volumes under framework agreements. Harbor craft operators exhibit the highest price sensitivity due to limited cycling requirements, while Norway's offshore platform operators prioritize availability guarantees over unit economics.
Supply Chain Analysis
Strategic stockpiling of lithium carbonate and cathode precursors prevails among battery system manufacturers facing FuelEU Maritime compliance deadlines. Supply concentrates in China for cell manufacturing, South Korea for integrated power electronics, and Japan for solid oxide fuel cell ceramics. Raw material dependencies span Australian spodumene, Chilean lithium brine, and Indonesian nickel laterite. Single-source vulnerability in high-purity electrolyte salts represents the dominant structural risk. Distribution runs through equipment integrators bundling turn-key hybrid packages for retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
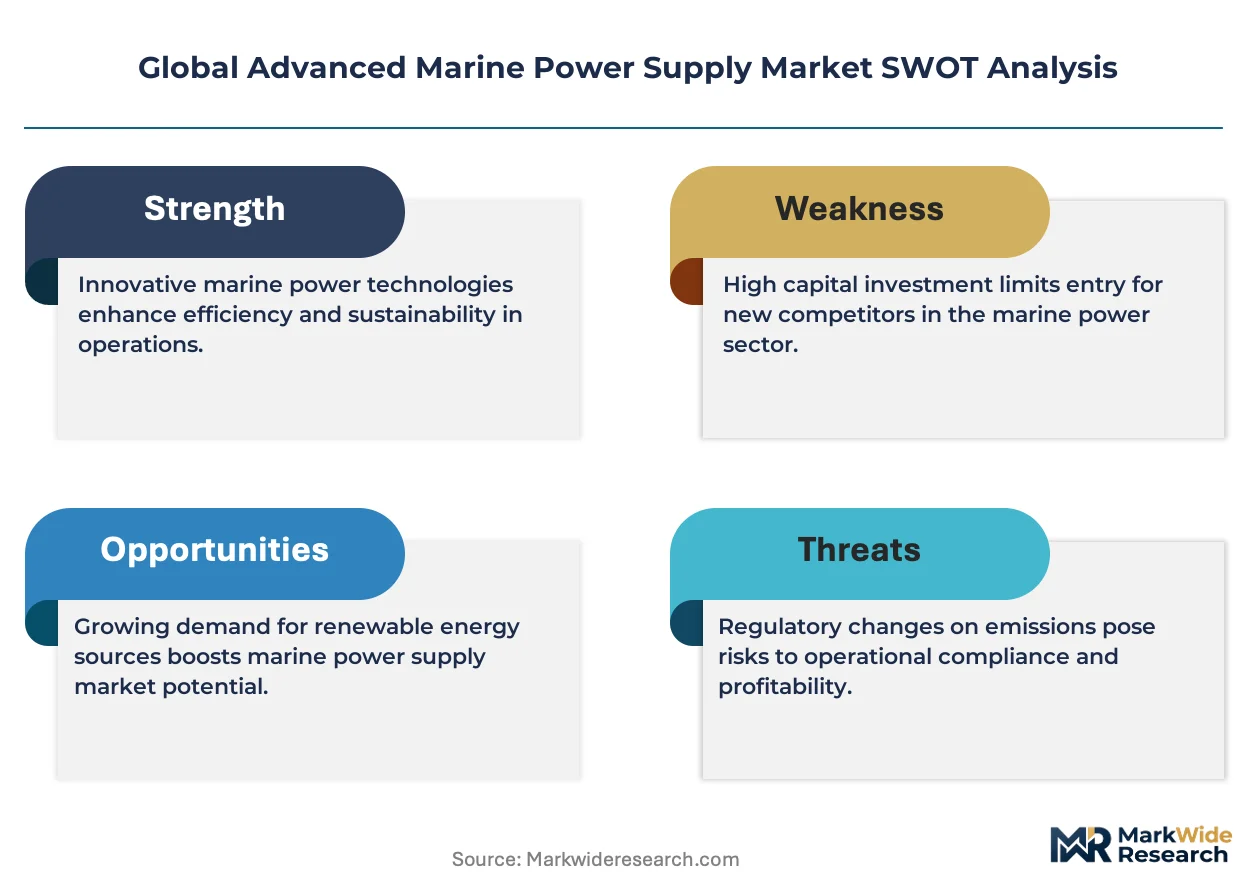
This market functions as a regulatory-moat story where DNV-ST-0038 certification entrenchment creates switching costs that lock vessel operators into qualified supplier relationships. The moat deepens as parallel IEC 60092 and EPA compliance documentation burdens compound qualification timelines.
For Market Incumbents: Fortify captive control over fuel cell integration engineering to defend against emerging pure-play battery specialists. Expand DNV-ST-0038 certification coverage into ammonia-compatible architectures before classification society rules crystallize. Capacity addition in South Korea's shipbuilding corridor anchors long-term yard relationships. Certification investment in solid-state DC circuit breakers preserves technical differentiation in 690V marine switchboards. For New Entrants and Emerging Players: Lead with modular battery container swap systems targeting Japan's aging short-sea shipping fleet replacement cycle. Japan's coastal retrofit segment offers the most penetrable white space given METI hydrogen infrastructure timelines and vessel age profiles. Platform-agnostic power optimization software provides a go-to-market angle that sidesteps hardware qualification barriers while capturing Norway's offshore energy corridor demand for digital energy management. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fuel cell engineering specialists holding captive hybrid system architecture capabilities. The five-to-ten year viability window hinges on FuelEU Maritime enforcement stringency and ammonia fuel compatibility standardization. Acquisition targets with parallel IEC 60092 and DNV-ST-0038 qualification pathways command scarcity premia. The signal to watch is classification society rule finalization for hydrogen storage and ammonia bunkering, which will redirect R&D allocation across the supplier base.| Strategic Initiative | Industry Significance |
|---|---|
| DNV-ST-0038 Certification Expansion | Qualification barriers bifurcate supplier tiers between certified and non-certified competitors. |
| Ammonia Fuel Cell Engineering | Early mover capability opens positioning in zero-carbon deep-sea shipping under EU Green Deal. |
| Power-as-a-Service Contracting | Leasing models with guaranteed availability clauses capture European ferry compliance budgets. |
| DC Distribution Bus Integration | AC-DC and DC-DC converter demand accelerates as vessel architectures shift from legacy AC infrastructure. |
| Shore-to-Ship Power Compatibility | Digital energy management platforms differentiate suppliers at ports with high-voltage connection capacity. |
Research Approach
Findings reconcile primary fieldwork against secondary review of classification society rule filings, customs trade data for marine electrical equipment, and SEC disclosures from diversified industrial electrification specialists. Primary interviews spanned naval architects with DC microgrid expertise, offshore platform procurement managers, ferry fleet technical directors, and marine equipment integrators. Secondary validation drew from DNV rule development notices, IEC 60092 amendment drafts, EPA vessel emissions enforcement data, and EU Green Deal implementation tracking. Bottom-up vessel order book analysis triangulates against top-down electrification spend projections from shipowner capital allocation disclosures.
Segmentation dimensions modeled span product type, technology chemistry, vessel application, and end-user procurement authority across the projection horizon. The analytical framework derives CAGRs from battery system capacity additions, fuel cell retrofit penetration curves, and power converter shipment volumes. Industry-specific forecast inputs include FuelEU Maritime carbon intensity benchmark phase-in schedules and METI hydrogen bunkering infrastructure deployment timelines. Regional splits weight order backlog concentration at Korean and Chinese newbuild yards against European retrofit demand.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement or classification society rule stability would require recalibration. Forecasts reflect assumptions on lithium supply expansion, cathode material cost trajectories, and hydrogen storage certification timelines. Revision becomes warranted when DNV-ST-0038 rule amendments or FuelEU Maritime benchmark stringency crosses thresholds that redirect vessel owner procurement priorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Middle-East and Africa Power Market
Power
Controllable Shunt Reactor for UHV Market
Power
Modified Sine Wave Home Inverters Market
Power
Global Power Line Communication (PLC) Systems Market
Power
High Voltage DC Power System Market
Power
Asia-Pacific Microturbine Market
Power
Power Rental Market
Power
Critical Power Market
Power
Distribution Feeder Protection System Market
Power
Asia-Pacific Turbomachinery Control Systems Market
Power
Statcom Market
Power
Combined Heat and Power (CHP) Systems Market
Power
North America Microturbine Market
Power
North America Micro CHP Market
Power
Gas Freeing Fan Market
Power
Colombia Power Market