
 Hydrogen Gas Generator Market | 2026-2036
Hydrogen Gas Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Gas Generator Market Insights
Chinese electrolyzer manufacturing is expanding faster than any other producer category, with domestic factories scaling alkaline and PEM lines for export markets. Air Liquide leverages its industrial gas infrastructure to anchor hydrogen supply contracts across European chemical corridors. Linde sustains leadership in large-scale steam methane reforming while competing in electrolyzer partnerships. Nel ASA specializes in containerized PEM systems for distributed refueling stations.
A hydrogen gas generator is an apparatus that produces hydrogen gas through electrolysis of water or reformation of hydrocarbon feedstocks, typically delivering output pressures from 10 to 30 bar and purity levels exceeding 99.999% for semiconductor and fuel cell applications. Its primary industrial purpose is to provide on-site, point-of-use hydrogen supply that eliminates transportation costs and storage hazards associated with compressed gas delivery. Electrolyzers now capture the fastest-growing margin pool as renewable-powered installations displace gray hydrogen in European chemical production. Stationary generators still dominate installed base value due to decades of refinery and ammonia plant reliance on centralized reforming units. Fuel cell systems for transportation applications are gaining traction where hydrogen mobility corridors in Germany, Japan, and California require reliable generation backup.
The EU Green Deal and F-Gas Regulation impose tightening carbon intensity thresholds on industrial hydrogen, forcing generators to document renewable sourcing or face exclusion from public procurement. EPA rules under the US Inflation Reduction Act condition clean hydrogen tax credits on lifecycle emissions verification, reshaping technology selection for domestic projects. China's dual carbon goals and MIIT efficiency standards are accelerating substitution of coal-based hydrogen in steel and ammonia plants. Stakeholders must monitor how certification schemes for renewable hydrogen proliferate across jurisdictions and determine which technology platforms qualify for premium pricing in each regulatory zone.
Market Dynamics
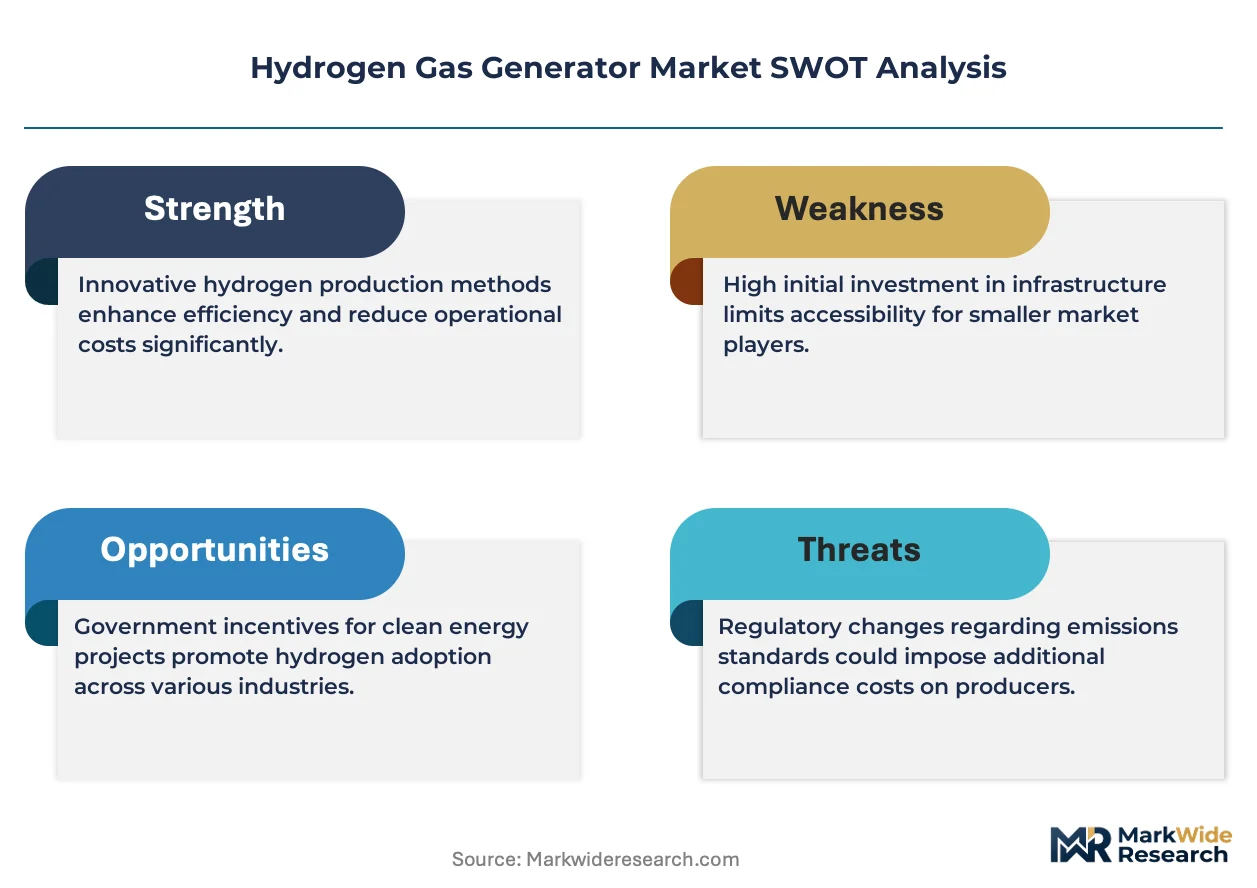
Electrolyzer technology maturation is compressing the cost gap between renewable-powered and fossil-derived hydrogen, forcing incumbent steam methane reforming operators to accelerate efficiency upgrades or risk volume erosion in refinery and ammonia plant contracts.
Growth Catalysts
- EU Green Deal carbon intensity mandates:The framework's tightening emissions thresholds are disqualifying gray hydrogen from public procurement in German chemical corridors, redirecting capital toward electrolyzer installations.
- On-site refinery hydrogen demand:US Gulf Coast refineries are deploying proton exchange membrane units to eliminate compressed gas delivery costs and storage liability exposure.
- Alkaline electrolyzer manufacturing scale-up:Chinese factory expansion is driving module cost reductions that enable export penetration into European and Southeast Asian industrial clusters.
Market Restraints
- Platinum group metal supply concentration:PEM stack production depends on South African and Russian palladium and iridium sourcing, exposing manufacturers to geopolitical disruption and price volatility.
- Grid interconnection queues:Renewable-powered electrolyzer projects in Germany and Spain face 18-36 month utility connection delays that compress project returns.
- Compressed natural gas substitution:Industrial thermal applications in the US Midwest and Gulf Coast retain CNG retrofit economics that undercut green hydrogen cost parity timelines.
Strategic Opportunities
- US Inflation Reduction Act clean hydrogen tax credits:The EPA's lifecycle emissions verification framework creates a $3/kg production incentive that reshapes technology selection for domestic project developers.
- Steel sector coal hydrogen displacement:China's MIIT efficiency standards and dual carbon goals are mandating electrolyzer procurement for blast furnace injection trials in Hebei and Jiangsu provinces.
- Containerized PEM system channel expansion:Distributed refueling station architectures in California and Japan are creating aftermarket service and remote monitoring revenue pools.
Industry Challenges
- Electrolyzer stack degradation modeling:The absence of standardized 10-year performance warranties complicates project finance underwriting and raises cost of capital for independent power producer developers.
- Renewable hydrogen certification interoperability:Competing schemes in the EU, Japan, and California create compliance fragmentation that delays offtake contracting for cross-border supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Gas Generator Market |
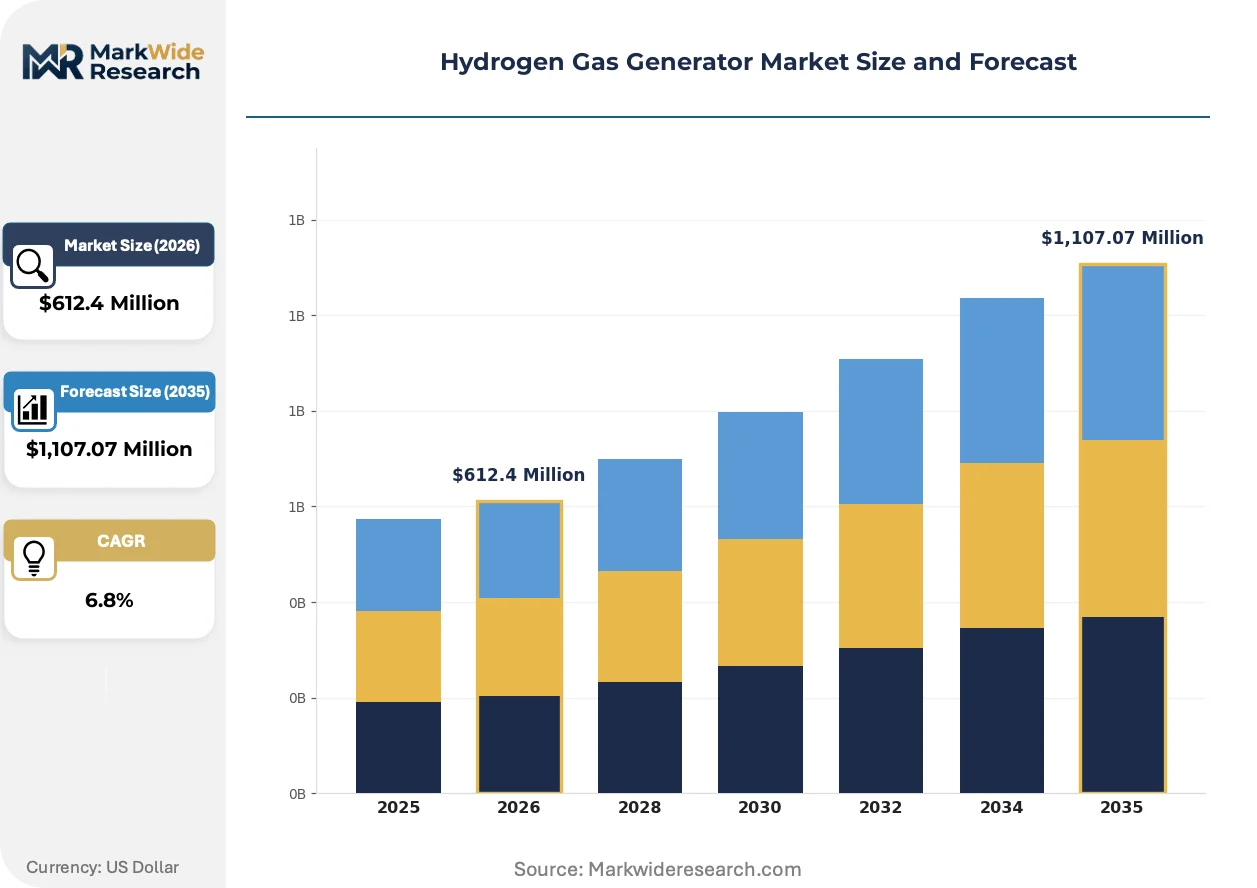
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary Generators, Portable Generators, Fuel Cell Systems, Electrolyzers End User: Energy Sector, Automotive Industry, Steel Manufacturing, Chemical Production Technology: Proton Exchange Membrane, Alkaline Electrolysis, High-Temperature Electrolysis, Solid Oxide Application: Power Generation, Transportation, Industrial Processes, Heating |
| Companies Covered | Air Liquide, Linde, Air Products and Chemicals, Nel ASA, Plug Power, Cummins, ITM Power, McPhy Energy, Siemens Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Gas Generator Market Trends and Innovations
Technology convergence between solid oxide electrolysis and industrial heat integration is redefining efficiency benchmarks, while regulatory pressure on lifecycle emissions is forcing documentation infrastructure investments across supply chains.
Solid oxide electrolysis cells are integrating waste heat recovery from adjacent industrial processes to achieve electrical efficiency above 85% LHV, a threshold that chemical producers in the Netherlands and Norway are targeting for ammonia and methanol retrofit projects. This thermal coupling architecture is compressing the operational expenditure gap with incumbent steam methane reforming in baseload hydrogen applications.
The EU F-Gas Regulation's phasedown of fluorinated greenhouse gases is forcing manufacturers to redesign PEM stack cooling systems and membrane humidification circuits, with compliance deadlines concentrating engineering resources on fluorine-free alternatives by 2027. German and French industrial gas suppliers are accelerating pilot deployments to validate membrane durability under the new constraints.
Refinery procurement teams are consolidating hydrogen supply contracts under long-term power purchase agreements tied to renewable generation, displacing spot-market gray hydrogen procurement in the US Gulf Coast and Rotterdam-Antwerp chemical clusters. This contract restructuring is compressing supplier margins while transferring volume risk to electrolyzer operators.
Hydrogen Gas Generator Market Segmentation
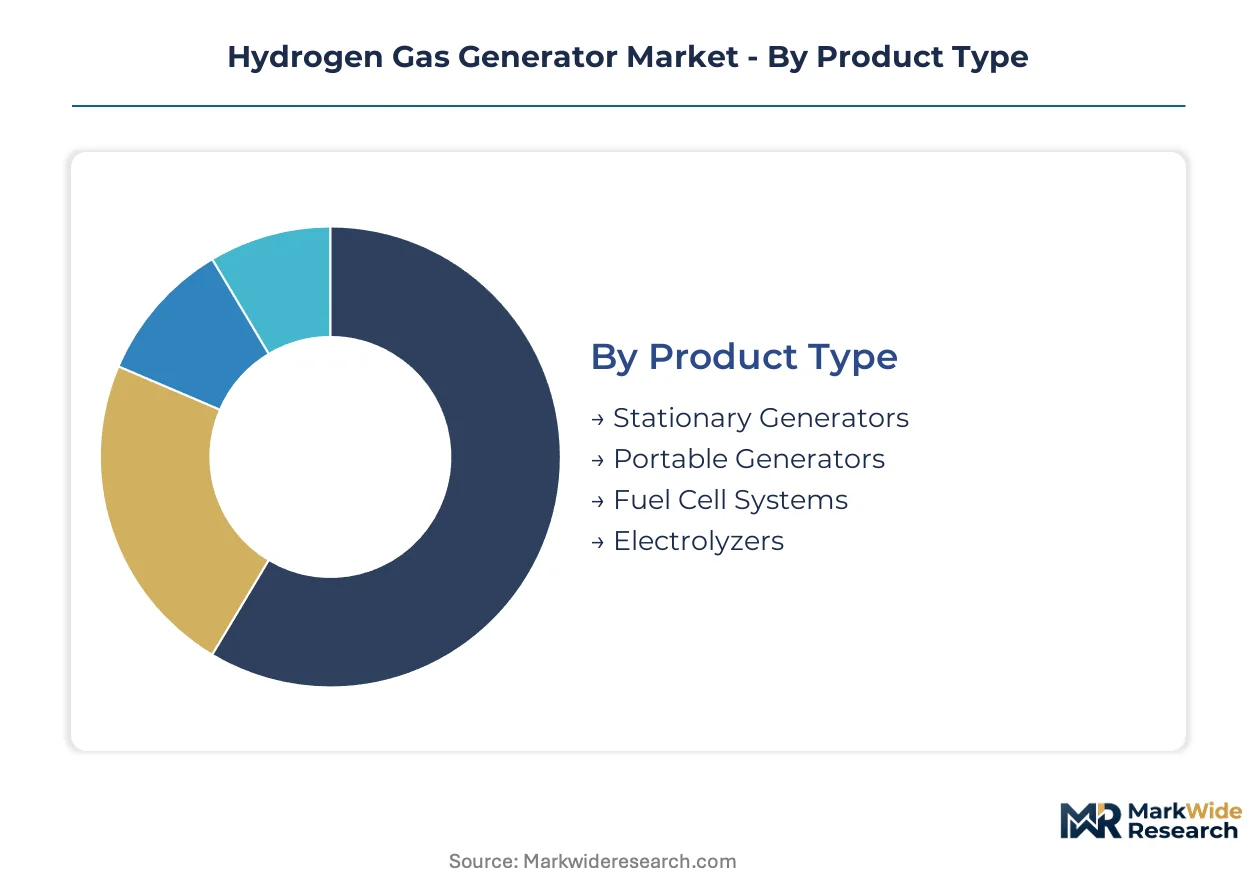
Segmentation reveals how hydrogen generation technologies align with distinct operational requirements across stationary industrial baseload, distributed mobility infrastructure, and emerging thermal applications. Each category exposes different margin structures, capital intensity thresholds, and regulatory exposure profiles that shape vendor strategy and customer procurement decisions.
Product Type:
Standalone units dominate refinery and chemical plant deployments where centralized hydrogen supply eliminates logistics complexity, while embedded systems integrate into vehicle platforms and building energy architectures.
- Stationary Generators:Large-capacity reforming and electrolysis systems permanently installed at industrial facilities, typically exceeding 1 MW output. Demand concentrates in US Gulf Coast refineries seeking to replace tube-trailer deliveries with on-site production under EPA emissions verification frameworks. These units anchor the installed base value due to decades of ammonia and petrochemical plant reliance.
- Electrolyzers:Modular units splitting water into hydrogen and oxygen using electrical current, with alkaline and PEM variants scaling from megawatt to gigawatt configurations. Procurement is accelerating in Germany's Ruhr chemical clusters where EU Green Deal carbon intensity mandates disqualify gray hydrogen from public contracts. This segment is gaining share fastest as renewable-powered installations displace fossil-derived supply.
- Portable Generators:Compact, transportable units designed for temporary industrial supply or remote field operations. Mining operations in Western Australia and construction sites in Alberta represent primary demand pockets.
- Fuel Cell Systems:Integrated generation-conversion units producing electricity from hydrogen electrochemical reaction. Deployment is concentrating in Japanese stationary power backup and California distributed energy resource networks.
Stationary generators lead volumes today; electrolyzers are gaining share fastest.
End User:
Cost tier segmentation separates capital-intensive process industries with long asset horizons from mobility sectors where operational flexibility commands premium pricing.
- Chemical Production:Ammonia, methanol, and refinery hydrotreating operations consuming hydrogen as feedstock or process input. German chemical corridors in North Rhine-Westphalia anchor electrolyzer procurement under EU F-Gas Regulation compliance deadlines. This segment leads volumes today.
- Energy Sector:Power-to-gas storage, grid balancing, and renewable curtailment mitigation applications. Project pipelines in Spain and Denmark face 18-36 month grid interconnection queues that compress developer returns.
- Steel Manufacturing:Blast furnace injection and direct reduction processes substituting hydrogen for metallurgical coal. China's MIIT efficiency standards are mandating electrolyzer trials in Hebei province steel clusters.
- Automotive Industry:Fuel cell vehicle manufacturing and hydrogen refueling station supply chains. California mobility corridors and Japan's Kanto region represent concentrated demand for containerized PEM backup systems.
Chemical production commands the largest revenue pool; steel manufacturing is climbing the fastest as regulatory deadlines force coal hydrogen displacement.
Technology:
Maturity gradients separate commercially proven platforms from emerging architectures still validating durability warranties and project finance acceptance.
- Alkaline Electrolysis:Liquid electrolyte systems operating at 60-80°C with nickel-based electrodes, achieving 60-70% system efficiency. Chinese manufacturing scale-up is driving module cost reductions that enable export penetration into Southeast Asian industrial clusters.
- Proton Exchange Membrane:Solid polymer electrolyte systems delivering rapid response and high purity output for semiconductor and fuel cell applications. Palladium and iridium supply concentration from South Africa and Russia exposes manufacturers to geopolitical disruption.
- Solid Oxide:Ceramic electrolyte cells operating at 700-900°C with potential for waste heat integration. Dutch and Norwegian chemical producers are piloting thermal coupling architectures to exceed 85% LHV electrical efficiency.
- High-Temperature Electrolysis:Steam-fed systems leveraging industrial waste heat to reduce electrical energy requirements. Demonstration projects in nuclear-coupled configurations remain pre-commercial.
Alkaline electrolysis dominates installed capacity; solid oxide is expanding most quickly as heat integration economics improve.
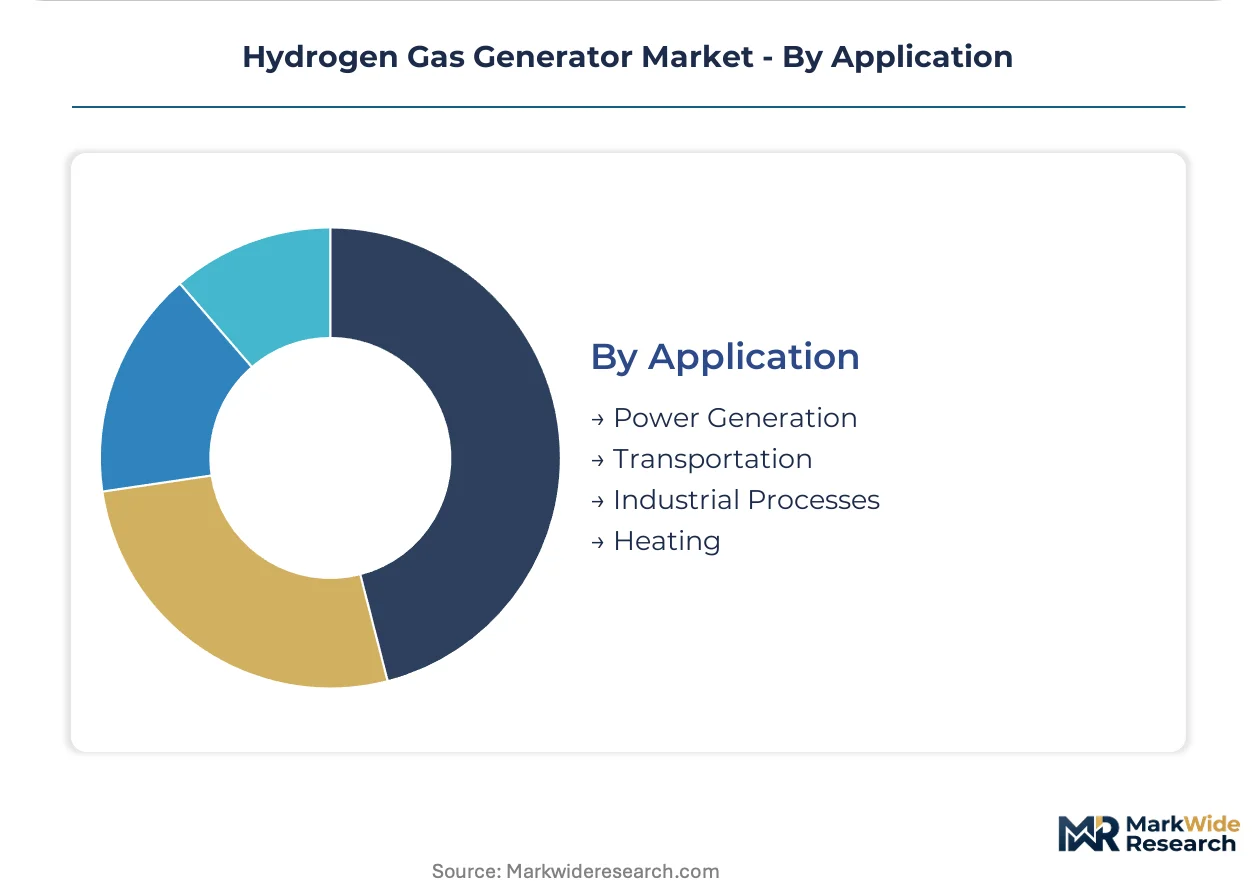
Application:
Volume concentration varies sharply between bulk thermal processes where hydrogen substitutes for natural gas and premium mobility applications where purity and pressure specifications command specialized equipment.
- Industrial Processes:Hydrotreating, desulfurization, ammonia synthesis, and methanol production consuming hydrogen as chemical input. US Gulf Coast refineries are consolidating supply contracts under long-term renewable power purchase agreements.
- Transportation:Fuel cell vehicle refueling and heavy-duty trucking corridors requiring 700 bar compression and 99.97% purity. Germany, Japan, and California infrastructure buildouts are creating aftermarket service revenue pools for remote monitoring systems.
- Power Generation:Grid-scale storage, peaking capacity, and islanded microgrids using hydrogen as energy carrier. Intermittency matching challenges constrain economic viability outside markets with high renewable curtailment.
- Heating:Industrial thermal applications and building sector pilot programs substituting hydrogen for natural gas. CNG retrofit economics in the US Midwest retain cost advantages that undercut green hydrogen timelines.
Industrial processes anchor current demand; transportation is scaling fastest where mobility corridor density reaches critical mass.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's chemical corridors anchor European electrolyzer procurement, while the United States Gulf Coast drives refinery on-site hydrogen deployment under IRA tax credit frameworks. China commands manufacturing scale for alkaline and PEM export lines. Japan and the Netherlands concentrate mobility infrastructure and heat-integrated pilot projects respectively.
United States
EPA lifecycle emissions verification under the Inflation Reduction Act conditions $3/kg clean hydrogen production incentives on documented carbon intensity. Gulf Coast refineries in Texas and Louisiana are consolidating supply contracts under long-term renewable power purchase agreements. Proton exchange membrane unit deployment accelerates as operators eliminate compressed gas delivery liability.
Germany
Ruhr region chemical clusters anchor electrolyzer procurement as EU Green Deal carbon intensity mandates disqualify gray hydrogen from public contracts. The F-Gas Regulation's fluorinated greenhouse gas phasedown forces PEM stack redesigns by 2027 compliance deadlines. North Rhine-Westphalia hydrogen pipeline networks are expanding to connect industrial offtake with renewable generation zones.
China
MIIT efficiency standards and dual carbon goals mandate electrolyzer trials for blast furnace injection in Hebei and Jiangsu province steel clusters. Domestic manufacturing scale-up drives alkaline and PEM module cost reductions for Southeast Asian export penetration. Zhejiang and Jiangsu factory complexes are expanding gigawatt-class production lines.
Japan
METI hydrogen mobility corridor investments concentrate containerized PEM demand in the Kanto region around Tokyo. Fuel cell vehicle manufacturing supply chains require 700 bar compression and 99.97% purity specifications. Osaka-based industrial gas infrastructure supports distributed refueling station backup generation architectures.
Netherlands
Port of Rotterdam chemical clusters pilot solid oxide electrolysis with waste heat integration targeting 85% LHV electrical efficiency for ammonia retrofit projects. Grid interconnection queues spanning 18-36 months compress developer returns on renewable-powered installations. Eemshaven renewable generation zones are positioning for green hydrogen export to German industrial corridors.
Hydrogen Gas Generator Market Competitive Landscape
Chinese producers anchor manufacturing scale; European and US industrial gas incumbents hold infrastructure-integrated positions. Market structure tiers between consolidated industrial gas majors with reforming asset bases and fragmented electrolyzer specialists scaling modular platforms. Three archetypes dominate: legacy hydrogen suppliers defending refinery contracts, pure-play electrolyzer vendors capturing renewable procurement, and diversified energy conglomerates hedging technology exposure. Competitive intensity concentrates on M&A for electrolyzer stack capabilities and strategic partnerships for renewable power offtake.
Within the industrial gas tier, Air Liquide and Linde occupy positions exemplifying infrastructure-anchored supply contract consolidation. Nel ASA represents the pure-play electrolyzer archetype focused on containerized system architectures. Among diversified energy conglomerates, Siemens Energy sits within a portfolio-spanning position linking power generation equipment with hydrogen production technology.
| Leading Market Players |
|---|
| Air Liquide |
| Linde |
| Air Products and Chemicals |
| Nel ASA |
| Plug Power |
| Cummins |
| ITM Power |
| McPhy Energy |
| Siemens Energy |
| Others |
Pricing and Supply Chain Analysis
US Gulf Coast refinery procurement teams anchor contract negotiations for large-scale proton exchange membrane units, compressing supplier margins through consolidated long-term power purchase agreements that transfer volume risk to electrolyzer operators.
Pricing Analysis
Capacity additions in China are reshaping price floors for alkaline electrolyzer modules as domestic factory expansion enables export penetration into Southeast Asian industrial clusters. Three-tier pricing structure across premium, standard, and economy levels separates containerized PEM systems with remote monitoring capabilities from basic reforming units and refurbished equipment. Cost compression in standard-tier alkaline systems is intensifying because Chinese manufacturing scale-up outpaces demand absorption in European chemical corridors. Refinery operators in Texas and Louisiana exhibit the highest price sensitivity due to compressed natural gas substitution economics, while semiconductor fabs in Japan accept premium pricing for 99.999% purity guarantees.
Supply Chain Analysis
Freight costs for iridium and palladium shipments from South Africa and Russia expose proton exchange membrane stack manufacturers to geopolitical disruption and maritime route volatility. Manufacturing concentration centers on China for alkaline and PEM module production, Germany for precision engineering components, and South Korea for advanced membrane materials. Raw material dependencies draw from platinum group metals, nickel-based electrodes, and fluoropolymer membranes. Single-source vulnerability in South African palladium sourcing represents the dominant structural risk. Distribution runs through industrial gas infrastructure incumbents with captive reforming assets and direct electrolyzer OEM channels for modular deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrolyzer technology maturation is compressing the cost gap between renewable-powered and fossil-derived hydrogen, creating margin expansion for operators capturing IRA tax credit premiums and EU Green Deal-compliant certification tiers.
For Market Incumbents: Deploy backward integration into iridium and palladium sourcing to insulate proton exchange membrane production from South African supply disruption. Anchor refinery contract renewals through bundled renewable power purchase agreements that lock in EPA lifecycle emissions verification compliance. Consolidate aftermarket service networks for containerized PEM systems before pure-play electrolyzer vendors establish remote monitoring footprints in California mobility corridors. For New Entrants and Emerging Players: Industrial gas distributors represent the most accessible channel partners for penetrating German chemical corridor procurement under EU F-Gas Regulation compliance deadlines. Target steel sector blast furnace injection trials in Hebei province where MIIT efficiency standards mandate electrolyzer procurement with limited incumbent presence. Pursue white-label manufacturing partnerships with Zhejiang factory complexes to bypass capital-intensive gigawatt-class production line investments. For Investors and Strategic Acquirers: Diversified energy conglomerates with power generation equipment portfolios are the most active acquirer in this space, seeking electrolyzer stack capabilities to hedge technology exposure. Mid-scale solid oxide specialists with waste heat integration pilots in the Netherlands and Norway represent the highest-conviction acquisition target archetype. Watch for electrolyzer stack degradation warranty standardization as the signal indicating project finance underwriting acceptance and cost of capital compression for independent power producer developers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PGM Sourcing | Insulates PEM manufacturers from South African palladium supply disruption and price volatility. |
| Long-term Power Purchase Agreement | Locks in EPA lifecycle emissions verification for IRA clean hydrogen tax credit eligibility. |
| Containerized PEM Channel Expansion | Captures aftermarket service revenue pools in California and Japan mobility corridors. |
| Solid Oxide Heat Integration Pilot | Validates 85% LHV electrical efficiency for ammonia retrofit projects in Dutch chemical clusters. |
| Fluorine-free Membrane Development | Ensures EU F-Gas Regulation compliance for PEM stack cooling systems by 2027 deadlines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with refinery procurement directors, electrolyzer OEM technical leads, industrial gas supply contract managers, and EPC contractors with secondary validation through EIA energy data, IEA hydrogen reports, SEC filings from listed industrial gas majors, and EU emissions trading system records. Bottom-up electrolyzer shipment tracking and top-down hydrogen demand modeling were triangulated against chemical production capacity announcements.
Historical reference periods spanning installed base formation through technology transition phases anchored the projection horizon across alkaline, PEM, and solid oxide technology platforms segmented by stationary generator, electrolyzer, and fuel cell system product categories. CAGRs were derived from unit shipment trajectories and average selling price compression curves, incorporating renewable power purchase agreement penetration rates and carbon intensity certification adoption as hydrogen-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to platinum group metal supply disruption, grid interconnection queue resolution timelines in Germany and Spain, and interoperability consensus across competing renewable hydrogen certification schemes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Liquid Organic Hydrogen Carrier (LOHC) Market
Hydrogen Energy
Alkaline Water Electrolysis Market
Hydrogen Energy
Green Hydrogen Storage Technology Market
Hydrogen Energy
Hydrogen Production Electrolyser Market
Hydrogen Energy
70MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Europe Hydrogen Generation Market
Hydrogen Energy
Green Energy Hydrogen Production System Market
Hydrogen Energy
Brown Hydrogen Market
Hydrogen Energy
Blue Hydrogen Market
Hydrogen Energy
Hydrogen Market
Hydrogen Energy
Hydrogen Purification Market
Hydrogen Energy
Hydrogen-Cooled Turbine Generator Market
Hydrogen Energy
United States Hydrogen Generation Market
Hydrogen Energy
Hydrogen Composite Tanks Market
Hydrogen Energy
Photovoltaic Hydrogen Production Market
Hydrogen Energy
Clean Hydrogen Market