
 Distribution Feeder Protection System Market | 2026-2036
Distribution Feeder Protection System Market Size, Share, and Industry Trends Forecast 2026-2036
Distribution Feeder Protection System Market Outlook
Market Context with Strategic Players
India is narrowing its technology gap in distribution automation through domestic manufacturing incentives and utility modernization programs. ABB leverages its digital relay portfolio to anchor European utility contracts while extending engineering services into emerging markets. Siemens competes on integrated feeder automation platforms that combine protection with SCADA-ready communication protocols. Schweitzer Engineering Laboratories specializes in high-speed recloser controls that dominate North American cooperative utility specifications.
Technical Definition and Structural Segments
A distribution feeder protection system comprises coordinated reclosers, fuses, circuit breakers, and protection relays engineered to detect fault conditions, isolate damaged sections, and restore power within cycles on medium-voltage radial networks. These systems operate through current transformers sampling phase and ground currents, with microprocessor-based relays executing impedance, overcurrent, and directional logic to clear faults before transformer or conductor thermal limits are exceeded. Protection relays command premium pricing due to firmware complexity and IEC 61850 interoperability requirements, while recloser demand accelerates fastest as utilities replace fuse-only rural feeders with automated sectionalizing. Smart technology deployments are displacing analog protection in urban density corridors where outage minutes carry regulatory penalty exposure.
Regulatory Frame and Forward-Looking Close
IEC 61850 and IEEE 1547 shape product interoperability mandates across multiple jurisdictions, while India's CEA enforces grid connectivity standards that require directional overcurrent coordination on all new distribution infrastructure. The EU F-Gas Regulation indirectly pressures utilities to minimize switching operations that vent sulfur hexafluoride, thereby favoring faster-acting electronic protection that reduces mechanical breaker duty cycles. Stakeholders must weigh the capital trade-off between full feeder automation and targeted recloser deployment as tariff structures evolve to penalize sustained interruption frequency.
Market Dynamics
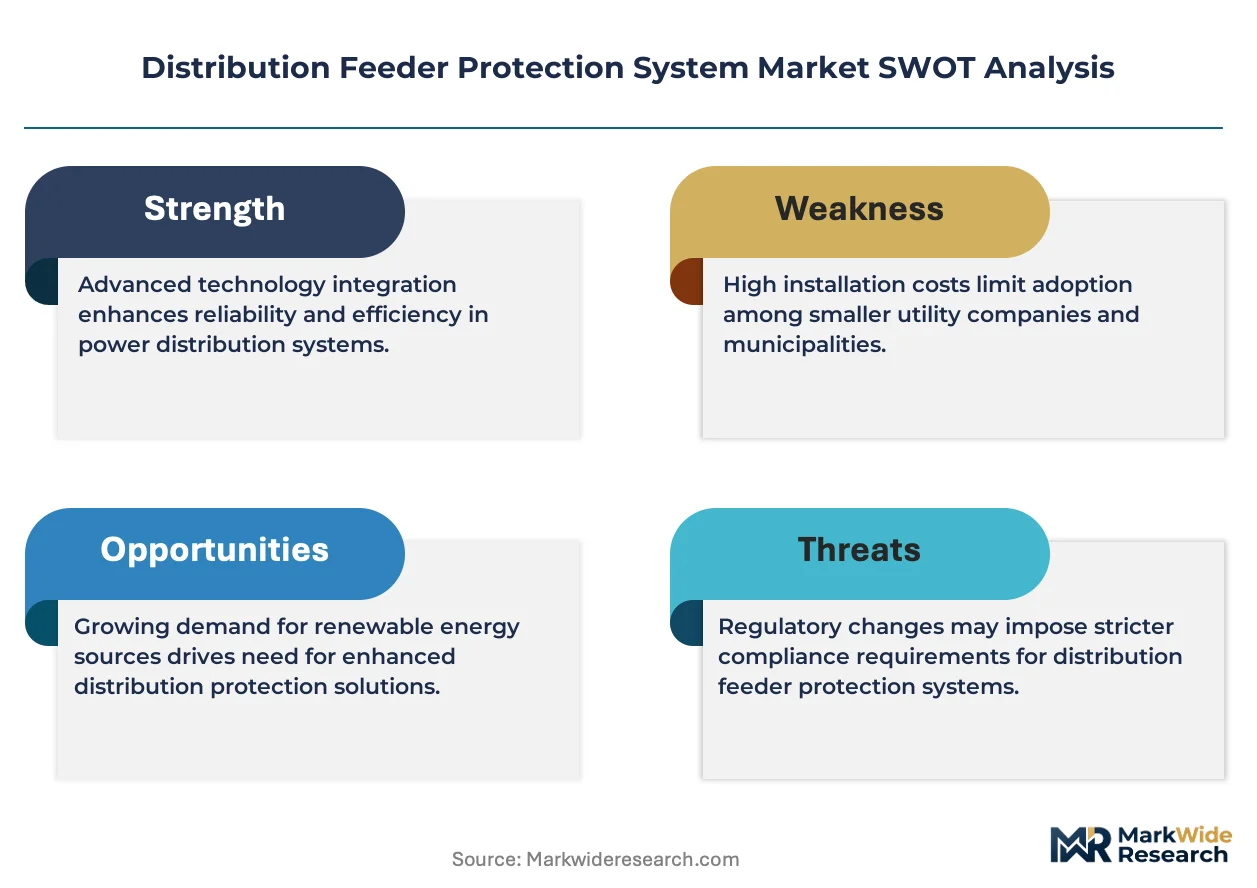
Digital twin integration is compressing commissioning cycles for feeder protection systems, forcing utilities to restructure capital planning around software-defined validation rather than physical testing protocols.
Growth Catalysts
- Rural electrification mandates:India's CEA grid connectivity standards require directional overcurrent coordination on all new distribution infrastructure, pulling recloser and relay procurement forward.
- IEC 61850 interoperability:Utility procurement specifications now mandate process bus communication, creating pull-through demand for microprocessor-based protection relays with embedded Ethernet.
- SF6 phase-down pressure:The EU F-Gas Regulation incentivizes faster-acting electronic protection to reduce mechanical breaker duty cycles and associated gas venting.
Market Restraints
- Copper and rare earth input volatility:Current transformer cores and relay magnetics face price swings that compress OEM margins on fixed-price utility contracts.
- Firmware complexity concentration:Protection algorithm development concentrates among specialized engineering teams in Germany and Switzerland, creating talent bottlenecks.
- Fuse substitution persistence:Cost-sensitive rural cooperatives in Southeast Asia continue specifying fuse-only sectionalizing, delaying automation adoption.
Strategic Opportunities
- Vietnam and Indonesia grid expansion:State-owned utilities are tendering feeder automation packages for new industrial zone electrification with greenfield IEC 61850 specifications.
- Digital twin convergence:Protection system vendors bundling real-time simulation with hardware sales capture multi-year software maintenance streams.
- India PLI scheme tailwind:Domestic manufacturing incentives for power sector equipment reduce landed cost disadvantages against imports.
Industry Challenges
- IEC 61850 certification timelines:Third-party interoperability testing for process bus implementations extends product launch schedules by 8-14 months.
- Legacy electromechanical replacement:Utilities with aging technician workforces struggle to bridge skill gaps between analog calibration and microprocessor configuration.
- SCADA integration complexity:Multi-vendor environments create protocol mapping burdens that delay project commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distribution Feeder Protection System Market |
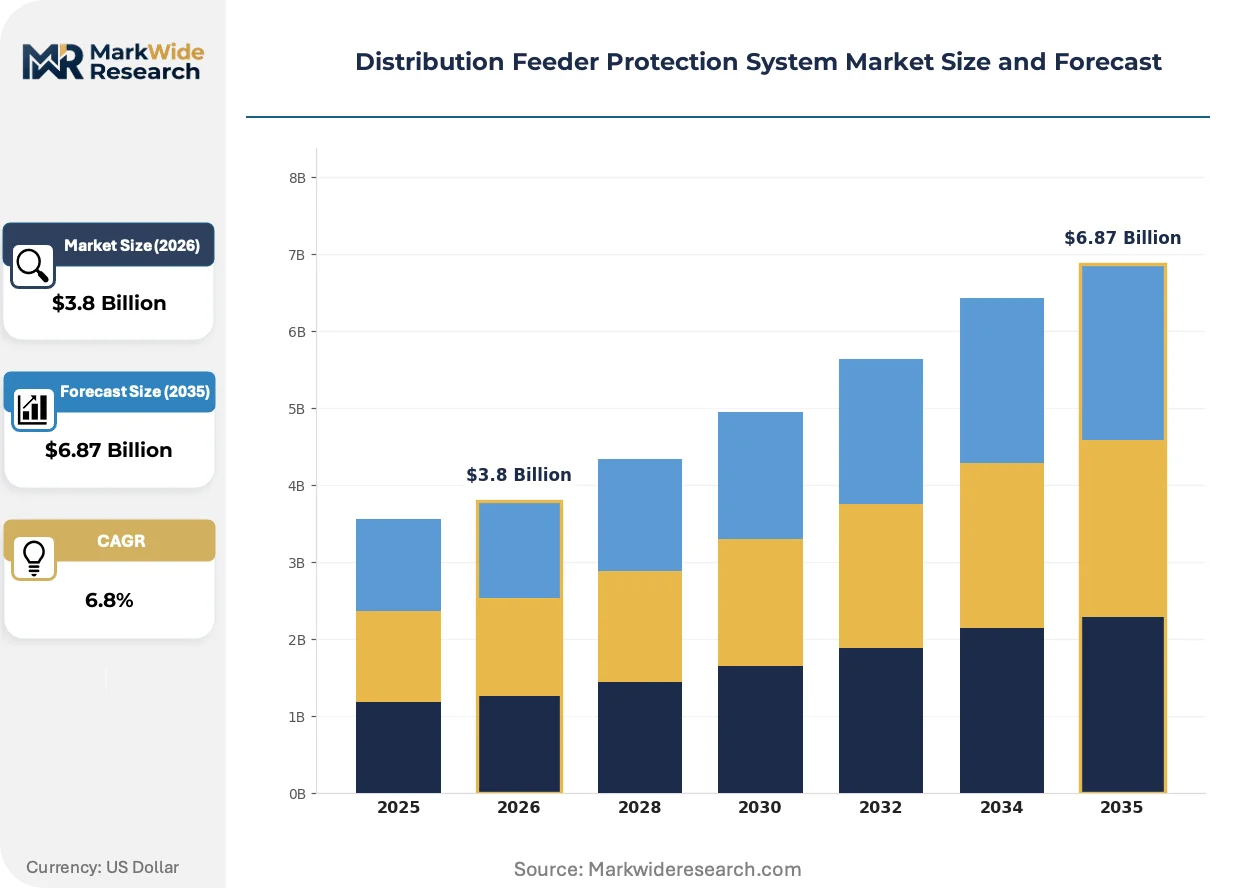
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.87 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reclosers, Fuses, Circuit Breakers, Protection Relays End User: Utilities, Industrial, Commercial, Residential Technology: Digital Protection, Analog Protection, Hybrid Systems, Smart Technology Installation: On-site, Remote, Indoor, Outdoor |
| Companies Covered | Eaton, Mitsubishi Electric Corporation, ABB, Fanox, Larsen & Toubro, Schneider Electric, General Electric, Schweitzer Engineering Laboratories, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distribution Feeder Protection System Market Strategic Shifts
Protection system architecture is pivoting from standalone hardware to networked intelligence, with firmware-defined functionality displacing fixed-logic electromechanical designs across utility specifications.
Adaptive protection algorithms are digitizing fault detection logic in real-time based on network topology changes. European transmission system operators are mandating these capabilities for meshed distribution networks. The technology is compressing coordination study timelines from weeks to hours.
The EU F-Gas Regulation is accelerating SF6-free switchgear pairing with electronic recloser controls. Manufacturers must redesign arc interruption physics while maintaining sub-cycle clearing speeds. German utilities are piloting vacuum interrupter combinations with integrated protection logic.
Performance-based contracting is displacing equipment-only procurement in urban density corridors. Australian distribution network service providers now specify guaranteed interruption frequency caps rather than hardware lists. Contractors absorb outage penalty exposure through integrated protection-maintenance bundles.
Distribution Feeder Protection System Market Segmentation
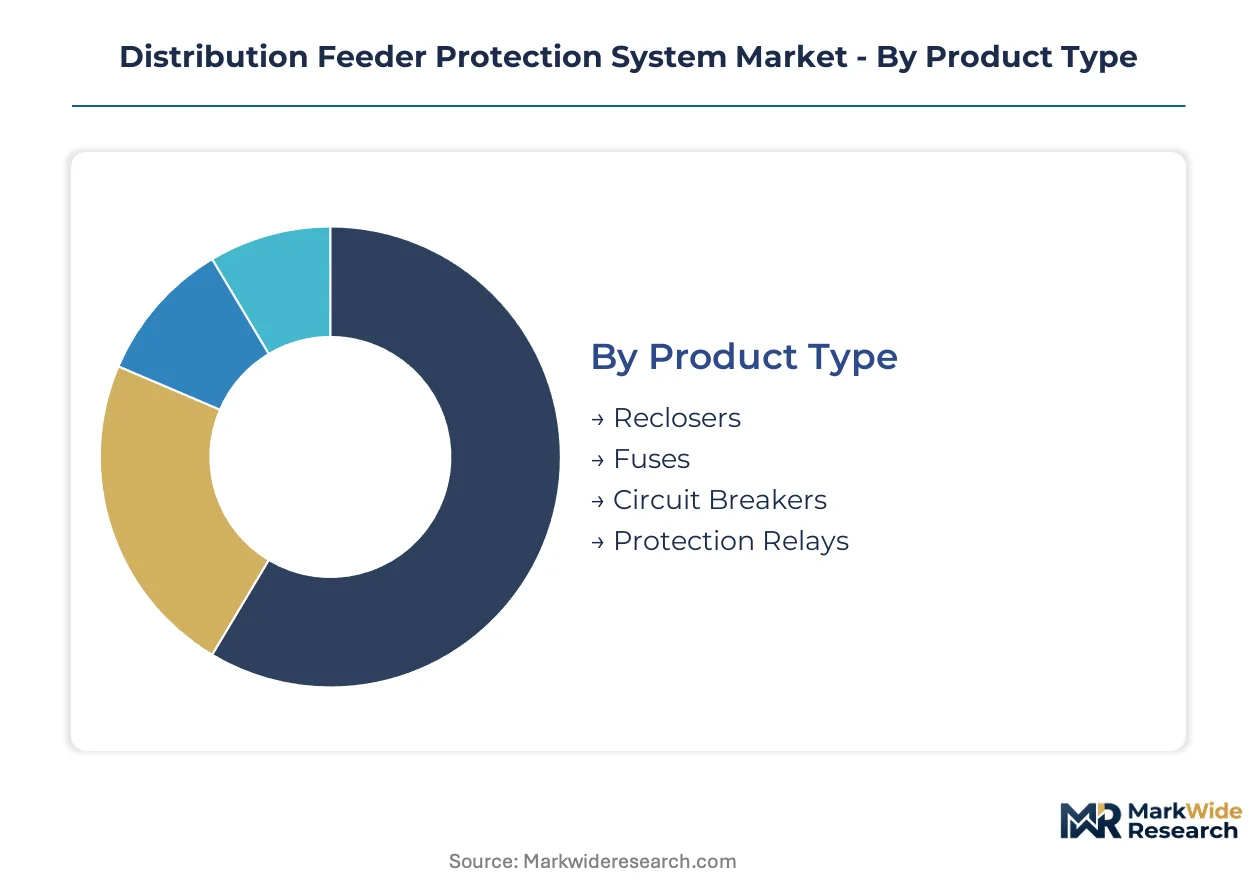
Feeder protection procurement splits sharply between legacy hardware replacement cycles and smart grid new-build specifications. Understanding these segment boundaries clarifies where vendors must engineer for interoperability versus cost minimization.
Product Type:
Cost tier differentiation separates commodity fuse hardware from firmware-intensive protection relays with embedded communication stacks.
- Protection Relays:Microprocessor-based units execute impedance, overcurrent, and directional logic with IEC 61850 Ethernet process bus integration. Demand concentrates in European urban density corridors where outage minutes trigger regulatory penalties under national energy regulator frameworks.
- Reclosers:Automated sectionalizing devices replace fuse-only rural feeders with fault isolation and restoration capabilities. Procurement accelerates across India's rural electrification corridors where CEA grid connectivity standards mandate directional coordination on new distribution infrastructure.
- Circuit Breakers:Mechanical interruption devices paired with electronic trip units for medium-voltage radial networks.
- Fuses:Passive overcurrent protection maintaining share in cost-sensitive Southeast Asian cooperative utility specifications.
Protection relays command the established base. The steepest expansion runs through reclosers.
End User:
Application context dictates specification stringency, from utility-grade interoperability mandates to commercial premises liability thresholds.
- Utilities:State-owned and investor-owned distribution operators specifying IEC 61850-mandated procurement with multi-vendor SCADA integration requirements. Investment concentrates in Asia-Pacific smart grid deployments where rural electrification programs and urban reliability mandates run in parallel.
- Industrial:Manufacturing facilities and processing plants requiring selective coordination with on-site generation under IEEE 1547 interconnection standards. Demand clusters around chemical and metals processing corridors in Germany and the US Gulf Coast where arc flash mitigation drives premium relay specifications.
- Commercial:Retail, healthcare, and data center facilities with uptime-dependent operations.
- Residential:Single-premise protection in master-metered developments and estate electrification.
Utilities anchor volume procurement. Industrial sites generate the fastest margin expansion through engineering-intensive customization.
Technology:
Maturity gradients separate installed electromechanical bases from firmware-defined architectures requiring digital workforce competencies.
- Digital Protection:Fully microprocessor-based relays with adaptive algorithms and real-time topology awareness. Adoption concentrates in European meshed distribution networks where transmission system operators mandate dynamic coordination capabilities.
- Smart Technology:Networked intelligence with digital twin integration and predictive maintenance analytics. Deployment accelerates in Australian urban density corridors where performance-based contracting specifies guaranteed interruption frequency caps rather than hardware lists.
- Hybrid Systems:Electromechanical sensing with electronic trip units bridging legacy and modern architectures.
- Analog Protection:Electromechanical and solid-state designs persisting in technician-constrained rural utilities.
Digital protection holds the incumbent revenue base. Smart technology is climbing the fastest as software-defined validation displaces physical testing protocols.
Installation:
Volume distribution reflects infrastructure age and climate exposure across utility service territories.
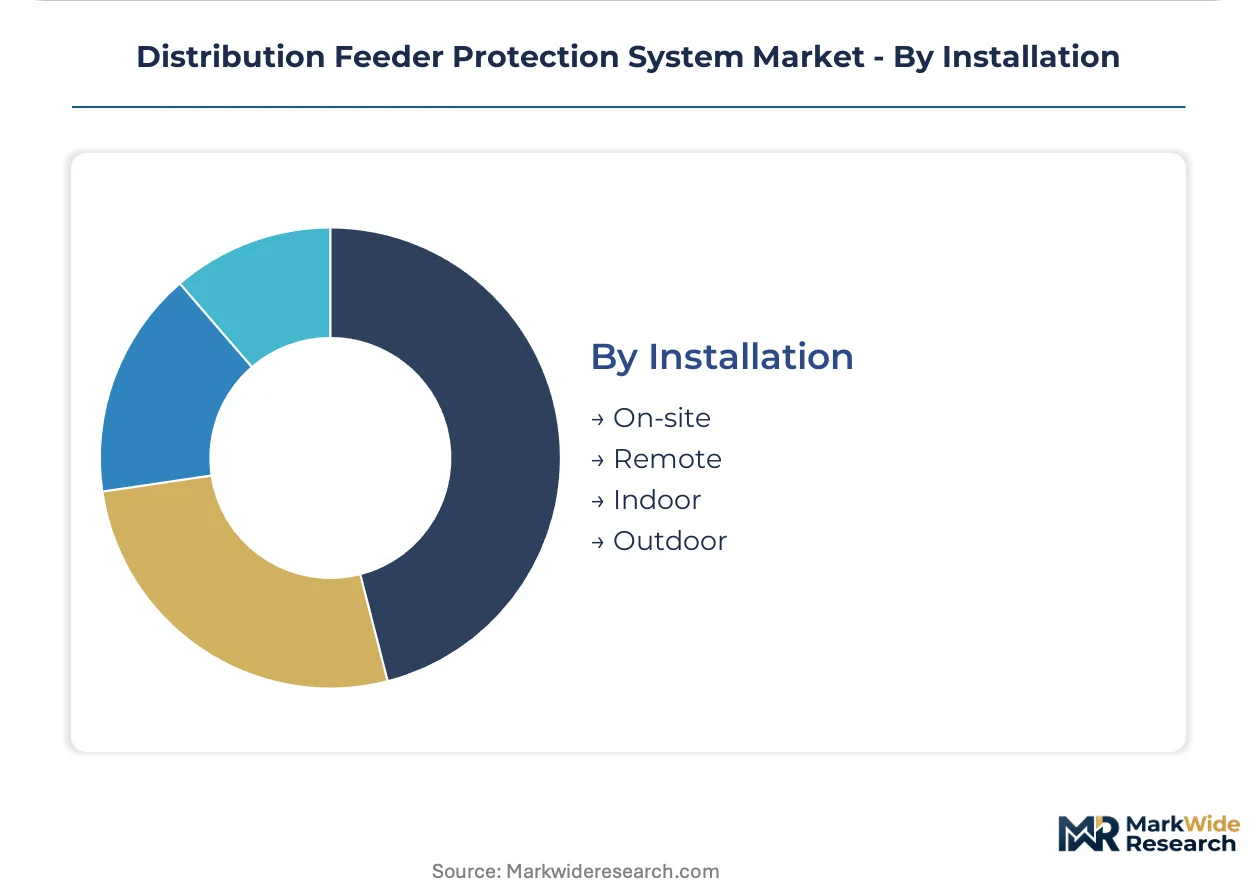
- Outdoor:Pole-mounted and pad-mounted equipment exposed to environmental stressors including moisture, temperature cycling, and particulate contamination. Specification dominates North American cooperative utilities and Southeast Asian rural electrification programs.
- Remote:Telecommunications-dependent monitoring and control for geographically dispersed feeders. Demand rises in Australian distribution networks and Canadian provincial utilities with extensive low-density service areas.
- On-site:Direct technician access for commissioning, maintenance, and fault response.
- Indoor:Climate-controlled substation and switchgear installations in urban density centers.
Outdoor configurations retain the largest installed base. Remote installation is gaining share fastest through SCADA integration and workforce optimization pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CEA grid connectivity standards in India are pulling recloser procurement forward across Asia-Pacific distribution networks. Utility modernization programs in Germany and the United States are accelerating digital relay replacement cycles. Rural electrification corridors in Southeast Asia are creating divergent specification tiers between fuse-only and automated sectionalizing deployments.
India
Rural electrification mandates under the Saubhagya scheme are driving recloser demand across Maharashtra and Gujarat distribution networks. CEA Technical Standards for Connectivity require directional overcurrent coordination on all new 11kV and 33kV infrastructure. Larsen & Toubro anchors domestic manufacturing through its electrical automation division in Mumbai-Pune industrial corridor.
Germany
Meshed distribution networks in Bavaria and North Rhine-Westphalia are mandating adaptive protection algorithms under transmission system operator specifications. The EU F-Gas Regulation pressures utilities to minimize SF6 venting through faster-acting electronic protection. Siemens anchors engineering development in Munich while piloting vacuum interrupter combinations with integrated logic.
United States
Cooperative utilities across Texas and the Midwest are replacing fuse-only feeders with automated reclosers under FERC reliability incentive frameworks. IEEE 1547 interconnection standards shape procurement for distributed generation integration. Schweitzer Engineering Laboratories dominates specifications in the Pacific Northwest through high-speed recloser control platforms.
China
State Grid Corporation is deploying smart feeder automation across Yangtze River Delta industrial zones under dual carbon policy targets. GB standards for distribution automation mandate IEC 61850 process bus compatibility in new substation construction. Mitsubishi Electric Corporation occupies position in high-voltage protection relay supply through joint ventures in Jiangsu province.
Australia
Distribution network service providers in New South Wales and Victoria are adopting performance-based contracting with guaranteed interruption frequency caps. The Australian Energy Regulator penalizes sustained outage minutes in urban density corridors. ABB captures software maintenance streams through digital twin integration bundled with hardware sales.
Distribution Feeder Protection System Market Competitive Environment
Integrated platform vendors and specialized protection engineering houses split the market across specification tiers. Consolidation concentrates among European and North American incumbents with embedded utility relationships. Three archetypes dominate: full-suite automation providers, recloser control specialists, and digital relay engineering houses. Competitive moves center on firmware licensing partnerships and backward integration into current transformer manufacturing.
Within the integrated platform tier, ABB and Siemens exemplify engineering-intensive positioning through digital relay portfolios and SCADA-ready communication stacks. Schneider Electric occupies a position spanning medium-voltage switchgear integration with protection logic. Among specialized engineering houses, Schweitzer Engineering Laboratories represents the recloser control archetype dominant in North American cooperative utility specifications. Eaton and General Electric sit within the diversified electrical equipment tier, leveraging circuit breaker manufacturing scale into feeder automation bundling. Larsen & Toubro anchors emerging market positioning through India's PLI scheme for domestic power sector equipment manufacturing.
| Leading Market Players |
|---|
| Eaton |
| Mitsubishi Electric Corporation |
| ABB |
| Fanox |
| Larsen & Toubro |
| Schneider Electric |
| General Electric |
| Schweitzer Engineering Laboratories |
| Siemens |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese relay manufacturing is compressing margins for European and North American OEMs while forcing suppliers toward firmware differentiation and service bundling to defend pricing power against commoditized hardware imports.
Pricing Analysis
Price spreads between German-engineered protection relays and Southeast Asian-assembled units exceed threefold, reflecting IEC 61850 certification premiums and embedded Ethernet process bus capabilities. Pricing stratifies across premium-certified, standard-compliant, and economy-tier hardware levels, with firmware complexity and SCADA integration depth as the primary differentiation drivers. Cost compression in economy-tier reclosers is intensifying because Indian domestic manufacturing incentives under the PLI scheme are eroding import landed-cost advantages. Rural cooperatives in Vietnam and Indonesia exhibit the highest price sensitivity, while European urban utilities prioritize guaranteed interruption frequency performance over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for current transformer cores and microprocessor relay assemblies. Manufacturing concentrates in China, Germany, and India, with China feeding commodity-grade fuse and recloser hardware, Germany anchoring high-reliability relay engineering, and India scaling domestic production under CEA procurement mandates. Relay production draws from copper winding stock, rare earth magnetics for current sensors, and silicon wafer supply for embedded processors. Distribution runs through utility-direct procurement channels for large-scale automation projects and electrical distributor networks for replacement hardware and rural electrification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware engineering talent scarcity in protection algorithm development creates a structural moat for incumbent vendors while constraining new entrant scale-up velocity.
For Market Incumbents: Entrench market position through backward integration into current transformer manufacturing to capture margin from copper and rare earth input volatility, while accelerating IEC 61850 certification pipelines to outpace 8-14 month third-party testing timelines that delay product launches. Defend against specialized recloser control specialists by bundling digital twin software maintenance streams with hardware sales to lock in multi-year utility relationships. For New Entrants and Emerging Players: Mid-market industrial facilities in India's chemical and metals processing corridors represent the most penetrable entry point, as these sites require selective coordination with on-site generation under IEEE 1547 standards but lack the procurement scale to attract tier-one vendor attention. Target Vietnam and Indonesia state-owned utilities tendering greenfield IEC 61850 feeder automation packages for new industrial zone electrification, leveraging firmware licensing partnerships to bypass in-house algorithm development bottlenecks. For Investors and Strategic Acquirers: Long-term, this sits as a utility-infrastructure replacement-cycle play because electromechanical protection bases across North American and European utilities are approaching end-of-life, forcing procurement decisions regardless of macroeconomic conditions. Acquisition focus should center on specialized engineering houses with captive IEC 61850 interoperability expertise and embedded relationships with cooperative utility specifications. Monitor CEA enforcement intensity on directional overcurrent coordination mandates as the signal for India demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 61850 Certification Acceleration | Third-party interoperability testing compresses product launch timelines by 8-14 months for process bus implementations. |
| Digital Twin Integration Bundling | Real-time simulation software paired with hardware sales captures multi-year maintenance streams from Australian utilities. |
| Domestic Manufacturing Scale-Up | India's PLI scheme for power sector equipment reduces landed cost disadvantages against Chinese imports. |
| SF6-Free Switchgear Pairing | Vacuum interrupter combinations with integrated protection logic address EU F-Gas Regulation compliance pressures. |
| Performance-Based Contracting | Guaranteed interruption frequency caps shift outage penalty exposure from utilities to contractors in urban density corridors. |
Study Parameters
Cross-validation between utility procurement database analysis and manufacturer shipment records anchors the qualitative findings on technology substitution patterns. Primary interviews with utility planning officers, protection relay product managers, EPC contractors, and distribution cooperative engineering directors combined with secondary validation from FERC reliability filings, CEA technical standards documentation, EU F-Gas Regulation impact assessments, and IEC 61850 interoperability test reports. Bottom-up segment sizing triangulates against top-down utility capital expenditure tracking across the analysis window.
Calibration against historical replacement cycles for electromechanical protection and smart grid deployment trajectories shapes the analytical framework. Segmentation dimensions modeled include product type tier, end-user application context, technology maturity gradient, and installation environment across the projection horizon. CAGRs derive from utility capital planning surveys and infrastructure age profiling, with inputs from rural electrification program budgets, urban reliability penalty frameworks, and industrial zone electrification pipelines.
Practitioners should monitor copper and rare earth price volatility, IEC 61850 certification backlog durations, and CEA enforcement consistency for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Europe Power Purchase Agreement Market
Power
Global UPS Market
Power
Kuwait Power Market
Power
Global Ancillary Services Power Market
Power
Asia-Pacific Alternating Current (AC) Drive Market
Power
North America Power Market
Power
Canada Power Market
Power
Power Rental Market
Power
Egypt Uninterruptible Power Supply (UPS) Market
Power
Static Synchronous Compensator (STATCOM) Market
Power
Recloser Control Market
Power
Rotating Phase Converter Market
Power
Saudi Arabia Power Market
Power
Electric Power Sports Market
Power
Asia-Pacific Microturbine Market
Power
Brunei Power Market