

Controllable Shunt Reactor for UHV Market Size, Share, and Industry Trends Forecast 2026-2036
Controllable Shunt Reactor for UHV Market Insights
Magnetically controlled reactor topologies is fragmenting the traditional iron-core product hierarchy as utilities demand faster response times for voltage stabilization. Siemens Energy leverages its European manufacturing base to sustain leadership in hybrid-core designs. Hitachi Energy anchors its position through deep integration with Japanese UHV demonstration projects. NR Electric dominates domestic procurement channels within China's state grid framework.
A controllable shunt reactor for UHV is an inductive compensation device rated for 800 kV and above, employing magnetic flux control or thyristor switching to deliver continuously variable reactive power absorption across transmission corridors. Its primary purpose is to suppress overvoltage during light-load conditions and enable dynamic voltage regulation across thousand-kilometer UHV links. Iron-core designs retain the largest installed base due to proven thermal performance, yet hybrid-core configurations are capturing the fastest expansion as operators seek reduced harmonic distortion. FACTS device integration represents the most concentrated margin pool, since bundled reactive compensation contracts command premium pricing from transmission operators.
China's GB standards and MEE efficiency mandates shape product certification requirements for domestic suppliers, while IEC 60076-6 governs international test protocols for load tap-changer and magnetically controlled variants. India's CEA grid code revisions and the EU's F-Gas Regulation are tightening specifications for insulating mediums and loss thresholds. Stakeholders must monitor how regional standard divergence affects platform standardization strategies.
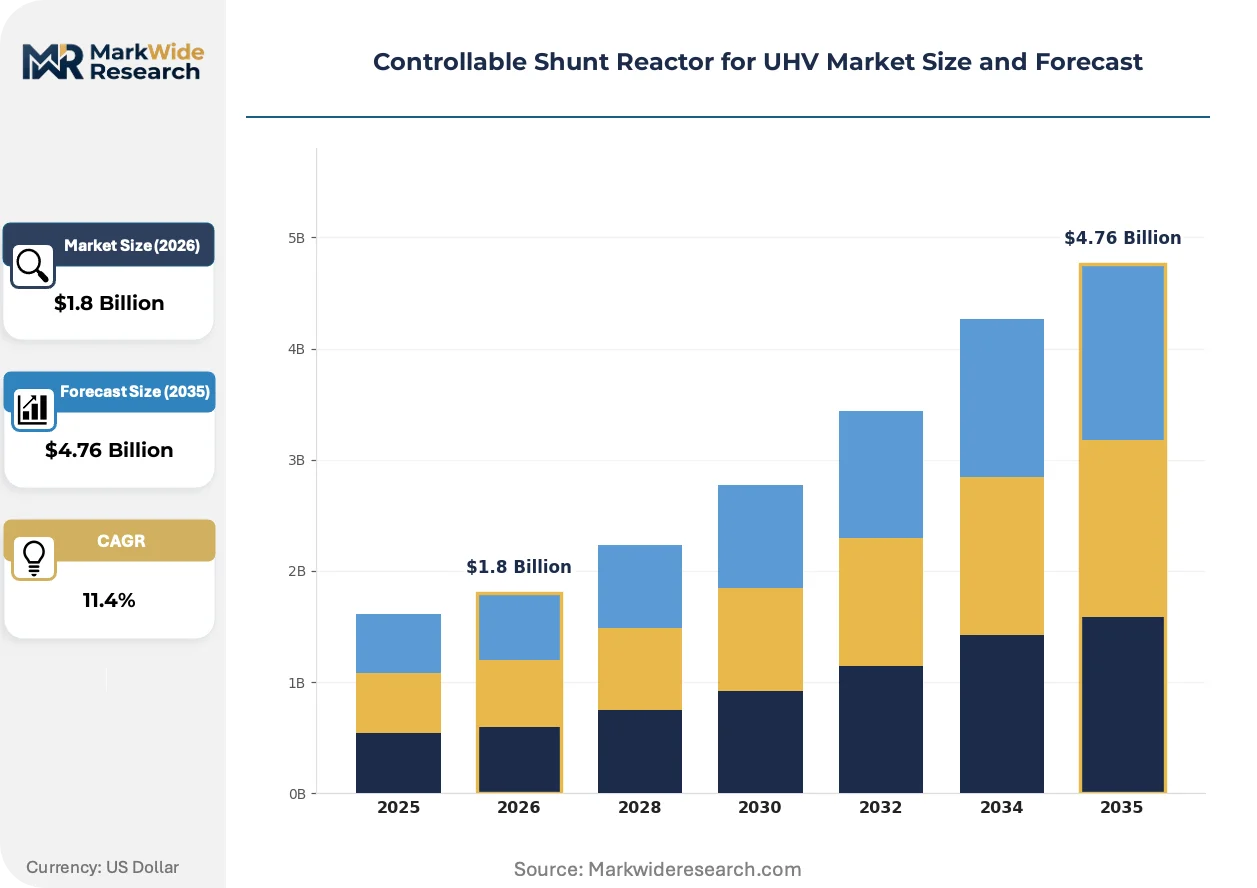
Market Dynamics
Magnetically controlled reactor topologies are fragmenting the traditional iron-core product hierarchy as transmission operators demand faster response times for dynamic voltage stabilization across ultra-high-voltage corridors.
Growth Catalysts
- Dual carbon mandates:China's MEE efficiency standards and carbon neutrality targets are accelerating replacement of fixed reactors with variable compensation devices in 800 kV and above substations.
- UHV corridor density:The Yangtze River Delta cluster hosts the highest concentration of operational 1000 kV lines, creating concentrated procurement pull for magnetically controlled variants.
- Thyristor switching maturation:Advances in high-voltage thyristor valve reliability are enabling continuous reactive power modulation without mechanical tap-changer wear.
Market Restraints
- Grain-oriented electrical steel concentration:Specialty core material supply concentrates among Japanese and European producers, exposing manufacturers to input cost volatility and allocation constraints.
- IEC 60076-6 test complexity:International certification protocols for load tap-changer variants impose extended validation timelines that delay product commercialization.
- Hybrid-core manufacturing scarcity:Production capability for combined iron-air core configurations remains limited to a handful of specialized facilities, constraining volume scalability.
Strategic Opportunities
- Indian grid modernization:CEA grid code revisions are mandating dynamic reactive compensation for new 765 kV corridors, opening procurement channels previously dominated by fixed reactors.
- FACTS integration convergence:Bundling controllable shunt reactors with STATCOM and SVC platforms creates premium-margin turnkey contracts for transmission operators seeking unified compensation solutions.
- EU F-Gas substitution:Tightening restrictions on SF6 insulating mediums are accelerating demand for dry-type and liquid-immersed alternatives in European UHV projects.
Industry Challenges
- Magnetic core modeling expertise:The shift toward hybrid-core designs requires scarce electromagnetic simulation capabilities that utilities and OEMs struggle to staff.
- Legacy SCADA integration:Retrofitting magnetically controlled units into existing substation automation architectures demands custom protocol gateways that extend commissioning timelines.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Controllable Shunt Reactor for UHV Market Trends and Innovations
Reactive compensation hardware is converging with power electronics and digital control systems, compressing the traditional boundary between passive grid assets and active FACTS devices.
Hybrid-core reactor technology is hybridizing magnetic circuit design by combining iron and air-gapped sections to achieve sub-cycle response times. State Grid Corporation of China is deploying these configurations across new 1100 kV demonstration corridors. The technology is hybridizing procurement specifications, forcing traditional iron-core suppliers to develop power electronics partnerships or cede premium contracts.
China's GB standards for grid equipment are tightening loss thresholds and harmonic emission limits for 800 kV and above compensation devices. Domestic suppliers must recertify existing product lines under revised MEE efficiency mandates. Magnetically controlled variants face the steepest compliance burden due to their complex excitation systems.
Transmission operators are consolidating reactive compensation procurement into multi-year framework agreements that bundle equipment supply with decade-long maintenance services. Chinese provincial grid companies pioneered this structure. The model is compressing vendor margins while locking out smaller manufacturers lacking service infrastructure.
Controllable Shunt Reactor for UHV Market Segmentation
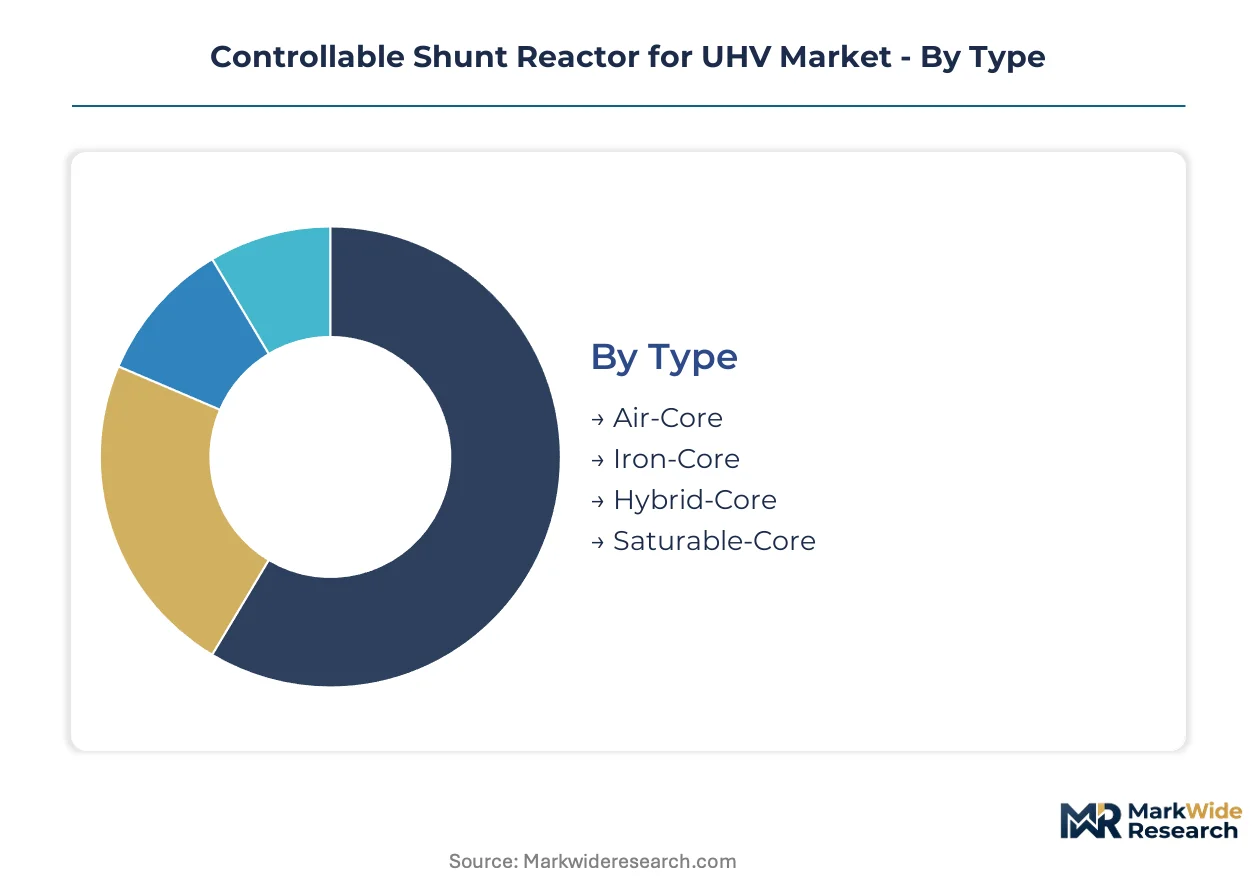
Segmentation in the Controllable Shunt Reactor for UHV market reveals how reactor topology, application context, and procurement channel shape technology selection and margin structure. Each dimension carries distinct certification requirements and competitive dynamics that vendors must navigate.
Type:
Cost tier determines material intensity and switching sophistication across reactor architectures.
- Iron-Core:Laminated grain-oriented electrical steel construction delivers proven thermal performance under continuous 800 kV+ operation. State Grid Corporation of China deploys these units across legacy 1000 kV corridors where harmonic tolerance permits slower mechanical tap-changer response.
- Hybrid-Core:Combined iron-air magnetic circuits achieve sub-cycle voltage stabilization through magnetically controlled excitation. The Yangtze River Delta cluster is absorbing these units fastest as operators replace fixed reactors under MEE efficiency mandates.
- Air-Core:Hollow conductor windings eliminate core saturation limits but demand larger footprint and higher capital outlay.
- Saturable-Core:Magnetic amplifier principles enable stepless reactive power modulation with reduced moving parts.
Iron-Core holds installed capacity. Hybrid-Core is rotating up the share rankings.
Application:
Application context dictates integration complexity and contract bundling potential.
- FACTS Devices:Unified reactive compensation platforms bundle controllable shunt reactors with STATCOM and SVC systems under single procurement frameworks. Transmission operators in China pay premium margins for turnkey FACTS integration that collapses vendor management overhead.
- Voltage Regulation:Dynamic absorption capability suppresses Ferranti effect overvoltage across thousand-kilometer UHV links during light-load conditions. Procurement concentrates in corridors with high renewable intermittency.
- HVDC Systems:Converter station reactive balance requirements drive demand for continuously variable inductive compensation.
- Grid Stability:Wide-area voltage collapse prevention mandates deploy controllable units as spinning reserve equivalents.
FACTS Devices command bundled pricing power. Voltage Regulation is climbing the fastest as a standalone application.
Installation Type:
Volume scale and site constraints differentiate deployment configurations.
- Substation-Level:Dedicated 800 kV+ bay installations accommodate largest unit ratings with full maintenance access. China's provincial grid companies specify these for greenfield UHV hubs.
- Outdoor:Weather-hardened enclosures suit corridor reinforcement projects where building footprint is unavailable. Demand tracks linear UHV expansion across western China transmission highways.
- Indoor:Climate-controlled housings protect thyristor switching electronics in extreme environments.
- On-Structure:Compact designs mount directly on transmission towers for mid-line compensation.
Substation-Level anchors procurement volume. Outdoor is gaining share fastest as retrofit demand accelerates.
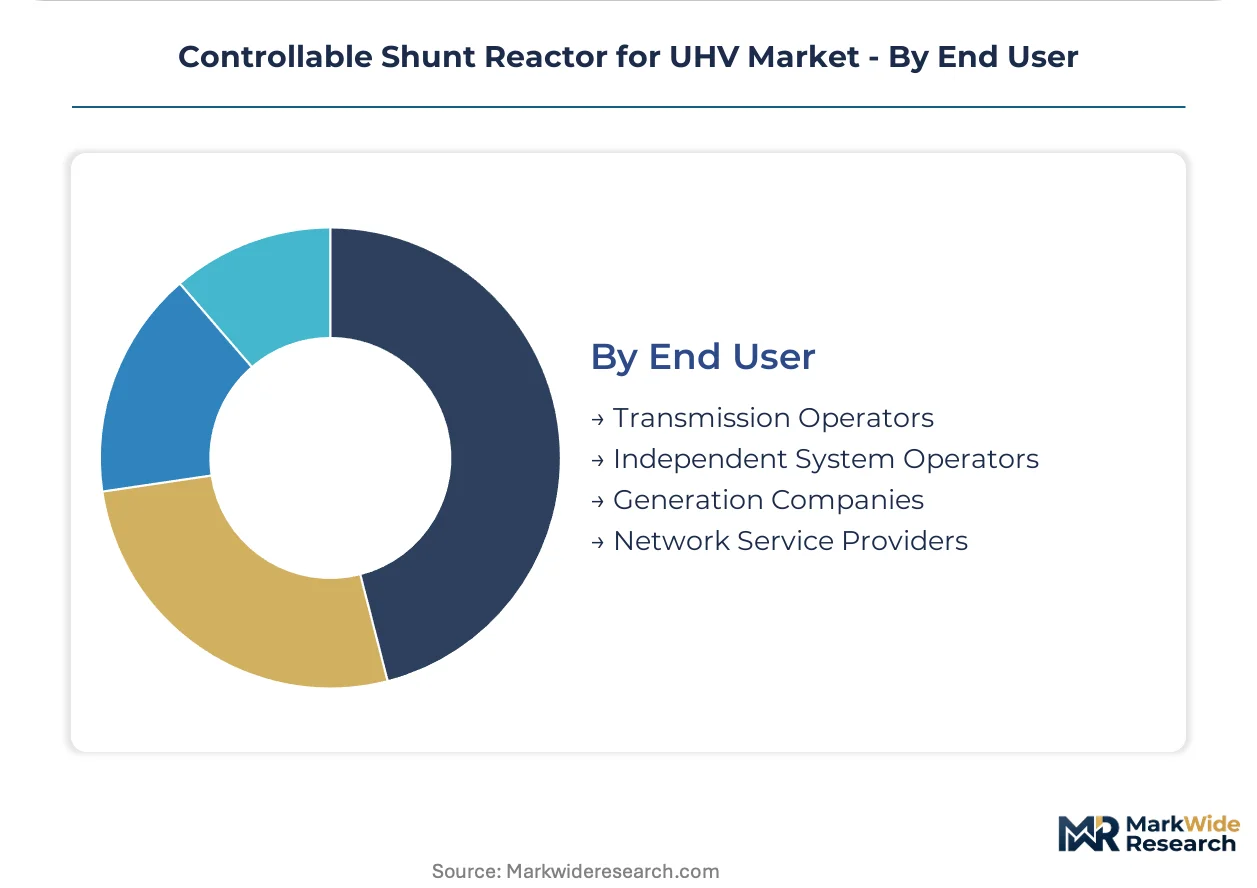
End User:
Customer type shapes contract duration and technical specification authority.
- Transmission Operators:State-owned grid companies in China dominate procurement through multi-year framework agreements bundling equipment with decade-long service contracts. These buyers set GB standards compliance thresholds that filter vendor eligibility.
- Independent System Operators:Regional coordination entities in India are mandating dynamic reactive compensation under revised CEA grid codes for new 765 kV corridors.
- Generation Companies:Utility-scale renewable developers procure controllable units for generator step-up voltage management.
- Network Service Providers:Private transmission concessionaires in select markets specify performance-based availability contracts.
Transmission Operators hold procurement concentration. Independent System Operators are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-owned transmission operators concentrate procurement authority across major UHV corridors. Their framework agreements bundle equipment supply with long-term service contracts, filtering vendor eligibility through compliance thresholds.
China
State Grid Corporation operates the densest 1000 kV network globally. MEE efficiency mandates and dual carbon goals are accelerating replacement of fixed reactors with magnetically controlled variants. The Yangtze River Delta cluster absorbs the highest concentration of new hybrid-core installations.
India
CEA grid code revisions now mandate dynamic reactive compensation for all new 765 kV corridors. Independent system operators are consolidating procurement authority previously fragmented across state utilities. Western transmission highways linking Gujarat to Maharashtra represent the fastest-absorbing corridor cluster.
United States
FERC Order 2023 compliance is driving reactive compensation upgrades across the Eastern Interconnection. Investor-owned utilities are bundling controllable reactor procurement with STATCOM integration for renewable-rich zones. Texas ERCOT territory is absorbing units fastest due to extreme voltage swing conditions.
Germany
The EU F-Gas Regulation is tightening specifications for insulating mediums in UHV substations. Transmission system operators are specifying dry-type alternatives for new corridor reinforcement. Industrial demand in the Rhine-Ruhr cluster is pulling voltage regulation equipment into the highest-density substation network.
Japan
METI grid stability mandates are requiring sub-cycle response capabilities for all new 500 kV+ compensation assets. Domestic suppliers leverage deep integration with demonstration UHV projects to anchor premium positioning. The Kanto-Tokyo corridor maintains the strictest harmonic emission thresholds.
Controllable Shunt Reactor for UHV Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement tiers. The vendor base stratifies into three concentration levels: integrated energy conglomerates with full FACTS portfolios, national champions capturing domestic framework agreements, and specialized reactor manufacturers serving retrofit demand. Two strategic archetypes dominate: vertically integrated power equipment suppliers and magnetics-focused engineering houses. Capacity expansion and technology licensing represent the dominant competitive moves.
Among integrated conglomerates, Hitachi Energy and Siemens Energy exemplify the full-platform archetype, bundling controllable reactors with power electronics and digital control systems. NR Electric occupies a distinct position as a national champion, leveraging deep procurement relationships within China's state grid framework. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning without determining specific technical capabilities or market share.
| Leading Market Players |
|---|
| Hitachi Energy |
| Siemens Energy |
| GE Vernova |
| Toshiba Energy Systems & Solutions |
| NR Electric |
| XD Group |
| TBEA |
| Faramax |
| ASTOR |
| Others |
Pricing and Supply Chain Analysis
Grain-oriented electrical steel tariff exposure determines both pricing tier spreads and supply chain shape across controllable shunt reactor manufacturing. Japanese and European specialty steel producers concentrate supply, forcing OEMs to absorb cost volatility or pass through indexation clauses in long-term transmission operator contracts.
Pricing Analysis
Cost-plus contracts with grain-oriented electrical steel indexation dominate procurement frameworks for 800 kV+ units. Three-tier pricing structure across premium hybrid-core, standard iron-core, and economy fixed-reactor replacement tiers reflects certification grade under GB standards and MEE efficiency mandates. Cost compression in standard iron-core segments is intensifying because Chinese provincial grid companies consolidate multi-year framework agreements. State-owned transmission operators exhibit lowest price sensitivity due to bundled service obligations, while independent renewable developers show highest sensitivity to capital outlay.
Supply Chain Analysis
Contract manufacturing capacity for hybrid-core assemblies concentrates among Japanese electromagnetic specialists and European power equipment foundries. Raw material dependencies center on grain-oriented electrical steel from Nippon Steel and ThyssenKrupp, high-voltage thyristor valves from German and Swiss semiconductor fabricators, and epoxy resin systems for dry-type insulation. Single-source vulnerability in specialty core steel exposes manufacturers to allocation constraints during peak procurement cycles. Distribution runs through direct OEM-transmission operator relationships anchored by decade-long service contracts, with limited spot market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fixed reactor substitution by magnetically controlled variants threatens incumbent iron-core specialists who fail to develop power electronics partnerships. Incumbents must navigate this technology transition while defending installed base maintenance revenue.
For Market Incumbents: Harden technology positioning through backward integration into thyristor switching module design or captive supply of magnetically controlled excitation systems. Secure GB standards recertification ahead of MEE efficiency mandate deadlines to filter competitor eligibility in State Grid framework agreements. Defend against hybrid-core specialists by anchoring long-term service contracts that lock out emerging power electronics partners.
For New Entrants and Emerging Players: Pursue FACTS integration convergence opportunities where bundled STATCOM-SVC-reactor contracts command premium margins from transmission operators seeking unified compensation platforms. Target Indian 765 kV corridor procurement under revised CEA grid codes as the most penetrable geography, leveraging regulatory mandate timing ahead of incumbent response. Lead with magnetically controlled reactor variants featuring sub-cycle response capabilities as the primary go-to-market angle.
For Investors and Strategic Acquirers: China's dual carbon goal enforcement reshapes the acquisition landscape by accelerating fixed reactor replacement cycles and expanding addressable market for variable compensation technologies. Long-term viability centers on platform breadth spanning iron-core legacy maintenance and hybrid-core growth segments. Prioritize targets with deep State Grid relationship infrastructure and in-house electromagnetic simulation capabilities. Monitor CEA grid code implementation pace in India as the critical inflection indicator for geographic diversification value.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Core Technology Licensing | Accelerates OEM access to sub-cycle response capabilities without captive R&D investment. |
| Thyristor Valve Supply Agreement | Secures high-voltage switching module allocation from European semiconductor fabricators. |
| GB Standards Recertification Program | Filters competitor eligibility under revised MEE efficiency mandates for 800 kV+ equipment. |
| FACTS Platform Integration Partnership | Creates turnkey reactive compensation bundles commanding premium pricing from State Grid. |
| Indian Corridor Localization Investment | Positions for CEA-mandated dynamic compensation procurement across 765 kV western highways. |
Research Methodology
Two parallel data streams informed the analysis: primary intelligence gathering and secondary validation. Primary interviews engaged transmission planning officers at State Grid Corporation and provincial grid companies, procurement leads at Indian independent system operators, power electronics engineering directors at FACTS integrators, and aftermarket service heads at reactor OEMs. Secondary sources included IEC 60076-6 test protocol documentation, CEA grid code revision filings, MEE efficiency mandate circulars, and customs trade data for grain-oriented electrical steel imports. Bottom-up unit deployment tracking across 1000 kV and 1100 kV corridors triangulated against top-down market value estimates.
Forecast inputs considered reactor topology substitution rates, UHV corridor buildout schedules, and regulatory mandate implementation timelines across the projection horizon. Segmentation modeling captured type dimension across iron-core, hybrid-core, air-core, and saturable-core architectures; application dimension spanning FACTS devices, voltage regulation, HVDC systems, and grid stability; and end-user dimension across transmission operators, independent system operators, generation companies, and network service providers. CAGRs derived from regression analysis of historical procurement volumes against corridor density and efficiency mandate enforcement intensity.
Sensitivities concentrate around grain-oriented electrical steel price volatility, CEA grid code implementation delays, and hybrid-core manufacturing yield rates. Forecasts reflect assumptions regarding State Grid dual carbon commitment continuity and MEE enforcement rigor. Quarterly review of provincial grid company framework agreement awards and Indian 765 kV corridor tender announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.