
 Asia Pacific Water Meter Market | 2026-2036
Asia Pacific Water Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Water Meter Market Outlook
Scarce calibration technician pools across Southeast Asia is redrawing competitive dynamics for precision instrument suppliers. Diehl Stiftung & Co. KG leverages its in-house metrology academies to sustain technician density in Indonesia and Vietnam. Kamstrup anchors Nordic design-to-cost discipline while competing aggressively on ultrasonic platform pricing. Aichi Tokei Denki Co. Ltd. dominates Japan's domestic replacement cycle through localized manufacturing scale and distributor lock-in arrangements.
Asia Pacific water meters are precision volumetric measurement instruments, typically brass or polymer-bodied with turbine, electromagnetic, or ultrasonic flow sensors, engineered to record potable water consumption across pressurized distribution networks. Smart meters with IoT-enabled radio frequency or cellular communication modules now transmit consumption data in fifteen-minute intervals to utility billing systems. Electromagnetic and ultrasonic segments command premium positioning where accuracy classes below R400 are specified for industrial custody transfer. Smart technology adoption accelerates fastest among municipalities pursuing district metering area strategies to pinpoint leakage. Mechanical meters retain volume dominance in India's price-sensitive residential tier but face margin compression from BIS certification costs.
India's BIS enforces IS 779 and IS 2373 accuracy standards that disqualify uncertified imports, while China's State Administration for Market Regulation (SAMR) mandates pattern approval for all new meter designs entering provincial tenders. Australia's National Measurement Institute (NMI) maintains separate verification protocols that fragment certification economies for multinationals. Stakeholders must weigh the capital cost of dual-certification laboratories against the revenue risk of exclusion from state-level utility procurement frameworks.
Market Dynamics
Utility digitization mandates across Southeast Asia are compressing replacement cycles for legacy mechanical meters while elevating procurement specifications toward AMI-compatible ultrasonic platforms. This structural pivot rewards suppliers with in-house metrology certification capabilities and penalizes import-dependent distributors.
Growth Catalysts
- Non-Revenue Water Targets:Municipal utilities in Indonesia and the Philippines face binding leakage reduction mandates that accelerate smart meter deployment for district metering area segmentation.
- BIS Metrology Upgrades:India's IS 779 and IS 2373 accuracy class revisions disqualify uncertified imports, creating procurement preference for compliant domestic and regional manufacturers.
- Ultrasonic Platform Maturity:Falling sensor production costs enable R400-class residential meters to penetrate China's tier-two city tenders previously dominated by turbine designs.
Market Restraints
- Brass Input Volatility:Copper price fluctuations compress margins for brass-bodied meter producers serving India's price-sensitive residential segment.
- Calibration Technician Scarcity:Indonesia and Vietnam lack sufficient metrology-trained field personnel to support rapid smart meter rollout timelines.
- Pattern Approval Fragmentation:China's SAMR mandates province-level verification that duplicates certification costs for multinationals targeting multiple provincial tenders.
Strategic Opportunities
- Vietnam's AMI Gap:Ho Chi Minh City and Hanoi utilities lag Bangkok and Singapore in smart penetration, creating first-mover advantage for ultrasonic platform suppliers.
- Cellular Module Convergence:NB-IoT and LoRa integration with ultrasonic sensors enables fifteen-minute interval data transmission without proprietary network infrastructure.
- Australia's NMI Pathway:Separate verification protocols create premium positioning for suppliers establishing dedicated certification laboratories serving Oceania utilities.
Industry Challenges
- Legacy Billing System Integration:Southeast Asian utilities operate fragmented CIS platforms that resist standardized AMI data formats, extending deployment timelines.
- Dual-Certification Capex Burden:Establishing BIS and SAMR-compliant testing facilities requires capital commitments that strain mid-tier regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Water Meter Market |
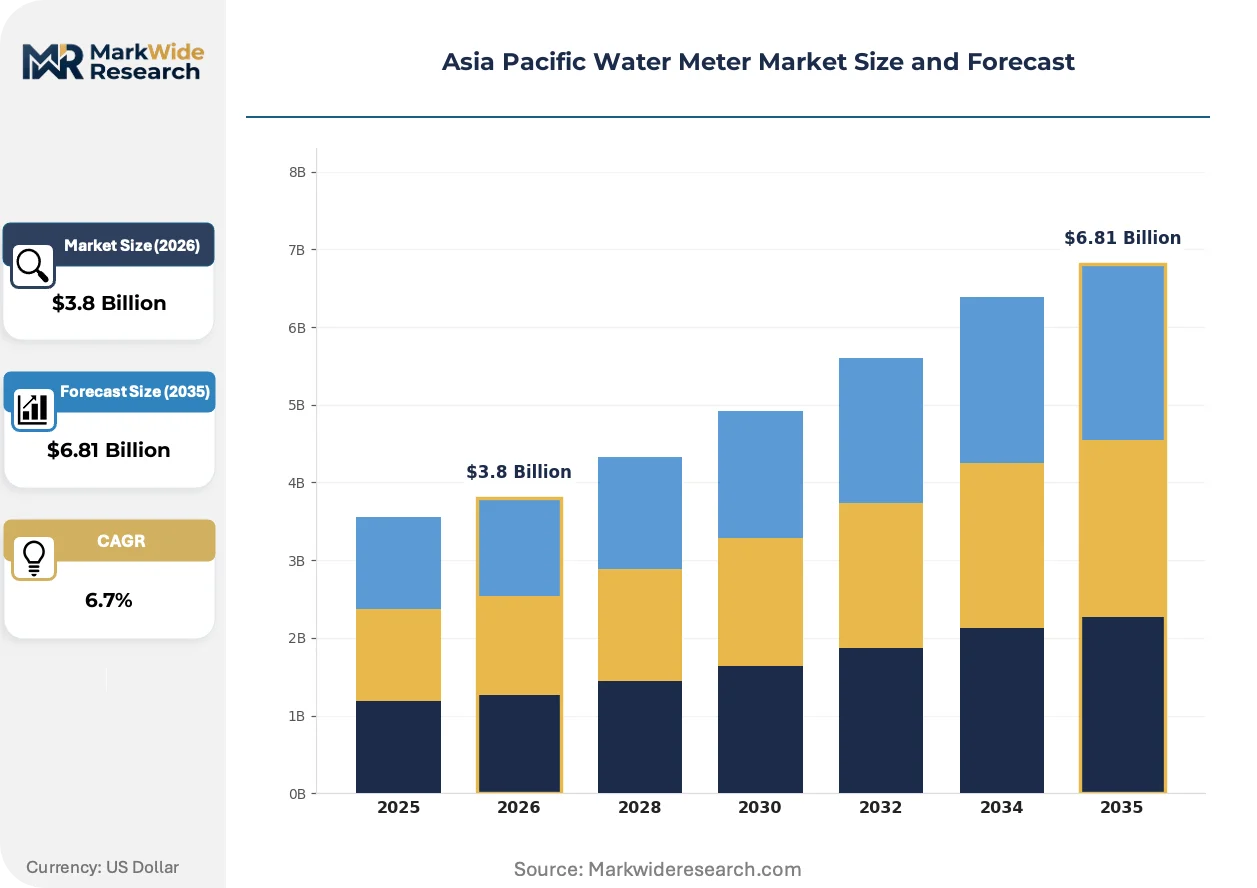
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Electromagnetic, Ultrasonic, Smart End User: Municipalities, Industrial Users, Commercial Establishments, Residential Customers Installation Type: Above Ground, Below Ground, Wall-Mounted, Sub-Metering Technology: Analog, Digital, IoT-Enabled, Remote Reading |
| Companies Covered | Honeywell International Inc., Diehl Stiftung & Co. KG, Arad Group, UPC Instruments Pvt. Ltd., Aichi Tokei Denki Co. Ltd., Badger Meter, Inc., Itron Inc., Kamstrup, Sensus (Xylem Inc.), Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Water Meter Market Strategic Shifts
Measurement technology migration and procurement specification tightening are reconfiguring competitive advantage toward precision engineering capabilities and regulatory compliance infrastructure.
Ultrasonic flow sensing is supplanting mechanical turbine designs in municipal tenders specifying R400 accuracy classes. China's tier-two cities and Australia's state water corporations now mandate solid-state measurement for new installations. This transition compresses revenue for brass-casting suppliers while elevating sensor electronics and firmware development as core competencies.
India's BIS enforcement of IS 779 and IS 2373 disqualifies uncertified imports from domestic procurement. Industrial consequence: regional manufacturers accelerate in-house testing laboratory construction. The residential replacement segment responds by consolidating purchase volumes toward BIS-certified domestic producers with verified metrology chains.
Service unbundling now separates meter hardware from data analytics and leakage detection software. Municipal utilities in Thailand and Malaysia contract AMI platform operators independently of device procurement. This pattern concentrates most visibly in Bangkok's metropolitan water authority, which now sources devices through competitive tender while negotiating data services through separate performance-based agreements.
Asia Pacific Water Meter Market Segmentation
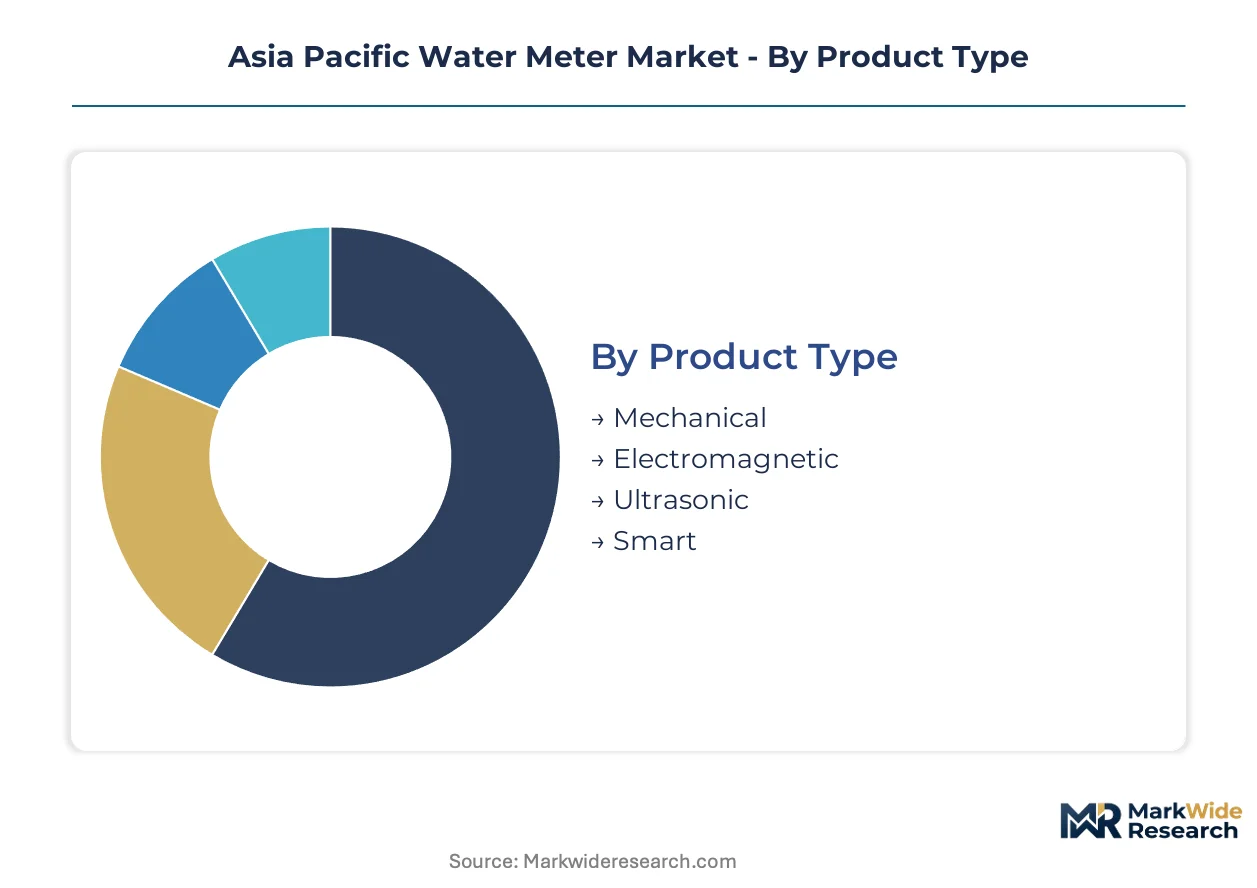
Asia Pacific water meter procurement splits sharply between domestic replacement cycles and export-oriented manufacturing hubs. Understanding these segment boundaries reveals where certification requirements, pricing power, and technology transitions concentrate.
Product Type:
Domestic demand concentrates in mechanical and smart meters across India and Southeast Asia, while electromagnetic and ultrasonic platforms serve industrial custody transfer applications with heavier export orientation toward Australia and Japan.
- Mechanical:Brass or polymer-bodied turbine meters dominate India's price-sensitive residential tier. BIS certification mandates under IS 779 and IS 2373 disqualify uncertified imports, consolidating procurement toward domestic manufacturers with verified metrology chains.
- Smart:IoT-enabled meters with RF or cellular communication modules transmit fifteen-minute consumption intervals to utility billing systems. Municipal digitization budgets in China's tier-two cities and Vietnam's AMI gap create first-mover positioning for platform suppliers with in-house certification capabilities.
- Electromagnetic:Solid-state flow measurement achieves R400 accuracy classes for industrial custody transfer. Demand concentrates in Australia's state water corporations and Japan's precision-oriented utility sector.
- Ultrasonic:Sensor-based volumetric measurement eliminates moving parts. China's SAMR pattern approval requirements and falling production costs enable penetration of tier-two city tenders previously reserved for mechanical designs.
Mechanical meters hold the largest share; momentum sits with smart platforms.
End User:
Cost tier stratification separates municipal bulk procurement from fragmented residential replacement, with industrial users commanding premium specification tolerance.
- Municipalities:District metering area strategies drive AMI deployment for leakage segmentation. Indonesia and the Philippines face binding non-revenue water reduction mandates that compress legacy mechanical replacement cycles.
- Industrial Users:Custody transfer applications specify electromagnetic and ultrasonic platforms below R400 accuracy classes. Australia's NMI verification protocols and Japan's precision standards create dual-certification requirements for multinationals.
- Commercial Establishments:Mid-scale consumption monitoring favors digital migration with moderate accuracy requirements. Bangkok and Singapore utilities lead smart penetration in this segment.
- Residential Customers:Volume dominance in India's tier-three and tier-four cities preserves mechanical meter demand. Brass input volatility compresses margins for producers serving this price-sensitive stratum.
Municipalities anchor procurement volume; industrial users generate margin concentration.
Installation Type:
Application environment dictates material specification and maintenance access requirements across tropical and temperate climate zones.
- Above Ground:Exposed mounting enables technician access for calibration and battery replacement. Vietnam and Indonesia's scarce metrology-trained field personnel favor this accessibility for smart meter rollout timelines.
- Below Ground:Pit installation protects meters from tampering and environmental exposure. China's provincial utilities specify corrosion-resistant polymer housings for high-groundwater regions.
- Wall-Mounted:Compact residential applications in dense urban environments. Singapore and Hong Kong building codes mandate this configuration for space-constrained utility rooms.
- Sub-Metering:Tenant-level consumption allocation in multi-unit commercial and residential developments. Thailand and Malaysia's service unbundling trend separates hardware procurement from data analytics contracts.
Above ground dominates maintenance-accessible markets; sub-metering climbs fastest amid building management digitization.
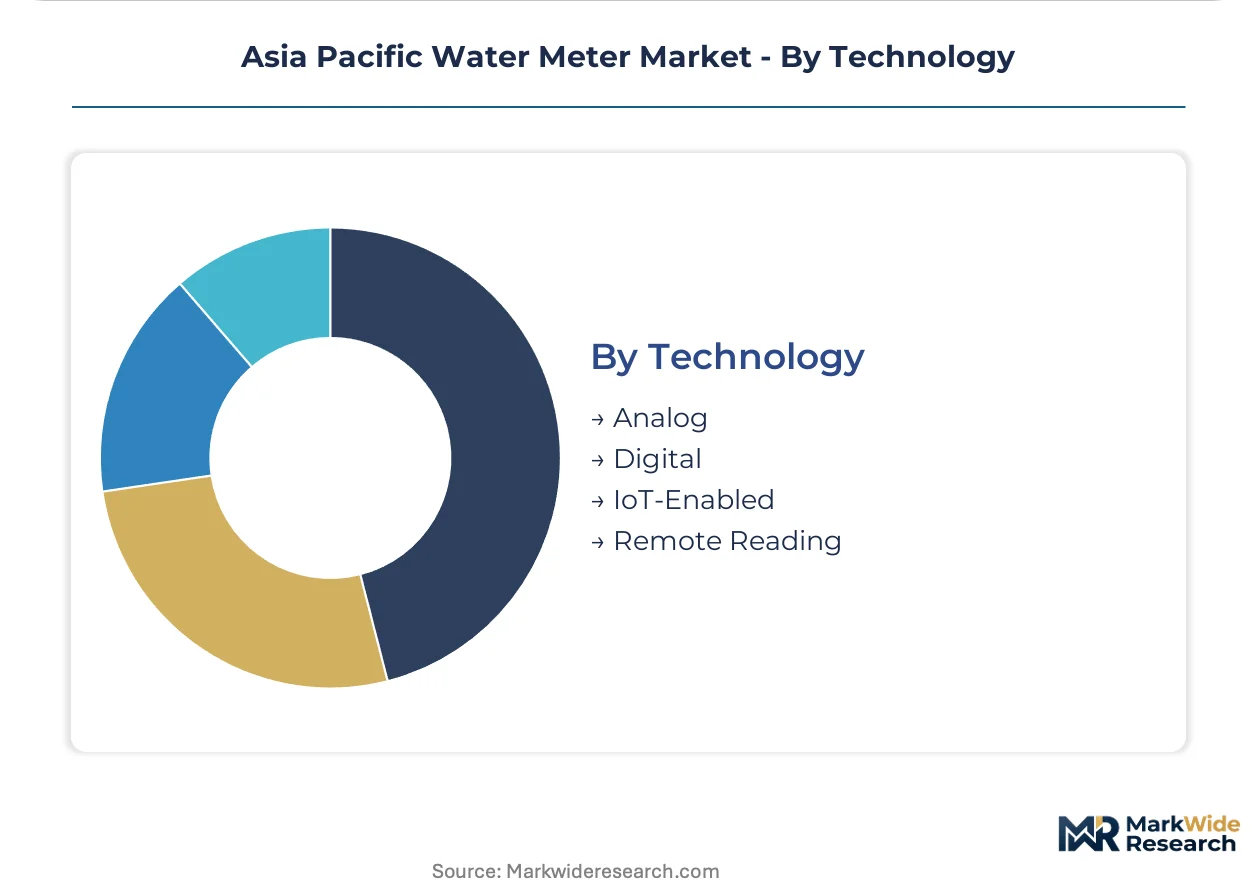
Technology:
Maturity gradient separates legacy analog infrastructure from converging digital and IoT platforms requiring firmware development competency.
- Analog:Mechanical dial displays persist in India's lowest-cost residential segment. BIS accuracy upgrades pressure gradual phase-out despite installed base scale.
- Digital:Electronic registers with LCD displays bridge transition from mechanical to solid-state measurement. China's tier-two cities specify digital readiness for future AMI integration.
- IoT-Enabled:Embedded communication modules enable automated data transmission without manual reading. NB-IoT and LoRa convergence eliminates proprietary network infrastructure requirements for Ho Chi Minh City and Hanoi utilities.
- Remote Reading:Drive-by or fixed-network RF collection systems predate full AMI deployment. Australia's dispersed population centers sustain demand for this intermediate technology tier.
Analog retains residual share; IoT-enabled platforms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's State Administration for Market Regulation anchors procurement governance across the dominant geography. SAMR's pattern approval requirements for provincial tenders create compliance barriers that reshape supplier presence. The region spans five distinct national markets with divergent digitization timelines and certification regimes.
China
Tier-two city utilities accelerate AMI budgets as provincial digitization mandates take effect. SAMR enforces pattern approval verification for each province, duplicating certification costs for multinationals. The Yangtze River Delta cluster concentrates ultrasonic platform manufacturing scale for domestic tender participation.
India
Domestic replacement cycles dominate volume as BIS enforces IS 779 and IS 2373 accuracy standards. The Bureau of Indian Standards disqualifies uncertified imports, consolidating procurement toward compliant regional manufacturers. Maharashtra and Gujarat industrial corridors anchor metrology laboratory construction for certification readiness.
Japan
Precision-oriented utilities drive electromagnetic and ultrasonic demand for industrial custody transfer. METI maintains stringent JIS standards that favor localized manufacturing scale. The Kansai region around Osaka sustains distributor lock-in arrangements for domestic replacement cycles.
Indonesia
Binding non-revenue water reduction mandates accelerate smart meter deployment for district metering area segmentation. Scarce calibration technician pools compress rollout timelines and elevate training infrastructure value. Jakarta's metropolitan water authority leads procurement specification tightening toward AMI-compatible platforms.
Australia
State water corporations mandate solid-state measurement for new installations with R400 accuracy class requirements. The National Measurement Institute maintains separate verification protocols that fragment certification economies. New South Wales and Victoria utilities sustain demand for remote reading systems amid dispersed population centers.
Asia Pacific Water Meter Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with certification infrastructure separating the tiers. Brass-casting scale and sensor electronics capability define divergent competitive positions. Three archetypes populate the landscape: metrology-integrated multinationals, regional certification specialists, and component-scale fabricators. Capacity expansion in testing laboratories and strategic partnerships for cellular module integration represent the dominant competitive moves.
Among Germany-based integrated groups, Diehl Stiftung & Co. KG exemplifies the metrology-integrated archetype through in-house academy structures. Denmark-based Kamstrup occupies a position on the Nordic design-to-cost vector, while Aichi Tokei Denki Co. Ltd. anchors the Japan-focused specialist tier. These three represent distinct geographic and capability positioning within the regional competitive set.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Diehl Stiftung & Co. KG |
| Arad Group |
| UPC Instruments Pvt. Ltd. |
| Aichi Tokei Denki Co. Ltd. |
| Badger Meter, Inc. |
| Itron Inc. |
| Kamstrup |
| Sensus (Xylem Inc.) |
| Others |
Value Chain & Pricing Dynamics
Brass-casting scale economies in India's domestic manufacturing cluster establish price floors for mechanical meters while compressing margins for import-dependent distributors. China's Yangtze River Delta sensor production concentration simultaneously drives ultrasonic platform cost curves downward, reshaping procurement specifications across Southeast Asian municipal tenders.
Pricing Analysis
China's tier-two cities command 15-25% premiums over India's price-sensitive residential tier for AMI-compatible ultrasonic platforms. Pricing stratifies across R400-class industrial custody transfer, municipal bulk procurement, and economy mechanical residential tiers, with BIS certification costs and brass input volatility squeezing margins at the bottom. Cost compression in India's mechanical segment intensifies because copper price fluctuations transfer directly to brass-bodied meter producers. Municipal utilities in Indonesia and the Philippines demonstrate lowest price sensitivity due to binding non-revenue water mandates, while India's tier-three residential replacement cycles exhibit acute cost consciousness.
Supply Chain Analysis
China and Japan anchor electromagnetic and ultrasonic sensor fabrication for precision custody transfer applications, while India's Maharashtra-Gujarat corridor concentrates brass-casting and mechanical meter assembly. Component sourcing draws from Taiwan for cellular communication modules, Germany for precision metrology instrumentation, and South Korea for polymer housing materials. Single-source vulnerability concentrates in ultrasonic transducer supply chains where Japanese and German component specialists dominate. Distribution runs through state-level utility procurement frameworks in China, municipal water authority tenders across Southeast Asia, and distributor lock-in arrangements in Japan's Kansai region.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific water meter market is entering a cyclical recovery phase as municipal digitization mandates deferred during procurement budget constraints now accelerate replacement cycles. India's BIS enforcement timeline and China's SAMR provincial tender expansion provide the cyclical impetus.
For Market Incumbents: Fortify certification infrastructure through in-house metrology academy construction in Indonesia and Vietnam to address calibration technician scarcity threatening rollout timelines. Deepen backward integration into ultrasonic sensor production to offset brass input volatility compressing mechanical meter margins. Prioritize BIS and SAMR dual-certification laboratory investment to defend against exclusion from state-level procurement frameworks. For New Entrants and Emerging Players: Lead with Vietnam's AMI gap in Ho Chi Minh City and Hanoi, where smart penetration lags Bangkok and Singapore by 3-5 years, creating first-mover positioning for NB-IoT integrated ultrasonic platforms. Target Australia's NMI verification pathway as a premium positioning opportunity requiring dedicated certification infrastructure that multinationals have underinvested in. Pursue service unbundling contracts separating meter hardware from data analytics to bypass established distributor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors metrology-integrated specialists with in-house certification capabilities over import-dependent distributors facing pattern approval fragmentation. Long-term viability over the next decade rests on suppliers capturing the transition from mechanical to solid-state measurement platforms. Acquisition target archetype: regional manufacturers with BIS-compliant testing facilities and verified supply chains serving India's domestic replacement cycle. The signal to watch is SAMR province-level tender volume acceleration in China's tier-two cities as digitization mandates take effect.| Strategic Initiative | Industry Significance |
|---|---|
| Metrology Laboratory Construction | BIS and SAMR dual-certification capabilities unlock state-level procurement frameworks across India and China. |
| Ultrasonic Platform Scale-Up | R400-class residential meter production cost curves enable penetration of tier-two city tenders previously reserved for mechanical designs. |
| Cellular Module Integration Partnership | NB-IoT and LoRa convergence eliminates proprietary network infrastructure requirements for Vietnam's AMI gap. |
| Calibration Technician Training Academy | In-house metrology academies address scarce technician pools compressing smart meter rollout timelines in Indonesia. |
| Service Unbundling Contract Structure | Separate hardware procurement from data analytics performance agreements mirrors Bangkok metropolitan water authority's procurement pattern. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with utility procurement officers, metrology laboratory directors, and water authority planning officials across China, India, Indonesia, and Australia; and secondary validation through SAMR pattern approval filings, BIS certification registries, state water corporation tender documents, and municipal digitization budget disclosures. Bottom-up triangulation across manufacturer shipment data and top-down reconciliation against utility capex plans anchored volume and value estimates.
Across the projection horizon, the analytical framework modeled demand by product type, end-user segment, installation configuration, and technology platform maturity, with CAGRs derived from regression analysis of historical replacement cycles against regulatory enforcement timelines. Forecast inputs incorporated provincial digitization mandate schedules, copper price trajectory assumptions, and technician training pipeline capacity in Southeast Asia.
Forecasts assume regulatory continuity in India's BIS enforcement regime and China's SAMR pattern approval requirements; material policy shifts in certification standards or import restrictions would require re-modeling. Recalibration cycles align with material shifts in municipal budget allocation patterns and metrology standard revision announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Electricity Meters (Smart Meters) Market
Smart Meters
Smart Meters Market
Smart Meters
US Water Meter Market
Smart Meters
North America Smart Meter Data Management Market
Smart Meters
LNG Metering Skids Market
Smart Meters
United States (US) Residential Smart Meters Market
Smart Meters
South and Central America Smart Metering Market
Smart Meters
Industrial Power Monitoring System Market
Smart Meters
Single-Phase Anti-Theft Meter Market
Smart Meters
Europe Water Meter Market
Smart Meters
Residential RF Smart Electric Meter Market
Smart Meters
Solar Meter Market
Smart Meters
Smart Meter Battery Market
Smart Meters
Commercial Non IC Card Gas Smart Meter Sales Market
Smart Meters
Smart Meter Data Management Market
Smart Meters
Smart Metering Systems Market