
 Middle-East and Africa Power Market | 2026-2036
Middle-East and Africa Power Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Power Market Foresight
The capital-intensity gap between integrated utility-scale developers and pure-play equipment suppliers is collapsing as project finance structures demand bundled engineering-procurement-construction capabilities. ACWA Power leverages its balance-sheet depth to originate multi-gigawatt pipelines across Saudi Arabia, Egypt, and Morocco. Eskom Holdings SOC Ltd anchors South Africa's baseload fleet while navigating structural reform mandates. Masdar competes aggressively on green hydrogen-linked power offtake structures in the UAE and beyond.
Middle-East and Africa power encompasses electricity production, delivery infrastructure, and grid management systems spanning thermal, renewable, and emerging hybrid architectures, with generation assets typically sized from distributed kilowatt-scale installations to centralized multi-gigawatt complexes serving industrial, municipal, and export markets. Natural gas retains primacy in Gulf Cooperation Council baseload planning, though solar capacity additions now outpace conventional permits across North African markets. Smart Grid technology commands disproportionate capital attention where utilities seek to reduce technical losses exceeding fifteen percent in legacy distribution networks. The Storage application dimension remains structurally underdeveloped relative to Generation, creating margin concentration for early movers securing lithium-ion or flow battery supply agreements.
CEA guidelines in South Africa, Egypt's NREA licensing protocols, and UAE regulatory frameworks administered by the Emirates Water and Electricity Company collectively shape developer qualification standards, local content thresholds, and tariff approval timelines. These bodies enforce divergent grid-code compliance requirements that fragment equipment sourcing strategies across jurisdictions. Stakeholders must monitor which regulatory regimes tighten carbon-intensity benchmarks fastest, as this determines where capital deployment yields permitted, bankable projects.
Market Dynamics
Data center operators across Gulf Cooperation Council states are scaling captive power purchases to match digital infrastructure buildouts, while Saudi Arabia's renewable energy localization mandates redirect procurement toward domestic-content-compliant developers. This dual pressure is compressing project timelines and reshaping developer qualification standards.
Growth Catalysts
- Renewable Portfolio Mandates:Saudi Arabia's regulatory push under localization requirements is redirecting procurement toward domestic-content-compliant developers, accelerating indigenous manufacturing capacity.
- Data Center Buildouts:Hyperscale facility operators in the UAE are signing long-term power purchase agreements that anchor multi-gigawatt generation pipelines.
- Solar Cost Parity:Photovoltaic levelized costs in North African markets now undercut combined-cycle gas economics, permitting solar capacity additions to outpace conventional permits.
Market Restraints
- Lithium-Ion Supply Concentration:Battery storage deployment faces structural constraints from concentrated cathode supply chains, limiting grid-scale project execution timelines.
- Technical Loss Burden:Legacy distribution networks across Egypt and Nigeria exhibit technical losses exceeding fifteen percent, eroding revenue recovery and deterring private capital.
- Gas Price Volatility:Combined-cycle plant economics remain exposed to liquefied natural gas spot price swings, complicating long-term tariff negotiations.
Strategic Opportunities
- Green Hydrogen Export Hubs:Morocco and Egypt are positioning electrolyzer-anchored industrial zones to capture European offtake demand under EU Green Deal hydrogen import quotas.
- Smart Grid Retrofits:Utilities in South Africa and Kenya are deploying advanced metering infrastructure to reduce commercial losses and enable demand response revenue streams.
- Hybrid Mini-Grids:Solar-plus-storage architectures are penetrating rural electrification programs in Ethiopia and Tanzania where grid extension remains uneconomical.
Industry Challenges
- Grid Code Fragmentation:Divergent interconnection standards enforced by South Africa's CEA, Egypt's NREA, and UAE's EWEC fragment equipment sourcing strategies and inflate engineering costs.
- Local Content Compliance:Developers must navigate conflicting domestic manufacturing thresholds across Saudi Arabia, Morocco, and Egypt, complicating pan-regional procurement.
- Technical Workforce Scarcity:Specialized commissioning expertise for inverter-based resources remains concentrated in European and East Asian labor pools, extending project ramp periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Power Market |
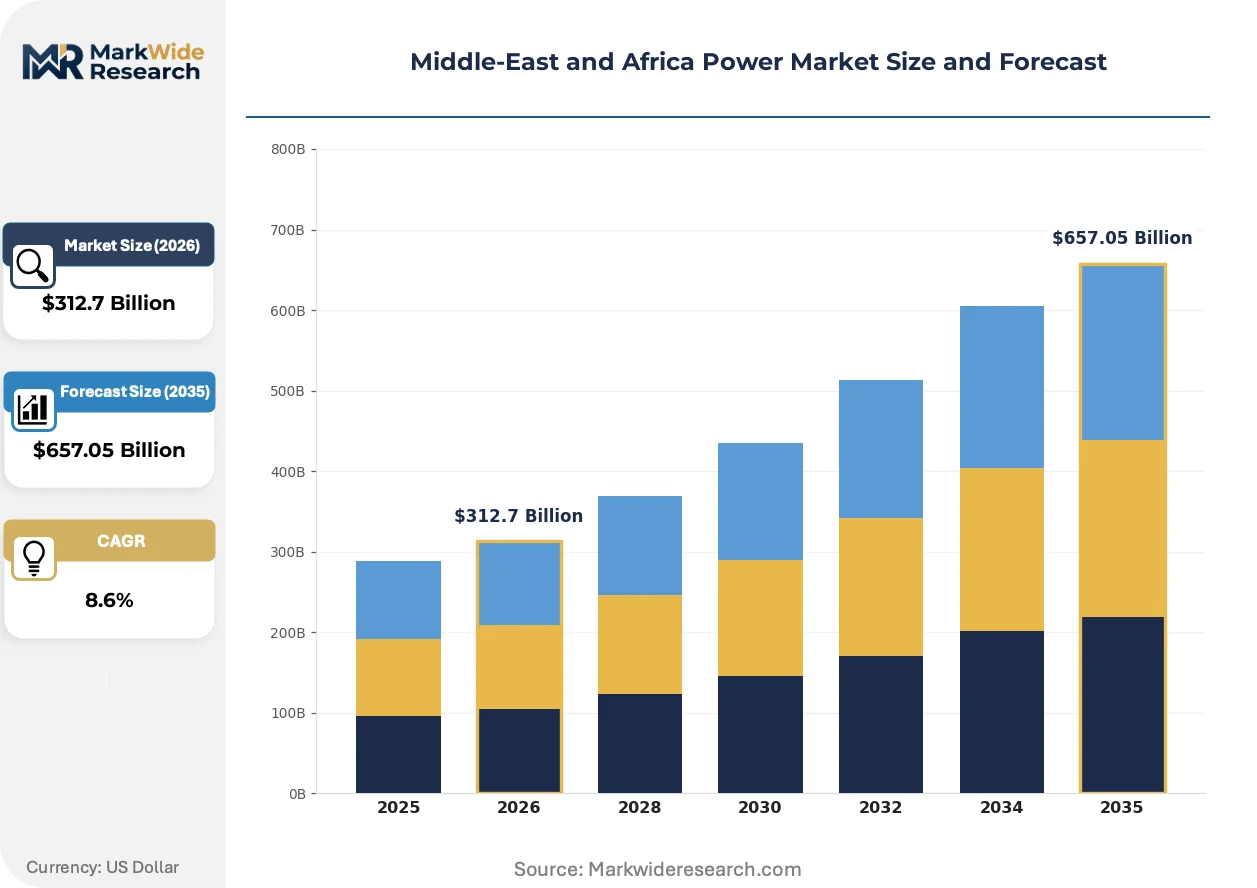
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $657.05 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Solar, Wind, Hydropower, Natural Gas End User: Industrial, Commercial, Residential, Government Application: Generation, Transmission, Distribution, Storage Technology: Smart Grid, Conventional, Renewable, Hybrid |
| Companies Covered | ACWA Power, Dubai Electricity and Water Authority, Eskom Holdings SOC Ltd, Saudi Electricity Company, Masdar, JinkoSolar Holding Co Ltd, Canadian Solar Inc, First Solar Inc, AMEA Power, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Power Market Shifts & Advancements
Digitization of asset management and modular system architectures are compressing deployment cycles across generation and grid infrastructure. These shifts favor developers with integrated engineering capabilities over pure equipment vendors.
Bifacial photovoltaic modules with tracking systems are decomposing the traditional cost advantage of single-axis fixed-tilt installations in Saudi Arabia's utility-scale solar program. ACWA Power and Masdar are deploying these configurations in the kingdom's renewable energy project office auctions, collapsing the levelized cost spread between premium and standard tier performance. This technology is decomposing the historical segmentation between high-efficiency and commodity module suppliers.
South Africa's CEA has tightened grid code compliance requirements for inverter-based resources, mandating enhanced fault ride-through capabilities and reactive power support. The regulation forces retrofit investments across existing photovoltaic and wind fleets while embedding compliance costs into new project development budgets. Independent power producers are responding by procuring power conversion systems from vendors with pre-certified platform architectures.
Data center operators in the UAE are unbundling traditional utility service models, contracting directly with independent power producers for dedicated renewable supply. This bypasses Emirates Water and Electricity Company tariff structures and enables carbon-free energy claims for hyperscale tenants. The shift is most visible in Dubai's Mohammed bin Rashid Al Maktoum Solar Park vicinity, where co-located facilities anchor captive offtake agreements.
Middle-East and Africa Power Market Segmentation
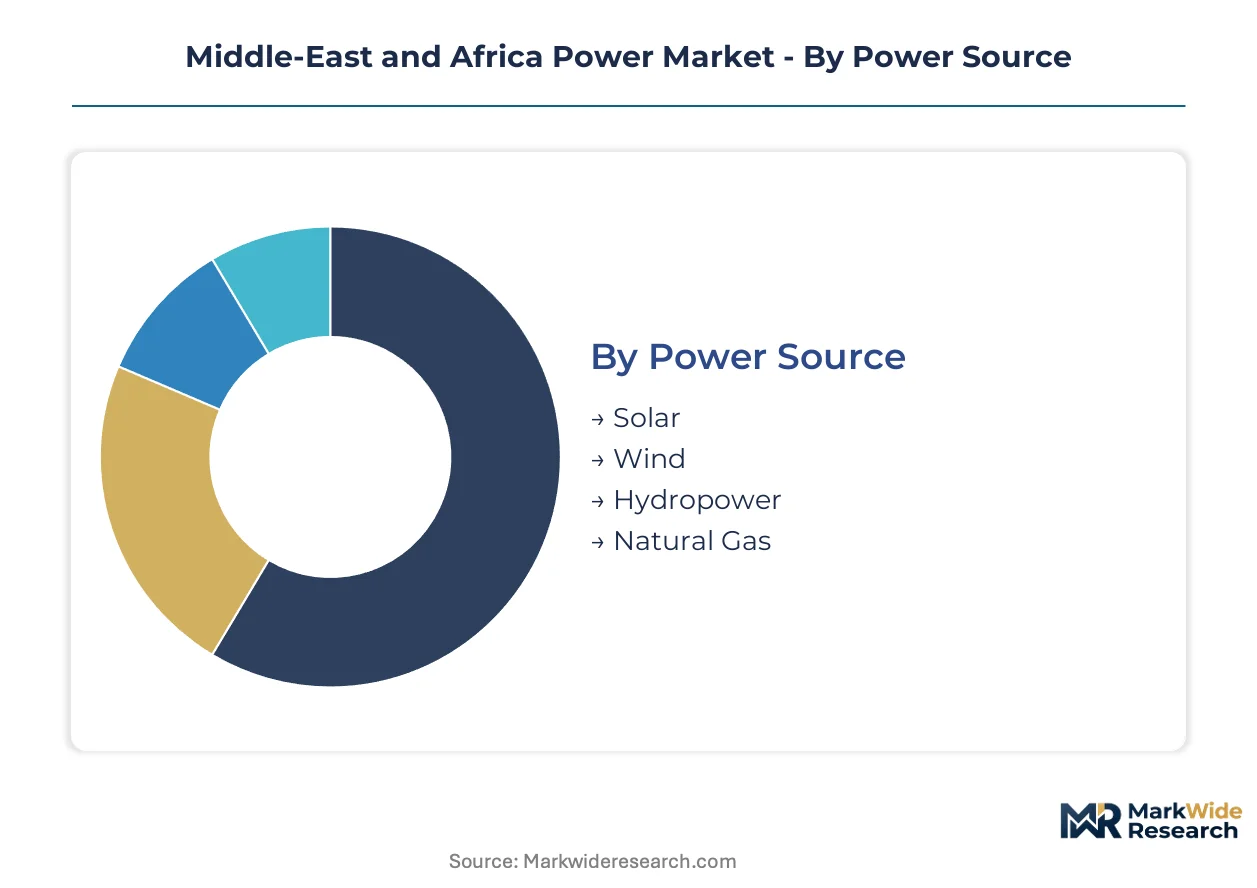
Power market segmentation across the Middle-East and Africa reveals divergent capital allocation patterns between Gulf Cooperation Council hydrocarbon economies and North African renewable front-runners. Channel structures vary sharply by segment, with captive industrial offtake dominating gas-fired generation while merchant solar flows through utility procurement frameworks.
Power Source:
Channel flows split between bilateral industrial contracts for thermal assets and competitive auctions for renewable capacity, with distinct financing structures governing each pathway.
- Solar:Photovoltaic installations deploy bifacial modules with tracking systems across Saudi Arabia's renewable energy project office auctions and the UAE's independent power producer frameworks. Demand concentrates in Dubai's Mohammed bin Rashid Al Maktoum Solar Park vicinity, where data center operators contract directly for dedicated renewable supply.
- Natural Gas:Combined-cycle turbines anchor baseload planning across Gulf Cooperation Council states, though project economics remain exposed to liquefied natural gas spot price volatility. Procurement flows through Emirates Water and Electricity Company tariff structures and bilateral industrial agreements.
- Wind:Onshore developments concentrate in Egypt's Gulf of Suez zone and Morocco's trade wind corridors, with offtake structured through national utility power purchase agreements.
- Hydropower:Large-scale assets in Ethiopia's Blue Nile basin and Zambia's Kariba complex serve regional export markets through interconnected transmission pools.
By volume, natural gas leads. By growth pace, solar is expanding most quickly.
End User:
Cost tiers stratify sharply, with industrial offtakers commanding priority dispatch and residential segments absorbing cross-subsidy burdens in regulated markets.
- Industrial:Aluminum smelters, petrochemical complexes, and desalination plants in Saudi Arabia and the UAE procure captive power through long-term agreements, bypassing utility intermediaries. Green hydrogen export hubs in Morocco and Egypt anchor electrolyzer-anchored demand clusters.
- Commercial:Hyperscale data center operators across Gulf Cooperation Council states scale renewable power purchases to match digital infrastructure buildouts, unbundling traditional utility service models.
- Residential:Grid-connected households in South Africa and Kenya benefit from smart metering deployments that reduce commercial losses, while rural electrification programs in Ethiopia and Tanzania rely on solar-plus-storage mini-grids.
- Government:Municipal loads and public infrastructure across Egypt and Nigeria strain legacy distribution networks exhibiting technical losses exceeding fifteen percent.
Industrial offtake commands the highest tariffs. Residential electrification programs show the steepest expansion trajectory in connection numbers.
Application:
Margin concentration varies by infrastructure maturity, with generation assets attracting developer competition while transmission and storage segments face supply-constrained execution timelines.
- Generation:Multi-gigawatt complexes serve industrial, municipal, and export markets through thermal, renewable, and hybrid architectures. ACWA Power and Masdar originate pipelines across Saudi Arabia, Egypt, and Morocco leveraging balance-sheet depth.
- Storage:Lithium-ion and flow battery supply agreements remain structurally underdeveloped relative to generation, creating margin concentration for early movers securing cathode supply chains.
- Transmission:High-voltage interconnectors link North African solar zones to European offtake markets under EU Green Deal hydrogen import quotas.
- Distribution:Smart Grid retrofits target technical loss reduction in South Africa and Kenya, deploying advanced metering infrastructure to enable demand response revenue streams.
Generation commands current capital deployment. Storage is gaining share fastest as grid-scale project timelines compress.
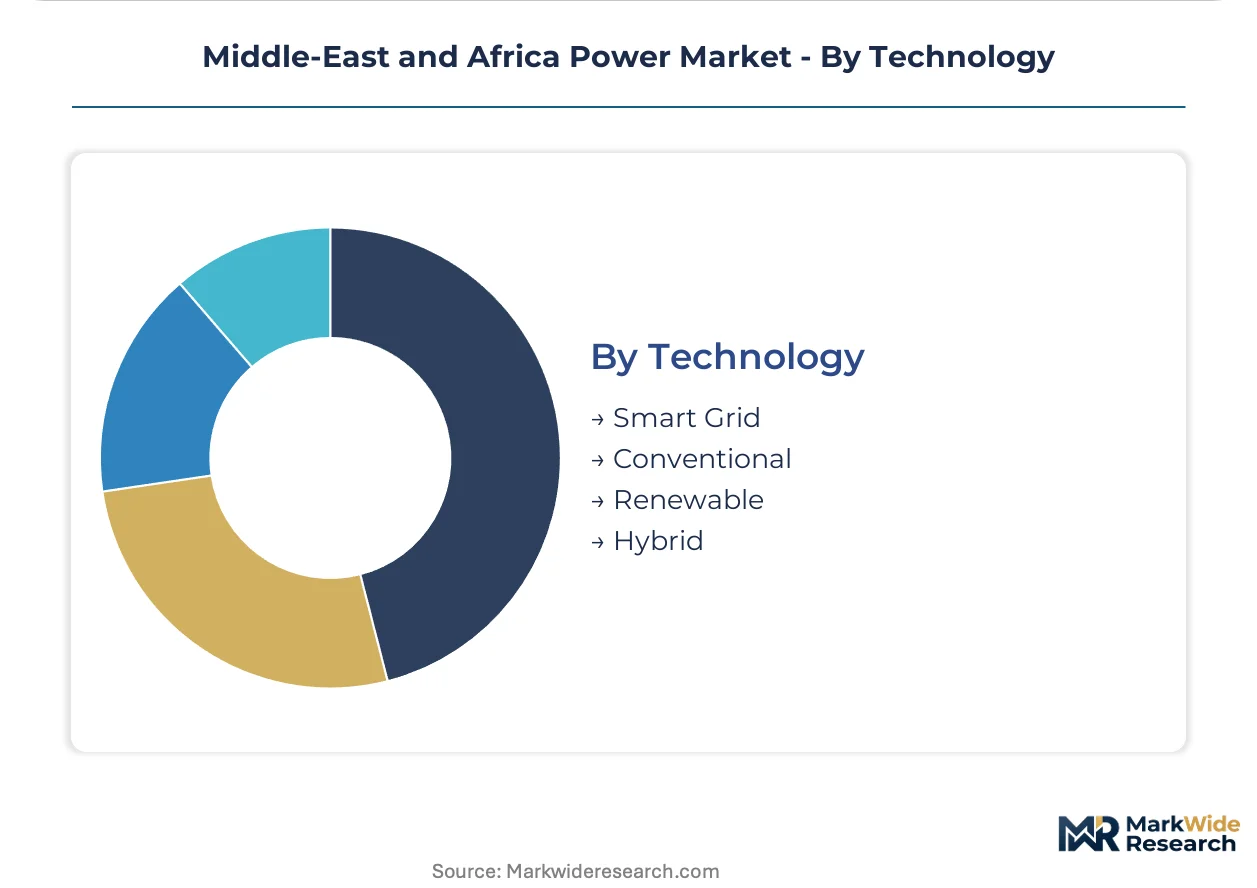
Technology:
Application context determines technology selection, with urban utilities favoring Smart Grid architectures while rural programs default to modular hybrid systems.
- Smart Grid:Advanced metering infrastructure and demand response platforms deploy across South Africa's CEA-regulated networks and Kenya's commercial loss reduction programs.
- Renewable:Inverter-based resources face tightened grid code compliance requirements mandating enhanced fault ride-through capabilities across existing photovoltaic and wind fleets.
- Hybrid:Solar-plus-storage architectures penetrate rural electrification programs in Ethiopia and Tanzania where grid extension remains uneconomical.
- Conventional:Thermal baseload assets in Egypt and Nigeria exhibit legacy distribution network constraints that erode revenue recovery.
Conventional technology retains installed capacity leadership. Hybrid configurations are climbing the fastest as modular deployment cycles compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Egypt and Nigeria exhibit acute price sensitivity where legacy distribution losses erode revenue recovery, while UAE and Saudi industrial offtakers absorb premium tariffs for dedicated renewable supply and captive reliability.
Saudi Arabia
Renewable energy localization mandates redirect procurement toward domestic-content-compliant developers, accelerating indigenous manufacturing capacity. The renewable energy project office enforces local content thresholds that reshape developer qualification standards. Riyadh and the Eastern Province host multi-gigawatt solar pipelines where ACWA Power originates bundled engineering-procurement-construction projects.
United Arab Emirates
Hyperscale data center operators scale captive power purchases to match digital infrastructure buildouts, unbundling traditional utility service models. Emirates Water and Electricity Company administers tariff structures and independent power producer frameworks that attract regional and international capital. Dubai's Mohammed bin Rashid Al Maktoum Solar Park vicinity anchors co-located facilities signing dedicated renewable offtake agreements.
South Africa
Structural reform mandates reshape baseload fleet planning while commercial loss reduction programs deploy advanced metering infrastructure. The Central Energy Authority tightens grid code compliance requirements for inverter-based resources, mandating enhanced fault ride-through capabilities. Industrial clusters around Johannesburg and Cape Town strain legacy distribution networks as independent power producers procure pre-certified power conversion systems.
Egypt
National utility power purchase agreements structure offtake for onshore wind developments in the Gulf of Suez zone. The New and Renewable Energy Authority licensing protocols enforce divergent interconnection standards that fragment equipment sourcing strategies. The Suez Canal Economic Zone positions electrolyzer-anchored industrial zones to capture European hydrogen import demand.
Morocco
Trade wind corridors concentrate onshore wind capacity while green hydrogen export hubs target EU Green Deal hydrogen import quotas. The national utility procurement frameworks compete with bilateral industrial agreements for developer attention. Ouarzazate and Tangier anchor solar and wind complexes serving both domestic load and export-oriented industrial zones.
Middle-East and Africa Power Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle-East and Africa power market. Integrated utility-scale developers with balance-sheet depth compete against pure-play equipment suppliers as project finance structures demand bundled capabilities. The market structure stratifies into three archetypes: Gulf-based sovereign-linked developers with multi-gigawatt pipelines, international module suppliers capturing auction volumes, and regional utilities navigating structural reform mandates. Dominant competitive moves include strategic partnerships for cathode supply chain security and geographic expansion into green hydrogen-linked offtake structures.
Within the sovereign-linked developer tier, ACWA Power and Masdar exemplify balance-sheet-driven pipeline origination across Saudi Arabia, Egypt, and Morocco. Eskom Holdings SOC Ltd anchors South Africa's baseload fleet while navigating structural reform mandates. Among international module suppliers, JinkoSolar Holding Co Ltd and Canadian Solar Inc occupy positions serving competitive auction volumes across North African markets.
| Leading Market Players |
|---|
| ACWA Power |
| Dubai Electricity and Water Authority |
| Eskom Holdings SOC Ltd |
| Saudi Electricity Company |
| Masdar |
| JinkoSolar Holding Co Ltd |
| Canadian Solar Inc |
| First Solar Inc |
| AMEA Power |
| Others |
Supply & Pricing Matrix
Multi-gigawatt pipeline scale economies in Saudi Arabia's renewable energy project office auctions compress balance-sheet barriers for integrated developers while establishing price floors that pure-play equipment vendors struggle to match. This scale concentration reshapes procurement leverage across the Middle-East and Africa power market, tilting contract awards toward bundled engineering-procurement-construction capabilities and squeezing margins for unintegrated suppliers.
Pricing Analysis
After-sales service revenue from long-term operations and maintenance contracts drives lifetime value for independent power producers across Gulf Cooperation Council markets. Contract-based long-term offtake structures dominate, with price differentiation resting on local content compliance thresholds and grid-code certification tiers enforced by Saudi Arabia's renewable energy project office and South Africa's Central Energy Authority. Pricing pressure stems from bifacial photovoltaic module commoditization collapsing spreads between premium and standard performance tiers. Industrial offtakers in the UAE absorb premium tariffs for captive renewable supply, while buyers in Egypt and Nigeria exhibit acute price sensitivity where legacy distribution losses erode revenue recovery.
Supply Chain Analysis
Strategic stockpiling of lithium-ion cathode materials and power conversion systems prevails over just-in-time preferences as developers buffer against concentrated East Asian supply chains. Manufacturing concentrates in China, South Korea, and Japan for battery cells and inverters, while module assembly feeds from Southeast Asian hubs. Raw material dependencies span polysilicon, lithium carbonate, and rare earth magnets for permanent-magnet generators. Single-source vulnerability in cathode precursor supply creates execution risk for grid-scale storage timelines. Distribution runs through Emirates Water and Electricity Company procurement frameworks in the UAE and bilateral industrial agreements across Saudi Arabia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle-East and Africa power market sits in early-cycle expansion as renewable capacity additions outpace conventional permits across North African markets and green hydrogen export hubs capture European offtake demand.
For Market Incumbents: Fortify balance-sheet depth to originate multi-gigawatt pipelines under Saudi Arabia's localization mandates, securing domestic-content-compliant manufacturing partnerships before qualification standards tighten. Deepen engineering-procurement-construction integration to defend margin position against pure-play equipment vendors as project finance structures demand bundled capabilities. Prioritize cathode supply chain security through strategic offtake agreements with East Asian producers. For New Entrants and Emerging Players: Differentiate on smart grid retrofit capabilities targeting South Africa and Kenya's commercial loss reduction programs, where technical losses exceeding fifteen percent create urgent demand for advanced metering infrastructure. Penetrate Ethiopia and Tanzania's rural electrification white space with solar-plus-storage hybrid mini-grids where grid extension remains uneconomical. Pursue direct data center captive power contracts in the UAE to bypass traditional utility intermediaries. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated developers with pre-certified inverter platforms and green hydrogen-linked offtake structures over pure-play module suppliers facing commoditization. Long-term viability over the next decade hinges on regulatory capture in jurisdictions tightening carbon-intensity benchmarks fastest. Target acquisition archetypes: sovereign-linked developers with established regulatory relationships in Saudi Arabia, Egypt, and Morocco. Watch for inflection in EU Green Deal hydrogen import quota implementation as demand signal for electrolyzer-anchored industrial zones.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Structuring | Long-term offtake contracts with UAE data center operators anchor project finance. |
| Backward Integration into Cathode Supply | Direct lithium precursor agreements reduce grid-scale storage execution risk. |
| Green Certification Program | EU Green Deal compliance unlocks European hydrogen export quotas for Moroccan hubs. |
| Technology Licensing | Bifacial tracking system IP transfers accelerate Saudi auction competitiveness. |
| Capacity Buildout | Multi-gigawatt solar pipelines in Riyadh and Eastern Province capture localization premiums. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EIA data, IEA reports, and project development databases to construct bottom-up and top-down triangulated estimates. Primary interviews engaged utility planning officers, independent power producer project developers, engineering-procurement-construction contractors, and grid operators across Saudi Arabia, the UAE, South Africa, Egypt, and Morocco. Secondary validation incorporated FERC filings where relevant to international developer participation, national regulatory submissions to Saudi Arabia's renewable energy project office, and Emirates Water and Electricity Company procurement disclosures.
Segmentation dimensions modeled span fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type across the analysis window. CAGRs derive from capacity deployment trajectories, tariff evolution under competitive auction mechanisms, and industrial offtake demand curves. Forecast inputs incorporate hyperscale data center power demand projections and green hydrogen electrolyzer capacity announcements targeting European export markets.
Material uncertainties — regulatory localization threshold revisions, lithium-ion supply chain disruptions, and gas price volatility — sit outside the modeled envelope. Forecasts reflect assumptions around grid code harmonization timelines and carbon-intensity benchmark adoption rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Solar UPS Market
Power
Wireless Power Receiver Market
Power
Malaysia Power EPC Market
Power
Europe Frequency Converter Market
Power
Controllable Shunt Reactor for UHV Market
Power
Resonant Power Converters Market
Power
Middle East and Africa Combined Heat & Power Market
Power
North America CHP Market
Power
Rotating Phase Converter Market
Power
Asia-Pacific Power Purchase Agreement Market
Power
Modular PSA Nitrogen Generator Market
Power
Power Rental Market
Power
Norway Power Market
Power
Canada Thermal Power Market
Power
Modified Sine Wave Home Inverters Market
Power
Denmark Power Market