
 Power Rental Market | 2026-2036
Power Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Power Rental Market Analysis
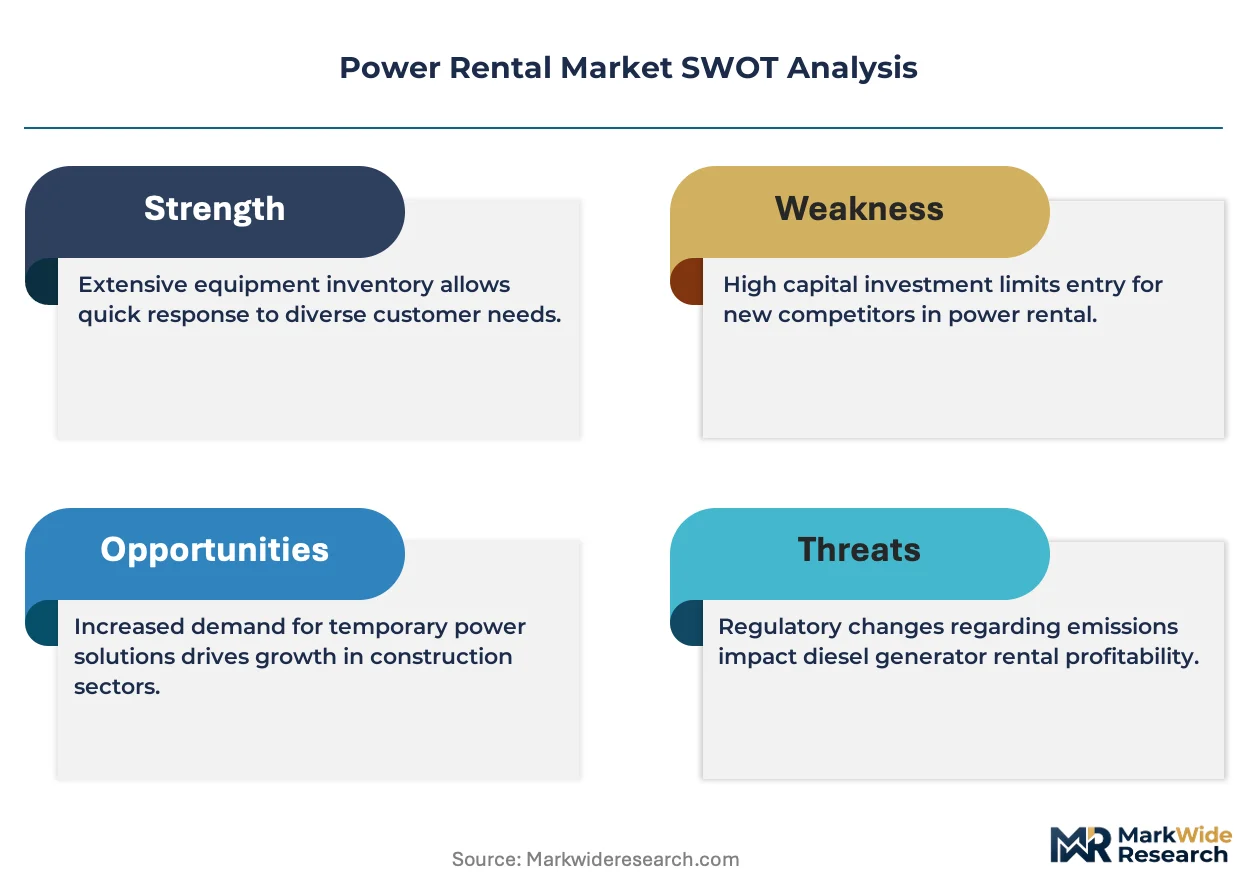
EPA Tier 4 Final certification is reorganizing competitive access across the North American power rental landscape. Cummins sustains technology leadership through in-house engine manufacturing that meets the stringent emissions threshold. Aggreko navigates dual-fuel portfolio transitions while maintaining fleet availability for industrial clients. United Rentals controls distribution density through branch-level inventory positioning across major metropolitan construction zones.
Power rental denotes the short-term or medium-term lease of mobile generation and distribution equipment, typically spanning reciprocating engine gensets from 20 kW to 2,000 kW with integrated switchgear and fuel storage for immediate deployment. The equipment serves critical functions where grid power is unavailable, insufficient, or prohibitively expensive to install permanently. Generators below 50 kW dominate event and retail backup applications where portability and rapid deployment carry premium value. The 201-500 kW segment anchors construction and manufacturing demand where load profiles fluctuate across project phases. Load banks represent a specialized margin pool as data center commissioning protocols tighten thermal verification requirements before facility handover.
EPA enforcement of Tier 4 Final standards for non-road diesel engines directly elevates fleet replacement costs and filters marginal operators from metropolitan markets. OSHA temporary power regulations for construction sites mandate ground-fault protection and qualified electrician oversight, shaping rental package configurations and service bundling. FERC interconnection rules for distributed generation influence how rental assets integrate with utility grids during peak demand events. Stakeholders must weigh the capital intensity of compliant fleet renewal against the contracting windows opening in data center and renewable energy construction verticals.
Market Dynamics
EPA Tier 4 Final compliance deadlines are forcing fleet turnover across the North American power rental landscape, compressing replacement cycles and elevating capital requirements for diesel genset operators.
Growth Catalysts
- Data Center Expansion:Hyperscale facility construction across Northern Virginia, Dallas-Fort Worth, and Phoenix is generating sustained demand for temporary power during commissioning and backup redundancy testing.
- OSHA Temporary Power Mandates:Ground-fault protection requirements for construction sites are expanding rental package scope toward bundled electrical safety services.
- Natural Gas Infrastructure:Pipeline density along the Gulf Coast petrochemical corridor is enabling dual-fuel and gas-only rental deployments with lower emissions profiles.
Market Restraints
- Engine Block Supply Concentration:Foundry capacity for large-bore diesel and gas engine castings concentrates in Germany, Japan, and select US Midwest manufacturing clusters.
- Platinum Group Metal Volatility:Diesel oxidation catalyst and selective catalytic reduction systems depend on palladium and rhodium pricing that fluctuates with automotive sector demand.
- FERC Interconnection Friction:Utility approval timelines for distributed generation tie-in extend deployment windows for grid-support rental projects.
Strategic Opportunities
- Renewable Energy Construction:Utility-scale solar and battery storage EPC contracts in Texas, California, and Arizona require mobile power for civil works and module installation phases.
- Remote Monitoring Convergence:Integration of telematics platforms with predictive maintenance algorithms is enabling condition-based service models that reduce unplanned downtime.
- IRA Clean Energy Incentives:Investment tax credit extensions for energy storage and renewable projects are accelerating construction timelines and associated temporary power demand.
Industry Challenges
- Tier 4 Final Certification Timeline:EPA engine family approval processes create bottlenecks for new model introductions, delaying fleet refresh programs.
- Electrical Technician Scarcity:Qualified electricians capable of temporary power system design and OSHA-compliant installation are concentrated in unionized metropolitan markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Rental Market |
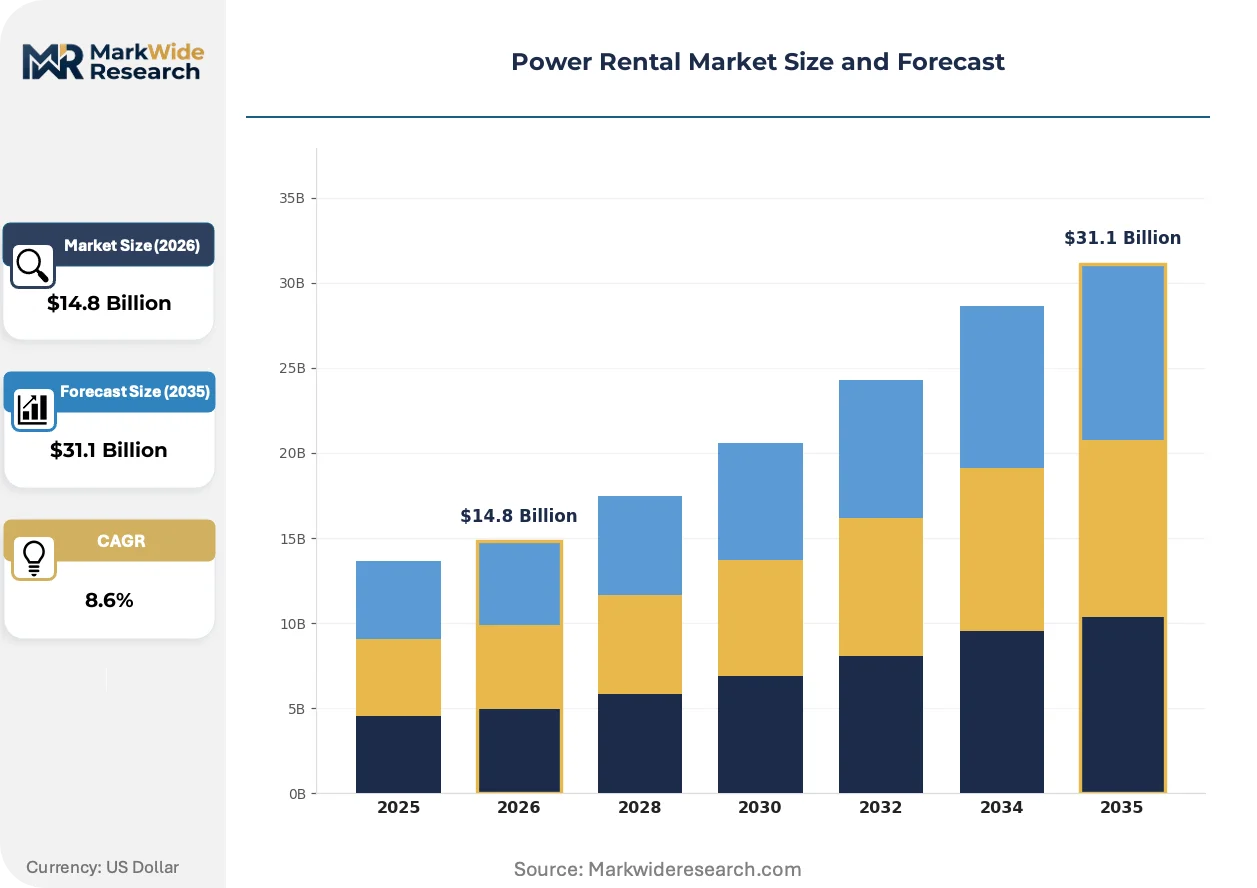
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
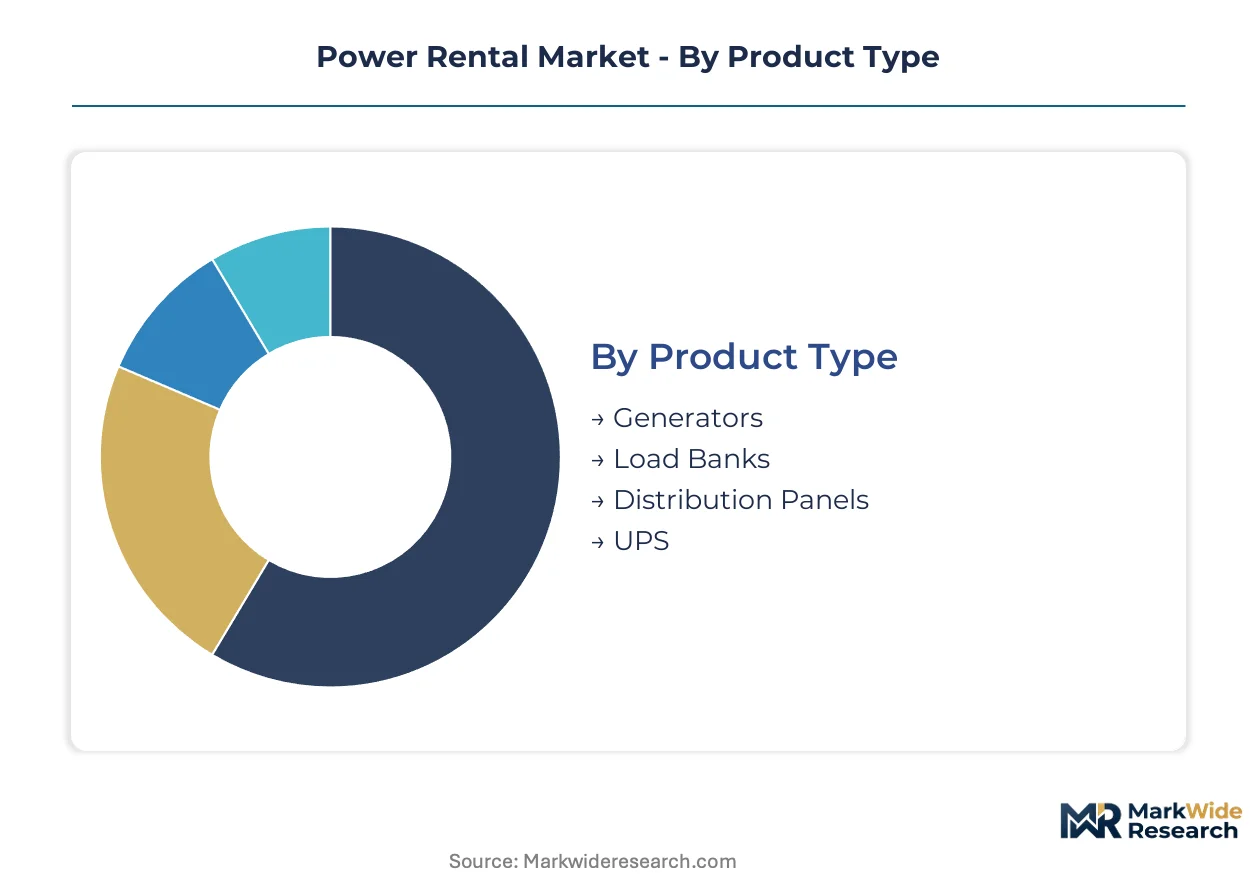
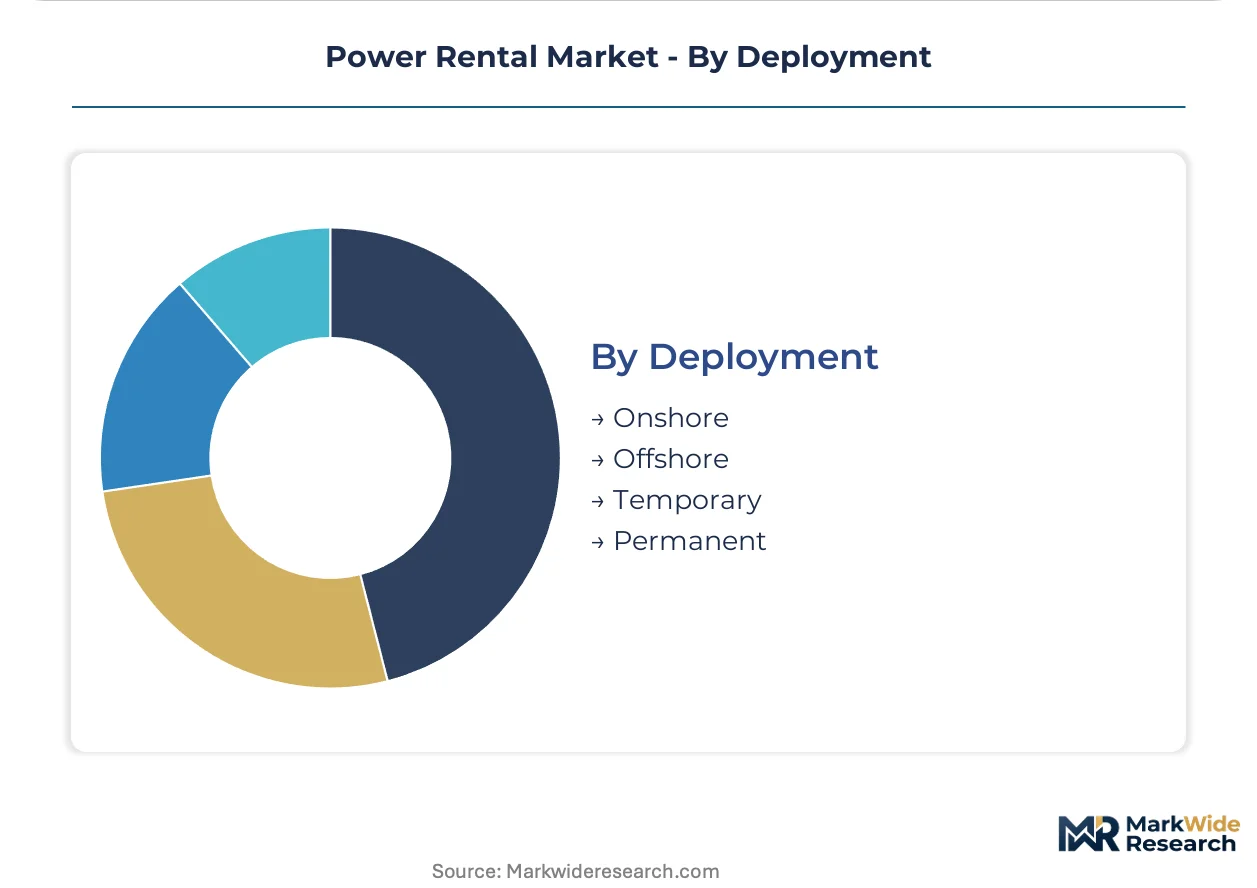
| Segmentation | Product Type: Generators, Load Banks, Distribution Panels, UPS End User: Construction, Events, Oil & Gas, Industrial Power Rating: Below 50 kW, 50-200 kW, 201-500 kW, Above 500 kW Deployment: Onshore, Offshore, Temporary, Permanent |
| Companies Covered | Atlas Copco, Cummins, Aggreko, Generac Power Systems, Herc Rentals, United Rentals, Caterpillar, Kohler, Ashtead Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Rental Market Emerging Trajectories
Mobile power systems are converging with digital infrastructure and alternative fuels, compressing deployment footprints while expanding remote operability.
Containerized battery energy storage systems paired with bidirectional inverters are miniaturizing the physical footprint of temporary power solutions. Data center operators in Loudoun County, Virginia are adopting these hybrid configurations for commissioning load banks and critical facility testing. The technology is miniaturizing site preparation requirements and reducing diesel fuel logistics for short-duration applications.
EPA enforcement of Tier 4 Final standards for non-road diesel engines above 751 horsepower is elevating aftertreatment complexity. Rental fleet operators must integrate diesel particulate filters, selective catalytic reduction, and diesel oxidation catalysts into mobile enclosures. The construction segment faces the steepest compliance costs as project-based rental periods struggle to amortize premium equipment premiums.
Equipment-as-a-service contracting is displacing traditional dry-hire rental arrangements in industrial manufacturing. Petrochemical facilities along the Texas Gulf Coast are procuring bundled packages that include fuel management, preventive maintenance, and 24/7 remote monitoring. This shift concentrates vendor relationships with full-service providers capable of outcome-based uptime guarantees.
Power Rental Market Segmentation
Power rental segmentation reveals divergent equipment economics across duty cycles and regulatory exposure. Substitution threats from battery storage and grid infrastructure reshape competitive intensity differently across product categories and deployment modes.
Product Type:
Generators face the most acute substitution pressure as containerized battery systems penetrate short-duration applications.
- Generators:Reciprocating engine gensets from 20 kW to 2,000 kW with integrated fuel storage and switchgear. Construction sites in Texas and Arizona concentrate demand where grid extension costs exceed rental premiums and EPA Tier 4 Final compliance elevates diesel equipment thresholds.
- Load Banks:Resistive and reactive testing equipment for commissioning and maintenance protocols. Data center operators in Northern Virginia drive demand as hyperscale facilities mandate thermal verification before handover, tightening turnaround requirements for rental providers.
- Distribution Panels:Temporary electrical distribution with ground-fault protection and circuit breakers.
- UPS:Uninterruptible power supply systems for critical load protection during generator startup.
Generators retain volume leadership; load banks hold the steepest expansion curve.
End User:
Cost tier stratification separates project-based construction demand from mission-critical industrial contracts with uptime penalties.
- Construction:Project-phase power for civil works, vertical construction, and commissioning. Utility-scale solar EPC contracts in California and Texas generate sustained demand as IRA incentives accelerate project timelines and associated temporary power windows.
- Industrial:Manufacturing backup and process continuity for petrochemical and food processing facilities. Gulf Coast petrochemical corridors in Texas and Louisiana concentrate demand where dual-fuel capability commands premium pricing and bundled service contracts.
- Events:Temporary power for concerts, festivals, and sporting venues requiring rapid deployment.
- Oil & Gas:Remote power for drilling, completion, and production operations.
Construction dominates transaction volume; industrial commands the highest margin per rental day.
Power Rating:
Application specificity drives divergence between portable sub-50 kW units and fixed-installation megawatt-class systems.
- 201-500 kW:Mid-range gensets anchoring commercial construction and manufacturing load profiles. Dallas-Fort Worth metropolitan construction zones concentrate demand where fluctuating power requirements across project phases favor rental over ownership.
- Below 50 kW:Portable inverter and conventional gensets for retail backup and event applications. Festival operators and small commercial tenants prioritize rapid deployment and minimal site preparation over fuel efficiency metrics.
- 50-200 kW:Light commercial and residential backup power systems.
- Above 500 kW:Heavy industrial and utility-scale temporary power installations.
The 201-500 kW band anchors revenue concentration; below 50 kW units are gaining share fastest in urban event markets.
Deployment:
Geography and duration separate mobile onshore applications from capital-intensive offshore installations.
- Onshore:Land-based deployment across construction, industrial, and event applications. Metropolitan branch networks in Houston, Phoenix, and Atlanta enable same-day delivery and service response for equipment-intensive projects.
- Temporary:Short-to-medium term rental arrangements from days to 24 months. Data center commissioning protocols in Loudoun County, Virginia standardize 6-18 month rental windows for load testing and backup redundancy verification.
- Offshore:Marine-rated equipment for platforms and vessels requiring corrosion resistance.
- Permanent:Extended rental or lease-to-own arrangements for infrastructure-constrained sites.
Onshore deployment retains volume leadership; temporary contracting is expanding most quickly as equipment-as-a-service models displace dry-hire arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast pipeline network anchors North American power rental demand through petrochemical corridor expansion and LNG export terminal construction. Grid interconnection bottlenecks in Northern Virginia and Dallas-Fort Worth concentrate data center commissioning requirements. Distributed solar buildouts across Rajasthan and Gujarat drive mobile power needs for civil works and module installation.
United States
EPA Tier 4 Final compliance deadlines compress diesel genset replacement cycles across construction and industrial verticals. FERC interconnection friction extends utility approval timelines for distributed generation tie-in, delaying grid-support rental deployments. Northern Virginia's Loudoun County data center cluster generates sustained demand for load bank rentals during facility commissioning protocols.
Germany
Industrial manufacturing backup requirements and renewable energy construction sustain rental equipment utilization across the Rhine-Ruhr and Bavarian industrial zones. The EU Green Deal's accelerated coal phaseout elevates temporary power needs for grid stabilization during renewable integration. Foundry capacity for large-bore engine castings concentrates in Baden-Württemberg and Lower Saxony, creating supply chain dependencies for rental fleet operators.
China
Dual carbon goals under MEE oversight accelerate utility-scale solar and battery storage EPC contracts across the Yangtze River Delta and Pearl River Delta. GB standards for non-road mobile machinery emissions elevate fleet compliance costs for domestic rental providers. Sichuan-Chongqing's data center construction boom generates concentrated demand for temporary power during hyperscale facility buildouts.
India
PLI scheme incentives for solar module manufacturing and semiconductor fabrication concentrate construction power needs in Gujarat and Karnataka. Central Electricity Authority grid codes for distributed generation influence rental asset integration during peak demand events. Telangana's pharmaceutical and data center corridors drive mission-critical backup requirements with uptime penalty structures.
Saudi Arabia
NEOM Northwest gigaproject construction and Red Sea tourism development generate sustained demand for mobile power across remote sites with limited grid access. The country's national petroleum regulator oversees dual-fuel deployment standards for petrochemical facilities in the Eastern Province. Riyadh's metro expansion and Qiddiya entertainment district construction anchor metropolitan rental demand with rapid-deployment requirements.
Power Rental Market Vendor Landscape
Listed leaders compete with private specialists across capital access and fleet scale dimensions. The market structure consolidates around engine-manufacturing incumbents with captive supply chains and independent rental operators with branch-level distribution density. Three archetypes dominate: integrated engine-rental hybrids, pure-play equipment lessors, and regional service specialists. Capacity expansion and portfolio diversification toward dual-fuel and battery-hybrid systems represent the dominant competitive vectors.
Among integrated engine-rental hybrids, Cummins exemplifies backward integration into in-house manufacturing that meets stringent emissions thresholds. Aggreko occupies a position within the pure-play equipment lessor archetype, navigating dual-fuel portfolio transitions while maintaining fleet availability. United Rentals anchors the scale-driven distribution tier through metropolitan branch networks that enable same-day equipment delivery and service response.
| Leading Market Players |
|---|
| Atlas Copco |
| Cummins |
| Aggreko |
| Generac Power Systems |
| Herc Rentals |
| United Rentals |
| Caterpillar |
| Kohler |
| Ashtead Group |
| Others |
Supply Flow & Price Mechanics
Equipment-as-a-service contracts lock in multi-year fuel management and maintenance bundles, anchoring price visibility for Gulf Coast petrochemical operators while securing foundry allocation for Tier 4 Final engine blocks. This contracting pattern concentrates procurement power with full-service providers capable of uptime guarantees.
Pricing Analysis
Volume-discount tiering separates hyperscale data center load bank rentals from spot-market construction genset demand. Three-tier pricing structure across premium EPA-certified, standard interim-tier, and economy non-compliant equipment reflects certification grade and bundled service intensity. Cost compression in the construction segment intensifies as project-based rental periods struggle to amortize Tier 4 Final equipment premiums. Event operators exhibit highest price sensitivity, prioritizing rapid deployment over fuel efficiency metrics.
Supply Chain Analysis
Inbound logistics costs from German and Japanese foundries concentrate engine block supply vulnerability through Hamburg and Yokohama port corridors. Large-bore diesel and gas engine castings draw from Baden-Württemberg, Aichi Prefecture, and Ohio River Valley manufacturing clusters. Palladium and rhodium dependency for aftertreatment systems creates commodity price volatility exposure. Distribution runs through metropolitan branch networks in Houston, Phoenix, and Atlanta enabling same-day equipment delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as EPA Tier 4 Final compliance filters marginal operators from metropolitan markets. Dual-fuel capability and battery-hybrid portfolios represent the primary demand-side shift opening specialist positions.
For Market Incumbents: Fortify fleet compliance density through captive foundry relationships securing Tier 4 Final engine allocation ahead of certification bottlenecks. Expand branch-level service bundling in Northern Virginia and Dallas-Fort Worth data center corridors to defend against containerized battery substitution in short-duration applications.
For New Entrants and Emerging Players: Lead with remote monitoring convergence and predictive maintenance algorithms targeting mid-market construction clients underserved by national rental networks. White-space opportunity concentrates in utility-scale solar EPC contracts across Texas and Arizona where IRA-accelerated timelines outpace incumbent equipment availability.
For Investors and Strategic Acquirers: Capital is best deployed toward regional service specialists with dense metropolitan branch networks and established utility relationships. Long-term viability hinges on dual-fuel portfolio transition completion. Watch FERC interconnection rulemaking as inflection signal for grid-support rental deployment windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Fleet Transition | Captures Gulf Coast petrochemical demand as EPA Tier 4 Final deadlines compress diesel replacement cycles. |
| Containerized Battery Hybrid Deployment | Penetrates data center commissioning protocols in Loudoun County with reduced site preparation requirements. |
| Remote Monitoring Platform Integration | Enables condition-based service contracts displacing traditional dry-hire arrangements in manufacturing verticals. |
| Metropolitan Branch Network Expansion | Secures same-day delivery capability in Phoenix and Atlanta construction zones against national competitors. |
| Load Bank Specialization | Captures margin pool from hyperscale facility thermal verification mandates tightening turnaround requirements. |
Methodological Framework
Desk research of EPA engine family certification databases, FERC interconnection filings, and EIA power plant construction data preceded structured interviews with rental fleet operations directors, data center commissioning engineers, EPC project managers, and petrochemical facility maintenance heads. Primary fieldwork combined with secondary validation from SEC 10-K equipment disclosures and customs import records for large-bore engine castings. Bottom-up equipment deployment estimates triangulated against top-down construction spending projections.
Variance decomposition across power rating segments, end-use verticals, fuel source categories, and regional regulatory frameworks shaped the analytical architecture. CAGRs derived from equipment replacement cycle modeling and construction pipeline tracking. Forecast inputs incorporated IRA incentive acceleration effects on solar EPC timelines and EPA enforcement intensity assumptions for non-compliant fleet retirement.
The analysis sits within stated boundaries; outcomes outside sustained data center construction velocity and Tier 4 Final enforcement consistency would require recalibration. Forecasts reflect documented assumptions regarding foundry capacity expansion and platinum group metal price stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Temporary Load Bank Rental Market
Power
Asia-Pacific Power Purchase Agreement Market
Power
Japan Power Market
Power
Power Sled Market
Power
Europe Frequency Converter Market
Power
Global Advanced Marine Power Supply Market
Power
Wind Alarm Controller Market
Power
Europe Power Purchase Agreement Market
Power
Gabon Power Market
Power
Saudi Arabia Power Market
Power
Portugal Power Market
Power
North America Power Market
Power
HVDC Capacitor Market
Power
Global Diesel Power Engine Market
Power
Existent Gum Steam Generator Market
Power
Nigeria Power Market