
 Combined Heat and Power (CHP) Systems Market | 2026-2036
Combined Heat and Power (CHP) Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Combined Heat and Power (CHP) Systems Market Outlook
Distributed energy resource integration is rewriting how thermal and electric loads get balanced at facility level. Siemens Energy leverages its gas turbine heritage to anchor large-scale industrial cogeneration deployments across Europe. Caterpillar sustains a dense service network that competes on uptime guarantees for engine-based installations. Mitsubishi Heavy Industries specializes in advanced combined cycle configurations that dominate utility-scale project tenders in Asia.
Combined Heat and Power systems simultaneously generate electricity and useful thermal energy from a single fuel source, typically achieving total system efficiencies of 75-85% through sequential energy extraction. Engine-based technology occupies the broadest installed base due to modularity and fast-start capability, while fuel cell segments attract premium project economics where hydrogen infrastructure matures. Natural gas remains the dominant fuel type for new capacity, though biogas feedstocks are gaining structural share where anaerobic digesters cluster near agricultural or wastewater operations.
The US Environmental Protection Agency administers the CHP Partnership program that certifies system efficiency thresholds and shapes federal procurement preferences. Germany's Federal Network Agency and the EU F-Gas Regulation together constrain refrigerant choices and emissions profiles for thermally driven equipment sold across member states. Stakeholders must monitor how carbon border adjustments and hydrogen blending mandates reshape fuel economics for existing gas turbine fleets.
Market Dynamics
The US Inflation Reduction Act's extension of tax credits for high-efficiency cogeneration equipment is accelerating capital redeployment toward distributed generation assets, compressing payback periods for hospital and industrial campus installations.
Growth Catalysts
- Hospital energy resilience mandates:Healthcare campuses are expanding CHP installations to maintain critical power during grid disruptions, with emergency preparedness regulations tightening across multiple jurisdictions.
- Germany's district heating networks:Industrial parks and municipal heating systems anchor project pipelines, with feed-in tariffs for efficient thermal generation stimulating equipment replacement cycles.
- Biogas anaerobic digester clustering:Agricultural and wastewater operations are deploying engine-based systems near fuel sources, eliminating transmission losses and securing waste-to-energy revenue streams.
Market Restraints
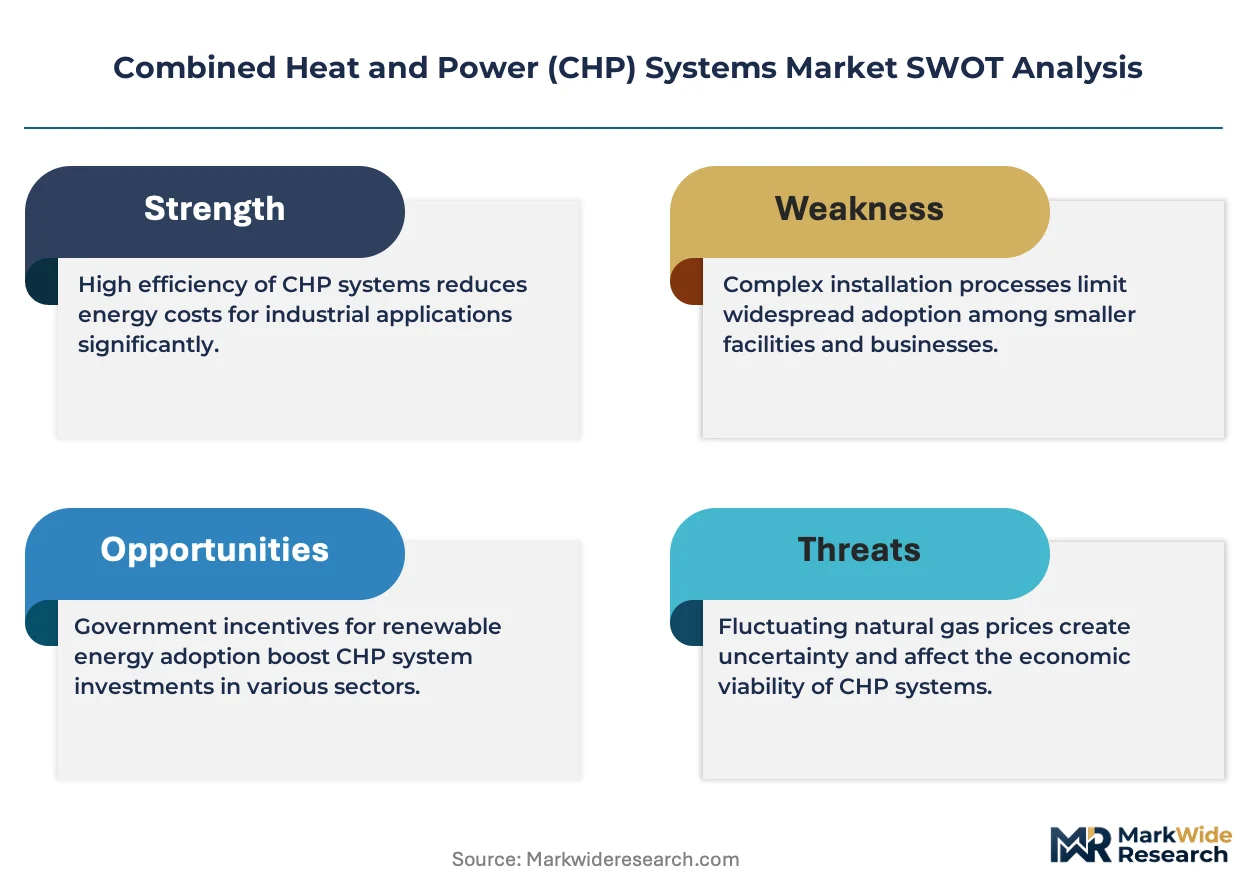
- Natural gas price volatility:Fuel cost swings compress project IRR calculations and deter long-term power purchase agreements for new capacity.
- EU F-Gas Regulation constraints:Refrigerant phase-down schedules limit thermally driven equipment options and extend engineering lead times for organic Rankine cycle systems.
- Interconnection queue delays:Utility approval timelines for grid-tied CHP projects stretch 18-36 months in congested transmission zones, freezing capital deployment.
Strategic Opportunities
- Hydrogen blending infrastructure:Gas turbine fleets capable of 30-50% hydrogen co-firing are capturing early-mover premiums in industrial clusters with electrolyzer proximity.
- US EPA CHP Partnership certification:Federal procurement preferences for efficiency-qualified systems create a compliant equipment tier commanding price premiums.
- Behind-the-meter microgrids:Data centers and semiconductor fabs are integrating CHP with battery storage to island from utility rates and reliability risks.
Industry Challenges
- Controls engineering scarcity:Talent shortages in thermal-electric load balancing and distributed energy resource management system integration are extending commissioning schedules.
- Legacy boiler room retrofits:Existing steam infrastructure incompatibility with high-pressure CHP outputs forces costly distribution system overhauls in aging facilities.
- Carbon accounting complexity:Scope 2 emission allocation between electricity and thermal output creates reporting friction for corporate sustainability disclosures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Combined Heat and Power (CHP) Systems Market |
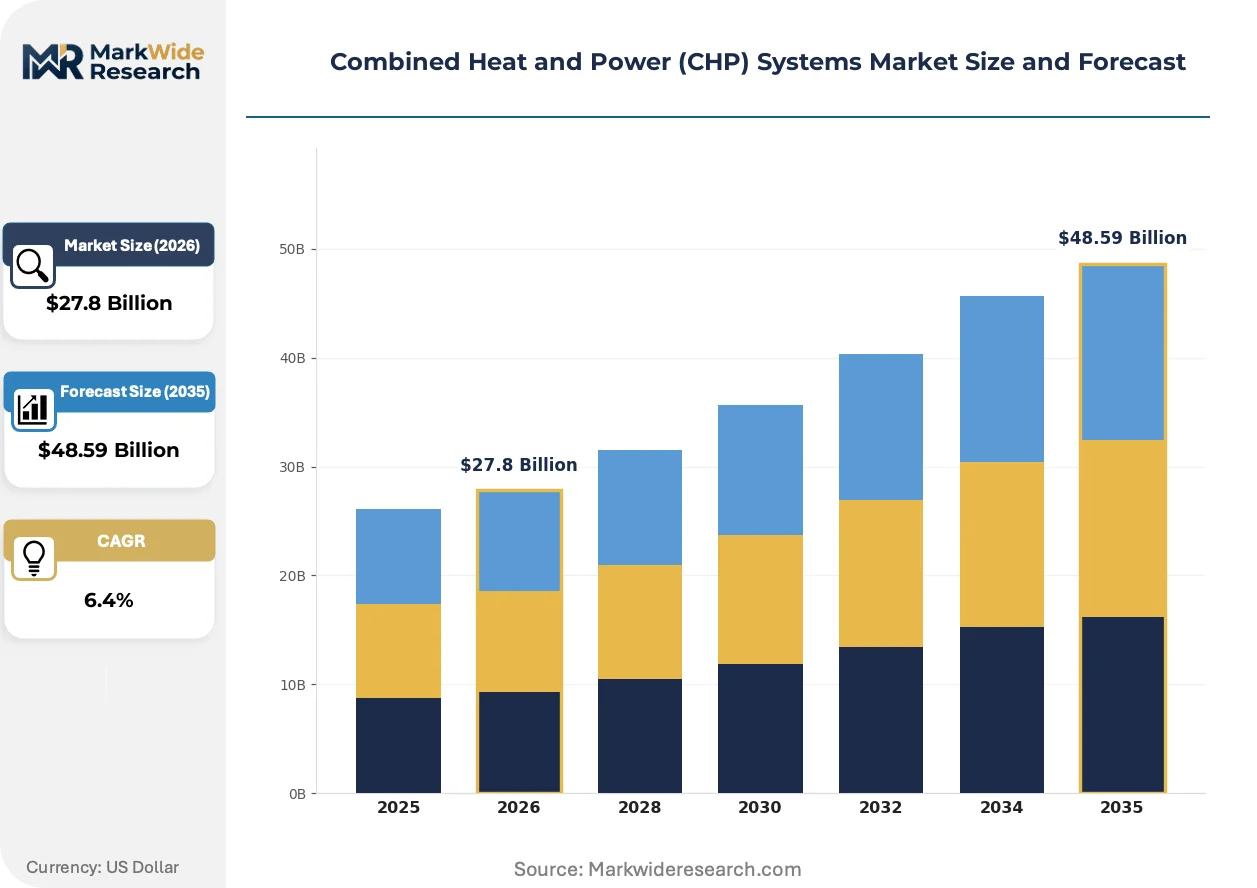
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $48.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Micro CHP, Gas Turbine, Engine-based, Fuel Cell Application: Residential, Industrial, Commercial, District Heating Fuel Type: Natural Gas, Biogas, Diesel, Biomass End User: Utilities, Manufacturing, Healthcare, Hospitality |
| Companies Covered | Veolia, Caterpillar, Siemens Energy, Bosch Thermotechnology, 2G Energy, GE Vernova, Mitsubishi Heavy Industries, Cummins, Wärtsilä, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Combined Heat and Power (CHP) Systems Market Strategic Shifts
Solid oxide fuel cells are crossing commercial viability thresholds, with hydrogen-ready designs compressing the technology adoption curve for premium efficiency applications.
Modular solid oxide fuel cell systems achieving 60% electrical efficiency are rendering obsolete traditional reciprocating engine installations in urban commercial buildings where emissions restrictions tighten. Property developers in Boston and San Francisco are specifying fuel cell prime power for new construction, accepting higher capital costs to secure air quality permits and avoid local combustion bans. The technology is rendering obsolete the historical trade-off between efficiency and siting flexibility.
The EU F-Gas Regulation's refrigerant phase-down is forcing equipment manufacturers to redesign absorption chiller and heat pump components around lower-GWP working fluids. Engineering teams are retooling supply chains for propane and ammonia-based systems, with certification delays compressing product launch windows. German and Dutch industrial buyers are accelerating procurement of F-Gas-compliant equipment ahead of 2027 import restrictions.
Power purchase agreement structures are unbundling thermal output from electricity sales, allowing district heating operators to contract heat separately from grid-exported power. This contractual innovation disrupts traditional cogeneration economics that bundled both commodities. Danish and Swedish municipal utilities are pioneering heat-only tariffs, with Finnish paper mills following to monetize process steam independently of volatile power markets.
Combined Heat and Power (CHP) Systems Market Segmentation
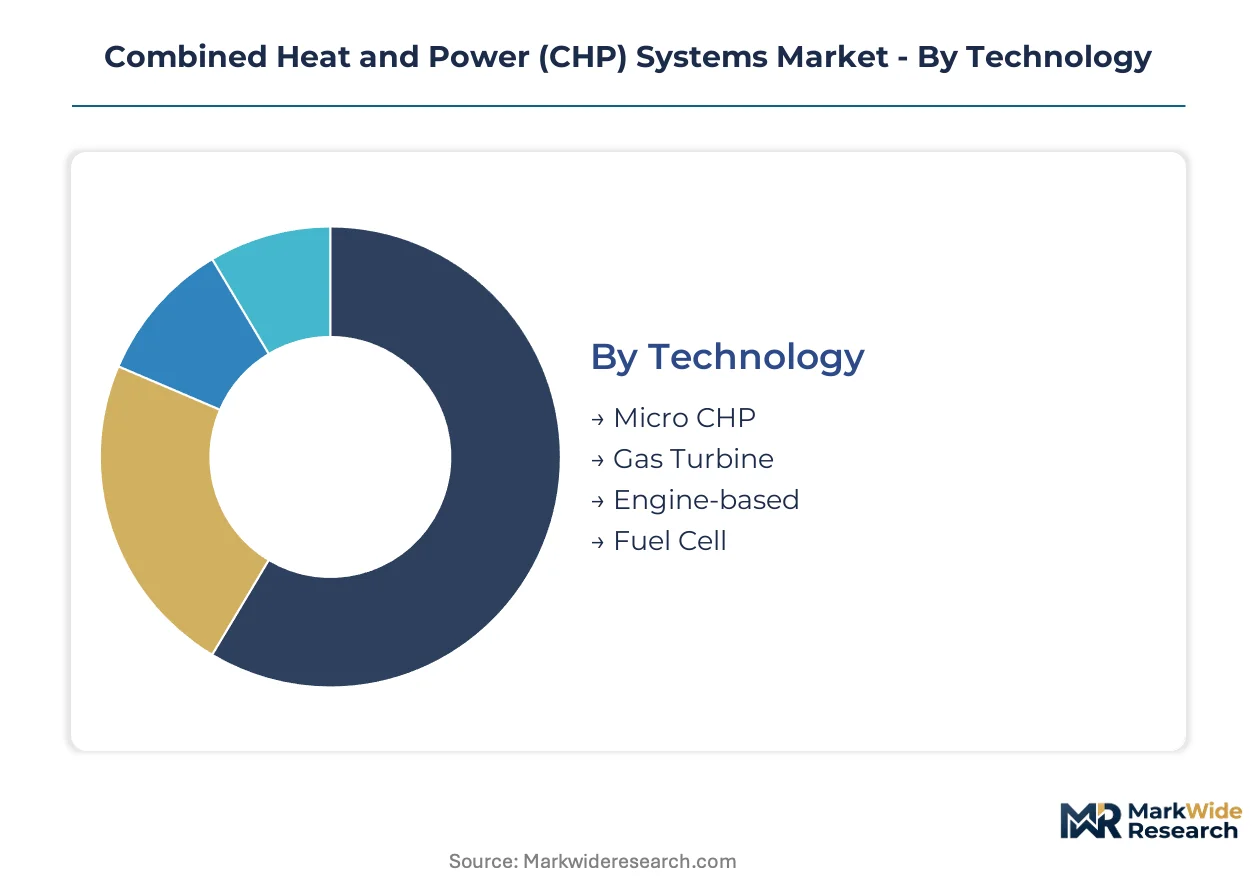
CHP system segmentation reveals how technology maturity, fuel economics, and end-use resilience requirements fragment procurement patterns across installations. Buyers select configurations based on thermal load profiles, grid reliability priorities, and available feedstock infrastructure rather than standardized specifications.
Technology:
Mature turbine architectures dominate utility-scale deployments while emerging fuel cell platforms capture premium efficiency niches in urban environments.
- Engine-based:Reciprocating engines deliver modular capacity increments from 100 kW to 50 MW with fast-start capability for emergency backup applications. Manufacturing campuses in Germany and hospital complexes in the US specify these systems for load-following flexibility and dense service network availability.
- Gas Turbine:Aeroderivative and industrial turbine configurations achieve 35-40% electrical efficiency at scales above 5 MW, anchoring large industrial cogeneration and district heating supply. Siemens Energy and Mitsubishi Heavy Industries compete for utility-scale tenders across Europe and Asia where high-pressure steam demand justifies capital intensity.
- Micro CHP:Residential-scale units below 50 kW serve single-family and small commercial thermal loads.
- Fuel Cell:Solid oxide and molten carbonate designs reach 60% electrical efficiency with minimal emissions, penetrating Boston and San Francisco new construction where combustion bans apply.
Engine-based systems handle the majority of throughput; fuel cell platforms are expanding most quickly on share in premium urban applications.
Application:
Volume concentrates in industrial process heat while commercial microgrids represent the steepest expansion trajectory for behind-the-meter configurations.
- Industrial:Chemical plants, refineries, and food processing facilities deploy CHP to capture waste heat for steam-driven processes, achieving 75-85% total system efficiency. Paper mills in Finland and petrochemical clusters in Germany anchor equipment replacement cycles with 20-year asset horizons.
- District Heating:Municipal and campus-scale thermal networks aggregate multiple heat sources to serve dense building stocks. Copenhagen and Stockholm utilities pioneer heat-only tariffs that unbundle thermal sales from electricity exports, restructuring traditional cogeneration economics.
- Commercial:Office complexes, retail centers, and data centers integrate CHP with battery storage for islanding capability.
- Residential:Single-family and multi-family buildings deploy micro-CHP for combined space heating and power generation.
Industrial applications command the largest installed base; district heating networks are gaining share fastest where municipal ownership enables long-term heat contracting.
Fuel Type:
Supply security and carbon accounting reshape procurement toward regionally available feedstocks with established delivery infrastructure.
- Natural Gas:Pipeline-delivered methane remains the dominant input for new capacity, offering consistent heating value and established burner management systems. Price volatility in European spot markets and US Henry Hub fluctuations compress project IRR calculations and deter long-term power purchase agreements.
- Biogas:Anaerobic digester output from agricultural operations and wastewater treatment plants delivers carbon-neutral thermal input for engine-based systems. Denmark and the Netherlands cluster installations near livestock operations to eliminate transmission losses and secure waste-to-energy revenue streams.
- Diesel:Distillate fuel serves remote installations and emergency backup configurations where pipeline gas is unavailable.
- Biomass:Wood chip and agricultural residue combustion drives steam turbine CHP in forestry and farming regions.
Natural gas retains the dominant throughput position; biogas is climbing the fastest on structural share where digester infrastructure matures.
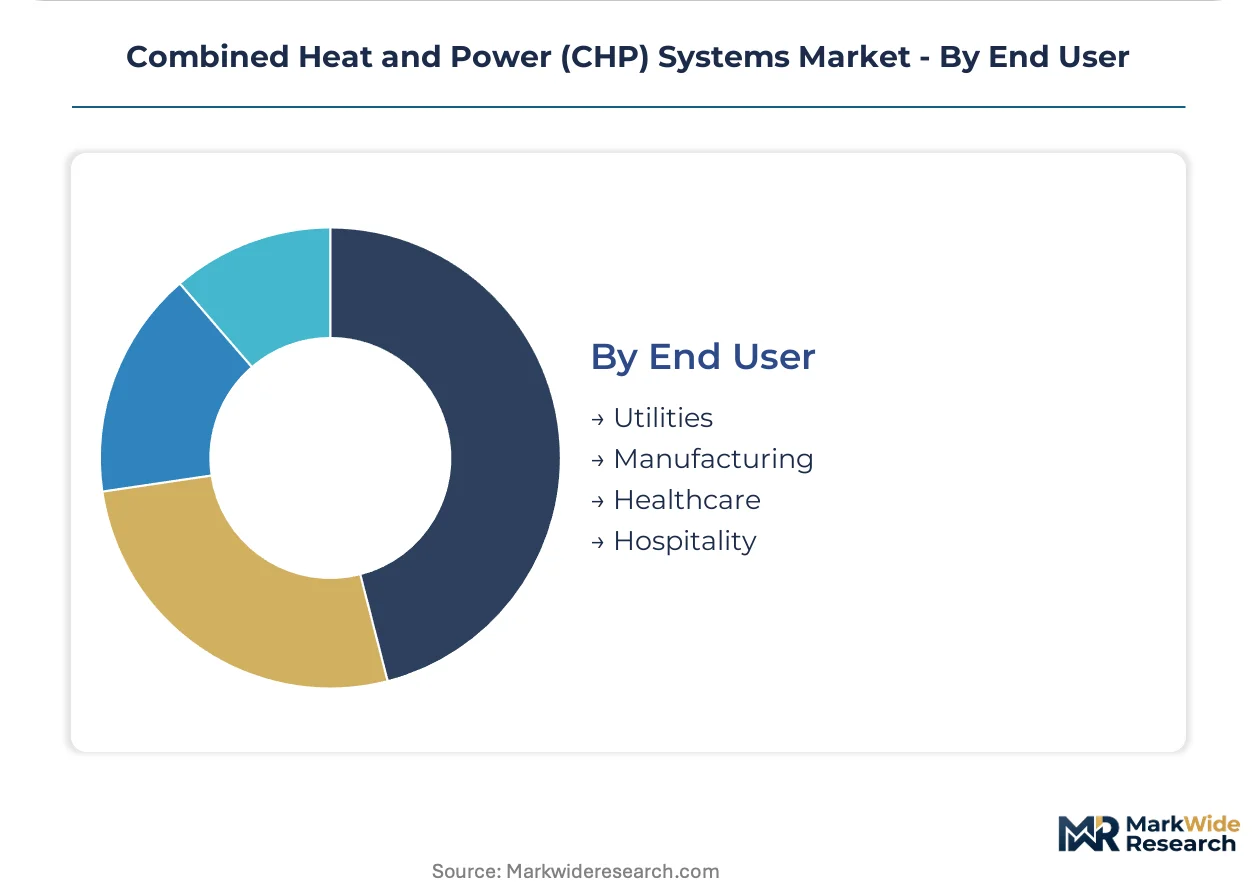
End User:
Resilience mandates and thermal load continuity requirements differentiate procurement specifications across facility types.
- Healthcare:Hospitals and research campuses install CHP to maintain critical power during grid disruptions, with emergency preparedness regulations tightening across multiple US states and EU member countries. The US Inflation Reduction Act's tax credit extension compresses payback periods for these installations.
- Manufacturing:Continuous process industries deploy CHP to secure steam supply independence from utility rate volatility. Semiconductor fabs and pharmaceutical plants integrate systems with battery storage to island from grid reliability risks.
- Utilities:Power generators and district heating operators procure large-scale turbine configurations for baseload thermal supply.
- Hospitality:Hotels and resorts deploy systems for combined space conditioning and power generation in remote or premium locations.
Healthcare and manufacturing jointly dominate current deployment; utility procurement is expanding most rapidly where district heating network modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial campuses and healthcare facilities drive procurement intensity across concentrated demand clusters. Buyers prioritize resilience mandates and thermal load continuity over standardized equipment specifications. Regulatory incentives in Germany, the United States, and Denmark anchor project economics through tax credits and feed-in tariffs.
Germany
District heating networks in North Rhine-Westphalia and Bavaria anchor equipment replacement cycles. The Federal Network Agency's feed-in tariffs for efficient thermal generation compress payback periods for municipal utilities. Industrial parks around Cologne and Munich cluster gas turbine installations serving chemical and automotive manufacturing campuses.
United States
Hospital energy resilience mandates tighten across California, Texas, and New York. The EPA's CHP Partnership program certifies efficiency thresholds that shape federal procurement preferences for healthcare and military installations. Data centers in Northern Virginia and semiconductor fabs in Arizona integrate engine-based systems with battery storage for islanding capability.
Denmark
Agricultural biogas clusters in Jutland and Zealand deploy engine-based systems near livestock operations. National waste-to-energy policies eliminate transmission losses and secure feedstock revenue streams for anaerobic digester projects. Copenhagen's municipal utility pioneers heat-only tariffs that unbundle thermal sales from electricity exports.
Japan
Industrial conglomerates in Kansai and Chubu regions deploy advanced combined cycle configurations for process steam independence. METI's hydrogen blending roadmaps stimulate turbine fleet retrofits capable of 30-50% co-firing. Paper mills in Kyushu and chemical complexes in Osaka anchor utility-scale project tenders.
United Kingdom
Healthcare campuses in London and Manchester expand CHP installations under emergency preparedness regulations. The country's national environmental regulator constrains emissions profiles for thermally driven equipment through carbon accounting frameworks. District heating schemes in Scotland and Northern England aggregate multiple heat sources for dense building stocks.
Combined Heat and Power (CHP) Systems Market Competitive Environment
Channel-controlling players compete with product-specialist players across technology tiers. Turbine manufacturers with gas turbine heritage anchor large-scale industrial deployments through engineering credibility and service density. Engine-based specialists compete on uptime guarantees and modular capacity increments. Three archetypes dominate: integrated energy service companies, component-focused equipment manufacturers, and fuel cell technology developers. Competitive moves concentrate on hydrogen-ready product line extensions and strategic partnerships for distributed energy resource integration.
Within the integrated service tier, Veolia exemplifies the energy-as-a-service model through long-term operational contracts. Siemens Energy and Mitsubishi Heavy Industries occupy positions anchored by aeroderivative and industrial turbine configurations. Among engine-based specialists, Caterpillar and Cummins represent the uptime-guarantee competitive vector. Wärtsilä sits within the fuel-flexibility archetype spanning natural gas and biogas applications. Bosch Thermotechnology and 2G Energy exemplify the European manufacturing base serving modular and residential-scale segments.
| Leading Market Players |
|---|
| Veolia |
| Caterpillar |
| Siemens Energy |
| Bosch Thermotechnology |
| 2G Energy |
| GE Vernova |
| Mitsubishi Heavy Industries |
| Cummins |
| Wärtsilä |
| Others |
Value Chain & Pricing Dynamics
The Rotterdam-Antwerp barge corridor anchors fuel logistics for European CHP deployments, with bunker fuel cost swings transmitting directly into turbine manufacturer pricing power and downstream project bid differentiation between integrated service providers and component vendors.
Pricing Analysis
Cost-plus contracts indexed to Henry Hub and TTF natural gas benchmarks dominate utility-scale turbine procurement, with Siemens Energy and Mitsubishi Heavy Industries applying escalation clauses that shift fuel volatility risk to district heating operators. Three-tier pricing structure across premium, standard, and economy levels separates EPA CHP Partnership-certified systems from baseline configurations and refurbished units, with certification premiums widening as the Inflation Reduction Act tightens federal procurement thresholds. Price erosion runs through the engine-based tier as Caterpillar and Cummins compete on uptime guarantees, squeezing margins for independent service providers lacking captive parts distribution. Hospital campuses and data center operators exhibit the lowest price sensitivity, prioritizing resilience specifications over capital cost, while municipal utilities in Eastern Europe face acute budget constraints that delay replacement cycles.
Supply Chain Analysis
Contract manufacturing for combustion turbine hot section components concentrates in Germany, Japan, and the United States, with Siemens Energy maintaining captive foundry capacity in Berlin and Mitsubishi Heavy Industries sourcing precision castings from Nagoya-area suppliers. Supply chains draw from nickel-based superalloy feedstocks, high-grade steel forgings, and precision electronic controls, with sourcing patterns tethered to aerospace industry capacity cycles. Single-source vulnerability persists for solid oxide fuel cell electrolyte ceramics, where limited qualified suppliers constrain production scaling for Bloom Energy and Mitsubishi Heavy Industries platforms. Distribution runs through original equipment manufacturer service networks for large installations, while modular engine-based systems reach end users through Caterpillar and Cummins dealer channels with embedded commissioning capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CHP market sits in early-cycle expansion as hospital resilience mandates and hydrogen blending roadmaps accelerate adoption beyond traditional industrial baseload applications, with policy tailwinds in Germany and the United States compressing payback periods for efficiency-qualified equipment.
For Market Incumbents: Entrench position by deepening backward integration into hydrogen-ready turbine retrofit capabilities and securing exclusive service contracts with district heating operators in North Rhine-Westphalia and Copenhagen. Fuel cell technology developers threaten engine-based incumbents in urban commercial segments where combustion bans tighten, necessitating certification investment in EPA CHP Partnership efficiency tiers to maintain federal procurement access. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, with Bangkok and Jakarta office complexes lacking established district heating infrastructure and facing rising grid reliability risks. Biogas engine packaging for agricultural clusters in Vietnam and Indonesia offers a second white-space target, with go-to-market execution best pursued through joint ventures with established EPC contractors possessing local permitting relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core energy equipment divisions, particularly European manufacturers with stranded gas turbine product lines requiring hydrogen co-firing investment to remain competitive. Long-term viability hinges on electrolyzer proximity and hydrogen pipeline access, with acquisition screening prioritizing firms holding service contracts with German chemical parks. The signal to watch is feed-in tariff adjustments for efficient thermal generation, with reductions triggering consolidation pressure on municipal utility suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Co-firing Retrofit | Gas turbine fleets in industrial clusters near electrolyzer projects capture early-mover premiums from METI and EU blending mandates. |
| EPA CHP Partnership Certification | Federal procurement preferences for efficiency-qualified systems create compliant equipment tier commanding price premiums in healthcare. |
| Biogas Fuel Flexibility Investment | Engine-based systems configured for agricultural digester output secure waste-to-energy revenue streams in Denmark and the Netherlands. |
| District Heating Service Contracting | Long-term operational agreements with Copenhagen and Stockholm utilities lock in thermal output monetization independent of power markets. |
| Fuel Cell Prime Power Specification | Solid oxide systems specified in Boston and San Francisco new construction secure air quality permits where combustion bans apply. |
Study Parameters
A standing panel of utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads provided ongoing calibration across primary interview cycles, with secondary validation drawing from EIA capacity data, IEA CHP deployment statistics, FERC interconnection filings, and EPA CHP Partnership certification records. Bottom-up equipment shipment tallies triangulated against top-down utility capex disclosures to anchor market sizing.
Scenario-bracketing around natural gas price trajectories and hydrogen infrastructure buildout timelines shaped projections across the analysis window, with segmentation modeling spanning fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns, with inputs including hospital resilience mandate expansion rates and district heating network modernization pipelines.
Practitioners should monitor interconnection queue clearance timelines and carbon border adjustment implementation for early signals of project pipeline acceleration or compression. Forecasts embed assumptions regarding IRA tax credit continuity and EU F-Gas Regulation phase-down schedules. Quarterly review of hydrogen blending mandate progress and feed-in tariff adjustments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Wireless Power Receiver Market
Power
United States Power Market
Power
Residential Portable Inverter Generator Market
Power
Static Synchronous Compensator (STATCOM) Market
Power
Europe Power Purchase Agreement Market
Power
Power Sled Market
Power
Asia-Pacific Alternating Current (AC) Drive Market
Power
Critical Power Market
Power
China Power Market
Power
Sudan Power Market
Power
Power Shelf Market
Power
Middle-East and Africa Power Rental Market
Power
Russian Federation Power Market
Power
Mexico Power EPC Market
Power
Portugal Power Market
Power
India Power Market