
 Critical Power Market | 2026-2036
Critical Power Market Size, Share, and Industry Trends Forecast 2026-2036
Critical Power Market Analysis
Multi-source procurement of critical power equipment is consolidating as end-users seek supply chain resilience against semiconductor and battery material shortages. Eaton leverages its integrated electrical infrastructure portfolio to anchor large data center contracts across North America. Siemens Energy competes through gas turbine and hydrogen-ready power solutions for industrial microgrids. Bloom Energy specializes in solid oxide fuel cell systems that sustain baseload operations for healthcare and telecom customers.
Critical power encompasses engineered systems that deliver continuous, conditioned electricity during grid disturbances, typically maintaining voltage within plus or minus two percent and switching to backup within four milliseconds for sensitive loads. Uninterruptible power supply units dominate product revenue due to mandatory deployment in financial trading floors and hospital surgical suites, while fuel cells represent the fastest-expanding product category as hydrogen infrastructure matures. Diesel generators retain the largest installed base but face structural margin compression from carbon compliance costs and restricted runtime permits in urban zones.
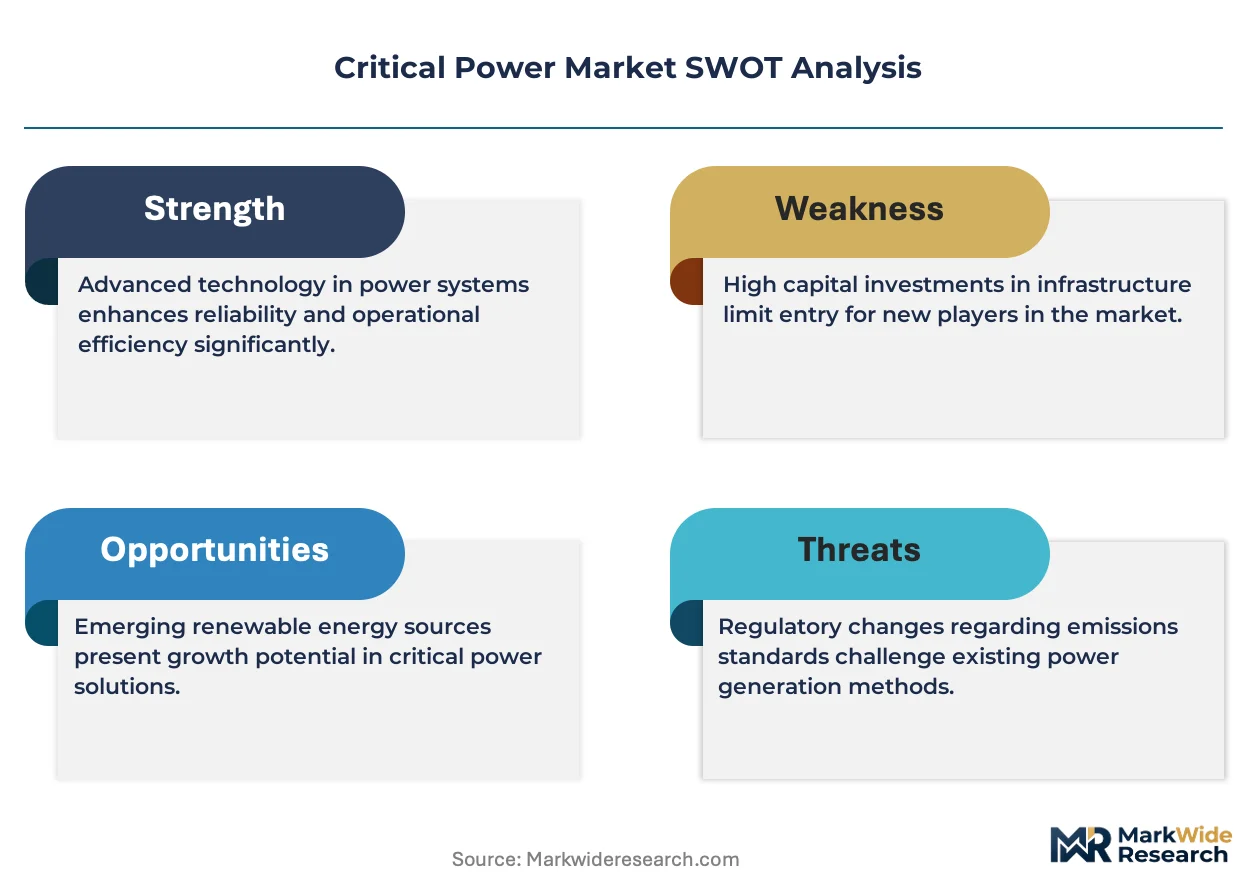
The EPA enforces Tier 4 final emissions standards for stationary diesel engines, forcing generator set manufacturers to add selective catalytic reduction or risk losing access to California and Texas data center projects. OSHA electrical safety regulations and NFPA 110 standards for emergency power supply systems shape installation protocols and service contract scopes across healthcare and industrial facilities. Stakeholders must monitor battery chemistry transitions and hydrogen supply chain readiness when committing to decade-long power infrastructure contracts.
Market Dynamics
AI compute loads are forcing data center operators to triple backup power density per rack, compressing procurement timelines from 18 months to under 9 months and privileging suppliers with captive battery cell supply.
Growth Catalysts
- EPA Tier 4 Final Standards:Stationary diesel emissions rules are accelerating hospital and telecom migration to solid oxide fuel cells in California and Texas markets.
- Hyperscale Facility Construction:United States data center buildouts are consuming megawatt-class UPS systems faster than manufacturers can expand silicon carbide inverter capacity.
- Hydrogen Infrastructure Maturation:Electrolyzer deployment clusters in Germany and Japan are enabling fuel cell microgrids for industrial baseload operations.
Market Restraints
- Lithium-Ion Supply Concentration:Cathode precursor refining concentrates in China, exposing North American UPS manufacturers to forced labor due diligence risks and IRA domestic content penalties.
- Technical Limitation of Solid Oxide Fuel Cells:Ceramic stack degradation above 850°C limits cycling frequency, constraining their use in variable renewable-hybrid microgrids.
- Carbon Compliance Cost Escalation:California's Cap-and-Trade program and EU ETS carbon border adjustments are structurally compressing diesel generator margins in urban zones.
Strategic Opportunities
- India Data Center Buildout:PLI scheme incentives for semiconductor and battery manufacturing are creating captive demand for indigenous critical power infrastructure.
- Healthcare Microgrids:NFPA 99 electrical system mandates for hospitals are opening design-build contracts integrating fuel cells with lithium-ion buffers.
- Edge Computing Nodes:5G base station densification in Brazil and South Korea requires modular UPS-fuel cell hybrids in 50-200kW footprints.
Industry Challenges
- Power Electronics Talent Scarcity:Silicon carbide inverter design and thermal management expertise pools concentrate at a handful of automotive suppliers, forcing critical power OEMs to poach or retrain.
- Multi-Chemistry Battery Integration:Deploying lithium-ion alongside emerging sodium-ion or solid-state cells in hybrid UPS architectures requires new battery management system firmware and fire suppression protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Critical Power Market |
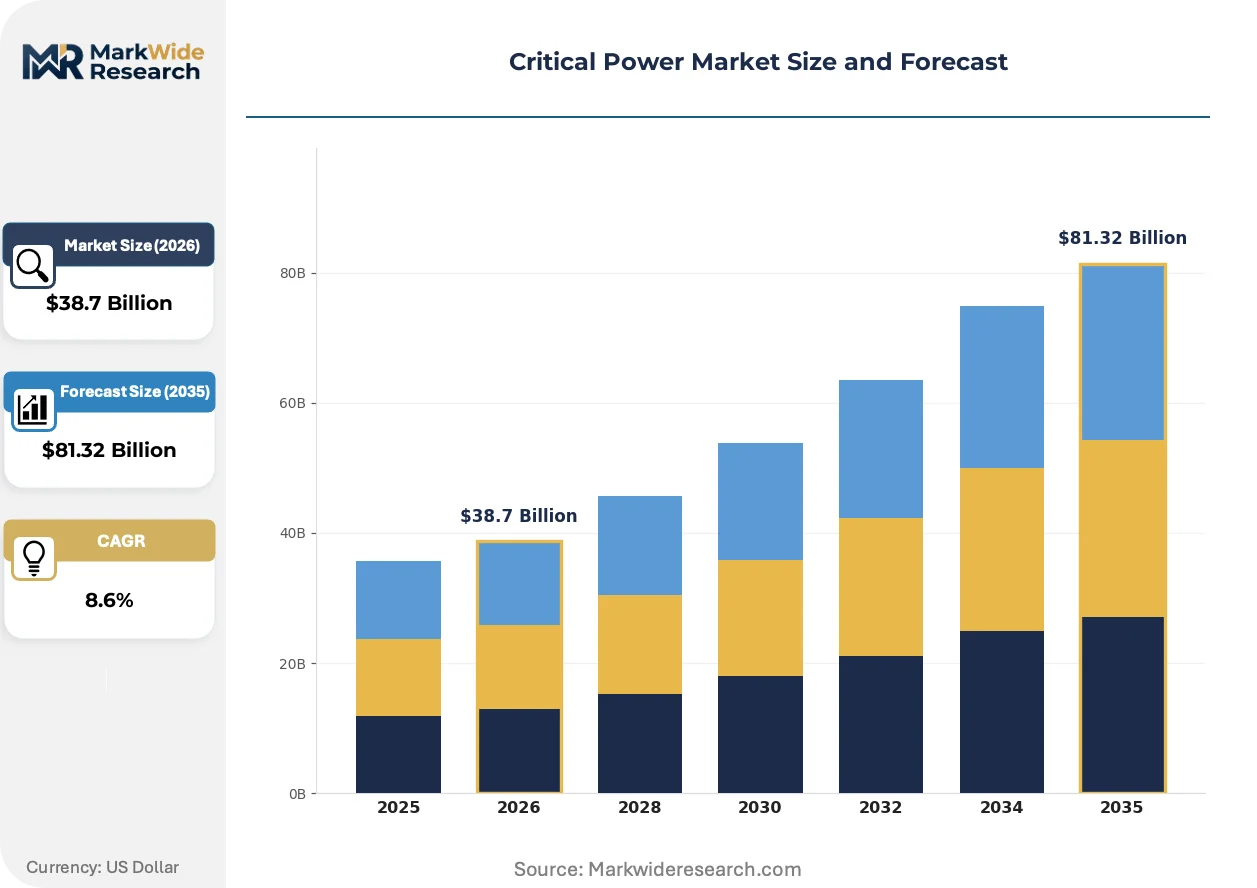
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Uninterruptible Power Supply, Diesel Generators, Gas Turbines, Fuel Cells End User: Healthcare, Data Centers, Manufacturing, Telecommunications Service Type: Maintenance, Installation, Consulting, Rental Technology: Hybrid Systems, Solar Power, Lithium-ion Batteries, Flywheel Storage |
| Companies Covered | Babcock & Wilcox, Bloom Energy, Siemens Energy, Wesco International, Baker Hughes, Hitachi Energy, Fluence Energy, Fluor Corporation, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Critical Power Market Emerging Trajectories
Fuel cell and battery hybrid architectures are displacing standalone diesel generators across mission-critical infrastructure, while solid-state power electronics compress switching losses and thermal footprint.
Silicon carbide MOSFETs replace legacy IGBTs in UPS inverters, cutting switching losses by two-thirds and enabling 50kW rack densities in hyperscale facilities. Google and Microsoft procurement specifications now mandate SiC-based designs for contracts above 10MW. This semiconductor transition is converging with liquid cooling architectures, allowing power electronics and compute loads to share thermal loops.
REACH substance restrictions and EU Battery Regulation due diligence rules are forcing European operators to document cobalt and lithium supply chains back to extraction. Siemens Energy and Schneider Electric have established dedicated compliance teams to audit smelter certifications. Medical device manufacturers in Germany face the tightest audit timelines, with notified body backlogs extending CE marking processes by 8-14 months.
Power-as-a-service contracts now capture 35% of new hospital and financial trading floor deployments, transferring CAPEX burdens to vendors who retain battery residual value. Eaton and Vertiv have built captive financing arms to capture this recurring revenue stream. This model penetrates fastest in the United States, where IRA investment tax credits reduce vendor cost of capital below commercial loan rates.
Critical Power Market Segmentation
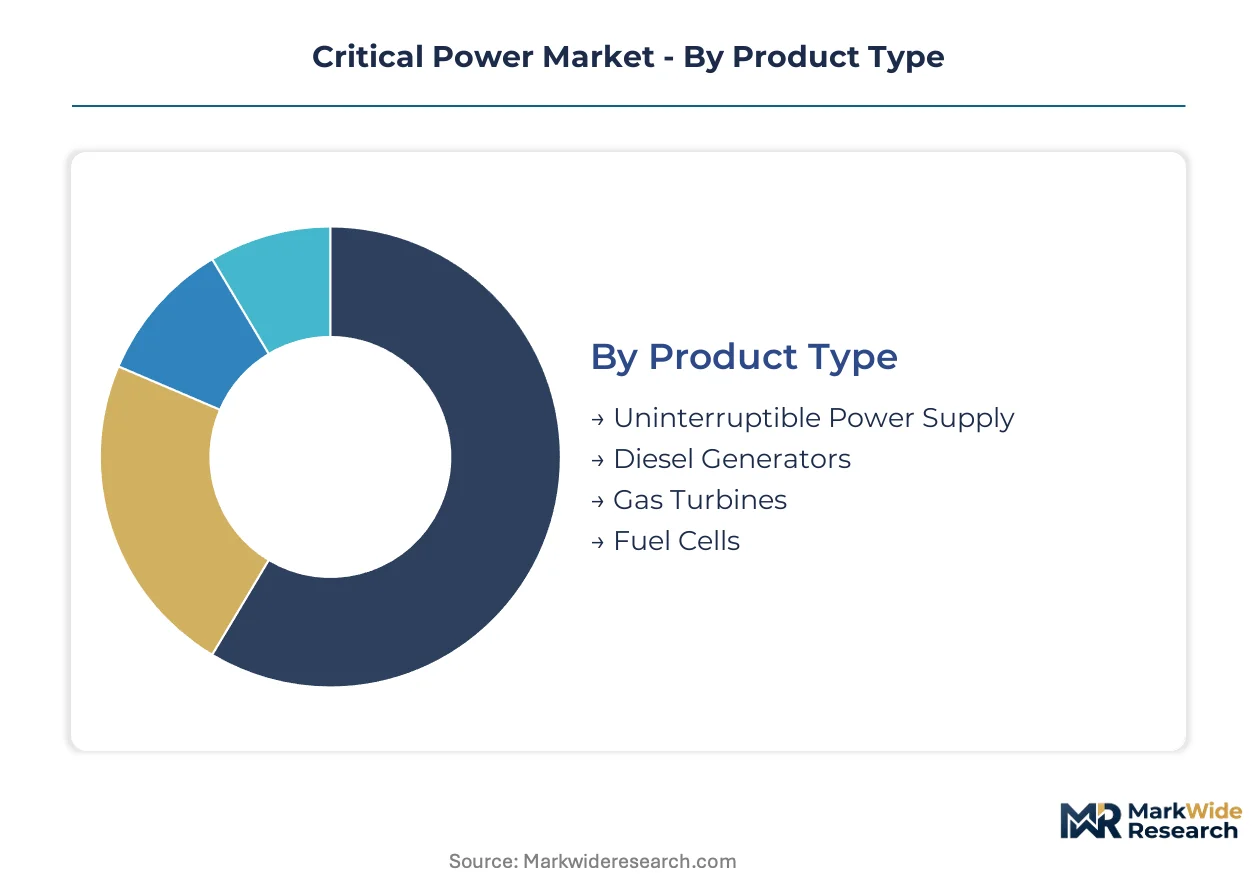
Critical power procurement decisions hinge on load characteristics, runtime requirements, and regulatory exposure. Equipment replacement cycles vary dramatically across segments—diesel generators face accelerated obsolescence from emissions rules, while UPS systems compress toward 7-year refresh intervals under silicon carbide transitions.
Product Type:
Upgrade urgency diverges sharply: silicon carbide inverter adoption is forcing premature UPS retirements, while diesel assets face stranded-value risk from carbon compliance costs.
- Uninterruptible Power Supply:Silicon carbide MOSFET architectures cut switching losses by two-thirds versus legacy IGBT designs. Hyperscale data center operators in the United States now mandate SiC-based specifications above 10MW, compressing procurement timelines from 18 months to under 9 months.
- Diesel Generators:Stationary engines face EPA Tier 4 final emissions mandates requiring selective catalytic reduction or exhaust gas recirculation retrofits. California and Texas data center projects increasingly exclude diesel from greenfield specifications due to Cap-and-Trade compliance costs and urban runtime permit restrictions.
- Gas Turbines:Hydrogen-ready turbine packages from Siemens Energy anchor industrial microgrid deployments in Germany and Japan electrolyzer clusters.
- Fuel Cells:Solid oxide systems from Bloom Energy sustain baseload operations for healthcare and telecom customers seeking zero-emission alternatives.
Diesel Generators sits at the top of the volume ranking, with Fuel Cells climbing the fastest.
End User:
Application-specific uptime requirements dictate equipment specification tiers—financial trading floors demand sub-4-millisecond transfer times, while manufacturing tolerates brief sags.
- Healthcare:NFPA 99 electrical system mandates and Joint Commission accreditation standards require emergency power supply systems with automatic transfer switches tested monthly. Surgical suites and intensive care units drive demand for online double-conversion UPS topologies with galvanic isolation.
- Data Centers:AI compute loads are tripling backup power density per rack, forcing operators to procure megawatt-class systems faster than manufacturers can expand silicon carbide inverter capacity. Google and Microsoft procurement specifications now exclude non-SiC designs for hyperscale contracts.
- Manufacturing:Semiconductor fabs and automotive paint lines require voltage sag ride-through capabilities, favoring rotary UPS and flywheel hybrids over battery-dependent architectures.
- Telecommunications:5G base station densification in Brazil and South Korea requires modular 50-200kW footprints combining fuel cells with lithium-ion buffers for remote site resilience.
Data Centers commands the steepest expansion trajectory, while Healthcare offers the most stable replacement revenue.
Service Type:
Contract structures are shifting from transactional installation toward recurring revenue models that capture battery residual value.
- Maintenance:Predictive analytics platforms using thermal imaging and impedance spectroscopy extend battery service intervals while reducing catastrophic failure risk. Eaton and Vertiv have built captive service arms to capture multi-year contracts.
- Installation:Silicon carbide inverter deployment requires specialized power electronics talent pools concentrated at automotive suppliers, forcing critical power OEMs to poach or retrain field technicians.
- Consulting:Microgrid design-build contracts integrating fuel cells with lithium-ion buffers are opening for engineering firms navigating NFPA 110 and OSHA electrical safety protocols.
- Rental:Temporary power for disaster recovery and planned maintenance favors trailer-mounted diesel and natural gas generators, though California emissions rules restrict deployment duration.
Maintenance generates the most recurring revenue, with Consulting gaining share fastest among new project development.
Technology:
Technology selection increasingly hinges on supply chain provenance and chemistry transition risk rather than pure performance metrics.
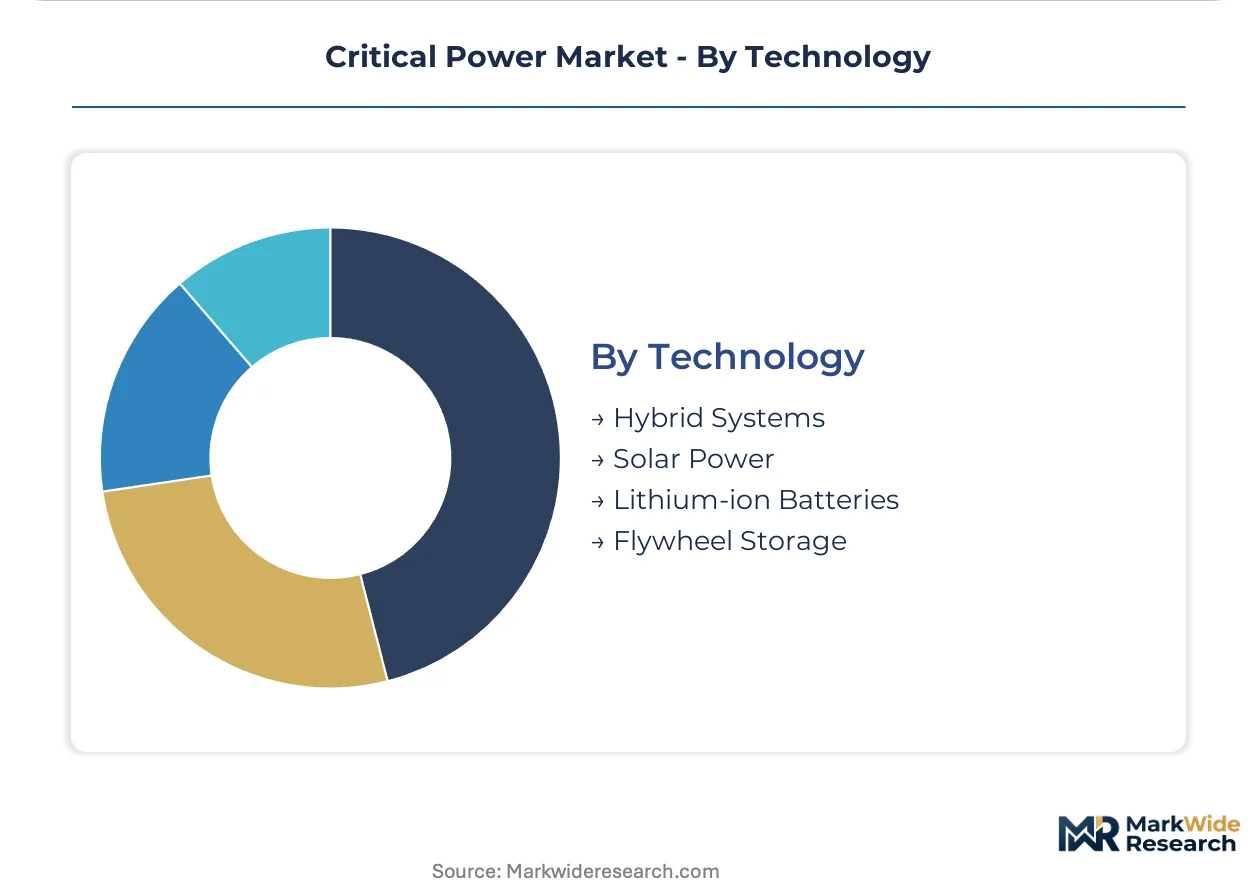
- Hybrid Systems:Fuel cell and battery combinations displace standalone diesel across mission-critical infrastructure, with solid oxide fuel cells providing baseload and lithium-ion buffers handling transient loads. Ceramic stack degradation above 850°C limits cycling frequency, constraining renewable-hybrid microgrid applications.
- Lithium-ion Batteries:Cathode precursor refining concentrates in China, exposing North American UPS manufacturers to forced labor due diligence risks and IRA domestic content penalties. Sodium-ion and solid-state alternatives require new battery management system firmware.
- Solar Power:Behind-the-meter PV integration with critical power systems requires anti-islanding protection and synchronized transfer controls.
- Flywheel Storage:Kinetic energy systems offer unlimited cycling for voltage sag correction in semiconductor manufacturing, though high capital cost limits penetration outside high-value process industries.
Lithium-ion Batteries dominates installed capacity, with Hybrid Systems expanding most quickly as hydrogen infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale data center construction in the United States is consuming megawatt-class UPS systems faster than manufacturers can expand silicon carbide inverter capacity. This concentration of AI-driven compute infrastructure is reshaping procurement patterns across major economies. The analysis examines five countries where critical power demand is structurally accelerating.
United States
Data center operators in Northern Virginia and Phoenix are tripling backup power density per rack to support AI workloads. The EPA's Tier 4 final emissions standards are forcing hospital and telecom migration to solid oxide fuel cells in California and Texas markets. Google and Microsoft procurement specifications now mandate silicon carbide-based designs for hyperscale contracts above 10MW.
Germany
Industrial microgrid deployments are clustering around electrolyzer facilities in the Rhineland and Bavaria. The EU Battery Regulation due diligence rules are forcing operators to document cobalt and lithium supply chains back to extraction. Siemens Energy anchors hydrogen-ready turbine packages for baseload operations in chemical corridor zones.
Japan
Electrolyzer deployment clusters are enabling fuel cell microgrids for semiconductor manufacturing in Kyushu and Kansai regions. METI hydrogen infrastructure roadmaps are accelerating solid oxide fuel cell adoption for mission-critical facilities. Tokyo-based financial institutions are specifying sub-4-millisecond transfer times for trading floor UPS systems.
India
PLI scheme incentives for semiconductor and battery manufacturing are creating captive demand for indigenous critical power infrastructure in Karnataka and Gujarat. The CEA mandates stringent grid reliability standards for data center certification. Mumbai and Hyderabad hyperscale facilities are compressing procurement timelines from 18 months to under 9 months.
South Korea
5G base station densification requires modular UPS-fuel cell hybrids in 50-200kW footprints across Seoul Capital Area and Busan-Ulsan. MFDS medical device regulations are extending CE marking alignment timelines for healthcare power systems. Samsung and SK Hynix semiconductor fabs are driving voltage sag ride-through specifications for critical power procurement.
Critical Power Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue fuel cell and battery hybrid architectures. The vendor base stratifies across integrated electrical infrastructure providers, gas turbine specialists, and solid oxide fuel cell innovators. Three archetypes dominate: captive battery cell suppliers, hydrogen-ready power solution providers, and power-as-a-service financiers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as procurement timelines compress.
Among diversified industrial conglomerates, Eaton and Siemens Energy exemplify scale-driven positioning across multiple technology vectors. Bloom Energy occupies a specialist position within the solid oxide fuel cell segment. These three companies represent contrasting strategic postures: integrated portfolio breadth, hydrogen-ready industrial power, and dedicated fuel cell innovation.
| Leading Market Players |
|---|
| Babcock & Wilcox |
| Bloom Energy |
| Siemens Energy |
| Wesco International |
| Baker Hughes |
| Hitachi Energy |
| Fluence Energy |
| Fluor Corporation |
| Eaton |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up service specialists have consolidated aftermarket maintenance networks across North America, tightening pricing discipline on multi-year UPS service contracts while squeezing independent distributors. This ownership concentration feeds into supply behavior through captive financing arms that bundle equipment procurement with residual value retention, compressing third-party margins.
Pricing Analysis
Input-cost pass-through from silicon carbide MOSFETs and lithium-ion cathode materials dominates equipment pricing, with OEMs indexing contract values to quarterly commodity benchmarks. Three-tier pricing structure across premium SiC-based systems, standard IGBT architectures, and economy-grade diesel generators differentiates by certification tier and thermal performance. Pricing pressure stems from IRA domestic content bonuses rewarding North American cell sourcing, compressing margins on China-dependent supply chains. Data center operators show lowest price sensitivity due to uptime penalties, while municipal telecom buyers negotiate hardest on total cost of ownership.
Supply Chain Analysis
Ocean freight rates from South Korean battery cell plants and Chinese silicon carbide wafer facilities dictate landed cost volatility for North American UPS assembly. Critical inputs concentrate in China for cathode precursor refining, South Korea for cell manufacturing, and Germany for power electronics engineering. Single-source vulnerability runs through ceramic stack suppliers for solid oxide fuel cells, where Bloom Energy maintains proprietary furnace capacity. Distribution runs through authorized dealer networks for enterprise accounts and direct OEM relationships for hyperscale contracts above 10MW.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Critical Power Market functions as a regulatory compounder, where EPA Tier 4 final emissions standards and IRA clean energy incentives structurally expand addressable demand for fuel cell and battery hybrid architectures.
For Market Incumbents: Deploy captive battery cell supply as the primary defensive lever. Eaton and Vertiv should expand silicon carbide inverter foundry partnerships to match Google and Microsoft procurement timelines compressed below nine months. Siemens Energy must anchor hydrogen-ready turbine capacity in Germany and Japan electrolyzer clusters before emerging fuel cell specialists capture industrial microgrid share. For New Entrants and Emerging Players: Solid-state battery chemistry offers a technology-first wedge into healthcare microgrid contracts where NFPA 99 mandates drive design-build opportunities. Target India's PLI scheme corridors in Karnataka and Gujarat, where indigenous critical power infrastructure demand outpaces established vendor presence. Lead with sodium-ion buffer systems that sidestep lithium-ion supply concentration and IRA domestic content penalties. For Investors and Strategic Acquirers: Valuations sit cheapest among power-as-a-service financiers with captive battery residual value models, not equipment manufacturers facing silicon carbide transition capex. Long-term viability hinges on hydrogen supply chain readiness and electrolyzer deployment velocity. Watch California Cap-and-Trade permit restrictions as the inflection signal for diesel generator stranded-value risk.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Foundry Partnership | Secures inverter capacity for hyperscale contracts above 10MW from Google and Microsoft. |
| Hydrogen Infrastructure Joint Venture | Positions turbine packages near Germany and Japan electrolyzer clusters for industrial microgrids. |
| Power-as-a-Service Financing Arm | Captures recurring revenue from hospital and financial trading floor deployments under IRA tax credits. |
| Solid Oxide Fuel Cell Stack Expansion | Addresses ceramic degradation limits above 850°C for renewable-hybrid cycling applications. |
| India PLI Scheme Localization | Aligns with CEA data center certification mandates in Mumbai and Hyderabad buildouts. |
Methodological Framework
Direct dialogue with data center procurement officers, hospital biomedical engineers, telecom infrastructure planners, and power electronics design leads grounded qualitative insights. Secondary validation drew from EPA stationary engine filings, FERC interconnection queues, hyperscaler capex disclosures, and silicon carbide supply chain databases. Bottom-up equipment shipment tallies and top-down grid reliability investment flows were triangulated against regulatory mandate timelines.
Segmentation-level outputs across UPS, diesel generator, gas turbine, and fuel cell product categories were projected alongside end-use splits in data centers, healthcare, manufacturing, and telecommunications. CAGRs were derived from equipment replacement cycle compression, emissions rule phase-ins, and hydrogen infrastructure deployment curves. Forecast inputs incorporated silicon carbide inverter adoption rates and lithium-ion versus sodium-ion chemistry transition probabilities.
The model holds under continued EPA Tier 4 enforcement and IRA credit continuity; deviation in hydrogen supply cost curves or semiconductor equipment lead times would shift fuel cell and SiC adoption trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Egypt Uninterruptible Power Supply (UPS) Market
Power
Middle East and Africa Combined Heat & Power Market
Power
Norway Power Market
Power
Green UPS Market
Power
Power Purchase Agreement Market
Power
Residential Portable Inverter Generator Market
Power
Angola Power EPC Market
Power
Mexico Power Market
Power
Power Rental Market
Power
Controllable Shunt Reactor for UHV Market
Power
Qatar Power Market
Power
Europe Frequency Converter Market
Power
Marine Thermal Fluid Heaters Market
Power
India Power Market
Power
Asia-Pacific Package Substation Market
Power
Denmark Power Market