
 North America Microturbine Market | 2026-2036
North America Microturbine Market Size, Share, and Industry Trends Forecast 2026-2036
North America Microturbine Market Insights
The gap between premium CHP-integrated systems and basic standalone units is shifting procurement criteria across the North America microturbine landscape. Capstone Green Energy Corporation leverages its recuperator technology to command premium positioning in combined heat and power installations. FlexEnergy Solutions sustains a niche in high-sulfur fuel applications where competitors struggle. Brayton Energy LLC anchors research-driven contracts with federal energy laboratories.
Microturbines are compact gas turbines typically rated below 500 kW, employing single-shaft designs with air bearings and recuperators to achieve electrical efficiencies of 25–35 percent; they serve primarily as distributed generation assets for baseload, backup, or prime power in locations with limited grid access. Natural gas configurations dominate current deployments, though biogas segments are gaining traction as landfill and agricultural digesters seek valorization pathways. The off-grid installation category occupies remote industrial sites, while combined heat and power systems capture the deepest margin pools through thermal energy credit stacking.
The EPA enforces emissions limits under the Clean Air Act that compel microturbine manufacturers to deploy lean-premix combustors and selective catalytic reduction, while FERC's Order 2222 facilitates aggregation of distributed resources into wholesale markets. State-level renewable portfolio standards in California and New York further widen addressable demand for biogas-fueled units. Stakeholders must weigh interconnection queue delays against the operational flexibility that microturbines provide at the grid edge.
Market Dynamics
The North America microturbine market is being fundamentally restructured by the EPA's tightening emissions thresholds for distributed generation, which force manufacturers to deploy lean-premix combustors and selective catalytic reduction systems while oil and gas operators accelerate flared gas-to-power deployments across Texas and the Permian Basin.
Growth Catalysts
- FERC Order 2222:The Federal Energy Regulatory Commission's aggregation mandate enables microturbine fleets to participate in wholesale electricity markets, unlocking new revenue streams for distributed resource owners in Texas and California.
- Flared gas valorization:Oil and gas operators in the Permian Basin and Bakken formation are deploying microturbines at wellheads to convert previously vented methane into grid-exportable power, reducing regulatory exposure under EPA methane rules.
- Biogas digester expansion:Agricultural and landfill gas projects across the Midwest and California are installing biogas-capable microturbines to monetize waste streams under state renewable portfolio standards.
Market Restraints
- Recuperator material costs:Nickel-based superalloy price volatility and supply concentration from specialty metal producers constrain margin expansion for OEMs manufacturing high-efficiency units.
- Interconnection queue delays:Regional transmission organizations across the US are processing distributed generation interconnection requests with 18-36 month backlogs, freezing project timelines and capital deployment.
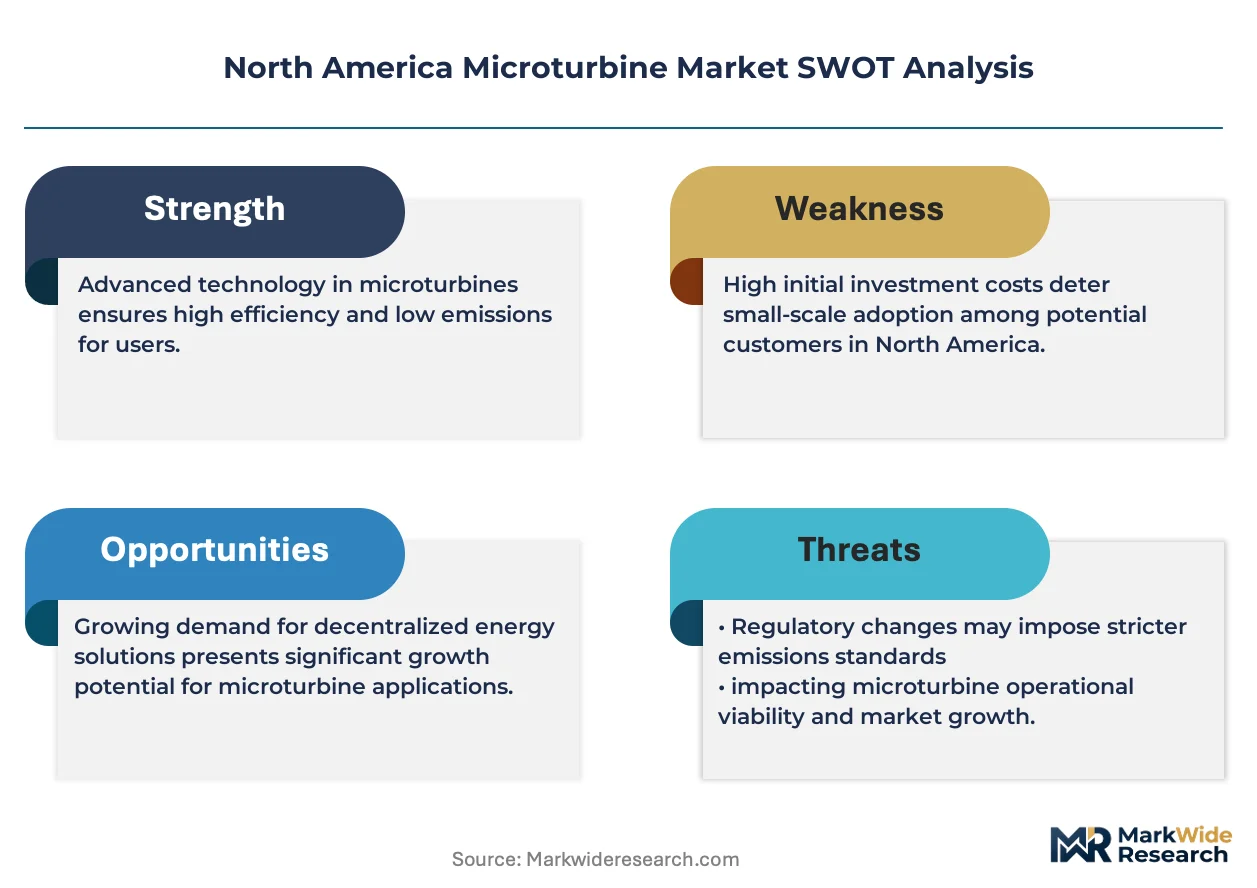
- Battery storage substitution:Lithium-ion battery systems with four-hour duration are capturing peak-shaving and backup power applications previously served by microturbines, particularly in California behind-the-meter installations.
Strategic Opportunities
- Mexico energy reform implementation:The Comisión Reguladora de Energía's opening of distributed generation markets creates first-mover positioning for US and Canadian OEMs in Baja California and industrial corridors near the border.
- Hydrogen fuel blending:Microturbine architectures capable of 30% hydrogen co-firing are absorbing pilot deployments at California wastewater treatment facilities seeking compliance with SB 100 decarbonization mandates.
- Energy-as-a-service channels:Third-party ownership models aggregating microturbine fleets for commercial and industrial campuses are displacing traditional equipment sales in Texas and New York deregulated markets.
Industry Challenges
- Combustion engineering talent scarcity:The specialized skill set required for lean-premix combustor design and emissions tuning is concentrated among a narrow cohort of gas turbine veterans, constraining R&D velocity.
- State-by-state certification fragmentation:Air quality districts in California, Texas, and New York maintain divergent permitting pathways for distributed generation, multiplying compliance engineering overhead for multi-state deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Microturbine Market |
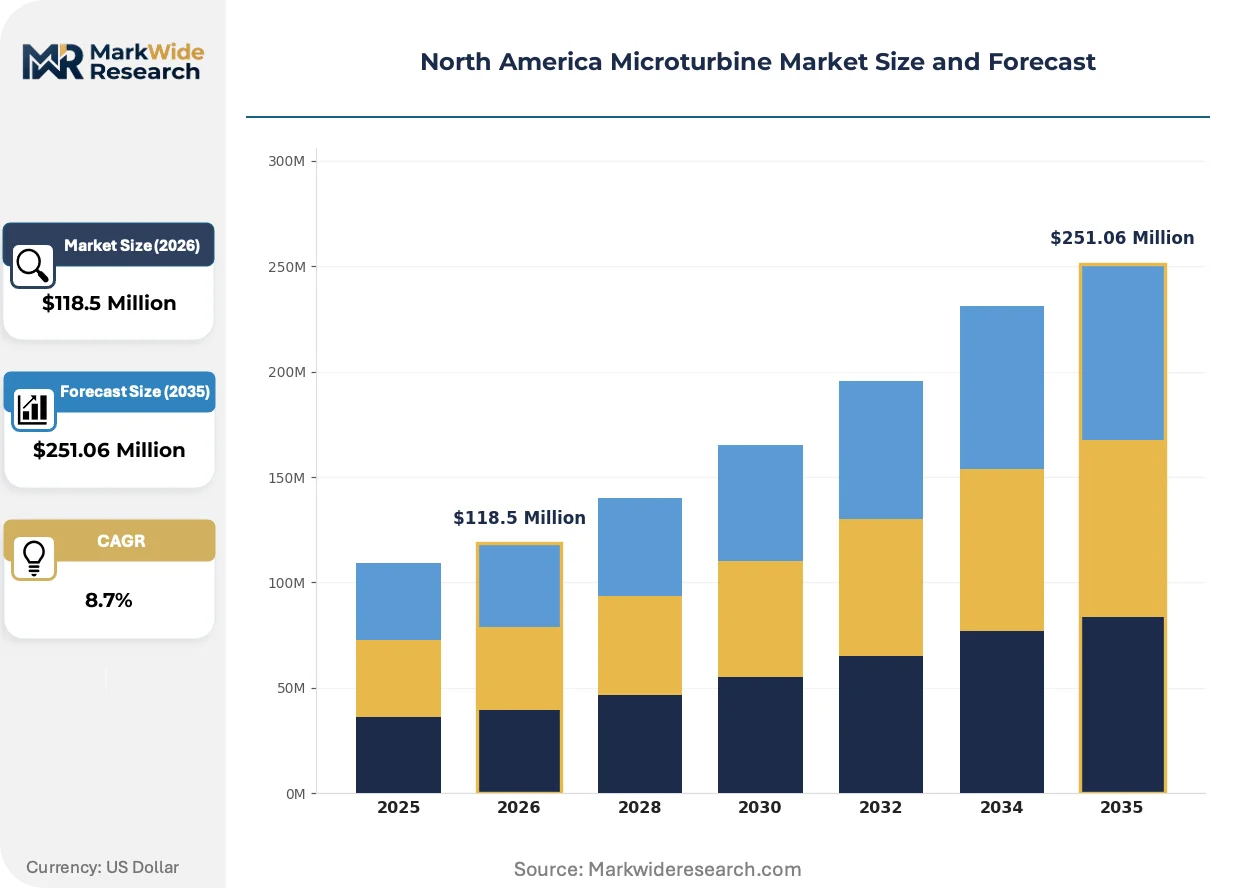
| Market Size in 2026 | $118.5 Million |
| Market Size in 2035 | $251.06 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Gas, Diesel, Biogas, Oil End User: Industrial, Commercial, Institutional, Residential Installation: On-Grid, Off-Grid, Combined Heat and Power, Standalone Application: Remote Power Generation, Backup Power, Peak Shaving, Renewable Integration |
| Companies Covered | Capstone Green Energy Corporation, FlexEnergy Solutions, Brayton Energy LLC, ICR Turbine Engine Corporation, UAV Turbines, Inc., Solar Turbines Incorporated, Calnetix Technologies LLC, Wilson Solarpower Corporation, Ansaldo Energia S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Microturbine Market Trends and Innovations
Technology convergence and regulatory stringency are compressing product development cycles across the North American microturbine landscape, with manufacturers racing to integrate hydrogen compatibility and digital remote monitoring before the next EPA compliance phase takes effect.
Recuperator technology is absorbing the primary engineering focus as OEMs pursue higher electrical efficiency to compete with fuel cells in combined heat and power applications. Oil and gas operators in the Permian Basin are piloting next-generation recuperator designs that push unit efficiency toward 35 percent. This efficiency compression is absorbing margin pressure from rising natural gas price volatility, allowing project economics to hold despite input cost fluctuations.
The EPA's Clean Air Act enforcement under the National Ambient Air Quality Standards is compelling manufacturers to certify lean-premix combustor variants across multiple output classes. Industrial facilities in non-attainment zones across California and Texas face construction moratoriums unless they deploy best available control technology, which now includes selective catalytic reduction for microturbines above 200 kW. The biogas-fueled segment is responding most aggressively, with landfill operators in the Northeast and agricultural digesters in the Midwest accelerating procurement to capture expiring state renewable energy credits.
Buyer contracting patterns are rotating from equipment ownership toward performance-based service agreements that bundle maintenance, fuel management, and carbon reporting. Commercial and industrial campuses in Texas and New York are displacing traditional capital purchase models with 10-15 year energy service contracts that transfer operational risk to OEMs or third-party aggregators. This shift is most visible in the data center vertical, where operators in Northern Virginia and Phoenix are procuring microturbine-backed microgrids through power purchase agreements rather than balance sheet deployment.
North America Microturbine Market Segmentation
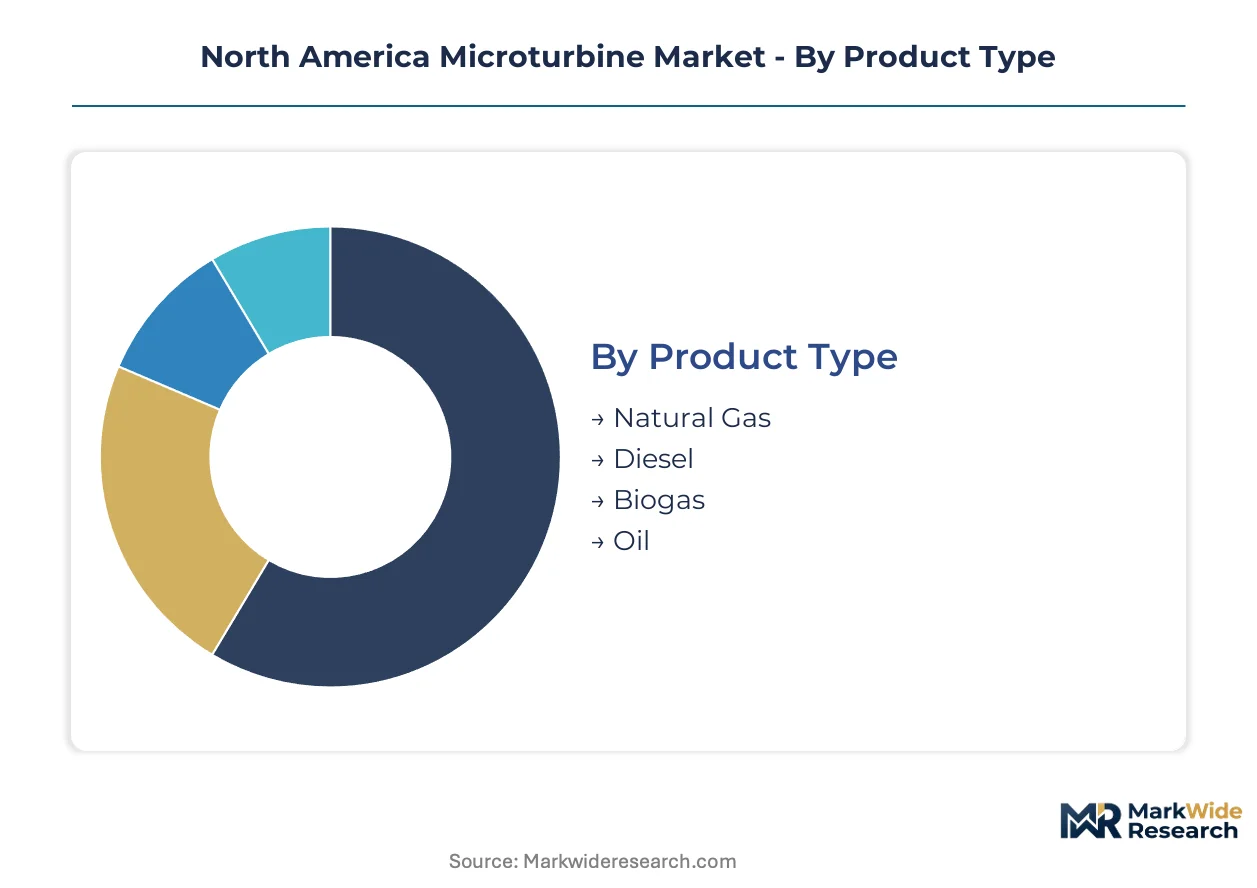
Microturbine procurement patterns across North America diverge sharply by fuel flexibility, grid interconnection strategy, and thermal energy recovery architecture. Understanding these segment boundaries clarifies why OEMs are restructuring product portfolios around recuperator efficiency tiers rather than raw output ratings.
Product Type:
Upgrade cycles in the North American microturbine market track fuel infrastructure maturity and emissions compliance trajectories, with operators replacing legacy diesel units ahead of EPA Tier 4 deadlines.
- Natural Gas:Configurations dominate current deployments through lean-premix combustor architectures optimized for pipeline gas specifications. Demand concentrates in Texas Permian Basin flared-gas-to-power projects where operators monetize previously vented methane under tightening EPA methane rules.
- Biogas:Systems require specialized fuel conditioning and sulfur-tolerant combustor materials to handle landfill and digester gas variability. California agricultural digesters and Northeast landfill operators are accelerating procurement to capture expiring state renewable energy credits ahead of program sunsets.
- Diesel:Units retain niche positioning for remote industrial sites lacking natural gas pipeline access, particularly in Alaska and northern Canadian territories.
- Oil:Configurations serve isolated mining camps and Arctic installations where liquid fuel logistics outperform gas infrastructure economics.
Natural Gas sits at the top of the volume ranking, with Biogas climbing the fastest.
End User:
Customer scale dictates maintenance contract structures and thermal energy monetization potential across the North American microturbine value chain.
- Industrial:Facilities deploy microturbines for combined heat and power integration with process steam or absorption cooling systems. Petrochemical complexes along the Texas Gulf Coast anchor demand through baseload power contracts and thermal energy credit stacking.
- Commercial:Campuses in deregulated Texas and New York markets favor energy-as-a-service procurement models over capital purchase. Third-party aggregators assume operational risk through 10-15 year performance contracts.
- Institutional:Universities and hospital systems leverage microturbines for resilience against grid instability, with FERC Order 2222 enabling wholesale market participation for aggregated campus fleets.
- Residential:Applications remain marginal due to capital intensity, limited to luxury estates and off-grid compounds in California fire-prone zones.
Industrial captures the deepest margin pools, while Commercial expands most quickly through third-party ownership channels.
Installation:
Interconnection queue delays and thermal load profiles determine whether operators pursue grid-tied or islanded microturbine architectures.
- Combined Heat and Power:Systems achieve maximum economic extraction through thermal energy credit stacking, requiring matched electrical and thermal load profiles. Data centers in Northern Virginia and Phoenix deploy CHP-backed microgrids through power purchase agreements.
- Off-Grid:Installations serve remote oil wellheads and mining operations where transmission extension costs exceed distributed generation capital. Permian Basin operators favor these configurations for flared gas valorization.
- On-Grid:Deployments face 18-36 month interconnection backlogs across Regional Transmission Organizations, freezing project timelines despite FERC Order 2222 aggregation benefits.
- Standalone:Units without thermal recovery occupy backup power niches where battery substitution pressure is intensifying.
Combined Heat and Power leads value capture, with Off-Grid gaining share fastest in oilfield electrification.
Application:
Duty cycle requirements and revenue stream diversity shape microturbine specification decisions across North American end-uses.
- Remote Power Generation:Applications demand ruggedized packaging and extended maintenance intervals for isolated sites. Alaska mining camps and Canadian Arctic installations specify these configurations.
- Backup Power:Systems face lithium-ion battery substitution in California behind-the-meter installations, though microturbines retain advantage for multi-day outage resilience.
- Peak Shaving:Deployments leverage FERC Order 2222 aggregation into wholesale markets, with Texas commercial campuses capturing demand response revenues.
- Renewable Integration:Biogas-fueled units paired with solar and storage anchor hybrid microgrids for California wastewater treatment facilities under SB 100 mandates.
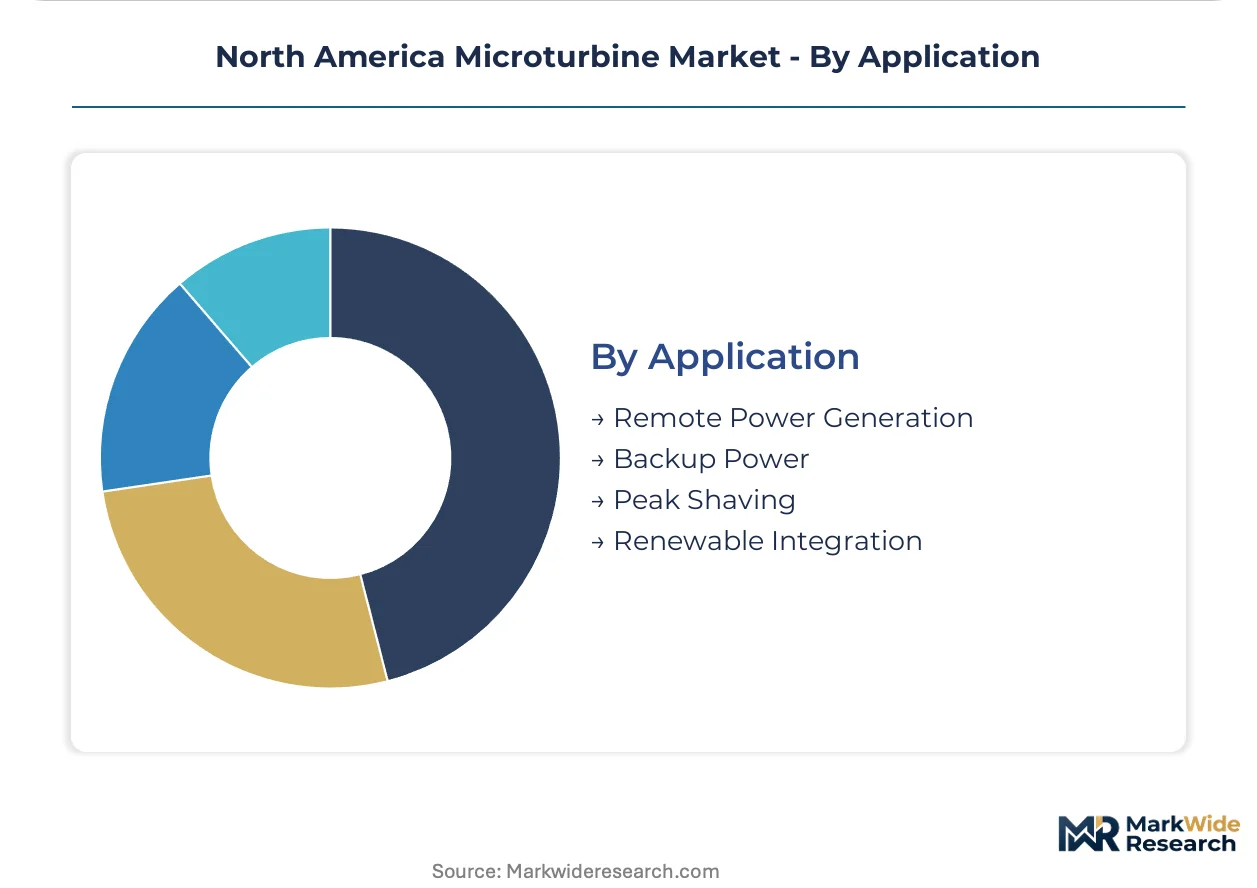
Remote Power Generation holds the largest installed base, with Renewable Integration posting the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States outpaces Canada in microturbine deployment velocity, while Mexico's energy reform creates new entry corridors for cross-border equipment suppliers.
United States
Texas Permian Basin operators deploy microturbines at wellheads to convert flared methane into exportable power under tightening EPA methane regulations. FERC Order 2222 enables aggregated distributed resources to access wholesale markets in California and Texas. Data centers in Northern Virginia and Phoenix procure CHP-backed microgrids through power purchase agreements rather than capital deployment.
Canada
Arctic mining camps and remote industrial sites in northern territories specify liquid-fuel microturbines where pipeline infrastructure proves uneconomical. Natural Resources Canada supports distributed generation pilots through technology demonstration programs. Alberta oil sands operators evaluate microturbine deployment for off-grid extraction power in Fort McMurray regional developments.
Mexico
The Comisión Reguladora de Energía's distributed generation market opening creates first-mover positioning for US and Canadian OEMs in Baja California industrial corridors. CFE interconnection reforms accelerate private power project approvals near the US border. Manufacturing clusters in Nuevo León and Tijuana explore on-site generation to manage electricity tariff volatility.
North America Microturbine Market Competitive Landscape
Top-tier vendors anchor recuperator technology leadership, while mid-tier specialists compete on fuel flexibility and regional service density. The vendor base stratifies across three efficiency tiers: premium CHP-integrated systems, standard grid-tied units, and ruggedized off-grid configurations. Strategic archetypes include technology licensors, energy-as-a-service aggregators, and federal research contractors. Competitive moves concentrate on hydrogen fuel blending certification and third-party ownership model expansion.
Within the technology-specialist tier, Capstone Green Energy Corporation and FlexEnergy Solutions exemplify divergent positioning strategies, with the former representing recuperator-integrated CHP systems and the latter occupying high-sulfur fuel tolerance niches. Brayton Energy LLC anchors the research-contractor archetype through federal laboratory relationships. These three entities collectively illustrate how competitive positioning fragments across thermal efficiency, fuel adaptability, and funding source dimensions rather than converging on uniform product specifications.
| Leading Market Players |
|---|
| Capstone Green Energy Corporation |
| FlexEnergy Solutions |
| Brayton Energy LLC |
| ICR Turbine Engine Corporation |
| UAV Turbines, Inc. |
| Solar Turbines Incorporated |
| Calnetix Technologies LLC |
| Wilson Solarpower Corporation |
| Ansaldo Energia S.p.A. |
| Others |
Pricing and Supply Chain Analysis
Nickel-based superalloy procurement from specialty metal producers cascades through recuperator manufacturing tiers, compressing margins for high-efficiency OEMs while forcing pricing stratification across premium CHP-integrated systems, standard grid-tied units, and ruggedized off-grid configurations.
Pricing Analysis
Capacity additions in Texas and California are reshaping price floors for microturbine fleets as FERC Order 2222 aggregation enables wholesale market participation. Three-tier pricing structure across premium, standard, and economy levels separates recuperator-integrated CHP systems from basic standalone units, with certification grade and thermal energy credit stacking as primary differentiation drivers. Cost compression in standard grid-tied tiers is intensifying because lithium-ion battery substitution erodes peak-shaving applications. Commercial campuses in deregulated markets exhibit highest price sensitivity, while oil and gas operators in the Permian Basin prioritize fuel flexibility over unit cost.
Supply Chain Analysis
Domestic-content mandates under the EPA's Clean Air Act enforcement are reshaping sourcing for lean-premix combustor components and selective catalytic reduction systems. Manufacturing concentrates in the United States, Canada, and Mexico under USMCA trade provisions, with critical dependencies on nickel superalloys, ceramic recuperator cores, and air bearing assemblies. Single-source vulnerability in specialty metal supply creates exposure to commodity price volatility. Distribution runs through OEM-direct channels for large industrial deployments and third-party energy-as-a-service aggregators for commercial campus installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America microturbine market offers margin-expansion pathways through recuperator efficiency upgrades that command premium positioning in combined heat and power installations.
For Market Incumbents: Hedge against battery storage substitution by deepening thermal energy credit stacking capabilities and securing long-term nickel superalloy offtake agreements. Prioritize hydrogen fuel blending certification to capture California SB 100 compliance-driven procurement. Lock in multi-state air quality district pre-certification to reduce permitting overhead for multi-site deployments. For New Entrants and Emerging Players: Capture white-space in Mexico's distributed generation market opening under Comisión Reguladora de Energía reforms, particularly in Baja California industrial corridors and Nuevo León manufacturing clusters. Target biogas-capable system demand from Midwest agricultural digesters seeking renewable energy credit monetization before program sunsets. Pursue energy-as-a-service channel partnerships rather than direct equipment sales to bypass incumbent service infrastructure. For Investors and Strategic Acquirers: Consolidation pressure builds where combustion engineering talent scarcity constrains R&D velocity for lean-premix combustor optimization. Long-term viability favors platforms with demonstrated hydrogen co-firing capability and established federal research laboratory relationships. Watch FERC interconnection queue reform progress as the signal for capital deployment acceleration in grid-tied segments.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Fuel Blending Certification | California wastewater treatment facilities under SB 100 mandates drive pilot deployments for 30% hydrogen co-firing capability. |
| Recuperator Efficiency Tier Expansion | Permian Basin oil and gas operators pilot next-generation designs pushing unit efficiency toward 35 percent threshold. |
| Energy-as-a-Service Channel Buildout | Texas and New York deregulated markets displace traditional equipment sales through third-party ownership aggregation models. |
| Biogas Fuel Conditioning Integration | Landfill operators in the Northeast accelerate procurement to capture expiring state renewable energy credit programs. |
| FERC Order 2222 Aggregation Platform | Wholesale market participation unlocks demand response revenue streams for commercial and industrial campus fleets. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads combine with secondary validation from EIA data, FERC filings, EPA emissions compliance databases, and project development registries. Cross-referencing OEM shipment records against interconnection queue filings enables triangulation of installed base estimates.
Input-output matrices map fuel source, generation capacity tier, and thermal recovery architecture across the projection horizon. Segmentation dimensions include natural gas, biogas, and hydrogen-compatible configurations; industrial, commercial, institutional, and residential end-users; and CHP, off-grid, on-grid, and standalone installation categories. CAGRs derive from regression analysis of historical deployment velocity against regulatory trigger timing and fuel price trajectory assumptions.
EPA methane rule enforcement stringency, nickel superalloy supply disruptions, and interconnection queue reform delays are the dominant revision risks to modeled outcomes. Forecasts embed assumptions regarding state renewable portfolio standard continuity and USMCA domestic content interpretation stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Mexico Power Market
Power
Qatar Power Market
Power
Uzbekistan Power Market
Power
Robotic Power Source Market
Power
Asia-Pacific Turbomachinery Control Systems Market
Power
Electric Arc Furnaces Market
Power
Brunei Power Market
Power
Statcom Market
Power
Asia-Pacific Package Substation Market
Power
Gabon Power Market
Power
Europe Frequency Converter Market
Power
High Voltage DC Power System Market
Power
Wireless Power Receiver Market
Power
Solar UPS Market
Power
North America CHP Market
Power
Europe Solar Inverter Market