
 Global Power Line Communication (PLC) Systems Market | 2026-2036
Global Power Line Communication (PLC) Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Power Line Communication (PLC) Systems Market Foresight
Multi-source procurement for PLC chipsets and modules is shifting toward vertically integrated supply arrangements among tier-one infrastructure vendors. Schneider Electric leverages captive semiconductor partnerships to secure OFDM controller supply for European utility rollouts. Siemens AG anchors its position through in-house powerline ASIC design capabilities that reduce dependency on external foundries. ABB competes by sustaining broad geographic manufacturing footprints across Switzerland, Poland, and China.
Power Line Communication systems transmit data over existing electrical wiring using modulated carrier frequencies, typically operating in the 3-500 kHz range for narrowband applications and extending to 30 MHz for broadband implementations. These systems enable bidirectional signaling between grid operators and endpoint devices without dedicated communication infrastructure. Orthogonal Frequency Division Multiplexing dominates utility-scale deployments due to superior noise immunity on low-voltage distribution lines. Smart Metering represents the most mature application segment with established margin pools, while Industrial Automation is gaining traction as factories integrate PLC-based device monitoring into legacy electrical networks.
The Federal Communications Commission in the United States governs PLC emissions under Part 15 rules, constraining signal power and frequency allocation to prevent interference with licensed services. The European Telecommunications Standards Institute maintains broadband PLC specifications that shape product certification requirements for CE marking and market access. China's Ministry of Industry and Information Technology oversees national PLC frequency bands through GB standards that differ from Western allocations. Stakeholders must monitor evolving electromagnetic compatibility regulations in each target jurisdiction to avoid costly redesign cycles.
Market Dynamics
Utility grid modernization mandates are compressing deployment timelines for OFDM-based powerline networks, forcing vendors to reconfigure supply chains around captive semiconductor capacity and regional certification requirements.
Growth Catalysts
- EU Green Deal smart metering mandates:The EU Green Deal requires 80% smart meter penetration by 2027, creating sustained procurement pull for narrowband PLC modules across Germany, Italy, and Spain.
- Industrial IoT retrofit demand:Manufacturing facilities in China and the United States are layering PLC-based condition monitoring onto existing motor control centers without rewiring infrastructure.
- Frequency harmonization:ETSI and IEEE standards convergence on CENELEC-A band definitions is reducing SKU fragmentation for multi-market product portfolios.
Market Restraints
- Silicon foundry concentration:Narrowband PLC modem production depends on 200mm analog-mixed foundry capacity concentrated in Taiwan and South Korea, exposing lead times to automotive chip demand cycles.
- Electromagnetic compatibility friction:FCC Part 15 emission limits in the United States constrain signal power below European allowances, forcing hardware redesigns for cross-Atlantic deployments.
- Wireless substitution threat:Low-power wide-area networks using unlicensed spectrum are capturing smart metering tenders in rural geographies where cellular backhaul exists.
Strategic Opportunities
- India's smart grid acceleration:India's Ministry of Power has tendered 250 million smart meters with domestic PLC requirements, creating localized manufacturing incentives under the PLI scheme.
- Vehicle-to-grid integration:Bidirectional charging protocols are converging with PLC standards for in-home energy management, opening automotive OEM partnerships.
- Building automation convergence:BACnet/IP over powerline is expanding into commercial HVAC retrofit markets where dedicated Ethernet cabling is cost-prohibitive.
Industry Challenges
- RF engineering talent scarcity:Mixed-signal designers capable of optimizing OFDM front-ends for noisy powerline channels command premium compensation in Germany and California.
- Multi-jurisdiction certification timelines:CE marking, FCC authorization, and China SRRC approval cycles for broadband PLC equipment often exceed 18 months, delaying revenue recognition.
- Legacy meter integration complexity:Hybrid deployments requiring protocol translation between DLMS/COSEM and proprietary AMR systems inflate commissioning costs for utilities with heterogeneous installed bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Power Line Communication (PLC) Systems Market |
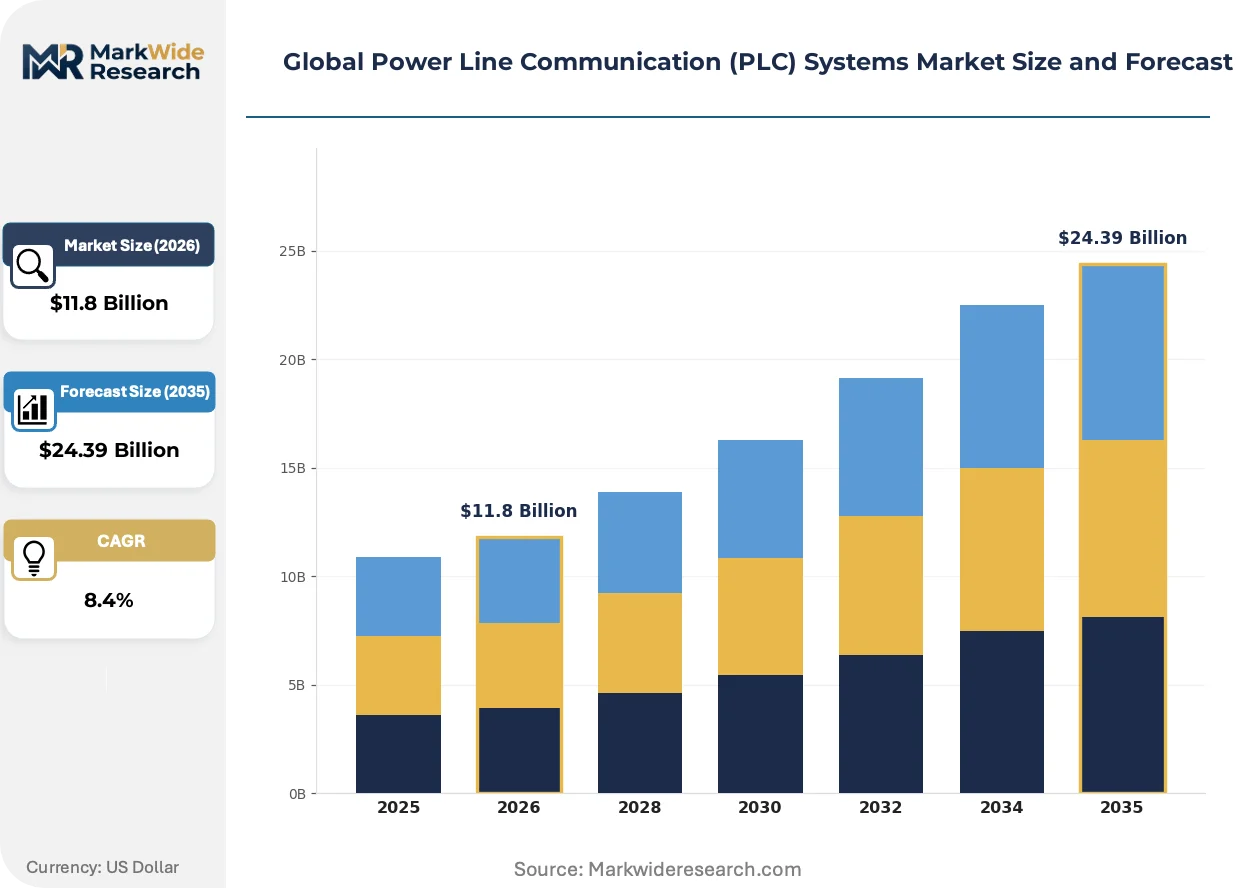
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Orthogonal Frequency Division Multiplexing, Spread Spectrum, Single Carrier, Wavelet, Time Division Multiplexing Application: Smart Metering, Home Automation, Grid Automation, Broadband Internet, Industrial Automation Product Type: Access PLC, In-House PLC, Outdoor PLC, Hybrid PLC, Narrowband PLC End User: Electric Utilities, Renewable Energy Operators, Industrial Facilities, Residential Communities, Commercial Complexes |
| Companies Covered | Schneider Electric, General Electric, Siemens AG, STMicroelectronics, Hitachi Energy Ltd., ABB, AMETEK Inc., TP-Link Technologies, Landis+Gyr Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Power Line Communication (PLC) Systems Market Shifts & Advancements
Orthogonal Frequency Division Multiplexing chipsets are penetrating adjacent industrial applications beyond their utility origins, while regulatory pressure on electromagnetic emissions intensifies design constraints across major economies.
G3-PLC and PRIME 1.4 physical layer implementations are expanding into electric vehicle supply equipment and solar inverter communication functions. Charging infrastructure OEMs in Germany and China are adopting these standards for plug-level data exchange without additional wiring. This technology migration is compressing development cycles for combined metering-communication system-on-chip designs.
The EU Green Deal's energy efficiency directives are tightening electromagnetic compatibility requirements for broadband PLC devices operating above 2 MHz. Manufacturers must now demonstrate compliance with updated ETSI EN 50561-3 limits before CE marking approval. Industrial automation vendors targeting European factory networks are redesigning coupling circuits to meet these thresholds.
Utility procurement departments are consolidating vendor relationships around full-stack system integrators rather than discrete component suppliers. State-owned grid operators in China and cooperative utilities in the United States now require turnkey deployment contracts spanning meters, concentrators, and head-end software. This behavioral shift favors vendors with captive installation service capabilities over pure-play chipset providers.
Global Power Line Communication (PLC) Systems Market Segmentation
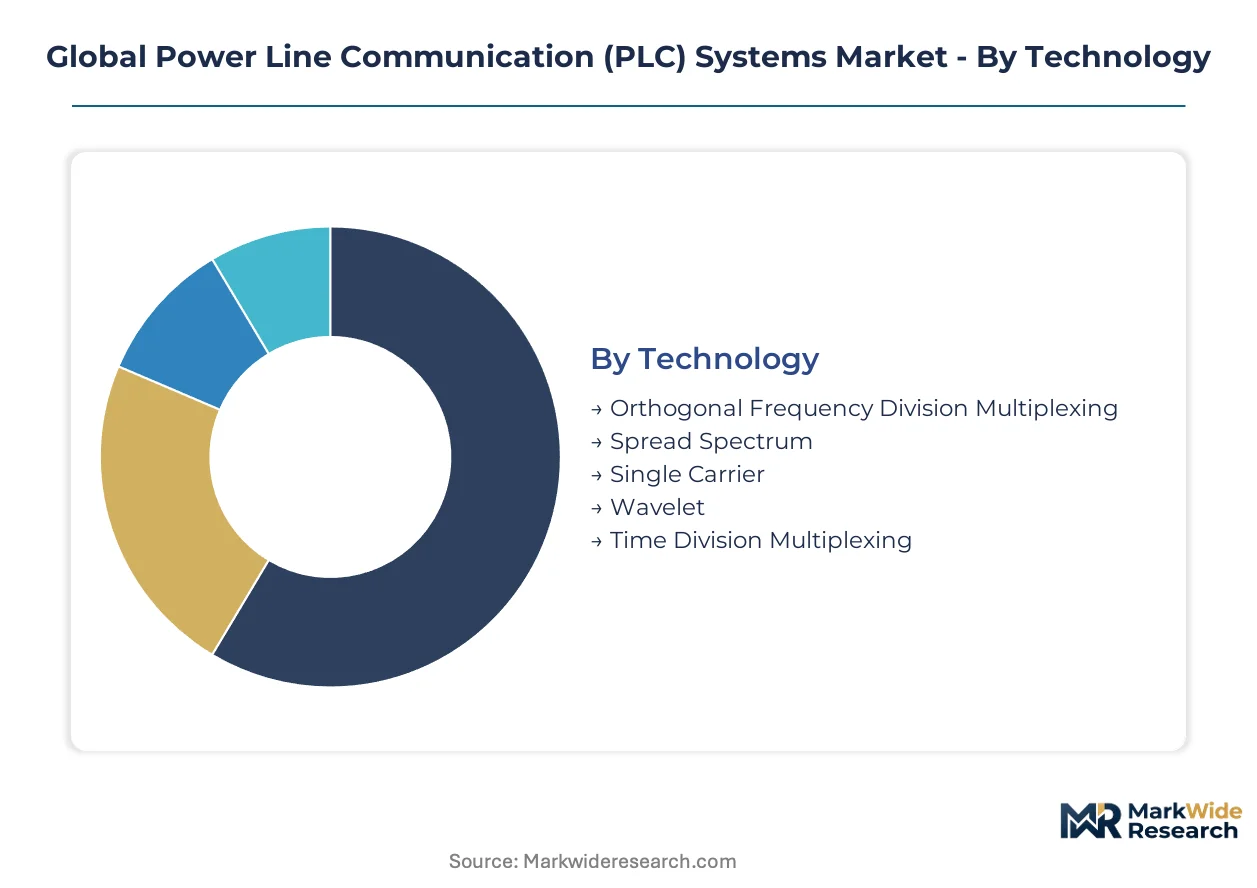
Technology and application boundaries in PLC systems determine which regulatory regimes apply. Vendors must align product architectures with specific certification pathways to avoid market exclusion.
Technology:
FCC Part 15 governs broadband implementations in the United States, while ETSI EN 50561-3 shapes CE marking requirements for European deployments. Narrowband standards face harmonization pressure across jurisdictions.
- Orthogonal Frequency Division Multiplexing:OFDM divides the powerline spectrum into multiple subcarriers, enabling robust data transmission despite electrical noise. Electric utilities in Germany and China specify OFDM for smart metering rollouts due to its superior performance on low-voltage distribution networks. ETSI and IEEE convergence on CENELEC-A band definitions is reducing SKU fragmentation for multi-market portfolios.
- Spread Spectrum:This technique spreads signal energy across a wide frequency band to resist interference and jamming. Industrial automation vendors in the United States favor spread spectrum for factory floor applications where motor drives generate substantial electrical noise. FCC emission limits constrain transmit power below European thresholds, forcing hardware redesigns for cross-Atlantic deployments.
- Single Carrier:Traditional narrowband approach using one frequency for data transmission.
- Wavelet:Advanced modulation using wavelet transforms for improved spectral efficiency.
- Time Division Multiplexing:Allocates distinct time slots to multiple data streams over shared powerline infrastructure.
OFDM sits at the top of the volume ranking, with Wavelet climbing the fastest as industrial vendors seek higher spectral efficiency.
Application:
End-use concentration varies sharply by geography. European procurement centers on smart metering mandates, while Chinese demand clusters around grid automation and industrial retrofit.
- Smart Metering:Bidirectional communication between utilities and endpoint meters for automated reading and load management. State-owned grid operators in China and cooperative utilities in the United States now require turnkey deployment contracts spanning meters, concentrators, and head-end software. The EU Green Deal mandates 80% smart meter penetration, creating sustained procurement pull across Germany, Italy, and Spain.
- Grid Automation:Real-time monitoring and control of transmission and distribution infrastructure. Electric utilities in China deploy PLC for substation automation and feeder line monitoring as part of national grid modernization programs. Frequency harmonization between ETSI and IEEE standards is accelerating cross-border equipment certification.
- Home Automation:Residential lighting, security, and climate control over existing wiring.
- Broadband Internet:High-speed data delivery in areas lacking fiber or cable infrastructure.
- Industrial Automation:Factory equipment monitoring layered onto legacy motor control centers without rewiring.
Smart Metering commands the largest revenue pool, with Industrial Automation expanding most quickly as manufacturing facilities prioritize retrofit connectivity.
Product Type:
Cost structures diverge between access-grade and premises-grade equipment. Outdoor installations carry premium pricing due to environmental hardening requirements.
- Narrowband PLC:Operates in the 3-500 kHz range for low-data-rate utility applications. Production depends on 200mm analog-mixed foundry capacity concentrated in Taiwan and South Korea, exposing lead times to automotive chip demand cycles. German utilities specify narrowband modules for residential smart meter deployments under EU Green Deal timelines.
- Access PLC:Last-mile connectivity from distribution transformers to customer premises.
- In-House PLC:Internal building networks for home and commercial automation.
- Outdoor PLC:Hardened equipment for pole-mounted and underground installations.
- Hybrid PLC:Combines powerline with wireless or fiber backhaul for redundancy.
Narrowband PLC leads volume shipments, with Hybrid PLC gaining share fastest as utilities seek resilient multi-path architectures.
End User:
Procurement authority concentrates differently across customer types. Electric utilities issue large tenders with extended qualification periods, while industrial buyers prioritize rapid deployment.
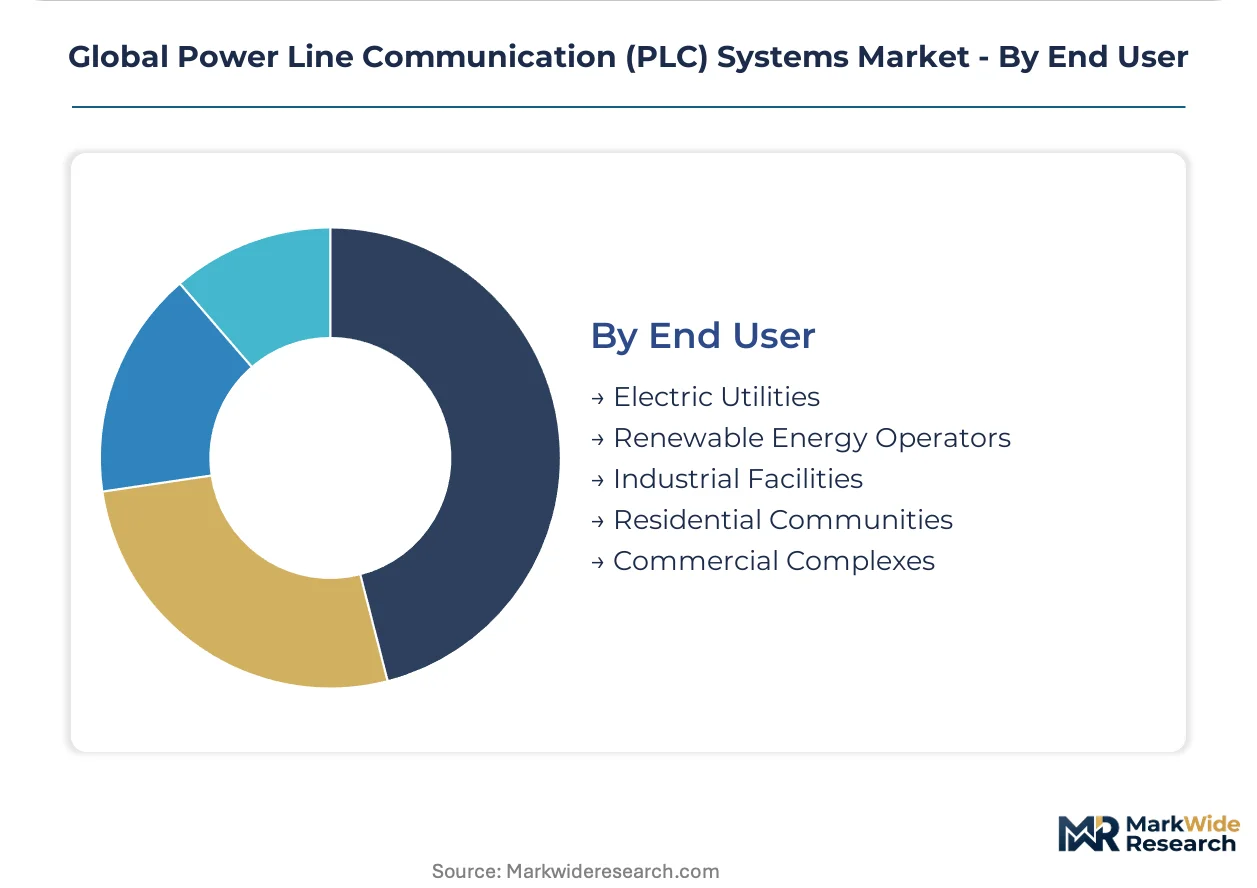
- Electric Utilities:Vertically integrated infrastructure owners operating transmission and distribution networks. China's State Grid Corporation tenders millions of PLC-enabled meters annually with domestic content requirements under the PLI scheme. Procurement departments are consolidating vendor relationships around full-stack system integrators rather than discrete component suppliers.
- Industrial Facilities:Manufacturing plants retrofitting condition monitoring onto existing electrical infrastructure. Factories in the United States and China layer PLC-based device monitoring into motor control centers without rewiring. BACnet/IP over powerline is expanding into commercial HVAC retrofit markets where dedicated Ethernet cabling is cost-prohibitive.
- Renewable Energy Operators:Solar and wind farms requiring inverter communication and grid integration.
- Residential Communities:Multi-unit dwellings and housing developments seeking shared infrastructure.
- Commercial Complexes:Office buildings, retail centers, and hospitality properties.
Electric Utilities anchor procurement volume, with Industrial Facilities showing the steepest expansion trajectory as IoT retrofit demand accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation clusters around Munich and Stuttgart generate concentrated PLC module procurement for factory energy management systems. State-level grid modernization programs in Bavaria and Baden-Württemberg specify OFDM-based powerline networks for substation monitoring.
Germany
Utility-scale smart meter deployments under the EU Green Deal mandate 80% penetration by 2027. ETSI EN 50561-3 electromagnetic compatibility standards shape product certification for CE marking. Siemens AG and ABB anchor manufacturing footprints across Switzerland, Poland, and domestic facilities near Zurich and Mannheim.
China
State Grid Corporation tenders millions of PLC-enabled meters annually with domestic content requirements. MIIT oversees national PLC frequency bands through GB standards that differ from Western allocations. Yangtze River Delta manufacturing clusters around Shanghai produce concentrators and head-end software for turnkey utility contracts.
United States
Cooperative utilities consolidate vendor relationships around full-stack system integrators for meter-to-cash operations. FCC Part 15 emission limits constrain signal power below European allowances, forcing hardware redesigns. Texas and California industrial facilities layer PLC-based condition monitoring onto existing motor control centers without rewiring infrastructure.
India
Ministry of Power tenders for 250 million smart meters specify domestic PLC requirements under the PLI scheme. Central Electricity Authority regulations mandate localized manufacturing incentives for grid infrastructure. Maharashtra and Gujarat industrial corridors host emerging assembly operations for narrowband modem production.
Japan
METI industrial IoT retrofit programs accelerate factory automation using powerline-based device monitoring. JIS standards govern electromagnetic compatibility for broadband PLC equipment in building automation. Kanto region electronics manufacturers integrate PLC chipsets into combined metering-communication system-on-chip designs.
Global Power Line Communication (PLC) Systems Market Competitive Landscape
Global majors compete with regional champions across technology licensing and captive semiconductor supply. The vendor base clusters around three tiers: diversified electrical equipment conglomerates with in-house ASIC design capabilities, specialized semiconductor firms supplying OFDM controllers, and system integrators delivering turnkey deployment contracts. Two dominant competitive moves define current positioning: backward integration into analog-mixed foundry partnerships and geographic expansion through regional certification acquisition.
Among European-based electrical equipment manufacturers, Schneider Electric, Siemens AG, and ABB exemplify the diversified conglomerate archetype. These entities occupy positions spanning captive semiconductor partnerships, in-house powerline ASIC capabilities, and broad geographic manufacturing footprints. STMicroelectronics represents the semiconductor specialist tier, supplying controller components to infrastructure vendors. Hitachi Energy Ltd. anchors the Asia-Pacific industrial automation segment. Landis+Gyr Group AG sits within the metering-focused system integrator category.
| Leading Market Players |
|---|
| Schneider Electric |
| General Electric |
| Siemens AG |
| STMicroelectronics |
| Hitachi Energy Ltd. |
| ABB |
| AMETEK Inc. |
| TP-Link Technologies |
| Landis+Gyr Group AG |
| Others |
Supply & Pricing Matrix
Analog-mixed foundry wafer costs cascade through narrowband PLC modem production into tiered hardware pricing that separates utility-scale deployments from industrial retrofit volumes, with 200mm capacity constraints in Taiwan and South Korea amplifying cost pass-through to German and Chinese procurement departments.
Pricing Analysis
Input-cost pass-through from semiconductor foundries shapes three-tier pricing structure across premium, standard, and economy levels for PLC chipsets and modules. Price differentiation hinges on certification grade—CE marking for European utility tenders versus FCC Part 15 authorization for North American deployments—and volume scale, with million-unit utility contracts commanding 30-40% discounts below industrial lot sizes. Cost compression in standard-tier modules is intensifying because automotive chip demand cycles are absorbing analog-mixed foundry capacity. Electric utilities exhibit lowest price sensitivity due to regulatory-mandated deployment timelines, while commercial building automation buyers demonstrate highest elasticity to hardware costs.
Supply Chain Analysis
RF engineering talent scarcity in Munich and Shanghai manufacturing clusters constrains production scaling for OFDM front-end optimization, forcing vendors to anchor assembly operations near design centers. Geographic supply concentration centers on Taiwan and South Korea for 200mm analog-mixed foundry output, with China and Germany hosting concentrator and head-end software integration. Raw material dependencies encompass silicon wafers, ferrite cores for coupling circuits, and epoxy molding compounds for environmental hardening. Single-source vulnerability pervades narrowband modem controller supply, where captive semiconductor partnerships at Schneider Electric and Siemens AG insulate against foundry allocation shocks. Distribution runs through direct utility procurement channels in China and cooperative buying consortia in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Power Line Communication Systems Market functions as a regulatory compounder where EU Green Deal smart metering mandates—specifically the 80% penetration requirement—generate irreversible procurement pull across German, Italian, and Spanish utilities.
For Market Incumbents: Extend captive foundry partnerships into long-term capacity reservation agreements to secure 200mm analog-mixed output against automotive demand cycles. Deepen backward integration into powerline ASIC design capabilities, following Siemens AG's in-house model, to reduce exposure to external semiconductor supply shocks. Prioritize multi-jurisdiction certification pre-positioning—CE marking, FCC authorization, and China SRRC approval—to compress 18-month approval timelines that delay revenue recognition. For New Entrants and Emerging Players: System integrators with turnkey deployment capabilities represent the most accessible channel partner type for penetrating utility procurement departments that now reject discrete component suppliers. Target India's 250 million smart meter tender under the PLI scheme, where domestic content requirements favor localized assembly operations over import-dependent competitors. Pursue vehicle-to-grid integration partnerships with automotive OEMs adopting G3-PLC standards for bidirectional charging protocols, a white-space segment with nascent competitive density. For Investors and Strategic Acquirers: Consolidation pressure builds where RF engineering talent scarcity intersects with multi-jurisdiction certification complexity, favoring acquisition of specialized semiconductor firms with proven OFDM controller portfolios. Five-to-ten-year viability favors vendors combining captive semiconductor supply with full-stack system integration capabilities. Monitor frequency harmonization progress between ETSI and IEEE standards as the inflection signal—convergence on CENELEC-A band definitions would eliminate SKU fragmentation penalties and accelerate margin recovery for multi-market product portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Semiconductor Partnership | Secures OFDM controller supply against automotive chip demand cycles absorbing Taiwan foundry capacity. |
| Multi-Jurisdiction Certification Pre-Positioning | Compresses CE marking, FCC authorization, and China SRRC approval timelines exceeding 18 months. |
| Turnkey Deployment Capability Buildout | Aligns with utility procurement consolidation around full-stack system integrators spanning meters and software. |
| Vehicle-to-Grid Protocol Integration | Captures automotive OEM partnerships as bidirectional charging converges with G3-PLC standards. |
| Regional Manufacturing Localization | Satisfies India's PLI scheme domestic content requirements for 250 million smart meter tenders. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility procurement officers, RF engineering directors at infrastructure vendors, semiconductor foundry planning executives, and regulatory affairs specialists at certification bodies with secondary validation against ETSI standards documentation, FCC Part 15 rulemakings, MIIT GB standard filings, and utility tender databases. Bottom-up shipment modeling for narrowband and broadband PLC modules triangulated against top-down grid modernization expenditure forecasts across German, Chinese, and United States markets.
Comparable-period anchoring linked historical deployment trajectories from EU Green Deal pilot programs through national smart grid acceleration initiatives to projection assumptions across the analysis window. Segmentation dimensions encompassed technology modulation type, application end-use, product bandwidth tier, and end-user procurement authority. CAGRs derived from logistic diffusion modeling of smart meter penetration curves, with inputs including foundry capacity utilization rates and frequency harmonization progress between standards bodies.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electromagnetic compatibility regulatory tightening, wireless substitution acceleration in rural cellular backhaul zones, and silicon foundry capacity reallocation toward automotive electrification. Forecasts reflect documented assumptions regarding standards convergence timelines and utility procurement behavioral shifts. Material deviation in EU Green Deal enforcement intensity or China's State Grid tender pacing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Middle-East and Africa Power Market
Power
Uzbekistan Power Market
Power
Russian Federation Power Market
Power
Vietnam Power Market
Power
Robotic Power Source Market
Power
Middle-East and Africa Power Rental Market
Power
Residential Portable Inverter Generator Market
Power
Europe Solar Inverter Market
Power
India Uninterruptible Power Supply (UPS) Market
Power
Global Ancillary Services Power Market
Power
Malaysia Power EPC Market
Power
Smart PV Inverters Market
Power
Qatar Power Market
Power
Oxy-Hydrogen Generators Market
Power
Global Advanced Marine Power Supply Market
Power
Temporary Load Bank Rental Market