
 High Voltage DC Power System Market | 2026-2036
High Voltage DC Power System Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage DC Power System Market Insights
IEC 62501 qualification for voltage source converters is unwinding the competitive landscape for smaller power electronics suppliers. Siemens Energy leverages its manufacturing scale across European converter stations. ABB Ltd. anchors its position through R&D intensity in modular multilevel converter architectures. Hitachi Energy Ltd. competes on geographic dominance in Asia-Pacific submarine cable projects.
High voltage DC power systems transmit electrical energy at direct current above 100 kV through overhead lines, submarine cables, or back-to-back converters, using thyristor or insulated-gate bipolar transistor switching to minimize reactive power losses over long distances. The primary purpose is bulk power transfer between asynchronous grids and integration of remote renewable generation. Voltage source converter technology leads deployment in offshore wind connections due to its black-start capability and compact footprint. Modular multilevel converter designs capture expanding margin pools as utilities prioritize grid stability services. Current source converter installations remain concentrated in mature point-to-point bulk transmission corridors.
FERC Order 2023 in the United States, the EU Green Deal framework, and China's GB/T 30553 standard collectively shape HVDC deployment timelines, interconnection rules, and equipment certification requirements. Germany's Bundesnetzagentur and China's National Energy Administration enforce grid codes that determine converter station technical specifications. Stakeholders must monitor regulatory harmonization between IEC standards and national grid codes as project developers evaluate supplier qualification status across multiple jurisdictions.
Market Dynamics
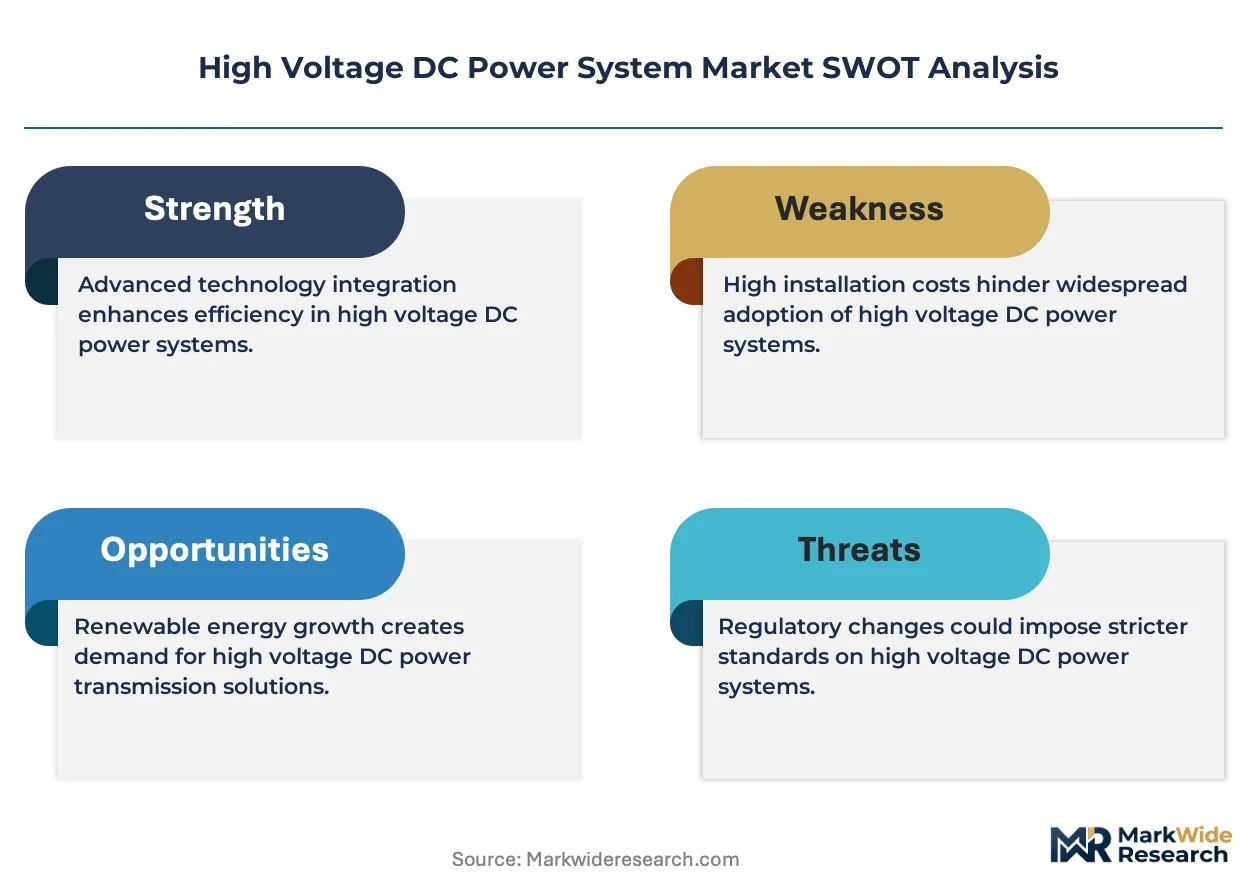
Silicon carbide semiconductor adoption is compressing converter station footprints and forcing incumbent suppliers to retool manufacturing lines or cede offshore wind procurement to qualified competitors.
Growth Catalysts
- Offshore wind integration mandates:Germany's Bundesnetzagentur and China's National Energy Administration enforce grid codes requiring HVDC connections for remote renewable clusters. Voltage source converter stations capture these procurement cycles.
- IEC 62501 qualification protocols:Standardized testing for voltage source converters accelerates supplier certification timelines. Utilities in the United States reference these protocols in FERC Order 2023 interconnection filings.
- Submarine cable corridors:Point-to-point bulk transmission projects across the North Sea and East China Sea drive demand for modular multilevel converter architectures with black-start capability.
Market Restraints
- Silicon carbide substrate shortages:Wafer supply concentrates among Japanese and US substrate manufacturers. Converter station lead times extend when semiconductor foundry capacity tightens.
- Specialized engineering talent scarcity:Power electronics design for HVDC systems requires hybrid expertise in high-voltage engineering and semiconductor physics. European technical universities produce insufficient graduates.
- Thyristor-based current source converter lock-in:Mature bulk transmission corridors in India and Brazil resist retrofitting to voltage source technology despite efficiency penalties.
Strategic Opportunities
- US-Mexico border interconnection projects:FERC Order 2023 streamlines permitting for asynchronous grid links. Developers seek pre-qualified converter station suppliers for Texas-California renewable corridors.
- Green hydrogen electrolyzer coupling:Offshore wind farms in the North Sea require co-located DC power systems for direct electrolyzer feed. Modular multilevel converters enable this integration.
- EU Green Deal carbon border adjustments:Imported HVDC equipment faces embodied carbon scrutiny. European converter station manufacturers leverage regional supply chains for qualification advantage.
Industry Challenges
- IEC 62501 certification timeline compression:Testing protocols for voltage source converters require 18-24 months. Project developers in Germany and China penalize suppliers missing qualification deadlines.
- Legacy thyristor system integration complexity:Back-to-back converter upgrades demand hybrid control architectures. Engineering teams struggle to synchronize current source and voltage source technologies.
- Submarine cable repair skill gaps:HVDC cable faults at depths exceeding 500 meters require specialized vessel fleets. North Sea maintenance contractors report technician shortages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage DC Power System Market |
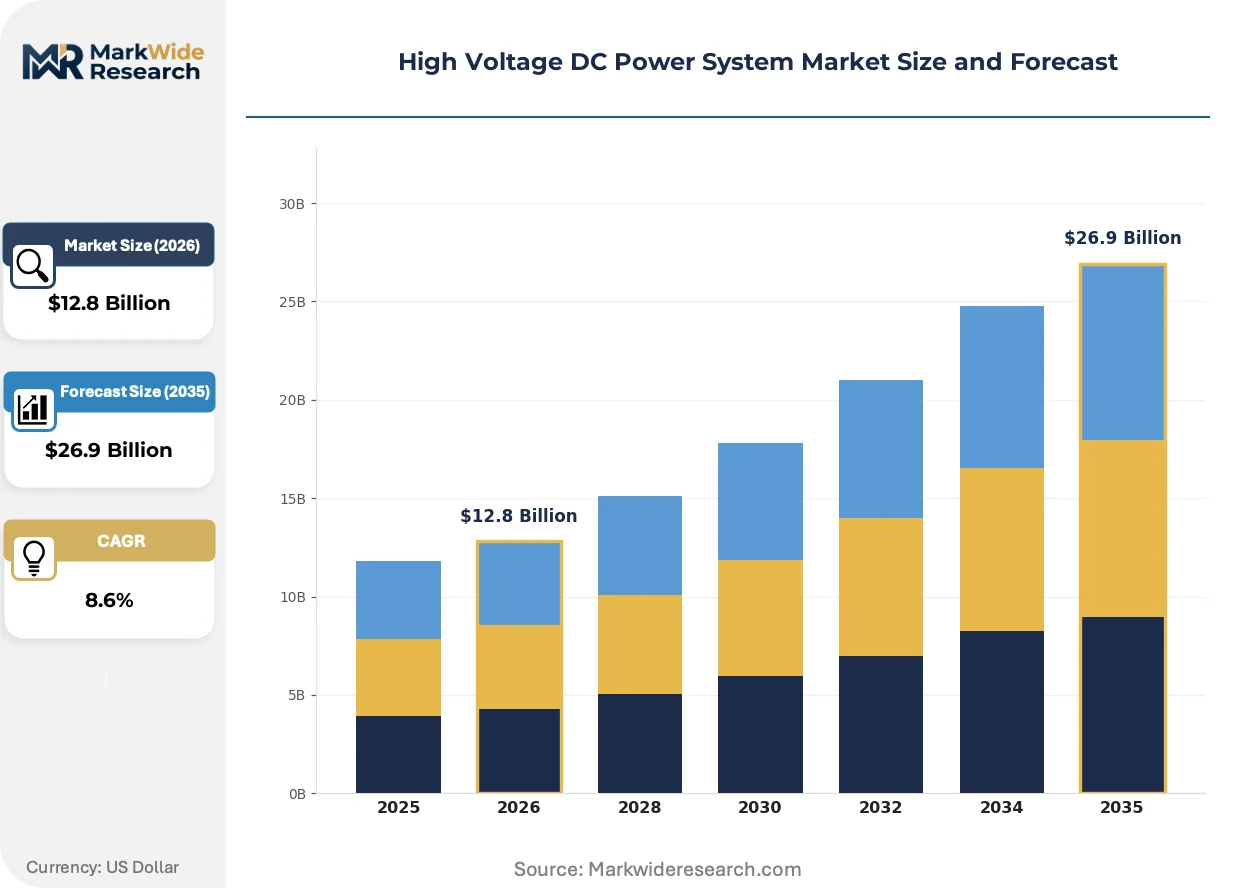
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Voltage Source Converter, Current Source Converter, Modular Multilevel Converter, Hybrid Converter Application: Renewable Energy Integration, Power Transmission, Electric Vehicles, Industrial Drives End User: Utility Providers, Manufacturing Sector, Transportation, Commercial Buildings Installation Type: Grid-connected, Off-grid, Brownfield, Greenfield |
| Companies Covered | Siemens Energy, General Electric Company, ABB Ltd., Toshiba Corporation, NKT A/S, LS Electric Co. Ltd, Mitsubishi Electric Corporation, Hitachi Energy Ltd., Prysmian Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage DC Power System Market Trends and Innovations
Power semiconductor material transitions and regulatory harmonization pressures are restructuring supplier qualification requirements and procurement evaluation criteria across HVDC project development.
Silicon carbide metal-oxide-semiconductor field-effect transistors enable higher switching frequencies at elevated temperatures compared to silicon insulated-gate bipolar transistors. Offshore wind developers in Germany and China specify SiC-based converter stations for platform weight reduction. This semiconductor transition is supplanting traditional thyristor architectures in new submarine cable projects.
The EU Green Deal framework mandates embodied carbon disclosure for grid infrastructure procurement. Germany's Bundesnetzagentur incorporates lifecycle emissions into converter station bid evaluation. European suppliers with regional semiconductor sourcing gain qualification preference over import-dependent competitors.
Utility procurement teams unbundle converter station supply from turnkey engineering contracts. Developers in the United States separately tender power modules, control systems, and installation services. This disaggregation compresses supplier margins but accelerates technology refresh cycles in competitive offshore wind auctions.
High Voltage DC Power System Market Segmentation
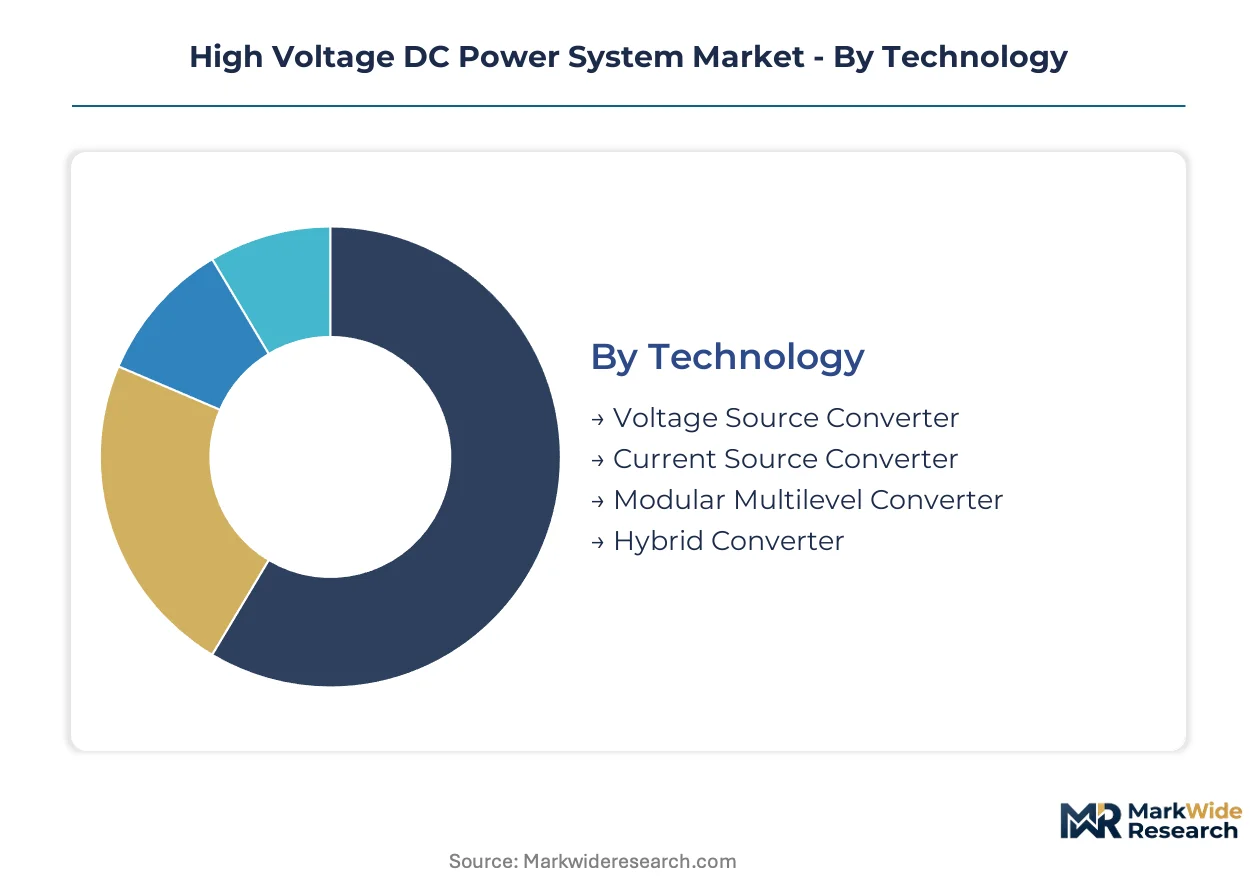
HVDC procurement channels diverge sharply by technology maturity and project scale. Utility buyers route voltage source converter orders through specialized EPC contractors, while industrial end users favor direct manufacturer relationships for smaller modular installations.
Technology:
Channel mix splits between turnkey station providers for bulk transmission and component suppliers for distributed renewable integration.
- Voltage Source Converter:IGBT and SiC-based switching enables black-start capability and compact offshore platform designs. Procurement concentrates in Germany's North Sea wind clusters and China's coastal renewable bases, where IEC 62501 qualification filters supplier pools.
- Modular Multilevel Converter:Stacked sub-module architecture delivers superior waveform quality and reduced filter requirements. Demand clusters in submarine cable corridors linking Norway to Germany and across the East China Sea, driven by grid stability service requirements.
- Current Source Converter:Thyristor-based line-commutated technology serves legacy bulk transmission corridors in India and Brazil with mature maintenance ecosystems.
- Hybrid Converter:Combines CSC reliability with VSC control flexibility for retrofit applications and asynchronous grid interconnections.
Voltage source converter dominates installed base. Modular multilevel converter is where expansion concentrates.
Application:
Cost tiering separates billion-dollar interconnector projects from sub-100MW industrial installations.
- Renewable Energy Integration:Offshore wind farms in Germany, China, and the United States mandate HVDC for distances exceeding 80 kilometers. Siemens Energy and ABB Ltd. capture procurement through pre-qualified converter station platforms.
- Power Transmission:Point-to-point bulk corridors across the North Sea and US-Mexico border drive demand for 500kV+ submarine and underground cable systems.
- Electric Vehicles:Fast-charging infrastructure and battery manufacturing plants require medium-voltage DC distribution with power quality management.
- Industrial Drives:Mining and steel operations in Australia and South Africa deploy HVDC for long-distance motor control and process efficiency.
Power transmission commands the highest project values. Renewable energy integration is expanding most quickly.
End User:
Customer type determines specification rigor and contract structure across procurement cycles.
- Utility Providers:Grid operators in Germany, China, and the United States enforce IEC 62501 and national grid code compliance through multi-year qualification programs.
- Manufacturing Sector:Aluminum smelters and semiconductor fabs require stable DC supply for electrolytic processes, sourcing through direct OEM relationships.
- Transportation:Railway electrification and port authorities in Japan and South Korea adopt HVDC for traction power and shore-to-ship connections.
- Commercial Buildings:Data centers in Singapore and the Netherlands trial DC microgrids for efficiency gains, though volume remains constrained by standardization gaps.
Utility providers anchor procurement volumes. Manufacturing sector offers the steepest expansion trajectory.
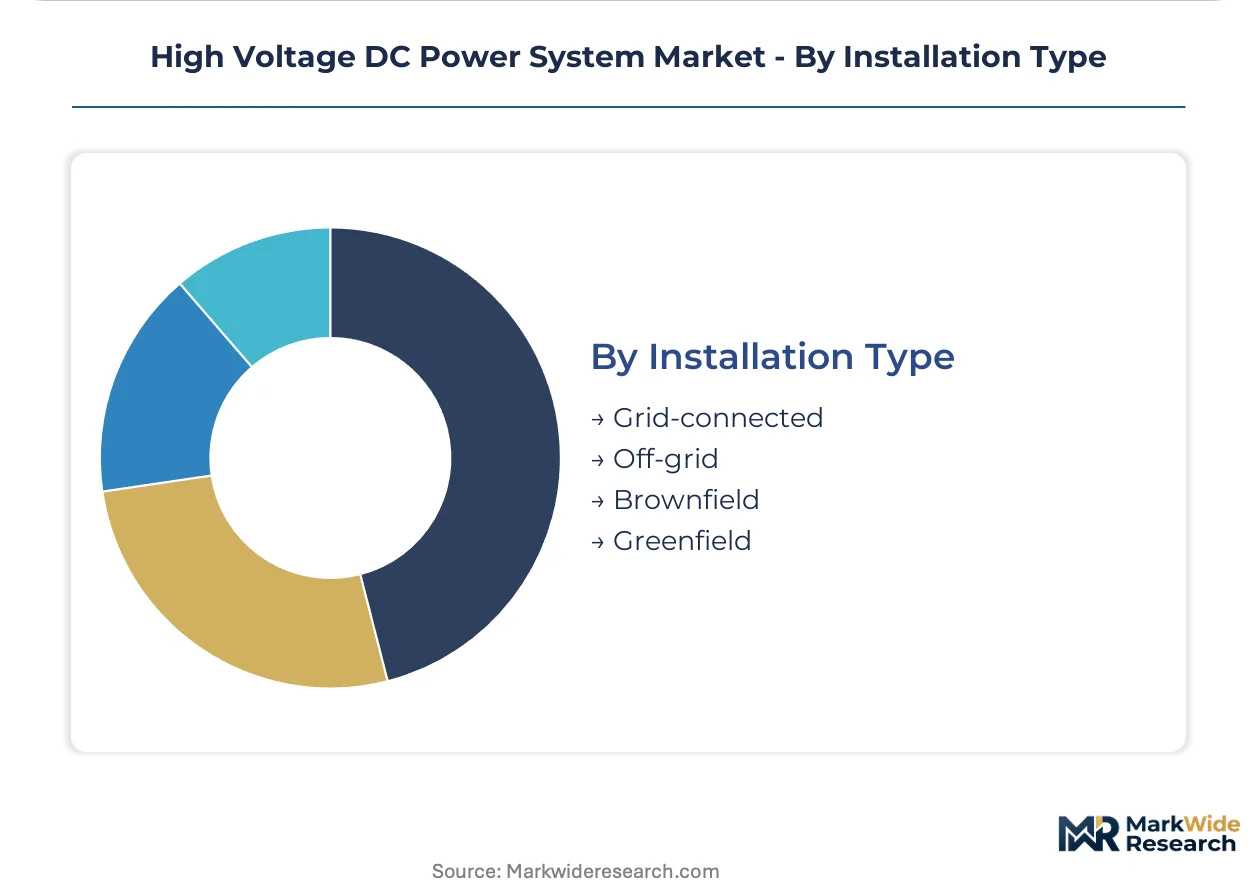
Installation Type:
Maturity gradient separates established grid codes from emerging technical standards.
- Grid-connected:Synchronous interconnection to national transmission networks requires compliance with Bundesnetzagentur, China's National Energy Administration, or FERC Order 2023 protocols.
- Brownfield:Retrofit of existing thyristor stations with hybrid control architectures addresses aging infrastructure in India and Brazil.
- Off-grid:Remote mining and island systems in Australia and Indonesia deploy containerized solutions with limited vendor competition.
- Greenfield:New converter stations benefit from SiC semiconductor integration and modular construction, though permitting timelines extend in Germany and the United States.
Grid-connected captures current revenue concentration. Greenfield is gaining share fastest as renewable buildouts accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility procurement teams in Germany, China, and the United States concentrate the majority of HVDC converter station orders. These buyers route contracts through specialized EPC contractors for bulk transmission projects while maintaining direct manufacturer relationships for smaller modular installations.
Germany
Offshore wind developers in the North Sea cluster drive voltage source converter demand for platform weight reduction. Bundesnetzagentur enforces grid codes requiring IEC 62501 qualification for all new interconnector projects. Siemens Energy anchors converter station manufacturing in Bavaria while supplying North Sea wind farm connections.
China
Coastal renewable bases along the East China Sea mandate HVDC for distances exceeding 80 kilometers. National Energy Administration protocols align with GB/T 30553 standards for equipment certification. State Grid Corporation concentrates procurement in Jiangsu and Guangdong provinces for submarine cable corridors.
United States
Texas-California renewable corridors and US-Mexico border interconnections accelerate asynchronous grid link development. FERC Order 2023 streamlines permitting timelines for converter station deployment. Project developers in the Southwest seek pre-qualified suppliers for greenfield installations.
United Kingdom
North Sea interconnectors linking Norway and continental Europe drive modular multilevel converter procurement. Ofgem regulates grid access tariffs and technical compliance for subsea cable projects. Scottish offshore wind clusters in the Moray Firth require black-start capable converter platforms.
India
Legacy thyristor-based transmission corridors in western states resist voltage source retrofit despite efficiency penalties. Central Electricity Authority maintains technical standards for bulk power transfer equipment. Maharashtra and Gujarat host maintenance ecosystems for mature current source converter installations.
High Voltage DC Power System Market Competitive Landscape
Player mix skews toward diversified electrical equipment conglomerates with captive semiconductor sourcing relationships. Three to five suppliers capture the majority of utility-scale converter station contracts through pre-qualification status. Strategic archetypes include integrated platform providers, component specialists, and cable-integrated system vendors. Competitive moves center on silicon carbide manufacturing partnerships and qualification timeline acceleration.
Within the integrated platform tier, Siemens Energy, ABB Ltd., and Hitachi Energy Ltd. occupy positions defined by geographic manufacturing footprints and converter architecture specialization. Siemens Energy exemplifies European-scale production across North Sea project clusters. ABB Ltd. represents R&D intensity in modular multilevel designs. Hitachi Energy Ltd. anchors Asia-Pacific submarine cable procurement through regional project presence.
| Leading Market Players |
|---|
| Siemens Energy |
| General Electric Company |
| ABB Ltd. |
| Toshiba Corporation |
| NKT A/S |
| LS Electric Co. Ltd |
| Mitsubishi Electric Corporation |
| Hitachi Energy Ltd. |
| Prysmian Group |
| Others |
Pricing and Supply Chain Analysis
IEC 62501 qualification protocols gate both supplier pool access and price tier separation in HVDC converter station procurement. Utilities in Germany and the United States reference these testing standards in bid evaluation, compressing margins for non-qualified competitors while enabling premium positioning for certified platform providers.
Pricing Analysis
Cost-plus contracts with copper and silicon carbide wafer indexation dominate utility-scale converter station procurement. Three-tier pricing structure across IEC 62501-certified premium, qualified-standard, and emerging-economy tiers reflects certification investment recovery timelines. Pricing pressure stems from SiC substrate shortages extending lead times for Japanese and US wafer-dependent suppliers. Merchant independent power producers exhibit highest price sensitivity, while state-backed grid operators in China absorb cost volatility through long-term supply agreements.
Supply Chain Analysis
Strait of Malacca transit routes and Red Sea corridor disruptions expose silicon carbide substrate shipments to extended logistics risk. Manufacturing concentrates in Germany for European North Sea projects, China for domestic coastal renewable bases, and Japan for power semiconductor foundry output. Converter station assembly draws from copper busbar suppliers in Chile, submarine cable manufacturers in Norway and Italy, and control system integrators in South Korea. Single-source vulnerability concentrates in 200mm SiC wafer production. Distribution runs through specialized EPC contractors for utility-scale projects and direct OEM relationships for industrial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HVDC platform economics approach an interoperability inflection as modular multilevel converter architectures displace proprietary thyristor legacy systems. The shift toward standardized sub-module designs and open control interfaces restructures supplier competitive moats around certification velocity rather than captive technology.
For Market Incumbents: Secure silicon carbide wafer offtake agreements with Japanese substrate manufacturers before foundry capacity tightens further. Accelerate IEC 62501 certification pipeline for second-source converter architectures to defend against emerging SiC-native competitors. Capacity expansion in Jiangsu province captures State Grid Corporation procurement cycles as China's coastal renewable buildout intensifies.
For New Entrants and Emerging Players: Anchor in US-Mexico border asynchronous interconnection projects where FERC Order 2023 streamlines permitting and pre-qualified supplier pools remain thin. Target greenfield offshore wind converter platforms in the US Gulf Coast as the most penetrable geography given nascent installation ecosystems. Pursue power module-only supply contracts to bypass turnkey EPC qualification barriers.
For Investors and Strategic Acquirers: FERC Order 2023 implementation reshapes the acquisition landscape toward developers with pre-qualified converter station relationships and Southwest interconnection project pipelines. Long-term viability centers on suppliers with captive SiC sourcing or backward integration into semiconductor manufacturing. Monitor Bundesnetzagentur grid code revisions as the signal for European procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Wafer Partnership | Secures substrate supply for Hitachi Energy and ABB Ltd. converter platform roadmaps. |
| IEC 62501 Certification Acceleration | Compresses supplier qualification timelines for German North Sea wind farm developers. |
| US-Mexico Border Project Development | Positions developers for FERC Order 2023 streamlined interconnection permitting. |
| Modular Multilevel Converter R&D | Enables grid stability services for Norway-Germany submarine cable corridors. |
| Green Hydrogen Electrolyzer Coupling | Integrates offshore wind DC systems with North Sea electrolyzer feed infrastructure. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FERC interconnection filings, IEC standard documentation, and EPC contractor project databases. Primary interviews engaged utility planning officers at Bundesnetzagentur-regulated grid operators, converter station procurement leads at offshore wind developers, and power semiconductor sourcing managers at European equipment manufacturers. Secondary validation drew from EIA transmission project trackers, IEA renewable integration reports, and customs data on HVDC component trade flows. Bottom-up project pipeline aggregation triangulates against top-down market sizing from equipment shipment records.
Segmentation dimensions modeled span converter technology architecture, application scale from bulk transmission to distributed renewable integration, end-user procurement structure, and installation type maturity. CAGRs derive from project announcement tracking and equipment order backlogs across the analysis window. Forecast inputs incorporate silicon carbide adoption curves in offshore wind specifications and regulatory harmonization timelines between IEC 62501 and national grid codes.
Material uncertainties — SiC wafer supply expansion rates, Bundesnetzagentur grid code revision timing, and FERC Order 2023 implementation consistency — sit outside the modeled envelope. Forecasts reflect assumptions on qualification timeline compression and semiconductor material transition velocity. Practitioners should keep alternative scenarios live as EU Green Deal carbon border adjustment mechanisms and China GB/T 30553 enforcement patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Europe Frequency Converter Market
Power
Oxy-Hydrogen Generators Market
Power
Vietnam Power Market
Power
Doubly Fed Induction Generator (DFIG) Market
Power
Robotic Power Source Market
Power
Wireless Power Receiver Market
Power
Middle-East and Africa Power Market
Power
Uzbekistan Power Market
Power
Wind Turbine Drivetrain Market
Power
Sudan Power EPC Market
Power
Saudi Arabia Power Market
Power
Denmark Power Market
Power
Distributed Buoyancy Modules Market
Power
Single-Phase Microinverter Market
Power
Mexico Power EPC Market
Power
Argentina Power Market