
 Asia-Pacific Turbomachinery Control Systems Market | 2026-2036
Asia-Pacific Turbomachinery Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Turbomachinery Control Systems Market Outlook
A scarcity of control systems engineers fluent in both turbomachinery physics and cyber-physical architectures is redrawing competitive boundaries across the Asia-Pacific. Siemens Energy AG leverages its apprenticeship pipelines in Germany to staff regional service hubs in Singapore and South Korea. Honeywell International Inc. sustains advantage through backward integration into sensor manufacturing, cutting lead times for critical pressure transmitters. Yokogawa Electric Corporation anchors its position in Japan's LNG import terminal sector, where turbine governor upgrades follow strict domestic uptime protocols.
Asia-Pacific turbomachinery control systems encompass hardware and software architectures that regulate rotational speed, load distribution, and thermal stress in turbines, compressors, and pumps, typically operating through closed-loop feedback with millisecond response latencies. These systems protect capital-intensive rotating equipment from surge, overspeed, and fatigue failure while optimizing fuel efficiency across continuous-duty industrial processes. Distributed Control Systems occupy the largest installed base owing to legacy penetration in combined-cycle power blocks, yet Advanced Process Control captures expanding margin pools as refineries pursue autonomous combustion tuning. Programmable Logic Controllers dominate marine propulsion retrofits where space constraints and salt-air corrosion demand ruggedized edge computing.
China's MEE enforces escalating NOx and particulate thresholds that force coal and gas turbine operators toward predictive emissions monitoring integrated within control loops. India's CEA mandates frequency response standards for grid-connected generators, directly shaping governor and load control procurement specifications for domestic utilities. Japan's METI drives hydrogen cofiring trials that require novel fuel-ratio control algorithms, creating certification hurdles for imported platforms. Stakeholders must weigh whether to engineer country-specific compliance modules or pursue modular architectures adaptable across the region's diverging regulatory trajectories.
Market Dynamics
The Asia-Pacific turbomachinery control systems sector confronts a structural talent compression where engineering expertise in cyber-physical architectures lags behind hardware deployment timelines, forcing vendors to reconfigure service delivery models and accelerate knowledge transfer protocols.
Growth Catalysts
- Dual carbon mandates:China's MEE enforces escalating NOx thresholds that compel coal and gas turbine operators toward integrated emissions monitoring within control loops, driving retrofit demand across legacy combined-cycle blocks.
- Grid frequency standards:India's CEA mandates strict frequency response protocols for grid-connected generators, directly shaping governor and load control procurement specifications for domestic utilities.
- Hydrogen cofiring trials:Japan's METI pilots novel fuel-ratio control algorithms for hydrogen blending, creating certification pathways that favor adaptive control architectures over rigid legacy platforms.
Market Restraints
- Specialized component concentration:High-precision pressure transmitters and vibration sensors concentrate among a limited supplier base in Germany and Japan, exposing procurement timelines to single-source fragility.
- Legacy asset inertia:Southeast Asian power utilities operate turbomachinery with 25-35 year service lives, compressing replacement cycles and delaying control system modernization despite efficiency penalties.
- Skill acquisition costs:Training control systems engineers fluent in both turbomachinery physics and industrial cybersecurity requires 18-24 month development horizons, inflating project staffing expenses.
Strategic Opportunities
- Vietnam power expansion:LNG-to-power project pipelines along the southern coastal corridor create greenfield demand for integrated turbine governor and compressor control platforms without legacy integration burdens.
- Autonomous combustion tuning:Advanced Process Control convergence with machine learning enables refineries in India's Gujarat-Maharashtra belt to pursue self-optimizing fuel-air mixtures, opening premium software margin pools.
- Marine propulsion retrofits:Ruggedized Programmable Logic Controllers penetrate cargo vessel and offshore support fleet upgrades where salt-air corrosion and space constraints disqualify conventional Distributed Control Systems.
Industry Challenges
- Cyber-physical certification timelines:IEC 62443 security standard compliance for turbine control networks extends vendor validation cycles by 8-14 months, delaying project handovers and compressing margin realization.
- Multi-vendor integration complexity:Retrofit projects must reconcile proprietary communication protocols from 1980s-era turbine governors with modern Ethernet-based distributed architectures, inflating commissioning risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Turbomachinery Control Systems Market |
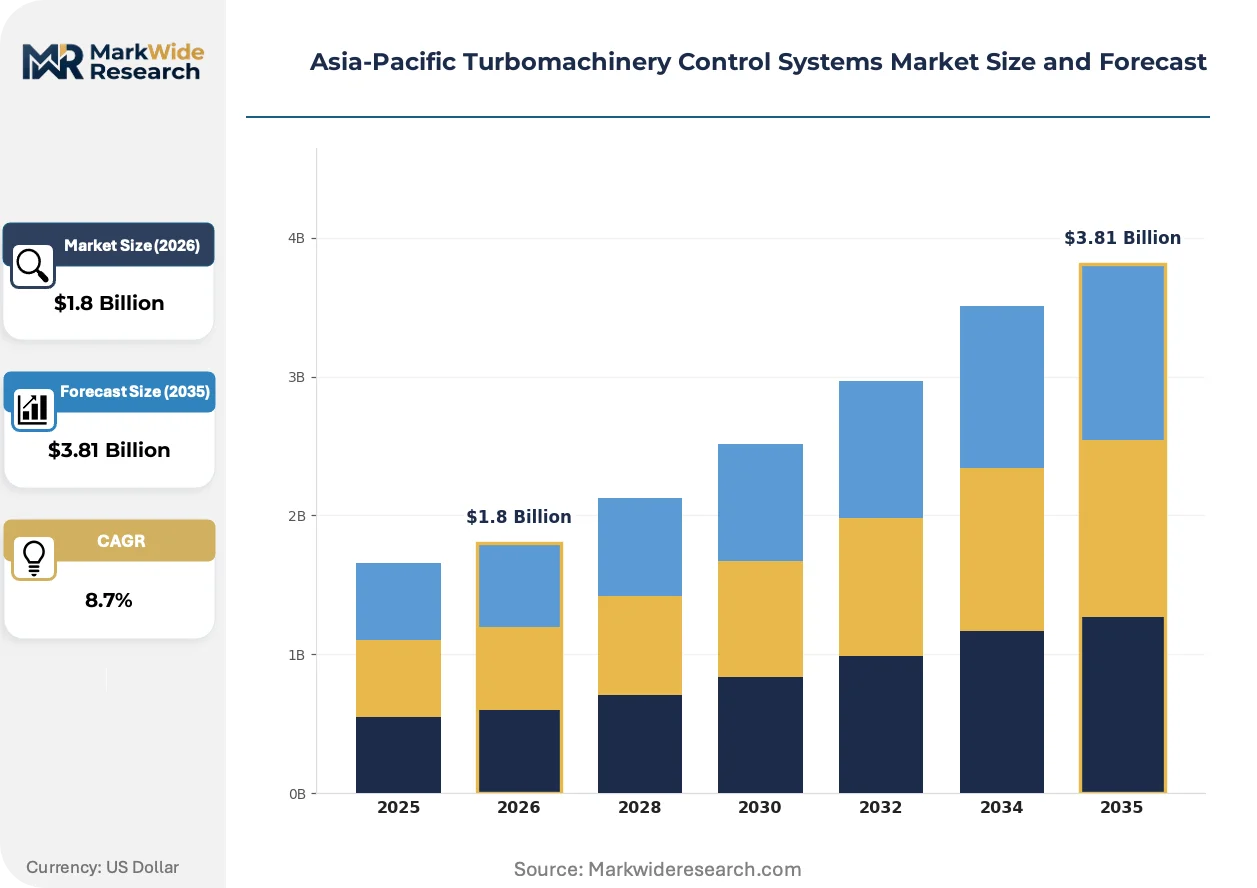
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Distributed Control Systems, Programmable Logic Controllers, Supervisory Control and Data Acquisition, Advanced Process Control Application: Power Generation, Oil & Gas, Aerospace, Marine End User: Utilities, Industrial Facilities, Manufacturing Plants, Research Institutions Deployment: Cloud-Based Systems, On-Premises Solutions, Hybrid Systems, Remote Monitoring |
| Companies Covered | ABB Ltd., Emerson Electric Co., General Electric Company, Siemens Energy AG, Yokogawa Electric Corporation, Honeywell International Inc., Rockwell Automation Inc., Schneider Electric SE, Hollysys Automation Technologies Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Turbomachinery Control Systems Market Strategic Shifts
Control architecture evolution across Asia-Pacific turbomachinery is fragmenting along two competing pathways: centralized predictive optimization versus edge-resilient autonomy. This divergence is reshaping R&D allocation, partnership strategies, and the geographic distribution of engineering talent.
Digital twin technology is bifurcating the control systems value chain. These virtual replicas enable real-time thermal stress modeling and surge prediction for multi-stage compressors. Japanese LNG terminal operators deploy twins for governor tuning without physical downtime. The technology is compressing traditional service revenue models while expanding software subscription streams.
China's MEE enforcement of predictive emissions monitoring systems (PEMS) is tightening compliance windows for coal and gas turbine operators. Industrial facilities must integrate continuous NOx and particulate verification within millisecond-control loops rather than periodic stack testing. Refineries in Shandong and Jiangsu provinces are prioritizing control vendors with certified PEMS modules to avoid production curtailments.
Asset owner engineering teams are unbundling long-term service contracts from initial control system procurement. Australian power utilities and Korean petrochemical complexes now negotiate hardware-software purchases separately from five-year maintenance agreements. This pattern concentrates in markets with mature independent service provider ecosystems, pressuring OEMs to defend aftermarket revenue through proprietary diagnostics rather than contractual lock-in.
Asia-Pacific Turbomachinery Control Systems Market Segmentation
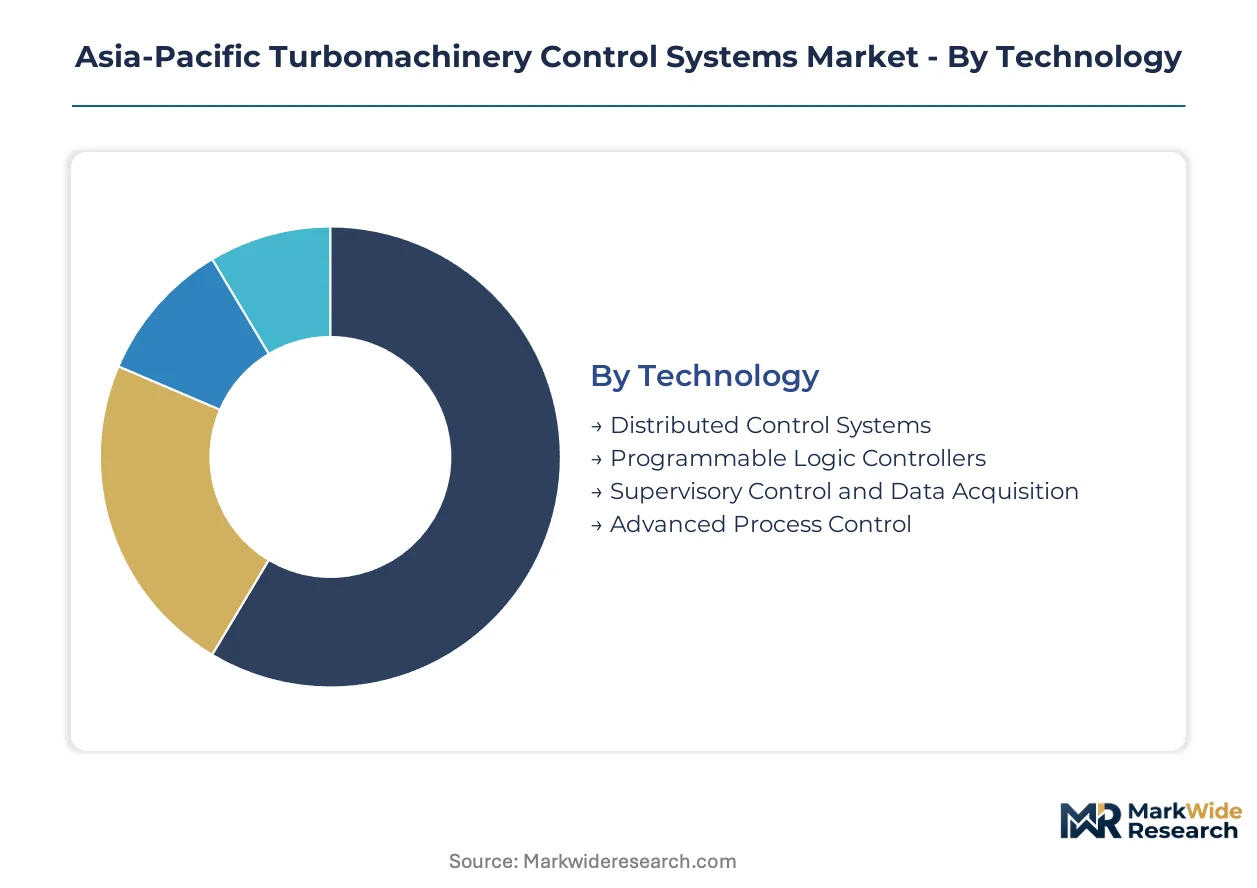
Technology choice in Asia-Pacific turbomachinery control systems determines compliance pathways and lifecycle economics. Each segment carries distinct regulatory footprints across China's MEE mandates, India's CEA frequency standards, and Japan's METI hydrogen trials.
Technology:
Regulatory differentiation across the region forces divergent technology procurement. China's MEE enforces predictive emissions monitoring that favors integrated platforms, while India's CEA grid codes prioritize governor response architectures.
- Distributed Control Systems:These centralized architectures manage turbine governor functions through redundant processor modules with millisecond scan rates. Power generation utilities across Southeast Asia favor DCS platforms for combined-cycle blocks where China's dual carbon retrofits and India's frequency mandates converge. MEE compliance modules for NOx monitoring now ship as standard DCS extensions.
- Advanced Process Control:Model-predictive algorithms enable autonomous combustion tuning and surge avoidance through real-time thermal stress modeling. Refineries in India's Gujarat-Maharashtra belt deploy APC for fuel-air optimization, with machine learning convergence opening premium software subscriptions. METI hydrogen cofiring trials in Japan require APC's adaptive fuel-ratio capabilities.
- Programmable Logic Controllers:Ruggedized edge controllers dominate marine propulsion retrofits where salt-air corrosion and space constraints disqualify centralized architectures.
- Supervisory Control and Data Acquisition:SCADA layers provide visualization and historical trending for geographically dispersed turbine assets across archipelagic utilities.
Distributed Control Systems handles the majority of throughput; Advanced Process Control is expanding most quickly on share.
Application:
Cost tier separation distinguishes mission-critical continuous duty from intermittent or mobile operations. Capital intensity and regulatory exposure vary sharply across these end-use contexts.
- Power Generation:Combined-cycle and coal turbine operators face the steepest compliance burdens. China's MEE NOx thresholds and India's CEA frequency response standards directly shape procurement specifications. Greenfield LNG-to-power projects in Vietnam's southern coastal corridor deploy integrated governor and compressor controls without legacy integration costs.
- Oil & Gas:Refineries pursue autonomous combustion tuning through APC convergence with machine learning. The Gujarat-Maharashtra industrial belt concentrates regional demand for multi-stage compressor surge protection and fuel optimization.
- Aerospace:Test cell and manufacturing applications require high-speed vibration monitoring with specialized pressure transmitter integration.
- Marine:Cargo vessel and offshore support fleet upgrades favor ruggedized PLC architectures where salt-air corrosion and space constraints dominate specification.
Power Generation absorbs the largest capital deployment; Oil & Gas is climbing the fastest on technology refresh intensity.
End User:
Customer type determines service contract structure and cybersecurity certification depth. Mature independent service provider ecosystems enable unbundling in some segments.
- Utilities:Grid-connected generators face India's CEA frequency response mandates and China's MEE emissions protocols. Australian power utilities now negotiate hardware-software purchases separately from maintenance agreements, pressuring OEMs toward proprietary diagnostics.
- Industrial Facilities:Petrochemical complexes in Korea and Australia drive demand for digital twin-enabled governor tuning without physical downtime.
- Manufacturing Plants:Process industries require integrated control platforms with millisecond response latencies for rotating equipment protection.
- Research Institutions:METI hydrogen cofiring trials in Japan create certification pathways favoring adaptive control architectures.
Utilities command the dominant procurement volume; Industrial Facilities are gaining share fastest on digital twin adoption.
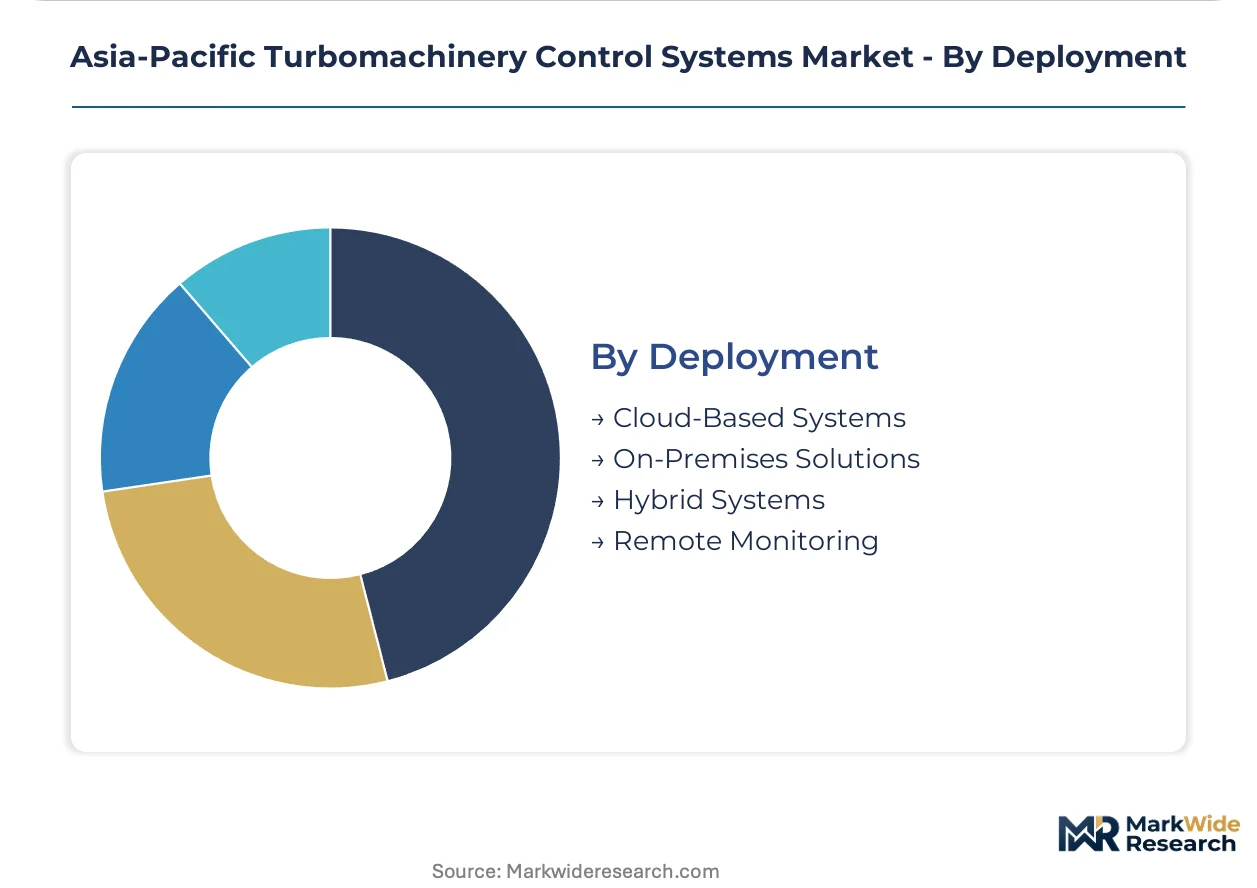
Deployment:
Supply concentration in high-precision sensors and cybersecurity certification timelines shape deployment architecture choices. IEC 62443 compliance extends validation cycles differently across these models.
- On-Premises Solutions:Air-gapped control networks remain mandatory for critical turbine governor functions in coal and combined-cycle plants. China's MEE enforcement of predictive emissions monitoring within control loops favors localized processing to minimize latency.
- Hybrid Systems:Edge-resilient autonomy with cloud-based optimization layers addresses the tension between millisecond control requirements and predictive analytics. Korean petrochemical complexes and Australian utilities pilot these architectures for digital twin deployment.
- Cloud-Based Systems:Non-critical visualization and historical trending migrate to hosted platforms where cybersecurity risk permits.
- Remote Monitoring:Archipelagic utilities across Southeast Asia deploy satellite-linked diagnostics for geographically dispersed assets.
On-Premises Solutions retains the largest installed base; Hybrid Systems show the steepest expansion trajectory on architecture evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE anchors regulatory momentum across Asia-Pacific turbomachinery control systems, with dual carbon mandates and NOx thresholds cascading procurement patterns through Southeast Asian power utilities and Indian refining corridors.
China
Coal and gas turbine operators face escalating MEE emissions benchmarks that force predictive emissions monitoring integration within millisecond-control loops. Shandong and Jiangsu refineries prioritize vendors with certified PEMS modules to avoid production curtailments. Yangtze River Delta industrial clusters drive retrofits of legacy combined-cycle blocks.
India
Grid-connected generators confront CEA frequency response mandates that directly shape governor and load control procurement specifications. The Gujarat-Maharashtra industrial belt concentrates demand for multi-stage compressor surge protection and fuel optimization. Refineries here deploy advanced process control for autonomous combustion tuning.
Japan
METI hydrogen cofiring trials require novel fuel-ratio control algorithms, creating certification hurdles for imported platforms. Kanto region LNG terminal operators deploy digital twins for governor tuning without physical downtime. Domestic uptime protocols anchor Yokogawa's position in import terminal turbine upgrades.
South Korea
Petrochemical complexes pilot hybrid edge-cloud architectures for digital twin deployment. Korean utilities negotiate hardware-software purchases separately from maintenance agreements, pressuring OEMs toward proprietary diagnostics. Busan-Ulsan industrial corridor drives demand for integrated turbine governor platforms.
Vietnam
LNG-to-power project pipelines along the southern coastal corridor create greenfield demand for integrated turbine governor and compressor control platforms. These installations proceed without legacy integration burdens that constrain retrofit timelines elsewhere. Independent service provider ecosystems remain underdeveloped, favoring bundled procurement.
Asia-Pacific Turbomachinery Control Systems Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across Asia-Pacific turbomachinery control systems. European-headquartered industrial conglomerates with captive sensor manufacturing anchor premium-tier positions, while Japanese specialists dominate domestic LNG terminal protocols. The vendor base separates into three strategic archetypes: integrated automation platforms, turbomachinery-native specialists, and regional system integrators. Competitive moves concentrate on backward integration into high-precision sensing components and apprenticeship pipeline construction for cyber-physical engineering talent.
Among integrated automation platforms, ABB Ltd., Emerson Electric Co., and Siemens Energy AG exemplify archetypes that leverage global service networks to staff regional hubs. These players occupy positions where distributed control system installed bases create recurring upgrade pathways. Siemens Energy AG draws specifically on German apprenticeship pipelines to populate Singapore and South Korean service centers, addressing the structural talent compression in cyber-physical architectures.
| Leading Market Players |
|---|
| ABB Ltd. |
| Emerson Electric Co. |
| General Electric Company |
| Siemens Energy AG |
| Yokogawa Electric Corporation |
| Honeywell International Inc. |
| Rockwell Automation Inc. |
| Schneider Electric SE |
| Hollysys Automation Technologies Ltd |
| Others |
Value Chain & Pricing Dynamics
Long-term service contracts bundled with initial hardware procurement lock in both supply access and price visibility across Asia-Pacific turbomachinery control systems, insulating vendors from spot-market volatility while compressing margins for buyers locked into legacy upgrade cycles.
Pricing Analysis
Price spreads between German-engineered sensor packages and Asian-assembled alternatives widen procurement arbitrage opportunities for Southeast Asian utilities. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth and after-sales bundling intensity. Cost compression in economy-tier PLC retrofits is intensifying because marine fleet operators prioritize upfront capital minimization over lifecycle service coverage. Refineries in India's Gujarat-Maharashtra belt exhibit lowest price sensitivity due to uptime penalty exposure, while Vietnamese greenfield LNG projects negotiate aggressively on total installed cost.
Supply Chain Analysis
Port congestion along the Shanghai-Rotterdam lane and container availability crunches in Busan extend lead times for high-precision pressure transmitters sourced from German specialist manufacturers. Component manufacturing concentrates in Germany, Japan, and South Korea, with vibration sensors and governor actuators drawing from captive production facilities in these markets. Single-source vulnerability pervades IEC 62443-certified cybersecurity modules, where qualified vendors remain limited. Distribution runs through OEM-direct channels for DCS platforms, while PLC retrofits penetrate via regional system integrators with marine sector specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-source control architectures and cloud-native SCADA platforms threaten incumbent proprietary ecosystems, forcing established vendors to defend integrated hardware-software positions against modular substitution.
For Market Incumbents: Fortify aftermarket revenue streams through proprietary diagnostic IP embedded in turbine governor firmware, countering unbundling pressures from Australian utilities and Korean petrochemical complexes. Deepen backward integration into vibration sensor manufacturing to cut dependency on Japanese and German component suppliers. Anchor service hub staffing through apprenticeship pipelines addressing cyber-physical engineering scarcity. For New Entrants and Emerging Players: Remote diagnostics capability gaps in archipelagic Southeast Asian utilities present white-space entry points where satellite-linked turbine monitoring remains underdeveloped. Target Vietnam's southern coastal LNG-to-power corridor with greenfield-optimized control platforms free from legacy protocol integration burdens. Pursue partnerships with local EPC contractors to bypass established OEM service networks. For Investors and Strategic Acquirers: Regional system integrators with marine sector PLC expertise and established relationships with Korean shipyards represent compelling acquisition targets as cargo fleet retrofits accelerate. Long-term viability hinges on positioning for hydrogen cofiring control algorithm certification under Japan's METI protocols. Watch for IEC 62443 compliance timeline compression as the inflection signal indicating vendor consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Cuts procurement lead times for pressure transmitters critical to MEE compliance modules. |
| Apprenticeship Pipeline Construction | Addresses cyber-physical engineering scarcity staffing Singapore and South Korean service hubs. |
| Digital Twin Platform Development | Enables governor tuning without physical downtime for Japanese LNG terminal operators. |
| Hydrogen Cofiring Control Certification | Unlocks METI trial participation requiring adaptive fuel-ratio algorithms. |
| Hybrid Edge-Cloud Architecture Deployment | Balances millisecond control requirements with predictive analytics for Korean petrochemical complexes. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, encompassing control systems engineers at Southeast Asian power utilities, procurement leads at Indian refineries, and aftermarket service heads at turbomachinery OEMs. Secondary validation drew from IEC 62443 certification databases, CEA grid code filings, and MEE emissions enforcement records. Bottom-up and top-down triangulation reconciled project-level procurement data with regional aggregate demand estimates.
Across the analysis window, forecasts model technology segmentation by control architecture type, application intensity across power generation and oil and gas, and deployment model evolution from on-premises toward hybrid systems. CAGRs derive from installed base depreciation curves, regulatory compliance timeline acceleration, and greenfield project pipeline tracking. Machine learning convergence in advanced process control and hydrogen cofiring trial expansion in Japan feed directly into adoption rate assumptions.
Forecasts assume regulatory continuity in China's MEE enforcement, India's CEA frequency mandates, and Japan's METI hydrogen protocols; material policy shifts would require re-modeling. Cybersecurity certification timeline extensions and single-source sensor supply disruptions represent specific risk factors that could compress realized growth. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Europe Microturbine Market
Power
Canada Thermal Power Market
Power
Egypt Uninterruptible Power Supply (UPS) Market
Power
Substation Automation System Market
Power
Kuwait Power Market
Power
Recloser Control Market
Power
Japan Uninterrupted Power Supply (UPS) Market
Power
North America Micro CHP Market
Power
Robotic Power Source Market
Power
Global Advanced Marine Power Supply Market
Power
Middle East and Africa Combined Heat & Power Market
Power
Uzbekistan Power Market
Power
Asia-Pacific Power Market
Power
Asia-Pacific Microturbine Market
Power
Middle-East and Africa Power Rental Market
Power
Nigeria Power Market