
 Thin Film Lithium-Ion Battery Market | 2026-2036
Thin Film Lithium-Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Thin Film Lithium-Ion Battery Market Intelligence
High energy density specifications above 500 Wh/L is reorganizing competitive priorities across the thin film lithium-ion battery landscape. Samsung SDI leverages its Korean manufacturing base to sustain wafer-scale deposition throughput for premium medical device contracts. Ilika Plc anchors European supply through its Stereax solid-state platform, which dominates microbattery shipments for industrial IoT sensors. Blue Spark Technologies differentiates via printable battery architectures that occupy niche wearable and disposable electronics segments.
Thin film lithium-ion batteries are electrochemical cells fabricated through vacuum deposition or printing processes, typically achieving thicknesses below 0.5 millimeters with solid-state or polymer electrolyte architectures; they deliver stable voltage output in mechanically stressed or spatially constrained environments where conventional cylindrical or pouch cells fail. Flexible battery formats lead commercial traction due to conformal integration requirements in skin-worn medical patches and curved consumer electronics housings, while solid-state technology captures the fastest expansion trajectory as manufacturers eliminate flammable liquid electrolytes from micro-scale designs. Microbatteries concentrate margin pools in aerospace and defense qualification programs where thermal stability and cycle life thresholds exceed consumer-grade specifications by an order of magnitude.
FDA device classification rules for implantable power sources mandate biocompatibility and hermetic sealing standards that reshape R&D spending across the supply chain, while EU Battery Regulation recycling content thresholds and CE marking requirements constrain market access for non-compliant Asian imports. Japan's METI subsidizes domestic solid-state battery pilot lines through its Green Innovation Fund, redirecting capital toward thin film process equipment vendors. Stakeholders must monitor evolving solid-state electrolyte material platforms and regional qualification timelines to align capacity investments with the next wave of medical and automotive design wins.
Market Dynamics
Solid-state electrolyte migration is compressing liquid electrolyte architectures across medical implant and automotive interior applications, forcing deposition equipment vendors to retool for sulfide and oxide ceramic process flows.
Growth Catalysts
- KBA automotive certification:Germany's vehicle interior sensor mandates are accelerating flexible battery qualification timelines for Tier 1 suppliers.
- FDA implantable power standards:Biocompatibility and hermetic sealing requirements are redirecting R&D budgets toward solid-state microbattery platforms.
- Industrial IoT sensor proliferation:Machine health monitoring in aerospace maintenance contracts is expanding demand for millimeter-scale cells with decade-long cycle life.
Market Restraints
- Thin-film deposition equipment scarcity:Vacuum sputtering and pulsed laser deposition systems face 18-month order backlogs from Korean and Japanese equipment vendors.
- Lithium metal anode supply concentration:Primary lithium refining capacity clusters in South American salt flats and Australian hard-rock mines, exposing cell manufacturers to raw material transit risk.
- Solid-state interface impedance:Ceramic electrolyte-electrode contact resistance remains an order of magnitude above liquid electrolyte wetting, constraining high-rate discharge performance.
Strategic Opportunities
- Subdermal drug delivery patches:Wearable pharmaceutical applications in North American dermatology clinics are creating demand for bioresorbable battery architectures.
- METI Green Innovation Fund:Japanese pilot line subsidies for solid-state process equipment are opening co-development partnerships with domestic machinery builders.
- EU Battery Regulation recycling thresholds:Recovery content mandates above 6% lithium by 2031 are incentivizing closed-loop collection networks for medical device returns.
Industry Challenges
- Multi-physics simulation talent gap:Electrochemical-mechanical coupled modeling for solid-state stack design requires rare expertise in finite element analysis and ionic transport theory.
- ISO 13485 medical device certification timelines:Implantable power source qualification cycles extend 24-36 months, compressing product refresh windows against technology obsolescence.
- Cleanroom capacity allocation:Microbattery fabrication competes with semiconductor and pharmaceutical production for Class 1000 environment slots, inflating slot pricing in manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin Film Lithium-Ion Battery Market |
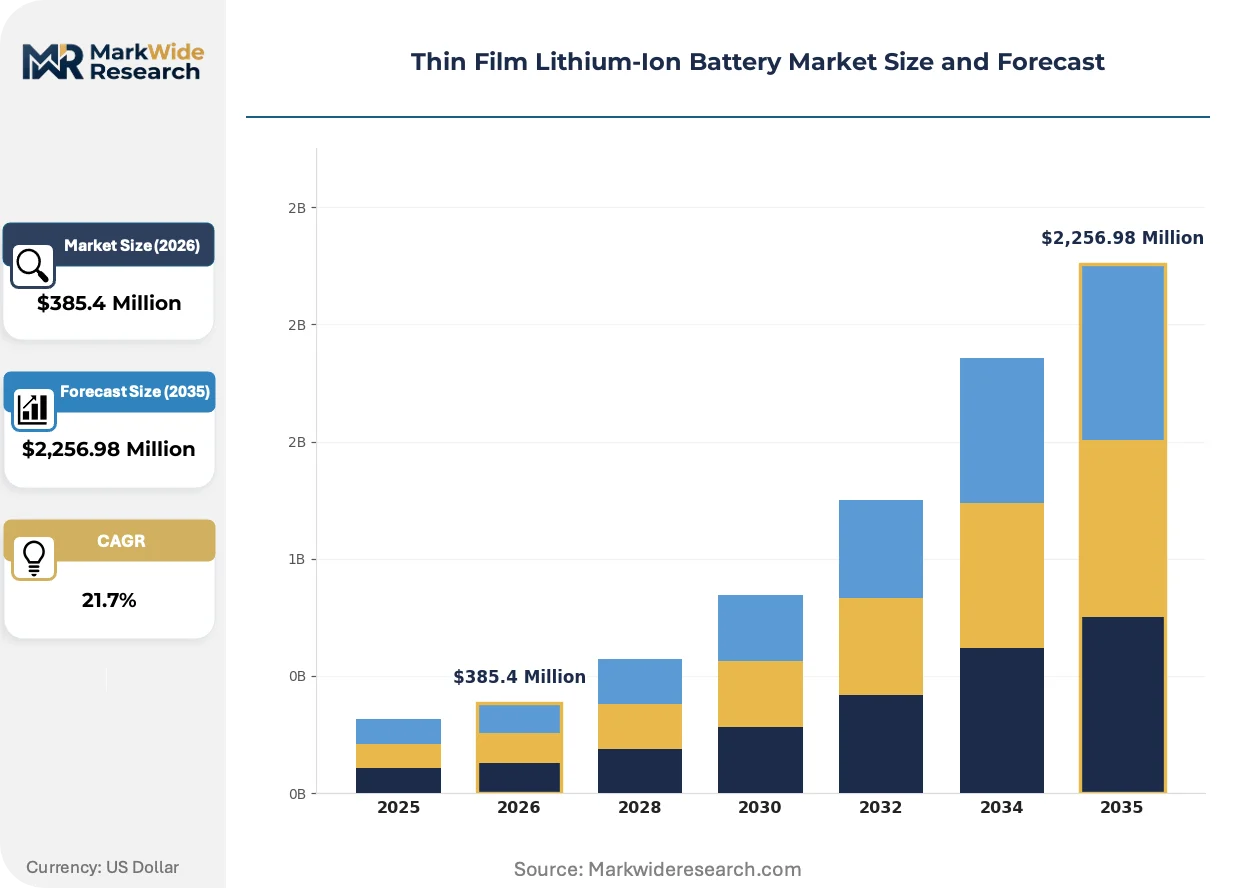
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $2,256.98 Million |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Batteries, Rigid Batteries, Energy Harvesting Devices, Wearable Electronics Technology: Thin Film Deposition, Solid State, Lithium Polymer, Microbatteries End User: Consumer Electronics, Electric Vehicles, Medical Devices, Aerospace Application: Smartphones, IoT Devices, Portable Electronics, Sensors |
| Companies Covered | LG Chem, Samsung SDI, Blue Spark Technologies, BrightVolt, Cymbet Corporation, Enfucell Oy, Ilika Plc, Imprint Energy, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin Film Lithium-Ion Battery Market Strategic Shifts & Innovations
Process architecture consolidation and regulatory material mandates are compressing legacy liquid electrolyte supply chains while elevating solid-state deposition expertise as the primary competitive moat.
Atomic layer deposition of lithium phosphorus oxynitride electrolytes is decomposing conventional sputtering throughput limitations in medical microbattery production. Cardiac pacemaker manufacturers are qualifying ALD-coated cells for 15-year implant lifespans. The technology is decomposing equipment vendor market share concentration by enabling modular reactor installations outside traditional vacuum cluster tool footprints.
EU Battery Regulation recycling content thresholds are mandating supply chain provenance documentation from cathode active material through final cell assembly. Non-compliant Asian imports face automatic CE marking exclusion from 2027. Medical device OEMs in Germany and France are pre-qualifying European-sourced solid-state cells to avoid customs detention risk.
Contract research organizations are displacing in-house battery development at mid-sized medical device firms. Boston and Minneapolis CROs now offer FDA pre-submission packages for implantable power sources, compressing internal R&D headcount. This channel shift concentrates most visible in North American neuromodulation device startups lacking Class III device regulatory experience.
Thin Film Lithium-Ion Battery Market Segmentation
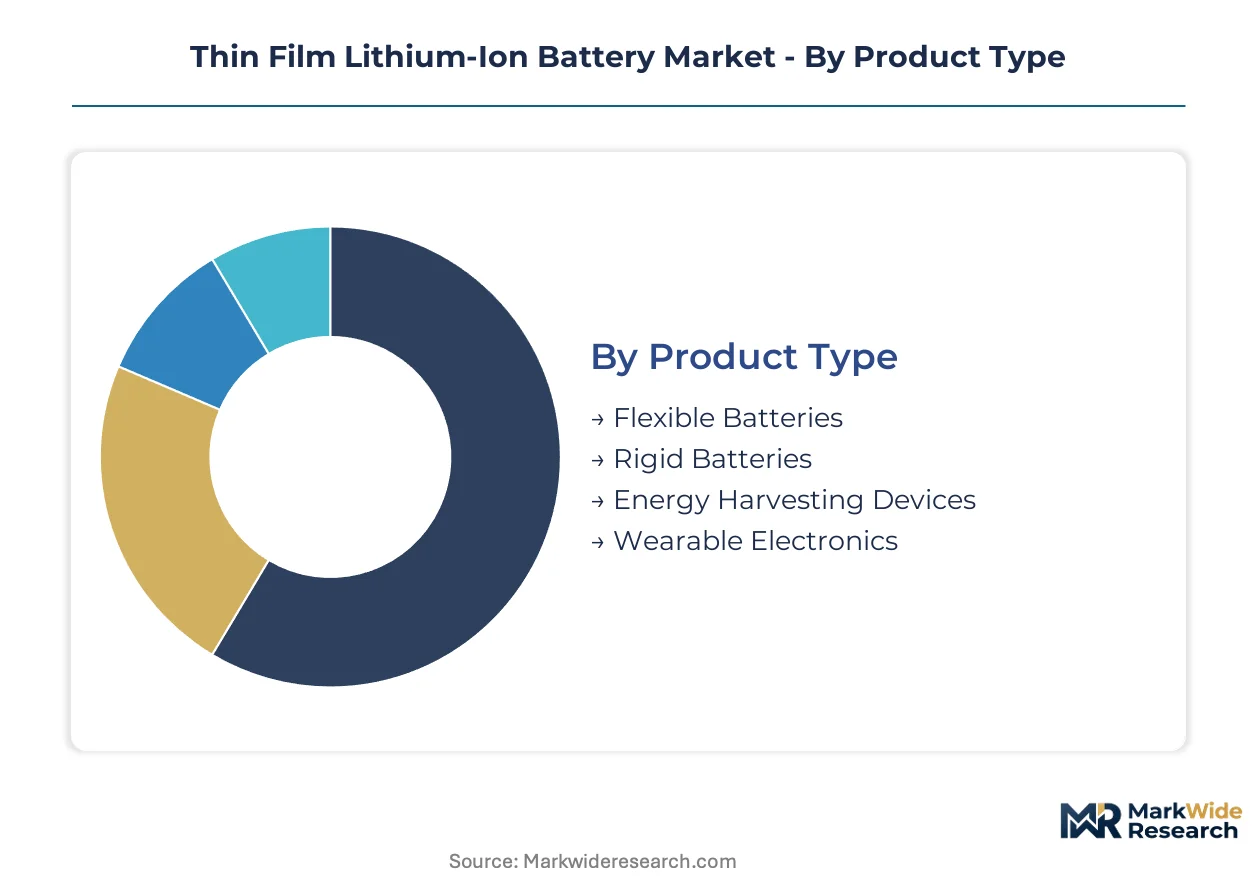
Thin film lithium-ion battery procurement channels diverge sharply across application requirements, with medical device OEMs demanding certified solid-state platforms while consumer electronics buyers prioritize flexible form factors. Channel strategy must align deposition capacity with end-use qualification timelines.
Product Type:
Flexible batteries flow through medical device distributors and wearable OEM direct procurement, while rigid formats concentrate in aerospace and defense contractor channels.
- Flexible Batteries:Polymer or metallic substrates enable bending radii below 5mm for skin-worn medical patches and curved consumer housings. Cardiac monitor manufacturers in Germany and the US are expanding procurement of conformal cells that survive million-cycle mechanical stress tests.
- Rigid Batteries:Ceramic or glass substrates deliver dimensional stability for high-temperature aerospace sensor applications. Defense qualification programs in the US and France are consolidating supplier lists around hermetic ceramic packages that withstand 150°C operational environments.
- Energy Harvesting Devices:Thin film photovoltaic and thermoelectric hybrids integrate with microbattery buffers for perpetual IoT nodes.
- Wearable Electronics:Sub-millimeter formats target disposable health monitors and fitness tracker bands.
By volume, Flexible Batteries lead. By expansion trajectory, Energy Harvesting Devices are climbing fastest.
Technology:
Cost tier stratification separates premium solid-state deposition from commodity lithium polymer printing, with microbattery formats commanding aerospace margins.
- Thin Film Deposition:Vacuum sputtering and pulsed laser deposition achieve sub-micron layer control for medical implant electrolytes. Korean equipment vendors are extending order backlogs for cluster tools serving Samsung SDI medical contracts.
- Solid State:Sulfide and oxide ceramic electrolytes eliminate flammable liquid components from micro-scale designs. Ilika Plc's Stereax platform is capturing industrial IoT sensor shipments through European distribution partnerships.
- Lithium Polymer:Gel electrolyte formats serve cost-sensitive consumer wearable applications.
- Microbatteries:Millimeter-scale cells target implantable drug delivery and neural stimulation devices.
Solid State captures the steepest margin tier. Thin Film Deposition maintains the broadest installed base.
End User:
Customer type determines certification burden, with medical and aerospace buyers demanding ISO 13485 and AS9100 traceability that consumer electronics purchasers waive.
- Consumer Electronics:Smartwatch and earbud manufacturers prioritize energy density above cycle life, accepting 500-cycle degradation profiles for thinner form factors.
- Electric Vehicles:Interior sensor and key fob applications are emerging as thin film entry points before traction battery scale-up.
- Medical Devices:Implantable cardiac monitors and drug pumps require 15-year operational lifespans with zero failure tolerance. FDA pre-submission timelines are compressing vendor selection windows to 24-month qualification cycles.
- Aerospace:Satellite and unmanned aerial vehicle subsystems demand thermal stability from -55°C to 125°C.
Medical Devices command the highest unit margins. Consumer Electronics drives aggregate volume.
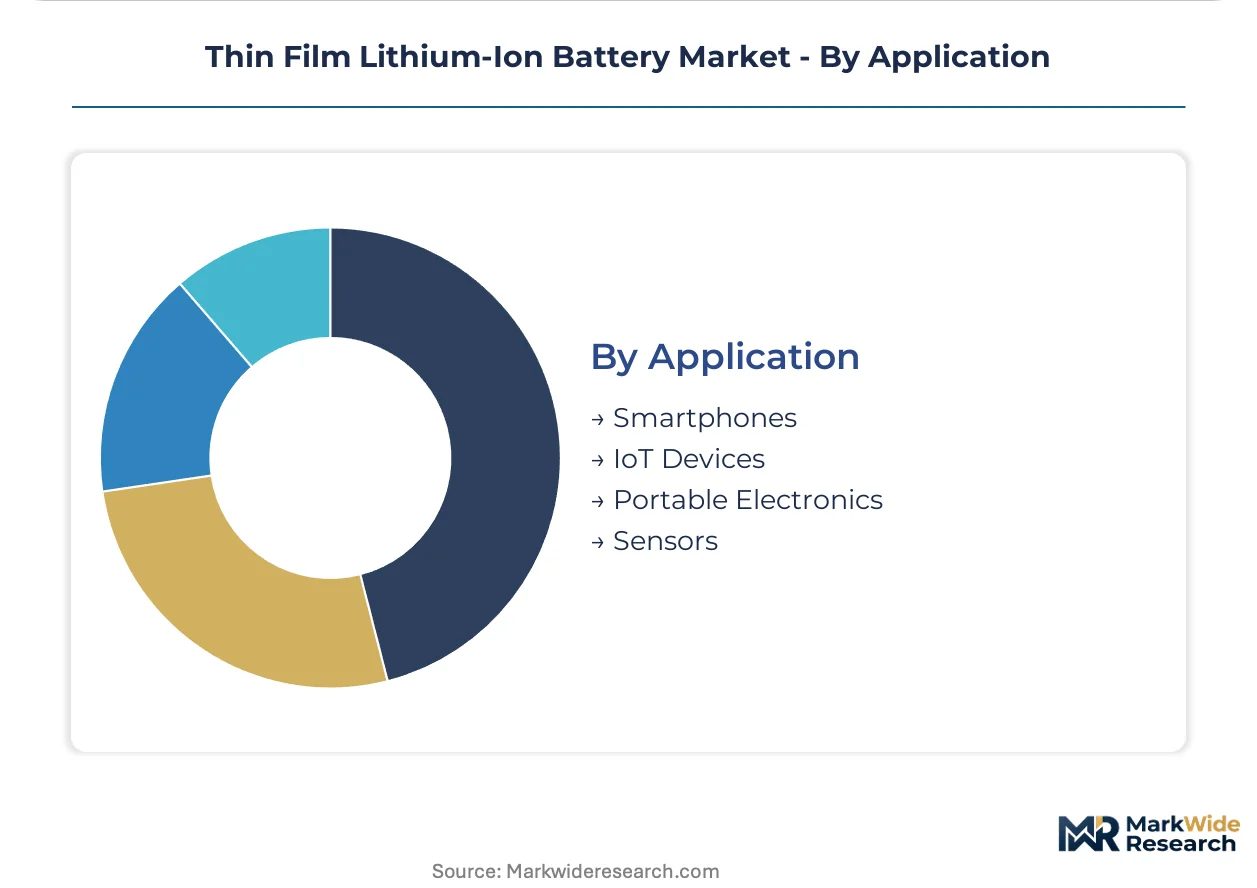
Application:
Geographic demand concentration varies by device category, with smartphone integration concentrating in East Asian manufacturing clusters while IoT sensor deployment spreads across German automotive and US industrial facilities.
- Smartphones:Foldable display hinge batteries and under-screen components are absorbing flexible thin film prototypes. Samsung Display pilot lines in Korea are testing 0.3mm cells for next-generation foldable flagships.
- IoT Devices:Industrial machine health monitors and agricultural soil sensors are expanding addressable volume. Fraunhofer institute partnerships in Germany are accelerating flexible battery integration into automotive interior sensor networks.
- Portable Electronics:Hearing aids and insulin pumps are migrating toward rechargeable thin film architectures.
- Sensors:Distributed environmental and structural monitoring nodes require decade-long unattended operation.
IoT Devices are gaining share fastest. Smartphones retain the largest single-application revenue pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean manufacturers export thin film deposition equipment to German automotive suppliers and US medical device OEMs, establishing the dominant trade-flow corridor in this market.
United States
FDA implantable power standards and neuromodulation device startups drive procurement of solid-state microbatteries. The IRA's domestic manufacturing incentives redirect capital toward medical battery pilot lines. Boston and Minneapolis host contract research organizations offering FDA pre-submission packages for implantable power sources.
Germany
KBA automotive certification requirements for vehicle interior sensors accelerate flexible battery qualification timelines. Fraunhofer institute partnerships advance integration into automotive sensor networks. Bavaria concentrates thin film R&D through collaborations between equipment vendors and Tier 1 suppliers.
South Korea
Samsung SDI leverages domestic wafer-scale deposition capacity for premium medical device contracts. METI-equivalent national programs subsidize solid-state pilot line investments. Seoul Capital Area equipment vendors face 18-month order backlogs for cluster tools serving medical microbattery production.
Japan
METI's Green Innovation Fund subsidizes domestic solid-state battery pilot lines, redirecting capital toward process equipment vendors. Industrial IoT sensor demand from aerospace maintenance contracts expands addressable volume. Nagoya and Osaka manufacturing clusters compete for cleanroom capacity with semiconductor production.
United Kingdom
Ilika Plc anchors European solid-state supply through its Stereax platform for industrial IoT sensors. Oxford and Cambridge research corridors advance atomic layer deposition techniques for medical microbatteries. UK-based CROs displace in-house battery development at mid-sized medical device firms lacking Class III regulatory experience.
Thin Film Lithium-Ion Battery Market Key Industry Players
Listed leaders compete with private specialists across capital access and R&D agility. The vendor base stratifies into three tiers: diversified electronics conglomerates with captive battery divisions, pure-play solid-state developers, and printable battery specialists. Korean and Japanese equipment vendors command deposition tool supply. Competitive moves center on strategic partnerships with medical device OEMs and co-development arrangements with automotive Tier 1 suppliers.
Within the diversified conglomerate tier, Samsung SDI and LG Chem represent scale-driven positions anchored by Korean manufacturing infrastructure. STMicroelectronics occupies a semiconductor-integrated archetype, leveraging MEMS fabrication expertise for microbattery production. Among pure-play solid-state developers, Ilika Plc exemplifies the European specialist model focused on industrial IoT and medical implant applications. Blue Spark Technologies sits within the printable battery segment, targeting disposable electronics and wearable health monitors where conformal form factors command premium positioning.
| Leading Market Players |
|---|
| LG Chem |
| Samsung SDI |
| Blue Spark Technologies |
| BrightVolt |
| Cymbet Corporation |
| Enfucell Oy |
| Ilika Plc |
| Imprint Energy |
| STMicroelectronics |
| Others |
Cost & Logistics Intelligence
Solid-state electrolyte substitution for liquid electrolyte architectures is redrawing procurement geography and collapsing historical cost premiums as Korean and Japanese equipment vendors command 18-month order backlogs for sulfide ceramic deposition tools.
Pricing Analysis
The technology-generation pricing gap separates legacy lithium polymer formats from emerging solid-state microbattery platforms and next-generation atomic layer deposition cells. Three-tier pricing structure across premium solid-state medical implants, standard flexible consumer formats, and economy lithium polymer wearables reflects certification grade and volume scale differentiation. Cost compression in consumer tiers is intensifying because printable battery specialists are flooding disposable electronics segments. Medical device OEMs exhibit the lowest price sensitivity due to FDA-mandated reliability thresholds, while fitness tracker manufacturers negotiate aggressively on per-unit costs.
Supply Chain Analysis
Container availability constraints on the Busan-Hamburg trade lane are elevating inbound logistics costs for German automotive Tier 1 suppliers sourcing Korean wafer-scale deposition equipment. Primary lithium refining capacity clusters in Chilean salt flats and Australian hard-rock mines, exposing cell manufacturers to raw material transit risk. Supply chain vulnerability centers on single-source dependency for pulsed laser deposition systems from Seoul Capital Area vendors. Distribution runs through medical device distributors for certified solid-state platforms and direct OEM procurement for consumer electronics volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin film lithium-ion battery penetration sits at early-cycle expansion, with FDA solid-state qualification timelines and KBA automotive certification mandates accelerating design-in momentum beyond historical lithium polymer adoption curves.
For Market Incumbents: Secure long-term offtake agreements with South Korean equipment vendors before order backlogs extend further, locking in deposition capacity for medical microbattery contracts. Anchor backward integration into lithium metal anode supply through Australian hard-rock mine partnerships to mitigate South American transit risk. Solid-state interface impedance challenges threaten high-rate discharge performance leadership, demanding R&D investment in ceramic electrolyte-electrode contact engineering. For New Entrants and Emerging Players: Post-FDA-submission technical support gaps at mid-sized neuromodulation device startups offer white-space entry points for contract research organizations bundling regulatory affairs with cell qualification. Target North American dermatology clinics deploying subdermal drug delivery patches, where bioresorbable battery architectures face minimal incumbent competition. Lead generation through Fraunhofer institute partnership announcements builds credibility with German automotive sensor procurement committees. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed pure-play solid-state developers holding Ilika Plc-type industrial IoT sensor positions but lacking medical implant certification infrastructure. Five-to-ten year viability hinges on successful navigation of ISO 13485 medical device qualification timelines against technology obsolescence risk. Watch for FDA pre-submission package completion rates among Boston and Minneapolis CROs as inflection indicator for medical segment capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Process Equipment Partnership | Korean cluster tool vendors are prioritizing medical microbattery contracts over consumer volumes. |
| Atomic Layer Deposition Scale-Up | Modular ALD reactor installations outside vacuum cluster footprints are decomposing equipment vendor concentration. |
| EU Battery Regulation Compliance Pathway | CE marking pre-qualification with European-sourced cells avoids customs detention risk from 2027. |
| FDA Pre-Submission Package Development | Boston CROs are compressing internal R&D headcount at mid-sized medical device firms. |
| Lithium Metal Anode Supply Integration | Australian hard-rock mine partnerships reduce South American salt flat transit exposure. |
Research Approach
Desk research of SEC filings from deposition equipment vendors, EU Battery Regulation implementation documents, and FDA 510(k) implantable power source databases preceded structured interviews with biomedical engineers at cardiac pacemaker manufacturers, procurement directors at German Tier 1 automotive suppliers, and cleanroom facility managers at Japanese solid-state pilot lines. Bottom-up cell shipment estimates by application and top-down equipment vendor revenue analysis were triangulated against Fraunhofer institute partnership announcements and METI subsidy disbursement records.
Variance decomposition across the projection horizon isolates volume drivers by technology segment, end-use certification tier, and regional regulatory cluster. Modeled dimensions include flexible versus rigid substrate formats, solid-state versus lithium polymer electrolyte architectures, and medical implant versus consumer electronics versus automotive interior sensor applications. CAGRs were derived from equipment vendor order backlog trajectories and medical device OEM design-in pipeline visibility. Forecast inputs incorporate KBA certification timeline acceleration and FDA hermetic sealing standard revision probability.
Forecasts assume regulatory continuity in FDA implantable power standards and EU Battery Regulation recycling thresholds; material policy shifts would require re-modeling. Specific risks include solid-state electrolyte material platform transitions, lithium metal anode supply disruptions, and cleanroom capacity competition with semiconductor production. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Liquid Lithium Ion Battery Market
Lithium-ion Battery
Germany Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium Nickel Manganese Cobalt Oxide Battery Market
Lithium-ion Battery
Pouch Lithium-Ion Batteries Market
Lithium-ion Battery
Prismatic Lithium Cobalt Oxide (LiCoO2) Battery Market
Lithium-ion Battery
India Electric Vehicle Battery Anode Market
Lithium-ion Battery
High Temperature Lithium Battery Market
Lithium-ion Battery
Radial Lithium-Ion Capacitor Market
Lithium-ion Battery
Power Lithium Battery Market
Lithium-ion Battery
Outdoor Lithium Battery Power Supplies Market
Lithium-ion Battery
Marine Lithium-Ion Battery Market
Lithium-ion Battery
Lithium-Ion Battery Packs Market
Lithium-ion Battery
Lithium-Ion Stationary Battery Market
Lithium-ion Battery
Global Pin Type Lithium-Based Battery Market
Lithium-ion Battery
Lithium-Ion Battery Anode Market
Lithium-ion Battery
Lithium Battery Pack Market