
 Global Marine Power Systems Market | 2026-2036
Global Marine Power Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Marine Power Systems Market Outlook
The EU Green Deal's maritime decarbonization targets are pivoting procurement criteria across European ferry operators and container lines. Wärtsilä anchors its position through integrated hybrid system architectures spanning diesel-electric and battery configurations. MAN Energy Solutions leads in dual-fuel engine development for LNG and methanol pathways. ABB Ltd. differentiates via electric propulsion motors and power distribution systems for ice-class vessels.
Marine power systems encompass propulsion machinery, auxiliary generators, and integrated energy management platforms engineered to deliver thrust and onboard electrical loads across varying sea states and duty cycles. These systems employ power ratings from below 1 MW for harbor craft to above 40 MW for deep-sea container vessels, with thermal efficiency, redundancy, and emissions compliance as core design parameters. Diesel electric configurations retain dominant installed base across commercial shipping, while fuel cell systems represent the fastest-expanding segment as hydrogen bunkering infrastructure matures in port clusters. Hybrid systems capture widening margin pools in offshore platform supply vessels where dynamic positioning loads favor battery buffering.
The International Maritime Organization's Energy Efficiency Existing Ship Index shapes retrofit demand, while the EU's FuelEU Maritime regulation mandates progressive greenhouse gas intensity reductions for vessels calling at European ports. The EPA's marine engine emission standards in the United States and China's MEE domestic emission control area requirements add layered compliance obligations for multinational operators. Stakeholders must track which regulatory jurisdiction governs their vessel routes and align capital deployment with the most stringent applicable standard.
Market Dynamics
The International Maritime Organization's carbon intensity regulations are compressing vessel upgrade cycles and forcing capital reallocation from conventional diesel architectures toward hybrid-electric and hydrogen-ready propulsion systems.
Growth Catalysts
- FuelEU Maritime Regulation:The EU's greenhouse gas intensity mandates for vessels calling at European ports are accelerating fleet renewal investments among container operators and ferry lines serving Rotterdam, Hamburg, and Antwerp.
- Battery Energy Density Gains:Lithium-ion cell chemistry improvements are extending electric-only operational range for harbor tugs and short-sea vessels, opening electrification pathways previously blocked by weight constraints.
- Offshore Wind Installation Vessels:The North Sea and Baltic Sea offshore wind buildout is generating specialized demand for dynamic positioning-capable hybrid propulsion systems in Norwegian, German, and Danish shipyards.
Market Restraints
- Hydrogen Bunkering Infrastructure Gaps:Port-side hydrogen liquefaction and compression facilities remain concentrated in Rotterdam, Singapore, and select Norwegian terminals, limiting fuel cell vessel operational range.
- Power Electronics Supply Concentration:Silicon carbide inverter modules and high-voltage switchgear production clusters in Germany, Japan, and South Korea create single-source vulnerability for system integrators.
- Dual-Fuel Engine Cost Premium:Methanol and ammonia-ready engine blocks command 25-40% capital cost premiums over conventional diesel equivalents, extending payback periods for shipowners.
Strategic Opportunities
- Indian Coastal Electrification:India's Sagarmala port modernization program and domestic emission control area designation create first-mover advantage for battery-hybrid system suppliers targeting Mumbai, Chennai, and Visakhapatnam harbors.
- Ammonia Propulsion Pathways:Convergence of solid oxide fuel cell technology with ammonia cracking systems offers zero-carbon deep-sea shipping solutions for bulk carriers and tankers on transpacific routes.
- EU Green Deal Maritime Funding:The European Investment Bank's vessel decarbonization financing instruments and Innovation Fund grants are de-risking first-of-kind hydrogen fuel cell retrofits for Mediterranean ferry operators.
Industry Challenges
- Marine Electrical System Certification:Lloyd's Register, DNV, and Bureau Veritas classification timelines for novel high-voltage architectures extend 18-24 months, delaying commercial deployment of next-generation power distribution platforms.
- Hybrid System Integration Complexity:Synchronization of battery management systems with diesel generator sets and shore power interfaces demands scarce marine electrical engineering expertise concentrated in Nordic and German technical universities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Marine Power Systems Market |
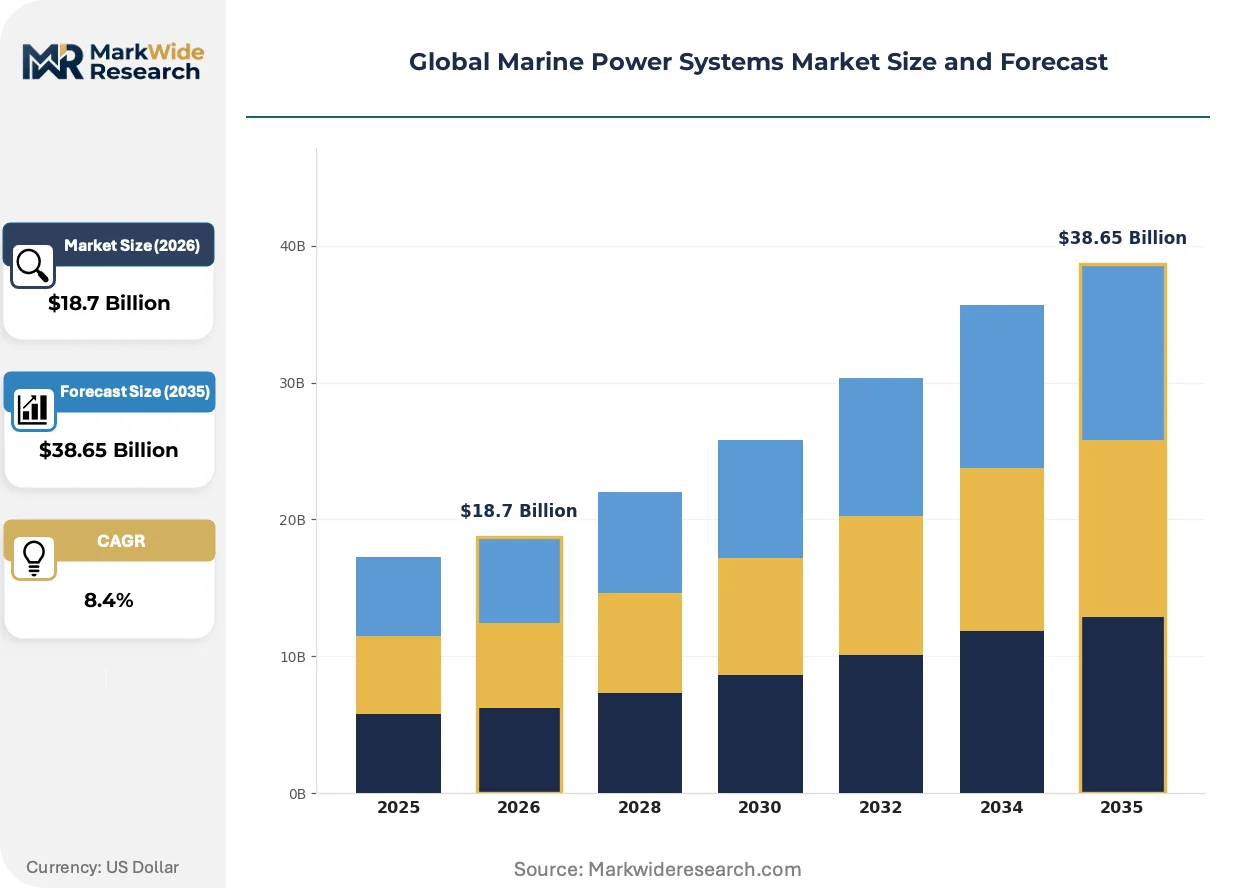
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Diesel Electric, Hybrid Systems, Fuel Cell Systems, Solar Power Systems Application: Commercial Vessels, Military Vessels, Offshore Platforms, Research Vessels Power Rating: Low Power, Medium Power, High Power, Ultra High Power End User: Shipyards, Operators, Government Agencies, Research Institutions |
| Companies Covered | ABB Ltd., MAN Energy Solutions, Wärtsilä, Rolls-Royce Power Systems, Volvo Penta, Caterpillar Inc., Siemens Energy, Mitsubishi Heavy Industries, Cummins Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Marine Power Systems Market Strategic Shifts
Propulsion system architecture is fragmenting across multiple fuel pathways as regulatory timelines outpace fuel infrastructure maturity, forcing shipowners into technology bets with 25-year asset lifecycles.
Solid oxide fuel cell stacks running on liquefied natural gas are electrifying auxiliary power generation for cruise ships and large yachts. Carnival Corporation and Royal Caribbean are piloting 1-2 MW installations on newbuild vessels. This electrification is compressing the addressable market for traditional auxiliary diesel generators in the premium passenger segment.
The EPA's marine engine emission standards and China's MEE domestic emission control area requirements are tightening in parallel, creating a compliance ceiling that no single technology currently satisfies across all trade lanes. Vessel operators serving both US West Coast and Chinese port clusters face conflicting sulfur and nitrogen oxide limits that favor dual-fuel engine investments with fuel-switching flexibility.
Shipowners are unbundling propulsion system procurement from vessel construction contracts, engaging directly with Wärtsilä, MAN Energy Solutions, and ABB for power plant specification before yard selection. This disintermediation shifts engineering risk to equipment suppliers and compresses shipyard margin pools in South Korean and Chinese newbuild markets. The pattern is most visible in LNG carrier and container vessel segments where power plant cost share exceeds 35% of hull value.
Global Marine Power Systems Market Segmentation
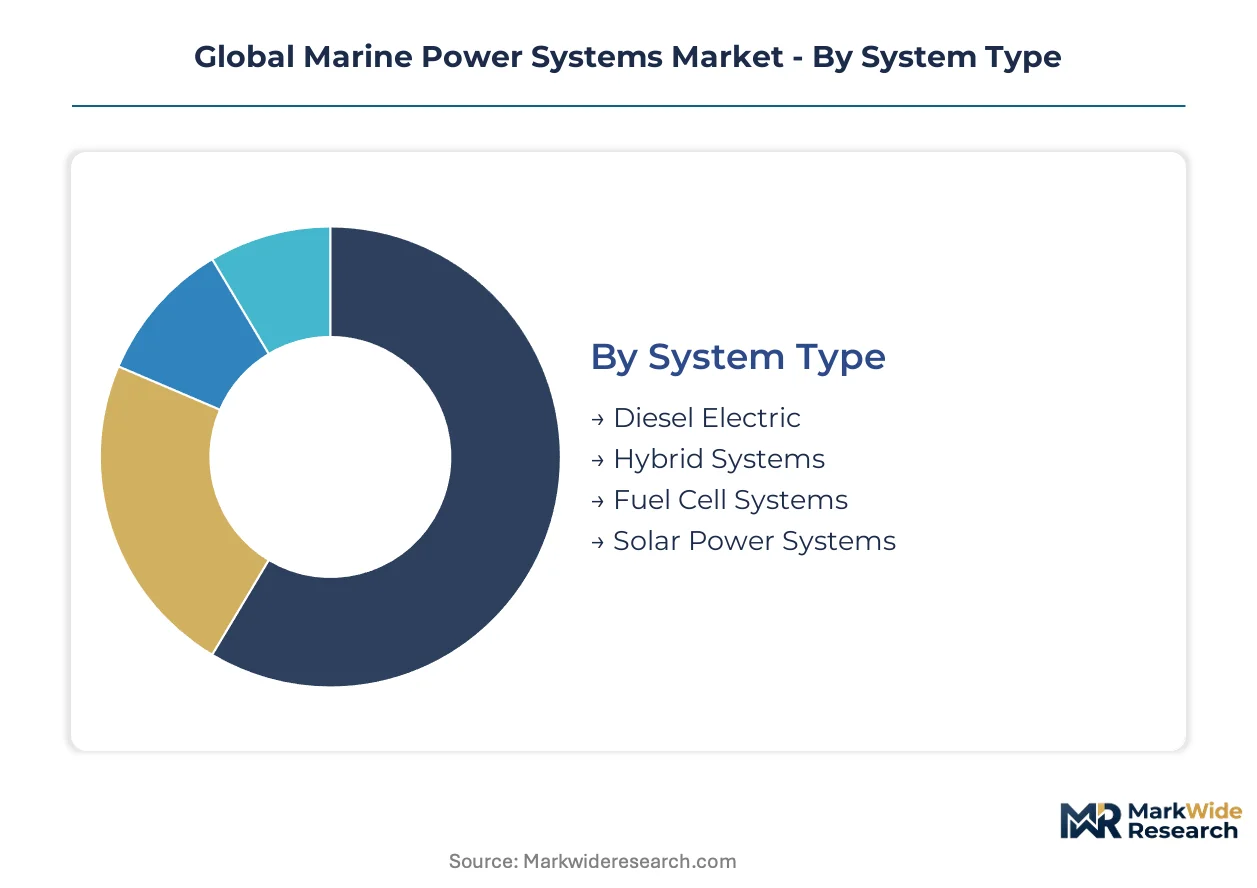
Segmentation reveals how capital deployment splits across propulsion architectures and vessel categories. Upgrade cycles differ sharply between deep-sea commercial fleets and specialized offshore assets.
System Type:
Replacement timelines compress where regulations force fuel pathway switches, stretching where legacy diesel infrastructure remains serviceable.
- Diesel Electric:Combines diesel prime movers with electric distribution for propulsion and hotel loads. Dominates installed base in container shipping and bulk carriers calling at Singapore, Rotterdam, and Shanghai. Retrofit demand concentrates on generator efficiency upgrades rather than full architecture replacement.
- Hybrid Systems:Integrates battery energy storage with conventional generation for load leveling and peak shaving. Norwegian offshore supply vessel operators and German ferry lines anchor procurement as dynamic positioning and frequent port calls favor battery buffering.
- Fuel Cell Systems:Electrochemical conversion of hydrogen or LNG to electricity without combustion. South Korean shipyards pilot megawatt-scale installations for coastal cargo routes where hydrogen bunkering trials concentrate in Busan and Ulsan.
- Solar Power Systems:Photovoltaic arrays supplement auxiliary loads on cruise ships and large yachts. Limited to niche applications where deck area permits installation and operational profiles favor daytime hotel load reduction.
Diesel electric sits at the top of the volume ranking, with fuel cell systems climbing the fastest.
Application:
Operational duty cycles determine power architecture selection, with intermittent high-load profiles favoring hybrid configurations over continuous-output systems.
- Commercial Vessels:Container ships, tankers, and bulk carriers moving global trade. Dual-fuel engine investments dominate newbuild specifications as operators hedge across LNG, methanol, and ammonia pathways for routes serving EU ports under FuelEU Maritime.
- Military Vessels:Naval surface combatants and auxiliary craft with stealth and survivability requirements. Diesel-electric architectures persist due to acoustic signature constraints and refueling infrastructure independence for extended deployment.
- Offshore Platforms:Fixed and floating production facilities plus drilling rigs. Hybrid systems gain share in North Sea installations where variable process loads and strict NOx regulations favor battery-backed generation.
- Research Vessels:Oceanographic and polar expedition ships with specialized maneuvering requirements. Silent electric propulsion modes for underwater acoustic research drive battery-hybrid specifications in German and Norwegian academic fleets.
Commercial vessels command the largest installed base, with offshore platforms expanding most rapidly.
Power Rating:
Capital intensity scales non-linearly with output, concentrating supplier relationships at the high end where engineering risk escalates.
- Low Power:Systems below 1 MW for harbor tugs, pilot boats, and inland waterway craft. Battery-electric architectures achieve technical feasibility here first, with Rotterdam and Amsterdam port authorities procuring electric tug fleets.
- Medium Power:1-10 MW range covering coastal cargo vessels, ferries, and offshore support vessels. Hybrid configurations dominate as fuel cost volatility and emissions regulations justify premium capital expenditure.
- High Power:10-40 MW systems for deep-sea container ships and tankers. Dual-fuel two-stroke engines from MAN Energy Solutions and Wärtsilä anchor specifications, with methanol-ready variants gaining traction.
- Ultra High Power:Above 40 MW for very large crude carriers and the largest container vessels. Limited supplier base concentrates on slow-speed two-stroke engines with exhaust gas treatment systems for IMO Tier III compliance.
High power ratings anchor revenue concentration, with low power segments gaining share fastest on electrification trends.
End User:
Procurement authority fragmentation shapes sales cycles, with direct operator engagement displacing traditional shipyard-mediated purchasing.
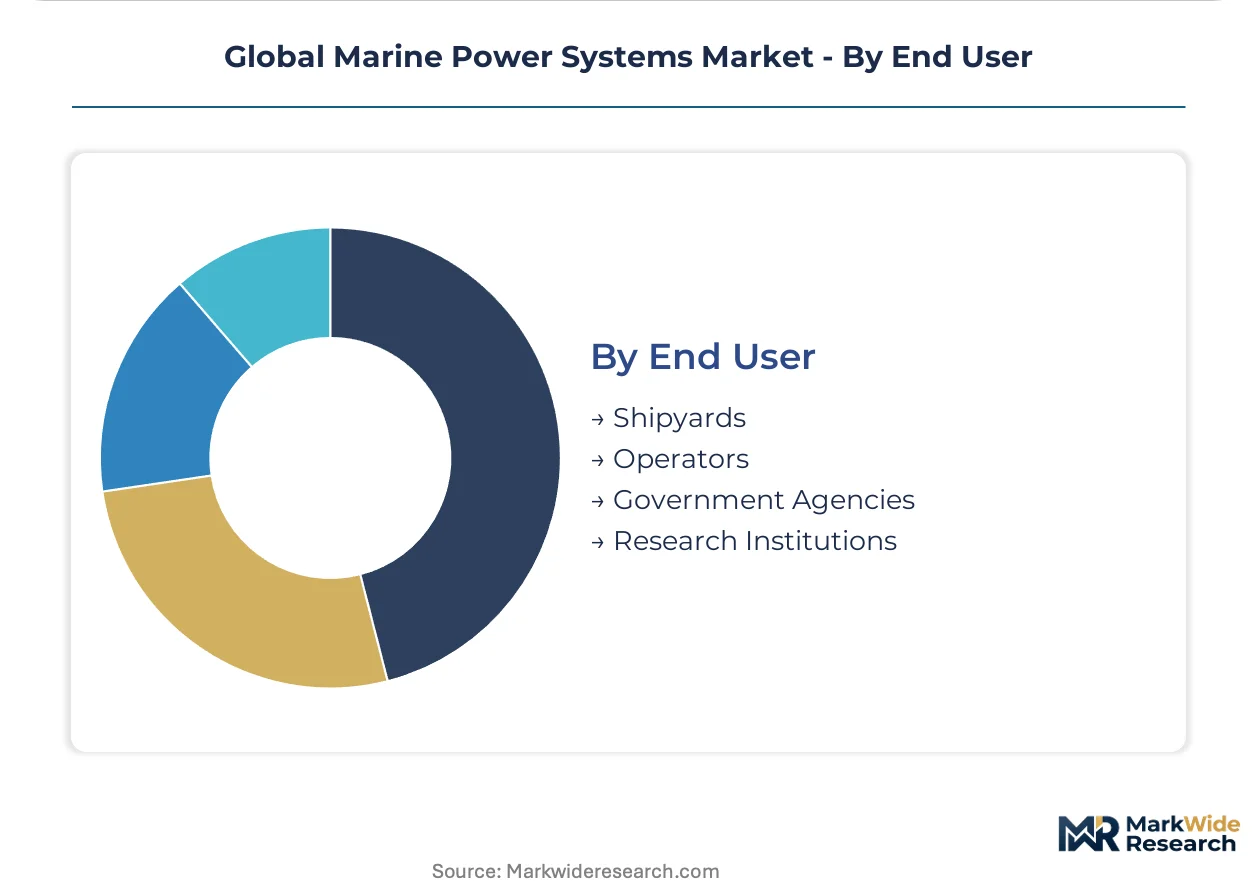
- Shipyards:Construction facilities in South Korea, China, and Japan integrating power plants into newbuild hulls. Margin compression here drives unbundling trends as operators specify systems independently.
- Operators:Container lines, ferry companies, and offshore vessel owners making direct equipment procurement decisions. Maersk, MSC, and CMA CGM increasingly contract Wärtsilä and ABB before yard selection.
- Government Agencies:Naval procurement authorities and coast guard fleets with sovereign specification requirements. Extended certification timelines and domestic content rules constrain supplier flexibility in US and European defense markets.
- Research Institutions:Academic and governmental oceanographic organizations with specialized mission profiles. Silent operation and precision maneuvering requirements favor electric and hybrid architectures in this niche.
Operators sit at the top of the volume ranking, with government agencies climbing the fastest on naval fleet renewal cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine electrical engineers and naval architects concentrate in Nordic technical universities and German shipbuilding clusters, anchoring regional innovation capacity. Their expertise shapes propulsion system specifications across commercial and offshore segments. This talent distribution drives geographic investment patterns in electrification infrastructure.
Norway
Offshore supply vessel operators in Stavanger and Bergen drive hybrid system procurement for dynamic positioning applications. The country's sovereign wealth fund channels capital into hydrogen bunkering trials at western port terminals. Norwegian shipyards in Sunnmøre specialize in battery-electric ferry construction for domestic coastal routes.
Germany
Elbe River ferry operators and Hamburg container terminals create concentrated demand for shore power and hybrid propulsion systems. The EU Green Deal's maritime decarbonization targets tighten procurement criteria for vessels calling at Bremerhaven and Wilhelmshaven. Siemens Energy and MAN Energy Solutions anchor high-voltage power electronics and dual-fuel engine development in Bavaria and Baden-Württemberg.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries integrate megawatt-scale fuel cell systems into coastal cargo vessel newbuilds. The Ministry of Trade, Industry and Energy funds hydrogen liquefaction infrastructure at Busan and Ulsan port complexes. Daewoo Shipbuilding & Marine Engineering pilots solid oxide fuel cell installations for auxiliary power generation.
United States
EPA marine engine emission standards and California Air Resources Board regulations compress upgrade cycles for vessels serving West Coast port clusters. Caterpillar Inc. and Cummins Inc. anchor medium-speed engine development and generator set manufacturing in Indiana and Illinois. Gulf Coast offshore platform operators in Houston procure hybrid power systems for floating production facilities.
Japan
Mitsubishi Heavy Industries and Kawasaki Heavy Industries develop ammonia-ready two-stroke engines for bulk carrier applications. METI's Green Innovation Fund de-risks hydrogen fuel cell retrofits for coastal shipping routes connecting Osaka, Nagoya, and Tokyo Bay. Yokohama and Kobe port authorities trial liquefied hydrogen import terminals to supply regional bunkering demand.
Global Marine Power Systems Market Competitive Environment
Capital-heavy producers compete with asset-light designers across propulsion system architecture. The market structure concentrates around integrated system suppliers with in-house generator, motor, and power distribution capabilities. Three archetypes dominate: full-stack integrators spanning diesel-electric to fuel cell platforms; specialized engine builders focusing on dual-fuel combustion technology; and electrical component suppliers capturing margin in high-voltage switchgear and silicon carbide inverters. Competitive moves center on unbundling procurement relationships with shipowners and securing classification society pre-certification for novel architectures.
Among Nordic-integrated full-stack suppliers, Wärtsilä and ABB Ltd. occupy positions spanning hybrid system design through shore power interfaces. German engine specialists MAN Energy Solutions and Rolls-Royce Power Systems exemplify the dual-fuel pathway archetype, anchoring methanol and ammonia-ready development programs. Caterpillar Inc. represents the North American industrial engine tier, serving offshore platform and workboat segments with medium-speed generator sets. Mitsubishi Heavy Industries anchors Japanese heavy industrial participation in large two-stroke propulsion machinery.
| Leading Market Players |
|---|
| ABB Ltd. |
| MAN Energy Solutions |
| Wärtsilä |
| Rolls-Royce Power Systems |
| Volvo Penta |
| Caterpillar Inc. |
| Siemens Energy |
| Mitsubishi Heavy Industries |
| Cummins Inc. |
| Others |
Value Chain & Pricing Dynamics
FuelEU Maritime's greenhouse gas intensity mandates for vessels calling at European ports are forcing shipowners toward dual-fuel and hybrid architectures, compelling suppliers to absorb certification costs and recalibrate pricing models around fuel-switching flexibility rather than base hardware margins.
Pricing Analysis
The bundled-vs-unbundled service split defines pricing architecture across marine power systems. Three-tier pricing structure across premium, standard, and economy levels separates IMO Tier III-certified dual-fuel engines from conventional diesel-electric configurations and basic generator set replacements. Price differentiation rests on classification society pre-certification status and after-sales service bundling. Cost compression in standard-tier diesel-electric retrofits is intensifying as shipowners unbundle procurement from yard contracts. Container lines exhibit lowest price sensitivity given regulatory compliance deadlines, while coastal ferry operators face acute budget constraints.
Supply Chain Analysis
Regional distribution centers in Hamburg, Singapore, and Busan anchor hub-and-spoke patterns for high-voltage switchgear and silicon carbide inverter modules. Manufacturing concentrates in Germany, South Korea, and Japan for power electronics; China dominates battery cell production. Raw material dependencies span copper busbar, rare earth magnets, and specialized marine-grade steel. Single-source vulnerability for silicon carbide wafers sourced from Japanese and German foundries creates supply chain risk. Distribution runs through OEM-direct channels for large propulsion systems and authorized service networks for aftermarket components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine power systems function as a stable compounder where regulatory compliance deadlines create predictable replacement cycles regardless of freight rate volatility.
For Market Incumbents: Deepen backward integration into battery management system software and power electronics firmware to defend against electrical component suppliers encroaching on system integration margins. Prioritize DNV and Lloyd's Register pre-certification for ammonia-ready architectures before competitors lock up classification society bandwidth. Anchor capacity in South Korean shipbuilding clusters where Hyundai Heavy Industries and Samsung Heavy Industries concentrate newbuild demand.
For New Entrants and Emerging Players: The price-point gap between premium fuel cell systems and economy-tier diesel retrofits offers entry space for mid-range hybrid offerings targeting Indian coastal electrification under Sagarmala port modernization. Target harbor tug and pilot boat segments where battery-electric feasibility is proven and procurement authority fragments across municipal port authorities. Pursue direct operator engagement models bypassing traditional shipyard mediation.
For Investors and Strategic Acquirers: Asymmetric upside sits with fuel cell stack developers possessing solid oxide technology applicable to both LNG and ammonia pathways. Long-term viability hinges on hydrogen bunkering infrastructure buildout pace rather than near-term order volume. Monitor Rotterdam and Singapore hydrogen liquefaction terminal commissioning as the inflection signal for fuel cell vessel commercialization.
| Strategic Initiative | Industry Significance |
|---|---|
| Fuel Cell Stack Scale-Up | Megawatt-scale solid oxide installations for Carnival Corporation cruise auxiliary power reduce diesel generator addressable market. |
| Ammonia-Ready Engine Certification | MAN Energy Solutions and Wärtsilä methanol-am dual-fuel blocks secure IMO compliance for EU container routes. |
| Battery-Hybrid Retrofit Programs | ABB Ltd. shore power interfaces and energy storage integration capture Norwegian offshore supply vessel upgrade cycles. |
| Hydrogen Bunkering Infrastructure | Port authority investments in Rotterdam, Busan, and Kobe liquefaction terminals enable fuel cell vessel operational range extension. |
| Direct Operator Procurement | Maersk and MSC unbundling power plant specification from yard contracts shifts engineering risk to Wärtsilä and ABB. |
Study Parameters
Multiple input streams — shipowner procurement directors, shipyard engineering leads, classification society technical managers, and port authority infrastructure planners — were reconciled against Lloyd's Register and DNV certification databases, IMO regulatory filing repositories, and European Investment Bank vessel financing disclosures. Primary interviews with marine electrical engineers at Nordic technical universities and German shipbuilding clusters were validated against customs trade data for power electronics imports and SEC filings from Caterpillar Inc. and Cummins Inc. Bottom-up vessel fleet analysis and top-down energy transition scenario modeling were triangulated.
Cross-referencing historical retrofit penetration patterns against expert panel input on FuelEU Maritime compliance timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include propulsion architecture type, vessel application category, power rating tier, and end-user procurement authority. CAGRs were derived from scenario-weighted demand curves incorporating hydrogen bunkering infrastructure buildout assumptions and battery energy density improvement trajectories. Industry-specific forecast inputs encompassed offshore wind installation vessel order books and cruise line newbuild specifications.
Caveats apply where hydrogen liquefaction terminal commissioning delays, silicon carbide supply disruptions, or IMO regulatory timeline extensions could materially shift the outlook. Forecasts reflect documented assumptions around fuel infrastructure buildout and classification society certification capacity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Marine Thermal Fluid Heaters Market
Power
United States Power Market
Power
Recloser Control Market
Power
India Uninterruptible Power Supply (UPS) Market
Power
Wireless Power Receiver Market
Power
Asia-Pacific Microturbine Market
Power
Saudi Arabia Power Market
Power
Flue Gas Desulfurization Unit Market
Power
Power Rental Market
Power
Middle-East and Africa Power Market
Power
Global Hydraulic Turbine Market
Power
Electric Power Sports Market
Power
Australia Power Market
Power
North America Power Market
Power
Global Advanced Marine Power Supply Market
Power
Qatar Power Market