
 Global Advanced Cardiovascular Life Support Market | 2026-2036
Global Advanced Cardiovascular Life Support Market Size, Share, and Industry Trends Forecast 2026-2036
Global Advanced Cardiovascular Life Support Market Intelligence
Revenue from training and certification programs is rewriting the competitive landscape for ACLS providers, shifting value from pure equipment sales. The American Heart Association dominates the development of guidelines and educational content, influencing global procurement decisions. Medtronic specializes in the hardware segment, engineering defibrillators and ventilators that align with these clinical protocols. The European Resuscitation Council anchors clinical practice guidelines and training methodologies across its member states.
Advanced Cardiovascular Life Support comprises a set of clinical interventions and algorithms for treating life-threatening cardiopulmonary emergencies. It requires specialized equipment, including defibrillators capable of biphasic waveform delivery and ventilators with multiple pressure-controlled respiratory modes. Defibrillators and cardiac monitors constitute the largest product type segments, driven by consistent replacement cycles in hospitals. Emergency Medical Services and Intensive Care Units represent the primary end-user segments, demanding high-reliability equipment for critical patient interventions.
Medical device regulations from the US FDA and Europe's EMA mandate stringent pre-market approval and post-market surveillance for ACLS equipment. In parallel, clinical guidelines from bodies like the American Heart Association and standards like ISO 13485 shape product design and training protocols. Stakeholders must now decide how to integrate AI-driven diagnostic aids while ensuring full regulatory compliance and patient safety.
Market Dynamics
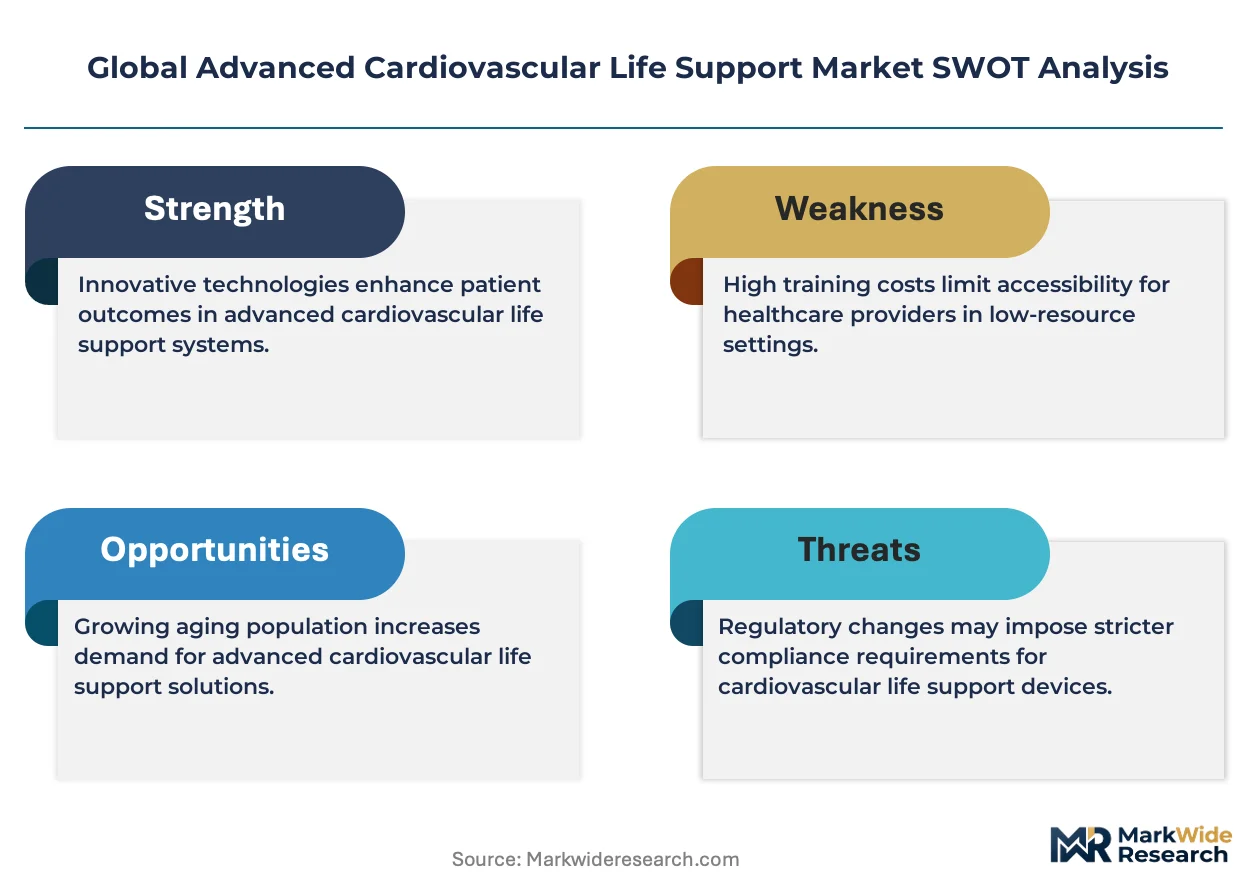
The central dynamic shaping the market is the integration of real-time data transmission and AI-driven diagnostics into devices, a technological push that strains existing regulatory frameworks from the FDA and EMA, creating friction between innovation and compliance pathways.
Growth Catalysts
- Guideline Standardization:The American Heart Association's clinical guidelines create a uniform global standard for resuscitation protocols, compelling hospitals and EMS providers worldwide to procure equipment with compliant features like biphasic waveform delivery.
- Infrastructure Investment:National healthcare modernization programs in countries like Germany and Japan are channeling significant capital into upgrading emergency medical services, where demand for advanced defibrillators and ventilators is concentrating.
- Connected Devices:The integration of real-time data transmission capabilities in new defibrillator models is driving adoption within Emergency Medical Services, as it allows for advance data sharing with receiving hospitals to improve patient outcomes.
Market Restraints
- Regulatory Scrutiny:Stringent pre-market approval requirements under Europe's Medical Device Regulation (MDR) and from the US FDA introduce significant delays and costs, slowing the commercialization of new ACLS technologies.
- High Capital Outlay:The substantial upfront cost of advanced defibrillators and ventilators equipped with multiple respiratory modes presents a significant barrier for smaller hospitals and volunteer-based emergency services, limiting market penetration.
- System Interoperability:Lack of standardized communication protocols makes it difficult to integrate new ACLS devices with legacy hospital information systems and electronic health records, creating data silos and operational friction.
Strategic Opportunities
- AI-Powered Diagnostics:Integrating AI algorithms into cardiac monitors to provide predictive alerts for cardiopulmonary emergencies offers a significant value-add, moving beyond reactive treatment to proactive patient management in ICUs.
- Training-as-a-Service Models:Developing bundled subscriptions that include equipment leasing, ongoing certification through bodies like the European Resuscitation Council, and software updates can create recurring revenue streams and increase customer retention.
- Tele-ICU Integration:Designing ACLS equipment for seamless integration with remote tele-ICU platforms can expand the market to rural and underserved healthcare facilities, enabling expert oversight of critical care from a distance.
Industry Challenges
- Cybersecurity Vulnerabilities:Protecting connected ACLS devices that transmit sensitive patient data from cybersecurity threats is a major operational challenge, requiring continuous software patching and compliance with frameworks like HIPAA.
- Specialized Skill Scarcity:A shortage of clinicians and paramedics adequately trained to utilize the advanced functionalities of modern ventilators and defibrillators limits the effective deployment and full clinical benefit of the equipment.
- Component Supply Chain:Dependence on a concentrated number of suppliers for critical electronic components, such as high-capacity capacitors for defibrillators, exposes manufacturers to significant supply chain disruption risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Advanced Cardiovascular Life Support Market |
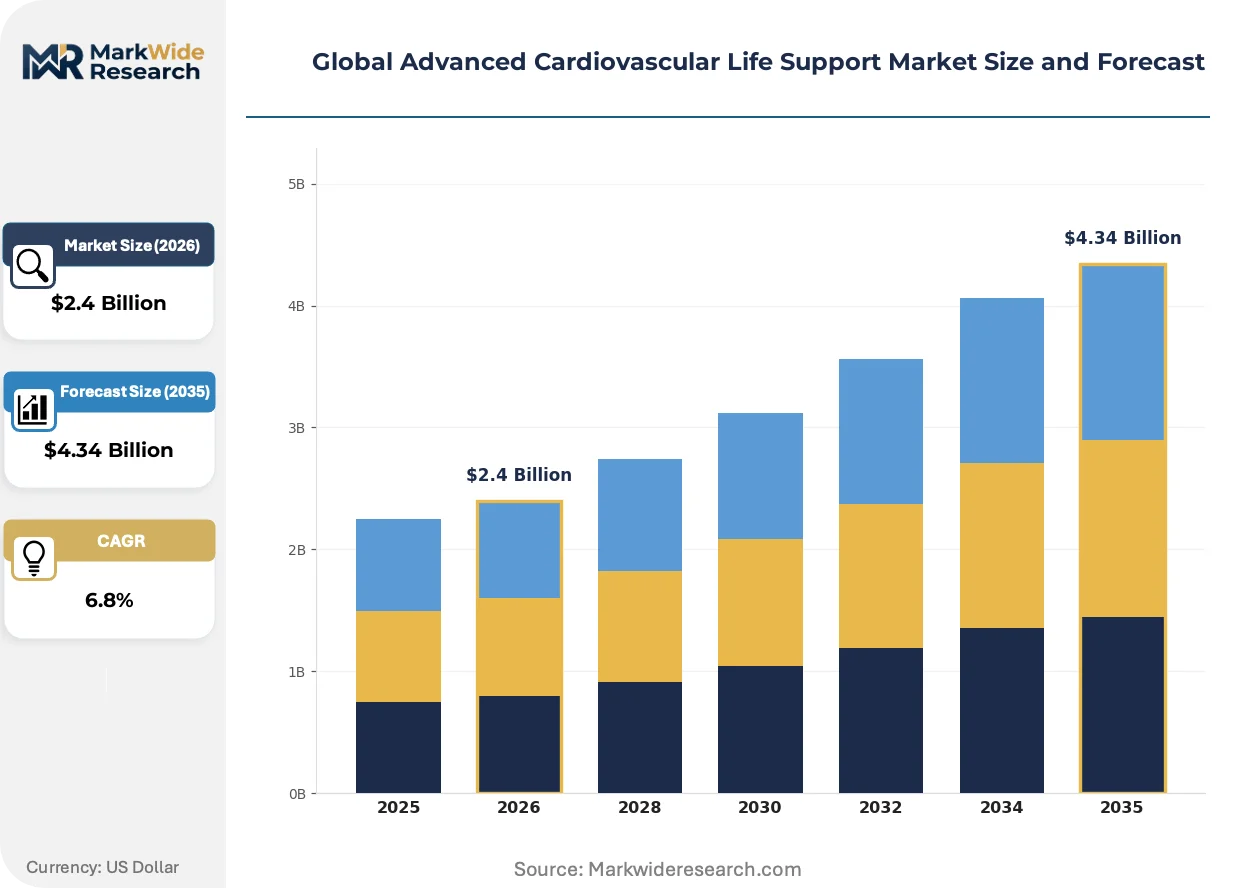
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Defibrillators, Cardiac Monitor, Ventilators, Resuscitation Equipment Application: Cardiac Arrest, Respiratory Failure, Arrhythmia Management, Shock Treatment End User: Emergency Medical Services, Ambulance Providers, Intensive Care Units, Outpatient Clinics Deployment: In-Hospital, Pre-Hospital, Mobile Units, Home Care Settings |
| Companies Covered | American Red Cross, American Academy of Pediatrics, American Heart Association, American College of Surgeons, American College of Emergency Physicians, American College of Cardiology, Health & Safety Institute, European Resuscitation Council, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Advanced Cardiovascular Life Support Market Strategic Shifts & Innovations
The market is evolving from a focus on standalone hardware sales to the delivery of integrated resuscitation systems. This shift combines advanced equipment, data analytics for clinical decision support, and continuous training programs to improve patient outcomes in critical care settings.
Artificial intelligence in diagnostic aids provides real-time analysis of patient vital signs and ECG rhythms. Emergency Medical Services and Intensive Care Units are the primary adopters of these systems. The function of the device is migrating from a purely therapeutic tool, which delivers a shock, to an active diagnostic partner that guides clinical intervention during a crisis.
Europe's Medical Device Regulation (MDR) is reshaping the compliance landscape for all ACLS equipment sold within the EU. The regulation mandates more rigorous clinical evidence and establishes a comprehensive post-market surveillance system for devices like ventilators and defibrillators. This particularly affects manufacturers who must now invest heavily in generating new clinical data for both new and existing products to maintain their CE marking.
A notable behavioral change is the transition from one-time capital purchases toward comprehensive service agreements that bundle hardware, software, and training. This model disrupts the traditional sales cycle focused on device specifications, replacing it with a solution-centric approach that emphasizes total cost of ownership and standardized care protocols. This trend is most pronounced in large hospital networks in the United States and Germany seeking to optimize operational budgets.
Global Advanced Cardiovascular Life Support Market Segmentation
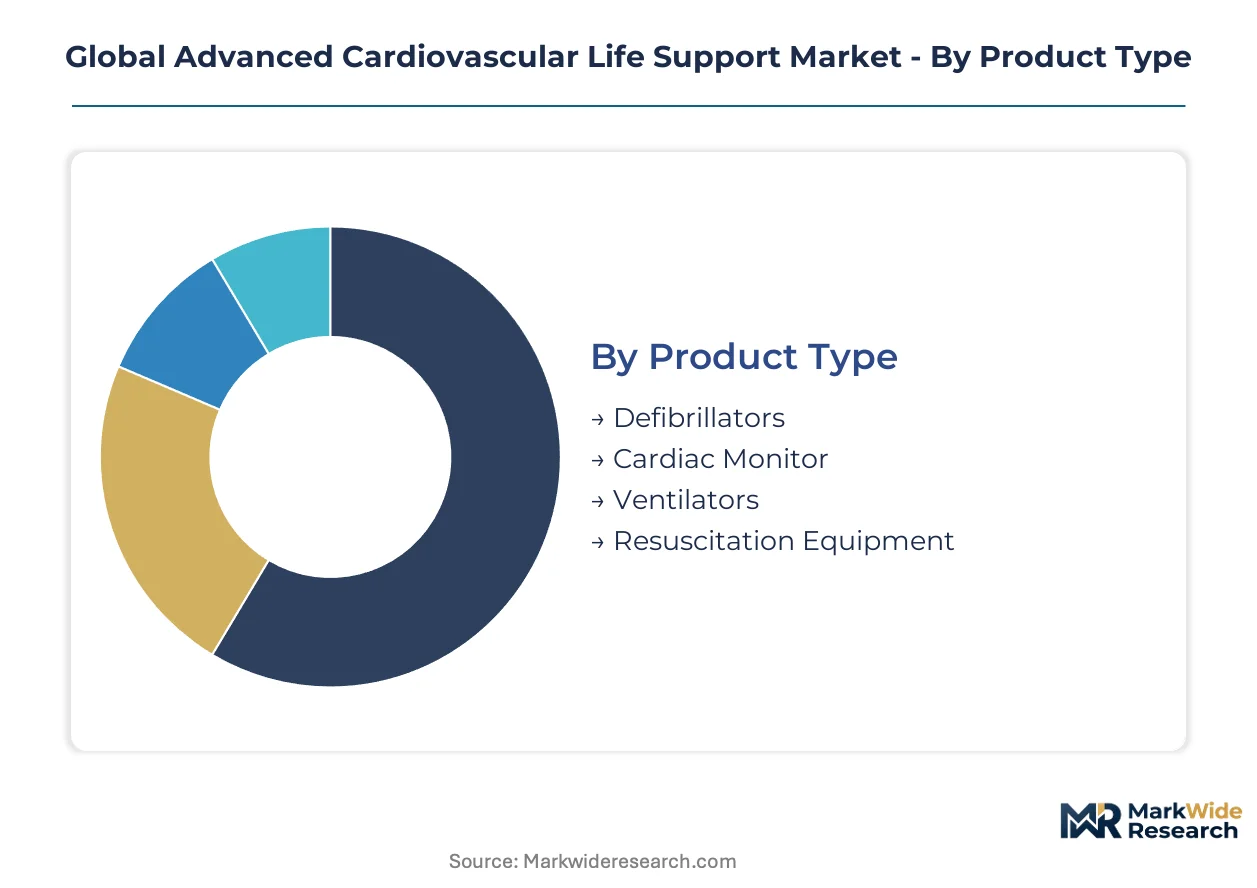
Understanding the Global Advanced Cardiovascular Life Support market through segmentation reveals distinct operational requirements and technological preferences across various healthcare settings. This granular view helps stakeholders align product development and service delivery with the specific demands of critical care interventions.
Product Type:
After-sales service intensity varies significantly across ACLS product types, driven by device complexity and regulatory maintenance schedules.
- Defibrillators:These devices deliver controlled electrical shocks to restore normal heart rhythm during cardiac arrest. Demand for advanced models with biphasic waveform delivery is high within emergency medical services globally.
- Cardiac Monitor:These devices continuously track and display vital cardiac parameters, including ECG rhythms and heart rate. Hospitals and intensive care units prioritize monitors with real-time data transmission capabilities for enhanced patient oversight.
- Ventilators:Mechanical ventilators support or replace breathing for patients in respiratory distress. Advanced pressure-controlled modes are crucial for managing complex cases in intensive care units.
- Resuscitation Equipment:This category includes a range of tools like manual resuscitators, intubation kits, and airway management devices. Emergency departments require comprehensive, reliable resuscitation kits.
Defibrillators holds the largest share; momentum sits with Cardiac Monitor.
Application:
The application focus for ACLS equipment directly influences procurement decisions and training protocols across healthcare facilities.
- Cardiac Arrest:This application involves immediate intervention to restore spontaneous circulation in patients experiencing sudden cardiac arrest. Emergency Medical Services prioritize rapid deployment and ease of use for these critical scenarios.
- Respiratory Failure:Management of respiratory failure requires advanced ventilation support and continuous monitoring of patient oxygenation. Intensive Care Units increasingly utilize devices with AI-driven diagnostic aids for proactive intervention.
- Arrhythmia Management:This application focuses on stabilizing irregular heart rhythms through defibrillation or cardioversion. Cardiology departments require precise control and diagnostic feedback from these systems.
- Shock Treatment:ACLS protocols address various forms of shock, requiring rapid fluid resuscitation and hemodynamic support. Emergency departments frequently employ integrated monitoring and treatment solutions.
Cardiac Arrest applications command significant market volume; Respiratory Failure applications are expanding most quickly.
End User:
The specific customer type dictates equipment features and service level agreements for ACLS solutions.
- Emergency Medical Services:These providers require rugged, portable, and highly reliable ACLS equipment for pre-hospital care. Data transmission capabilities to receiving hospitals are a primary procurement driver.
- Ambulance Providers:Ambulance services represent a critical component of pre-hospital care, demanding compact and durable defibrillators and resuscitation kits. Training and rapid maintenance support are essential for their operations.
- Intensive Care Units:ICUs utilize sophisticated ACLS equipment for continuous patient monitoring and advanced life support. Integration with hospital information systems and predictive analytics are highly valued.
- Outpatient Clinics:These facilities typically require basic resuscitation equipment for immediate response to medical emergencies. Training and ease of use are paramount for non-specialized staff.
Emergency Medical Services represent the dominant end-user segment; Intensive Care Units are experiencing the steepest expansion trajectory.
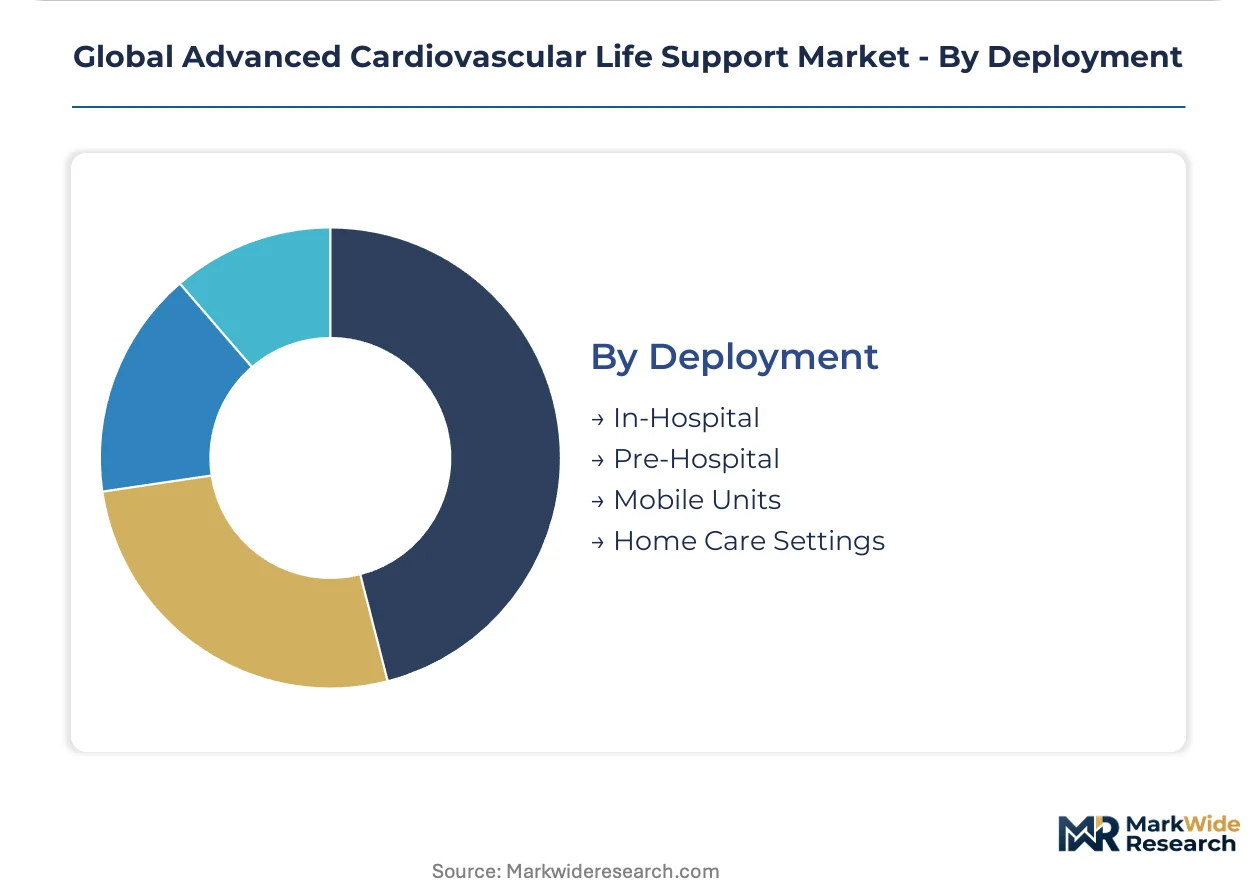
Deployment:
Volume concentration varies by deployment type, influencing product design for portability, connectivity, and power requirements.
- In-Hospital:This segment includes all ACLS equipment utilized within hospital settings, including emergency departments and operating rooms. Integration with existing infrastructure and electronic health records is a key consideration.
- Pre-Hospital:ACLS devices deployed in ambulances and other emergency vehicles fall into this category. Durability, battery life, and rapid data sharing are critical for effective pre-hospital interventions.
- Mobile Units:This segment encompasses specialized medical units that provide care outside fixed healthcare facilities, often in remote or disaster-stricken areas. Telemedicine capabilities are increasingly important for these deployments.
- Home Care Settings:A smaller but expanding segment, home care involves deploying basic resuscitation equipment for patients with chronic conditions. User-friendliness and remote monitoring capabilities are important.
In-Hospital deployment accounts for the largest share; Pre-Hospital deployment is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global Advanced Cardiovascular Life Support market exhibits distinct regional supply concentrations driven by advanced healthcare infrastructure and evolving regulatory environments. Demand for sophisticated ACLS equipment is particularly high in developed economies. These regions actively invest in emergency medical services and critical care facilities, driving market growth.
United States
United States demand for advanced defibrillators and real-time data transmission capabilities remains strong within Emergency Medical Services. The US FDA mandates stringent pre-market approval and post-market surveillance for all ACLS equipment. Major medical device manufacturers in California and the Boston-Cambridge region drive innovation in cardiac monitoring and AI-powered diagnostic aids.
Germany
Germany's national healthcare modernization programs funnel significant capital into upgrading emergency medical services, fueling demand for advanced ventilators and defibrillators. Europe's Medical Device Regulation (MDR) mandates rigorous clinical evidence for all ACLS equipment sold. Bavaria's medical technology cluster actively develops sophisticated resuscitation equipment, often integrating with large hospital networks in Berlin.
Japan
Japanese healthcare infrastructure investments drive concentrated demand for advanced defibrillators and connected cardiac monitors. The PMDA oversees strict regulatory pathways for medical devices, ensuring compliance and patient safety. Tokyo's advanced medical research centers integrate AI-driven diagnostic aids into critical care protocols, influencing device development.
United Kingdom
United Kingdom public health initiatives focus on improving critical incident response times, driving procurement of advanced ACLS equipment for EMS providers. The MHRA sets standards for medical device approval, influencing NHS procurement decisions for ventilators and defibrillators. London's health tech ecosystem actively integrates tele-ICU platforms with advanced ACLS equipment, expanding care access.
China
China's expanding healthcare access and investment in emergency and critical care infrastructure create substantial demand for ACLS equipment. The NMPA regulates medical devices, requiring local clinical trials and specific pre-market approvals for new technologies. The Yangtze River Delta region sees significant investment in medical device manufacturing and adoption of integrated resuscitation systems.
Global Advanced Cardiovascular Life Support Market Key Industry Players
Hardware manufacturers and specialized training providers split the Advanced Cardiovascular Life Support market. The competitive landscape is evolving from pure equipment sales towards integrated solutions that bundle equipment, software, and training. Companies pursue strategic partnerships for technology licensing and invest in portfolio diversification to include advanced diagnostic aids. This shift emphasizes outcome-based solutions over standalone device specifications, particularly in critical care settings.
Within the hardware manufacturing segment, Medtronic exemplifies a global leader specializing in engineering defibrillators and ventilators that align with established clinical protocols. Organizations focused on clinical guidelines and educational content, such as the American Heart Association and the European Resuscitation Council, anchor global procurement decisions and training methodologies. These entities collectively shape the functional requirements and adoption patterns for ACLS equipment worldwide. Their influence drives standardization in resuscitation protocols and promotes the integration of advanced technologies like biphasic waveform delivery.
| Leading Market Players |
|---|
| American Red Cross |
| American Academy of Pediatrics |
| American Heart Association |
| American College of Surgeons |
| American College of Emergency Physicians |
| American College of Cardiology |
| Health & Safety Institute |
| European Resuscitation Council |
| Medtronic |
| Others |
Cost & Logistics Intelligence
Dependence on a concentrated number of suppliers for critical electronic components, such as high-capacity capacitors for defibrillators, directly impacts where margin pools sit for equipment manufacturers.
Pricing Analysis
Europe's Medical Device Regulation (MDR) dictates the pricing tier structure, compelling manufacturers to invest in rigorous clinical evidence for CE marking. The dominant pricing model is a hybrid of per-unit transactional sales and subscription-based service agreements. Price differentiation stems from certification level, such as FDA approval, and the inclusion of comprehensive after-sales service bundles. Pricing pressure intensifies due to the substantial upfront capital outlay required for advanced equipment. Smaller hospitals and volunteer-based emergency services exhibit higher price sensitivity compared to large hospital networks.
Supply Chain Analysis
Export control regimes on advanced electronic components, particularly microprocessors and specialized sensors, limit material flows globally. Geographic supply concentration for these critical inputs centers on China, Japan, and the United States. The supply chain relies heavily on high-capacity capacitors and advanced biphasic waveform delivery chips. Single-source vulnerability for these specialized components presents a significant structural risk. Distribution runs through direct sales channels for major hospital systems and established distributor networks for smaller clinics and Emergency Medical Services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Advanced Cardiovascular Life Support market is in an early-cycle expansion phase, driven by the increasing penetration of AI-driven diagnostic aids. This tailwind creates significant opportunities for strategic positioning.
For Market Incumbents: Pre-empt emerging AI-driven diagnostic specialists by actively acquiring niche software firms and investing heavily in advanced algorithm development. Diversify revenue streams beyond pure hardware sales by expanding comprehensive service agreements that bundle equipment, software updates, and ongoing training. Mitigate potential regulatory shifts concerning AI in medical devices through early engagement with bodies like the US FDA and Europe's EMA.
For New Entrants and Emerging Players: Rural and underserved healthcare facilities represent a significant geographic underpenetration. Target these areas with integrated tele-ICU solutions and user-friendly, bundled service models that include equipment leasing and certification programs. Focus on developing AI-powered diagnostic aids that seamlessly integrate with existing legacy hospital information systems, offering a clear go-to-market angle for operational efficiency.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-tier medical device manufacturers specializing in specific ACLS product types or regional markets. Long-term viability for the next decade is strong, supported by persistent demand for critical care interventions and technological advancements. Identify acquisition targets with robust software capabilities or proprietary AI algorithms that enhance predictive analytics. Regulatory clarity for AI in diagnostics will be a key signal to watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Integrating AI into existing hardware provides predictive alerts for proactive patient management. |
| Hospital System Partnership | Securing long-term service agreements ensures consistent revenue streams and deep market penetration. |
| CE Marking Pathway | Ensuring compliance with Europe's MDR is critical for market access and product credibility. |
| Training-as-a-Service Model | Bundling hardware with ongoing certification creates recurring revenue and enhances customer retention. |
| Tele-ICU Integration | Expanding market reach to rural facilities enables expert oversight of critical care remotely. |
Research Approach
Cross-validation between clinician interviews and regulatory filings anchors the qualitative findings, ensuring a robust market perspective. This study combined extensive primary interviews with critical care clinicians, hospital purchasing committees, medical device engineers, and regulatory affairs leads. Secondary validation involved analysis of US FDA filings, Europe's EMA and MDR guidelines, American Heart Association guidelines, and ISO 13485 standards. Both bottom-up and top-down triangulation methods were employed to refine market size and forecast data.
The calibration approach integrates historical market performance with future demand projections across the analysis window. The analytical framework modeled market segmentation dimensions including product type, application, end user, deployment, and regional regulatory clusters. Compound annual growth rates were derived from a comprehensive assessment of market drivers, restraints, and strategic opportunities. Key industry-specific forecast inputs included national healthcare infrastructure investments and the ongoing standardization of clinical guidelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by AI-driven diagnostic startups or major hardware manufacturers would shift outcomes. Forecasts reflect assumptions regarding technological adoption rates and regulatory stability. Material shifts in cybersecurity threats or critical component supply chain dynamics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Vasculitis Market
Cardiovascular
Middle East and Africa Acute Coronary Syndrome Market
Cardiovascular
Cardiovascular Clinical Trials Market
Cardiovascular
Restrictive Cardiomyopathy Treatment Market
Cardiovascular
Angina Pectoris Treatment Market
Cardiovascular
Cardiovascular Pledgets Market
Cardiovascular
Carotid Artery Stenosis Market
Cardiovascular
Peripheral Artery Disease Market
Cardiovascular
Stable Angina Management Market
Cardiovascular
Ventricular Tachycardia Market
Cardiovascular
Angina Pectoris Market
Cardiovascular
Eisenmenger Syndrome Treatment Market
Cardiovascular
Paroxysmal Supraventricular Tachycardia (PSVT) Market
Cardiovascular
Myocardial Infarction Therapeutics Market
Cardiovascular
Heart Block Therapeutics Market
Cardiovascular
Antihypertensive Market