
 Angina Pectoris Treatment Market | 2026-2036
Angina Pectoris Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Angina Pectoris Treatment Market Intelligence
Gene-silencing and RNA-targeted platforms are rewriting the development trajectory for next-generation antianginal therapies. Novartis AG leverages its siRNA expertise to extend its cardiovascular franchise beyond traditional small-molecule nitrates. Pfizer Inc. anchors its position through sustained investment in extended-release formulation science. AstraZeneca competes aggressively in the antiplatelet segment with manufacturing scale that supports global supply security.
Angina pectoris treatment encompasses pharmacological interventions that reduce myocardial oxygen demand or increase coronary blood flow, with nitrates functioning primarily through venodilation that decreases preload and beta blockers lowering heart rate and contractility to reduce cardiac workload. The therapy area segmentation reveals stable angina as the mature volume base where generic beta blockers and calcium channel blockers dominate prescribing, while microvascular angina represents the fastest-growing diagnostic category as coronary microvascular dysfunction gains clinical recognition. Among delivery modes, extended-release formulations command premium positioning due to improved patient compliance and reduced breakthrough angina episodes compared to immediate-release alternatives.
The FDA governs new drug approvals and label expansions for antianginal therapies through its Division of Cardiology and Nephrology, while the EMA's Committee for Medicinal Products for Human Use coordinates centralized cardiovascular assessments across European member states. REACH and RoHS frameworks indirectly shape device-drug combination products such as transdermal nitroglycerin patches through material safety and environmental compliance requirements. Stakeholders must monitor how evolving FDA guidance on patient-reported outcomes in angina trials reshapes evidentiary standards for novel mechanisms including late sodium current inhibition and coronary vasodilation targets.
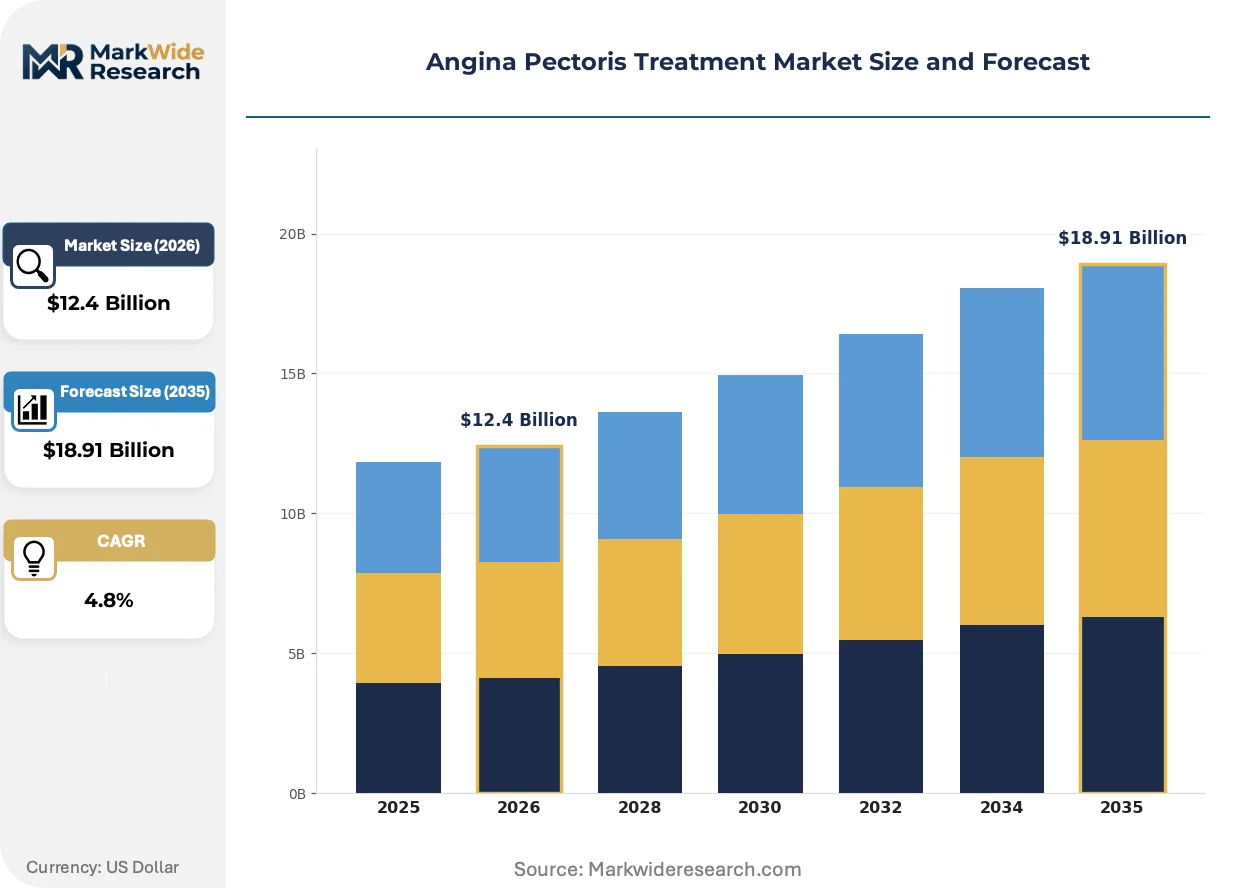
Market Dynamics
FDA's accelerated approval pathways for cardiovascular therapies are compressing development timelines while forcing sponsors to generate real-world evidence post-market. This regulatory velocity is hybridizing with gene-silencing platforms to reshape competitive entry patterns.
Growth Catalysts
- REACH and RoHS frameworks:These European material safety mandates are driving reformulation of transdermal nitroglycerin patches toward biocompatible adhesives and recyclable substrates, expanding device-drug combination product categories.
- Cardiology clinics:Outpatient stable angina management protocols are expanding across the United States as interventional cardiology infrastructure matures, shifting treatment volumes from hospital settings.
- siRNA platforms:Gene-silencing mechanisms targeting coronary microvascular dysfunction are advancing through clinical pipelines, creating novel therapeutic categories beyond traditional hemodynamic agents.
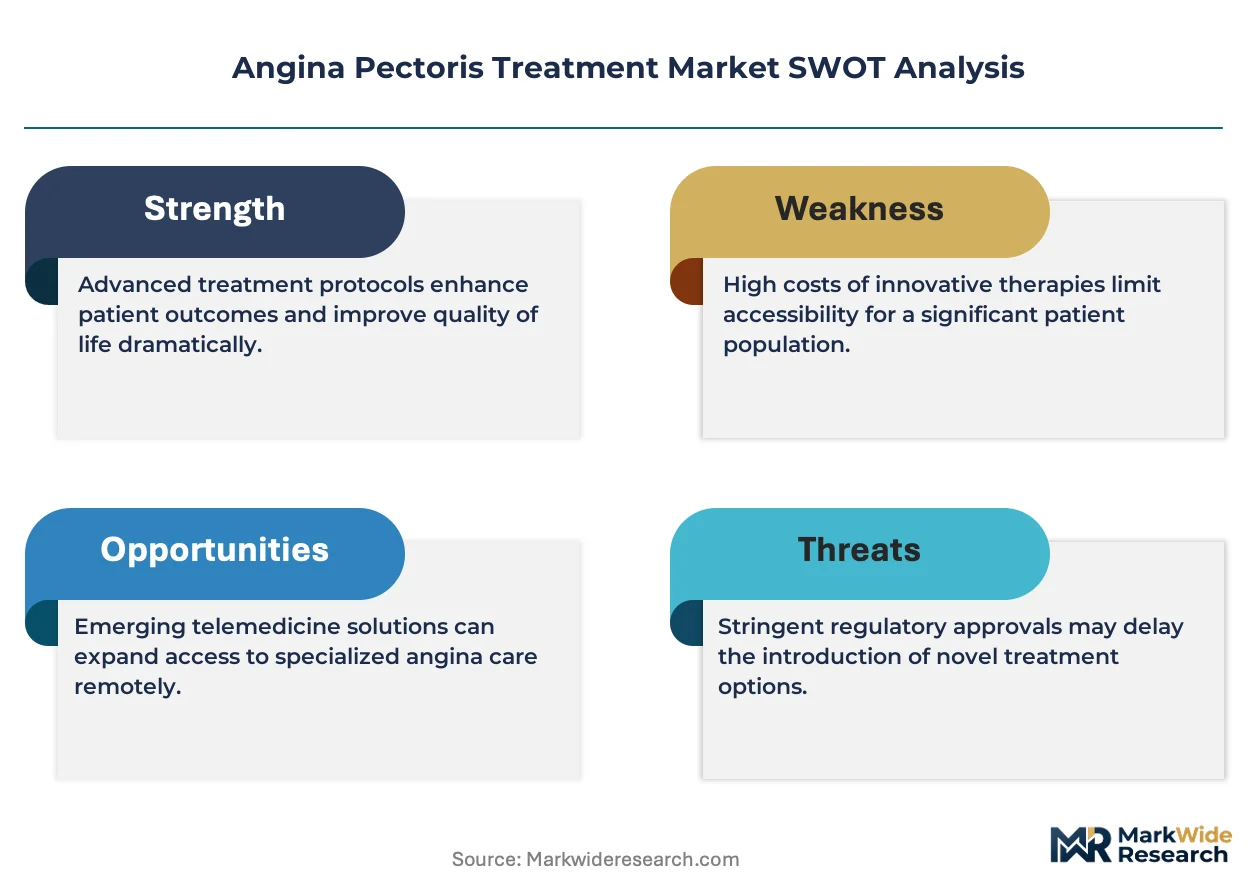
Market Restraints
- Generic beta blocker saturation:Stable angina prescribing is dominated by off-patent calcium channel blockers and nitrates, eroding pricing power for incremental formulation improvements.
- Microvascular angina diagnostic underdevelopment:Coronary microvascular dysfunction lacks standardized non-invasive testing protocols, delaying patient identification and therapy initiation.
- Extended-release formulation complexity:Manufacturing scale-up for polymer-matrix nitroglycerin systems requires specialized equipment and batch validation timelines that constrain supply responsiveness.
Strategic Opportunities
- Late sodium current inhibitors:Novel mechanisms addressing myocardial ischemia without hypotensive side effects represent white space for differentiated antianginal development.
- Patient-reported outcome integration:FDA guidance on angina-specific quality-of-life endpoints is enabling label differentiation based on symptomatic benefit rather than surrogate hemodynamic measures.
- Japan's aging demographic:METI-supported geriatric cardiovascular research programs are creating demand for polypharmacy-optimized antianginal regimens with reduced drug interaction profiles.
Industry Challenges
- Cardiovascular trial recruitment:Competing demands from heart failure and anticoagulant studies are constraining eligible patient access for novel antianginal pivotal trials.
- Legacy EHR integration:Electronic health record systems in US cardiology practices require custom configuration to capture angina episode frequency data for real-world evidence generation.
- Multidisciplinary care coordination:Optimal microvascular angina management demands alignment between interventional cardiologists, rheumatologists, and pain specialists with divergent incentive structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Angina Pectoris Treatment Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $18.91 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrates, Beta Blockers, Calcium Channel Blockers, Antiplatelet Agents, Ranolazine Therapy Area: Stable Angina, Variant Angina, Unstable Angina, Microvascular Angina End User: Cardiology Clinics, Outpatient Facilities, Specialty Hospitals, Diagnostic Centers Delivery Mode: Oral, Intravenous, Transdermal, Sublingual, Extended-Release |
| Companies Covered | Novartis AG, Merck & Co., Inc., Pfizer Inc., Sanofi S.A., Gilead Sciences, AstraZeneca, GlaxoSmithKline Plc., Amgen Inc., Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Angina Pectoris Treatment Market Strategic Shifts & Innovations
RNA-targeted platforms and extended-release formulation science are converging to redefine therapeutic durability and dosing convenience. These advances are compressing the gap between symptomatic relief and disease modification.
Gene-silencing therapies targeting PCSK9 and lipoprotein pathways are hybridizing with traditional antianginal mechanisms. Cardiology clinics in the United States are piloting these combinations for patients with refractory stable angina and concurrent dyslipidemia. The structural consequence is a shift from episodic symptom management toward sustained coronary risk reduction within single therapeutic regimens.
The FDA's Division of Cardiology and Nephrology is tightening evidentiary requirements for breakthrough therapy designations in angina, demanding demonstration of sustained exercise tolerance improvement beyond 12 weeks. This policy compression is forcing sponsors to extend placebo-controlled trial durations and incorporate ambulatory ECG monitoring. Extended-release beta blocker formulations face the steepest compliance burden given their established generic competition.
Hospital procurement committees are unbundling antianginal selection from broader cardiovascular bundle contracts, enabling pharmacy and therapeutics committees to evaluate mechanism-specific value. This fragmentation is displacing incumbent therapeutic classes in favor of agents with differentiated cardiovascular outcome data. The shift is most visible in German and French cardiology departments where DRG refinement has sharpened cost-per-QALY scrutiny.
Angina Pectoris Treatment Market Segmentation
Segmentation in the angina pectoris treatment market reveals how prescribing patterns diverge across clinical settings and therapeutic mechanisms. Understanding these divisions exposes where formulation innovation commands premium positioning versus where generic substitution dominates.
Product Type:
Cost tier determines competitive intensity across pharmacological classes, with mature oral generics competing against patent-protected extended-release formulations.
- Nitrates:Venodilating agents reduce preload through nitric oxide-mediated smooth muscle relaxation. Demand concentrates in United States outpatient cardiology clinics where breakthrough angina management protocols favor sublingual nitroglycerin for acute rescue. Formulation stability challenges in transdermal patches create supply concentration among specialized polymer manufacturers.
- Beta Blockers:Cardioselective and non-selective agents lower myocardial oxygen demand via heart rate and contractility reduction. United States prescribing volumes dominate stable angina maintenance therapy, though generic metoprolol and atenolol saturation erodes branded pricing power. Extended-release carvedilol formulations retain modest differentiation through once-daily compliance advantages.
- Calcium Channel Blockers:Dihydropyridine and non-dihydropyridine classes dilate coronary arteries and reduce afterload. German and French hospital formularies favor amlodipine for vasospastic angina given its favorable side-effect profile.
- Antiplatelet Agents:P2Y12 inhibitors and aspirin derivatives prevent thrombotic complications in unstable presentations. Japanese geriatric cardiology programs drive demand for low-dose maintenance regimens.
- Ranolazine:Late sodium current inhibitor addressing refractory angina without hemodynamic compromise. United States specialty pharmacies manage distribution given metabolic interaction monitoring requirements.
Beta blockers command the established base. The steepest expansion runs through ranolazine as refractory patient identification improves.
Therapy Area:
Application severity stratifies treatment intensity, with diagnostic category determining whether acute intervention or chronic management protocols apply.
- Stable Angina:Predictable exertion-induced chest pain managed through outpatient pharmacological optimization. United States cardiology clinics handle the largest patient volumes through nurse-led titration protocols. Generic beta blocker and nitrate dominance constrains revenue per patient despite high visit frequency.
- Microvascular Angina:Coronary microvascular dysfunction with non-obstructive coronary arteries represents the most rapidly expanding diagnostic category. United States academic medical centers pioneer invasive coronary function testing to identify these patients. siRNA platform development targets endothelial dysfunction mechanisms absent in epicardial disease.
- Variant Angina:Prinzmetal's angina triggered by coronary vasospasm requires calcium channel blocker therapy. Japanese emergency departments maintain high diagnostic vigilance given population prevalence patterns.
- Unstable Angina:Acute coronary syndrome without biomarker elevation demands immediate antiplatelet loading and revascularization assessment. German chest pain units standardize rapid rule-out protocols.
Stable angina generates the volume base. Microvascular angina climbs the fastest as recognition of coronary microvascular dysfunction spreads.
End User:
Customer type shapes procurement authority and formulary control, with site-of-care migration altering competitive dynamics.
- Cardiology Clinics:United States outpatient settings increasingly manage stable angina through protocol-driven titration algorithms. Pharmacy benefit managers influence product selection through prior authorization requirements.
- Specialty Hospitals:Acute coronary syndrome presentations drive intravenous nitroglycerin and antiplatelet utilization. French public hospital groups negotiate mechanism-based tenders.
- Outpatient Facilities:Ambulatory surgical centers handle post-revascularization antianginal transitions. United States Medicare reimbursement shifts favor site-neutral payment.
- Diagnostic Centers:Stress testing facilities identify angina etiology and guide initial therapy selection. Japanese imaging centers integrate coronary function assessment.
Cardiology clinics anchor outpatient volume. Specialty hospitals retain acute intervention authority.
Delivery Mode:
Formulation maturity determines manufacturing complexity and patient compliance trade-offs across administration routes.
- Extended-Release:Polymer-matrix and osmotic pump technologies enable sustained plasma levels with reduced dosing frequency. United States Medicare Part D plans favor these formulations for adherence quality metrics despite generic immediate-release alternatives.
- Oral:Immediate-release tablets and capsules dominate maintenance therapy for cost-sensitive stable angina populations. Indian generic manufacturers supply bulk active pharmaceutical ingredients globally.
- Transdermal:Nitroglycerin patches provide continuous prophylaxis with bypassed first-pass metabolism. REACH and RoHS compliance drives adhesive reformulation in European markets.
- Sublingual:Rapid-onset nitroglycerin spray and tablets remain essential for acute angina rescue. United States emergency medical services stock standardized concentrations.
- Intravenous:Hospital-controlled infusion enables titrated hemodynamic management in unstable presentations. German intensive care units maintain standardized protocols.
Oral formulations capture the volume base. Extended-release delivery gains share fastest through compliance-linked reimbursement incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical exports supply extended-release formulation technologies to United States cardiology clinics, while Japanese siRNA research programs feed into North American gene-silencing clinical pipelines.
United States
FDA's Division of Cardiology and Nephrology governs accelerated approval pathways for novel antianginal mechanisms. Medicare Part D reimbursement incentives favor extended-release formulations for adherence quality metrics. Boston and Minneapolis academic medical centers pioneer invasive coronary function testing for microvascular angina identification.
Germany
EMA centralized assessments coordinate cardiovascular therapy approvals across member states. REACH frameworks mandate biocompatible adhesive reformulation for transdermal nitroglycerin patches. Berlin and Munich public hospital groups negotiate mechanism-based tenders that displace incumbent therapeutic classes.
Japan
METI-supported geriatric cardiovascular research programs drive demand for polypharmacy-optimized antianginal regimens. PMDA reviews prioritize reduced drug interaction profiles for aging populations. Tokyo and Osaka emergency departments maintain high diagnostic vigilance for variant angina given population prevalence patterns.
India
CDSCO regulatory pathways shape generic beta blocker and nitrate manufacturing scale. PLI scheme incentives attract active pharmaceutical ingredient production for cost-sensitive stable angina markets. Hyderabad and Ahmedabad generic manufacturers supply bulk APIs to United States and European formulators.
Switzerland
Swissmedic coordinates with EMA on cardiovascular therapy assessments while maintaining independent label authority. Geneva and Basel pharmaceutical clusters concentrate extended-release polymer-matrix formulation expertise. Specialized manufacturers supply nitroglycerin patch substrates compliant with REACH and RoHS material safety mandates.
Angina Pectoris Treatment Market Key Industry Players
On the supply side, the industry is structured around three strategic tiers: diversified pharmaceutical conglomerates with cardiovascular franchises, mid-cap specialists in extended-release formulation science, and emerging RNA-targeted platform developers. Competitive moves concentrate on gene-silencing technology licensing and geographic expansion into Japanese geriatric cardiology programs.
Among Swiss-based pharmaceutical conglomerates, Novartis AG exemplifies the gene-silencing platform archetype through siRNA expertise extending beyond traditional small-molecule nitrates. Pfizer Inc. occupies a position anchored in extended-release formulation science investment. AstraZeneca represents the manufacturing-scale archetype competing in antiplatelet segments with global supply security capabilities.
| Leading Market Players |
|---|
| Novartis AG |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Sanofi S.A. |
| Gilead Sciences |
| AstraZeneca |
| GlaxoSmithKline Plc. |
| Amgen Inc. |
| Bayer AG |
| Others |
Cost & Logistics Intelligence
The Rotterdam-Antwerp pharmaceutical freight corridor carries polymer-matrix nitroglycerin precursors from Swiss manufacturers to German formulators, with freight cost volatility amplifying margin compression at the generic beta blocker tier while enabling premium capture for REACH-compliant transdermal patch substrates.
Pricing Analysis
The pricing gap between immediate-release oral generics, extended-release polymer-matrix formulations, and emerging siRNA-platform therapies spans three technology generations. Three-tier pricing structure across premium extended-release, standard oral maintenance, and economy generic rescue segments dominates stable angina prescribing. Price differentiation rests on formulation complexity and FDA bioequivalence certification tiers. Cost compression in the oral generic tier intensifies because Indian API manufacturers scale metoprolol and atenolol production. Hospital procurement committees exhibit the highest price sensitivity; specialty pharmacies managing ranolazine distribution show the lowest.
Supply Chain Analysis
REACH and RoHS export-control frameworks restrict adhesive substrate flows from non-compliant Asian suppliers, forcing European patch manufacturers toward Swiss and German polymer sources. Active pharmaceutical ingredient production concentrates in India, China, and Switzerland. Formulation science expertise draws from Basel and Geneva clusters. Supply chain risk centers on single-source dependency for specialized nitroglycerin patch substrates. Distribution runs through cardiology clinic procurement committees and hospital pharmacy and therapeutics committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as microvascular angina diagnostic protocols penetrate United States academic medical centers and Japanese geriatric cardiology programs.
For Market Incumbents: Entrench position through backward integration into polymer-matrix substrate production and captive supply of nitroglycerin API. The siRNA platform threat from Novartis AG and emerging gene-silencing developers demands accelerated extended-release formulation patent filings. Vertical integration into specialized adhesive manufacturing represents the critical defensive lever. For New Entrants and Emerging Players: Build out coronary function testing service capabilities alongside diagnostic-center partnerships to capture microvascular angina patient identification. The United States outpatient cardiology clinic segment offers the most penetrable entry point. A go-to-market angle anchored in real-world evidence generation for FDA breakthrough therapy designation distinguishes novel mechanism candidates. For Investors and Strategic Acquirers: Carve-out targets emerge from mid-cap extended-release formulation specialists with stranded polymer-matrix expertise. Long-term viability favors developers with siRNA platform adjacencies into cardiovascular indications. Watch FDA guidance on patient-reported outcome endpoints as the inflection signal for mechanism-based pricing premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA accelerated approval compresses timelines for novel antianginal mechanisms. |
| Manufacturing Scale-Up | Extended-release polymer-matrix production requires specialized batch validation equipment. |
| Licensing Agreement | Gene-silencing platform access extends cardiovascular franchises beyond small molecules. |
| Pipeline Diversification | Late sodium current inhibitors address refractory angina without hypotensive side effects. |
| Reimbursement Strategy | Medicare Part D adherence metrics favor extended-release formulation placement. |
Research Approach
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided ongoing calibration across primary interviews and secondary validation. FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases anchored bottom-up and top-down triangulation.
Scenario-bracketing framed analytical approaches across the analysis window, with segmentation modeling across therapy area, delivery mode, end-user setting, and regional regulatory cluster. CAGRs derived from patient volume projections, pricing tier trajectories, and penetration curve assumptions for microvascular angina identification protocols.
The forecast holds incumbent behavior within observed patterns; aggressive moves by siRNA platform developers or generic API manufacturers would shift outcomes. Material shifts in FDA evidentiary requirements for breakthrough therapy designation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Endocarditis Therapeutics Market
Cardiovascular
Cardiometabolic Disease Market
Cardiovascular
Cardiac Valvulotome Market
Cardiovascular
Global Hypotension Treatment Market
Cardiovascular
Stroke Management Market
Cardiovascular
Angina Market
Cardiovascular
Stable Angina Management Market
Cardiovascular
Ventricular Tachycardia Market
Cardiovascular
Myocardial Infarction Market
Cardiovascular
Cardio-Selective Beta Blockers Market
Cardiovascular
Acute Heart Failure (AHF) Therapeutics Market
Cardiovascular
Ischemia Reperfusion Injury Therapeutics Market
Cardiovascular
Vasculitis Market
Cardiovascular
Global Pericarditis Market
Cardiovascular
Coronary Artery Disease Therapeutics Market
Cardiovascular
Ischemia Reperfusion Injury Treatment Market